
 Vehicle Electrification Market | 2026-2036
Vehicle Electrification Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Electrification Market Intelligence
The capital-intensity divergence between integrated powertrain specialists and component-focused suppliers is rotating competitive advantage toward firms with captive semiconductor and battery management capabilities. Robert Bosch GmbH leverages its in-house silicon carbide chip fabrication to control costs across inverter and motor control modules. Continental AG anchors its position through vertical integration into thermal management systems that extend electric range in cold climates. BorgWarner Inc. competes by specializing in integrated drive modules that reduce assembly complexity for automakers.
Vehicle electrification encompasses the substitution of internal combustion propulsion with electric drivetrain architectures, typically employing high-voltage battery packs above 400 volts, permanent magnet synchronous motors, and power electronics with switching frequencies exceeding 10 kilohertz to deliver torque response within milliseconds for passenger and commercial mobility. Battery Electric Vehicles command the dominant revenue share where lithium-ion cell chemistry achieves energy densities above 250 watt-hours per kilogram, while Solid-state Batteries represent the fastest-advancing technology segment as manufacturers resolve ceramic electrolyte manufacturing yield challenges. Regenerative Braking Systems constitute a mature margin pool where incremental hardware cost is low but software calibration differentiates vehicle efficiency ratings.
The US EPA tailpipe standards and NHTSA corporate average fuel economy rules mandate fleet-wide emission reductions that force automakers to electrify light-duty lineups or purchase regulatory credits. China's MIIT new energy vehicle mandate requires minimum electric production quotas that directly shape supplier order books and battery capacity allocation. Europe's F-Gas Regulation and REACH chemical restrictions further constrain refrigerant and thermal fluid choices in electrified thermal systems. Stakeholders must monitor how battery raw material sourcing rules in multiple jurisdictions reshape cell cost structures and supplier qualification timelines.
Market Dynamics
Capital allocation patterns across the vehicle electrification ecosystem are pivoting decisively toward in-house battery cell production and captive silicon carbide foundry capacity, compressing margins for pure-play component vendors unable to match integrated cost structures.
Growth Catalysts
- China's MIIT new energy vehicle mandate:Production quotas for electrified powertrains directly shape supplier order books and battery capacity allocation across tier-one manufacturing clusters.
- Commercial fleet electrification:Logistics operators in Germany's Rhine-Ruhr corridor and California's Central Valley are converting heavy-duty routes to electric drivetrains as total cost equations invert.
- Lithium-ion energy density thresholds:Cell chemistries exceeding 250 watt-hours per kilogram are unlocking extended-range passenger segments previously reserved for combustion architectures.
Market Restraints
- Cathode raw material concentration:Cobalt and lithium refining capacity clusters in the Democratic Republic of Congo and Chile's Atacama salt flats, exposing cell producers to geopolitical supply disruption.
- Charging infrastructure gap:High-voltage DC fast-charging networks remain sparse across India's National Highways and Brazil's interior states, constraining battery electric vehicle penetration.
- REACH chemical compliance:Europe's restrictions on thermal fluid chemistries and refrigerant selections add qualification timelines and reformulation costs for thermal management suppliers.
Strategic Opportunities
- Indonesia's nickel processing ascent:Integrated battery material parks in Sulawesi and Halmahera are attracting cathode precursor investments that bypass traditional Chinese refining dominance.
- Solid-state ceramic electrolyte manufacturing:Resolving yield challenges in sulfide and oxide solid-state cell production opens pathways to energy densities exceeding 400 watt-hours per kilogram.
- US Inflation Reduction Act domestic content credits:Battery assembly and critical mineral sourcing incentives are reshaping North American supplier location decisions and joint venture structures.
Industry Challenges
- Power electronics firmware calibration:The scarcity of engineers proficient in 10+ kilohertz switching frequency control algorithms is delaying inverter platform releases across multiple OEM programs.
- Battery management system certification:Functional safety validation to ISO 26262 ASIL-D standards requires 18-24 month validation cycles that compress product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Electrification Market |
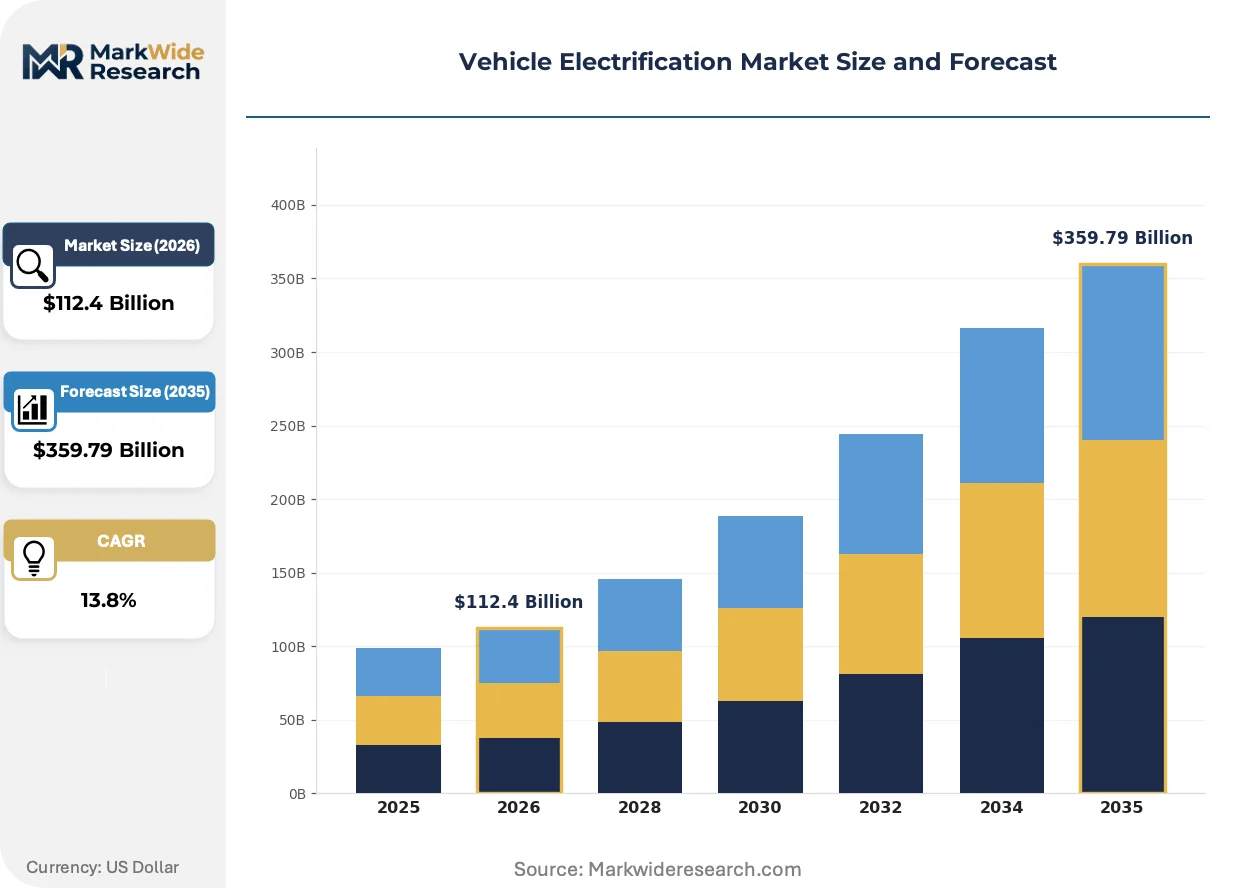
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $359.79 Billion |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Electric Vehicles, Plug-in Hybrid Electric Vehicles, Fuel Cell Electric Vehicles, Hybrid Electric Vehicles Technology: Li-ion Batteries, Solid-state Batteries, Fuel Cell Technology, Regenerative Braking Systems End User: Automakers, Fleet Operators, Public Transportation, Ride-sharing Services Charging Infrastructure: Fast Chargers, Level 2 Chargers, Wireless Charging, Battery Swapping Stations |
| Companies Covered | Robert Bosch GmbH, Continental AG, Denso Corporation, BorgWarner Inc., Delphi Technologies PLC, Johnson Electric Holdings Limited, ZF Friedrichshafen AG, Mitsubishi Electric Corporation, Aptiv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Electrification Market Strategic Shifts & Innovations
Electrification architectures are diverging across voltage classes and thermal management philosophies, forcing suppliers to place parallel bets on divergent technical roadmaps rather than converging on unified standards.
Silicon carbide power semiconductors are fragmenting competitive positioning in traction inverters by enabling switching frequencies that reduce motor size and thermal load. European premium OEMs and Korean battery electric vehicle platforms are adopting 800-volt architectures that demand SiC MOSFETs, compressing market share for legacy silicon IGBT suppliers. The technology is fragmenting inverter supplier tiers into SiC-capable integrated specialists and silicon-dependent component vendors facing margin erosion.
The US EPA tailpipe standards and NHTSA corporate average fuel economy rules are tightening fleet-wide emission budgets that force light-duty lineups toward electrification or regulatory credit purchases. Automakers are rebalancing production mix toward battery electric and plug-in hybrid configurations to avoid penalty exposure. Light-duty truck and SUV segments in the US market face the steepest compliance cost escalation, accelerating powertrain platform consolidation.
Fleet procurement departments are consolidating supplier relationships around integrated drivetrain modules rather than discrete component sourcing. Commercial vehicle operators in Germany and California are awarding multi-year contracts to powertrain integrators capable of warrantying complete electric axle assemblies. This concentration is most pronounced in heavy-duty logistics corridors where uptime guarantees and single-source accountability override component-level cost minimization.
Vehicle Electrification Market Segmentation
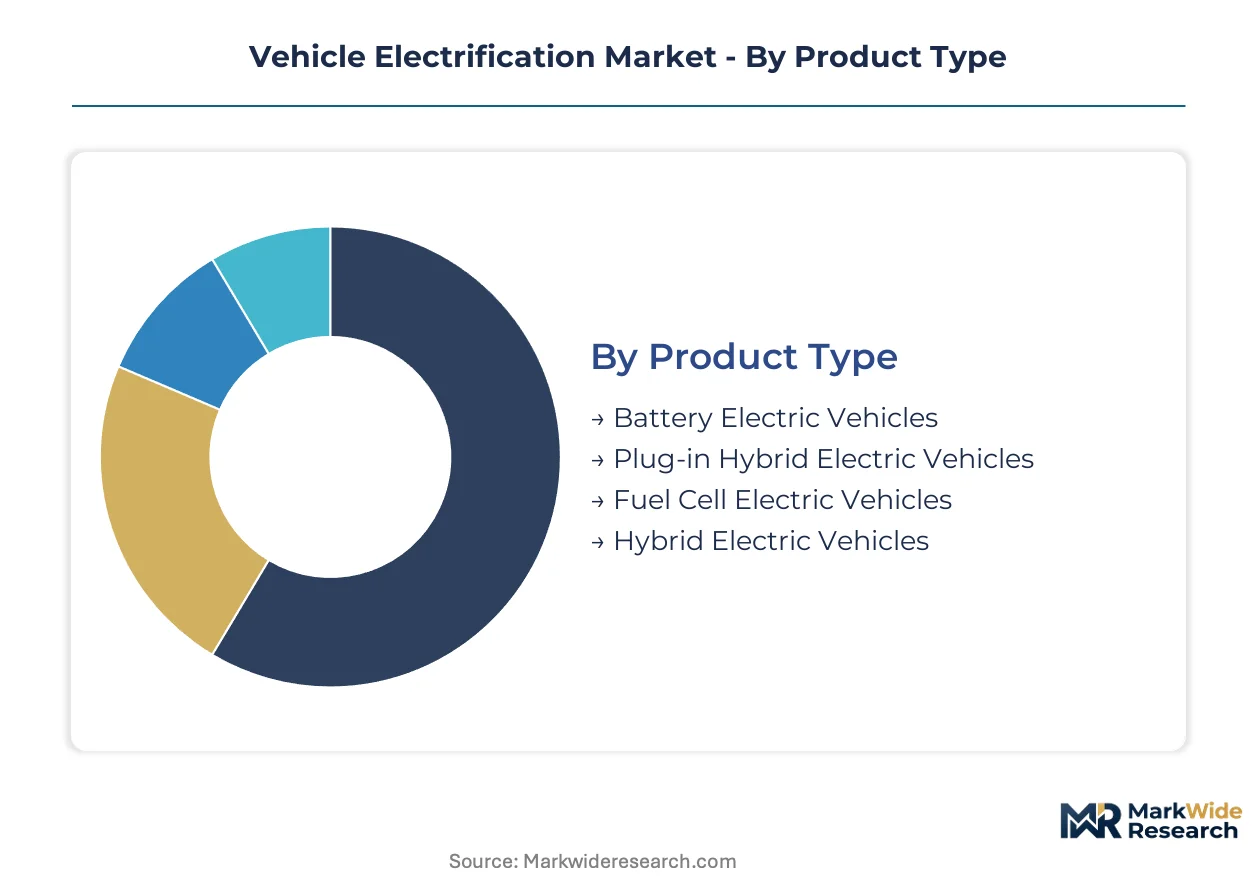
Electrification markets fragment across powertrain architectures, energy storage chemistries, and charging modalities that each carry distinct margin profiles and supplier qualification barriers. Segment boundaries are hardening as automakers lock in multi-year platform commitments and regulators impose technology-specific compliance pathways.
Product Type:
Margin concentration sits with architectures that maximize battery capacity and minimize powertrain complexity.
- Battery Electric Vehicles:Pure-electric architectures employing lithium-ion packs above 400 volts and permanent magnet synchronous motors eliminate mechanical transmission losses entirely. Demand clusters in Germany's automotive manufacturing belt around Stuttgart and Wolfsburg, where OEM assembly plants require tier-one suppliers to co-locate for just-in-sequence delivery.
- Plug-in Hybrid Electric Vehicles:Dual-powertrain systems combining downsized combustion engines with electric ranges exceeding 50 kilometers bridge regulatory compliance and consumer range anxiety. Fleet procurement departments in California's Central Valley are converting heavy-duty routes to plug-in configurations as total cost equations invert.
- Fuel Cell Electric Vehicles:Proton exchange membrane stacks paired with compressed hydrogen storage serve long-haul commercial corridors where battery weight penalties constrain payload.
- Hybrid Electric Vehicles:Mild-hybrid 48-volt systems represent a mature margin pool where incremental hardware cost is low but software calibration differentiates vehicle efficiency ratings.
Battery Electric Vehicles hold installed capacity. Plug-in Hybrid Electric Vehicles is rotating up the share rankings.
Technology:
Cost structures diverge sharply between established cell chemistries and next-generation solid-state platforms.
- Li-ion Batteries:NMC and LFP cell chemistries achieving energy densities above 250 watt-hours per kilogram dominate current production. China's MIIT new energy vehicle mandate requires minimum electric production quotas that directly shape supplier order books and battery capacity allocation.
- Solid-state Batteries:Ceramic electrolyte architectures promise energy densities exceeding 400 watt-hours per kilogram once sulfide and oxide manufacturing yields stabilize. Korean battery electric vehicle platforms are adopting 800-volt architectures that demand advanced thermal management.
- Fuel Cell Technology:PEM stack systems with platinum-group catalyst loadings compete in heavy-duty logistics where refueling speed outweighs infrastructure capital requirements.
- Regenerative Braking Systems:Motor-generator units with 10+ kilohertz switching frequency control algorithms recover kinetic energy during deceleration events.
Li-ion Batteries holds installed capacity. Solid-state Batteries is climbing the fastest.
End User:
Procurement sophistication varies from integrated OEM engineering teams to price-sensitive fleet operators.
- Automakers:Integrated powertrain engineering divisions specify complete electric axle assemblies with single-source warranty accountability. The US EPA tailpipe standards and NHTSA corporate average fuel economy rules mandate fleet-wide emission reductions that force light-duty lineups toward electrification.
- Fleet Operators:Logistics procurement departments award multi-year contracts based on total cost of ownership calculations including energy, maintenance, and residual value.
- Public Transportation:Municipal transit authorities specify depot-charged electric buses with overnight Level 2 infrastructure and route-specific range guarantees.
- Ride-sharing Services:Mobility platforms prioritize vehicles with DC fast-charging compatibility to minimize downtime between fare-generating hours.
Automakers holds installed capacity. Fleet Operators is rotating up the share rankings.
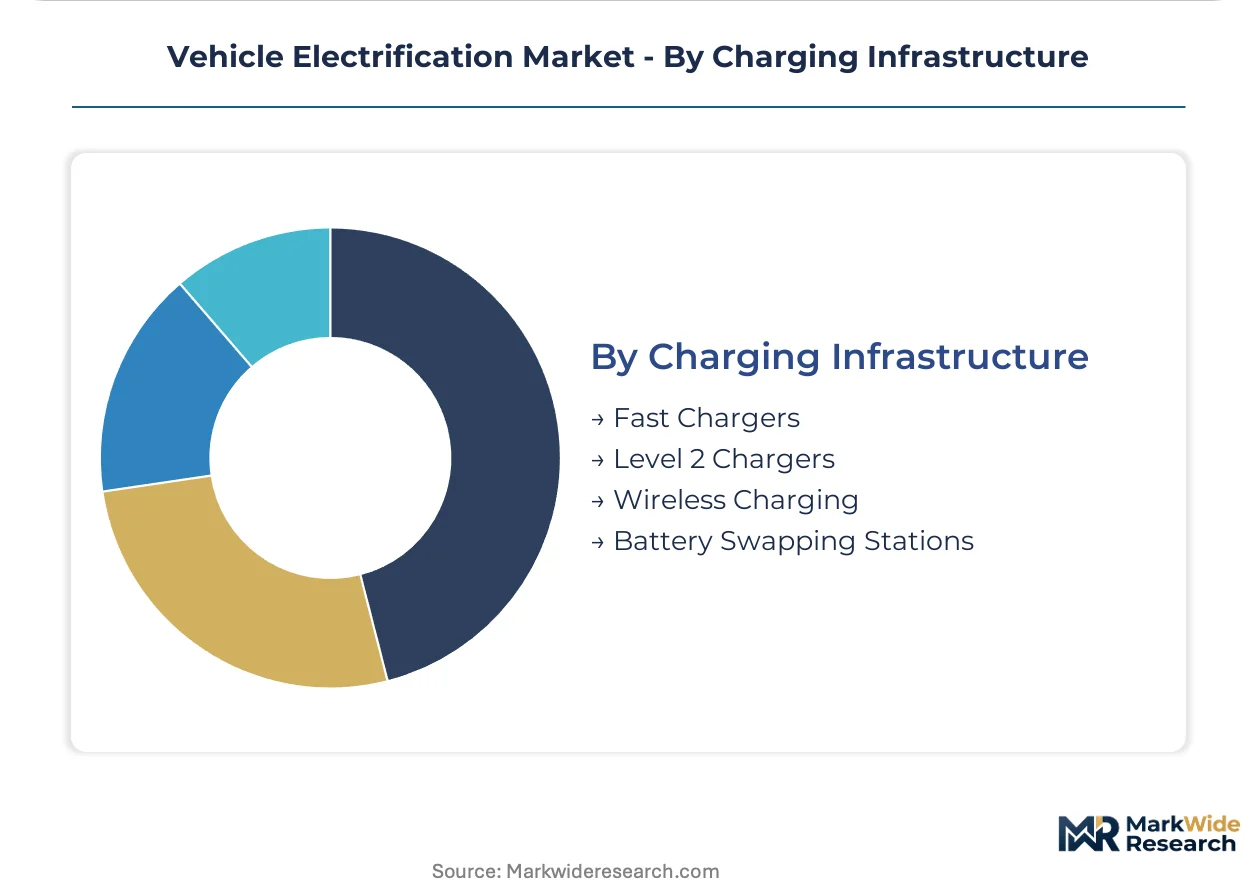
Charging Infrastructure:
Capital deployment intensity separates high-voltage DC networks from lower-power distributed solutions.
- Fast Chargers:DC stations delivering 150+ kilowatts enable 10-80% state-of-charge events within 20 minutes. High-voltage DC fast-charging networks remain sparse across India's National Highways and Brazil's interior states.
- Level 2 Chargers:AC equipment supplying 7-19 kilowatts dominates residential and workplace installations where dwell times exceed four hours.
- Wireless Charging:Inductive pads with aligned coil geometries automate energy transfer for fleet depots and premium passenger segments.
- Battery Swapping Stations:Automated exchange systems serving commercial vehicle corridors where asset utilization demands sub-five-minute energy replenishment.
Fast Chargers holds installed capacity. Battery Swapping Stations is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany's automotive manufacturing belt exceeds that of India's emerging production zones by a factor reflecting captive silicon carbide capacity and tier-one supplier density. China's MIIT mandate concentrates battery allocation decisions in Yangtze River Delta industrial parks. The US Inflation Reduction Act redirects supplier location calculus toward North American assembly corridors.
China
MIIT production quotas for electrified powertrains dominate supplier order books and cell capacity allocation across tier-one manufacturing clusters. Dual carbon goals from MEE enforce fleet emission trajectories that automakers meet through battery electric platform commitments. Yangtze River Delta industrial parks around Shanghai and Suzhou concentrate cathode precursor plants and power electronics assembly for domestic OEMs.
Germany
Commercial fleet operators in the Rhine-Ruhr corridor accelerate heavy-duty route electrification as total cost equations invert toward battery electric drivetrains. European Commission CO2 standards mandate fleet-wide emission reductions that compress ICE production timelines. Stuttgart and Wolfsburg anchor tier-one supplier clusters where Bosch and Continental co-locate inverter and thermal management production for just-in-sequence delivery.
United States
EPA tailpipe standards and NHTSA fuel economy rules force light-duty truck electrification or regulatory credit purchases across Detroit Three lineups. Inflation Reduction Act domestic content credits reshape battery assembly joint venture structures toward Michigan and Tennessee corridors. California's Central Valley logistics operators award multi-year contracts to integrated drivetrain specialists warrantying complete electric axle assemblies.
Japan
METI technology roadmaps prioritize solid-state battery commercialization timelines that Korean and Chinese cell producers race to match. Automotive engineering divisions in Toyota City and Nissan's Yokohama headquarters specify 800-volt architectures demanding silicon carbide MOSFET traction inverters. Kansai industrial belt suppliers concentrate motor-generator unit production for hybrid and plug-in hybrid platforms.
South Korea
Battery electric vehicle platforms from Hyundai and Kia adopt 800-volt architectures that demand advanced thermal management and SiC power electronics. MFDS chemical registration requirements intersect with REACH-equivalent substance controls on electrolyte additives and thermal fluids. Seoul Capital Area suppliers cluster near OEM engineering centers for powertrain integration programs.
Vehicle Electrification Market Key Industry Players
Concentration sits with integrated powertrain specialists possessing captive semiconductor fabrication and battery management system capabilities. The vendor base spans three tiers: diversified industrial conglomerates with in-house silicon carbide foundries, thermal management specialists with backward integration into refrigerant chemistry, and modular assembly integrators reducing OEM line complexity. Dominant competitive moves include capacity expansion into Indonesian nickel processing corridors and strategic partnerships around solid-state electrolyte manufacturing yields.
Within the integrated tier, Robert Bosch GmbH and Continental AG exemplify archetypes of captive supply chain control. BorgWarner Inc. occupies a position representing modular integration specialists. These three entities anchor the competitive structure through differentiated vertical scope rather than scale alone.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| BorgWarner Inc. |
| Delphi Technologies PLC |
| Johnson Electric Holdings Limited |
| ZF Friedrichshafen AG |
| Mitsubishi Electric Corporation |
| Aptiv |
| Others |
Cost & Logistics Intelligence
Silicon carbide substrate substitution for legacy silicon IGBTs simultaneously shifts power electronics sourcing toward Taiwan and South Korea while compressing inverter module pricing spreads across automotive qualification tiers. This material transition redraws foundry capacity allocation and forces tier-two suppliers into contract manufacturing arrangements that erode margin capture.
Pricing Analysis
The customization-premium spread between configured-to-order 800-volt traction inverters and standard 400-volt platforms widens as OEMs demand application-specific thermal packaging and firmware calibration. Three-tier pricing structure across premium SiC-enabled, standard silicon-based, and economy remanufactured tiers reflects certification grade and volume scale differentiation. Pricing pressure stems from captive silicon carbide foundry investments by integrated tier-one suppliers. Fleet operators exhibit highest price sensitivity, while premium passenger OEMs prioritize performance metrics over unit cost.
Supply Chain Analysis
China and South Korea anchor cathode precursor and cell manufacturing, while Indonesia's Sulawesi corridor feeds nickel processing expansion. The vehicle electrification supply chain draws from Chilean lithium brine, Congolese cobalt, and Australian spodumene concentrates. Single-source vulnerability concentrates in ceramic electrolyte precursor purification. Distribution runs through just-in-sequence delivery corridors co-located with Stuttgart, Wolfsburg, and Shanghai assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vehicle electrification market functions as a service-attach opportunity where battery management system software subscriptions and predictive maintenance analytics expand faster than hardware replacement cycles. Recurring revenue layers from over-the-air calibration updates and thermal system optimization services now outpace cell and motor unit sales growth.
For Market Incumbents: Shield margin position by accelerating captive silicon carbide foundry completion ahead of Korean and Chinese capacity ramps. Secure long-term cathode precursor offtake from Indonesian integrated battery material parks before nickel processing congestion intensifies. ISO 26262 ASIL-D certification investment represents the priority defensive lever against modular assembly specialists. For New Entrants and Emerging Players: UL 2580 battery safety certification fast-track opens fleet operator procurement channels previously locked behind incumbent warranty networks. Target India's National Highways charging infrastructure gap and Brazil's interior logistics corridors where DC fast-charging scarcity constrains established supplier deployment. White-space entry runs through depot-charged electric bus thermal management retrofit programs. For Investors and Strategic Acquirers: Capital is best deployed toward solid-state electrolyte manufacturing specialists resolving sulfide and oxide yield challenges. Five-to-ten-year viability framing favors acquisition targets with ceramic electrolyte precursor purification capabilities and Korean OEM qualification relationships. The signal to watch is 800-volt platform adoption velocity across European premium passenger segments.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term cell offtake contracts with Korean producers secure capacity allocation ahead of MIIT quota enforcement. |
| Silicon Carbide Foundry Investment | In-house SiC wafer fabrication reduces inverter cost exposure to Taiwan and South Korea supply concentration. |
| Software-Defined Vehicle Investment | Battery management system firmware subscriptions generate recurring revenue streams beyond hardware replacement cycles. |
| Geographic Manufacturing Footprint | North American assembly joint ventures qualify for IRA domestic content credits reshaping supplier location decisions. |
| Charging Infrastructure Partnership | DC fast-charging network deployment unlocks fleet operator procurement in India's highway corridors and Brazil's interior states. |
Research Approach
Desk research of vehicle production databases, IHS Markit registration data, and SEC supplier filings preceded structured interviews with OEM platform engineers, tier-one procurement directors, thermal management R&D leads, and fleet operator sustainability officers. Primary fieldwork combined with secondary validation across EPA tailpipe standard filings, MIIT new energy vehicle mandate documentation, and European Commission CO2 compliance records. Bottom-up cell and motor unit shipment aggregation triangulated against top-down OEM platform commitment tracking.
Variance decomposition across propulsion architecture, vehicle class, content per vehicle, and regional production cluster dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level shipment trajectories and value-per-unit evolution modeled battery chemistry transitions and voltage class migration. Forecast inputs incorporated silicon carbide adoption curves and solid-state battery yield improvement timelines without year-specific milestones.
Decision-makers should treat outputs as directional under continued lithium-ion cost reduction and 800-volt platform proliferation assumptions; material deviation in solid-state commercialization timelines or cathode raw material supply disruption would warrant model refresh. Forecasts reflect documented base-case assumptions regarding regulatory enforcement consistency and charging infrastructure deployment velocity. Recalibration cycles align with material shifts in MIIT mandate stringency, IRA credit phase-out schedules, and European Commission CO2 trajectory revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Commercial Electric Vehicle Resistive Braking System Market
Electric Vehicles
Electric Vehicle Transmission Market
Electric Vehicles
ASEAN E-Bike Market
Electric Vehicles
ASEAN Countries Plug-In Hybrid Electric Vehicle Battery Market
Electric Vehicles
Europe Electric Car Market
Electric Vehicles
Construction Electric Vehicle Market
Electric Vehicles
Electric Vehicle Liquid-Cooled Charging Connector Market
Electric Vehicles
Electric Vehicle Rental Market
Electric Vehicles
India Electric Vehicle Market
Electric Vehicles
United States Electric Pick-Up Trucks Market
Electric Vehicles
Electric Vehicle Reducer Market
Electric Vehicles
United Kingdom E-Bike Market
Electric Vehicles
UK Electric Bus Battery Pack Market
Electric Vehicles
Electric Vehicle Lithium-Ion Battery Market
Electric Vehicles
Asia-Pacific Lithium-Ion Battery for Electric Vehicle Market
Electric Vehicles
North America Electric Vehicle (EV) Fluids Market