
 Road Profile Laser Sensor Market | 2026-2036
Road Profile Laser Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Road Profile Laser Sensor Market Analytics
The EU Green Deal's infrastructure resilience targets are consolidating investment in precision road monitoring equipment across member states. SICK AG leverages its industrial sensor heritage to dominate calibration-intensive European contracts. Micro-Epsilon anchors its position through sub-micron resolution R&D for OEM integration programs. Pavemetrics Systems Inc. specializes in turn-key mobile profiling platforms that sustain recurring service revenue from North American state DOTs.
A road profile laser sensor projects structured light or time-of-flight laser beams onto pavement surfaces to capture longitudinal and transverse elevation data with sub-millimeter accuracy, typically operating at sampling frequencies exceeding 16 kHz for highway-speed deployment. Its primary purpose is to quantify International Roughness Index values, rut depths, and macrotexture for asset management and regulatory compliance. Mobile sensors command the largest installed base due to continuous-scan efficiency on active roadways, while integrated systems capture concentrated margin pools from automated pavement evaluation vehicles. Infrastructure evaluation leads application demand as agencies shift from periodic spot-checks to network-level condition surveys.
ISO 13473 governs pavement texture measurement protocols, the EU F-Gas Regulation shapes equipment portability standards, and China's GB/T 26764 dictates domestic profiler certification requirements. These frameworks collectively mandate traceable calibration chains that elevate replacement costs for non-compliant legacy equipment. Stakeholders must weigh captive sensor development against modular procurement as regulatory divergence between jurisdictions accelerates.
Market Dynamics
Highway maintenance agencies are replacing contact-based profilers with non-destructive laser systems as ISO 13473 compliance mandates tighten surface measurement protocols across major road networks. This regulatory compression is accelerating capital rotation toward mobile profiling platforms capable of network-level condition surveys.
Growth Catalysts
- ISO 13473 Protocol Harmonization:International standardization of pavement texture measurement creates procurement clarity for highway agencies upgrading legacy contact-based systems.
- Network-Level Asset Management:Transportation departments shift from periodic spot-checks to continuous road condition monitoring, expanding mobile sensor deployment.
- Laser Triangulation Advances:Sub-millimeter accuracy at highway speeds enables real-time International Roughness Index quantification without traffic disruption.
Market Restraints
- Calibration Chain Costs:Traceable calibration requirements under EU F-Gas Regulation and GB/T 26764 elevate lifecycle ownership costs for precision laser sensors.
- Optics Supply Concentration:Specialized laser diode and detector fabrication concentrates among German and Japanese component suppliers, creating input bottlenecks.
- Electromechanical Substitutes:Accelerometer-based inertial profilers retain cost advantages for lower-speed municipal applications, limiting addressable market expansion.
Strategic Opportunities
- Provincial Transport Bureau Modernization:China's MEE-mandated road quality audits accelerate replacement cycles for manual measurement tools in second-tier provinces.
- AI-Enhanced Defect Classification:Machine vision integration with laser profiling enables automated crack detection and predictive maintenance scheduling.
- Service Revenue Unbundling:Turn-key platform vendors capture recurring calibration and data analytics contracts separate from hardware sales.
Industry Challenges
- Metrology Talent Scarcity:Shortage of technicians trained in laser interferometry and pavement engineering slows deployment scaling for state DOTs.
- Legacy System Integration:Proprietary data formats from incumbent profiler fleets complicate sensor retrofitting and network data aggregation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Road Profile Laser Sensor Market |
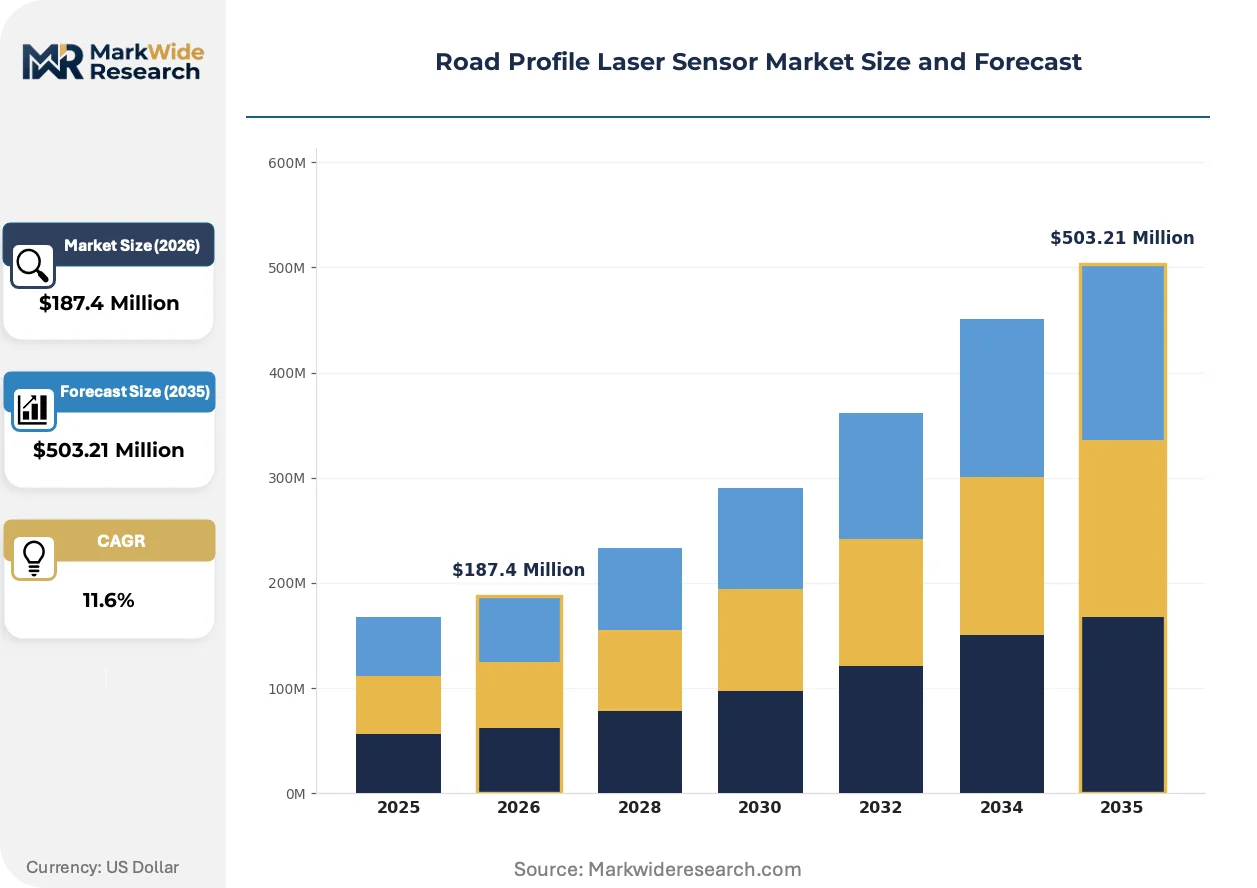
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Sensors, Mobile Sensors, Handheld Sensors, Integrated Systems Application: Infrastructure Evaluation, Surface Profiling, Vehicle Testing, Quality Control End User: Construction Companies, Government Agencies, Automotive Manufacturers, Research Institutions Installation Type: Permanent Installation, Portable Installation, Semi-Permanent Installation, Temporary Setup |
| Companies Covered | LMI Technologies Inc., Micro-Epsilon, Schmitt Industries Inc., SICK AG, FARO Technologies Inc., Trimble Inc., Teledyne Technologies Incorporated, ViaTech AS, Pavemetrics Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Road Profile Laser Sensor Market Evolving Landscape
Sensor fusion architectures are redefining competitive positioning as vendors combine laser profiling with complementary measurement modalities. This convergence is compressing hardware differentiation while expanding software and analytics value capture.
Multi-line laser triangulation is absorbing market share from single-point time-of-flight systems in high-speed profiling applications. German highway agencies specify multi-line configurations for simultaneous longitudinal and transverse capture. The technology is absorbing calibration complexity into integrated sensor heads, reducing field maintenance requirements.
EU F-Gas Regulation portability standards are reshaping equipment design priorities for mobile deployment. Compliance mandates sealed optical paths and reduced refrigerant-dependent cooling systems. European OEM integration programs face compressed certification timelines as member states align enforcement.
State DOTs are unbundling hardware procurement from data analytics subscriptions. North American agencies now specify open data formats and API access as mandatory bid requirements. This purchasing pattern shift is most visible in California and Texas, where multi-year service contracts now exceed sensor hardware value in total contract awards.
Road Profile Laser Sensor Market Segmentation
Procurement patterns in the road profile laser sensor market diverge sharply across deployment contexts, with highway-speed mobile systems commanding fundamentally different technical specifications than laboratory-grade static units. Understanding these segment boundaries clarifies where upgrade capital concentrates and which installation modes capture recurring service revenue.
Product Type:
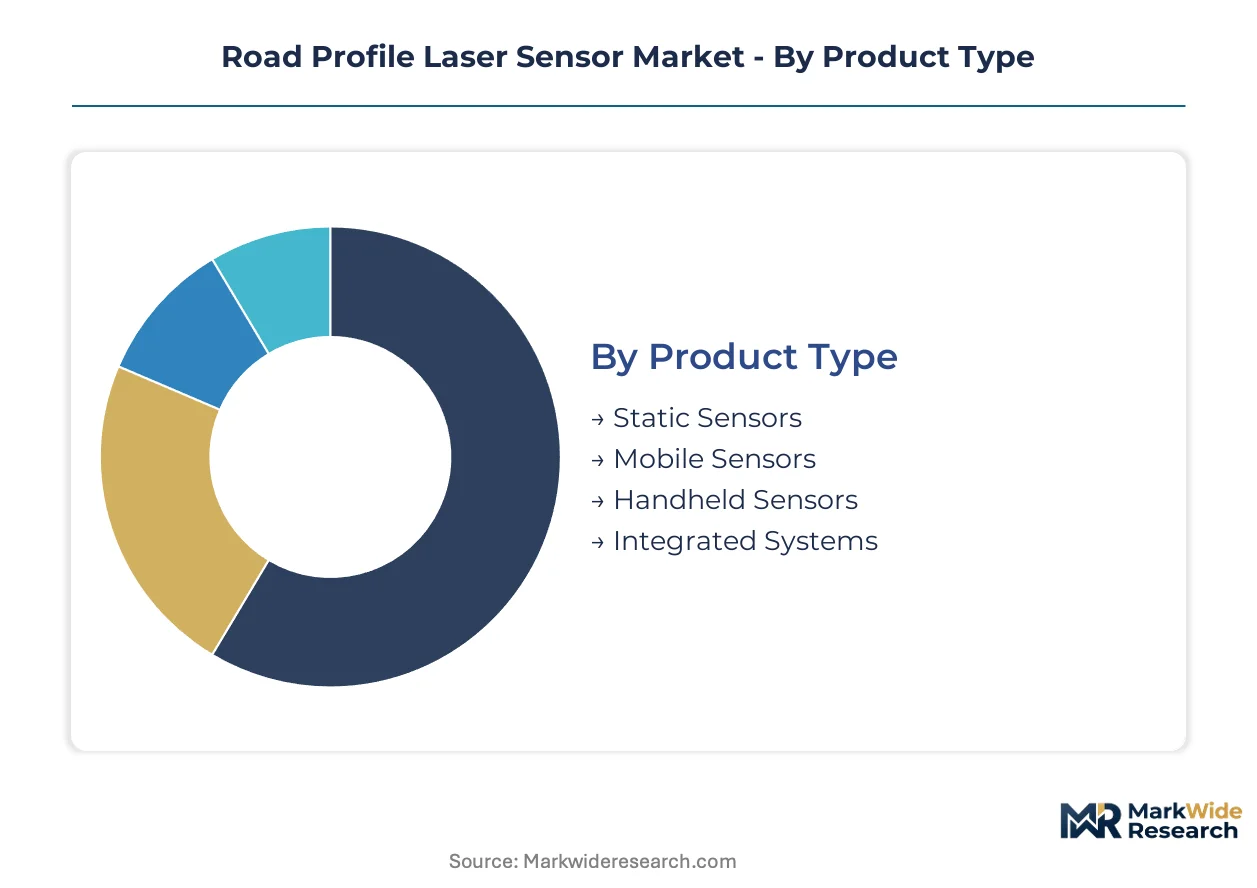
Replacement cycles accelerate where ISO 13473 compliance deadlines force retirement of contact-based legacy equipment, with mobile platforms absorbing the largest capital allocations.
- Mobile Sensors:These highway-speed units mount on dedicated profiling vehicles and capture continuous longitudinal elevation data at sampling frequencies exceeding 16 kHz. German KBA-certified configurations dominate European procurement, while China's provincial transport bureaus specify MEE-aligned variants for network-level audits.
- Integrated Systems:Turn-key automated pavement evaluation vehicles combine laser triangulation with inertial reference frames and GPS positioning in factory-calibrated packages. North American state DOTs favor these for multi-year service contracts where data analytics revenue exceeds hardware value.
- Static Sensors:Laboratory-grade units for controlled pavement specimen analysis with sub-micron repeatability.
- Handheld Sensors:Portable spot-measurement devices for municipal maintenance crews verifying localized surface defects.
Volume placements concentrate in Mobile Sensors; the faster expansion belongs to Integrated Systems.
Application:
Cost tiering separates regulatory-mandated infrastructure surveys from discretionary quality control budgets, with compliance-driven applications commanding premium pricing.
- Infrastructure Evaluation:Network-level condition surveys for highway asset management represent the largest addressable demand pool. Japan's METI-funded road maintenance programs and US state DOT pavement management systems drive specification convergence around multi-line laser triangulation.
- Surface Profiling:Real-time macrotexture and rut depth quantification for construction acceptance testing. European contractors face EU F-Gas Regulation portability requirements that elevate sealed optical path specifications.
- Vehicle Testing:Proving ground applications for suspension development and NVH validation.
- Quality Control:Manufacturing line inspection for pavement material producers.
Capital deployment tilts toward Infrastructure Evaluation; Surface Profiling climbs fastest as construction acceptance protocols tighten.
End User:
Customer type determines procurement modality, with government agencies mandating open data formats while commercial buyers prioritize turn-key integration.
- Government Agencies:Highway departments and transport ministries specify traceable calibration chains under ISO 13473, EU F-Gas Regulation, and GB/T 26764. California and Texas DOTs now require API access and subscription-based analytics in RFPs.
- Construction Companies:Tier-one contractors building expressways in China's second-tier provinces upgrade from manual measurement to laser-based acceptance testing.
- Automotive Manufacturers:Proving ground operators and suspension engineering teams.
- Research Institutions:Universities and national laboratories developing next-generation profiling algorithms.
Government Agencies anchor installed base expansion; Construction Companies gain share fastest as provincial modernization accelerates.
Installation Type:
Supply concentration in German and Japanese optics suppliers shapes which installation modes achieve cost-competitive scaling.
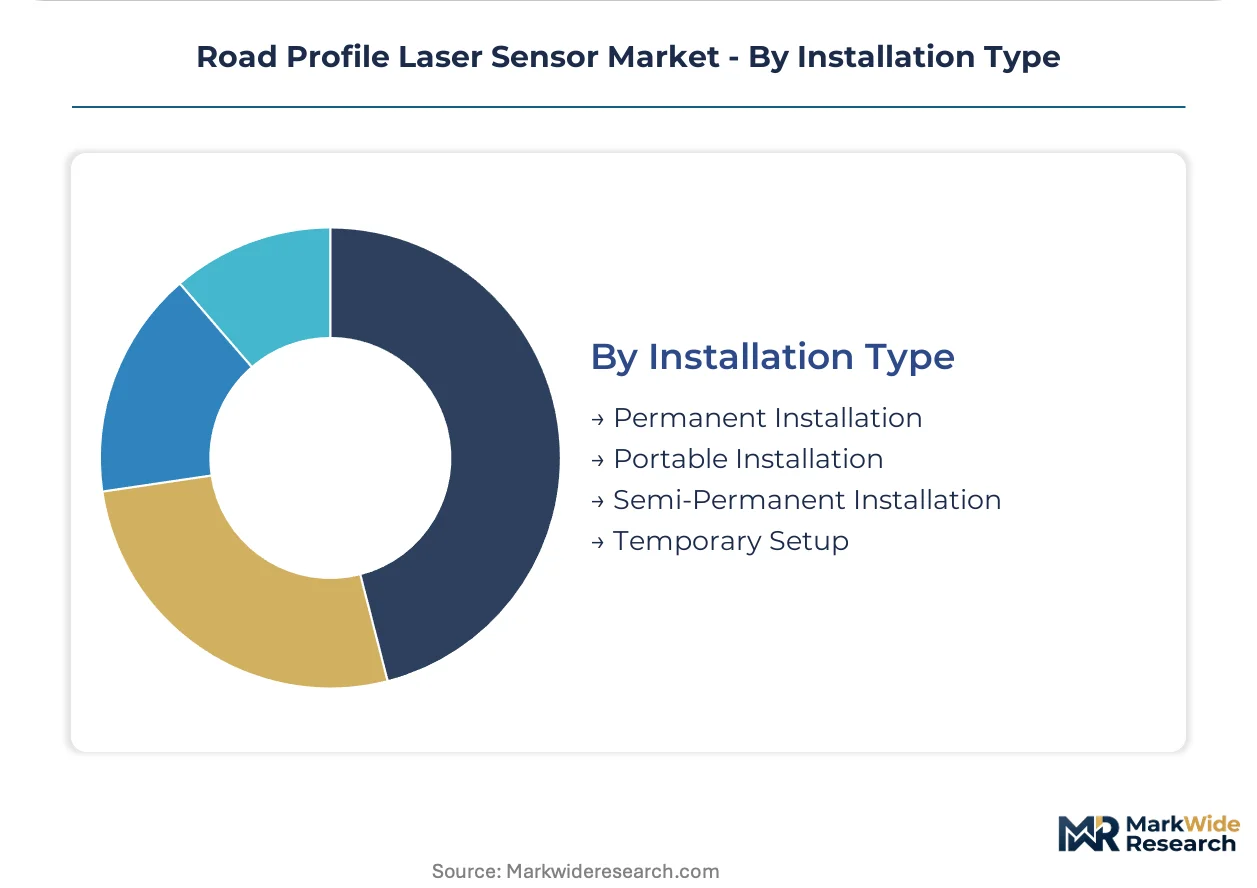
- Portable Installation:Vehicle-mounted configurations dominate mobile profiling, with rapid deployment between project sites. EU F-Gas Regulation compliance mandates sealed optical paths that complicate field cooling system design.
- Permanent Installation:Fixed monitoring stations at critical bridge decks or tunnel portals. These capture concentrated margins from automated alert systems but face limited addressable volume.
- Semi-Permanent Installation:Seasonal deployment on dedicated profiling fleets with winter storage protocols.
- Temporary Setup:Short-duration rental configurations for construction project acceptance.
Hardware shipments concentrate in Portable Installation; Permanent Installation shows steepest expansion trajectory where critical infrastructure monitoring budgets expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich's industrial sensor corridor anchors European procurement for ISO 13473-compliant mobile profiling systems. German KBA certification standards diffuse across neighboring highway networks. Japanese Kanto region manufacturers supply precision optics to global profiler integrators.
United States
State DOTs in California and Texas mandate API-accessible data formats in multi-year service contracts. NHTSA-influenced pavement management protocols accelerate replacement of contact-based legacy equipment. Midwest highway maintenance depots concentrate mobile sensor deployment for interstate network surveys.
Germany
KBA-certified configurations dominate Autobahn maintenance procurement under tightening EU F-Gas Regulation compliance deadlines. Bavarian sensor manufacturers supply sealed optical path systems for portable deployment. Rhine-Ruhr industrial clusters integrate laser triangulation into automated pavement evaluation vehicle production.
China
Provincial transport bureaus in second-tier provinces execute MEE-mandated road quality audits using GB/T 26764-certified profilers. Yangtze River Delta equipment integrators scale mobile platform assembly. Sichuan-Chongqing highway agencies modernize from manual measurement tools to non-destructive laser alternatives.
Japan
METI-funded road maintenance programs drive specification convergence around multi-line laser triangulation systems. Kansai region precision optics fabricators supply laser diode components to global profiler manufacturers. Nagoya automotive proving grounds deploy integrated profiling systems for NVH validation protocols.
Road Profile Laser Sensor Market Competitive Landscape
The competitive structure tilts toward industrial sensor heritage players with established calibration service networks. Tier-one vendors capture premium positioning through traceable metrology chains, while mid-scale specialists penetrate provincial modernization cycles in emerging markets. Two archetypes dominate: precision optics fabricators with sub-micron resolution capabilities, and turn-key platform integrators with recurring service revenue models. Capacity expansion in Asian assembly operations and strategic partnerships for AI-enhanced defect classification represent the dominant competitive vectors.
Within the precision optics tier, Micro-Epsilon exemplifies sub-micron resolution R&D positioning for OEM integration programs. SICK AG anchors European calibration-intensive contract capture through its industrial sensor heritage. Pavemetrics Systems Inc. occupies a position representing turn-key mobile profiling specialists serving North American state DOT subscription models.
| Leading Market Players |
|---|
| LMI Technologies Inc. |
| Micro-Epsilon |
| Schmitt Industries Inc. |
| SICK AG |
| FARO Technologies Inc. |
| Trimble Inc. |
| Teledyne Technologies Incorporated |
| ViaTech AS |
| Pavemetrics Systems Inc. |
| Others |
Value Network & Pricing Analysis
Germanium and indium price indices on the London Metal Exchange cascade through laser diode fabrication costs into tiered equipment pricing. Procurement officers at state DOTs and provincial transport bureaus face compressed negotiation windows as optical component lead times extend.
Pricing Analysis
Outcome-based pricing anchored to network survey throughput dominates state DOT procurement, with California and Texas agencies specifying per-mile data delivery contracts over hardware ownership. Price differentiation rests on ISO 13473 certification tier and sealed optical path compliance under EU F-Gas Regulation. Cost compression in standard mobile sensor configurations intensifies as Chinese equipment integrators scale assembly capacity. Municipal maintenance crews exhibit highest price sensitivity, while federal highway agencies absorb premium pricing for traceable calibration chains.
Supply Chain Analysis
Regional distribution centers in Munich, Yokohama, and Shanghai coordinate hub-and-spoke fulfillment for profiler integrators across three continents. Laser diode fabrication concentrates in Germany and Japan, with detector arrays sourcing from South Korean foundries. Supply chain risk centers on single-source vulnerability for sub-micron optical components subject to export control classifications. Distribution runs through certified metrology service partners who maintain field calibration equipment pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The road profile laser sensor market sits in a technology-transition phase as multi-line laser triangulation displaces single-point time-of-flight systems in highway-speed applications.
For Market Incumbents: Hedge against margin erosion in mobile sensor commoditization by deepening captive supply of sealed optical path assemblies. Accelerate R&D investment in AI-enhanced defect classification software to capture recurring analytics revenue that exceeds hardware value in North American state DOT contracts. For New Entrants and Emerging Players: Launch via equipment-as-a-service models targeting China's second-tier provincial transport bureaus executing MEE-mandated modernization cycles. Penetrate the handheld sensor segment for municipal spot-measurement applications where incumbent presence remains thin and price sensitivity creates entry tolerance. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision optics fabricators with sub-micron resolution capabilities in Germany's Bavarian industrial corridor. Long-term viability hinges on software-analytics revenue attachment rates exceeding hardware depreciation cycles. Monitor GB/T 26764 certification timeline acceleration as inflection indicator for Chinese market access premium.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Line Laser Triangulation R&D | Captures German KBA certification requirements for simultaneous longitudinal-transverse data capture. |
| AI-Enhanced Defect Classification Integration | Enables predictive maintenance scheduling for Japan's METI-funded road maintenance programs. |
| Sealed Optical Path Manufacturing Scale-Up | Secures EU F-Gas Regulation compliance for portable deployment across member state highway networks. |
| Calibration Service Network Expansion | Generates recurring revenue streams from ISO 13473-mandated traceability requirements. |
| Provincial Transport Bureau Partnership Programs | Accelerates penetration of China's MEE-mandated road quality audit modernization cycles. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with highway maintenance directors, pavement engineering consultants, laser sensor procurement officers, and metrology calibration technicians combined with secondary validation from KBA type-approval databases, MEE audit protocols, and state DOT RFP archives. Bottom-up equipment shipment tallies and top-down infrastructure budget appropriations underwent triangulation to converge volume estimates.
Data-stream reconciliation across mobile sensor deployments, integrated system deliveries, and static laboratory unit placements shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application context, end-user category, and installation mode alongside regional regulatory cluster alignment. CAGRs derived from slope-log regression on normalized deployment curves, with highway-speed sampling frequency thresholds and GB/T 26764 certification penetration curves serving as industry-specific forecast inputs.
Regulatory enforcement delays, optical component export restrictions, and provincial budget freeze triggers are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding ISO 13473 harmonization timelines and EU F-Gas Regulation implementation consistency. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Vehicle As a Service Market
Smart Transportation Solutions
US Smart Highway Market
Smart Transportation Solutions
Bike Sharing Market
Smart Transportation Solutions
North America IoT Transportation Market
Smart Transportation Solutions
Fleet Management Software Market
Smart Transportation Solutions
Global IoT Fleet Management Market
Smart Transportation Solutions
Europe Connected Cars Market
Smart Transportation Solutions
Smart Transportation Solution Market
Smart Transportation Solutions
Global Smart Commute Market
Smart Transportation Solutions
Off-Street Parking Management System Market
Smart Transportation Solutions
Thailand Ride Hailing Market
Smart Transportation Solutions
Transportation Vehicle Automated Passenger Counting (APC) System Market
Smart Transportation Solutions
Road Weather Information Systems (RWIS) Market
Smart Transportation Solutions
Intelligent Airways Transportation Market
Smart Transportation Solutions
Global Integrated Traffic System Market
Smart Transportation Solutions
France Ridesharing Market