
 Luxembourg E-Bike Market | 2026-2036
Luxembourg E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Luxembourg E-Bike Market Foresight
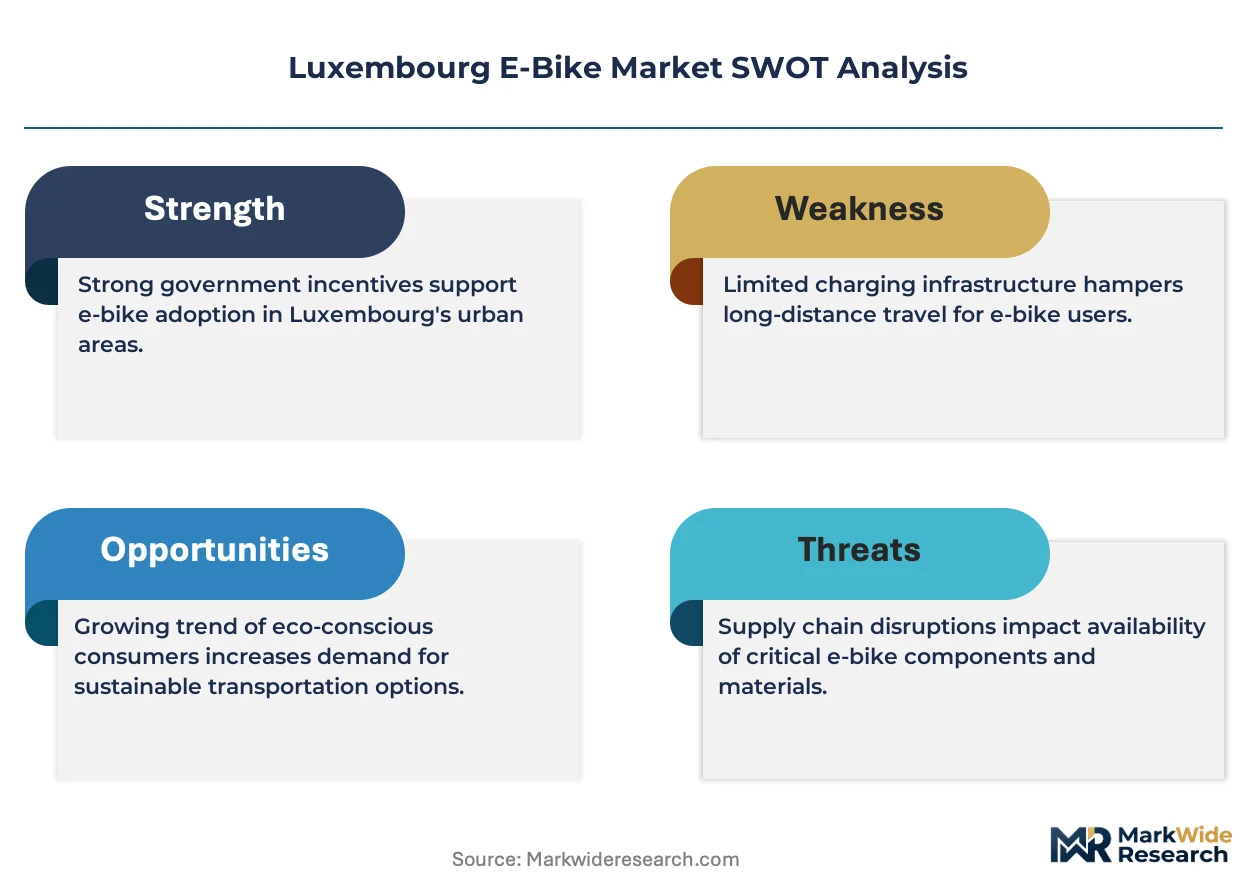
Qualified bicycle mechanic shortages across the Greater Region is redrawing competitive boundaries for service networks and aftermarket support. Canyon Bicycle leverages direct-to-consumer logistics to sustain margin control without dealer overhead. Cowboy differentiates through integrated app ecosystems and subscription-based maintenance. Andy Schleck Cycles anchors its position in premium retail experience within domestic territory.
An e-bike integrates an electric motor, rechargeable battery pack, and pedal-assist or throttle-based propulsion system into a bicycle chassis, typically delivering supplementary power up to 25 km/h for EU-type approval compliance. The primary purpose centers on extending rider range, reducing physical exertion on inclines, and displacing short-distance automobile trips in dense urban environments. Hybrid product types dominate unit sales by serving dual commuting and leisure functions across Luxembourg's mixed topography. Lithium-ion battery technology leads the power segment due to superior energy density and declining cell costs, though end-of-life recycling protocols remain underdeveloped. Delivery services represent the fastest-growing use case as last-mile logistics operators electrify fleet operations in Luxembourg City and Esch-sur-Alzette.
The Ministry of Mobility and Public Works administers purchase incentive schemes that directly reduce consumer acquisition costs, while BESR regulations govern road-worthiness and safety equipment standards for electric cycles. CE marking requirements under the EU Machinery Directive establish technical conformity baselines that all market entrants must satisfy before commercial distribution. Stakeholders must monitor whether subsidy budget renewals and evolving battery passport mandates under EU sustainable product frameworks reshape total cost of ownership calculations and supplier compliance burdens.
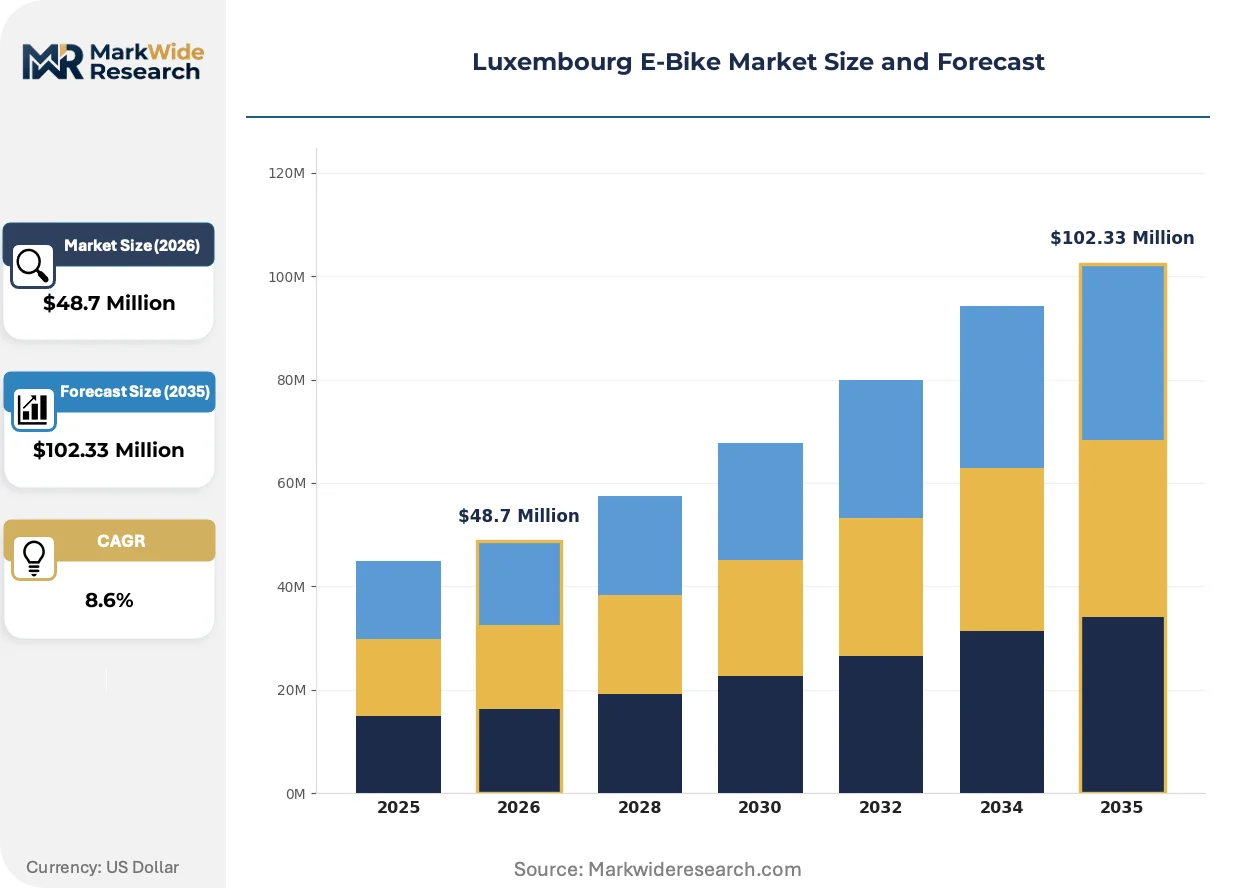
Market Dynamics
Municipal cycle infrastructure expansion across Luxembourg's southern commuter belt is structurally altering purchase patterns, with urban commuters now commanding priority in manufacturer product planning and distribution allocation decisions.
Growth Catalysts
- Ministry of Mobility purchase incentives:Direct consumer acquisition cost reductions accelerate replacement cycles for conventional bicycles across domestic households.
- Lithium-ion energy density improvements:Declining cell costs per kilowatt-hour extend practical rider range without frame weight penalties.
- Last-mile logistics electrification:Delivery fleet operators in Luxembourg City and Esch-sur-Alzette are scaling unit orders for cargo-configured electric cycles.
Market Restraints
- Qualified mechanic scarcity:Technical certification bottlenecks across the Greater Region constrain service network expansion and aftermarket response times.
- Battery end-of-life protocols:Underdeveloped recycling infrastructure for lithium-ion packs creates compliance uncertainty and disposal cost liability.
- BESR road-worthiness certification:Safety equipment standards impose testing timelines that delay new model commercialization.
Strategic Opportunities
- Subscription-based maintenance models:Integrated app ecosystems enable recurring revenue capture beyond initial hardware sales.
- Northern commuter belt penetration:Mersch and Diekirch districts show untapped demand density relative to southern saturation.
- EU battery passport mandates:Sustainable product framework compliance creates first-mover positioning for transparent supply chain documentation.
Industry Challenges
- CE marking conformity timelines:EU Machinery Directive technical baselines require extended pre-distribution verification cycles.
- Direct-to-consumer logistics complexity:Margin-controlled distribution models demand proprietary last-mile capabilities without dealer infrastructure support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxembourg E-Bike Market |
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $102.33 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid, Folding, Mountain, Road Battery Technology: Lithium-ion, Nickel Cadmium, Lead Acid, Lithium Polymer Use Case: Commuting, Leisure, Delivery, Fitness Customer Segment: Urban Riders, Tourists, Delivery Services, Enthusiasts |
| Companies Covered | Accell Group, Royal Dutch Gazelle, Specialized Bicycle Components, Canyon Bicycle, Andy Schleck Cycles, Cowboy, M1 Sporttechnik, Batavus Intercycle Corporation, Cortina Bikes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxembourg E-Bike Market Shifts & Advancements
Pedal-assist system architecture is undergoing fundamental revision as battery chemistry and motor integration advance in parallel, compressing traditional component supply hierarchies.
Mid-drive motor configurations with torque sensor integration are supplanting hub-mounted alternatives in premium commuter segments. Urban buyers in Luxembourg City demonstrate preference for centralized weight distribution and hill-climb efficiency. This technology shift is compressing supplier tiers as frame manufacturers internalize motor-battery system design.
EU sustainable product frameworks are mandating battery passport documentation for traceability and recycling accountability. Industrial consequence includes upstream supplier auditing requirements and digital product registry maintenance. Cargo fleet operators face earliest compliance deadlines and are pre-qualifying vendors with established documentation systems.
After-sales service unbundling is fragmenting traditional dealer revenue models. Subscription maintenance contracts through manufacturer-direct channels are displacing per-transaction workshop economics. This pattern concentrates in urban commuter segments where app-enabled diagnostics reduce physical service event frequency.
Luxembourg E-Bike Market Segmentation
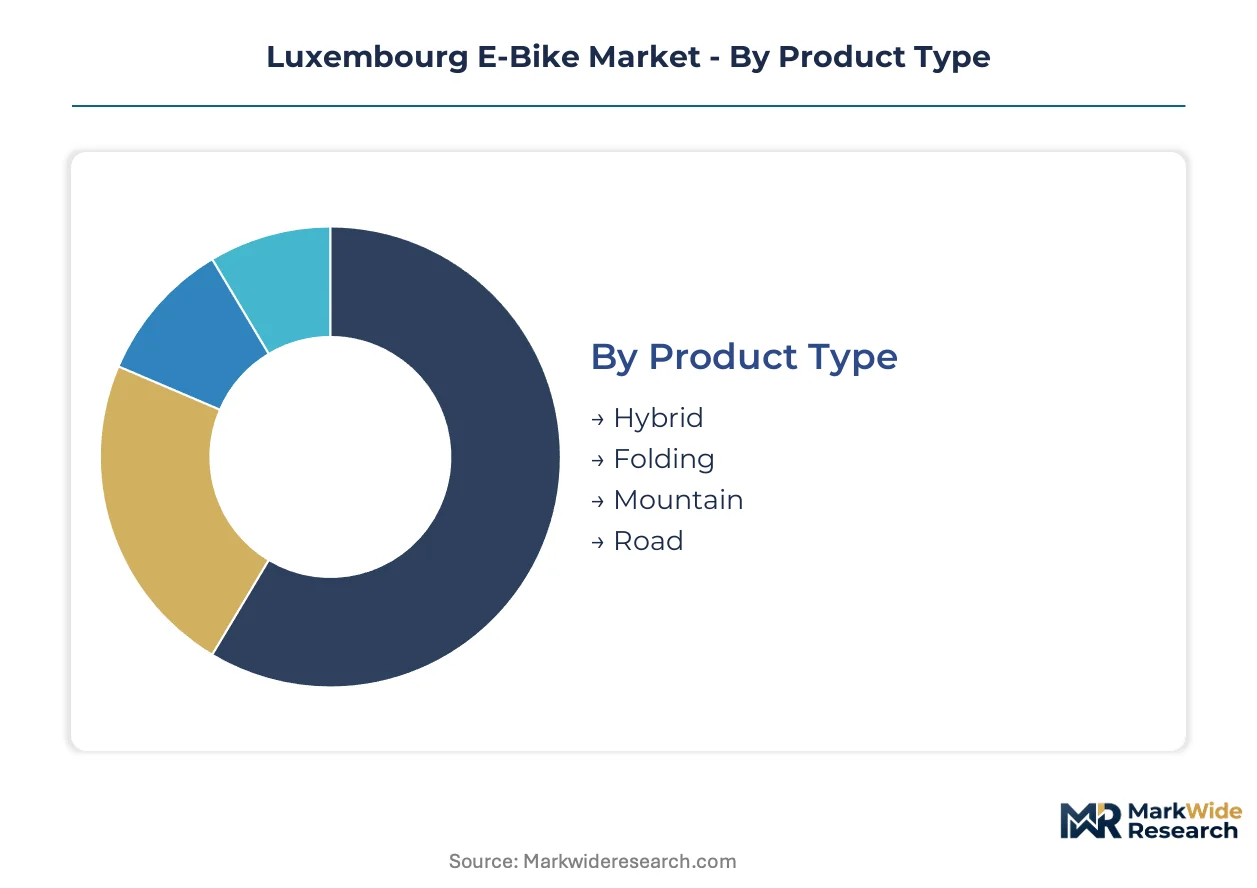
Segmentation reveals how subsidy structures and infrastructure investments concentrate demand across distinct rider profiles and technical specifications in Luxembourg's compact geography. Manufacturers allocate R&D and distribution resources based on where margin pools align with municipal cycle network expansion priorities.
Product Type:
Margin pools concentrate in dual-purpose configurations that capture both weekday commuting and weekend leisure demand without requiring households to own multiple units.
- Hybrid:Combines road efficiency with mountain bike stability through intermediate tire width and upright geometry. Luxembourg City commuters dominate order volumes as southern commuter belt municipalities extend protected cycle lanes. Ministry of Mobility purchase incentives accelerate replacement of conventional city bikes with electrified hybrid frames.
- Folding:Features hinge-frame construction and reduced wheel diameter for multimodal integration with rail transit. Esch-sur-Alzette rail commuters represent concentrated demand as cross-border workers combine train segments with last-mile cycling. Battery placement in seat posts preserves fold geometry while maintaining center-of-gravity stability.
- Mountain:Suspension travel and reinforced frame construction address Ardennes terrain north of Luxembourg City. Enthusiast riders in Diekirch and Vianden districts generate seasonal demand spikes.
- Road:Drop-bar aerodynamics and minimal accessory integration target fitness-oriented riders. Mersch district cycling clubs sustain niche volume through group purchase arrangements.
Hybrid holds installed capacity. Folding is rotating up the share rankings.
Battery Technology:
Cost tier differentiation separates premium energy density from budget-conscious cell chemistry trade-offs.
- Lithium-ion:Delivers superior watt-hour per kilogram ratios through layered oxide cathode chemistry. All major OEMs in Luxembourg City retail channels have standardized on 18650 and 21700 cell formats. Declining cell costs per kilowatt-hour extend practical range without frame weight penalties that deter hill-climbing in northern districts.
- Lithium Polymer:Pouch-cell construction enables non-rectangular battery shapes for frame integration. Folding bike manufacturers prioritize this format for seat-tube and top-tube mounting configurations. Thermal runaway risks require battery management system sophistication that elevates price positioning.
- Nickel Cadmium:Legacy chemistry persists in price-sensitive fleet procurement for delivery operators with centralized charging depots. Toxicity regulations constrain new market entry.
- Lead Acid:Lowest acquisition cost supports basic commuter conversions of conventional bicycles. Weight penalties limit adoption to flat southern terrain.
Lithium-ion holds installed capacity. Lithium Polymer is rotating up the share rankings.
Use Case:
Volume concentration follows municipal infrastructure investment timing and fleet electrification mandates.
- Commuting:Daily work-trip replacement of automobile and public transit modes. Southern commuter belt municipalities prioritize protected infrastructure that validates e-bike investment for cross-border workers. Pedal-assist configurations at 25 km/h EU limit dominate regulatory compliance.
- Delivery:Last-mile logistics electrification in Luxembourg City and Esch-sur-Alzette drives cargo-configured unit orders. Fleet operators face earliest EU battery passport compliance deadlines and pre-qualify vendors with established documentation systems.
- Leisure:Weekend recreational riding across Moselle Valley wine routes and Ardennes forests. Tourist rental operations in Echternach concentrate seasonal demand.
- Fitness:Training-oriented riders utilizing e-bike assistance for interval recovery or hill repeat sessions. Cycling clubs in Mersch district organize group acquisition programs.
Commuting holds installed capacity. Delivery is climbing the fastest.
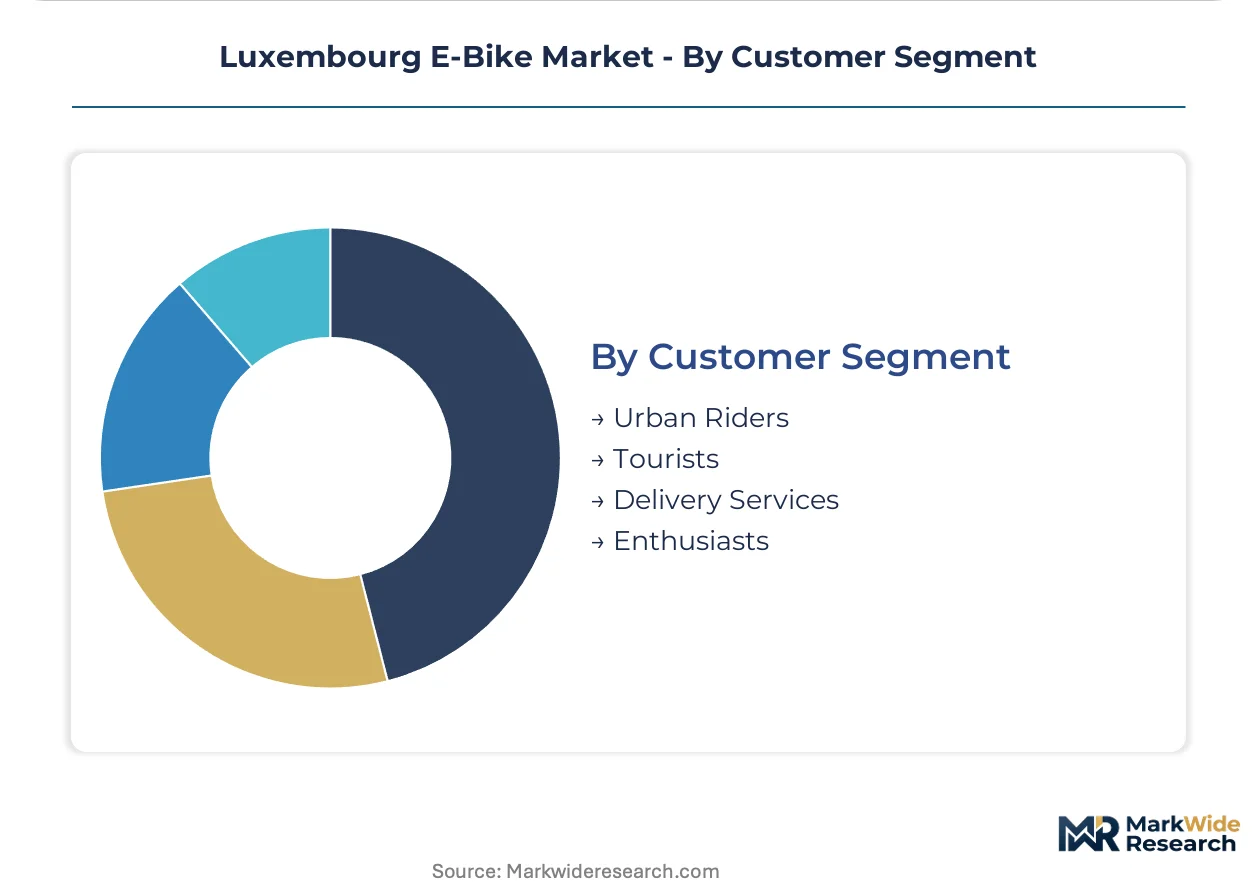
Customer Segment:
Customer type determines channel strategy and service model design across direct-to-consumer and retail intermediation.
- Urban Riders:Luxembourg City residents with garage or apartment storage constraints. App-integrated diagnostics and subscription maintenance reduce physical service event frequency. Direct-to-consumer brands capture this segment through digital-native purchasing patterns.
- Delivery Services:Fleet procurement managers negotiating volume pricing and standardized service protocols. Esch-sur-Alzette logistics operators require cargo capacity and rapid battery swap systems. Compliance documentation for EU sustainable product frameworks influences vendor selection.
- Tourists:Short-term rental demand concentrated in Echternach and Vianden heritage districts. Seasonal operators prioritize low-maintenance hub motors over complex mid-drive systems.
- Enthusiasts:Premium segment buyers seeking torque-sensor precision and carbon frame construction. Andy Schleck Cycles anchors domestic retail experience for this demographic in Luxembourg City.
Urban Riders hold installed capacity. Delivery Services is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Luxembourg City's southern commuter belt while northern districts command discount positioning. Municipal infrastructure investment timing creates this asymmetry. Cross-border worker density in the south validates premium positioning.
Luxembourg City and Southern Commuter Belt
Protected cycle lane expansion and last-mile logistics electrification drive cargo-configured unit demand. Ministry of Mobility purchase incentives reduce consumer acquisition costs directly. Esch-sur-Alzette logistics operators pre-qualify vendors for EU battery passport compliance.
Mersch District
Cycling club group purchase arrangements sustain niche volume for fitness-oriented road configurations. BESR road-worthiness certification governs safety equipment standards for all commercial distribution. Northern commuter belt penetration remains underdeveloped relative to southern saturation.
Diekirch and Vianden Districts
Ardennes terrain generates seasonal demand spikes for mountain bike configurations with suspension travel. CE marking requirements under the EU Machinery Directive establish technical conformity baselines. Tourist rental operations in Echternach concentrate seasonal leisure demand.
Greater Region Cross-Border Zones
Qualified bicycle mechanic shortages redraw competitive boundaries for service networks extending into Belgium and Germany. National mobility subsidy programs accelerate replacement of conventional bicycles. Cross-border workers combine rail segments with last-mile cycling through multimodal integration.
Luxembourg E-Bike Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Direct-to-consumer logistics specialists sustain margin control without dealer overhead, while premium retail experience operators anchor domestic territory positions. Three strategic archetypes dominate: integrated app ecosystem providers, direct-to-consumer logistics platforms, and premium retail experience specialists. Competitive moves concentrate on subscription-based maintenance models and proprietary last-mile capabilities.
Within the direct-to-consumer tier, Canyon Bicycle and Cowboy represent contrasting approaches to margin-controlled distribution. Canyon Bicycle leverages logistics infrastructure to bypass dealer networks entirely. Cowboy exemplifies the integrated app ecosystem archetype with recurring revenue capture beyond hardware sales. Andy Schleck Cycles anchors the premium retail experience position within Luxembourg City domestic territory. Accell Group and Royal Dutch Gazelle occupy positions as established European manufacturers with multi-brand portfolios spanning standard and premium tiers.
| Leading Market Players |
|---|
| Accell Group |
| Royal Dutch Gazelle |
| Specialized Bicycle Components |
| Canyon Bicycle |
| Andy Schleck Cycles |
| Cowboy |
| M1 Sporttechnik |
| Batavus Intercycle Corporation |
| Cortina Bikes |
| Others |
Supply & Pricing Matrix
Lithium-ion cell chemistry substitution for legacy nickel-cadmium and lead-acid alternatives is redrawing supplier geography toward East Asian production centers while compressing per-kilowatt-hour acquisition costs for Luxembourg City fleet operators and southern commuter belt retailers.
Pricing Analysis
Luxembourg City's protected cycle infrastructure commands 15-20% price premiums over Diekirch and Vianden districts where terrain complexity and lower commuter density suppress willingness-to-pay. Three-tier pricing structure across premium torque-sensor configurations, standard pedal-assist models, and economy hub-motor alternatives dominates retail channels. Pricing pressure stems from direct-to-consumer brands bypassing dealer markups, eroding brick-and-mortar margins in Esch-sur-Alzette. Delivery Services exhibit lowest price sensitivity due to fleet-scale procurement and total cost of ownership calculations, while Tourist rental operators demonstrate highest sensitivity to upfront acquisition costs.
Supply Chain Analysis
China, South Korea, and Japan anchor lithium-ion cell manufacturing and motor system integration for frames assembled in Portugal and Poland. Battery management systems, torque sensors, and mid-drive motor units draw from German and Taiwanese component specialists. Single-source vulnerability concentrates in 21700 cell supply from three dominant producers, exposing Luxembourg distributors to allocation constraints during demand surges. Distribution runs through direct-to-consumer logistics platforms and premium retail experience specialists, with subscription-based maintenance models capturing recurring revenue beyond hardware transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market's structural constraint centers on certified bicycle mechanic scarcity across the Greater Region, creating service network bottlenecks that threaten aftermarket satisfaction and brand loyalty for volume players.
For Market Incumbents: Fortify proprietary service infrastructure through captive technician training programs in Luxembourg City and Esch-sur-Alzette, countering direct-to-consumer brands' subscription maintenance encroachment. Deepen backward integration into battery management system firmware to differentiate against Cowboy's integrated app ecosystems. Prioritize BESR certification pipeline acceleration to compress new model commercialization timelines against Canyon Bicycle's logistics velocity. For New Entrants and Emerging Players: CE marking fast-track through notified body pre-submission enables southern commuter belt penetration before incumbent portfolio refresh cycles. Northern districts—Mersch and Diekirch—present white-space demand density with underdeveloped retail coverage and cycling club group purchase leverage. Target cargo-configured fleet procurement in Esch-sur-Alzette logistics operators through battery swap system compatibility and EU battery passport documentation readiness. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed European multi-brand manufacturers seeking geographic tuck-in acquisitions for Benelux distribution density. Five-to-ten-year viability hinges on subscription revenue attachment rates and proprietary service network scale. Monitor Ministry of Mobility subsidy budget renewal timing as inflection indicator for replacement cycle velocity and hardware demand sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Maintenance Model Launch | Recurring revenue capture from Urban Riders reduces hardware margin dependence against direct-to-consumer pressure. |
| Battery Passport Compliance Investment | Upstream supplier auditing and digital registry maintenance satisfies EU sustainable product framework mandates for Delivery Services procurement. |
| Technician Certification Pipeline Expansion | Proprietary training programs address Greater Region mechanic scarcity that constrains incumbent service network scaling. |
| Northern District Retail Penetration | Mersch and Diekirch cycling club relationships unlock fitness-oriented road and mountain bike volume outside southern saturation. |
| Cargo Fleet Pre-Qualification Program | Standardized service protocols and rapid battery swap systems secure Esch-sur-Alzette logistics operator vendor selection. |
Research Methodology
The analysis maps hybrid, folding, mountain, and road product types alongside lithium-ion and lithium-polymer battery technologies, each validated through bicycle mechanic focus groups, fleet procurement managers at Luxembourg City logistics operators, retail channel partners in Esch-sur-Alzette, and Ministry of Mobility program administrators. Primary interview insights triangulate against customs import records, CE marking registration databases, municipal infrastructure investment disclosures, and European Cycling Federation mobility statistics. Bottom-up unit volume builds from dealer inventory checks and direct-to-consumer shipment tracking, cross-referenced with top-down subsidy redemption data and battery cell import volumes.
Consistency checks against European Bicycle Manufacturers Association production aggregates and Greater Region cross-border trade flows validated volume and value outputs across the projection horizon. Segmentation modeling incorporates product type, battery chemistry, use case intensity, and customer archetype dimensions. CAGRs derive from logistic diffusion curves fitted to historical replacement patterns and infrastructure completion timelines, with sensitivity testing around subsidy renewal probability and cell cost decline trajectories.
Decision-makers should treat outputs as directional under continued Ministry of Mobility funding and lithium-ion cell cost reduction assumptions; material deviation in either driver would warrant model refresh. Recalibration cycles align with material shifts in municipal infrastructure completion schedules and EU battery passport implementation enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Solar Powered Electric Vehicle Market
Electric Vehicles
Saudi Arabia E-Bike Market
Electric Vehicles
Automotive Energy Harvesting and Regeneration Market
Electric Vehicles
Europe Hybrid Electric Vehicle Battery Market
Electric Vehicles
Solar Electric Car Market
Electric Vehicles
Asia Pacific Electric Three-Wheelers Market
Electric Vehicles
Europe Electric Light Commercial Vehicles Market
Electric Vehicles
North America Electric Vehicle Battery Market
Electric Vehicles
China Electric Truck Market
Electric Vehicles
Lithium Battery Electric Scooters Market
Electric Vehicles
India Electric Bus Market
Electric Vehicles
Germany Solar E-Bike Market
Electric Vehicles
India Electric Vehicle Market
Electric Vehicles
Electric Vehicle on Board Charger Market
Electric Vehicles
Electric Vehicle Battery Cases Market
Electric Vehicles
Middle-East and Africa Electric Vehicle (EV) Fluids Market