
 Middle East Refrigerated Truck Market | 2026-2036
Middle East Refrigerated Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Refrigerated Truck Market Insights
Euro VI emission-grade chassis specification is redrawing procurement standards across Gulf fleet operators. Thermo King leverages its integrated electric refrigeration unit portfolio to anchor premium positioning in Saudi Arabia's pharmaceutical logistics sector. Carrier Transicold sustains manufacturing scale advantages through its regional assembly presence, while TSSC competes on localized service density across the UAE's free-zone distribution hubs.
A refrigerated truck is a commercial vehicle equipped with an insulated cargo box and mechanical refrigeration unit capable of maintaining temperatures between -20°C and +20°C for transporting perishable goods. The chassis integrates a vapor-compression or cryogenic cooling system with polyurethane foam insulation rated at thermal conductivity values below 0.022 W/m·K, enabling continuous cold-chain integrity across ambient desert conditions exceeding 45°C. Multi-temperature configurations command the widest margin pools by allowing simultaneous transport of frozen seafood, chilled dairy, and ambient confectionery in segmented compartments. Box truck configurations lead unit volume in last-mile food delivery across dense urban zones, while trailer formats dominate pharmaceutical long-haul routes between Jeddah and Riyadh.
Saudi Arabia's SFDA mandates GDP-compliant temperature monitoring with continuous data logging for all pharmaceutical transport, reshaping fleet retrofit demand. The UAE's MOHAP enforces parallel cold-chain standards for vaccine distribution, while Bahrain's national drug regulator aligns with GCC harmonized guidelines. Stakeholders must weigh electric refrigeration unit Total Cost of Ownership against diesel alternatives as Gulf utilities expand charging infrastructure for commercial corridors.
Market Dynamics
Pharmaceutical cold-chain compliance mandates from Saudi Arabia's SFDA and the UAE's MOHAP are forcing fleet-wide retrofit investments across Gulf logistics corridors, compressing equipment replacement cycles and elevating specification thresholds for temperature verification systems.
Growth Catalysts
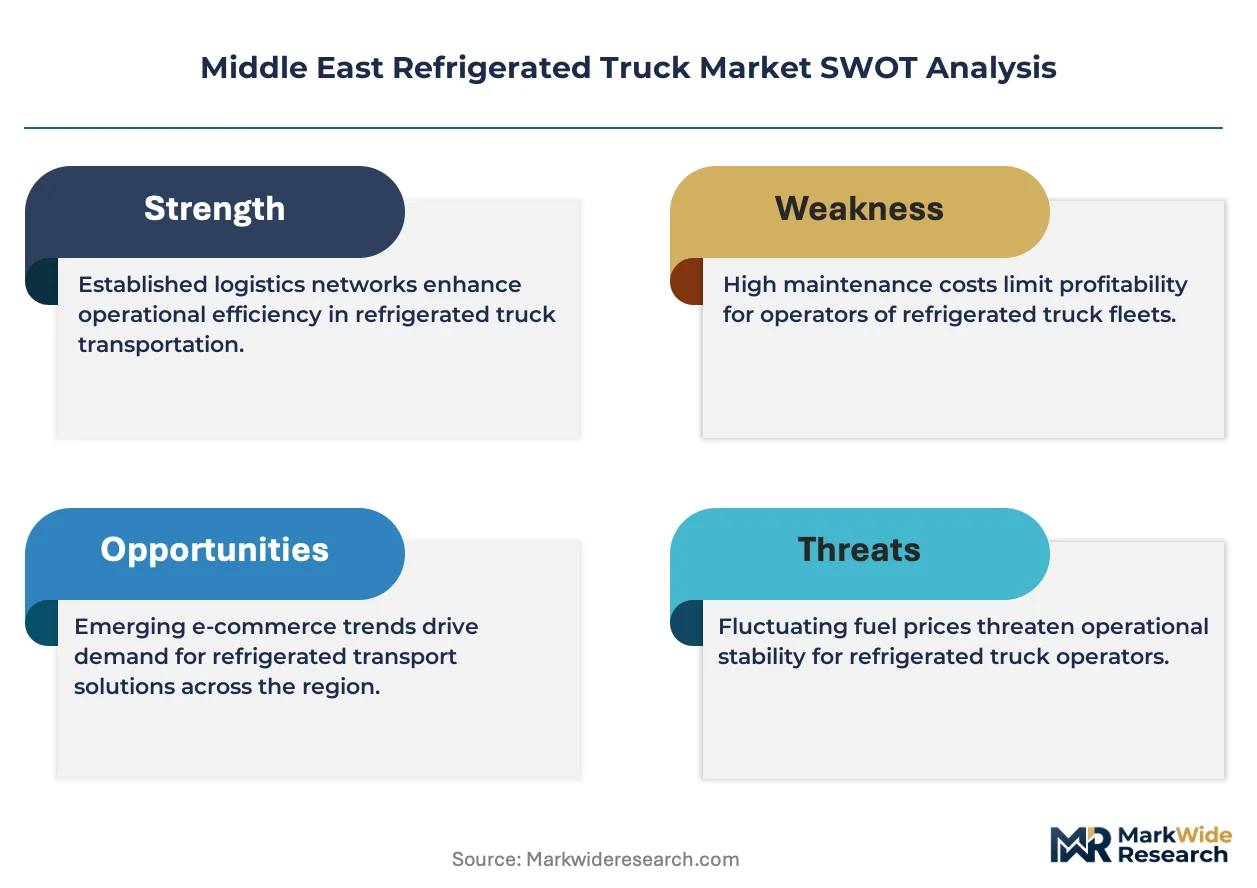
- SFDA GDP Enforcement:Saudi Arabia's pharmaceutical regulator mandates continuous temperature monitoring with data logging for all medicine transport, accelerating fleet compliance upgrades across Riyadh-Jeddah corridors.
- Perishable Import Volumes:Dubai-Jebel Ali logistics hubs strain existing refrigerated capacity as seafood and dairy import tonnage expands, triggering capacity additions in box truck and trailer configurations.
- Multi-Temperature Units:Segmented compartment designs enabling simultaneous frozen, chilled, and ambient transport command premium positioning in foodservice distribution networks.
Market Restraints
- Polyurethane Input Volatility:Insulation foam thermal conductivity specifications below 0.022 W/m·K depend on petrochemical feedstock pricing subject to regional supply disruptions.
- Chassis Supply Concentration:Euro VI emission-grade commercial vehicle platforms concentrate with limited certified suppliers serving Gulf markets, extending procurement lead times.
- Desert Thermal Load:Ambient conditions exceeding 45°C impose mechanical stress on vapor-compression refrigeration units, elevating maintenance frequency and compressor replacement rates.
Strategic Opportunities
- Bahrain Pharmaceutical Logistics:The island kingdom's alignment with GCC harmonized cold-chain guidelines creates compliance-ready entry points for GDP-certified fleet operators.
- Electric Refrigeration Convergence:Battery-electric chassis integration with electric refrigeration units offers total cost of ownership advantages as Gulf utilities expand commercial corridor charging infrastructure.
- Last-Mile Food Delivery:Dense urban zones in Doha and Kuwait City generate demand for compact box truck configurations with rapid door-cycle recovery capabilities.
Industry Challenges
- GDP Certification Timeline:Fleet operators face extended validation periods for temperature mapping and qualification protocols required by Saudi and Emirati pharmaceutical regulators.
- Technician Skill Scarcity:Refrigeration system diagnostics and electric unit maintenance require specialized training programs that Gulf technical institutes have yet to scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Refrigerated Truck Market |
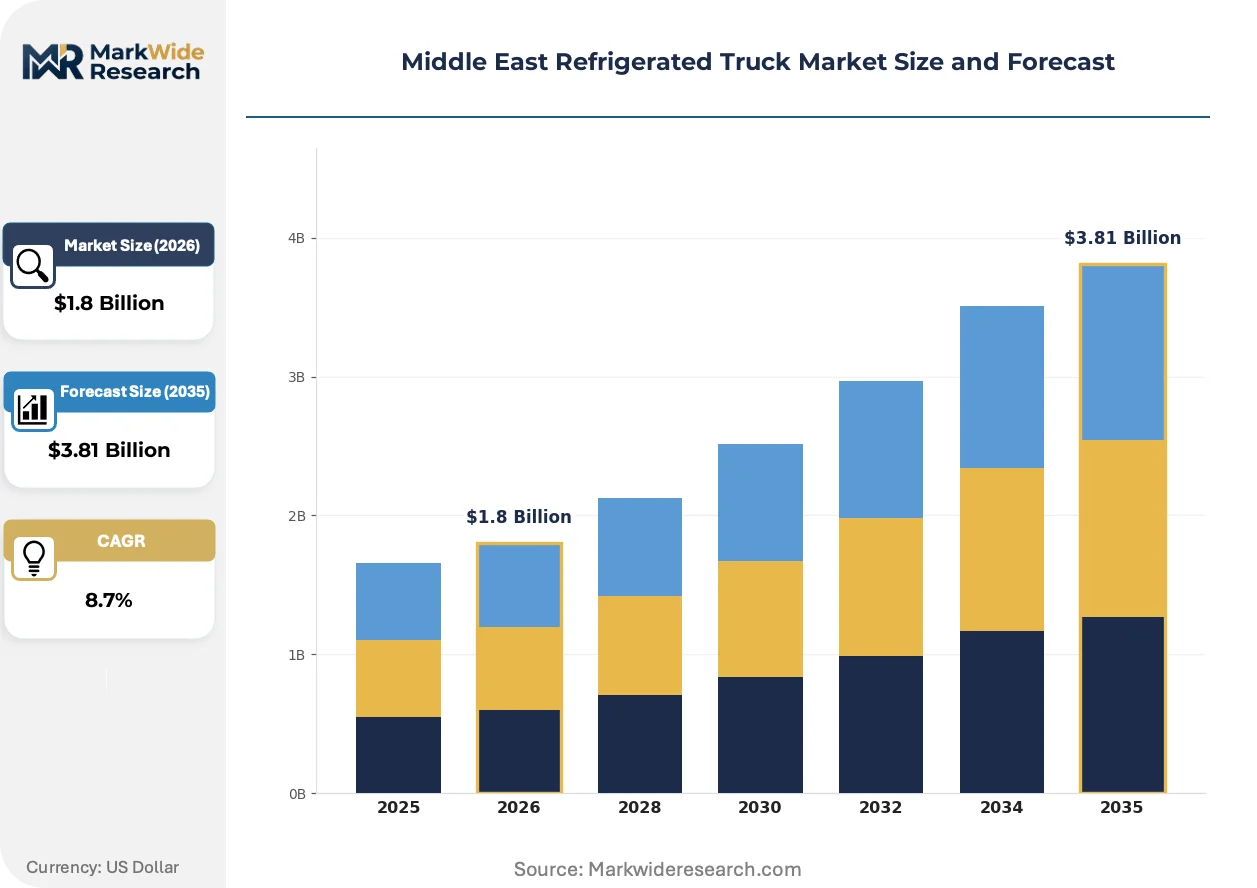
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chilled, Frozen, Multi-Temperature, Thermo King End User: Food and Beverage, Pharmaceutical, Agriculture, Logistics Temperature Range: -20°C to 0°C, 0°C to +10°C, +10°C to +20°C, Ambient Truck Configuration: Single Compartment, Dual Compartment, Trailer, Box Truck |
| Companies Covered | Frigoblock, Foton Group, Thermo King, TSSC (Harwal Group), ISUZU, Carrier Transicold, Zanotti, KRONE, Daikin, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Refrigerated Truck Market Trends and Innovations
Equipment specification standards across Gulf markets are pivoting from diesel-dependent architectures toward integrated electric systems, while regulatory enforcement tightens documentation requirements for temperature-sensitive cargo integrity.
Telematics-enabled refrigeration control is decomposing traditional fleet management approaches across Saudi pharmaceutical distributors. Real-time temperature monitoring with automated alert systems allows logistics operators to demonstrate continuous GDP compliance during SFDA inspections. This capability compresses competitive differentiation toward data transparency rather than equipment hardware alone.
MOHAP vaccine distribution standards in the UAE now parallel Saudi GDP requirements, extending cold-chain verification mandates to cover last-mile delivery segments previously exempt from continuous monitoring. Pharmaceutical fleet operators must retrofit existing units with validated data loggers or face distribution license suspension. The Dubai-Jebel Ali corridor exhibits the densest concentration of compliance-driven equipment upgrades.
Foodservice procurement teams now bundle refrigeration equipment with outcome-based service agreements covering uptime guarantees and preventive maintenance. Large catering operators in Abu Dhabi and Riyadh negotiate total cost of ownership contracts that shift compressor replacement risk to equipment providers. This preference shift favors suppliers with localized service density over pure manufacturing scale advantages.
Middle East Refrigerated Truck Market Segmentation
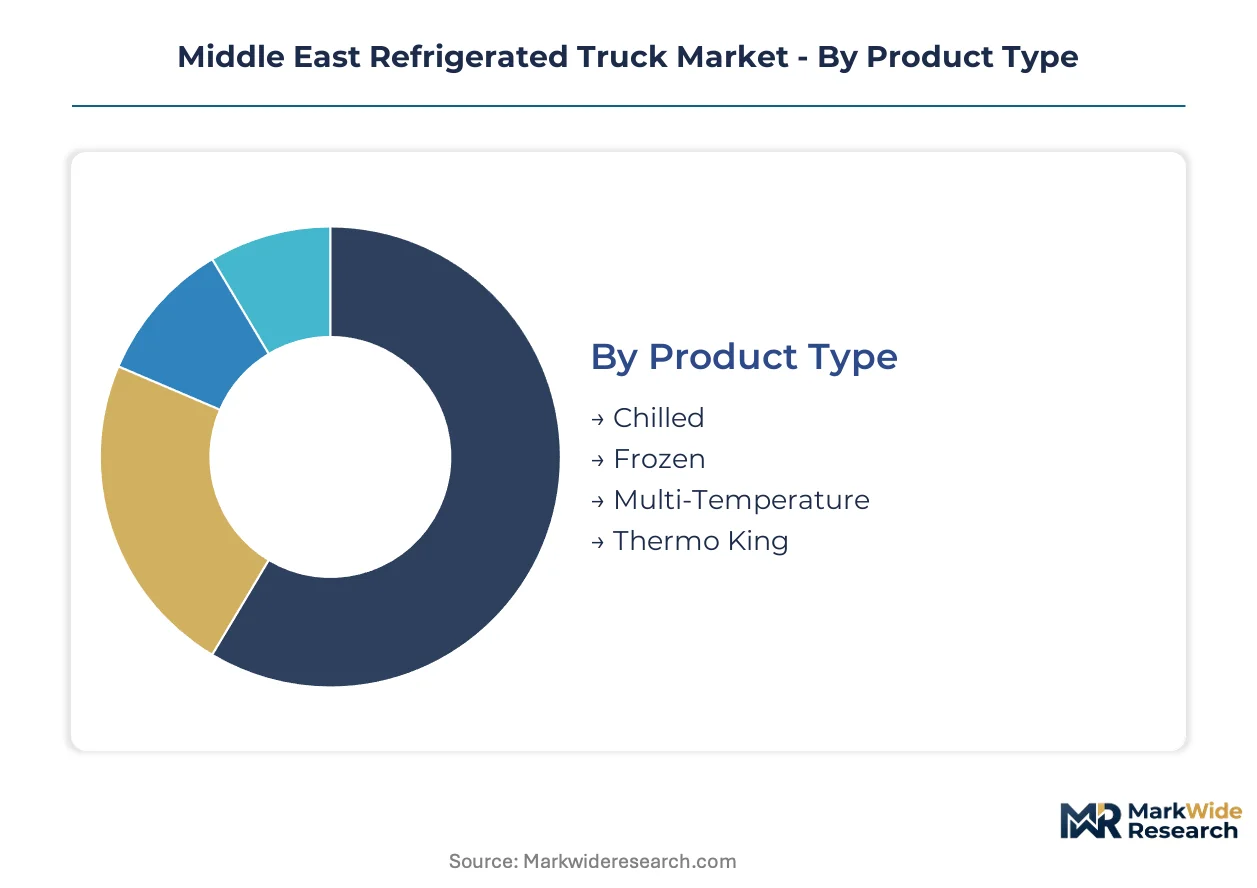
Refrigerated truck segmentation in the Middle East reflects divergent pressure points across payload requirements, regulatory exposure, and thermal load conditions. Fleet procurement decisions increasingly hinge on whether a segment can absorb GDP compliance costs or withstand desert ambient stress without excessive maintenance burden.
Product Type:
Multi-temperature configurations face the strongest substitution pressure from single-temperature units when route density cannot justify compartment complexity.
- Chilled:Maintains 0°C to +10°C through vapor-compression cycles optimized for dairy, fresh produce, and prepared foods. UAE foodservice distributors in Dubai and Abu Dhabi concentrate procurement here as hotel and catering volumes recover.
- Frozen:Sustains -20°C through reinforced insulation and higher-capacity compressors for seafood and ice cream transport. Saudi Arabia's Red Sea import corridors drive fleet investment as Jeddah port volumes strain existing capacity.
- Multi-Temperature:Segmented compartments enable simultaneous frozen, chilled, and ambient cargo in a single chassis.
- Thermo King:Integrated electric refrigeration units with telematics-enabled temperature logging for GDP compliance.
Chilled configurations anchor the volume base while multi-temperature units gain share at the steepest rate.
End User:
Cost tier differentiation separates capital-intensive pharmaceutical fleets from price-sensitive agricultural operators.
- Pharmaceutical:SFDA and MOHAP GDP mandates enforce continuous data logging with validated qualification protocols. Saudi distributors face compressed replacement cycles as temperature verification becomes a licensing condition.
- Food and Beverage:Hotel, restaurant, and catering supply chains dominate procurement in Qatar and Kuwait urban corridors.
- Agriculture:Seasonal harvest transport for dates, vegetables, and dairy from Saudi Arabia's Qassim region.
- Logistics:Third-party cold-chain providers serving multiple end-users under contract.
Food and beverage anchors the volume base while pharmaceutical applications gain share at the steepest rate.
Temperature Range:
Application concentration determines which thermal bands command specification premiums versus commodity positioning.
- 0°C to +10°C:Chilled band for dairy, fresh meat, and pharmaceutical stability. The UAE's vaccine distribution network under MOHAP supervision concentrates demand here with strict excursion limits.
- -20°C to 0°C:Frozen band requiring reinforced compressor capacity and thicker polyurethane insulation.
- +10°C to +20°C:Cool chain for chocolates, cosmetics, and certain biologics.
- Aient:Non-refrigerated compartments in multi-temperature configurations for shelf-stable goods.
The 0°C to +10°C band anchors the volume base while the -20°C to 0°C band gains share at the steepest rate.
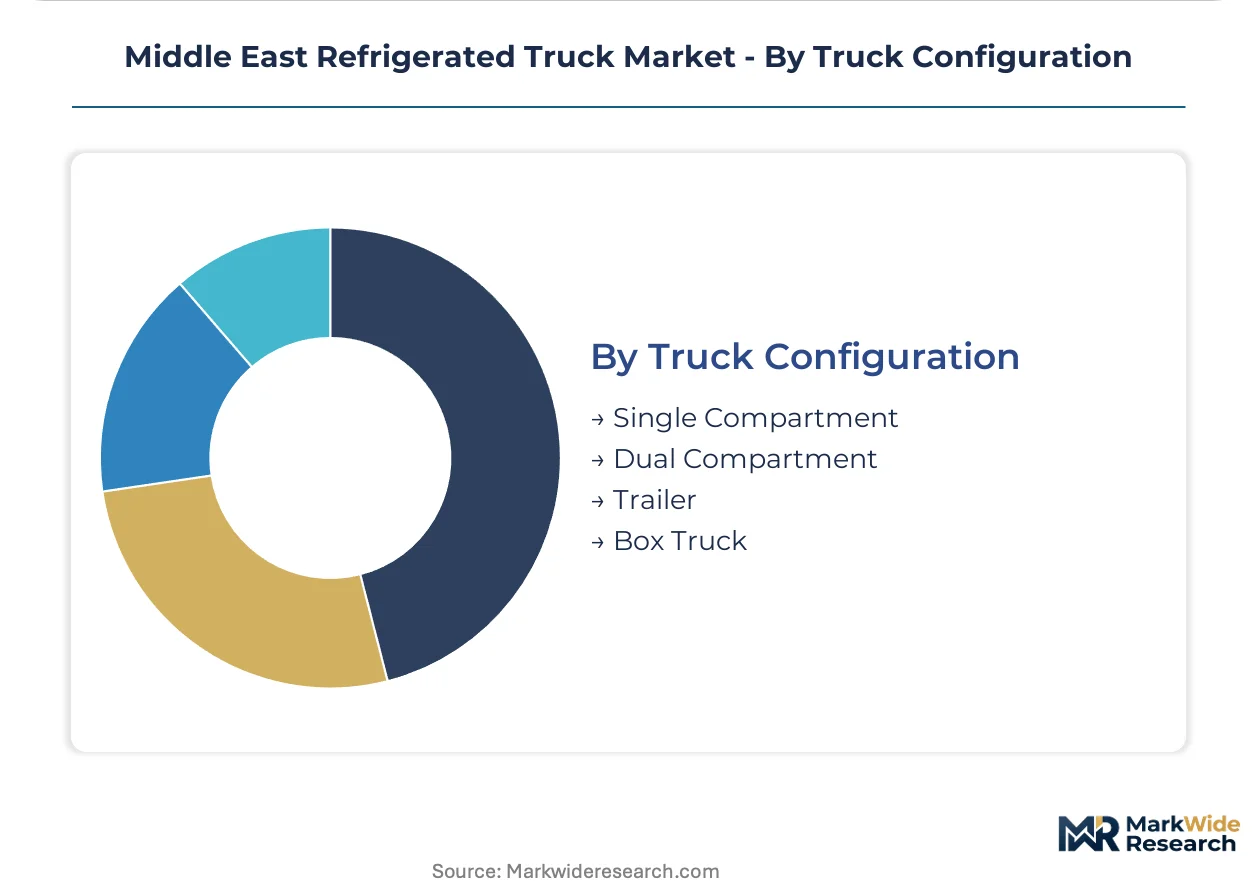
Truck Configuration:
Customer type splits between urban last-mile operators needing maneuverability and long-haul corridors demanding payload maximization.
- Box Truck:Compact chassis with integrated refrigeration for dense urban delivery in Doha, Kuwait City, and Riyadh. Rapid door-cycle recovery capabilities matter most here as stop frequency degrades thermal stability.
- Trailer:High-capacity long-haul format dominating pharmaceutical routes between Jeddah and Riyadh.
- Single Compartment:Dedicated temperature zone for homogeneous cargo loads.
- Dual Compartment:Split frozen and chilled zones for mixed loads without full multi-temperature complexity.
Box truck configurations anchor the volume base while trailer formats gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Middle East refrigerated truck market reflects a structural trade imbalance where import-dependent economies drive cold-chain capacity expansion faster than domestic manufacturing can supply equipment. Perishable cargo flows through maritime gateways into temperature-controlled distribution networks that remain underbuilt relative to volume growth.
Saudi Arabia
Pharmaceutical distribution corridors between Jeddah and Riyadh command the region's strictest cold-chain specifications. The Saudi Food and Drug Authority enforces GDP compliance with continuous temperature logging as a licensing condition for medicine transport. Fleet operators in the Riyadh metropolitan cluster face compressed equipment replacement cycles to meet these validation protocols.
United Arab Emirates
Dubai-Jebel Ali logistics hubs strain existing refrigerated capacity as seafood and dairy import tonnage expands. The Ministry of Health and Prevention mandates parallel cold-chain standards for vaccine distribution that extend to last-mile delivery segments. Pharmaceutical fleet concentration in Dubai's free-zone distribution corridors drives the densest compliance-driven equipment upgrade activity.
Qatar
Doha's dense urban zones generate concentrated demand for compact box truck configurations with rapid door-cycle recovery capabilities. The country's national food security program subsidizes cold-chain infrastructure for perishable imports. Logistics operators cluster around Hamad Port and the Mesaieed industrial zone to serve hotel and catering supply chains.
Kuwait
Kuwait City's last-mile food delivery networks anchor procurement for maneuverable refrigerated chassis. The national pharmaceutical regulator aligns with GCC harmonized cold-chain guidelines, creating compliance-ready entry conditions for GDP-certified operators. Shuwaikh Port and the Sulaibiya logistics corridor concentrate fleet deployment for consumer goods distribution.
Bahrain
The island kingdom's pharmaceutical logistics sector benefits from streamlined customs procedures and GCC regulatory alignment. The national drug authority enforces temperature verification standards that match Saudi and Emirati benchmarks. Fleet operators concentrate in the Mina Salman port zone to serve regional re-export trade in temperature-sensitive cargo.
Middle East Refrigerated Truck Market Competitive Landscape
Listed refrigeration equipment manufacturers compete with private specialists across technology integration and service density dimensions. The vendor base organizes around three tiers: integrated system providers with electric portfolio breadth, regional assemblers leveraging manufacturing scale, and localized service specialists competing on maintenance network reach. Strategic moves center on telematics-enabled compliance documentation and outcome-based service contracts that shift equipment risk to suppliers.
Among the integrated system tier, Thermo King and Carrier Transicold exemplify divergent approaches to Gulf market positioning. Thermo King anchors premium positioning through electric refrigeration units with GDP-compliant data logging capabilities. Carrier Transicold occupies the manufacturing scale vector through regional assembly presence that shortens procurement lead times for Euro VI chassis integration. TSSC represents the localized service density archetype, competing through maintenance network coverage across UAE free-zone distribution hubs rather than equipment innovation alone.
| Leading Market Players |
|---|
| Frigoblock |
| Foton Group |
| Thermo King |
| TSSC (Harwal Group) |
| ISUZU |
| Carrier Transicold |
| Zanotti |
| KRONE |
| Daikin |
| Others |
Pricing and Supply Chain Analysis
SFDA GDP certification gates both supplier qualification and price differentiation across Saudi pharmaceutical fleets, compressing procurement timelines for compliant equipment while elevating margin pools for validated systems. Buyers face tiered cost structures where continuous temperature logging capabilities separate premium positioning from commodity chassis.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across GDP-certified, standard refrigerated, and economy chassis tiers. Price differentiation hinges on telematics integration depth and polyurethane insulation grade rated below 0.022 W/m·K. Pricing pressure intensifies in standard tiers as Euro VI chassis scarcity extends procurement lead times. Agricultural operators in Saudi Arabia's Qassim region exhibit highest price sensitivity, while pharmaceutical distributors absorb premiums for compliance documentation.
Supply Chain Analysis
Red Sea container congestion and Jebel Ali port throughput constraints elevate inbound logistics costs for polyurethane foam and compressor assemblies. Manufacturing concentrates in Germany, China, and South Korea for refrigeration units, while chassis sourcing draws from Japanese and European OEMs. Single-source vulnerability runs through Euro VI emission-grade platform suppliers serving Gulf markets. Distribution runs through Dubai-Jebel Ali free-zone hubs for regional re-export to Saudi Arabia, Qatar, and Bahrain.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across SFDA, MOHAP, and GCC harmonized guidelines creates niche opportunities for compliance-specialized fleet operators and localized service providers. Pharmaceutical cold-chain mandates generate asymmetric entry points where certification speed trumps manufacturing scale.
For Market Incumbents: Compound service density advantages through preventive maintenance contracts covering compressor replacement risk, while securing backward integration into telematics-enabled temperature logging systems. Electric refrigeration unit portfolios threaten diesel-dependent installed bases, demanding rapid GDP qualification protocol streamlining to defend Riyadh-Jebel Ali corridor positioning. For New Entrants and Emerging Players: Bahrain's GDP certification fast-track offers lowest regulatory friction for GCC market entry, given alignment with Saudi and Emirati standards without equivalent validation backlog. Target pharmaceutical third-party logistics contracts in Doha's Hamad Port zone, where national food security subsidies reduce customer acquisition costs. Lead with outcome-based uptime guarantees rather than equipment specifications. For Investors and Strategic Acquirers: SFDA enforcement timeline reshapes the acquisition landscape toward GDP-validated fleet operators with established temperature mapping protocols. Five-to-ten year viability favors service-dense specialists over pure manufacturing scale. Watch electric refrigeration unit adoption rates across Saudi pharmaceutical corridors as inflection signal for technology displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| GDP Certification Fast-Track Investment | SFDA validation protocols compress competitive timelines for Saudi pharmaceutical fleet access. |
| Electric Refrigeration Portfolio Expansion | Thermo King's integrated battery-electric units anchor premium positioning in Riyadh-Jeddah corridors. |
| Service Network Density Buildout | TSSC's UAE free-zone maintenance coverage competes against Carrier Transicold's manufacturing scale. |
| Multi-Temperature Configuration Development | Segmented compartments enable simultaneous frozen, chilled, and ambient cargo for foodservice distributors. |
| Telematics-Enabled Compliance Documentation | Real-time temperature logging satisfies MOHAP vaccine distribution mandates across Dubai-Jebel Ali hubs. |
Research Methodology
The analysis maps chassis configuration tiers, refrigeration unit technologies, and end-user compliance requirements, each validated through fleet procurement managers, pharmaceutical logistics directors, and cold-chain equipment distributors. Primary interviews with SFDA-qualified operators, MOHAP-registered distributors, and GCC regulatory affairs specialists combined with secondary validation from customs trade data, pharmaceutical licensing registries, and Euro VI chassis certification databases. Bottom-up equipment shipment analysis triangulates against top-down cold-chain capacity expansion estimates.
Consistency checks validated volume and value outputs against regional port throughput data and pharmaceutical import tonnage trends across the projection horizon. Segmentation modeling incorporated temperature range specifications, truck configuration types, payload capacity tiers, and regulatory compliance clusters. CAGRs derived from equipment replacement cycle compression analysis and GDP mandate enforcement timelines. Forecast inputs included polyurethane feedstock pricing volatility and Euro VI chassis availability constraints.
Decision-makers should treat outputs as directional under assumptions of sustained SFDA enforcement intensity and Gulf utility charging infrastructure expansion; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Dump Trucks Market
Heavy-Duty Trucks
Hard Tonneau Cover Market
Heavy-Duty Trucks
Turret Truck Market
Heavy-Duty Trucks
Mexico Refrigerated Truck Market
Heavy-Duty Trucks
United States Refrigerated Trucking Market
Heavy-Duty Trucks
Dump Trucks and Mining Trucks Market
Heavy-Duty Trucks
North America Vacuum Truck Market
Heavy-Duty Trucks
Global Vocational Truck Market
Heavy-Duty Trucks
Truck Headache Rack Market
Heavy-Duty Trucks
Global Connected Truck Market
Heavy-Duty Trucks
Poly Trucks Market
Heavy-Duty Trucks
Europe Medium & Heavy-Duty Truck Rental Market
Heavy-Duty Trucks
Digger Derrick Truck Market
Heavy-Duty Trucks
Garbage Truck Bodies Market
Heavy-Duty Trucks
High Performance Trucks Market
Heavy-Duty Trucks
Hydrogen Trucks Market