
 Aircraft Modernization Market | 2026-2036
Aircraft Modernization Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Modernization Market Analysis
The certified airframe mechanic labor pool is collapsing across North America and Western Europe, forcing defense agencies and commercial MRO providers to extend outsourcing contracts and accelerate automation deployment. Boeing Defense, Space & Security leverages its proprietary digital thread infrastructure to capture integrated avionics upgrade programs for legacy military platforms. BAE Systems sustains long-term positions in European fighter retrofit markets through sovereign sustainment partnerships with the UK Ministry of Defence and NATO allied fleets. Lockheed Martin Corporation dominates the C-130 and F-16 structural modification pipeline, anchoring revenue through multi-year performance-based logistics contracts that bundle repair, retrofit, and customization services.
Aircraft modernization encompasses the systematic engineering overhaul of existing airframes, propulsion systems, and mission electronics to restore operational capability, extend certified service life, or achieve regulatory compliance with evolved airworthiness standards; core processes include structural fatigue remediation, wire harness replacement, and flight control computer upgrades to MIL-STD-1553B or newer open systems architectures. Avionics upgrade work captures disproportionate value as operators replace analog instrumentation with digital cockpit suites integrating synthetic vision and terrain awareness warning systems. Engine overhaul demand concentrates on high-bypass turbofan fleets where OEM-certified refurbishment restores thrust-specific fuel consumption within new-production tolerance bands. Military aviation end users drive structural modification volumes through service life extension programs that add 10,000–15,000 flight hours to aging bomber and tanker platforms.
The FAA mandates TCAS II and ADS-B Out equipage under 14 CFR 91.225, while EASA enforces equivalent requirements through its Airspace Infringement Prevention program, collectively compelling commercial operators to allocate capital toward navigation systems and digital cockpit retrofits or face operational restrictions in controlled airspace. The EPA's aircraft engine emission standards under 40 CFR Part 87 and ICAO's Carbon Offsetting and Reduction Scheme for International Aviation are reshaping fuel efficiency solution procurement, with operators prioritizing winglets, engine re-fanning, and aerodynamic fairings to reduce specific fuel consumption. Stakeholders must monitor how FAA reauthorization priorities and EASA's evolving CS-25 special conditions for autonomous flight control integration will alter certification pathways for automation systems retrofit onto legacy type certificates.
Market Dynamics
The collapse of certified airframe mechanic labor pools across NATO member states is forcing defense agencies and commercial MRO providers into extended outsourcing contracts and accelerated automation deployment, fundamentally restructuring how upgrade work gets executed.
Growth Catalysts
- FAA ADS-B Out Mandate:The 14 CFR 91.225 requirement compels commercial operators to prioritize avionics upgrade investments or face controlled airspace restrictions, sustaining retrofit demand across aging narrowbody fleets.
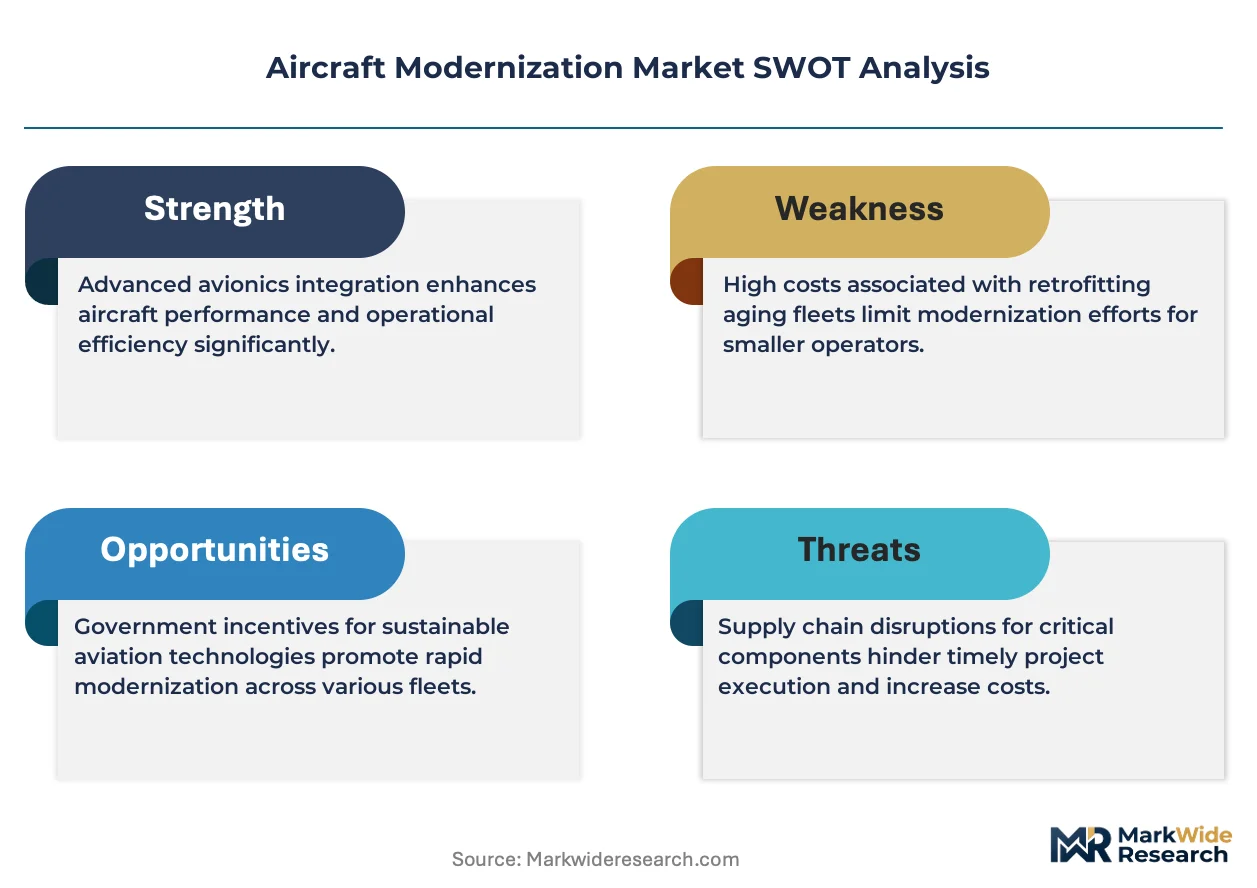
- KC-135 Re-Engining:The US Air Force's multi-decade sustainment commitment to this tanker platform anchors structural modification and propulsion overhaul volumes through 2040.
- Synthetic Vision Integration:Digital cockpit suites incorporating terrain awareness warning systems capture disproportionate value as operators replace analog instrumentation.
Market Restraints
- Titanium Supply Concentration:Russian and Chinese dominance in sponge production creates input cost volatility for structural fatigue remediation programs requiring high-strength alloys.
- MIL-STD-1553B Legacy Architecture:Proprietary bus systems in Cold War-era platforms resist open systems migration, constraining flight control computer upgrade pathways.
- EPA Part 87 Emission Standards:Refurbished engine certification against evolving thresholds adds regulatory friction to overhaul shop throughput.
Strategic Opportunities
- Indian Defense Modernization:The country's fighter retrofit requirements under the Ministry of Defence's indigenization push create white space for avionics integration partnerships.
- ICAO CORSIA Compliance:The Carbon Offsetting and Reduction Scheme creates regulatory tailwind for winglets, aerodynamic fairings, and engine re-fanning procurement.
- Digital Thread Convergence:Integration of model-based systems engineering with predictive maintenance analytics enables performance-based logistics bundling for legacy platforms.
Industry Challenges
- Airframe Mechanic Pipeline Collapse:The certified labor pool contraction across North America and Western Europe forces reliance on automation and foreign contract labor.
- Type Certificate Amendment Timelines:FAA and EASA certification pathways for autonomous flight control retrofits onto legacy airframes extend program schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Modernization Market |
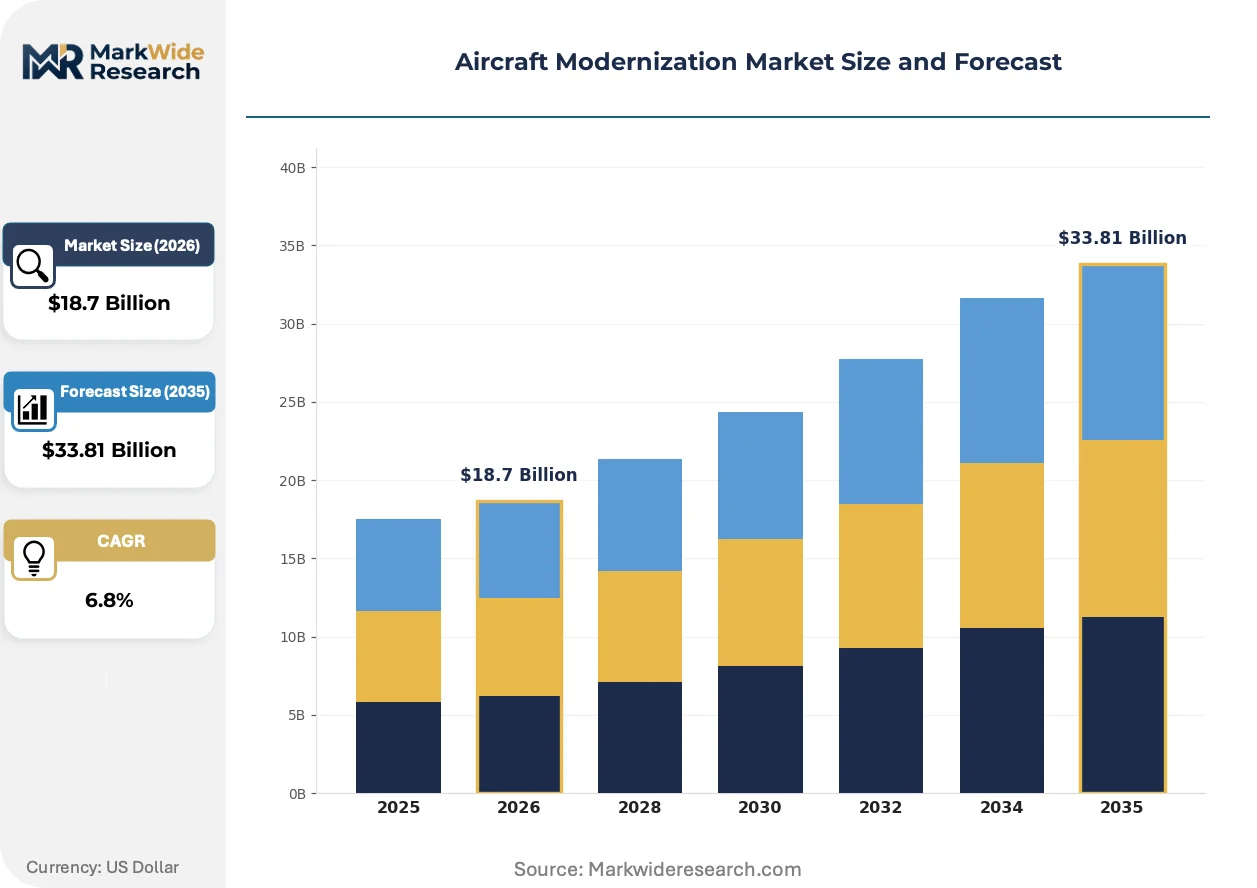
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Avionics Upgrade, Airframe Enhancement, Engine Overhaul, Structural Modification Service Type: Maintenance, Retrofit, Repair, Customization End User: Commercial Aviation, Military Aviation, Cargo Carriers, Charter Services Technology: Digital Cockpit, Automation Systems, Fuel Efficiency Solutions, Navigation Systems |
| Companies Covered | Boeing Defense, Space & Security, BAE Systems, Lockheed Martin Corporation, Collins Aerospace, Airbus Defence and Space, Northrop Grumman Corporation, GE Aerospace, Peraton, Raytheon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Modernization Market Emerging Trajectories
Digital engineering infrastructures are actively displacing paper-based technical data packages across military and commercial upgrade programs, compressing design-to-installation cycles while enabling predictive configuration management.
Open systems architectures are bifurcating the avionics upgrade market. Modular mission computers compliant with the Future Airborne Capability Environment standard enable rapid software refreshes without hardware replacement. Military operators across NATO fleets are adopting these standards aggressively. The technology is bifurcating vendor ecosystems between proprietary legacy incumbents and modular challengers.
EASA's evolving CS-25 special conditions for autonomous flight control integration are reshaping certification requirements for retrofit automation systems. The regulatory framework demands enhanced software assurance evidence for legacy type certificate amendments. European commercial operators and defense fleets face the most stringent compliance pathways, driving investment in formal verification tools.
Performance-based logistics contracts are displacing transactional spare parts procurement across military sustainment programs. The US Air Force's C-130 and F-16 structural modification pipelines anchor multi-year agreements bundling repair, retrofit, and customization. Defense agencies in the United States lead this behavioral shift, with allied NATO members piloting equivalent models.
Aircraft Modernization Market Segmentation
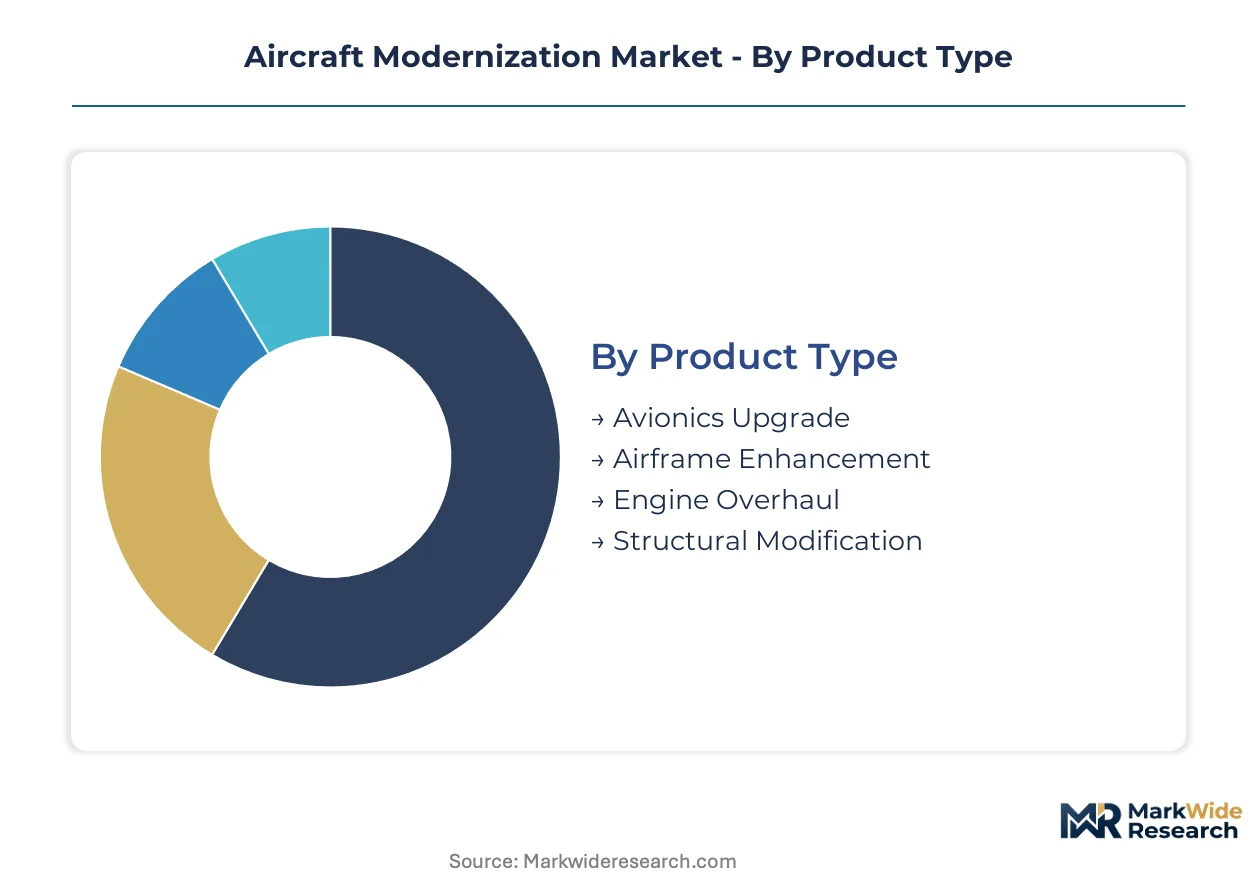
Segmentation in aircraft modernization reveals how regulatory mandates, labor scarcity, and platform age concentrate investment across distinct technical domains. Each category isolates where capital flows, which capabilities command premium pricing, and where substitute technologies threaten incumbent solutions.
Product Type:
Avionics upgrade and engine overhaul segments face acute substitution pressure from new-production aircraft deliveries, while structural modification and airframe enhancement work proves irreplaceable for extending certified service life on platforms with decades of remaining utility.
- Avionics Upgrade:Digital cockpit suites integrating synthetic vision, terrain awareness warning systems, and ADS-B Out transponders replace analog instrumentation. Demand concentrates in the United States where FAA mandates under 14 CFR 91.225 compel narrowbody fleet retrofits or operational restrictions in controlled airspace.
- Engine Overhaul:OEM-certified refurbishment restores thrust-specific fuel consumption within new-production tolerance bands for high-bypass turbofan fleets. The US Air Force's KC-135 re-engining program anchors multi-decade sustainment commitments through 2040, insulating this segment from near-term demand erosion.
- Airframe Enhancement:Aerodynamic fairings, winglets, and drag reduction modifications improve fuel efficiency on legacy platforms.
- Structural Modification:Fatigue remediation, corrosion repair, and service life extension programs add 10,000–15,000 flight hours to aging bomber and tanker airframes.
Engine overhaul retains volume leadership; avionics upgrade holds the steepest expansion curve.
Service Type:
Cost tier differentiation separates transactional repair work from bundled performance-based contracts, with military sustainment programs driving structural shifts toward long-term agreements that merge multiple service categories.
- Retrofit:Systematic engineering overhauls of propulsion, avionics, and mission electronics to achieve regulatory compliance or restore operational capability. NATO member states accelerate retrofit programs amid supply chain constraints on new aircraft deliveries, concentrating demand in European fighter fleets and US tanker platforms.
- Maintenance:Scheduled inspections, preventive servicing, and airworthiness directive compliance sustain certified flight status. The collapse of certified airframe mechanic labor pools across North America and Western Europe forces defense agencies and commercial MRO providers into extended outsourcing contracts.
- Repair:Corrective action on failed components, battle damage remediation, and unscheduled restoration of airworthy condition.
- Customization:Mission-specific modifications including sensor integration, weapons carriage adaptation, and special operations configuration.
Maintenance commands the widest customer base; retrofit generates the highest contract values per platform.
End User:
Application maturity varies sharply, with military aviation sustaining structural modification pipelines through multi-year performance-based logistics while commercial operators prioritize discrete avionics upgrades to meet regulatory deadlines.
- Military Aviation:Service life extension programs for bomber, tanker, and fighter platforms drive structural modification volumes. The US Air Force's C-130 and F-16 pipelines anchor multi-year agreements bundling repair, retrofit, and customization, with allied NATO members piloting equivalent contract models.
- Commercial Aviation:Narrowbody and regional jet fleets prioritize ADS-B Out equipage, TCAS II installation, and digital cockpit retrofits to maintain access to controlled airspace under FAA and EASA mandates.
- Cargo Carriers:Freighter conversion programs and heavy maintenance on converted passenger aircraft sustain demand for airframe enhancement services.
- Charter Services:Business aviation and private operators pursue discretionary avionics upgrades for operational capability and resale value preservation.
Military aviation dominates absolute spending; commercial aviation shows the most uniform regulatory-driven demand.
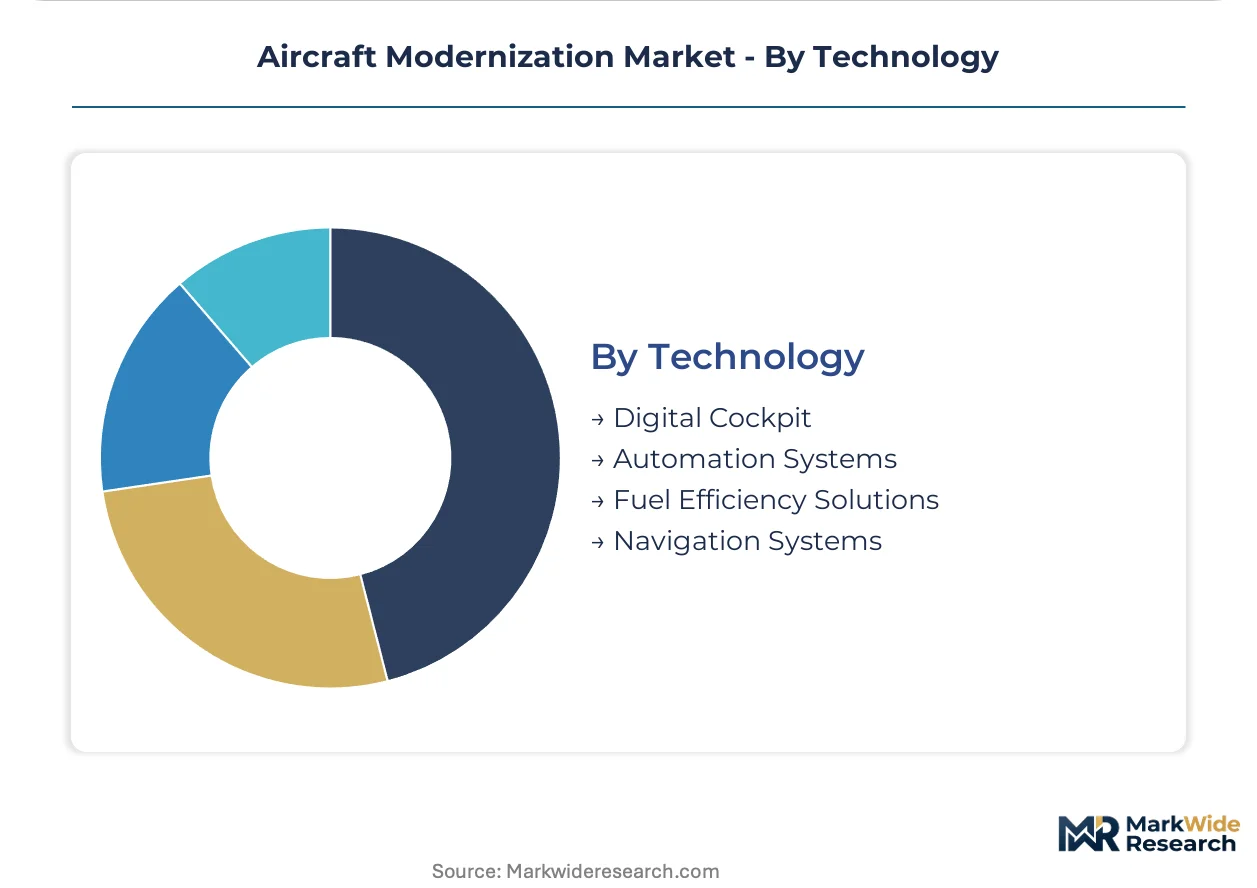
Technology:
Supply concentration in digital engineering tools and formal verification capabilities favors vendors with integrated model-based systems engineering infrastructure, fragmenting competitive positions in legacy analog replacement versus modular open systems.
- Digital Cockpit:Integrated display systems, electronic flight instrument systems, and crew alerting computers replace electromechanical gauges. EASA's evolving CS-25 special conditions for autonomous flight control integration reshape certification requirements, demanding enhanced software assurance evidence for legacy type certificate amendments.
- Automation Systems:Flight control computer upgrades from MIL-STD-1553B to open systems architectures enable rapid software refreshes. Modular mission computers compliant with the Future Airborne Capability Environment standard bifurcate vendor ecosystems between proprietary legacy incumbents and modular challengers.
- Fuel Efficiency Solutions:Winglets, aerodynamic fairings, and engine re-fanning reduce specific fuel consumption to meet ICAO CORSIA compliance pathways.
- Navigation Systems:GPS augmentation, inertial reference systems, and required navigation performance equipment enable NextGen airspace operations.
Digital cockpit captures the largest installed base upgrade opportunity; fuel efficiency solutions are climbing the fastest as emission standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FAA's ADS-B Out mandate under 14 CFR 91.225 anchors North American retrofit demand, while EASA's equivalent airspace requirements and India's defense indigenization push create parallel growth corridors across distinct regulatory environments.
United States
The US Air Force's KC-135 re-engining and C-5 avionics modernization programs anchor multi-decade sustainment commitments through 2040. The FAA mandates TCAS II and ADS-B Out equipage under 14 CFR 91.225, compelling narrowbody fleet retrofits. Seattle-Tacoma and Wichita clusters concentrate Boeing Defense and Collins Aerospace engineering capacity for integrated avionics upgrades.
Germany
EASA's Airspace Infringement Prevention program enforces navigation system retrofits equivalent to FAA mandates, driving digital cockpit procurement across Lufthansa Group and TUI fleets. The EU Green Deal's aviation emission targets accelerate winglet and aerodynamic fairing adoption. Hamburg and Munich MRO hubs specialize in A320 family avionics integration and engine overhaul workflows.
United Kingdom
BAE Systems sustains sovereign sustainment partnerships with the UK Ministry of Defence for Eurofighter Typhoon retrofit programs. The Civil Aviation Authority aligns with EASA CS-25 special conditions for autonomous flight control certification. Bristol and Lancashire engineering centers focus on structural life extension for RAF transport and tanker platforms.
India
The Ministry of Defence's indigenization push creates white space for avionics integration partnerships on Su-30MKI and Jaguar fleets. DGFT import substitution policies favor local MRO joint ventures with foreign OEMs. Bangalore and Hyderabad clusters concentrate Hindustan Aeronautics Limited and private sector digital cockpit upgrade capabilities.
Japan
METI procurement guidelines prioritize domestic MRO participation in F-15J and C-2 transport modernization. The Japan Civil Aviation Bureau enforces ICAO-aligned NextGen equipage deadlines for commercial operators. Nagoya and Komaki aerospace districts host Mitsubishi Heavy Industries structural modification facilities for regional and military platforms.
Aircraft Modernization Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the modernization value chain. The market structure concentrates around defense-prime integrators with proprietary digital thread infrastructure, tier-1 avionics specialists with modular open systems platforms, and engine OEMs with certified overhaul networks. Three archetypes dominate: full-service integrators bundling airframe, propulsion, and mission systems; avionics modularists leveraging FACE-standard compliance; and performance-based logistics operators anchoring multi-year sustainment contracts. Competitive moves center on strategic partnerships with sovereign defense agencies and vertical integration into predictive maintenance analytics.
Among US-based defense integrators, Boeing Defense, Space & Security and Lockheed Martin Corporation exemplify the full-service archetype through multi-year military sustainment pipelines. BAE Systems occupies a parallel position in European fighter retrofit markets through UK and NATO allied fleet partnerships. These three anchors demonstrate how proprietary digital infrastructure and sovereign sustainment relationships create defensive positioning against modular challengers.
| Leading Market Players |
|---|
| Boeing Defense, Space & Security |
| BAE Systems |
| Lockheed Martin Corporation |
| Collins Aerospace |
| Airbus Defence and Space |
| Northrop Grumman Corporation |
| GE Aerospace |
| Peraton |
| Raytheon Technologies |
| Others |
Supply Flow & Price Mechanics
Ninety-day titanium sponge lead times from Russian and Chinese suppliers compress inventory buffers for structural fatigue remediation programs, concentrating pricing power with alloy processors who command premium spreads on certified aerospace-grade material. This input scarcity propagates through avionics integration and engine overhaul tiers, forcing MRO providers to absorb cost volatility or pass through to defense agencies and commercial operators with long-term contract leverage.
Pricing Analysis
North American avionics upgrade contracts trade at fifteen-to-twenty percent premiums over equivalent European engagements, reflecting FAA mandate urgency and domestic labor scarcity. Project-based pricing dominates, with cost differentiation driven by certification tier (FAA Part 21 versus military airworthiness) and aftermarket service bundling. Cost compression in standard-grade structural modification runs through titanium input volatility and mechanic wage inflation. Defense agencies show least price sensitivity due to sovereign sustainment mandates; regional commercial operators face acute budget constraints on discretionary retrofits.
Supply Chain Analysis
Russia and China dominate titanium sponge production, while the United States and France concentrate precision-forged airframe components and avionics module fabrication. High-strength alloys, MIL-spec wire harnesses, and open-architecture mission computers constitute critical input dependencies. Single-source vulnerability on titanium feedstock exposes structural modification programs to geopolitical disruption. Distribution runs through OEM-certified overhaul networks and sovereign military supply chains, with tier-1 integrators controlling access to proprietary technical data packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aircraft modernization incumbents face substitution pressure from new-production narrowbody deliveries as supply chain constraints ease and lessor rates compress, requiring defensive positioning around irreplaceable structural life extension work.
For Market Incumbents: Fortify proprietary digital thread infrastructure to capture integrated avionics upgrade programs for legacy military platforms where type certificate knowledge creates moats. Deepen backward integration into predictive maintenance analytics to anchor multi-year performance-based logistics contracts against modular open-systems challengers. Lockheed Martin and Boeing Defense demonstrate how sovereign sustainment relationships insulate revenue from commercial new-build substitution. For New Entrants and Emerging Players: Anchor in India's fighter retrofit requirements under the Ministry of Defence's indigenization push, where DGFT import substitution policies favor local MRO joint ventures with foreign OEMs. Target modular mission computer integration compliant with FACE standards, penetrating the bifurcation between proprietary legacy incumbents and open-architecture challengers. Partner with Hindustan Aeronautics Limited for digital cockpit upgrades on Su-30MKI and Jaguar fleets. For Investors and Strategic Acquirers: Carve-out targets emerge from defense-prime divestitures of non-core MRO assets and regional overhaul shop consolidations facing mechanic pipeline collapse. Long-term viability rests on platforms with decades of remaining utility—tankers, bombers, maritime patrol—where service life extension programs sustain predictable revenue. Monitor FAA reauthorization priorities and EASA CS-25 special condition evolution as inflection signals for automation retrofit certification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Thread Infrastructure Deployment | Boeing Defense leverages model-based systems engineering to compress design-to-installation cycles on C-5 avionics modernization. |
| Sovereign Sustainment Partnership Formation | BAE Systems anchors Eurofighter Typhoon retrofit revenue through UK Ministry of Defence multi-year performance contracts. |
| Open Architecture Platform Development | FACE-compliant modular mission computers enable rapid software refreshes without hardware replacement across NATO fleets. |
| Predictive Maintenance Analytics Integration | Performance-based logistics bundling merges repair, retrofit, and customization into recurring revenue streams for legacy platforms. |
| Regional MRO Joint Venture Establishment | Foreign OEM partnerships with HAL and private Indian operators capture defense indigenization procurement preferences. |
Methodological Framework
The analysis maps avionics upgrade, engine overhaul, structural modification, and airframe enhancement segments, each validated through program managers at defense primes, MRO operations directors, and fleet sustainment officers at NATO air forces. Primary interviews with FAA certification engineers and EASA airworthiness specialists cross-reference against secondary validation from FAA ADS-B Out compliance databases, EASA CS-25 special condition amendments, and military budget justification documents. Bottom-up platform-level spend estimates triangulate with top-down market aggregation across the analysis window.
Consistency checks against external benchmarks validate volume and value outputs across product type, service tier, end-user category, and technology generation segmentation. CAGRs derive from fitted growth curves applied to platform retirement schedules, regulatory mandate deadlines, and defense procurement pipelines. Modeled inputs include KC-135 re-engining program commitments, narrowbody fleet age distributions, and certified mechanic labor pool trajectories across North America and Western Europe.
Material uncertainties—supply chain disruption on titanium sponge, FAA reauthorization delays, EASA autonomous flight control certification timeline extensions—sit outside the modeled envelope. Forecasts reflect assumptions on sovereign defense spending continuity and commercial aviation traffic recovery trajectories. Recalibration cycles align with material shifts in regulatory mandate enforcement and new-production aircraft delivery rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Nigeria Aircraft Maintenance Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
MRO Software Market
Aircraft Maintenance and MRO Solutions
Aircraft Maintenance Market
Aircraft Maintenance and MRO Solutions
Aviation MRO Software Market
Aircraft Maintenance and MRO Solutions
Cloud MRO Software Market
Aircraft Maintenance and MRO Solutions
Aircraft Tire Balancer Market
Aircraft Maintenance and MRO Solutions
Aircraft Weighing Scales Market
Aircraft Maintenance and MRO Solutions
Aircraft Line Maintenance Market
Aircraft Maintenance and MRO Solutions
Aircraft Recycling Market
Aircraft Maintenance and MRO Solutions
Aircraft Autoclave Market
Aircraft Maintenance and MRO Solutions
Europe Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Middle-East and Africa Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Frame Alignment Systems Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Training Market
Aircraft Maintenance and MRO Solutions
Middle-East and Africa Aircraft MRO Market