
 Aircraft Maintenance Market | 2026-2036
Aircraft Maintenance Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Maintenance Market Analysis
Power-by-the-hour leasing and asset-light fleet management is reconfiguring capital deployment across the MRO value chain, shifting financial risk from operators to service providers. Lufthansa Technik AG leverages its integrated component pool to sustain long-term contracts with flag carriers. GE Aviation anchors its position through captive engine overhaul networks spanning multiple continents. ST Engineering Aerospace competes aggressively on turnaround time for narrow-body heavy checks.
Aircraft maintenance encompasses the inspection, repair, overhaul, and modification of airframes, engines, and components to preserve airworthiness and operational reliability, governed by flight-hour cycles and calendar-based intervals set by type certificates. The discipline relies on non-destructive testing protocols, boroscope inspections, and material traceability systems to detect fatigue cracks and corrosion before structural failure. Base Maintenance commands the largest revenue pool due to labor-intensive C-check and D-check cycles, while Predictive Maintenance grows fastest as sensor-derived health monitoring displaces scheduled interventions. Commercial Airlines dominate end-user demand, though Cargo Operators expand share as converted freighter fleets age and require specialized heavy maintenance.
The FAA mandates continued operational safety management under 14 CFR Part 121, while EASA enforces Part 145 certification standards that determine which repair stations access European-registered aircraft. The EU Green Deal's sustainable aviation fuel trajectory pressures MRO providers to certify compatibility of legacy fuel systems with new blend specifications. Stakeholders must decide whether to build predictive analytics capabilities in-house or partner with specialized software vendors before regulatory mandates harden around real-time airworthiness data reporting.
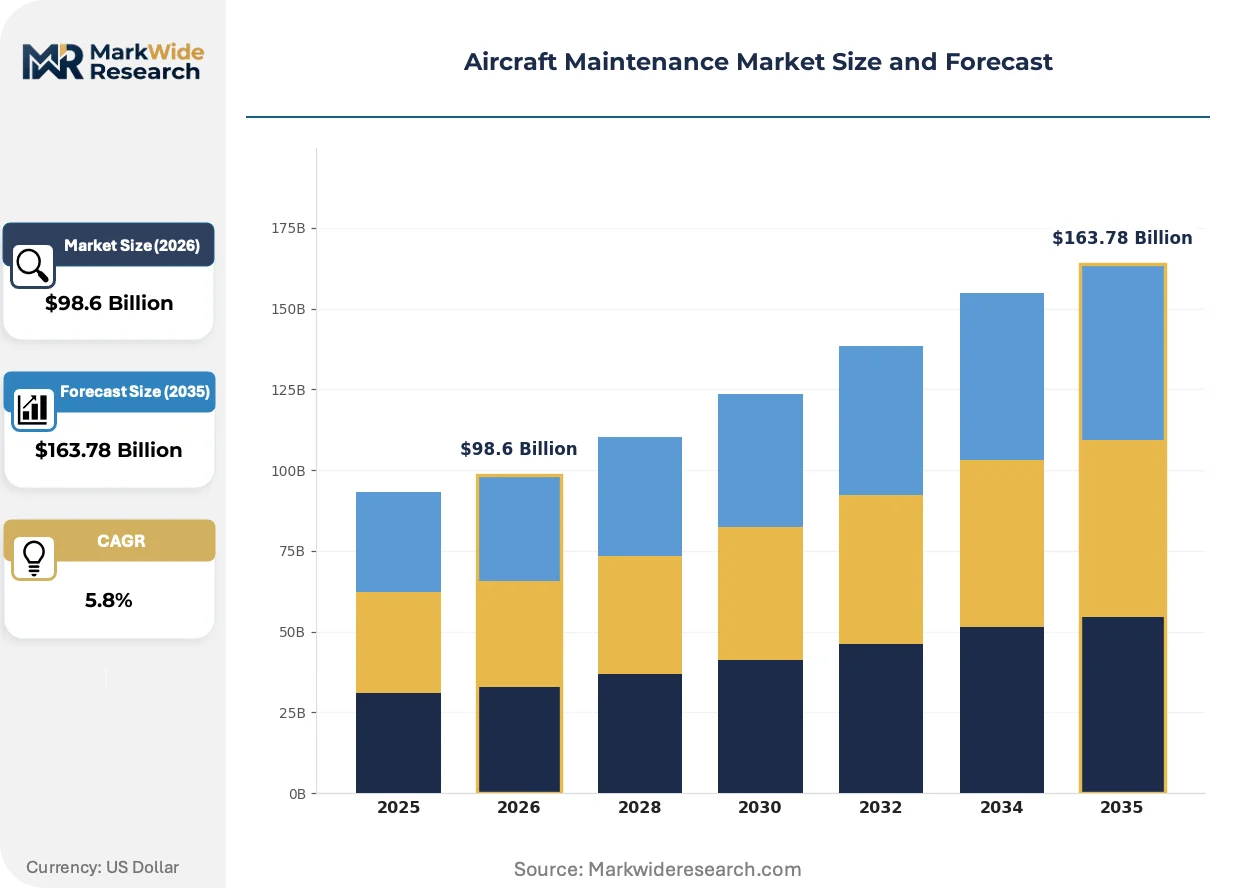
Market Dynamics
Power-by-the-hour contracts are compressing capital cycles across the MRO value chain, transferring financial exposure from airline operators to third-party service providers and reshaping how maintenance capacity gets financed and deployed.
Growth Catalysts
- FAA Aging Aircraft Directives:The FAA's updated airworthiness directive framework mandates deeper structural inspection protocols, expanding mandatory work scopes for mature narrow-body and wide-body fleets.
- Sensor-Derived Health Monitoring:Predictive maintenance platforms using real-time engine and airframe telemetry are displacing calendar-based interventions, creating demand for analytics-integrated service contracts.
- Seletar Aerospace Cluster:Singapore's concentrated MRO infrastructure at Seletar Aerospace Park draws heavy check volume from Southeast Asian low-cost carriers, consolidating regional maintenance gravity.
Market Restraints
- Specialized Technician Scarcity:The pipeline of airframe and powerplant certificated mechanics has not kept pace with fleet expansion, constraining turnaround capacity at major base maintenance facilities.
- Titanium and Superalloy Input Volatility:Engine overhaul shops face margin pressure from fluctuating aerospace-grade material costs, particularly for high-pressure turbine component replacements.
- EASA Part 145 Certification Barriers:European regulatory standards limit repair station access to EU-registered aircraft, fragmenting cross-border maintenance networks and raising compliance overhead.
Strategic Opportunities
- Converted Freighter Aging:Cargo operators expanding dedicated freighter fleets require specialized heavy maintenance for passenger-to-cargo conversions, opening dedicated hangar capacity allocations.
- EU Green Deal SAF Mandates:The sustainable aviation fuel trajectory pressures MRO providers to certify legacy fuel system compatibility with new blend specifications ahead of enforcement deadlines.
- AI-Enhanced NDT Convergence:Machine vision paired with ultrasonic testing is automating crack detection in airframe structures, compressing inspection timelines and labor intensity.
Industry Challenges
- Real-Time Airworthiness Data Mandates:Regulators are hardening reporting requirements around continuous operational safety management, forcing MROs to integrate legacy paper-based traceability systems with digital platforms.
- Component Pool Capital Intensity:Long-term power-by-the-hour contracts require providers to pre-position rotable inventory, tying up working capital in engine modules and landing gear assemblies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Maintenance Market |
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $163.78 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Line Maintenance, Base Maintenance, Overhaul, Modification End User: Commercial Airlines, Cargo Operators, Private Operators, Government Agencies Technology: Predictive Maintenance, Digital Twin, Maintenance Management Systems, Drones Maintenance Type: Regular Inspection, Unscheduled Repair, Component Replacement, Scheduled Maintenance |
| Companies Covered | AAR Corp, Lufthansa Technik AG, GE Aviation, ST Engineering Aerospace, Delta TechOps, RTX Corporation, HAECO Americas, Pratt & Whitney, Rolls-Royce, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Maintenance Market Emerging Trajectories
Digital thread technologies are rewiring how maintenance data flows from flight operations through repair stations, collapsing information latency and enabling condition-based rather than interval-driven interventions.
Borescope inspection augmented by machine learning is migrating from scheduled engine shop visits to on-wing predictive assessments. Low-cost carriers in Southeast Asia now mandate AI-assisted borescope reads for lease-return conditions. This compression of diagnostic cycles is reducing unscheduled removals and extending on-wing time.
EASA's Part 145 certification standards are tightening audit frequencies for non-EU repair stations accessing European-registered aircraft. The regulation forces third-party MROs in Singapore and Turkey to upgrade quality management systems. Asian providers are responding by hiring former EASA surveyors to pre-validate compliance.
Airline procurement departments are unbundling heavy maintenance from integrated component support, splitting contracts between base check specialists and engine pool managers. This disintermediation fragments vendor relationships previously held by full-service MROs. The pattern is most visible among Middle Eastern flag carriers renegotiating long-term agreements.
Aircraft Maintenance Market Segmentation
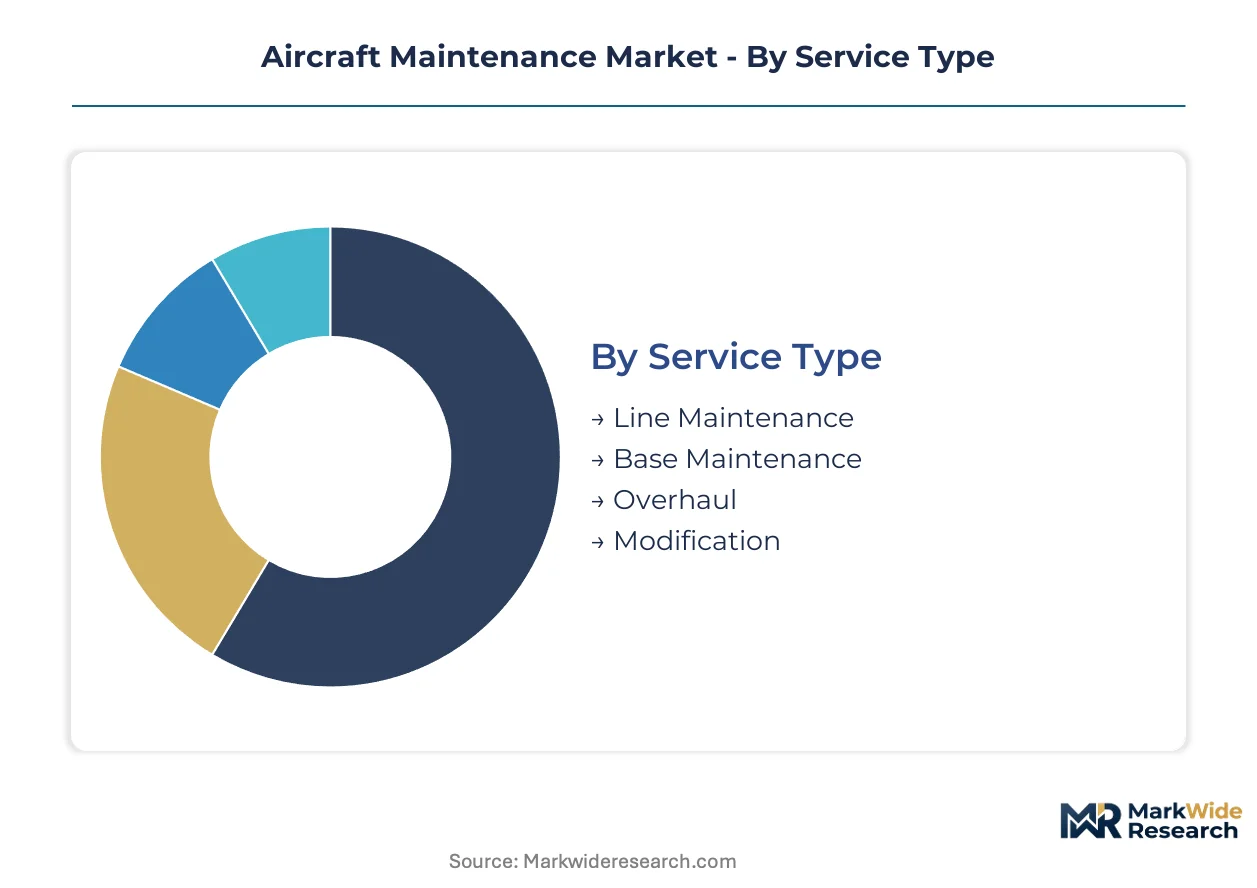
Aircraft maintenance segmentation reveals how capital, technology, and regulatory pressure distribute across service tiers. Understanding these divisions exposes where margin pools concentrate and which capability investments yield competitive separation.
Service Type:
Mature service lines anchor revenue stability while emerging formats reshape capital deployment cycles.
- Line Maintenance:Routine pre-flight, transit, and daily checks performed at airport gates and remote stands. Demand concentrates at hub airports in Singapore, Dubai, and Frankfurt where narrow-body turnaround density justifies dedicated rapid-response crews. FAA Part 121 mandates drive minimum staffing levels regardless of flight volume fluctuations.
- Base Maintenance:Labor-intensive C-check and D-check cycles requiring hangar confinement for structural inspection and system overhaul. Southeast Asian low-cost carriers outsource these heavy checks to Seletar Aerospace Park providers rather than building captive facilities. EASA Part 145 certification barriers limit which third-party stations handle European-registered aircraft.
- Overhaul:Engine and component shop visits involving disassembly, non-destructive testing, and reassembly to manufacturer specifications.
- Modification:Passenger-to-freighter conversions, cabin reconfigurations, and avionics upgrades extending airframe economic life.
Base Maintenance retains volume leadership; Modification holds the steepest expansion curve.
End User:
Customer type determines contract structure, payment terms, and technical specification intensity.
- Commercial Airlines:Full-service and low-cost carriers generating scheduled maintenance demand tied to fleet age and utilization rates. Flag carriers in the Middle East are unbundling heavy maintenance from integrated component support, splitting contracts between specialists. Power-by-the-hour agreements transfer financial risk to MRO providers.
- Cargo Operators:Dedicated freighter fleets and converted passenger aircraft requiring specialized heavy maintenance. Aging converted freighters in North American and European express networks drive demand for structural reinforcements and door cut modifications.
- Private Operators:Business jet and fractional ownership fleets demanding flexible scheduling and premium turnaround guarantees.
- Government Agencies:Military and coast guard aircraft subject to distinct procurement protocols and security-cleared technician requirements.
Commercial Airlines dominate absolute spend; Cargo Operators are climbing the fastest as e-commerce logistics networks expand dedicated freighter capacity.
Technology:
Technology adoption splits between proven digital infrastructure and experimental platforms seeking regulatory validation.
- Predictive Maintenance:Sensor-derived health monitoring platforms using real-time engine and airframe telemetry to displace calendar-based interventions. GE Aviation and Rolls-Royce deploy these analytics across their captive overhaul networks. EASA mandates on continuous operational safety management harden requirements for real-time data reporting.
- Digital Twin:Virtual airframe and engine replicas enabling simulated stress testing and remaining-life prediction.
- Maintenance Management Systems:Enterprise software tracking work orders, labor allocation, and regulatory documentation across repair station networks.
- Drones:Automated exterior inspection platforms reducing scaffold time for airframe damage assessment.
Predictive Maintenance commands the largest implementation budgets; Digital Twin represents the most experimental deployment category.
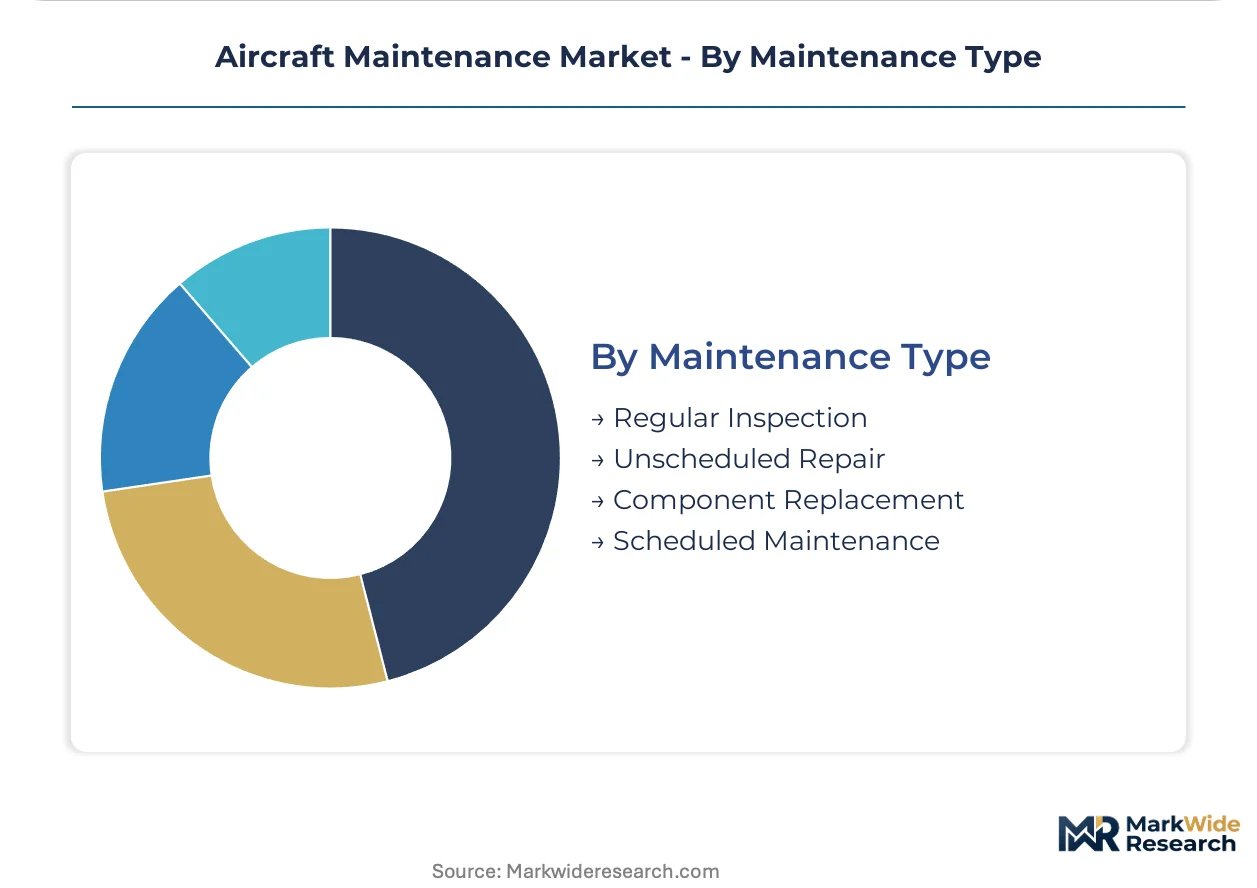
Maintenance Type:
Work scope classification follows regulatory intervals, failure modes, and supply chain availability.
- Regular Inspection:Calendar and flight-hour mandated checks from A-checks through D-checks defined by type certificates. FAA aging aircraft directives deepen structural inspection protocols for mature narrow-body fleets. Singapore's MRO cluster captures regional volume through concentrated hangar capacity and EASA-aligned quality systems.
- Unscheduled Repair:Ad-hoc interventions addressing in-service failures, foreign object damage, and airworthiness directive compliance.
- Component Replacement:Rotable and consumable part exchanges governed by pool availability and repair turnaround times.
- Scheduled Maintenance:Pre-planned interventions aligned with lease return conditions and seasonal fleet utilization patterns.
Regular Inspection absorbs the greatest labor hours; Predictive analytics integration is accelerating fastest within Scheduled Maintenance planning cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Singapore's Seletar Aerospace Park while cost-sensitive Southeast Asian carriers drive volume toward third-party heavy-check providers. This asymmetry shapes how MRO capacity deploys across the Asia-Pacific rim and beyond.
United States
The FAA's aging aircraft directives deepen structural inspection mandates for mature narrow-body fleets operated by major network carriers. Delta TechOps and other airline-affiliated MROs leverage domestic hangar capacity to capture this mandatory work scope. Dallas-Fort Worth and Atlanta anchor the heaviest concentration of base maintenance infrastructure serving North American operators.
Singapore
Low-cost carriers from Indonesia, the Philippines, and Vietnam outsource C-check and D-check cycles to Seletar's clustered MRO facilities rather than building captive infrastructure. EASA Part 145 certification requirements filter which third-party stations handle European-registered aircraft transiting through Changi. ST Engineering Aerospace compresses turnaround times for narrow-body heavy checks to capture this regional flow.
Germany
Lufthansa Technik AG sustains long-term power-by-the-hour contracts with flag carriers through integrated component pools and captive overhaul networks. The country's national aviation regulator enforces stringent continued airworthiness management organization standards. Hamburg anchors the deepest concentration of wide-body heavy maintenance capacity serving European and Middle Eastern operators.
United Arab Emirates
Middle Eastern flag carriers are unbundling heavy maintenance from integrated component support, splitting contracts between base-check specialists and engine pool managers. The General Civil Aviation Authority aligns its regulatory framework with EASA standards to facilitate cross-border maintenance access. Dubai's MRO cluster draws heavy-check volume from African and South Asian operators seeking premium turnaround guarantees.
China
Domestic airlines expand dedicated MRO capacity to serve the world's second-largest commercial fleet, though foreign repair station access remains constrained by certification reciprocity limitations. The Civil Aviation Administration of China tightens oversight of continued airworthiness management under evolving Part 145-equivalent standards. Shanghai and Beijing concentrate the majority of indigenous heavy-maintenance infrastructure serving state-owned carriers.
Aircraft Maintenance Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in narrower technical niches. The market structures around three distinct tiers: full-service MROs with captive airline heritage, independent third-party heavy-check providers, and OEM-affiliated engine overhaul networks. Consolidation pressure intensifies as airlines unbundle integrated contracts and procurement departments split vendor relationships. Geographic expansion into Southeast Asian MRO clusters and strategic partnerships for predictive analytics capabilities represent the dominant competitive vectors.
Among North American service providers, AAR Corp exemplifies the independent third-party archetype serving diversified airline portfolios. Lufthansa Technik AG anchors the European full-service tier through its integrated component pool model. GE Aviation occupies a distinctive position as an OEM-captive engine overhaul network spanning multiple continents. ST Engineering Aerospace represents the Asia-Pacific specialist archetype competing aggressively on narrow-body turnaround velocity from its Singapore base.
| Leading Market Players |
|---|
| AAR Corp |
| Lufthansa Technik AG |
| GE Aviation |
| ST Engineering Aerospace |
| Delta TechOps |
| RTX Corporation |
| HAECO Americas |
| Pratt & Whitney |
| Rolls-Royce |
| Others |
Supply Flow & Price Mechanics
Changi-Singapore freight corridors absorb elevated logistics costs for titanium and superalloy shipments, concentrating procurement leverage among Seletar-based MRO providers while forcing tier-2 shops in Indonesia and Vietnam to accept thinner margins on heavy-check contracts.
Pricing Analysis
The customization-premium spread separates EASA Part 145-certified base maintenance from uncertified line maintenance, with flag carriers paying substantial uplifts for integrated component pool guarantees. Pricing stratifies across OEM-authorized overhaul, independent heavy-check providers, and non-certified line stations based on audit frequency and material traceability systems. Cost compression in narrow-body C-checks is intensifying because low-cost carriers unbundle engine support from airframe contracts. Cargo operators show least price sensitivity due to lease-return penalties and specialized freighter modification requirements.
Supply Chain Analysis
Contract manufacturing concentration for engine overhaul rests on GE Aviation and Pratt & Whitney captive networks spanning the United States, Germany, and Singapore. Aerospace-grade titanium draws from Japanese and Russian smelters, while superalloy castings hinge on precision foundries in the United States and France. Single-source vulnerability pervades high-pressure turbine blade supply, with FAA airworthiness directives mandating specific OEM-approved sources. Distribution runs through rotable component pools pre-positioned at Seletar, Hamburg, and Dallas-Fort Worth hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent MROs face substitution pressure from predictive analytics platforms that displace scheduled interventions with condition-based maintenance, eroding the volume foundation of calendar-driven heavy-check contracts.
For Market Incumbents: Harden predictive maintenance capabilities through captive software development or exclusive partnerships with sensor-analytics vendors before EASA mandates harden around real-time airworthiness reporting. Deepen vertical integration into aerospace-grade material recycling to offset titanium and superalloy input volatility threatening engine overhaul margins. For New Entrants and Emerging Players: Establish a beachhead in converted freighter heavy maintenance, where aging passenger-to-cargo fleets in North American express networks outstrip dedicated hangar capacity. Target Southeast Asian low-cost carriers with AI-assisted borescope inspection services for lease-return conditions, leveraging faster turnaround guarantees against incumbent base maintenance providers. For Investors and Strategic Acquirers: EASA Part 145 certification tightening reshapes the acquisition landscape toward repair stations with pre-validated quality management systems and former regulator surveyors on staff. Prioritize mid-cap Asian providers with Seletar proximity and narrow-body heavy-check velocity. Monitor FAA aging aircraft directive expansion as the inflection signal for mandatory structural inspection volume.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Development | Sensor-derived health monitoring displaces calendar-based interventions, compressing revenue cycles for traditional base maintenance. |
| EASA Part 145 Certification Pre-Validation | Repair stations hiring former EASA surveyors secure access to European-registered aircraft transiting through Singapore and Dubai. |
| Converted Freighter Hangar Capacity Allocation | Dedicated passenger-to-cargo modification lines capture aging narrow-body feedstock from e-commerce logistics expansion. |
| Aerospace Material Recycling Integration | Captive titanium and superalloy reclamation insulates engine overhaul margins from primary metal price volatility. |
| Power-by-the-Hour Contract Restructuring | Unbundling component support from heavy maintenance fragments vendor relationships and shifts capital risk to MRO providers. |
Methodological Framework
A standing panel of base maintenance directors, power-by-the-hour contract managers, EASA quality auditors, and airline procurement executives provided ongoing calibration across primary interview cycles. Secondary validation drew from FAA airworthiness directive filings, EASA Part 145 certification registries, airline fleet planning disclosures, and customs records for aerospace-grade titanium and superalloy trade flows. Bottom-up triangulation across repair station capacity utilization and top-down reconciliation against fleet age demographics anchored the analytical framework.
Scenario bracketing around FAA regulatory enforcement intensity, low-cost carrier outsourcing propensity, and predictive maintenance adoption curves bounded the projection horizon. Segmentation dimensions modeled encompass service type, end-user category, technology adoption tier, and geographic regulatory cluster. CAGRs were derived from elasticity-adjusted fleet growth projections and maintenance interval compression factors. Industry-specific forecast inputs included engine shop visit rates by mature narrow-body fleet segment and Seletar Aerospace Park hangar utilization benchmarks.
Stress conditions across titanium price volatility, EASA audit frequency acceleration, and low-cost carrier captive MRO buildout were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding continued regulatory harmonization between FAA and EASA frameworks. Quarterly review of fleet retirement schedules and predictive maintenance platform deployment rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Aircraft Landing Gear Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Africa Aircraft Windshield Wiper and Washer System Market
Aircraft Maintenance and MRO Solutions
Military Aviation Maintenance, Repair, and Overhaul Market
Aircraft Maintenance and MRO Solutions
Middle-East and Africa Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Vacuum Cleaners Market
Aircraft Maintenance and MRO Solutions
Aircraft Weight Scale Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Training Market
Aircraft Maintenance and MRO Solutions
MRO Protective Coatings Market
Aircraft Maintenance and MRO Solutions
Global Degaussing System Market
Aircraft Maintenance and MRO Solutions
Gas Turbine MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Exterior Strip and Repaint Services Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Weighing Scales Market
Aircraft Maintenance and MRO Solutions
US Aerospace Components MRO Market
Aircraft Maintenance and MRO Solutions
Digital MRO Market
Aircraft Maintenance and MRO Solutions
Aviation Engine MRO Market