
 Cloud MRO Software Market | 2026-2036
Cloud MRO Software Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud MRO Software Market Analysis
Software-defined predictive maintenance modules are repositioning how aviation operators contract for fleet uptime, shifting capital expenditure toward recurring subscription models. IFS AB leverages deep aerospace configuration logic to sustain competitive positioning among flag carriers with complex mixed fleets. Ramco Systems anchors its presence across Asia-Pacific through aviation-specific compliance architectures. TRAX Technologies specializes in mobile-first maintenance execution, differentiating its platform for line maintenance crews requiring offline capability.
Cloud MRO software encompasses browser-accessible applications that manage maintenance, repair, and overhaul operations through centralized databases, API-connected asset registries, and role-based workflow engines processing airworthiness directives, parts traceability, and labor documentation in real time. Its primary purpose is eliminating paper-based technical records while enforcing regulatory compliance across distributed maintenance networks. Maintenance Management functions constitute the established revenue base where operator mandates for digital logbooks have already penetrated large carriers, while Predictive Maintenance features represent the fastest-expanding margin pool as machine learning models trained on sensor data reduce unscheduled removal rates. Hybrid Cloud deployments are gaining structural importance among defense contractors and national airlines with sovereignty requirements that preclude pure public cloud architectures.
FAA airworthiness standards, EASA continuing airworthiness management organization rules, and ICAO safety management system protocols collectively mandate auditable digital records, directly shaping procurement criteria for MRO software vendors seeking operator certification. India's DGCA has aligned with these frameworks while adding BIS data localization requirements that influence hosting architecture decisions for vendors operating in that jurisdiction. Stakeholders must monitor how evolving cybersecurity directives from aviation regulators reshape API interoperability standards and third-party integration requirements.
Market Dynamics
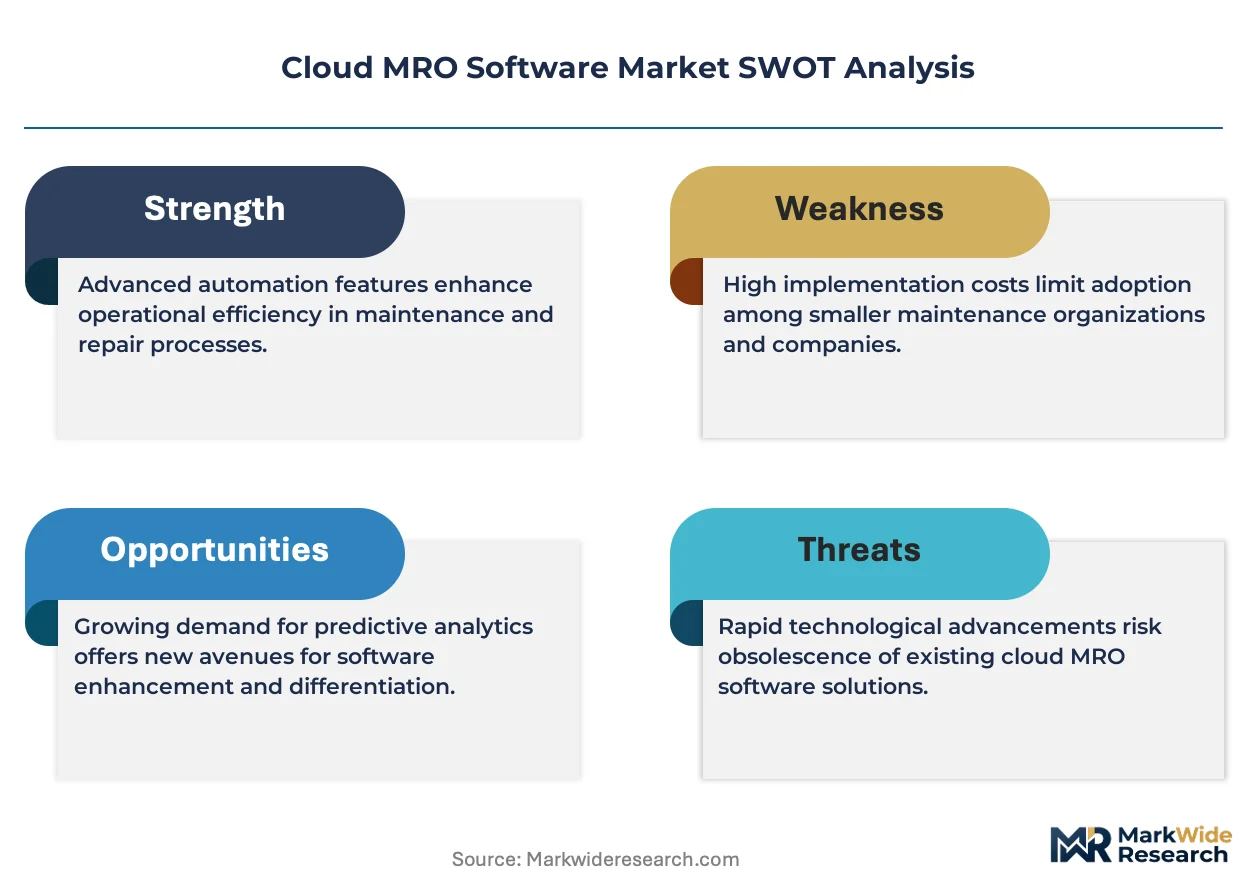
Airlines are abandoning perpetual licensing for predictive maintenance modules, converting capital expenditure into recurring subscriptions that lock vendors into long-term data relationships and reshape contract negotiation leverage.
Growth Catalysts
- FAA Airworthiness Directives:Mandates for digital technical records push legacy operators toward browser-accessible MRO platforms, eliminating paper-based compliance gaps.
- Sensor Fusion Architectures:Engine health monitoring systems generate continuous data streams that feed machine learning models, reducing unscheduled component removals.
- India:Carriers modernizing narrow-body fleets and MRO facilities digitizing operations create concentrated demand for cloud-native compliance architectures.
Market Restraints
- Hybrid Cloud Infrastructure Costs:Defense contractors and national airlines with sovereignty requirements face elevated capital outlays for private cloud nodes.
- API Interoperability Friction:Fragmented data standards between OEM sensor protocols and third-party MRO platforms delay integration timelines.
- Cybersecurity Certification Delays:Evolving aviation regulator directives on API security reshape vendor development roadmaps and extend procurement cycles.
Strategic Opportunities
- Line Maintenance Mobility:Offline-capable mobile execution platforms address tarmac connectivity gaps, opening segments beyond hangar-based heavy maintenance.
- EASA Continuing Airworthiness Management:CAMO rules create compliance tailwinds for vendors offering integrated continuing airworthiness documentation.
- Parts Traceability Convergence:Blockchain-anchored provenance systems merging with legacy MRO databases unlock new subscription revenue pools.
Industry Challenges
- Aerospace Configuration Expertise Scarcity:Vendors struggle to hire engineers fluent in mixed-fleet maintenance logic and regulatory documentation standards.
- Legacy System Integration Complexity:Decades-old ERP installations in established carriers resist API-connected asset registry migration without multimillion-dollar middleware investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud MRO Software Market |
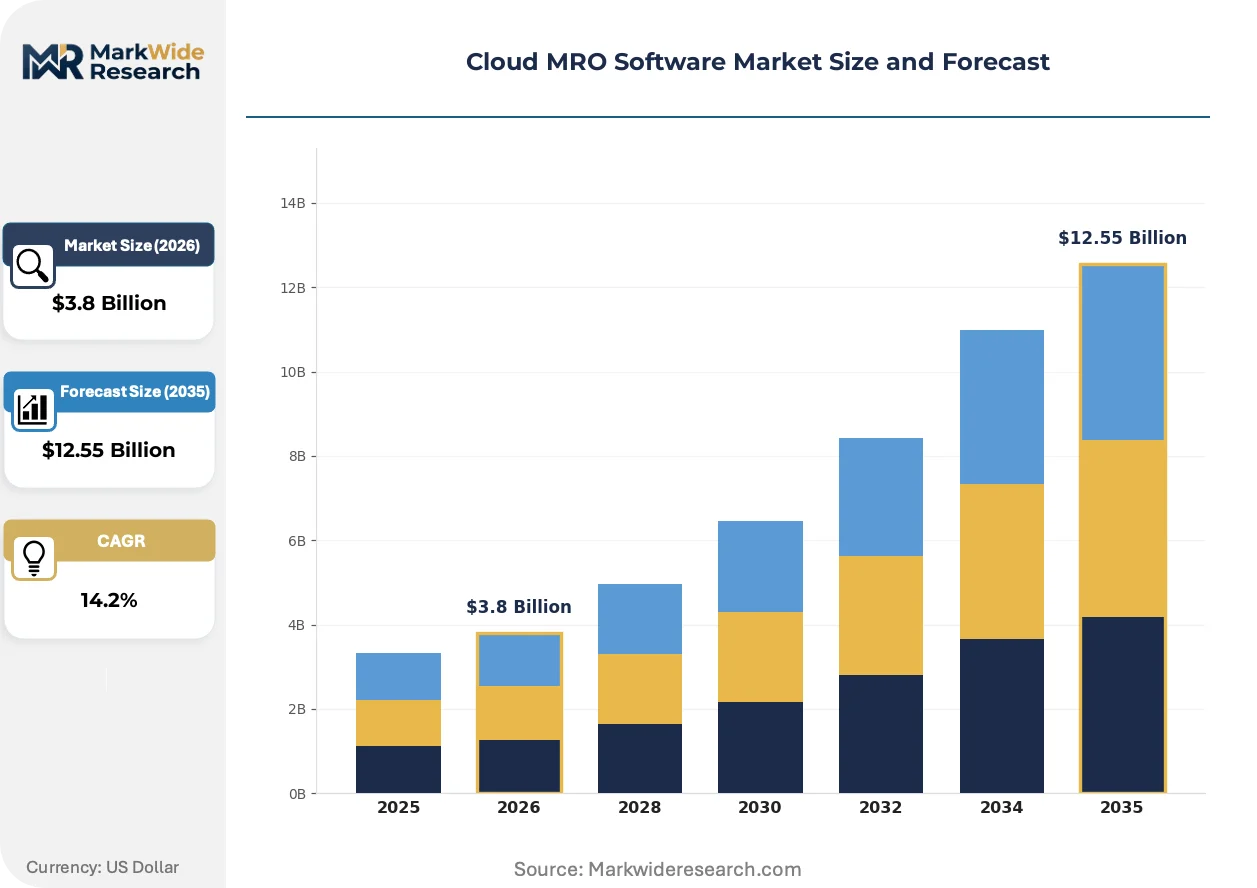
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Maintenance Management, Inventory Control, Analytics Tools, Workflow Automation Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud End User: Aerospace, Manufacturing, Oil & Gas, Transportation Feature: Mobile Access, Predictive Maintenance, Real-time Reporting, Asset Tracking |
| Companies Covered | Ultramain Systems, Veryon, Ramco Systems, Swiss Aviation Software, AMOS Group AG, IFS AB, CAMP Systems, Rusada, TRAX Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud MRO Software Market Emerging Trajectories
Machine learning inference at the edge is compressing maintenance decision cycles from days to hours, while regulatory data localization mandates force vendors to rearchitect hosting strategies around sovereign cloud requirements.
Digital twin frameworks are expanding into fleet-wide simulation environments that mirror physical aircraft systems in real time. Low-cost carriers in Southeast Asia deploy these models to optimize component swap schedules across high-utilization narrow-body operations. The technology is expanding into contract structures where vendors guarantee uptime thresholds rather than selling software licenses alone.
EASA continuing airworthiness management organization rules now require auditable digital records for all EU-registered commercial aircraft. This industrial consequence forces non-European MRO software vendors to establish EU data residency or lose CAMO-certified operator contracts. Maintenance management functions serving European flag carriers face the most acute compliance pressure, accelerating procurement of platforms with embedded regulatory workflow engines.
Airline technical procurement teams now demand API-first architectures that unbundle monolithic MRO suites into interoperable microservices. Third-party predictive analytics vendors are displacing integrated platform incumbents in line maintenance segments where modular deployment reduces switching costs. This pattern concentrates among Asia-Pacific carriers modernizing legacy fleets, where greenfield infrastructure decisions favor composable software stacks over single-vendor dependencies.
Cloud MRO Software Market Segmentation
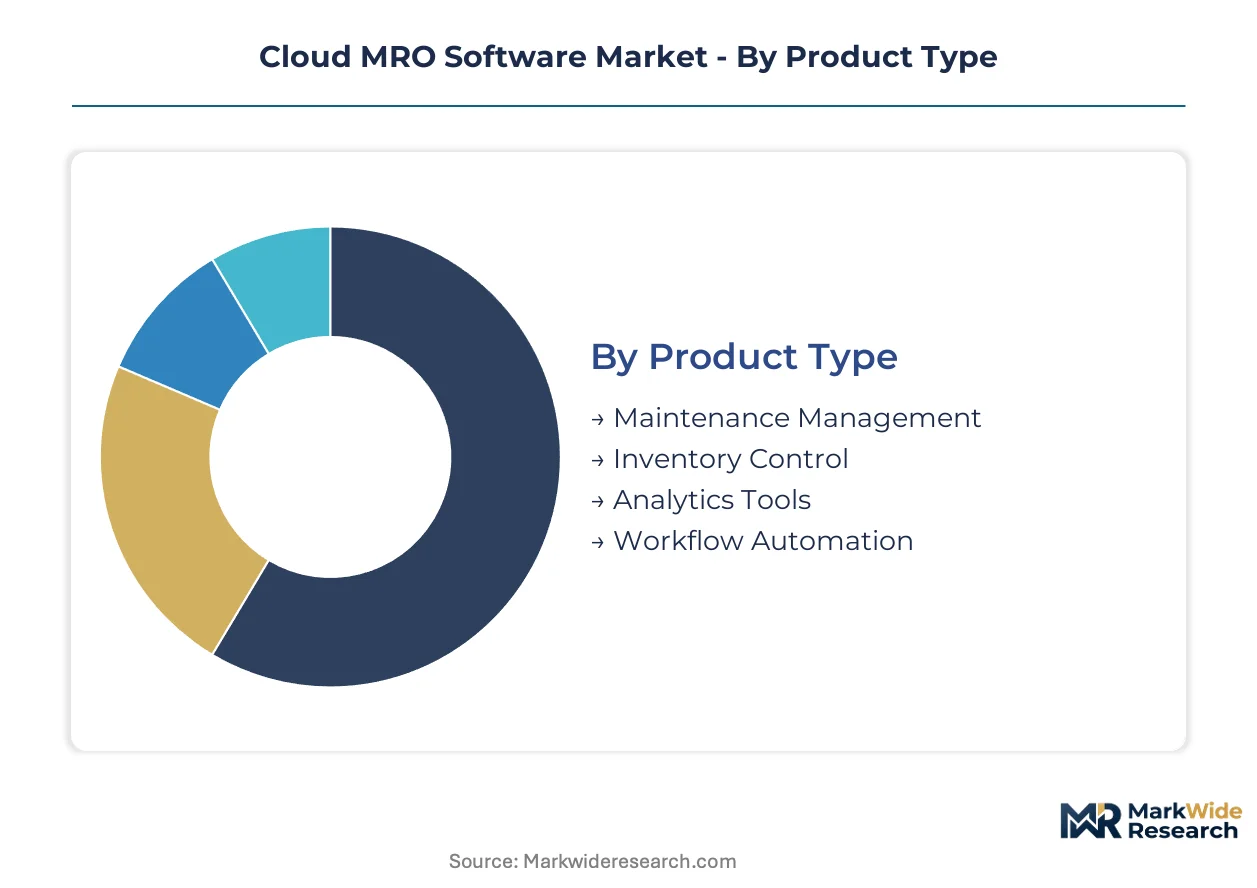
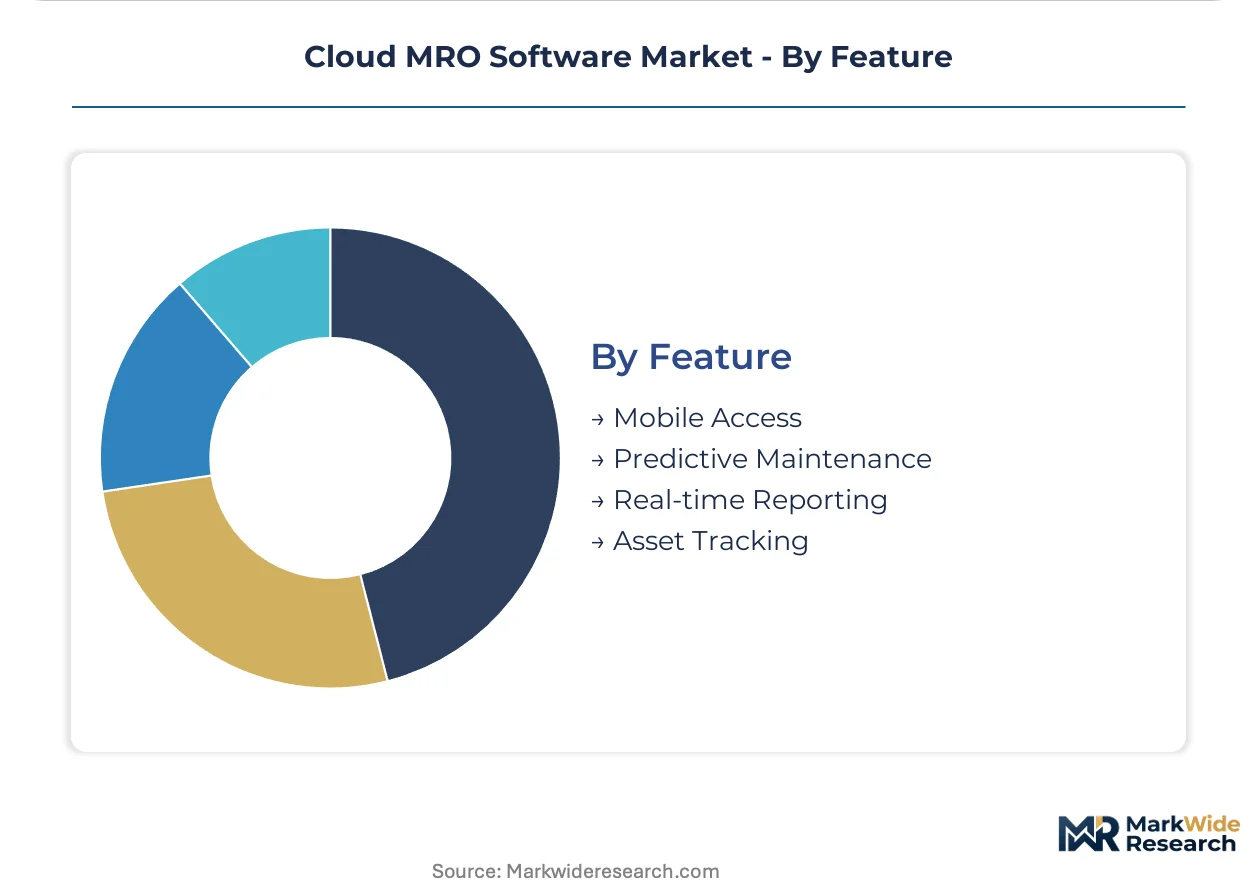
Cloud MRO software procurement patterns diverge sharply across operational contexts, with fleet complexity and regulatory exposure dictating feature prioritization. Deployment architecture decisions increasingly reflect data sovereignty mandates rather than pure cost optimization.
Product Type:
Buyers differentiate by maintenance operational maturity, with legacy carriers prioritizing compliance documentation while digital-native operators seek predictive capabilities.
- Maintenance Management:Core modules governing work order execution, labor certification tracking, and airworthiness directive compliance form the established revenue base. Large flag carriers with mixed fleets drive demand here as FAA and EASA mandates force digitization of technical logbooks.
- Predictive Maintenance:Machine learning models trained on sensor fusion data reduce unscheduled component removals. Asia-Pacific narrow-body operators expanding fleet utilization rates represent the most active procurement segment for these capabilities.
- Inventory Control:Parts traceability engines with blockchain-anchored provenance documentation address supply chain integrity requirements.
- Analytics Tools:Fleet-wide performance dashboards aggregate maintenance cost data across distributed MRO networks.
- Workflow Automation:Rule-based engines streamline documentation approval chains for CAMO-certified operators.
Maintenance Management leads volumes today; Predictive Maintenance is gaining share fastest.
Deployment:
Architecture selection tracks organizational data governance requirements, with defense contractors and national airlines operating under distinct constraints from commercial low-cost carriers.
- Public Cloud:Browser-accessible SaaS platforms minimize capital outlay for regional carriers and independent MRO facilities. Southeast Asian operators modernizing legacy fleets favor this model for rapid deployment without infrastructure investment.
- Hybrid Cloud:Split architectures host sensitive airworthiness data on private nodes while leveraging public cloud for analytics workloads. India's DGCA data localization requirements and BIS standards push vendors toward this configuration for contracts with domestic carriers.
- Private Cloud:Sovereign infrastructure satisfies military aviation and government fleet security protocols.
- Multi-Cloud:Distributed hosting across providers mitigates vendor lock-in risks for large operator groups.
Public Cloud dominates current installations; Hybrid Cloud shows the steepest expansion trajectory among new procurements.
End User:
Industry verticals exhibit divergent regulatory density and asset criticality profiles, shaping software configuration requirements and contract structures.
- Aerospace:Commercial aviation operators with CAMO obligations and continuing airworthiness management requirements constitute the primary demand source. FAA airworthiness directives and EASA compliance frameworks mandate auditable digital records, creating non-negotiable procurement criteria.
- Manufacturing:Heavy industrial equipment operators leverage MRO platforms for production line uptime optimization, though with lighter regulatory documentation burdens than aviation.
- Oil & Gas:Offshore platform maintenance teams require offline-capable mobile execution for connectivity-constrained environments.
- Transportation:Rail and maritime operators adopt adapted aviation-grade compliance architectures for safety-critical fleet management.
Aerospace commands the dominant share; Manufacturing is expanding most quickly as Industry 4.0 digitization spreads.
Feature:
Capability prioritization reflects workforce mobility patterns and the shift from reactive to condition-based maintenance paradigms.
- Predictive Maintenance:Sensor data ingestion pipelines and machine learning inference engines transform maintenance scheduling from calendar-based to condition-driven models. Engine health monitoring integration is climbing fastest among Asia-Pacific carriers with high-utilization narrow-body operations.
- Mobile Access:Offline-synchronized tablet applications enable line maintenance crews to execute tasks on the tarmac without hangar connectivity. This capability opens segments beyond traditional heavy maintenance facilities.
- Real-time Reporting:Live dashboard feeds for maintenance control centers accelerate decision cycles during aircraft-on-ground events.
- Asset Tracking:RFID and IoT-enabled component location services reduce parts search time in distributed MRO networks.
Mobile Access leads current feature adoption; Predictive Maintenance is climbing fastest in new contract specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates procurement velocity for cloud MRO platforms, while Germany anchors European compliance architecture development. Divergent regulatory timelines across aviation authorities reshape vendor hosting strategies and contract localization requirements.
United States
FAA airworthiness directives mandate digital technical records for commercial operators, accelerating legacy carrier migrations. The FAA's Part 121 regulations enforce auditable maintenance documentation standards. Dallas-Fort Worth and Seattle-Tacoma aerospace clusters host MRO facilities digitizing operations under these compliance pressures.
Germany
Lufthansa Technik's engineering standards drive demand for integrated continuing airworthiness platforms. EASA continuing airworthiness management organization rules require EU data residency for CAMO-certified operators. Hamburg and Munich MRO hubs digitize heavy maintenance workflows to satisfy these documentation mandates.
India
IndiGo and Air India narrow-body fleet expansions create concentrated demand for predictive maintenance modules. DGCA alignment with ICAO safety management protocols plus BIS data localization requirements push vendors toward hybrid cloud architectures. Bangalore and Hyderabad MRO facilities digitize line maintenance operations under these combined pressures.
United Kingdom
Heathrow and Gatwick-based MRO providers modernize legacy ERP installations to satisfy post-Brexit regulatory divergence from EASA frameworks. The Civil Aviation Authority's digital record-keeping mandates reshape procurement criteria for maintenance platforms. London's aviation finance clusters influence software subscription contract structures across European operator networks.
United Arab Emirates
Emirates and Etihad engineering divisions deploy sensor fusion architectures across wide-body fleets. GCAA regulations align with ICAO standards while adding cybersecurity certification layers for third-party MRO platform integrations. Dubai South's MRO campus attracts vendors establishing Middle East data residency for regional carrier contracts.
Cloud MRO Software Market Vendor Landscape
Top-tier vendors anchor the compliance-intensive segment, while specialized boutiques occupy predictive analytics niches. The vendor base stratifies across three tiers: full-suite incumbents with aerospace configuration depth, modular specialists in mobile execution, and emerging players in blockchain-anchored parts traceability. Strategic moves concentrate on API-first architecture investments and sovereign cloud partnerships for data localization mandates.
Within the aerospace configuration tier, IFS AB and Ramco Systems exemplify vendors sustaining competitive positioning through regulatory workflow depth. TRAX Technologies occupies a distinct position in mobile-first maintenance execution. Swiss Aviation Software and AMOS Group AG anchor European compliance architecture development. These named entities represent archetypal competitive positions rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Ultramain Systems |
| Veryon |
| Ramco Systems |
| Swiss Aviation Software |
| AMOS Group AG |
| IFS AB |
| CAMP Systems |
| Rusada |
| TRAX Technologies |
| Others |
Supply Flow & Price Mechanics
Data center compute pricing indices cascade through cloud MRO software supply chains, compressing margin structures for vendors hosting sensor fusion workloads while amplifying differentiation premiums for sovereign-compliant architectures. This cost transmission splits procurement into subscription tiers tethered to deployment complexity and regulatory certification depth.
Pricing Analysis
Capacity additions in India's Bangalore and Hyderabad cloud regions are reshaping price floors for Asia-Pacific deployments, forcing incumbent vendors toward three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on EASA CAMO certification tier and API interoperability depth, with FAA-compliant modules commanding premiums over baseline maintenance management offerings. Pricing pressure stems from open-source analytics engines displacing proprietary predictive models in line maintenance segments. Low-cost Southeast Asian carriers exhibit acute price sensitivity, while European flag carriers prioritize compliance assurance over subscription cost.
Supply Chain Analysis
Regional distribution centers in Germany, India, and the United Arab Emirates anchor hub-and-spoke delivery patterns for cloud MRO platform deployment. Software development concentrates in Sweden, Switzerland, and the United States, with implementation services drawing from India's technical workforce and Germany's aerospace engineering clusters. Raw material dependencies span hyperscaler compute capacity, aviation sensor protocol licenses, and blockchain node infrastructure. Supply chain risk centers on single-source vulnerability for engine health monitoring API integrations with OEMs. Distribution runs through certified implementation partners and direct enterprise sales teams serving flag carrier procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud MRO software offers margin expansion through predictive maintenance module attach rates, where sensor data monetization converts capital expenditure into recurring revenue streams with 3-5 year contract tenures.
For Market Incumbents: Cement aerospace configuration depth as the primary defensive moat against modular analytics entrants displacing integrated suites in Asia-Pacific greenfield procurements. Acquire mobile-first execution specialists to close line maintenance capability gaps exposed by TRAX Technologies' offline-synchronized platforms. Prioritize sovereign cloud partnerships in India and Germany to satisfy DGCA and EASA data localization mandates before compliance deadlines harden procurement criteria. For New Entrants and Emerging Players: Independent MRO facilities in Southeast Asia represent the most penetrable channel partner type for API-first microservices architectures unbundling legacy platform functionality. Target India's narrow-body fleet modernization wave with predictive maintenance modules priced below full-suite incumbents. Pursue OEM sensor protocol licensing agreements as the critical go-to-market angle, bypassing years of aviation configuration expertise accumulation. For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid cloud infrastructure specialists possessing pre-certified sovereign hosting nodes in India and EU jurisdictions. Long-term viability favors vendors with embedded regulatory workflow engines rather than pure analytics plays vulnerable to open-source displacement. Monitor FAA cybersecurity directive implementation timelines as the signal to watch for procurement cycle acceleration and vendor consolidation triggers.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | Establishes DGCA-compliant data residency for Indian carrier contracts against BIS localization mandates. |
| API-First Architecture Investment | Unbundles monolithic suites into interoperable microservices for Asia-Pacific greenfield procurement preferences. |
| Mobile Execution Platform Acquisition | Closes line maintenance capability gaps for tarmac connectivity-constrained operations beyond hangar facilities. |
| Sensor Protocol Licensing Agreement | Secures OEM data stream access for predictive maintenance model training and unscheduled removal reduction. |
| Blockchain Traceability Module Launch | Captures parts provenance subscription revenue as supply chain integrity requirements harden across aviation MRO networks. |
Methodological Framework
Coverage spans the United States, Germany, India, the United Kingdom, and the United Arab Emirates, with primary inputs from each jurisdiction triangulated against secondary validation. Chief technology officers at flag carriers, MRO facility operations directors, aviation regulatory compliance officers, and platform integration specialists contributed structured interviews. Secondary sources include FAA airworthiness directive filings, EASA continuing airworthiness management organization documentation, DGCA circulars, SEC filings from listed aerospace software vendors, and hyperscaler regional capex disclosures. Bottom-up deployment counts and top-down addressable market sizing were reconciled through iterative cross-checks.
Rate-of-change decomposition separates baseline maintenance management module growth from predictive maintenance acceleration across the analysis window. Segmentation dimensions modeled include deployment architecture, fleet complexity tier, regulatory jurisdiction cluster, and integration maturity level. CAGRs derive from installed base expansion rates, subscription pricing trajectory assumptions, and attach rate progression for advanced analytics features. Industry-specific forecast inputs incorporate narrow-body fleet delivery schedules and EASA CAMO compliance deadline phasing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to aviation regulator cybersecurity directive evolution and OEM data sharing policy shifts. Outputs reflect documented assumptions regarding sensor fusion adoption curves and sovereign cloud infrastructure buildout timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Africa Aviation MRO Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Maintenance Repair and Overhaul (MRO) Market
Aircraft Maintenance and MRO Solutions
Narrowbody Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Storage, Preservation and Reactivation Services Market
Aircraft Maintenance and MRO Solutions
Aviation Asset Management Market
Aircraft Maintenance and MRO Solutions
Aircraft Wheel Bead Breakers Market
Aircraft Maintenance and MRO Solutions
Airline Maintenance Software Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Disassembly Dismantling and Recycling Market
Aircraft Maintenance and MRO Solutions
GCC Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Nigeria Aircraft Maintenance Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Component MRO Market
Aircraft Maintenance and MRO Solutions
Aviation MRO Software Market
Aircraft Maintenance and MRO Solutions
North America Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
MRO Software Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Software Market