
 Aircraft Carrier Arresting Systems Market | 2026-2036
Aircraft Carrier Arresting Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Carrier Arresting Systems Market Analysis
Naval aviation procurement is unwinding from legacy platform maintenance toward next-generation carrier construction programs. General Atomics leverages its electromagnetic aircraft launch and recovery system portfolio to anchor the U.S. Navy's Ford-class modernization. Curtiss-Wright Corporation sustains its position through advanced arresting engine and control system manufacturing for allied fleets. Safran competes in European carrier upgrade cycles with integrated landing systems for the French Navy's Charles de Gaulle and future PANG programs.
Aircraft carrier arresting systems comprise high-tensile wire rope, hydraulic damping mechanisms, and electromechanical controls engineered to decelerate landing aircraft from approach speeds exceeding 150 knots to full stop within 340 feet. These systems integrate with flight deck operations to ensure recovery of both manned fighters and unmanned aerial vehicles under adverse sea states. Wire rope systems retain the largest installed base across Nimitz and Queen Elizabeth class carriers, while magnetic and electromechanical technologies are displacing legacy hydraulic architectures in new construction programs. Smart systems with embedded load sensors and predictive maintenance algorithms command premium positioning, whereas integrated solutions bundling launch and recovery functions capture expanding margin pools from full-deck modernization contracts.
The U.S. Navy's Naval Sea Systems Command sets arresting gear certification standards that dictate product qualification timelines for all suppliers. The EU Green Deal's defense industrial emissions framework and REACH chemical compliance for hydraulic fluids shape material selection and aftermarket service protocols in European programs. China's GB standards and military equipment quality certification from the national defense regulator impose localization requirements on foreign component suppliers. Stakeholders must monitor electromagnetic recovery technology maturation against legacy hydraulic retrofit economics as carrier fleets bifurcate between new construction and life-extension pathways.
Market Dynamics
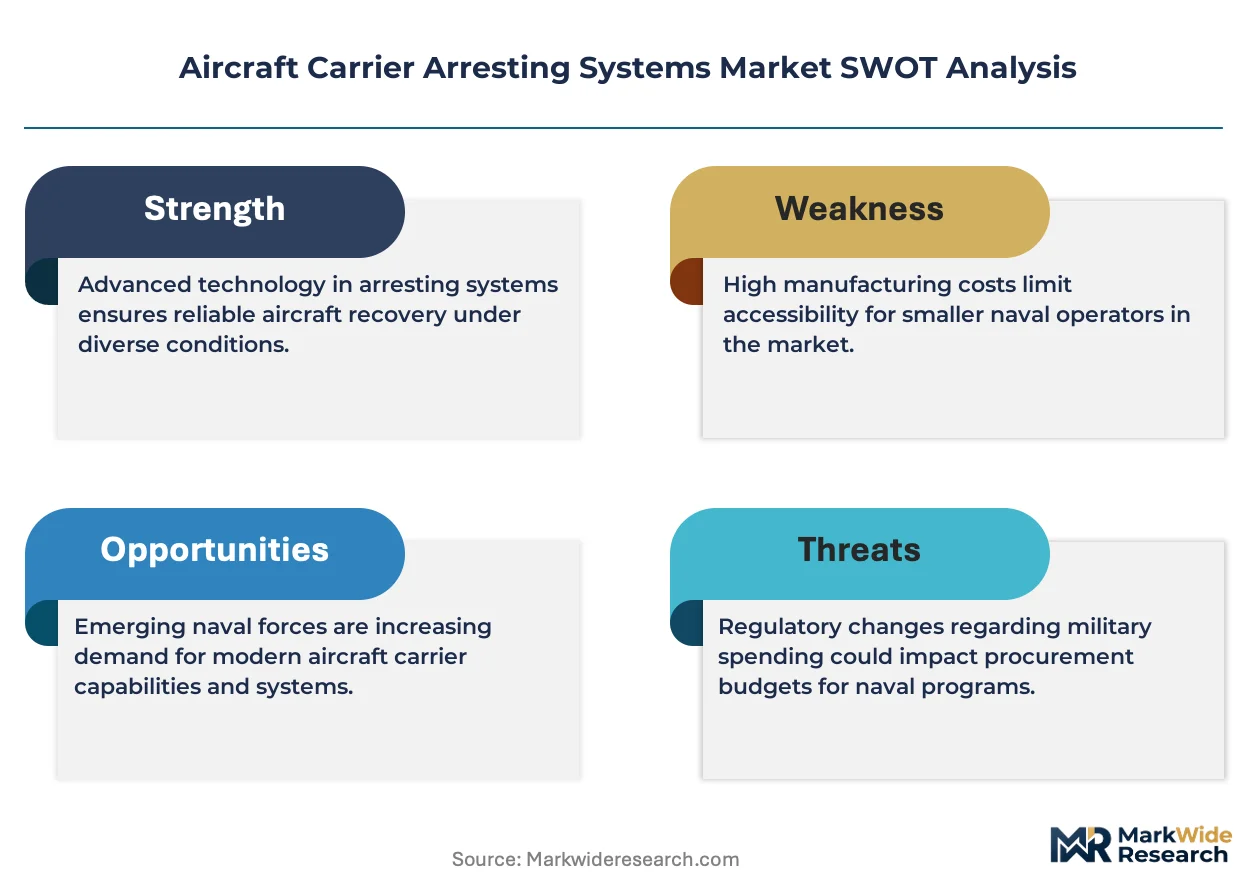
Electromagnetic aircraft recovery systems are bifurcating carrier fleets between new construction programs adopting advanced arresting gear and legacy hydraulic systems facing life-extension economics. This technology transition concentrates procurement authority within naval modernization budgets while reshaping supplier qualification requirements across NATO and Pacific theater programs.
Growth Catalysts
- Naval Modernization Budgets:The U.S. Navy's Ford-class carrier program and China's dual carrier fleet expansion are concentrating procurement of advanced recovery systems in Pacific theater construction yards.
- REACH Chemical Compliance:The EU Green Deal's defense industrial emissions framework is accelerating replacement of hydraulic fluids in European carrier upgrade cycles, creating aftermarket demand for electromechanical alternatives.
- UAV Integration Requirements:Unmanned aerial vehicle recovery operations are driving specification updates for arresting systems capable of handling lighter approach weights and variable landing profiles.
Market Restraints
- Specialized Alloy Supply Concentration:High-tensile wire rope production depends on limited domestic superalloy capacity in the United States and Japan, exposing programs to input cost volatility.
- Naval Sea Systems Command Certification:U.S. Navy qualification timelines for arresting gear components create 18-24 month product approval cycles that delay supplier market entry.
- Legacy Hydraulic Retrofit Economics:Nimitz-class life-extension programs face capital allocation trade-offs between full electromagnetic conversion and incremental hydraulic system refurbishment.
Strategic Opportunities
- Indian Indigenous Carrier Programs:INS Vikrant and planned sister ships are creating regional aftermarket growth for integrated landing systems and localized maintenance capabilities.
- GB Standards Localization:China's military equipment quality certification requirements are opening pathways for joint-venture suppliers meeting national defense regulator specifications.
- Sensor-Enabled Predictive Maintenance:Embedded load monitoring and algorithmic wear prediction are converging with flight deck automation to create premium service contract opportunities.
Industry Challenges
- Electromechanical-Hydraulic Integration:Flight deck crews must maintain operational proficiency across mixed system architectures during multi-decade fleet transition periods.
- Specialized Technician Pipeline:Arresting engine overhaul and control system calibration require naval aviation maintenance ratings with limited training capacity across allied fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Carrier Arresting Systems Market |
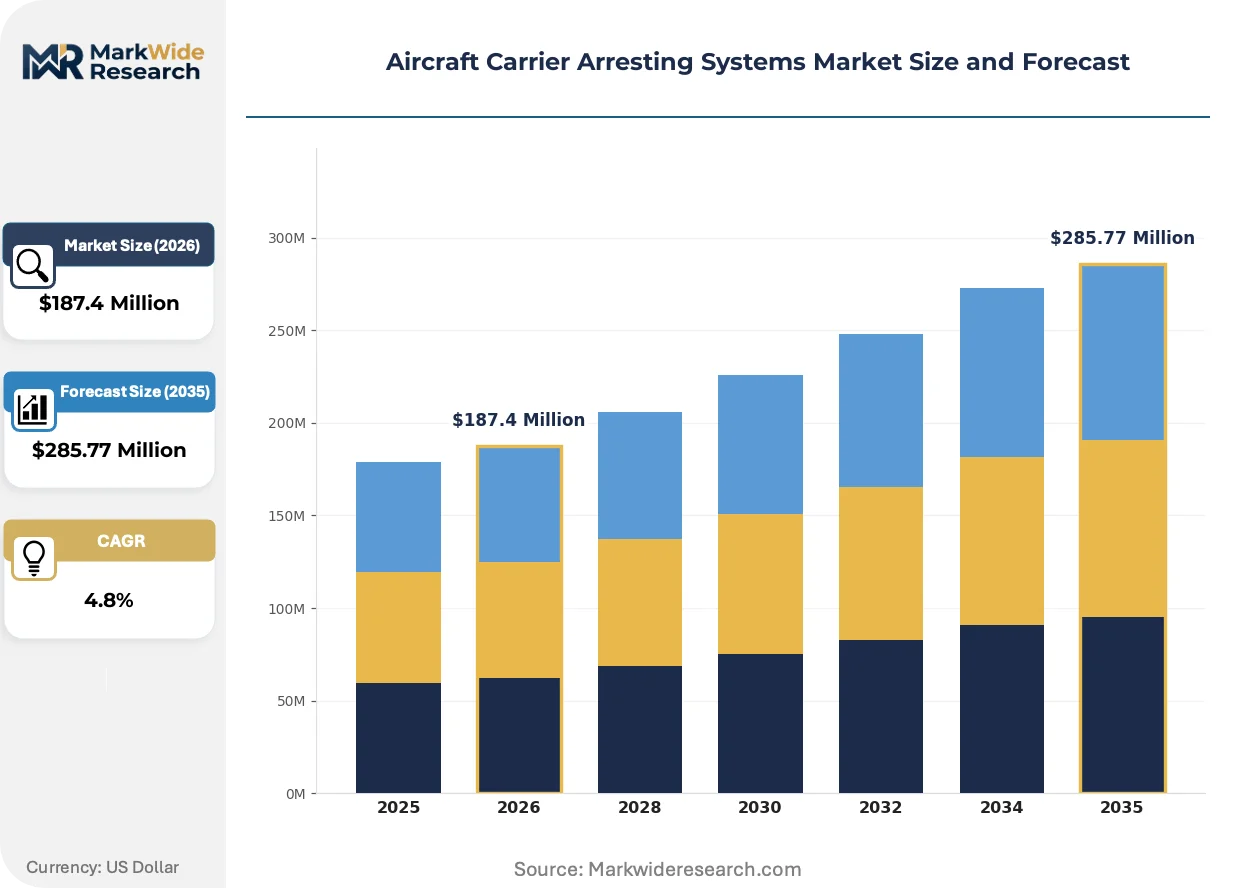
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Wire Rope, Hydraulic, Magnetic, Pneumatic Application: Naval Operations, Aircraft Recovery, Testing Facilities, Simulation Operations End User: Military, Defense Contractors, Research Institutions, Government Agencies Technology: Electromechanical, Smart Systems, Integrated Solutions, Legacy Systems |
| Companies Covered | General Atomics, Curtiss-Wright Corporation, SCAMA AB, Safran, MacTaggart Scott, QinetiQ, A-Laskuvarjo, WireCo WorldGroup, Atech Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Carrier Arresting Systems Market Emerging Trajectories
Arresting system architecture is transitioning from passive mechanical damping to active electromechanical control, embedding intelligence that reshapes both procurement specifications and through-life support economics. This shift redefines supplier value capture toward integrated platform solutions.
Advanced Electromagnetic Aircraft Recovery System (AAG) technology is displacing legacy hydraulic arresting engines in new carrier construction. The U.S. Navy's Ford-class program and France's future PANG carrier are specifying electromagnetic solutions for improved energy modulation and reduced manning requirements. This displacement is compressing the addressable market for traditional hydraulic component suppliers while elevating system integrators with full-deck modernization capabilities.
REACH chemical compliance and the EU Green Deal's defense industrial emissions framework are restricting hydraulic fluid formulations in European naval programs. France's Charles de Gaulle mid-life refit and UK Queen Elizabeth-class sustainment are selecting synthetic alternatives and electromechanical architectures to meet ECHA substance restrictions. Mediterranean and Atlantic-based carrier operations are accelerating material substitution timelines ahead of regulatory deadlines.
Buyer consolidation around full-deck modernization contracts is unbundling legacy component supply arrangements. Naval Sea Systems Command and equivalent European procurement authorities are awarding integrated launch-and-recovery system packages rather than discrete arresting gear procurements. This pattern is most visible in U.S. and French programs, where single-source accountability for electromagnetic catapults and arresting systems is becoming standard contracting practice.
Aircraft Carrier Arresting Systems Market Segmentation
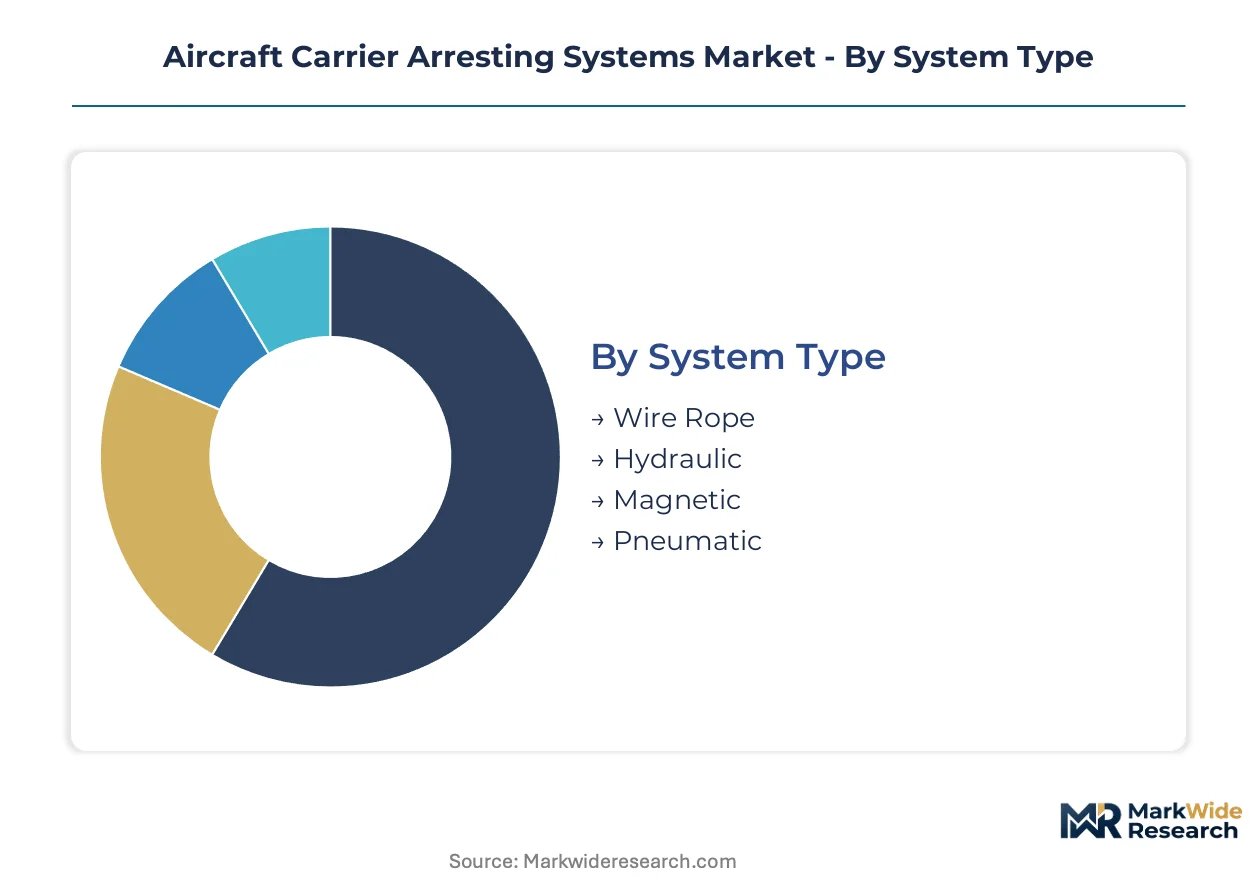
Arresting system procurement patterns diverge sharply between new carrier construction and legacy fleet sustainment, with each segment demanding distinct engineering specifications and certification pathways. Suppliers must align product portfolios across these fault lines to capture both electromagnetic modernization contracts and hydraulic aftermarket service revenue.
System Type:
Wire rope and hydraulic systems anchor domestic procurement in established carrier fleets across the United States, France, and the United Kingdom, while magnetic architectures concentrate in export-led new construction programs.
- Wire Rope:High-tensile alloy cables engineered to absorb kinetic energy from landing aircraft through friction braking mechanisms. Demand concentrates in Nimitz-class and Queen Elizabeth-class life-extension programs, constrained by superalloy supply bottlenecks in U.S. and Japanese foundries.
- Hydraulic:Fluid-based damping systems utilizing pressurized accumulators to control aircraft deceleration rates. Procurement runs through Charles de Gaulle mid-life refit and allied legacy carrier sustainment, pressured by REACH chemical compliance deadlines for hydraulic fluid formulations.
- Magnetic:Electromagnetic eddy-current braking without mechanical friction surfaces. Emerging specification for China's dual carrier fleet expansion and France's PANG program.
- Pneumatic:Compressed-air actuated arresting engines for expeditionary and training applications. Limited procurement through U.S. Navy shore-based testing facilities.
Wire rope commands the established base. The steepest expansion runs through magnetic systems.
Application:
Cost tier differentiation separates mission-critical naval operations from lower-specification training and simulation environments, with pricing stratifying across performance certification levels.
- Naval Operations:Fleet deployment configurations meeting full-spectrum combat recovery requirements under adverse sea states. Procurement authority concentrates in U.S. Naval Sea Systems Command and China's national defense regulator certification pathways.
- Aircraft Recovery:Dedicated carrier-based landing systems integrating with flight deck automation. Specifications tightening for unmanned aerial vehicle compatibility across U.S. Next Generation Air Dominance requirements.
- Testing Facilities:Shore-based validation systems for arresting gear qualification. Demand from U.S. Navy Lakehurst and equivalent European test centers.
- Simulation Operations:Training replicas without full-load certification requirements. Lower-margin procurement through allied naval aviation schools.
Naval operations capture the premium tier. Aircraft recovery is gaining share fastest through UAV integration mandates.
End User:
Volume concentration sits with military service branches, while defense contractors and research institutions fragment across specialized development programs and aftermarket niches.
- Military:Uniformed naval aviation services operating fleet carriers and amphibious assault ships. Procurement scale dominates in U.S. Navy Ford-class and China's dual carrier construction.
- Defense Contractors:Prime integrators holding full-deck modernization contracts. General Atomics and Safran anchor electromagnetic system integration for U.S. and French programs.
- Research Institutions:Academic and government laboratories advancing arresting gear materials science. Limited procurement through Office of Naval Research and European defense research frameworks.
- Government Agencies:Coast guard and maritime security services with reduced specification requirements. Peripheral demand in training and border security applications.
Military end users command the volume base. Defense contractors are expanding most quickly through integrated launch-and-recovery packaging.
Technology:
Maturity curves separate legacy hydraulic architectures from emerging electromechanical and smart system specifications, with margin pools concentrating in predictive maintenance and integrated solution bundles.
- Electromechanical:Motor-driven energy absorption replacing hydraulic damping. Specifications from Ford-class and PANG programs displace legacy architectures.
- Smart Systems:Sensor-embedded arresting gear with algorithmic wear prediction and automated deck control. Premium positioning through U.S. Navy predictive maintenance contracts.
- Integrated Solutions:Combined electromagnetic launch and recovery system packages. Single-source accountability becoming standard in Naval Sea Systems Command procurement.
- Legacy Systems:Conventional hydraulic and mechanical architectures requiring sustainment. Aftermarket service revenue from Nimitz-class and allied legacy fleets.
Legacy systems command the installed base. Smart systems are climbing the fastest through sensor-enabled service contract expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Navy's Ford-class carrier program at Newport News Shipbuilding underwrites American naval aviation infrastructure investment. China's dual carrier fleet expansion at Dalian and Shanghai yards concentrates Pacific theater procurement. India's indigenous carrier construction at Cochin Shipyard drives regional aftermarket formation.
United States
Naval Sea Systems Command certification requirements govern arresting gear procurement for Ford-class and Nimitz-class programs. The U.S. Navy's Next Generation Air Dominance requirements are tightening electromagnetic recovery specifications at Lakehurst test facilities. Huntington Ingalls Industries' Newport News yard anchors Atlantic carrier construction while General Atomics integrates electromagnetic systems for Pacific fleet modernization.
China
Dual carrier construction at Dalian Shipyard and Jiangnan Changxingdao Yard is scaling electromagnetic arresting system procurement. GB standards and military equipment quality certification from the national defense regulator impose localization mandates on foreign component suppliers. Shanghai's naval aviation industrial cluster is consolidating electromechanical manufacturing capacity for indigenous carrier programs.
France
The Charles de Gaulle mid-life refit and future PANG carrier program are specifying electromagnetic recovery architectures. REACH chemical compliance and the EU Green Deal's defense industrial emissions framework are accelerating hydraulic fluid substitution in Atlantic-based operations. DCNS facilities at Toulon anchor Mediterranean carrier sustainment and technology transfer for integrated landing systems.
India
INS Vikrant commissioning and planned indigenous carrier follow-ons are creating aftermarket demand for arresting gear maintenance. The Ministry of Defence's indigenization mandates under the Defence Acquisition Procedure favor localized component sourcing. Cochin Shipyard Limited is building regional maintenance capabilities for wire rope and hydraulic system overhaul.
United Kingdom
Queen Elizabeth-class sustainment contracts are selecting electromechanical alternatives to meet ECHA substance restrictions on hydraulic fluids. The UK Ministry of Defence's carrier strike group deployment requirements are tightening arresting system reliability specifications for North Atlantic operations. Babcock facilities at Rosyth anchor Firth of Forth naval engineering capacity for integrated deck system modernization.
Aircraft Carrier Arresting Systems Market Vendor Landscape
Concentration sits with system integrators holding electromagnetic launch-and-recovery contracts across NATO and Pacific theater programs. Tiered supplier relationships separate prime integrators from specialized component manufacturers in wire rope and hydraulic damping technologies. Two strategic archetypes dominate: full-deck modernization specialists bundling catapult and arresting functions, and legacy sustainment providers capturing hydraulic aftermarket revenue. Competitive positioning crystallizes around Naval Sea Systems Command qualification timelines and EU Green Deal compliance capabilities.
Among defense-electronics conglomerates, General Atomics and Curtiss-Wright Corporation exemplify the integrated-systems archetype, while Safran occupies a position within European carrier upgrade cycles. General Atomics represents the electromagnetic technology vector through its Ford-class program relationships. Curtiss-Wright Corporation anchors legacy hydraulic and emerging electromechanical supply chains for allied fleet sustainment. Safran exemplifies transatlantic positioning across French naval programs and export opportunities.
| Leading Market Players |
|---|
| General Atomics |
| Curtiss-Wright Corporation |
| SCAMA AB |
| Safran |
| MacTaggart Scott |
| QinetiQ |
| A-Laskuvarjo |
| WireCo WorldGroup |
| Atech Inc. |
| Others |
Supply Flow & Price Mechanics
Naval Sea Systems Command certification requirements gate both supplier qualification and price differentiation simultaneously, compressing procurement timelines while elevating certified system integrators above commodity component vendors. This regulatory threshold concentrates pricing power with electromagnetic technology holders and fragments aftermarket service economics across legacy hydraulic sustainment providers.
Pricing Analysis
Volume-discount tiering structures dominate procurement, with three-tier pricing separating electromagnetic system packages from hydraulic refurbishment bundles and discrete wire rope component sales. Price differentiation hinges on certification grade under Naval Sea Systems Command pathways and after-sales service bundling spanning predictive maintenance contracts. Pricing pressure stems from REACH chemical compliance deadlines accelerating hydraulic fluid substitution in European programs. Defense contractors exhibit lowest price sensitivity given single-source accountability requirements, while research institutions and training facilities face tightened capital allocation scrutiny.
Supply Chain Analysis
Strait of Malacca transit routes underpin superalloy shipment security for high-tensile wire rope production, exposing programs to geopolitical friction. Supply concentrates in United States, Japan, and Chinese foundries for nickel-based alloys, with hydraulic damping components drawing from German and Italian precision manufacturing clusters. Single-source vulnerability sits with domestic superalloy capacity constraints in allied nations. Distribution runs through prime integrators holding full-deck modernization contracts rather than discrete component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electromagnetic aircraft recovery systems are disrupting carrier fleet economics, with Naval Sea Systems Command certification timelines compressing supplier windows and REACH compliance forcing material substitution across Atlantic theater programs.
For Market Incumbents: Fortify electromagnetic system integration capabilities through backward control over superalloy supply chains and accelerated Naval Sea Systems Command qualification investment. Electromechanical-hydraulic integration complexity threatens operational proficiency maintenance across mixed fleet architectures. Capacity addition in Indian industrial corridors anchors regional aftermarket capture against indigenous carrier program expansion. For New Entrants and Emerging Players: Differentiate on sensor-enabled predictive maintenance algorithms bundled with localized service contracts. White-space concentration sits with Indian indigenous carrier programs and Chinese joint-venture pathways meeting GB standards localization mandates. Shore-based testing facility procurement offers lowest certification barrier entry. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electromagnetic system manufacturing as Ford-class and PANG program scale demands fixed-asset deployment. Long-term viability favors system integrators with dual launch-and-recovery capabilities over discrete component suppliers. Acquisition target archetype: mid-tier electromechanical specialists with Naval Sea Systems Command qualification progress. The signal to watch is electromagnetic recovery technology maturation against legacy hydraulic retrofit economics in Nimitz-class life-extension decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Electromagnetic System Integration | Single-source accountability for Ford-class and PANG programs consolidates procurement authority with certified integrators. |
| Superalloy Supply Securement | Backward integration into nickel-based alloy production mitigates Japanese and U.S. foundry capacity constraints. |
| Predictive Maintenance Platform Launch | Sensor-embedded arresting gear with algorithmic wear prediction commands premium service contract positioning. |
| Indian Joint Venture Formation | Localized maintenance capabilities at Cochin Shipyard align with Defence Acquisition Procedure indigenization mandates. |
| REACH Compliance Transition | Synthetic hydraulic fluid alternatives and electromechanical architectures meet ECHA substance restrictions ahead of deadlines. |
Methodological Framework
Initial hypotheses were tested against primary input from naval aviation maintenance ratings, carrier program procurement officers, arresting gear system engineers, and electromagnetic technology specialists and refined through secondary validation. Primary fieldwork drew from U.S. Naval Sea Systems Command documentation, French Direction Générale de l'Armement procurement records, and Indian Ministry of Defence acquisition circulars. Secondary sources encompassed customs trade data for superalloy shipments, SEC 10-K filings from listed defense-electronics conglomerates, and carrier construction yard capacity disclosures. Bottom-up segment sizing triangulated against top-down naval modernization budget allocation analysis.
Variance-decomposition framing isolated technology transition effects from fleet sustainment economics across the projection horizon. Segmentation dimensions modeled encompass system type, application tier, end-user category, and technology maturity curve. CAGRs were derived from expenditure phasing aligned to carrier construction and refit schedules. Industry-specific forecast inputs included electromagnetic recovery technology qualification timelines and REACH chemical compliance substitution rates.
The analysis sits within stated boundaries; outcomes outside sustained Pacific theater carrier construction activity or accelerated EU Green Deal enforcement would require recalibration. Forecasts reflect assumptions regarding Naval Sea Systems Command certification pathway stability and superalloy supply chain continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Rubber Tracks for Defense and Security Market
Military Equipment and Infrastructure
NATO Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Global Mine Countermeasures Market
Military Equipment and Infrastructure
Land Digital Battlefield Market
Military Equipment and Infrastructure
Global Remote Weapon Station Market
Military Equipment and Infrastructure
Next Generation Military Power Supply Market
Military Equipment and Infrastructure
Deployable Military Shelter Systems Market
Military Equipment and Infrastructure
CBRNE Defense Market
Military Equipment and Infrastructure
Global Stealth Warfare Market
Military Equipment and Infrastructure
Global Armor Materials Market
Military Equipment and Infrastructure
Air Independent Propulsion Systems for Submarine Market
Military Equipment and Infrastructure
Man Portable Military Electronics Market
Military Equipment and Infrastructure
Asia-Pacific Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Global Landing String Equipment Market
Military Equipment and Infrastructure
Soft Wall Military Shelter Market
Military Equipment and Infrastructure
Global Soldier Modernization Market