
 Global Mine Countermeasures Market | 2026-2036
Global Mine Countermeasures Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mine Countermeasures Market Foresight
UK shipyard investment in Portsmouth and Glasgow is tilting Atlantic-facing capacity toward next-generation mine countermeasures. BAE Systems plc leverages its Type 26 frigate integration expertise to sustain long-term naval platform contracts across Commonwealth fleets. Thales S.A. anchors European sonar development through its underwater systems division in France, while Naval Group S.A. competes for littoral vessel programs with steel-hulled mine warfare designs optimized for shallow-water acoustics.
Mine countermeasures encompass the detection, classification, and neutralization of sea mines through platforms operating at depths from 10 to 200 meters, employing variable-frequency sonar arrays, magnetic influence sweeps, and remotely deployed explosive charges to secure shipping lanes and naval operating areas. Unmanned underwater vehicles are displacing crewed vessels in the most hazardous clearance phases, concentrating R&D investment in autonomous navigation and tetherless communication architectures. Detection sonar systems retain the deepest margin pools due to dual-use port security applications, while neutralization equipment faces slower replacement cycles tied to munitions stockpile treaties.
The US Navy's Naval Sea Systems Command sets procurement specifications that cascade into NATO STANAG requirements, forcing non-US suppliers to certify magnetic and acoustic signatures against American test ranges. EMA and national maritime safety regulators in France, Germany, and Italy enforce diver-protection protocols that constrain neutralization timelines and elevate robotic system reliability standards. Stakeholders must weigh the capital intensity of autonomous platform development against the operational risk of crewed vessel attrition in contested chokepoints.
Market Dynamics
Unmanned underwater vehicles are compressing operational risk tolerance among NATO naval commands, forcing procurement officers to rebalance crewed vessel replacement cycles against autonomous platform reliability thresholds.
Growth Catalysts
- NATO STANAG interoperability mandates:The US Naval Sea Systems Command sets acoustic and magnetic signature standards that cascade into procurement specifications for Estonian, Latvian, and Finnish maritime authorities.
- Legacy seabed contamination:Elevated ordnance density in Baltic Sea littoral zones drives sustained demand for shallow-water clearance platforms operating at 10-200 meter depths.
- Variable-frequency sonar arrays:Dual-use port security applications in commercial maritime infrastructure extend addressable demand beyond military end-users.
Market Restraints
- Tetherless communication architectures:Underwater acoustic bandwidth constraints limit real-time command-and-control reliability for autonomous neutralization missions.
- Munitions stockpile treaties:Replacement cycles for explosive neutralization charges face multilateral arms control verification timelines that compress inventory turnover.
- Magnetic influence sweep certification:US Navy test range access concentrates validation capacity in North American facilities, elongating European supplier qualification periods.
Strategic Opportunities
- Commonwealth fleet integration:UK Type 26 frigate programs create captive demand for modular mine countermeasures payloads across Australian and Canadian naval modernization schedules.
- EMA diver-protection protocols:Regulatory constraints on human intervention in neutralization phases accelerate robotic system reliability investment thresholds.
- AI-enabled autonomous navigation:Convergence of machine-learning obstacle recognition with inertial positioning systems enables single-platform classification-to-neutralization workflows.
Industry Challenges
- Acoustic signature engineering talent:Shallow-water sonar optimization requires specialized hydroacoustic expertise concentrated in French and British defense research establishments.
- ISO 9001 maritime equipment certification:Quality management system audits for autonomous underwater vehicle production impose 18-24 month pre-qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mine Countermeasures Market |
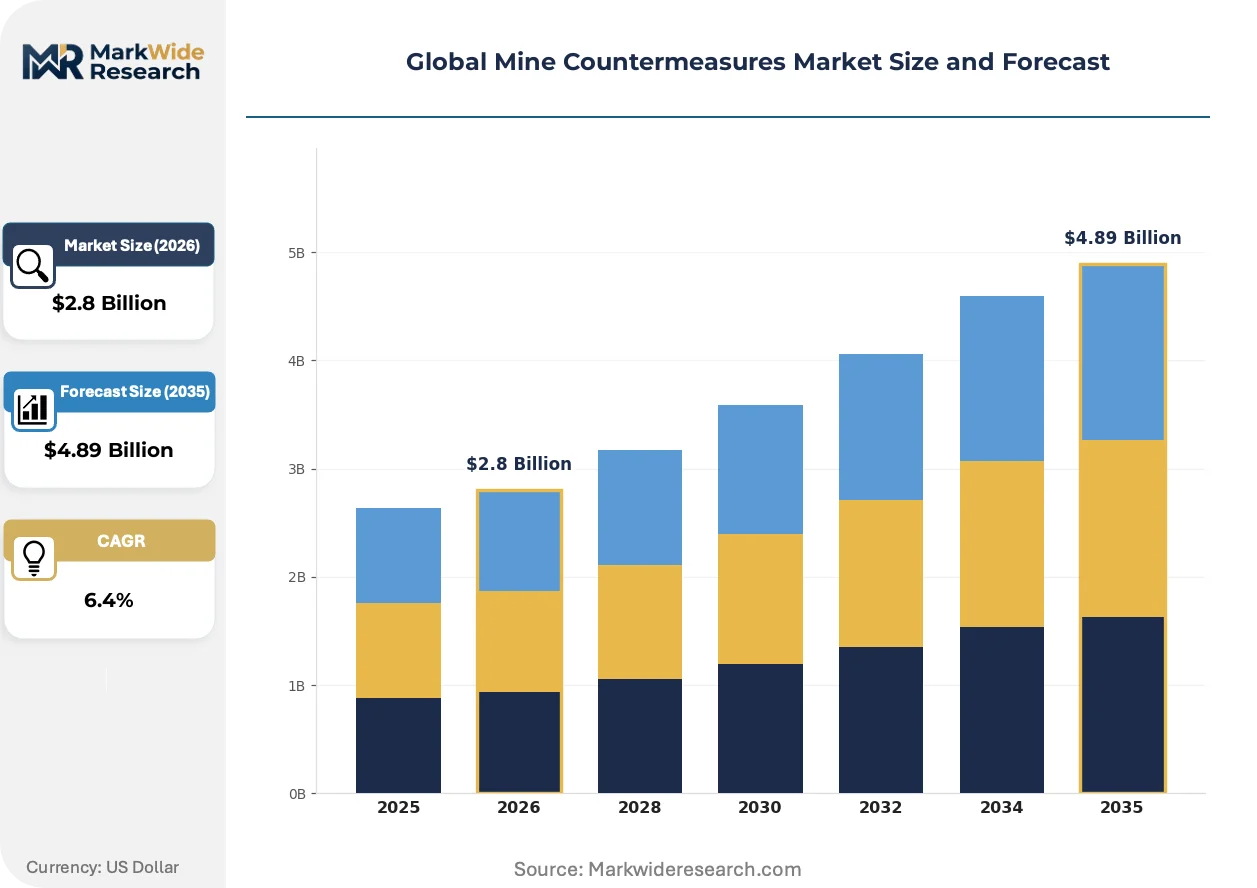
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mine Hunting Vessels, Mine Sweeping Systems, Unmanned Underwater Vehicles, Detection Sonar Systems, Neutralization Equipment Technology: Acoustic, Magnetic, Mechanical, Magnetic-Acoustic, Electro-Optical Application: Naval Defense, Port Security, Coastal Surveillance, Maritime Escort, Explosive Ordnance Disposal End User: Naval Forces, Defense Contractors, Security Agencies, Maritime Authorities |
| Companies Covered | Northrop Grumman Corporation, BAE Systems plc, RTX Corporation, Mitsubishi Heavy Industries Ltd., L3Harris Technologies Inc., Lockheed Martin Corporation, Thales S.A., Naval Group S.A., General Dynamics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mine Countermeasures Market Shifts & Advancements
Autonomous platform architectures are fragmenting traditional vessel procurement patterns, compressing the boundary between detection and neutralization phases while elevating software-defined mission reconfiguration.
Synthetic aperture sonar is hybridizing detection and classification functions into continuous seabed mapping workflows. Royal Navy mine countermeasures squadrons are field-testing these systems for Baltic Sea route surveys. The technology is hybridizing operational timelines by collapsing sequential search-classify-neutralize stages into single-pass missions.
EU Green Deal sustainability criteria are penetrating naval vessel procurement specifications, mandating lifecycle carbon accounting for steel-hulled mine warfare designs. French and Italian maritime regulators now require environmental product declarations for newbuild littoral vessels. Shipyards in Scotland and Portsmouth are responding with hybrid-electric propulsion architectures that satisfy both NATO STANAG mobility requirements and CSRD disclosure obligations.
Fleet operators are unbundling platform ownership from mission execution, contracting autonomous system availability through service-level agreements rather than capital acquisition. UK and Australian naval commands are piloting this model for Baltic Sea rotational deployments. The shift is most visible in Commonwealth procurement frameworks where through-life support costs dominate total ownership evaluation.
Global Mine Countermeasures Market Segmentation
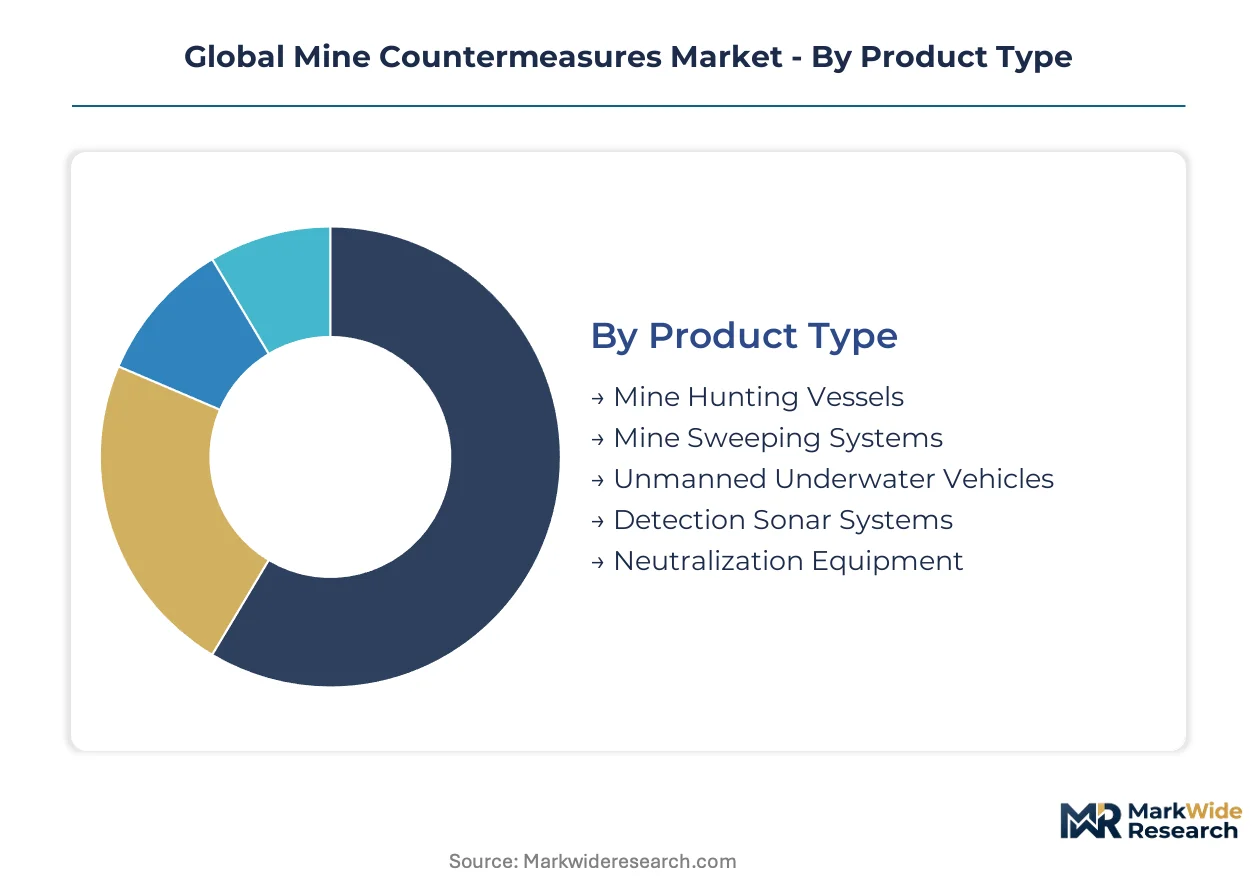
Segmentation in mine countermeasures reflects divergent procurement cycles across platform types, with unmanned systems compressing replacement timelines while hull-based assets extend service lives through modular retrofits. Technology choices cascade through operational specifications, determining which naval forces can field interoperable assets under NATO STANAG frameworks.
Product Type:
Replacement cycles vary dramatically, with unmanned platforms turning over every 5-7 years versus 25-30 year hull lifecycles for crewed vessels.
- Unmanned Underwater Vehicles:Tetherless and tethered autonomous platforms execute detection-to-neutralization workflows without crew exposure. Estonian, Latvian, and Finnish maritime authorities are concentrating procurement here for Baltic Sea littoral clearance where legacy ordnance density is highest.
- Detection Sonar Systems:Variable-frequency and synthetic aperture arrays operating at 10-200 meter depths provide seabed mapping and mine classification. Dual-use port security applications in commercial maritime infrastructure extend demand beyond naval end-users, with harbor authorities in Belgium and the Netherlands deploying shore-based installations.
- Mine Hunting Vessels:Steel and composite-hulled crewed platforms remain the capital backbone for sustained operational presence.
- Mine Sweeping Systems:Magnetic influence and acoustic sweep gear generates artificial signatures to trigger ordnance.
- Neutralization Equipment:Remotely deployed explosive charges and shaped disruptors face inventory constraints from multilateral arms control verification.
Detection Sonar Systems anchors the volume base while Unmanned Underwater Vehicles gains share at the steepest rate.
Technology:
Cost tiers separate legacy mechanical approaches from software-defined multi-sensor fusion architectures commanding premium procurement budgets.
- Acoustic:Active and passive sonar arrays dominate seabed detection, with frequency agility determining performance against buried and proud mines. Royal Navy mine countermeasures squadrons prioritize acoustic signature engineering for Baltic Sea route surveys.
- Magnetic-Acoustic:Combined sensor fusion platforms integrate magnetic anomaly detection with acoustic imaging to reduce false classification rates. US Naval Sea Systems Command procurement specifications favor this approach for contested chokepoint clearance.
- Magnetic:Influence sweeps and magnetometers trigger or detect ferrous ordnance.
- Mechanical:Cable cutters and chain sweeps address contact-fused legacy mines.
- Electro-Optical:Laser line scanning and camera systems support identification in turbid littoral waters.
Acoustic technology captures the largest installed base whereas Magnetic-Acoustic configurations are expanding most quickly through NATO interoperability mandates.
Application:
Customer maturity varies, with naval defense representing established doctrine while explosive ordnance disposal units adopt robotic systems through experimental acquisition pathways.
- Naval Defense:Fleet-level mine countermeasures squadrons execute area clearance for amphibious operations and carrier strike group transits. UK Type 26 frigate integration programs create captive demand for modular payloads across Australian and Canadian modernization schedules.
- Port Security:Harbor authorities and commercial terminal operators deploy fixed and mobile detection assets for chokepoint protection. EMA diver-protection protocols in France, Germany, and Italy constrain neutralization timelines and elevate robotic reliability standards.
- Coastal Surveillance:Littoral monitoring for seabed contamination extends beyond military operations.
- Maritime Escort:Route survey and clearance for high-value vessel transits.
- Explosive Ordnance Disposal:Specialist units conduct render-safe procedures on recovered or complex ordnance.
Naval Defense maintains the deepest procurement commitments while Port Security is climbing the fastest as commercial infrastructure hardening accelerates.
End User:
Supply concentration favors defense contractors with captive shipyard access, while security agencies fragment demand across bespoke procurement frameworks.
- Naval Forces:National navies and coast guards operate the preponderance of dedicated mine countermeasures platforms. NATO STANAG interoperability mandates cascade from US Naval Sea Systems Command specifications into Estonian, Latvian, and Finnish maritime authority procurement.
- Defense Contractors:Systems integrators and platform OEMs sustain through-life support revenues. BAE Systems plc leverages Type 26 frigate expertise for Commonwealth fleet integration; Thales S.A. anchors European sonar development through its underwater systems division in France.
- Security Agencies:National police and border forces acquire limited portable detection capabilities.
- Maritime Authorities:Civilian port and waterway management bodies operate commercial-grade clearance assets.
Naval Forces anchor the volume base while Defense Contractors gain share at the steepest rate through availability-based service contracting models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across naval procurement frameworks, with NATO interoperability mandates driving standardization in European littoral zones while Indo-Pacific operators prioritize sovereign platform development.
United States
The US Navy's Naval Sea Systems Command dominates specification-setting for autonomous mine-hunting platforms, cascading acoustic signature standards into allied procurement. FCC and FAA regulations intersect with underwater systems through export control classifications on tetherless communication architectures. Virginia-class submarine builders in Connecticut and Virginia anchor defense industrial base concentration for integrated naval electronics.
United Kingdom
Royal Navy mine countermeasures squadrons field-test synthetic aperture sonar for Baltic Sea route surveys, compressing search-classify-neutralize timelines. UK shipyard investment in Portsmouth and Glasgow channels Atlantic-facing capacity toward next-generation clearance platforms. BAE Systems plc leverages Type 26 frigate integration expertise to sustain Commonwealth fleet contracts.
France
Thales S.A. anchors European sonar development through its underwater systems division, supplying variable-frequency arrays for littoral zone operations. EMA diver-protection protocols constrain neutralization timelines and elevate robotic reliability standards. Naval Group S.A. competes for steel-hulled mine warfare designs optimized for shallow-water acoustics from its Paris-headquartered operations.
Germany
KBA and national maritime safety regulators enforce certification timelines for magnetic influence sweep equipment, elongating European supplier qualification periods. German naval modernization prioritizes Baltic Sea seabed clearance where legacy ordnance density remains elevated. Shipyards in Kiel and Hamburg concentrate steel-hulled vessel construction for NATO STANAG interoperability.
Australia
Commonwealth fleet integration programs create captive demand for modular mine countermeasures payloads synchronized with UK Type 26 frigate schedules. TGA and Defence export controls govern autonomous underwater vehicle procurement for Indo-Pacific rotational deployments. Perth and Adelaide defense clusters concentrate through-life support capabilities for availability-based service contracting.
Global Mine Countermeasures Market Competitive Landscape
Capability concentration sits with specialized sonar engineering houses; scale advantage sits with diversified defense conglomerates. The vendor base stratifies across three tiers: platform integrators with captive shipyard access, sensor specialists with hydroacoustic intellectual property, and autonomy software vendors with navigation algorithm portfolios. Dominant competitive moves include strategic partnerships for NATO STANAG certification and geographic expansion into Baltic Sea littoral markets.
Among diversified defense conglomerates, Northrop Grumman Corporation, BAE Systems plc, and Thales S.A. exemplify contrasting strategic positions. Northrop Grumman Corporation represents the US-centric platform integration archetype with Naval Sea Systems Command specification alignment. BAE Systems plc occupies a position bridging UK sovereign capability with Commonwealth export frameworks. Thales S.A. anchors European sensor development through specialized underwater systems expertise concentrated in French defense research establishments.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| BAE Systems plc |
| RTX Corporation |
| Mitsubishi Heavy Industries Ltd. |
| L3Harris Technologies Inc. |
| Lockheed Martin Corporation |
| Thales S.A. |
| Naval Group S.A. |
| General Dynamics Corporation |
| Others |
Supply & Pricing Matrix
Baltic Sea container routes from Kiel to Tallinn concentrate logistics costs for European sonar component suppliers, compressing margins for detection system OEMs while amplifying price differentiation between NATO-certified and commercial-grade equipment tiers.
Pricing Analysis
Transatlantic price spreads exceed 35% between US Navy-certified magnetic sweep systems and equivalent European commercial variants, reflecting divergent certification costs and test range access fees. Three-tier pricing structure across NATO STANAG-compliant, national-military-grade, and commercial-harbor tiers anchors the market, with ISO 9001 maritime equipment certification and US Naval Sea Systems Command validation as the primary differentiation levers. Pricing pressure stems from Estonian and Latvian procurement officers consolidating orders under framework agreements that squeeze unit margins. Port security authorities in Belgium and the Netherlands exhibit highest price sensitivity due to municipal budget constraints, while Commonwealth naval commands show lowest sensitivity given through-life support bundling.
Supply Chain Analysis
Tariff exposure between US and EU defense electronics suppliers dominates supply chain risk planning for autonomous underwater vehicle manufacturers. Component concentration rests on France for hydroacoustic transducer arrays, the United Kingdom for synthetic aperture sonar processing units, and the United States for tetherless communication chipsets. Rare earth magnet dependencies for magnetic influence sweeps and lithium-ion cell supplies for AUV power systems create dual raw material vulnerabilities. Single-source vulnerability persists at the precision machining tier for titanium pressure hull components. Distribution runs through national defense procurement agencies with NATO STANAG interoperability gates, supplemented by direct commercial harbor authority contracting for port security applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autonomous platform adoption in Baltic Sea littoral zones signals early-cycle expansion, with unmanned underwater vehicle procurement displacing crewed vessel replacement schedules faster than projected.
For Market Incumbents: Pre-empt modular payload standardization by embedding software-defined mission reconfiguration into next-generation detection sonar architectures before Australian and Canadian Type 26 integration programs lock in specifications. Threats from Chinese UUV manufacturers with cost-advantaged magnetic-acoustic fusion systems require accelerated NATO STANAG certification timelines as defensive leverage. Vertical integration into in-house titanium pressure hull production secures supply continuity against machining capacity bottlenecks. For New Entrants and Emerging Players: Establish a beachhead in commercial port security detection systems, where EMA diver-protection protocols in France, Germany, and Italy are forcing harbor authorities toward robotic reliability standards without incumbent lock-in. The Belgian and Dutch municipal harbor markets offer lowest penetration resistance due to fragmented procurement and absence of long-term service agreements. Go-to-market through EPC contractors specializing in maritime infrastructure hardening bypasses direct defense procurement complexity. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified defense conglomerates seeking to divest non-core underwater systems divisions amid portfolio rebalancing toward space and cyber. Long-term viability hinges on software-defined autonomy stacks rather than hardware platforms, favoring acquisition of navigation algorithm specialists over vessel integrators. Signal to watch: UK-Australia reciprocal defense procurement treaty expansions into mine countermeasures payloads.| Strategic Initiative | Industry Significance |
|---|---|
| NATO STANAG Certification Investment | US Naval Sea Systems Command test range access unlocks Estonian, Latvian, and Finnish procurement eligibility. |
| Backward Integration into Titanium Machining | In-house pressure hull production mitigates single-source vulnerability at German and French specialist suppliers. |
| Availability-Based Service Contracting | UK and Australian naval pilot programs shift revenue from capital sale to through-life platform management. |
| Synthetic Aperture Sonar Platform Integration | Royal Navy Baltic Sea field-testing validates single-pass search-classify-neutralize workflows for Commonwealth export. |
| Hybrid-Electric Propulsion Development | Scottish and Portsmouth shipyards satisfy EU Green Deal lifecycle carbon accounting for French and Italian naval tenders. |
Research Methodology
Desk research of NATO STANAG documentation, national defense procurement registers, and EMA maritime safety protocols preceded structured interviews with naval program managers, autonomous systems engineers, shipyard procurement directors, and port authority operations chiefs. Primary fieldwork across UK, French, and German defense research establishments was cross-validated against secondary sources including customs trade data for UUV component flows, SEC 10-K filings of listed defense conglomerates, and IHS Markit naval vessel construction databases. Bottom-up platform deployment forecasts were triangulated with top-down defense budget allocation analysis.
Assumptions held fixed across the modeling period include NATO membership continuity for Baltic Sea states, existing multilateral arms control treaty frameworks governing explosive neutralization charges, and current FCC export control classifications on tetherless underwater communications. Variables permitted to fluctuate encompass EU Green Deal procurement penetration rates, Australian-UK defense industrial integration depth, and commercial harbor security automation adoption curves. CAGRs were derived from weighted scenario analysis across platform replacement timelines, with unmanned system turnover rates and crewed vessel service life extensions as primary segmentation inputs.
Stress conditions across rare earth magnet supply disruption, Baltic Sea seabed clearance urgency escalation, and diver-protection protocol regulatory tightening were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding NATO interoperability mandate enforcement and Commonwealth fleet synchronization schedules. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Next Generation Military Power Supply Market
Military Equipment and Infrastructure
Global Armor Materials Market
Military Equipment and Infrastructure
Global Soldier Modernization Market
Military Equipment and Infrastructure
CBRN Protection Equipment Market
Military Equipment and Infrastructure
Latin America Defense Market
Military Equipment and Infrastructure
NATO Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Naval Vessel Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
Military Wearable Computers Market
Military Equipment and Infrastructure
Military Tent and Shelter Market
Military Equipment and Infrastructure
Rocket Solid Propulsion Market
Military Equipment and Infrastructure
Military Optoelectronic System Market
Military Equipment and Infrastructure
Military Displays Market
Military Equipment and Infrastructure
Asia-Pacific Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Land Digital Battlefield Market
Military Equipment and Infrastructure
Air Independent Propulsion Systems for Submarine Market
Military Equipment and Infrastructure
Used Serviceable Material (USM) Market