
 Land Digital Battlefield Market | 2026-2036
Land Digital Battlefield Market Size, Share, and Industry Trends Forecast 2026-2036
Land Digital Battlefield Market Insights
Platform licensing revenue is narrowing relative to integrated system sales as prime contractors bundle hardware with multi-year sustainment contracts. Lockheed Martin leverages its Sikorsky heritage to dominate rotary-wing mission system integration. BAE Systems anchors European land electronics through its Swedish and UK vehicle upgrade programs. Elbit Systems specializes in helmet-mounted situational awareness displays that extend soldier-level digital connectivity.
The land digital battlefield encompasses networked ground combat systems integrating sensors, processors, and effectors through standardized data architectures operating at sub-millisecond latency thresholds, designed to compress the sensor-to-shooter timeline for mechanized and dismounted formations. Command and control systems occupy the largest value pool given their role as the backbone architecture for joint force coordination. Artificial intelligence applications within threat detection represent the fastest-expanding technology segment as armies automate target recognition from electro-optical and signals intelligence feeds.
The US Department of Defense's Joint All-Domain Command and Control framework and NATO's Federated Mission Networking standards shape procurement specifications for cross-national interoperability, while the EU AI Act imposes algorithmic transparency requirements on autonomous targeting aids sold into European defense markets. Stakeholders must monitor how export control revisions under the US International Traffic in Arms Regulations affect software-defined radio and cryptographic module transfers to allied digitization programs.
Market Dynamics
The US Department of Defense's Joint All-Domain Command and Control initiative is compressing procurement timelines as NATO allies harmonize network architectures around Federated Mission Networking standards. This interoperability mandate is forcing prime contractors to restructure software development cycles and open proprietary interfaces.
Growth Catalysts
- JADC2 Framework Mandate:The US DoD's directive requires all ground systems to integrate with joint force networks, creating immediate procurement pull for command and control platforms across brigade formations.
- AI-Enabled Target Recognition:Machine learning algorithms processing electro-optical feeds are automating threat detection workflows, reducing sensor-to-shooter latency for mechanized units below human reaction thresholds.
- Australia Land 400 Program:Canberra's armored vehicle modernization is driving demand for integrated battle management systems that bridge vehicle electronics with dismounted soldier networks.
Market Restraints
- ITAR Compliance Burden:US International Traffic in Arms Regulations create licensing friction for software-defined radio and cryptographic module exports to allied digitization programs, delaying fielding schedules.
- Semiconductor Supply Concentration:Advanced FPGA and secure processor fabrication concentrates in Taiwan and South Korea, exposing prime contractors to single-source vulnerability for mission-critical compute components.
- Legacy Analog Infrastructure:Existing vehicle fleets with MIL-STD-1553 data buses impose retrofit costs that deter rapid platform-wide upgrades, fragmenting network architectures within formations.
Strategic Opportunities
- EU AI Act Algorithmic Transparency:Brussels' mandatory explainability requirements for autonomous targeting aids create first-mover advantage for vendors with interpretable machine learning architectures in European defense markets.
- Helmet-Mounted Display Integration:Convergence of augmented reality optics with tactical radio networks opens soldier-level connectivity upgrades that bypass vehicle-centric procurement cycles.
- Poland's Wolf Armored Vehicle Program:Warsaw's accelerated mechanized modernization offers entry point for battle management system providers outside established US-German supply relationships.
Industry Challenges
- Cross-Domain Security Clearance Bottlenecks:Software engineers with both NATO collateral and national compartmented clearances remain scarce, throttling development velocity for multi-national program teams.
- Multi-Standard Protocol Harmonization:Bridging Link-16, Soldier Radio Waveform, and national proprietary data links requires complex gateway development that extends integration testing timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Land Digital Battlefield Market |
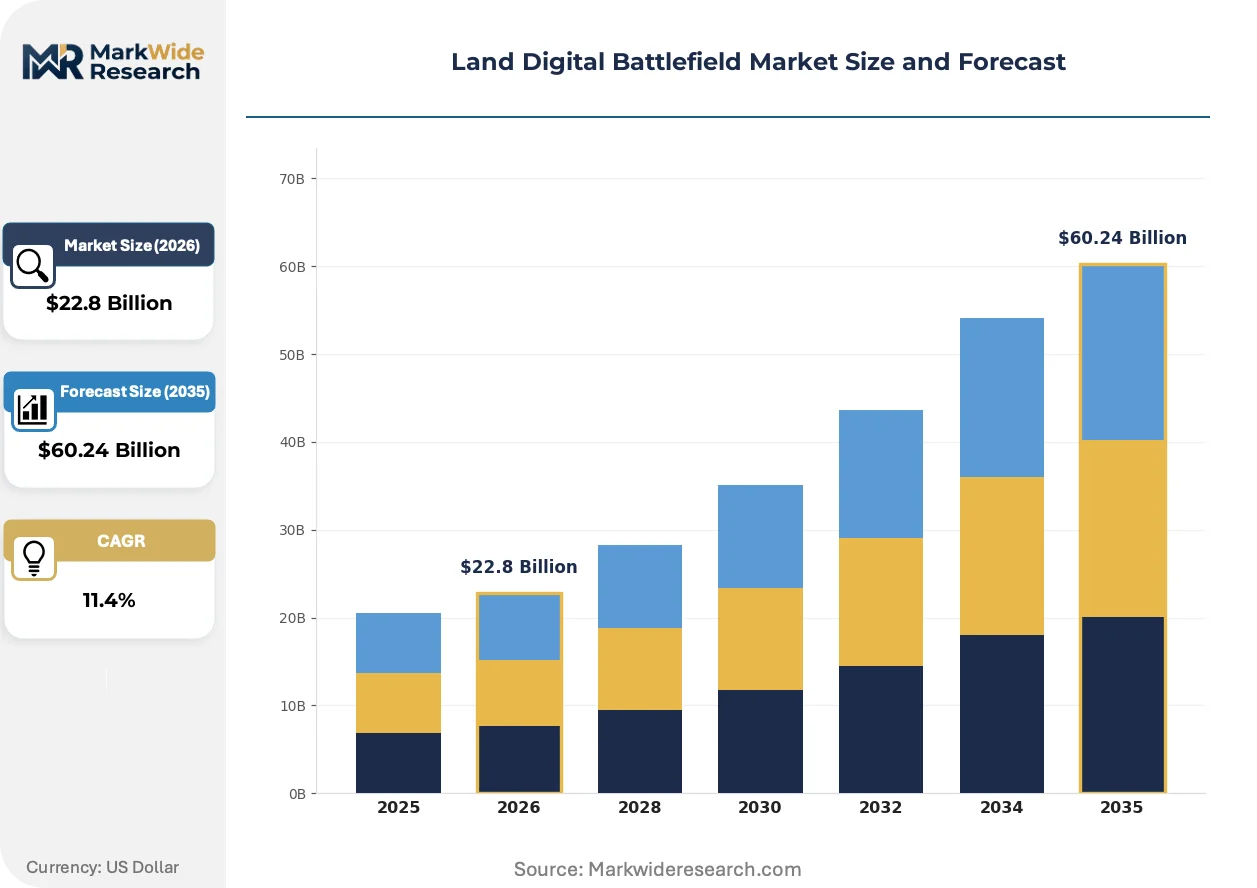
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $60.24 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Command & Control, Reconnaissance, Communication, Surveillance, Electronic Warfare, Cyber Defense Technology: Artificial Intelligence, Internet of Things, Cloud Computing, Big Data Analytics, Edge Computing, Blockchain Application: Force Coordination, Threat Detection, Situational Awareness, Logistics Management, Resource Allocation, Tactical Planning End User: Defense Forces, Special Operations Units, Border Security Agencies, Peacekeeping Organizations, Military Training Centers, Intelligence Services |
| Companies Covered | Lockheed Martin, Northrop Grumman, BAE Systems, General Dynamics, RTX Corporation, Thales Group, Elbit Systems, L3Harris Technologies, Raytheon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Land Digital Battlefield Market Trends and Innovations
Software-defined architectures are displacing hardware-fixed systems across ground combat platforms, enabling capability upgrades through firmware rather than physical retrofit. This shift compresses modernization cycles and alters long-term supplier relationships.
Edge computing nodes embedded in armored vehicles are digitizing sensor fusion workloads that previously required rear-echelon processing. German mechanized brigades are fielding these systems under accelerated procurement authorities. The technology is digitizing command post operations by enabling onboard threat correlation without satellite uplink dependency.
The EU AI Act imposes mandatory algorithmic transparency documentation on autonomous targeting aids sold into European defense markets. Vendors must now submit conformity assessments explaining machine learning decision pathways to national procurement authorities. Infantry fighting vehicle programs in France and Sweden are requiring these certifications as gate criteria for bid evaluation.
Buyers are consolidating sustainment contracts with platform original equipment manufacturers rather than fragmenting support across subsystem vendors. Australia's Land 400 Phase 3 procurement bundles 25-year through-life support with vehicle delivery, locking out third-party maintenance providers. This pattern concentrates recurring revenue with primes who control software update pipelines and cryptographic key management infrastructure.
Land Digital Battlefield Market Segmentation
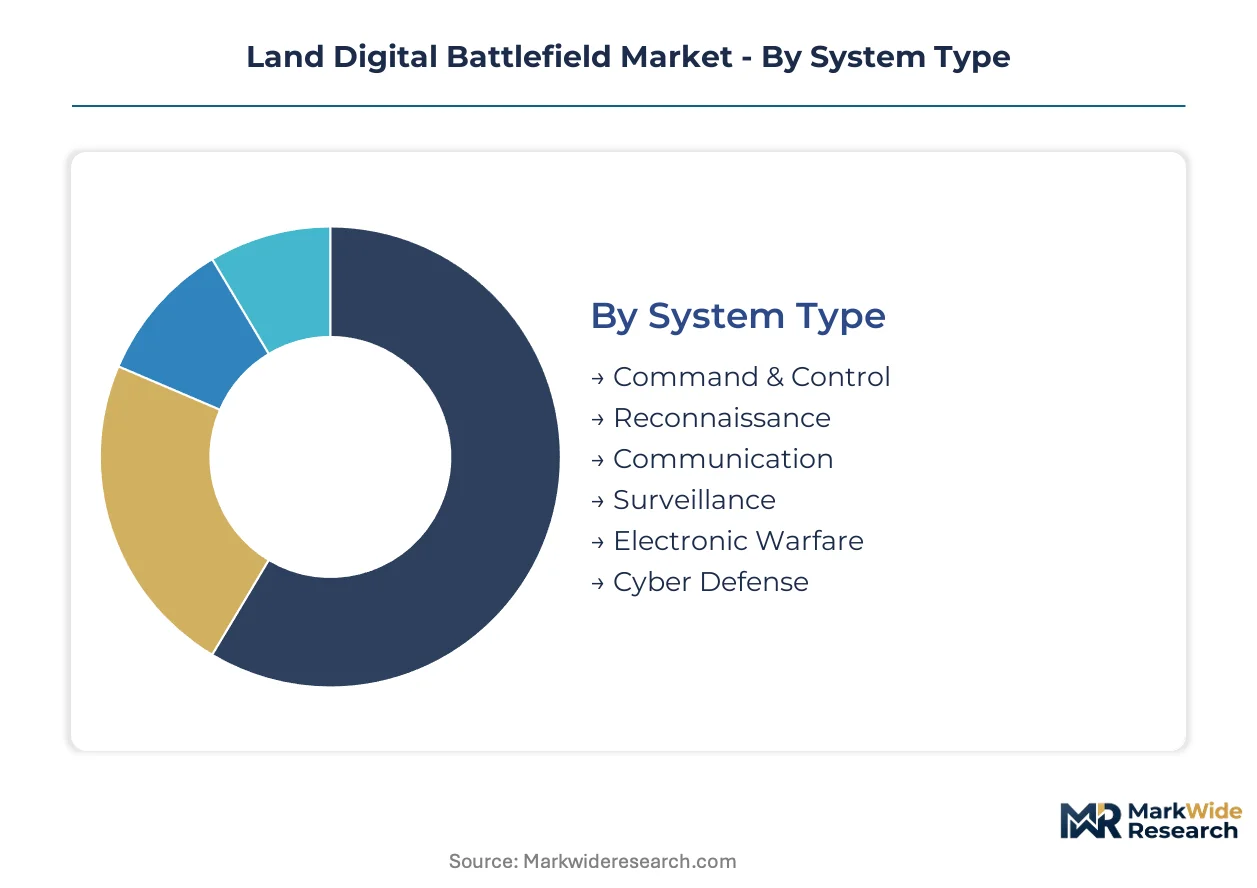
Land digital battlefield procurement diverges sharply across operational echelons and threat environments. System architecture choices determine interoperability with allied networks and compliance with national data sovereignty mandates.
System Type:
Command hierarchies from brigade to platoon level demand layered capabilities spanning kinetic and non-kinetic effects.
- Command & Control:Backbone architectures integrating sensor feeds with fire direction centers through standardized data buses. Brigade-level modernization programs in the United States and Germany concentrate procurement here, driven by JADC2 interoperability mandates and Federated Mission Networking certification requirements.
- Electronic Warfare:Spectrum dominance systems for jamming, direction-finding, and signals intelligence collection. Polish and Baltic state defense ministries prioritize this segment amid heightened electromagnetic contestation near NATO's eastern flank.
- Reconnaissance:Unmanned ground vehicle payloads and standoff sensor suites for target acquisition.
- Communication:Software-defined radios and waveform-agnostic networking equipment.
- Surveillance:Persistent electro-optical and infrared monitoring arrays for area denial operations.
- Cyber Defense:Intrusion detection and network hardening tools for tactical edge systems.
The dominant share belongs to Command & Control, while Electronic Warfare is closing the gap fastest.
Technology:
Processing location and algorithmic autonomy define procurement evaluation criteria across defense ministries.
- Artificial Intelligence:Machine learning pipelines for automated target recognition and predictive maintenance. French and Swedish infantry fighting vehicle programs require EU AI Act conformity assessments, creating compliance barriers for opaque neural architectures.
- Edge Computing:Onboard vehicle processors enabling threat correlation without satellite dependency. German mechanized brigades field these systems under accelerated procurement authorities to reduce command post signature and latency.
- Internet of Things:Sensor mesh networks linking dismounted soldiers with vehicle platforms.
- Cloud Computing:Centralized data lakes for multi-domain operational planning.
- Big Data Analytics:Pattern recognition across historical engagement datasets.
- Blockchain:Distributed ledger applications for supply chain integrity and cryptographic key management.
Artificial Intelligence commands the largest development budgets, though Edge Computing is expanding most quickly as armies harden against contested logistics environments.
Application:
Functional use cases align with operational tempo requirements from high-intensity combat to stabilization missions.
- Situational Awareness:Helmet-mounted displays and augmented reality overlays extending soldier-level digital connectivity. Australia's Land 400 program integrates these with vehicle battle management systems, bridging mounted and dismounted formations.
- Threat Detection:Automated sensor fusion reducing sensor-to-shooter timelines below human reaction thresholds. Mechanized units in NATO's eastern flank prioritize this capability for counter-battery and anti-armor operations.
- Force Coordination:Multi-echelon network synchronization for joint combined arms operations.
- Logistics Management:Predictive supply routing and maintenance scheduling algorithms.
- Resource Allocation:Dynamic ammunition and fuel distribution optimization.
- Tactical Planning:AI-assisted course-of-action development for company commanders.
Situational Awareness retains the widest deployment footprint, while Threat Detection is gaining share fastest as automation priorities intensify.
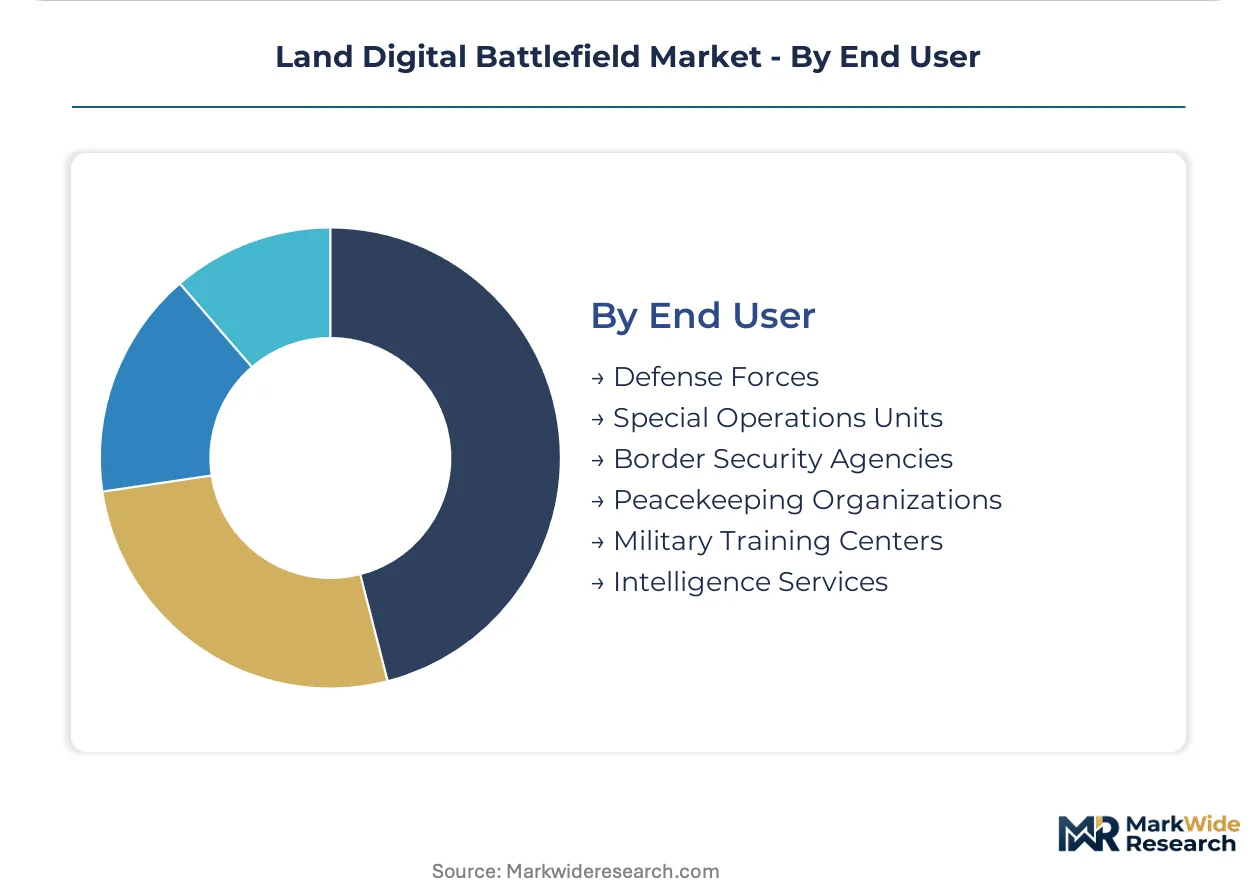
End User:
Institutional buyers vary in procurement authority, security clearance thresholds, and interoperability requirements.
- Defense Forces:Conventional army, marine, and air-ground liaison units with brigade-scale modernization budgets. The United States and Germany anchor volume through multi-year network infrastructure programs.
- Special Operations Units:Small-footprint formations requiring low-probability-of-intercept communications and rapid technology refresh cycles. These units often bypass standard acquisition channels through special access programs.
- Border Security Agencies:Paramilitary organizations with surveillance-heavy mission profiles.
- Peacekeeping Organizations:Multinational forces with strict rules of engagement and information-sharing protocols.
- Military Training Centers:Institutions procuring synthetic training environments and live-virtual-constructive integration.
- Intelligence Services:Technical collection units with specialized cyber and signals requirements.
Defense Forces dominate procurement volumes, while Special Operations Units are expanding fastest through off-cycle acquisition authorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement patterns diverge sharply across NATO allies, with the United States prioritizing joint-force interoperability while European states balance national sovereignty requirements against alliance standardization mandates.
United States
The Pentagon's Joint All-Domain Command and Control initiative drives brigade-level digitization through accelerated procurement authorities. US International Traffic in Arms Regulations impose licensing friction on software-defined radio exports to allied programs. Huntsville's defense corridor hosts prime contractors restructuring development cycles around open architecture mandates.
Germany
Berlin's mechanized brigades field edge-computing nodes under compressed fielding schedules to reduce command post electromagnetic signatures. The EU AI Act's algorithmic transparency requirements shape conformity assessments for autonomous targeting systems. Bavaria's vehicle electronics cluster anchors European land systems integration through accelerated upgrade programs.
Australia
Canberra's Land 400 armored vehicle modernization bundles 25-year sustainment contracts with integrated battle management system procurement. The Australian Signals Directorate mandates cryptographic module certifications for tactical network equipment. Victoria's defense manufacturing precinct concentrates vehicle electronics integration for regional export markets.
Poland
Warsaw's Wolf armored vehicle program offers entry points for battle management providers outside established transatlantic supply relationships. NATO's Federated Mission Networking standards govern cross-border interoperability specifications for eastern flank formations. The country's central European logistics hub attracts subsystem vendors seeking proximity to rapid mechanized modernization timelines.
Sweden
Stockholm's infantry fighting vehicle programs require EU AI Act documentation explaining machine learning decision pathways as mandatory bid criteria. The Swedish Defence Materiel Administration prioritizes helmet-mounted situational awareness displays linking dismounted soldiers with vehicle networks. Linköping's aerospace and defense cluster specializes in sensor fusion architectures for sub-arctic operational environments.
Land Digital Battlefield Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another, producing a bifurcated structure where system integrators control program architectures while component specialists capture niche technology margins. Prime contractors dominate through multi-year sustainment bundling that locks out third-party maintenance providers. Three archetypes define competitive positioning: full-spectrum platform integrators, subsystem technology specialists, and software-defined capability providers. Consolidation pressures intensify as defense ministries consolidate procurement authority with original equipment manufacturers.
Within the full-spectrum integrator tier, Lockheed Martin and BAE Systems occupy positions defined by rotary-wing and vehicle electronics heritage respectively. Elbit Systems exemplifies the specialist archetype through concentrated exposure to soldier-level connectivity systems. These three anchors demonstrate how geographic origin—American, British, and Israeli—correlates with distinct technology focus areas rather than direct segment competition.
| Leading Market Players |
|---|
| Lockheed Martin |
| Northrop Grumman |
| BAE Systems |
| General Dynamics |
| RTX Corporation |
| Thales Group |
| Elbit Systems |
| L3Harris Technologies |
| Raytheon Technologies |
| Others |
Pricing and Supply Chain Analysis
Huntsville's defense corridor concentrates prime contractor engineering capacity for command and control system integration, concentrating pricing power with Lockheed Martin and Northrop Grumman as they bundle multi-year sustainment contracts that fragment third-party maintenance competition. Taiwan's semiconductor fabrication dominance for advanced FPGAs and secure processors creates single-source vulnerability that primes pass through to defense ministries via cost-plus contract structures.
Pricing Analysis
Long-term offtake contracts dominate procurement as Australia's Land 400 program bundles 25-year through-life support with vehicle delivery, locking in recurring revenue streams. Price differentiation separates NATO Federated Mission Networking-certified systems from national proprietary architectures, with JADC2 interoperability commanding premium positioning. Cost compression in software-defined radio modules intensifies as ITAR licensing friction delays allied fielding schedules. Border security agencies exhibit highest price sensitivity due to constrained procurement budgets, while special operations units prioritize capability over unit economics.
Supply Chain Analysis
Extended payment terms from prime contractors to subsystem vendors characterize supplier financing as program milestones stretch across multi-year development cycles. Advanced FPGA and secure processor fabrication concentrates in Taiwan and South Korea, while vehicle electronics integration clusters in Germany and the United States. The supply chain draws from gallium nitride substrates for radar components, rare earth elements for magnet manufacturing, and radiation-hardened semiconductors for tactical edge computing. Single-source vulnerability in Taiwan semiconductor fabrication exposes prime contractors to geopolitical disruption. Distribution runs through defense ministry procurement authorities with national security clearance requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Land digital battlefield markets sit in early-cycle expansion as JADC2 interoperability mandates force brigade-level modernization across NATO member states, creating sustained procurement pull for networked command architectures.
For Market Incumbents: Insulate recurring revenue streams by deepening software update pipeline control and cryptographic key management infrastructure that locks out third-party sustainment providers. Accelerate open architecture certification to preempt EU AI Act algorithmic transparency requirements that threaten opaque neural network deployments. Vertical integration into edge computing node manufacturing reduces Taiwan semiconductor exposure. For New Entrants and Emerging Players: Build out helmet-mounted situational awareness display capabilities that bypass vehicle-centric procurement cycles through soldier-level connectivity upgrades. Poland's Wolf armored vehicle program offers the most penetrable entry point for battle management providers outside established US-German supply relationships. Pursue rapid NATO Federated Mission Networking certification as a go-to-market wedge. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-defined capability providers with multi-year sustainment bundling authority, positioning them favorably across the 5-10 year defense modernization window. Acquisition targets should concentrate on edge computing specialists with EU AI Act conformity assessment capabilities. Monitor JADC2 procurement acceleration rates as the primary inflection indicator for valuation expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Open Architecture Certification | Enables JADC2 interoperability compliance that unlocks NATO allied procurement budgets. |
| EU AI Act Conformity Assessment | Mandatory algorithmic transparency documentation gates French and Swedish infantry fighting vehicle bids. |
| Multi-Year Sustainment Bundling | Australia's Land 400 Phase 3 locks 25-year support contracts with vehicle delivery, excluding third-party maintenance. |
| Edge Computing Node Integration | German mechanized brigades field onboard threat correlation systems under accelerated procurement authorities. |
| Helmet-Mounted Display Convergence | Augmented reality optics with tactical radio networks bypass vehicle-centric procurement cycles for soldier connectivity. |
Research Methodology
A standing panel of program managers at defense ministries, prime contractor capture executives, subsystem vendor business development leads, and military procurement officers provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from NATO standardization agreements, US DoD budget justification documents, EU defense procurement directives, and national parliamentary defense committee records. Bottom-up program-level data triangulated against top-down defense expenditure forecasts.
Scenario-bracketing around JADC2 implementation timelines and EU AI Act enforcement intensity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include system type hierarchy, processing location architecture, operational application, and end-user procurement authority. CAGRs derived from deployment schedule acceleration curves and allied interoperability mandate compliance rates. Industry-specific inputs encompassed ITAR licensing queue durations and Taiwan semiconductor capacity allocation priorities.
Practitioners should monitor JADC2 procurement acceleration, EU AI Act conformity assessment backlog, and Taiwan geopolitical stability for early signals of forecast deviation. Macroeconomic defense budget compression, regulatory restriction expansion, or semiconductor supply disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Europe Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Military Infrastructure and Logistics Market
Military Equipment and Infrastructure
Manpack Military Antennas Market
Military Equipment and Infrastructure
Europe Digital Battlefield Market
Military Equipment and Infrastructure
Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Global Remote Weapon Station Market
Military Equipment and Infrastructure
Soft Wall Military Shelter Market
Military Equipment and Infrastructure
CBRN Protection Equipment Market
Military Equipment and Infrastructure
Turret Handlers Market
Military Equipment and Infrastructure
Howitzer Artillery System Market
Military Equipment and Infrastructure
Used Serviceable Material (USM) Market
Military Equipment and Infrastructure
Military Displays Market
Military Equipment and Infrastructure
Rocket Solid Propulsion Market
Military Equipment and Infrastructure
Military Test Equipment Market
Military Equipment and Infrastructure
Aircraft Carrier Arresting Systems Market
Military Equipment and Infrastructure
Defense Logistics Market