
 Infrared Suppression Systems Market | 2026-2036
Infrared Suppression Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Infrared Suppression Systems Market Analytics
The performance gap between field-proven active suppression suites and baseline passive coatings is repositioning procurement criteria across defense ministries. Northrop Grumman Corporation leverages decades of fixed-wing infrared countermeasures heritage to anchor naval aviation contracts. BAE Systems sustains rotorcraft-specific cooling architectures through integrated platform partnerships with European NATO operators. Elbit Systems competes in the upgrade-kit segment by specializing in compact, retrofittable exhaust suppressors for aging utility helicopter fleets.
Infrared suppression systems encompass engineered hardware and materials that attenuate thermal signatures emitted by engines, exhaust plumes, and airframe surfaces, typically operating across the three-to-five-micrometer and eight-to-fourteen-micrometer atmospheric transmission bands to reduce detection probability by heat-seeking threats. The primary purpose centers on platform survivability, extending mission endurance in contested airspace where infrared-guided weapons dominate kill chains. Cooling systems and hybrid systems command the largest share of current program spend because they address the highest-signature sources with measurable reduction metrics, while advanced materials represents the fastest-expanding technology category as metamaterial films and ceramic matrix composites mature from laboratory qualification to airworthiness certification. Detectors within the product-type dimension remain a smaller revenue pool but carry above-average margins due to sensor fusion requirements linking infrared suppression with missile warning architectures.
The US Department of Defense, NATO's Airborne Early Warning and Control Program Management Agency, and Israel's Ministry of Defense set operational requirements that directly determine subsystem specifications, test protocols, and platform-integration timelines for infrared suppression hardware. Compliance with these frameworks shapes market access, as non-aligned suppliers face technology-transfer barriers and foreign military sales approval processes that extend contract cycles. Stakeholders must monitor evolving directed-energy threat profiles and corresponding signature-management specifications that will redefine performance thresholds before the next major platform refresh cycle.
Market Dynamics
The US Department of Defense's next-generation survivability specifications are compressing upgrade timelines for legacy rotorcraft fleets, forcing prime contractors to accelerate qualification cycles for hybrid suppression architectures.
Growth Catalysts
- Directed-Energy Threat Proliferation:NATO member states are mandating enhanced signature management for platforms operating in contested electromagnetic environments, expanding the addressable hardware base for exhaust-cooling systems.
- Hybrid System Maturation:The convergence of active cooling with metamaterial coatings is creating measurable detection-range reduction metrics that defense procurement offices now require in technical specifications.
- Israeli Combat Theater Demand:Sustained operational tempo in the Gaza and Lebanon corridors is driving rapid-fielding contracts for retrofittable suppression kits on utility helicopter fleets.
Market Restraints
- Ceramic Matrix Composite Input Volatility:Specialized feedstock for high-temperature suppressor components faces supply concentration from a limited qualified supplier base in Japan and the United States.
- Technology Transfer Barriers:US International Traffic in Arms Regulations and allied foreign military sales protocols extend contract cycles for non-aligned suppliers seeking NATO platform integration.
- Passive Coating Substitution:Baseline emissivity-reduction paints retain procurement share for budget-constrained upgrade programs where full active suppression suites exceed available funding.
Strategic Opportunities
- Unmanned Platform Integration:Medium-altitude long-endurance drones operating in denied airspace create demand for miniaturized suppressor architectures with reduced power and weight budgets.
- United Kingdom Industrial Partnership:The UK's Defence and Security Industrial Strategy incentivizes domestic manufacturing of rotorcraft survivability hardware through preferred supplier frameworks.
- Sensor Fusion Convergence:Integration of infrared suppression with missile warning system detectors enables bundled procurement contracts and recurring revenue from fused-architecture sustainment.
Industry Challenges
- Thermal Management Engineering Scarcity:The specialized skill set combining aerodynamics, materials science, and signature physics faces recruitment competition from commercial aerospace and energy sectors.
- Airworthiness Certification Timeline:FAA and military airworthiness authorities require extended flight-test protocols for novel suppressor geometries, compressing program margins and delaying revenue recognition.
- Legacy Platform Interface Complexity:Aging helicopter engine compartments impose physical constraints on retrofit suppressor packaging, forcing costly structural modifications or performance trade-offs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infrared Suppression Systems Market |
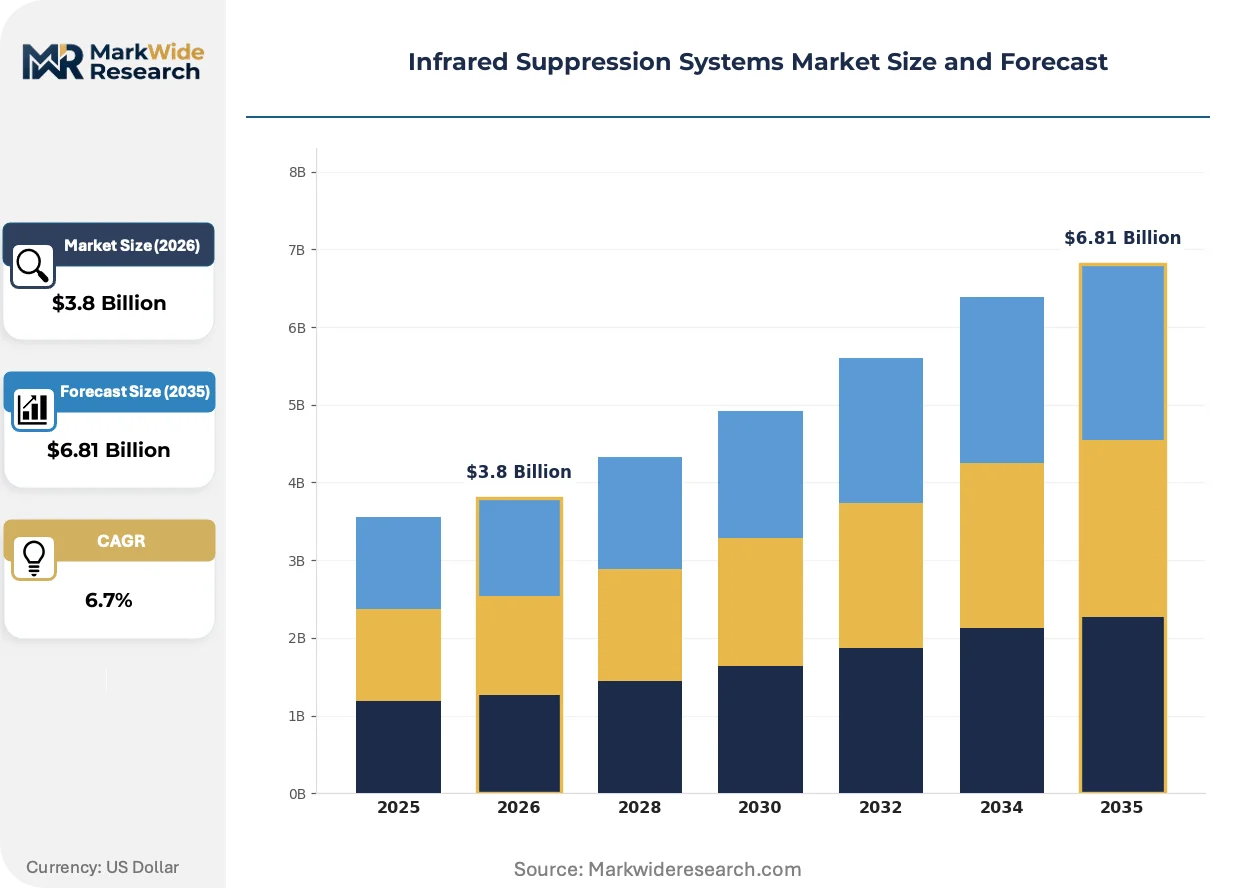
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cooling Systems, Filters, Coatings, Detectors Application: Aerospace, Military, Electronics, Automotive Technology: Passive Systems, Active Systems, Hybrid Systems, Advanced Materials End User: Defense, Commercial, Industrial, Research Institutions |
| Companies Covered | Northrop Grumman Corporation, BAE Systems, Raytheon Technologies Corporation, Leonardo S.p.A., Elbit Systems, Saab AB, Thales Group, L3Harris Technologies, Lockheed Martin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infrared Suppression Systems Market Evolving Landscape
Metamaterial films and ceramic matrix composites are transitioning from laboratory qualification to production airworthiness, while procurement offices rewrite technical specifications to prioritize measurable signature reduction over hardware lineage.
Electrochromic adaptive coatings are electrifying the suppressor landscape by enabling real-time emissivity modulation across atmospheric transmission bands. Naval aviation programs are piloting these materials on maritime patrol platforms where thermal contrast against water backgrounds demands dynamic response. This capability is electrifying competitive positioning by rewarding suppliers with materials-science depth over traditional hardware integrators.
REACH regulation amendments in the European Union are restricting high-emissivity coating chemistries previously standard in rotorcraft exhaust treatments. Industrial consequence includes accelerated reformulation programs for suppliers seeking continued access to European NATO upgrade contracts. French and German defense ministries are most affected, driving procurement preference toward suppliers with certified low-emissivity alternatives already in production.
Platform-as-a-service contracting is penetrating military sustainment, with defense ministries unbundling suppressor hardware from long-term performance guarantees. Original equipment manufacturers face margin compression as third-party logistics providers capture aftermarket service revenue. This pattern is most visible in United States Army aviation brigades, where contractor logistics support contracts now specify availability metrics rather than component replacement schedules.
Infrared Suppression Systems Market Segmentation
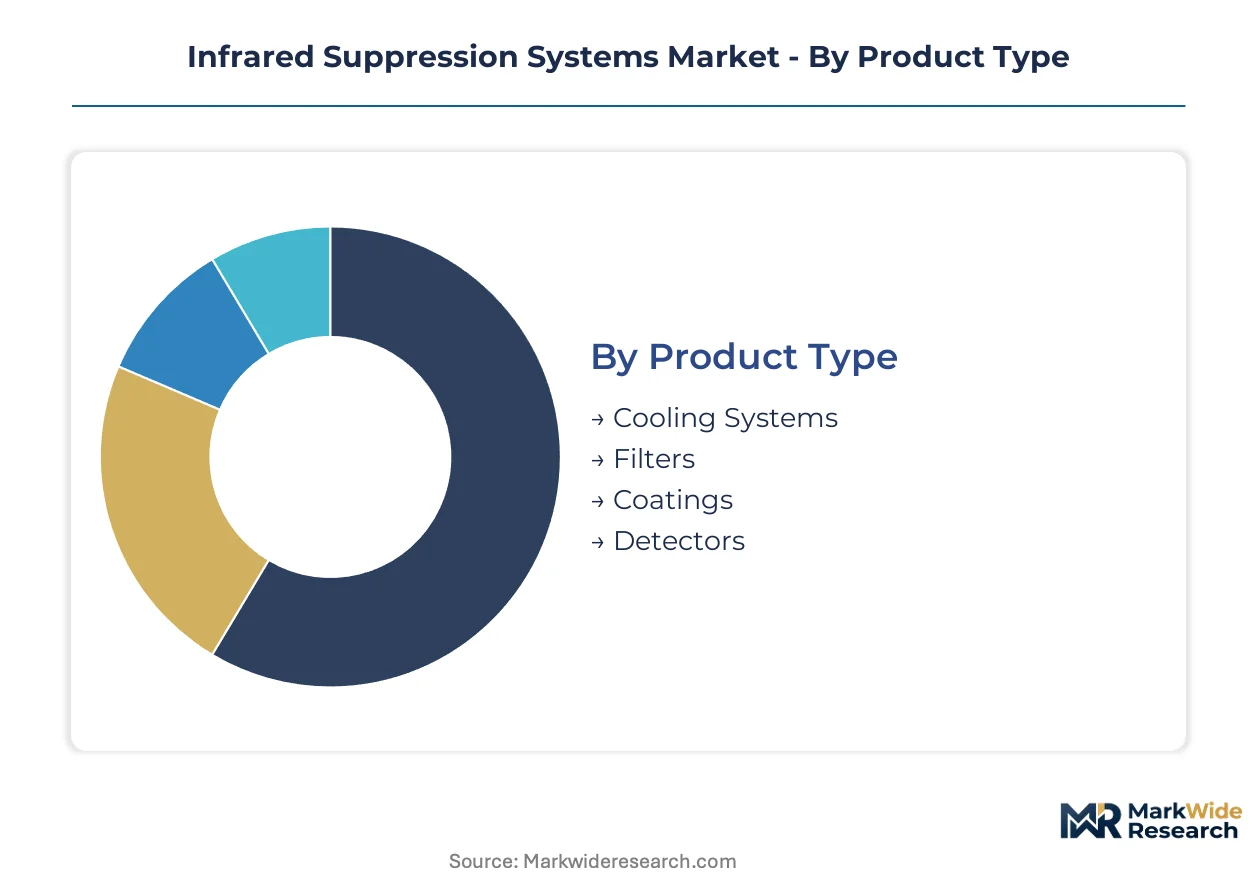
Infrared suppression systems serve divergent thermal-signature threats across fixed-wing, rotorcraft, and ground platforms, requiring procurement offices to match hardware specifications to mission profiles rather than platform categories alone. Segmentation reveals where cooling architectures command premium pricing versus where passive coatings satisfy budget-constrained programs.
Product Type:
Defense procurement offices differentiate hardware investments based on measurable signature-reduction metrics versus installation complexity.
- Cooling Systems:Engine exhaust-cooling hardware mixes ambient air with hot gases to suppress plume temperatures below heat-seeking seeker thresholds. US Army aviation brigades and Israeli Defense Forces helicopter fleets drive concentrated demand for retrofittable ejector suppressors on aging utility platforms where engine compartment geometry limits passive alternatives.
- Filters:Spectral filters block specific atmospheric transmission bands to reduce detection probability against particular threat seekers. NATO naval aviation programs in the United Kingdom and France prioritize filter integration for maritime patrol platforms operating against sea-skimming infrared-guided missiles.
- Coatings:Emissivity-modifying surface treatments attenuate thermal radiation from airframe skins and engine nacelles. Budget-constrained upgrade programs in European NATO states retain coating procurement where full active suppression suites exceed available funding envelopes.
- Detectors:Infrared warning sensors integrated with suppression system controllers enable automated threat-response protocols. Above-average margins characterize this segment due to sensor-fusion requirements linking signature management with missile-warning architectures.
Cooling systems lead volumes today; detectors are gaining share fastest.
Application:
Mission environment determines whether platforms require full active suppression or baseline passive protection.
- Aerospace:Fixed-wing military aircraft and unmanned platforms demand miniaturized suppressor architectures with reduced power and weight budgets. Medium-altitude long-endurance drone programs in Israel and the United States create emerging demand for compact exhaust-cooling solutions.
- Military:Rotorcraft fleets across NATO member states represent the dominant addressable hardware base, with attack and utility helicopters requiring comprehensive signature management against shoulder-launched threats. US Department of Defense survivability specifications compress upgrade timelines for legacy fleets.
- Electronics:Thermal management for high-power electronic warfare suites employs suppression hardware to mask heat signatures from adversary sensors. Specialized applications in signals intelligence platforms drive limited but high-specification demand.
- Automotive:Ground vehicle infrared suppression addresses engine and exhaust signatures for armored platforms operating in contested environments. Limited procurement volume reflects cost constraints on mechanized infantry vehicle upgrade programs.
Military applications dominate current spend; aerospace platforms show steepest expansion trajectory.
Technology:
Technology selection reflects the trade-off between proven field performance and emerging capability maturation.
- Passive Systems:Baseline emissivity-reduction architectures rely on material properties alone without active cooling or power consumption. Mature qualification histories and lower unit costs sustain procurement share for budget-constrained programs in secondary NATO markets.
- Active Systems:Powered cooling and mechanical suppression mechanisms deliver measurable detection-range reduction metrics. US and Israeli defense ministries mandate active architectures for frontline combat platforms where survivability requirements override cost considerations.
- Hybrid Systems:Convergence of active cooling with advanced coatings creates multi-layer signature suppression with quantifiable performance advantages. NATO procurement offices increasingly require hybrid specifications in technical standards for next-generation platform contracts.
- Advanced Materials:Metamaterial films and ceramic matrix composites transition from laboratory qualification to production airworthiness certification. French and German defense ministries accelerate adoption following REACH regulation amendments restricting legacy coating chemistries.
Hybrid systems command the largest program spend; advanced materials are climbing the fastest.
End User:
Funding authority and operational tempo separate defense procurement patterns from commercial and industrial adoption.
- Defense:Military ministries in the United States, United Kingdom, and Israel sustain program funding through active combat operations and indigenous manufacturing requirements. US International Traffic in Arms Regulations and allied foreign military sales protocols shape supplier access and contract cycles.
- Commercial:Civil aviation applications remain minimal due to absence of heat-seeking threat environments and regulatory certification costs. Limited demand concentrates in executive transport platforms operating in contested regions.
- Industrial:Oil and gas infrastructure protection against hostile surveillance employs infrared suppression for critical facilities. Geographic concentration in Middle Eastern production facilities drives specialized procurement outside mainstream defense channels.
- Research Institutions:National laboratories and university programs qualify novel materials and architectures for future platform integration. US Department of Defense research contracts and European defense research frameworks sustain this segment.
Defense end users anchor absolute volumes; research institutions expand most quickly as metamaterial development accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized thermal management engineers concentrate in defense aerospace clusters across the United States, United Kingdom, Israel, and select European NATO states, anchoring regional capability for exhaust-cooling and emissivity-reduction hardware development.
United States
US Army aviation brigades and naval aviation programs drive concentrated procurement for retrofittable ejector suppressors and hybrid cooling architectures. The Department of Defense's next-generation survivability specifications compress upgrade timelines for legacy rotorcraft fleets. Huntsville, Alabama and the Dallas-Fort Worth metroplex host prime contractor engineering centers where qualification cycles for active suppression systems accelerate.
United Kingdom
Royal Navy maritime patrol platforms and RAF rotorcraft fleets sustain demand for spectral filters and exhaust-cooling hardware against sea-skimming infrared threats. The Defence and Security Industrial Strategy incentivizes domestic manufacturing through preferred supplier frameworks. Bristol and the South West England cluster concentrate BAE Systems platform-integration capabilities for European NATO operators.
Israel
Sustained operational tempo in Gaza and Lebanon corridors drives rapid-fielding contracts for compact, retrofittable exhaust suppressors on aging utility helicopter fleets. The Ministry of Defense sets stringent signature-reduction specifications that shape regional technical standards. Haifa and the central coastal plain host Elbit Systems engineering facilities specializing in miniaturized suppressor architectures.
Germany
Luftwaffe and Bundeswehr aviation programs prioritize REACH-compliant low-emissivity coating alternatives following EU regulation amendments restricting legacy chemistries. The defense ministry accelerates hybrid system adoption for next-generation platform contracts. Munich and Bavaria concentrate materials-science research institutions qualifying metamaterial films for production airworthiness.
France
Naval aviation programs in Brest and the Brittany coast pilot electrochromic adaptive coatings for maritime patrol platforms requiring dynamic thermal response against water backgrounds. The Direction Générale de l'Armement mandates measurable detection-range reduction metrics in technical specifications. Toulouse and the Occitanie aerospace cluster integrate suppression hardware with missile warning system architectures.
Infrared Suppression Systems Market Competitive Landscape
Top-tier vendors anchor platform-integration contracts, while mid-tier specialists occupy retrofit-kit and component supply positions. The vendor base stratifies across three tiers: prime contractors with airworthiness certification authority, subsystem integrators with platform-specific partnerships, and materials suppliers transitioning laboratory innovations to production. Two strategic archetypes dominate: heritage defense conglomerates leveraging fixed-wing countermeasures expertise into naval aviation, and rotorcraft-focused specialists engineering compact cooling architectures. Competitive moves concentrate on strategic partnerships with NATO procurement offices and technology licensing for metamaterial qualification.
Within the heritage defense conglomerate tier, Northrop Grumman Corporation and Raytheon Technologies Corporation exemplify vendors translating decades of fixed-wing infrared countermeasures heritage into naval aviation contract positions. Among rotorcraft-focused specialists, Elbit Systems occupies a position representing compact, retrofittable exhaust suppressor engineering for aging utility helicopter fleets. BAE Systems sits within the European platform-integration archetype, anchoring rotorcraft-specific cooling architectures through sustained partnerships with NATO operators.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| BAE Systems |
| Raytheon Technologies Corporation |
| Leonardo S.p.A. |
| Elbit Systems |
| Saab AB |
| Thales Group |
| L3Harris Technologies |
| Lockheed Martin Corporation |
| Others |
Value Network & Pricing Analysis
Sovereign-backed defense contractors and family-owned materials specialists anchor supply-side ownership patterns, concentrating pricing power among qualified suppliers of ceramic matrix composites and metamaterial films while compressing margins for hardware integrators facing unbundled service contracting.
Pricing Analysis
Bundled long-term performance guarantees are unbundling into hardware-only transactions with separate sustainment contracts. Three-tier pricing structure across certified airworthiness, qualified production, and developmental qualification levels separates prime contractors from subsystem integrators and laboratory-stage materials suppliers. Cost compression in retrofit kit segments is intensifying because defense ministries now specify availability metrics rather than component replacement schedules. Budget-constrained European NATO operators exhibit highest price sensitivity, while US and Israeli frontline combat programs demonstrate lowest sensitivity due to survivability mandates overriding cost considerations.
Supply Chain Analysis
Freight costs for specialized high-temperature feedstock concentrate supply risk in trans-Pacific lanes serving US and Japanese ceramic matrix composite producers. Manufacturing gravity centers on the United States, United Kingdom, and Israel for exhaust-cooling hardware, with Japan and Germany anchoring advanced materials feedstock. Critical inputs include silicon carbide fibers, pyrolytic carbon matrices, and rare-earth-doped metamaterial substrates. Single-source vulnerability from qualified Japanese suppliers of ceramic precursors threatens production continuity. Distribution runs through prime contractor logistics networks with foreign military sales approval gates controlling access to NATO platform integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement offices now prioritize measurable signature-reduction metrics over hardware lineage, elevating suppliers with certified metamaterial production and hybrid system airworthiness.
For Market Incumbents: Acquire specialized thermal management engineering capabilities to offset recruitment competition from commercial aerospace. Lock in multi-year ceramic matrix composite offtake agreements with Japanese feedstock suppliers before qualification barriers harden. Backward integration into metamaterial film production secures margin capture as REACH amendments displace legacy coating chemistries. For New Entrants and Emerging Players: Electrochromic adaptive coating architectures offer technology-first entry into naval aviation programs requiring dynamic thermal response. White-space concentrates in unmanned platform miniaturization where reduced power and weight budgets favor compact suppressor designs. Israeli rapid-fielding contracts for utility helicopter retrofits present the most penetrable near-term demand pool. Go-to-market positioning should emphasize airworthiness certification speed over performance differentiation. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier subsystem integrators with platform-specific NATO partnerships but limited materials-science depth. Five-to-ten-year viability hinges on hybrid system adoption curves and directed-energy threat proliferation timelines. Acquisition target archetype: rotorcraft-focused cooling specialists with Israeli Defense Forces contract history and transferable unmanned platform architectures. Monitor electrochromic coating pilot program outcomes in French naval aviation as inflection indicator for technology transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Metamaterial Production Certification | REACH-compliant qualification unlocks French and German defense ministry procurement preference. |
| Hybrid System Airworthiness Investment | FAA and military authority certification accelerates revenue recognition for novel suppressor geometries. |
| Sensor Fusion Architecture Integration | Missile warning system bundling captures recurring sustainment revenue from US Army aviation brigades. |
| Unmanned Platform Miniaturization | Compact exhaust-cooling solutions address medium-altitude long-endurance drone demand in Israel and the United States. |
| Ceramic Matrix Composite Backward Integration | In-house pyrolytic carbon production mitigates single-source vulnerability from Japanese feedstock concentration. |
Research Methodology
Coverage spans the United States, United Kingdom, Israel, Germany, and France, with primary inputs from each defense aerospace cluster. The approach combines structured interviews with thermal management engineering directors, platform integration leads at prime contractors, defense ministry procurement officers, and materials-science research directors with secondary validation from FAA airworthiness databases, US Department of Defense contract disclosures, EU REACH regulatory filings, and customs trade records for ceramic matrix composite feedstock. Bottom-up platform installation forecasts triangulate against top-down defense budget allocation analysis.
Granularity-level modeling distinguishes active cooling architectures from passive coatings at the technology tier, segments rotorcraft from fixed-wing and unmanned applications, and tracks metamaterial versus conventional material qualification status. CAGRs derive from defense ministry procurement pipeline analysis weighted by platform refresh timelines and survivability specification evolution. Industry-specific forecast inputs include directed-energy threat proliferation curves and REACH amendment implementation schedules affecting coating chemistry reformulation.
The model holds under sustained NATO defense spending and ceramic matrix composite supply continuity; deviation in Japanese feedstock export restrictions or directed-energy threat acceleration would shift hybrid system adoption trajectories. Forecasts reflect documented assumptions regarding airworthiness certification timelines and foreign military sales approval durations. Stakeholders should weight assumptions against their own operating context and contract visibility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ISR
Intelligence Surveillance and Reconnaissance (ISR) Market
ISR
NATO C4ISR Market
ISR
Brazil C4ISR Market
ISR
Airborne ISR Market
ISR
North America C5ISR Market
ISR
C6ISR Market
ISR
Japan C4ISR Market
ISR
Naval ISR Market
ISR
C5ISR Market
ISR
Asia-Pacific C4ISR Market
ISR
Active Phased Array Radar (APAR) Market
ISR
Synthetic Aperture Radar (SAR) Market
ISR
Saudi Arabia C4ISR Market
ISR
North America Airborne ISR Market
ISR
IFF System Market
ISR
United States C4ISR Market