
 Global Stratospheric UAV Payload Technology Market | 2026-2036
Global Stratospheric UAV Payload Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stratospheric UAV Payload Technology Market Foresight
The EU Green Deal's emissions monitoring mandates for maritime and border surveillance is pivoting procurement toward solar-electric stratospheric platforms that reduce per-mission carbon intensity. Lockheed Martin leverages its Skunk Works heritage in high-altitude systems to sustain classified contract pipelines. Raytheon Technologies anchors its position through integrated radar-electro-optical payload families. Boeing competes via its Aurora Flight Sciences subsidiary's expertise in ultra-long-endurance airframe-payload coupling.
Stratospheric UAV payload technology encompasses sensor suites, communication arrays, and power management systems engineered for operation at altitudes between eighteen and twenty-two kilometers, where atmospheric density permits extended loiter with minimal propulsive energy while exposing equipment to temperatures ranging from minus fifty-six to minus seventy degrees Celsius and intense ultraviolet radiation. These payloads serve military intelligence-gathering, climate monitoring, and telecommunications relay missions from quasi-stationary positions above conventional air traffic. Electro-optical and infrared technology segments dominate current procurement volumes due to their maturity in targeting and wide-area surveillance applications, while synthetic aperture radar and hyperspectral imaging represent the fastest-expanding categories as all-weather capability and spectral discrimination become operational requirements. Navigation systems and environmental monitors within the payload type dimension command premium margins where integration with semi-autonomous control architectures reduces operator burden.
FAA oversight of high-altitude platform station certifications shapes market access timelines for commercial operators in the United States, while EASA's emerging framework under the EU Drone Strategy influences European procurement specifications. China's MIIT coordinates national standards for near-space vehicle payloads through GB standard development that affects export-competitive positioning. Stakeholders must monitor how military classification thresholds interact with civilian spectrum allocation decisions at the ITU level.
Market Dynamics
Synthetic aperture radar miniaturization is compressing payload development cycles and forcing electro-optical incumbents to diversify their sensor architectures or cede share to radar-native suppliers.
Growth Catalysts
- NATO ISR Modernization:Defense agencies across member states are consolidating procurement frameworks for stratospheric intelligence platforms, creating pooled demand volumes that justify dedicated production lines.
- FAA HAPS Certification Maturation:The United States regulator's advancing framework for high-altitude platform stations is reducing airworthiness uncertainty for commercial operators and accelerating platform availability timelines.
- EU Green Deal Maritime Mandates:Emissions monitoring requirements for shipping corridors are pivoting surveillance procurement toward solar-electric stratospheric systems that eliminate per-mission fuel consumption.
Market Restraints
- Ultra-Low Temperature Component Costs:Electronics rated for sustained operation at minus seventy degrees Celsius command three to five times standard aerospace pricing, inflating payload bills of material.
- Chinese GB Standard Export Friction:MIIT-coordinated national standards for near-space vehicles create technical barriers for non-domestic payload suppliers seeking access to Chinese platform integrators.
- ITU Spectrum Allocation Uncertainty:Military classification thresholds for communication payloads interact unpredictably with civilian spectrum decisions, delaying frequency authorization timelines.
Strategic Opportunities
- Telecommunications Relay White Space:Rural broadband gaps in India and sub-Saharan Africa present addressable demand for stratospheric payload operators capable of delivering cellular backhaul from quasi-stationary positions.
- Hyperspectral-SAR Sensor Fusion:Convergence of spectral discrimination and all-weather radar imaging is opening new application categories in precision agriculture and mineral exploration previously served by satellite constellations.
- EASA Drone Strategy Alignment:The European regulator's emerging high-altitude framework is creating first-mover advantages for payload suppliers certifying to draft specifications before formal adoption.
Industry Challenges
- Stratospheric Systems Engineering Talent Scarcity:The intersection of high-altitude aerodynamics, extreme-environment electronics, and semi-autonomous control requires skill sets concentrated in a handful of defense contractors and national laboratories.
- Dual-Use Export Control Complexity:Payload technologies with civilian climate monitoring and military ISR applications trigger multi-jurisdiction licensing reviews that extend sales cycle duration unpredictably.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stratospheric UAV Payload Technology Market |
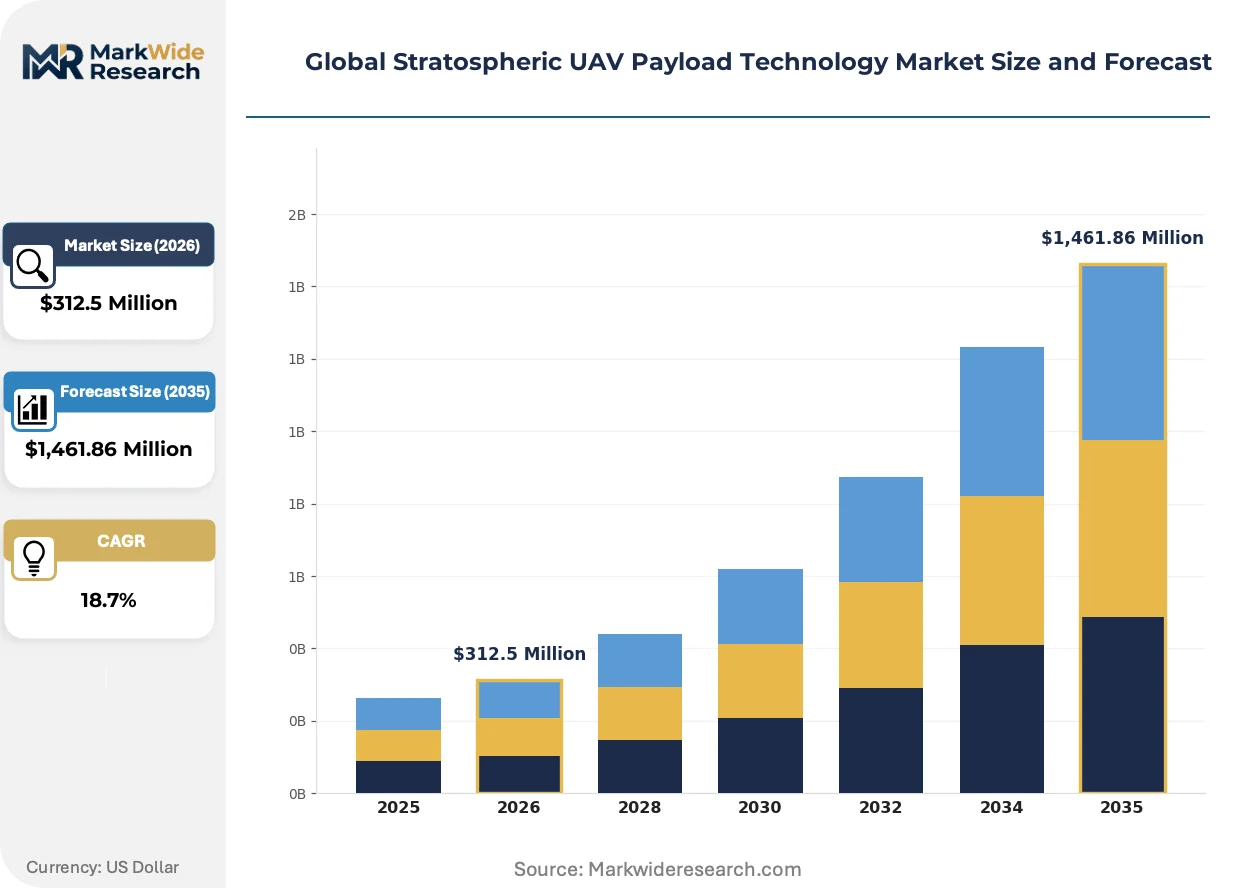
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $1,461.86 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payload Type: Communication Equipment, Surveillance Cameras, Weather Sensors, Scientific Instruments, Navigation Systems, Environmental Monitors Technology: Electro-Optical, Infrared, LiDAR, Radar, Hyperspectral Imaging, Synthetic Aperture Radar End User: Defense Agencies, Weather Forecasting Organizations, Agricultural Analysts, Space Research Entities, Disaster Management Authorities Deployment Mode: High Altitude Platforms, Semi-Autonomous Control, Remote Pilot Operation, Real-Time Data Transmission, Satellite Integration |
| Companies Covered | Lockheed Martin Corporation, Raytheon Technologies Corporation, Boeing Company, BAE Systems, AeroVironment, Northrop Grumman, Thales Group, HAPSMobile, Airbus SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stratospheric UAV Payload Technology Market Shifts & Advancements
Miniaturization of synthetic aperture radar arrays is fragmenting the historical electro-optical monopoly on targeting payloads and enabling multi-sensor architectures previously excluded by mass and power constraints.
Compact SAR front-ends operating at X-band and Ku-band frequencies now deliver sub-meter resolution from stratospheric altitudes while consuming under two hundred watts. Defense procurement offices in the United States and United Kingdom are specifying these radars as primary sensors for contested environments where cloud cover degrades electro-optical utility. The technology is modularizing payload design, allowing integrators to swap sensor suites between missions without airframe modification and compressing development timelines for specialized variants.
EASA's emerging high-altitude platform framework under the EU Drone Strategy is establishing airworthiness criteria that diverge from FAA HAPS pathways, creating parallel certification tracks. European platform developers must now engineer payloads to dual regulatory specifications or accept market access limitations. Climate monitoring missions with public funding exposure face the most stringent documentation requirements, while classified military programs operate under accelerated national security exemptions.
Buyers are unbundling payload procurement from platform acquisition, reversing the historical integrated-system contracting model. Defense agencies now issue separate solicitations for sensor suites, communication arrays, and power management subsystems, then integrate through third-party systems engineers. This fragmentation is most pronounced in the United States, where the Space Development Agency's proliferated architecture philosophy is migrating downward to stratospheric layers and rewarding component-specialist suppliers over vertically integrated primes.
Global Stratospheric UAV Payload Technology Market Segmentation
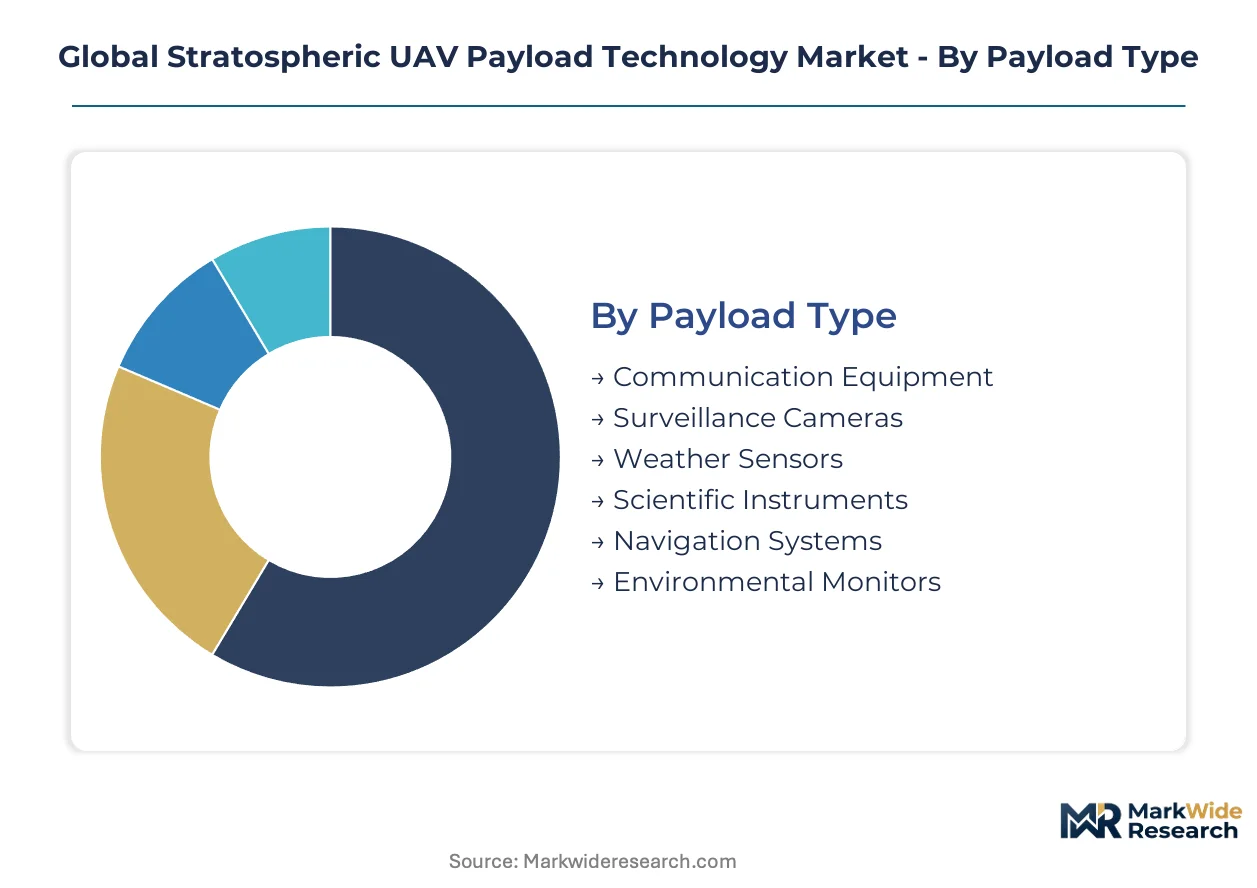
Segmentation in stratospheric UAV payload technology reveals how sensor architectures, control modalities, and user requirements fragment procurement patterns across defense and civilian applications. Payload suppliers must align development roadmaps with distinct integration depths, from standalone surveillance cameras to fully embedded synthetic aperture radar systems.
Payload Type:
Standalone communication equipment and surveillance cameras operate as bolt-on modules with standardized interfaces, while navigation systems and environmental monitors demand deeper airframe-embedded integration with power and thermal management subsystems.
- Communication Equipment:Radio frequency arrays and optical laser terminals engineered for stratospheric relay missions handle bandwidth aggregation across cellular backhaul and military networks. Demand concentrates in the United States where FAA HAPS certification timelines are compressing, though ITU spectrum allocation uncertainty delays frequency authorization for cross-border operations.
- Surveillance Cameras:Electro-optical and infrared gimbal systems deliver wide-area motion imagery from quasi-stationary positions above conventional air traffic. NATO member states are consolidating procurement frameworks for these payloads, creating pooled demand volumes that justify dedicated production lines for ISR modernization programs.
- Weather Sensors:Atmospheric profiling instruments measuring temperature, pressure, and humidity gradients support climate monitoring missions.
- Scientific Instruments:Cosmic radiation detectors and ozone sampling equipment serve space research entities with specialized mission requirements.
- Navigation Systems:GPS-denied positioning architectures using celestial or terrain-referenced algorithms require tight integration with flight control computers.
- Environmental Monitors:Air quality and emissions detection payloads serve EU Green Deal maritime surveillance mandates with solar-electric platform compatibility.
Volume placements concentrate in Surveillance Cameras; the faster expansion belongs to Communication Equipment.
Technology:
Cost tiering separates mature electro-optical systems from emerging radar architectures, with price differentials reflecting thermal management complexity and all-weather operational envelopes.
- Electro-Optical:Visible-spectrum imaging sensors with sub-meter ground sample distance from stratospheric altitudes remain the procurement default for clear-weather missions. United Kingdom defense offices specify these as secondary sensors in contested environments where cloud cover degrades primary utility.
- Infrared:Thermal imaging arrays detect heat signatures through darkness and limited atmospheric obscuration for targeting and search applications. Agricultural Analysts in Australia and Brazil are adopting these payloads for drought stress monitoring and irrigation management at reduced per-acre survey costs versus satellite alternatives.
- LiDAR:Laser ranging systems generate three-dimensional terrain models for disaster response and infrastructure assessment.
- Radar:Active electronically scanned arrays provide all-weather detection capabilities independent of solar illumination.
- Hyperspectral Imaging:Spectral discrimination across hundreds of narrow bands enables mineral exploration and precision agriculture previously served by satellite constellations.
- Synthetic Aperture Radar:Miniaturized X-band and Ku-band front-ends now deliver sub-meter resolution while consuming under two hundred watts, fragmenting the historical electro-optical monopoly on targeting payloads.
Procurement volume clusters in Electro-Optical; Synthetic Aperture Radar is climbing the fastest as defense specifications prioritize contested-environment survivability.
End User:
Application maturity varies sharply across user types, with defense agencies driving specifications for extreme-environment reliability while agricultural and research users accept reduced operational envelopes for cost efficiency.
- Defense Agencies:Classified military programs operate under accelerated national security exemptions that bypass civilian airworthiness documentation, though dual-use export control complexity extends sales cycle duration unpredictably for suppliers with civilian climate monitoring product lines.
- Weather Forecasting Organizations:Publicly funded atmospheric monitoring missions face stringent EASA documentation requirements under emerging high-altitude platform frameworks. European platform developers must engineer payloads to dual regulatory specifications or accept market access limitations.
- Agricultural Analysts:Commercial crop health assessment services demand rapid revisit rates and spectral discrimination at price points below satellite imagery subscriptions.
- Space Research Entities:Near-space environment characterization missions require radiation-hardened electronics rated for sustained operation at minus seventy degrees Celsius.
- Disaster Management Authorities:Rapid deployment requirements for earthquake and flood response favor modular payload architectures swappable between missions without airframe modification.
Contract value concentrates with Defense Agencies; Disaster Management Authorities are expanding most quickly as civil protection budgets formalize stratospheric rapid response capabilities.
Deployment Mode:
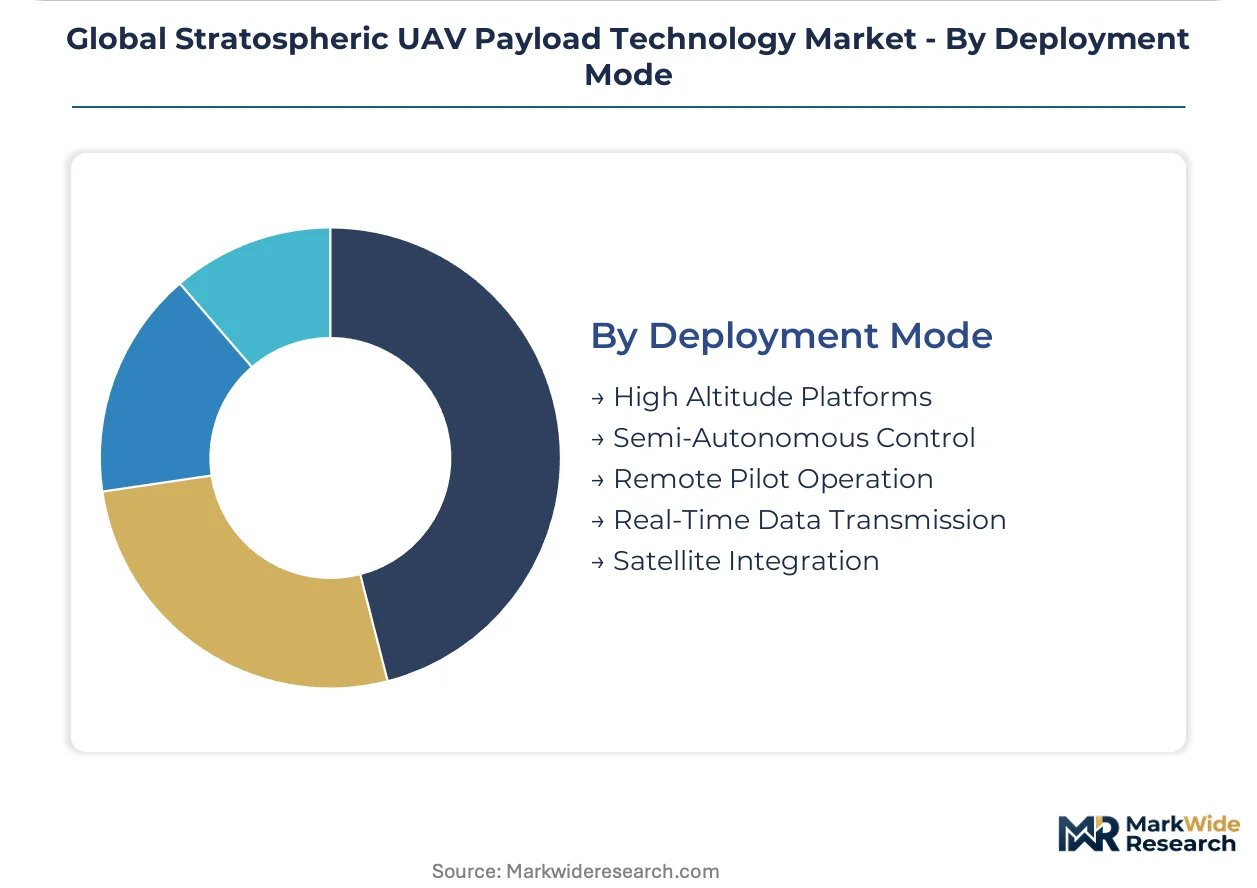
Customer type differentiation separates government operators with dedicated ground infrastructure from commercial entities relying on third-party satellite integration and real-time data transmission services.
- High Altitude Platforms:Quasi-stationary positioning at eighteen to twenty-two kilometers altitude enables persistent loiter with minimal propulsive energy. India's rural broadband gaps and sub-Saharan Africa's cellular infrastructure deficits present addressable demand for operators capable of delivering backhaul from these positions.
- Semi-Autonomous Control:Reduced operator burden through automated flight path management and sensor tasking commands premium margins where integration with navigation and environmental monitor subsystems compresses mission planning timelines.
- Remote Pilot Operation:Man-in-the-loop control architectures persist in regulatory environments where full autonomy lacks certification pathways.
- Real-Time Data Transmission:Low-latency relay to ground stations or direct-to-user terminals supports time-critical applications including disaster response and military targeting.
- Satellite Integration:Beyond-line-of-sight connectivity through geostationary or low-earth-orbit relays extends operational range for oceanic and polar missions.
Platform procurement concentrates in High Altitude Platforms; Semi-Autonomous Control is gaining share fastest as operator scarcity drives automation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denver-Aurora hosts the densest concentration of stratospheric payload engineering talent, anchored by national laboratories and defense contractor campuses that feed classified military programs and FAA certification pathways.
United States
Defense agencies in Colorado and Virginia drive procurement of synthetic aperture radar payloads for contested-environment ISR missions. FAA HAPS certification frameworks are maturing through the Denver-based Flight Standards District Office, reducing airworthiness uncertainty for commercial operators. Lockheed Martin's Skunk Works facilities in Palmdale, California, sustain classified contract pipelines for high-altitude platform integration.
United Kingdom
UK defense offices specify electro-optical systems as secondary sensors alongside primary radar architectures for NATO interoperability. The Ministry of Defence's Defence Science and Technology Laboratory in Porton Down coordinates payload testing for extreme-environment reliability. BAE Systems' facilities in Lancashire anchor domestic integration capabilities for stratospheric surveillance platforms.
China
MIIT-coordinated GB standards for near-space vehicle payloads create technical barriers that favor domestic suppliers for military and climate monitoring missions. The Beijing-Tianjin-Hebei corridor concentrates platform integrators seeking export-competitive positioning through state-funded research institutes. Shanghai's aerospace cluster advances solar-electric propulsion systems compatible with stratospheric loiter requirements.
Germany
EASA's emerging high-altitude platform framework under the EU Drone Strategy is establishing airworthiness criteria that diverge from FAA pathways, forcing dual-certification engineering. Bavaria's Munich-Augsburg corridor hosts payload specialists adapting to stringent documentation requirements for publicly funded climate missions. Airbus Defence and Space in Ottobrunn leverages satellite heritage for stratospheric communication relay development.
Israel
Defense procurement prioritizes miniaturized sensor fusion architectures for border surveillance and maritime emissions monitoring. The Israel Defense Forces accelerate adoption of semi-autonomous control systems that reduce operator burden in persistent loiter missions. Rafael Advanced Defense Systems and Elbit Systems in Haifa anchor a cluster specializing in GPS-denied navigation payloads for contested electromagnetic environments.
Global Stratospheric UAV Payload Technology Market Competitive Landscape
The competitive structure tilts toward vertically integrated defense primes with classified program access. Tiered specialization separates radar-native suppliers from electro-optical incumbents diversifying through sensor fusion architectures. Three archetypes dominate: legacy aerospace conglomerates with Skunk Works heritage, radar-electronics specialists leveraging semiconductor miniaturization, and platform-agnostic payload integrators serving fragmented civilian demand. Consolidation pressure intensifies through M&A targeting extreme-environment electronics capabilities and strategic partnerships bridging FAA-EASA regulatory divergence.
Among US-based defense primes, Lockheed Martin Corporation and Raytheon Technologies Corporation exemplify the vertically integrated archetype with sustained access to classified military pipelines. Boeing Company occupies a position spanning both integrated system contracting and unbundled payload supply through its Aurora Flight Sciences subsidiary. Thales Group represents the European counterweight, anchoring EASA-aligned certification capabilities for dual-use climate and security missions.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Raytheon Technologies Corporation |
| Boeing Company |
| BAE Systems |
| AeroVironment |
| Northrop Grumman |
| Thales Group |
| HAPSMobile |
| Airbus SE |
| Others |
Supply & Pricing Matrix
NATO ISR procurement consolidation into pooled framework agreements is compressing supplier margins and forcing payload manufacturers toward dual-use certification investments that recover cost through civilian climate monitoring contracts. This demand-side consolidation reshapes how component specialists price modular sensor architectures against integrated system primes.
Pricing Analysis
Value-based pricing anchored on mission-hours-delivered dominates stratospheric payload contracting, with electro-optical systems commanding premium-mid-economy pricing differentiation based on thermal management certification grade. Price differentiation separates ITAR-compliant military variants from export-restricted commercial tiers, with volume scale driving standardization in communication arrays. Pricing pressure stems from SAR miniaturization commoditizing resolution benchmarks, while defense agencies show least price sensitivity for GPS-denied navigation subsystems requiring celestial-referenced algorithms.
Supply Chain Analysis
Radiation-hardened electronics supply rests on United States, United Kingdom, and Israeli specialty semiconductor fabricators with captive cleanroom capacity for minus-seventy-degree-rated components. Raw material dependencies center on gallium nitride substrates for radar front-ends, indium phosphide for laser terminals, and aerospace-grade aluminum-lithium alloys for gimbal structures. Single-source vulnerability concentrates in X-band MMIC foundries, where distribution runs through defense-authorized distributors with cleared personnel requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stratospheric payload manufacturing operates under extreme-environment electronics talent scarcity that props pricing power for qualified suppliers. This supply-constrained structure favors incumbents with captive national laboratory relationships and burdens new entrants with extended certification timelines.
For Market Incumbents: Cement classified program access through Skunk Works heritage preservation and accelerated FAA HAPS certification pathways for commercial derivatives. Lockheed Martin's Palmdale facilities demonstrate how backward integration into ultra-long-endurance airframe-payload coupling defends against radar-native suppliers displacing electro-optical incumbents in NATO procurement. For New Entrants and Emerging Players: Enter via EU Green Deal maritime emissions monitoring mandates where EASA documentation requirements create first-mover windows for solar-electric platform specialists. India's rural broadband gaps and sub-Saharan Africa's cellular infrastructure deficits present the most penetrable white-space for communication relay payloads, with cellular backhaul service contracts offering the clearest go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with platform-agnostic payload integrators given EASA-FAA regulatory divergence creating dual-certification premiums. Long-term viability over the coming decade hinges on semi-autonomous control architecture capabilities that reduce operator burden, with acquisition targets clustering in extreme-environment electronics specialists. The signal to watch is ITU spectrum allocation decisions for military-civilian frequency sharing thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| SAR Miniaturization Investment | Compact X-band front-ends fragment electro-optical targeting dominance in contested environments. |
| Dual Certification Engineering | EASA-FAA parallel tracks open first-mover premiums for climate-mission payload suppliers. |
| Backward Integration into MMICs | Captive gallium nitride foundry capacity reduces single-source radar component vulnerability. |
| Semi-Autonomous Control Development | Automated sensor tasking commands premium margins where operator scarcity intensifies. |
| Hyperspectral-SAR Sensor Fusion | Converged spectral-radar architectures displace satellite constellations in precision agriculture. |
Research Methodology
Multi-period observation of FAA HAPS certification timelines, NATO procurement framework consolidations, and EASA emerging airworthiness criteria anchored the trend analysis, supplemented by interviews with payload engineering directors at defense primes, EASA certification specialists, and procurement officers at climate monitoring agencies. Secondary validation drew from ITU spectrum allocation filings, SEC 10-K aerospace segment disclosures, and EU Green Deal implementation progress reports. Bottom-up segment sizing triangulated against top-down defense budget appropriation analysis.
Segment-weighting across payload type, technology, end user, and deployment mode dimensions structured the analytical framework, with synthetic aperture radar and hyperspectral imaging growth rates derived from defense specification priority shifts and agricultural analyst adoption curves. CAGRs were computed from installed base projections and replacement cycle assumptions, incorporating FAA regulatory maturation pace and MIIT GB standard export friction as industry-specific forecast inputs across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ITU spectrum allocation deadlock or accelerated Chinese GB standard enforcement. Assumptions reflect current defense classification thresholds and civilian airworthiness documentation requirements, with military-civilian dual-use export control complexity and stratospheric systems engineering talent scarcity as primary revision triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Short-Range Delivery Drone Market
UAV
Toy Drones Market
UAV
Miniature Drone Market
UAV
Industrial Drones Market
UAV
Fuel Cell UAV Market
UAV
Solar Powered Drones Market
UAV
Drone Identification System Market
UAV
Home Security Drone Market
UAV
Airborne Digital Battlefield Market
UAV
Multirotor Drones Market
UAV
Electric Glider Market
UAV
FPV Drone Goggles Market
UAV
Europe Tethered Drone Market
UAV
Unmanned Combat Aerial Vehicle Market
UAV
Tethered Drones Market
UAV
Global Drone Services Market