
 North America Airborne ISR Market | 2026-2036
North America Airborne ISR Market Size, Share, and Industry Trends Forecast 2026-2036
North America Airborne ISR Market Intelligence
Multi-sensor fusion certification is unwinding legacy single-payload procurement patterns across defense aviation. Northrop Grumman Corporation leverages its integrated sensor suites to anchor naval aviation programs. Lockheed Martin Corporation dominates long-endurance manned ISR with its specialized airborne early warning platforms. BAE Systems plc sustains competitive positioning through in-house production of signals intelligence subsystems.
Airborne ISR encompasses intelligence, surveillance, and reconnaissance operations conducted from aerial platforms using sensor payloads operating across electro-optical, radar, and signals intelligence bands, typically at altitudes from 10,000 to 60,000 feet with dwell times exceeding 12 hours for persistent coverage. The primary purpose is generating actionable intelligence for military command, border enforcement, and disaster response through real-time data collection and cross-cueing between sensor modalities. UAV platforms lead procurement volume due to lower operating costs and reduced crew risk, while manned aircraft retain margin concentration in strategic command-and-control missions. Multi-sensor technology is displacing single-payload configurations as operators demand simultaneous full-motion video, synthetic aperture radar, and electronic intelligence from common airframes.
FAA regulations govern unmanned system airspace integration and beyond-visual-line-of-sight operations, while DoD standards mandate cyber-hardening and interoperability across joint force architectures. NIST frameworks influence encryption protocols for classified data transmission between airborne nodes and ground stations. Stakeholders must monitor evolving spectrum allocation decisions and counter-drone policy shifts that could redirect platform investment toward hardened, contested-environment designs.
Market Dynamics
Multi-sensor fusion requirements are compressing procurement timelines across defense aviation as operators demand simultaneous electro-optical, radar, and signals intelligence from single airframes. FAA airworthiness certification for unmanned systems is tightening faster than contractor development cycles can absorb, creating structural friction between fielding urgency and safety validation.
Growth Catalysts
- DoD Cyber-Hardening Mandates:Pentagon interoperability standards are forcing sensor subsystem upgrades across legacy fleets, generating retrofit demand for encrypted data links and hardened ground stations.
- Southwestern US Test Range Concentration:Arizona and New Mexico defense installations cluster training corridors and evaluation airspace, concentrating procurement decisions and accelerating platform validation cycles.
- Synthetic Aperture Radar Miniaturization:Reduced SWaP (size, weight, and power) radar payloads are enabling Group 4-5 UAVs to carry previously manned-platform-only capabilities.
Market Restraints
- Gallium Nitride Substrate Supply:Domestic production shortfalls for high-frequency radar components create input cost volatility and delivery uncertainty for active electronically scanned array manufacturers.
- FAA Beyond-Visual-Line-of-Sight Friction:Certificate of Waiver or Authorization processing delays for unmanned systems in civil airspace restrict commercial ISR expansion and dual-use technology crossovers.
- Manned Platform Substitution Threat:Long-endurance UAVs with satellite communications relay are compressing mission sets previously reserved for crewed airborne early warning aircraft.
Strategic Opportunities
- Canadian Arctic Surveillance Gap:NORAD modernization priorities are opening procurement channels for ice-hardened, extended-range platforms capable of operating above 70 degrees north latitude.
- AI-Enabled Sensor Cross-Cueing:Machine learning algorithms fusing electro-optical and electronic intelligence streams in real-time are reducing analyst workload and enabling single-operator ground stations.
- Indigenous Procurement Preferences:US Buy American provisions and Canadian Industrial and Technological Benefits policies are redirecting subsystem sourcing toward domestic manufacturing clusters.
Industry Challenges
- Airworthiness Certification Timeline Compression:FAA and DoD parallel certification tracks for unmanned systems require duplicate testing protocols, stretching engineering resources and delaying fielding schedules.
- Signals Intelligence Talent Scarcity:Specialized electromagnetic spectrum analysts and radar signature engineers command premium compensation, constraining program expansion for mid-tier contractors.
- Legacy Data Link Interoperability:Proprietary communication protocols from single-vendor platforms resist integration with joint force architectures, forcing expensive gateway development or fleet-wide replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Airborne ISR Market |
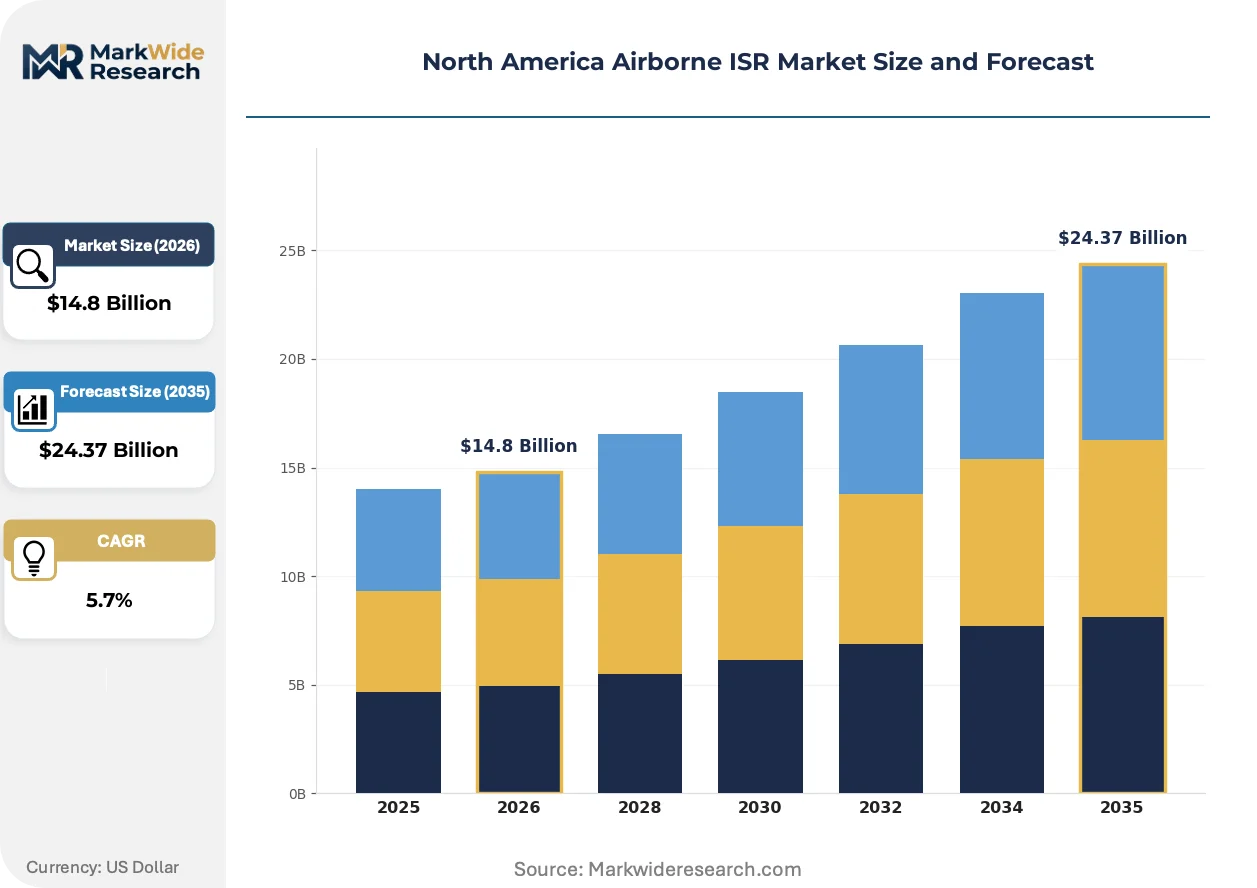
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: UAV, Manned Aircraft, Balloons, Satellites Technology: Electro-Optical, Radar, Signals Intelligence, Multi-Sensor End User: Military, Government, Homeland Security, Intelligence Agencies Deployment: On-Premise, Cloud, Hybrid, Mobile |
| Companies Covered | BAE Systems plc, Thales Group, Northrop Grumman Corporation, Airbus SE, General Dynamics, RTX Corporation, Boeing, Leidos Holdings, Inc., Lockheed Martin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Airborne ISR Market Strategic Shifts & Innovations
Open systems architecture mandates are dismantling proprietary sensor integration stacks across defense aviation. Modular payload standards are enabling faster technology refresh cycles and reducing vendor lock-in for platform operators.
Spectral imaging payloads spanning visible through short-wave infrared bands are fragmenting the electro-optical market into specialized wavelength-optimized configurations. Naval aviation programs are adopting multi-band systems for maritime domain awareness missions. This fragmentation is compressing single-sensor vendor margins while rewarding integrated suite providers with platform-level contracts.
FAA Part 89 Remote Identification requirements for unmanned systems are mandating broadcast transponder integration across all civil airspace operations. Defense contractors must now engineer military-grade platforms with dual-use identification systems or face restricted domestic flight testing. The southwestern United States test range operators are absorbing these compliance costs earliest due to dense civil-military airspace overlap.
Defense procurement offices are consolidating multi-year platform awards into single-source indefinite-delivery contracts with embedded technology refresh clauses. Traditional component-by-component bidding is yielding to architecture-level competitions where subsystem vendors compete within prime contractor supply chains. This pattern is most pronounced in US Navy and US Air Force ISR programs, where platform commonality drives lifecycle cost reduction mandates.
North America Airborne ISR Market Segmentation
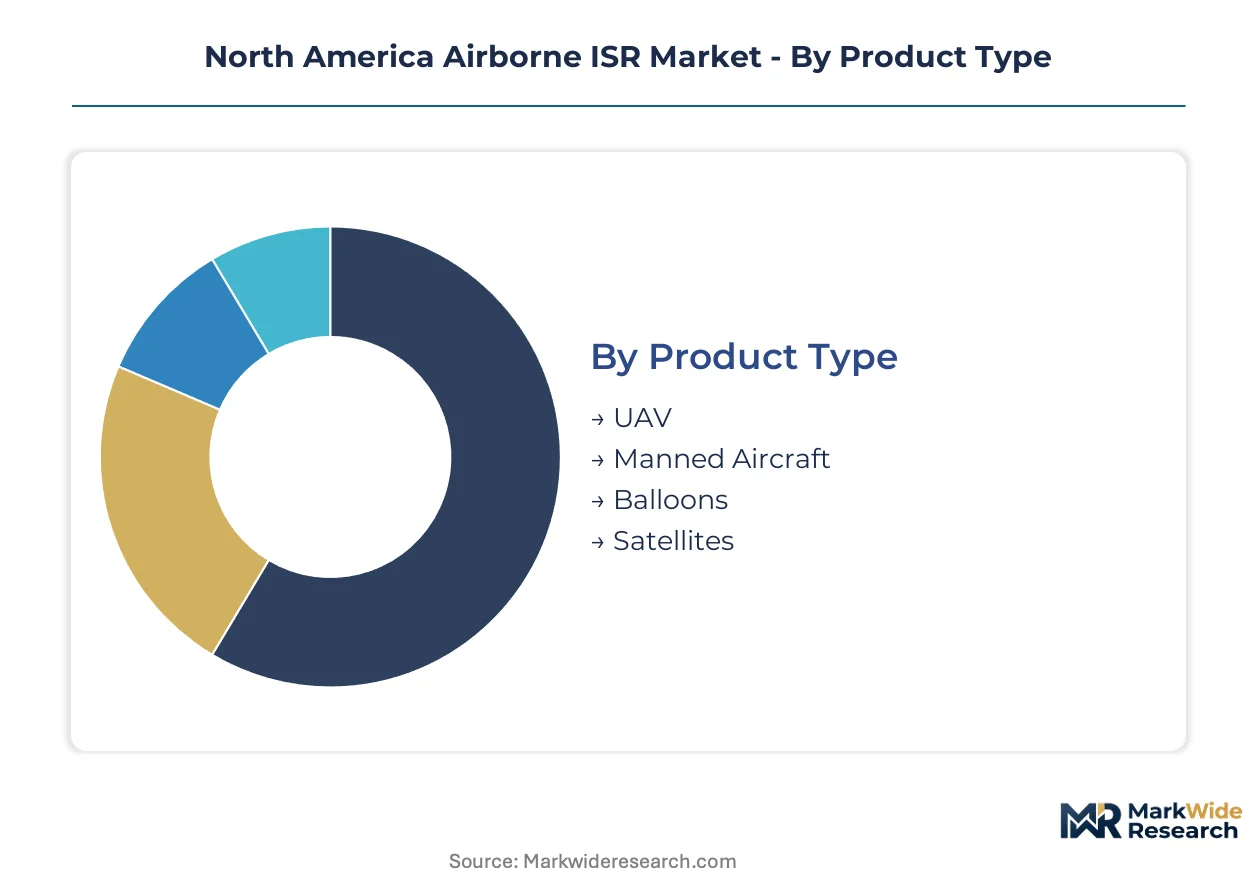
Segmentation reveals how FAA airworthiness classifications and DoD procurement tiers allocate investment across platform types and sensor configurations. Procurement officers weight endurance specifications against certification timelines when selecting across these categories.
Product Type:
FAA Part 107 and Part 89 regulations create divergent certification burdens across unmanned and manned platforms, directly shaping procurement economics.
- UAV:Group 4-5 unmanned systems dominate procurement volume through reduced operating costs and elimination of crew risk. Arizona and New Mexico test ranges concentrate validation activity for beyond-visual-line-of-sight operations, though Certificate of Waiver processing delays constrain commercial expansion.
- Manned Aircraft:Long-endurance platforms retain strategic command-and-control missions where human decision authority remains mandatory. Southwestern US training corridors sustain crewed platform evaluation, though satellite-relay UAVs compress traditional mission sets.
- Balloons:Stratospheric persistent platforms operate above controlled airspace, bypassing FAA integration requirements entirely.
- Satellites:Space-based assets provide coverage beyond atmospheric constraints, complementing rather than substituting for responsive airborne collection.
Established volume favors UAV; emerging adoption favors Balloons.
Technology:
Cost tiers separate legacy single-payload configurations from integrated multi-sensor suites demanding advanced data fusion architectures.
- Multi-Sensor:Simultaneous electro-optical, radar, and signals intelligence collection from common airframes is displacing single-payload procurement. Real-time cross-cueing algorithms reduce analyst workload and enable single-operator ground stations.
- Electro-Optical:Full-motion video and spectral imaging span visible through short-wave infrared bands. Naval aviation programs adopt multi-band variants for maritime domain awareness.
- Radar:Synthetic aperture radar miniaturization enables Group 4-5 UAV carriage of previously manned-platform-only capabilities.
- Signals Intelligence:Electronic intelligence subsystems require specialized electromagnetic spectrum analysts commanding premium compensation.
Procurement concentration sits with Multi-Sensor; capability gaps persist in Signals Intelligence talent pipelines.
End User:
Customer type determines classification thresholds and interoperability mandates across joint force architectures.
- Military:Pentagon cyber-hardening standards force sensor subsystem upgrades across legacy fleets, generating retrofit demand for encrypted data links.
- Homeland Security:Border enforcement applications concentrate in southwestern US corridors where civil-military airspace overlap demands dual-use identification systems.
- Government:Non-defense federal agencies face tighter FAA integration constraints than military operators.
- Intelligence Agencies:Specialized collection requirements drive classified program development outside standard procurement channels.
Military commands procurement volume; Homeland Security offers the steepest expansion trajectory as border technology modernization accelerates.
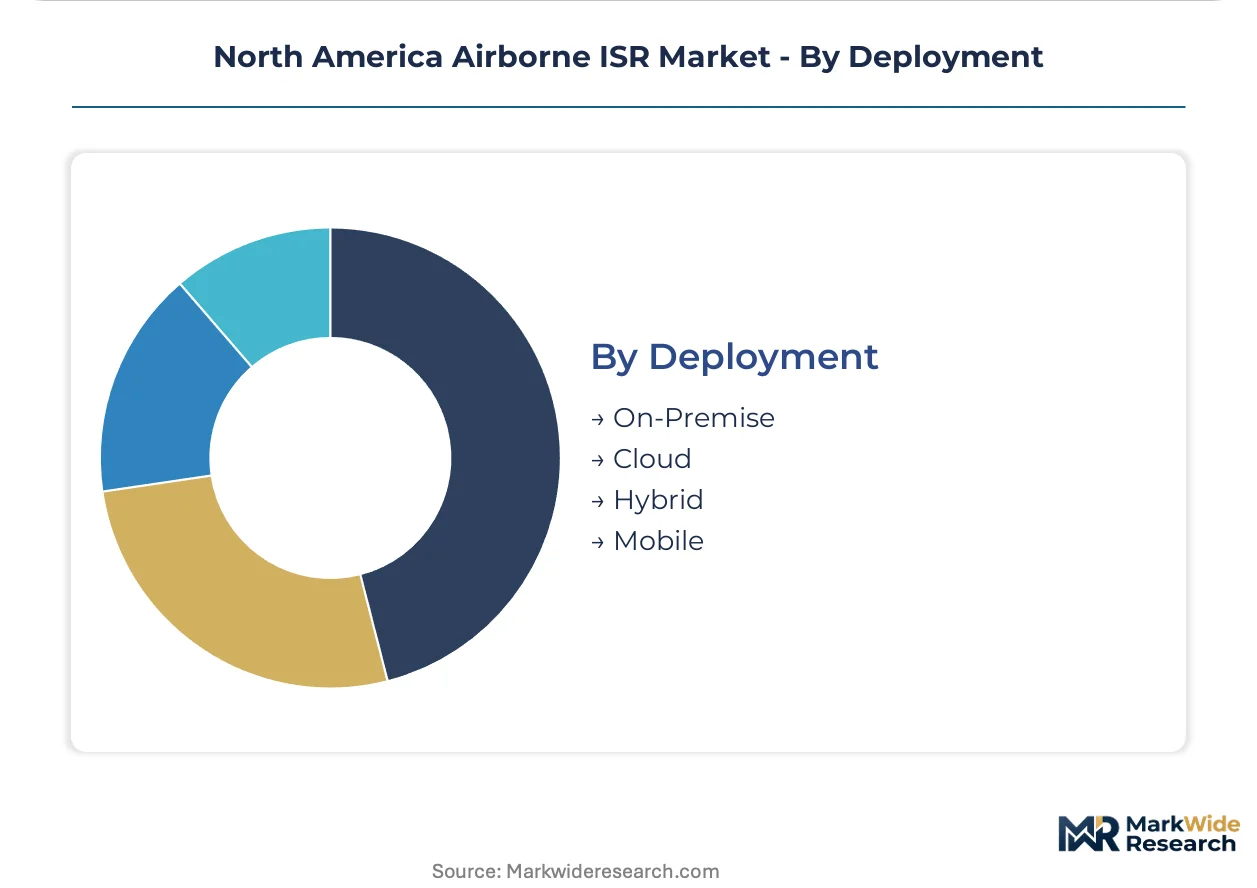
Deployment:
Maturity levels separate field-proven on-premise architectures from emerging cloud-native ground station concepts.
- On-Premise:Hardened ground stations with classified processing capability remain standard for military and intelligence operations.
- Hybrid:Split architectures route unclassified preprocessing to commercial cloud while retaining sensitive analysis on secure infrastructure.
- Cloud:Commercial cloud ground stations face NIST encryption protocol compliance for classified data transmission.
- Mobile:Forward-deployable ground stations enable expeditionary operations from austere locations.
On-premise infrastructure anchors current operations; hybrid architectures gain share fastest as operators balance security with processing scalability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada exports specialized signals intelligence subsystems to United States defense primes, while Mexico supplies precision-manufactured radar components to southwestern US test range operators. This cross-border trade flow shapes procurement patterns across the tri-national defense industrial base.
United States
Pentagon cyber-hardening mandates and NORAD modernization drive multi-sensor platform demand. FAA Part 89 Remote Identification requirements tighten unmanned system certification timelines. Arizona and New Mexico test ranges concentrate validation activity for beyond-visual-line-of-sight operations near major defense installations.
Canada
Arctic surveillance gaps and NORAD integration priorities create demand for ice-hardened, extended-range platforms. Canadian Industrial and Technological Benefits policies redirect subsystem sourcing toward domestic manufacturing clusters. Alberta and Ontario host signals intelligence subsystem production serving cross-border defense programs.
Mexico
Precision manufacturing clusters near the US border supply radar component substrates and electro-optical housing assemblies. Mexico's aerospace supplier base attracts tier-2 contracts from southwestern US primes. Baja California and Chihuahua concentrate maquiladora operations supporting Group 4-5 UAV airframe fabrication.
North America Airborne ISR Market Key Industry Players
Listed leaders compete with private specialists across platform integration and subsystem tiers. The vendor base stratifies between full-system primes and component-focused suppliers. Three archetypes dominate: integrated sensor suite providers, long-endurance manned platform specialists, and signals intelligence subsystem manufacturers. M&A activity concentrates on data fusion software assets, while strategic partnerships bridge FAA certification gaps for unmanned entrants.
Within the integrated sensor tier, Northrop Grumman Corporation and Lockheed Martin Corporation exemplify platform-level consolidation. BAE Systems plc occupies a position among European-heritage specialists competing for NORAD-related contracts. These three anchors represent divergent strategic postures: naval aviation program anchoring, long-endurance manned dominance, and in-house signals intelligence production.
| Leading Market Players |
|---|
| BAE Systems plc |
| Thales Group |
| Northrop Grumman Corporation |
| Airbus SE |
| General Dynamics |
| RTX Corporation |
| Boeing |
| Leidos Holdings, Inc. |
| Lockheed Martin Corporation |
| Others |
Cost & Logistics Intelligence
Scale economies in active electronically scanned array manufacturing concentrate pricing power among domestic GaN substrate producers, compressing margins for tier-2 radar integrators while elevating floor prices for hardened military-grade sensor suites. Southwestern US test range operators absorb these cost structures earliest due to concentrated demand for beyond-visual-line-of-sight validation.
Pricing Analysis
Multi-sensor fusion platforms command substantial premiums over legacy single-payload configurations, while prior-generation electro-optical systems face accelerating price erosion. Three-tier pricing structure across hardened military-grade, dual-use certified, and commercial-tier platforms separates procurement tiers by FAA certification level and DoD cyber-hardening compliance. Pricing pressure stems from gallium nitride substrate supply volatility and domestic production shortfalls. Intelligence agencies exhibit lowest price sensitivity due to classified program budgets, while commercial UAV operators face acute margin compression from Certificate of Waiver processing delays.
Supply Chain Analysis
Container availability constraints on transpacific lanes from Taiwanese semiconductor foundries and South Korean radar component suppliers inflate inbound logistics costs for southwestern US primes. Gallium nitride substrates, precision-machined electro-optical housings, and encrypted data link chipsets draw from concentrated Asian manufacturing clusters. Single-source vulnerability in high-frequency radar component supply creates structural risk for active electronically scanned array production timelines. Distribution runs through prime contractor supply chains with embedded technology refresh clauses rather than open component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electromagnetic spectrum analyst talent scarcity constrains program expansion across mid-tier contractors, making human capital retention and automated cross-cueing development decisive competitive differentiators. Platform operators must prioritize capability acquisition over hardware procurement in this constrained environment.
For Market Incumbents: Shield long-endurance manned platform margins by accelerating AI-enabled sensor cross-cueing integration that reduces crew complement requirements. Lockheed Martin Corporation and Northrop Grumman Corporation should deepen in-house GaN substrate production to escape gallium nitride supply volatility. FAA certification timeline compression threatens fielding schedules; incumbents must pre-position engineering resources for parallel airworthiness tracks. For New Entrants and Emerging Players: Differentiate on Arctic-hardened platform specialization for Canadian NORAD modernization channels, where ice-resistant extended-range capabilities face limited incumbent competition. The Canadian Industrial and Technological Benefits policy creates procurement preference for domestic manufacturing clusters. Target mobile ground station architectures for expeditionary operations, leveraging cloud-native preprocessing to bypass hardened infrastructure requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated sensor suite providers with embedded technology refresh clauses in indefinite-delivery contracts. Long-term viability across the projection horizon rests on data fusion software assets rather than airframe fabrication capacity. Acquisition target archetype: signals intelligence subsystem specialists with in-house electromagnetic spectrum analyst pipelines. Watch FAA spectrum allocation decisions as inflection indicator for contested-environment platform investment redirection.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Sensor Fusion Platform Integration | Northrop Grumman Corporation leverages integrated suites to anchor naval aviation program awards. |
| Arctic-Hardened Extended-Range Development | Canadian NORAD modernization opens procurement channels for ice-resistant platforms above 70 degrees north. |
| AI-Enabled Sensor Cross-Cueing Investment | Machine learning algorithms reduce analyst workload and enable single-operator ground station architectures. |
| GaN Substrate Backward Integration | Domestic production control mitigates active electronically scanned array input cost volatility. |
| Mobile Ground Station Cloud-Native Transition | Hybrid architectures balance NIST encryption compliance with commercial cloud processing scalability. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with Pentagon program officers, FAA certification engineers, prime contractor subsystem procurement leads, and southwestern US test range operations directors. Secondary validation drew from DoD budget justification documents, FAA airworthiness directive filings, NIST cybersecurity framework publications, and NORAD modernization strategy papers. Bottom-up platform deployment estimates triangulated against top-down defense procurement budget allocations.
Across the analysis window, the forecasting framework modeled platform type segmentation by FAA airworthiness classification, technology tier by sensor integration complexity, end user by classification threshold, and deployment architecture by security-hardening level. CAGRs were derived from procurement timeline compression rates and technology refresh cycle frequencies. Synthetic aperture radar miniaturization trajectories and cyber-hardening mandate compliance costs served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained defense budget authorization levels or fundamental FAA unmanned system integration policy shifts would require recalibration. Forecasts reflect documented assumptions regarding gallium nitride substrate supply normalization and electromagnetic spectrum analyst pipeline expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ISR
C5ISR Market
ISR
North America C5ISR Market
ISR
Active Phased Array Radar (APAR) Market
ISR
C6ISR Market
ISR
Australia C4ISR Market
ISR
Airborne ISR Market
ISR
Synthetic Aperture Radar (SAR) Market
ISR
Air Based C4ISR Market
ISR
United States C4ISR Market
ISR
IFF System Market
ISR
C4ISR Market
ISR
Eastern Europe C4ISR Market
ISR
Asia-Pacific C4ISR Market
ISR
Japan C4ISR Market
ISR
Infrared Suppression Systems Market
ISR
Intelligence Surveillance and Reconnaissance (ISR) Market