
 Airport Cargo Community Digital Collaboration Platforms Market | 2026-2036
Airport Cargo Community Digital Collaboration Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Cargo Community Digital Collaboration Platforms Market Insights
Platform licensing revenue is narrowing as vendors shift toward transaction-based and managed-service models. CHAMP Cargosystems leverages its heritage in airline messaging standards to anchor enterprise deployments across European hub airports. Kale Logistics Solutions competes through deep customs-technology integration, particularly in South Asian trade corridors. IBS Software differentiates via cloud-native cargo management suites that extend into passenger-to-cargo conversion workflows.
Airport cargo community digital collaboration platforms constitute software ecosystems that interconnect airlines, ground handlers, freight forwarders, customs brokers, and regulators through standardized data exchange protocols such as ONE Record and Cargo-IMP/Cargo-XML messaging. These platforms automate document interchange, shipment visibility, and billing reconciliation across fragmented multimodal supply chains. Cloud-based deployments lead adoption among mid-tier airports seeking lower capital burden, while hybrid architectures dominate at major hubs requiring localized control over sensitive customs data. Real-time tracking functionality commands premium positioning as shippers demand granular visibility comparable to parcel networks. Automated documentation segments show the fastest expansion, driven by customs authorities mandating pre-arrival data submission.
FAA modernization directives and EU Customs Union Code reforms shape platform requirements on opposite sides of the Atlantic, forcing vendors to maintain dual compliance architectures. ECHA's REACH-related supply chain disclosure rules and emerging carbon-border mechanisms add layers of data provenance that platforms must encode. Stakeholders must decide whether to consolidate around vendor-neutral community platforms or accept proprietary ecosystems locked to dominant airport operators.
Market Dynamics
Freight forwarders and ground handlers face mounting pressure to unify fragmented data exchanges as customs authorities mandate pre-arrival documentation and real-time shipment visibility. The shift from proprietary EDI protocols toward vendor-neutral standards like ONE Record is compressing platform switching costs and rewiring competitive positioning.
Growth Catalysts
- EU Customs Union Code Reforms:Pre-arrival data submission requirements force freight forwarders onto automated documentation platforms, eliminating paper-based clearance workflows at major European hubs.
- Carbon-border adjustment mechanisms:Emerging emissions-tracking mandates in the EU and UK require granular supply-chain provenance data that only integrated community platforms can encode across multimodal handoffs.
- Pharmaceutical cold-chain expansion:Temperature-sensitive biologics traffic through Frankfurt, Amsterdam, and Singapore is driving demand for real-time IoT integration within cargo community systems.
Market Restraints
- Legacy system entrenchment:Major hub airports in Germany and the Netherlands face sunk-cost barriers from decades-old Cargo-IMP messaging infrastructure that resists ONE Record migration.
- Handler consolidation risk:Ground handling markets at London Heathrow and Paris Charles de Gaulle concentrate among three operators, creating single-platform dependency and limiting vendor choice.
- Data-sovereignty fragmentation:China's cross-border data transfer rules and Russia's localization mandates force dual-architecture deployments that inflate engineering overhead.
Strategic Opportunities
- India's PLI-linked cargo corridors:Electronics and pharmaceutical manufacturing incentives under India's Production-Linked Incentive scheme are spawning greenfield airport digitization at Bangalore and Hyderabad.
- Passenger-to-cargo conversion workflows:Airlines retiring widebody fleets create demand for modular platform extensions that manage cabin-loading configurations and temporary freighter certifications.
- Saudi Arabia's logistics zone investments:King Salman International Airport's cargo city development offers first-mover positioning for cloud-native platform vendors absent legacy entanglements.
Industry Challenges
- ONE Record interoperability gaps:IATA's standard lacks mature implementation guidelines for customs-broker integration, forcing expensive bilateral API development between platforms and national single-window systems.
- Cybersecurity certification timelines:EU NIS2 directive and national critical-infrastructure designations impose 12-18 month approval cycles for platform updates, slowing feature deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Cargo Community Digital Collaboration Platforms Market |
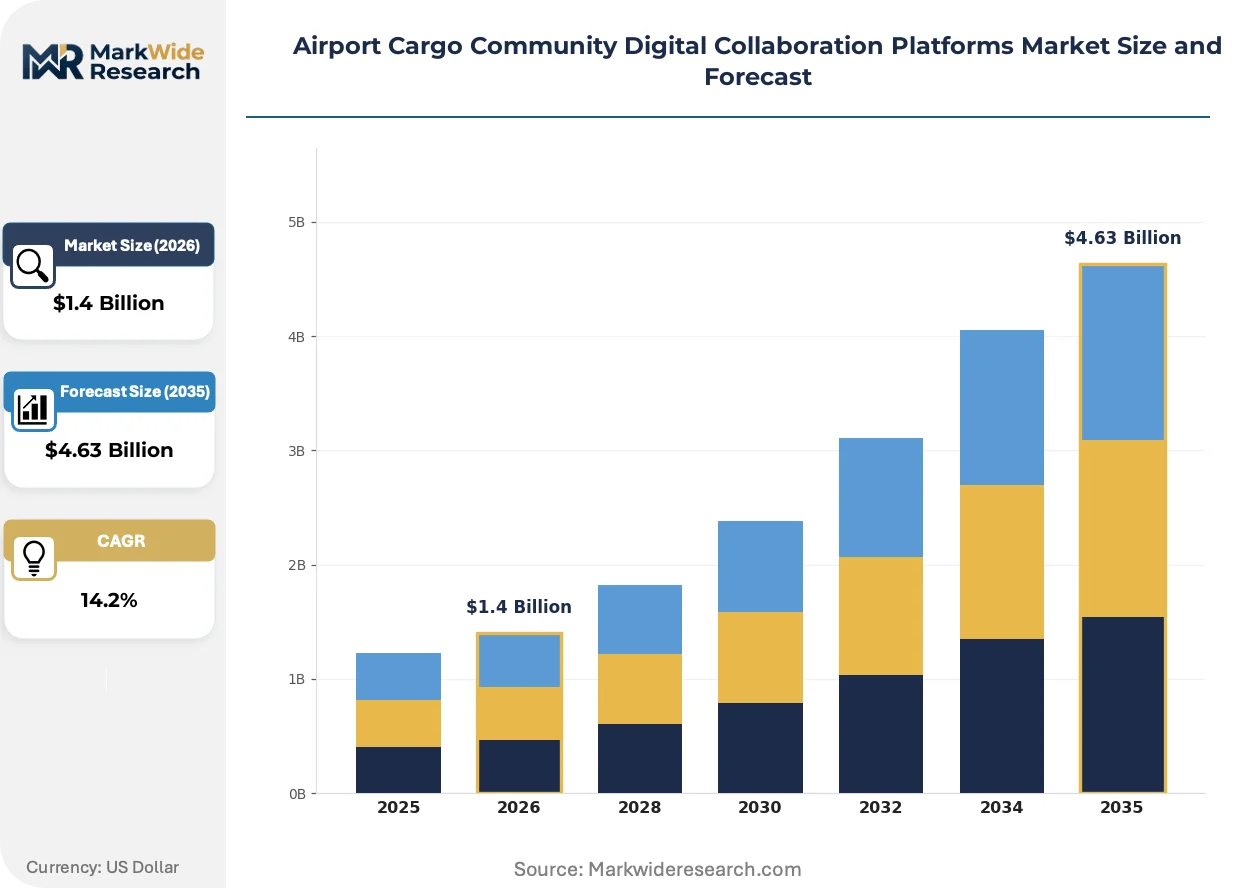
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $4.63 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Cloud-Based, On-Premises, Hybrid, SaaS Deployment Mode: Public Cloud, Private Cloud, Managed Services, Hosted Environment End User: Freight Forwarders, Customs Brokers, Ground Handlers, Air Cargo Carriers, Warehouse Operators Key Feature: Real-Time Tracking, Automated Documentation, Billing & Settlement, Data Analytics, Compliance Management |
| Companies Covered | CHAMP Cargosystems, Kale Logistics Solutions, IBS Software, Siemens Logistics, Wipro, Accelya, E2open, SITA, Descartes Systems Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Cargo Community Digital Collaboration Platforms Market Trends and Innovations
Platform architectures are pivoting from licensed software toward consumption-based revenue models as vendors embed deeper into transaction flows. This structural shift is compressing upfront procurement cycles while elongating vendor-customer relationships.
API-first cargo community platforms is migrating from monolithic enterprise suites toward modular microservices that freight forwarders compose through low-code interfaces. Mid-tier handlers in Southeast Asia adopt these stacks fastest, bypassing capital-intensive on-premise deployments. The technology is migrating from centralized control toward distributed orchestration that lets shippers swap visibility providers without re-integrating core messaging.
EU Green Deal digital reporting requirements now mandate machine-readable emissions documentation for all import categories above defined thresholds. This forces platform vendors to embed carbon calculators directly into booking workflows rather than bolting them on as reporting modules. Pharmaceutical and automotive verticals face the steepest compliance ramps, driving premium pricing for pre-certified platform configurations.
Shippers now unbundle visibility from execution, procuring real-time tracking through specialized SaaS layers while retaining legacy platforms for customs filing. This bifurcation pressures incumbent vendors to open data architectures or lose the analytics-rich tier of the customer base. The pattern is most pronounced among European fashion and electronics retailers managing seasonal volume spikes.
Airport Cargo Community Digital Collaboration Platforms Market Segmentation
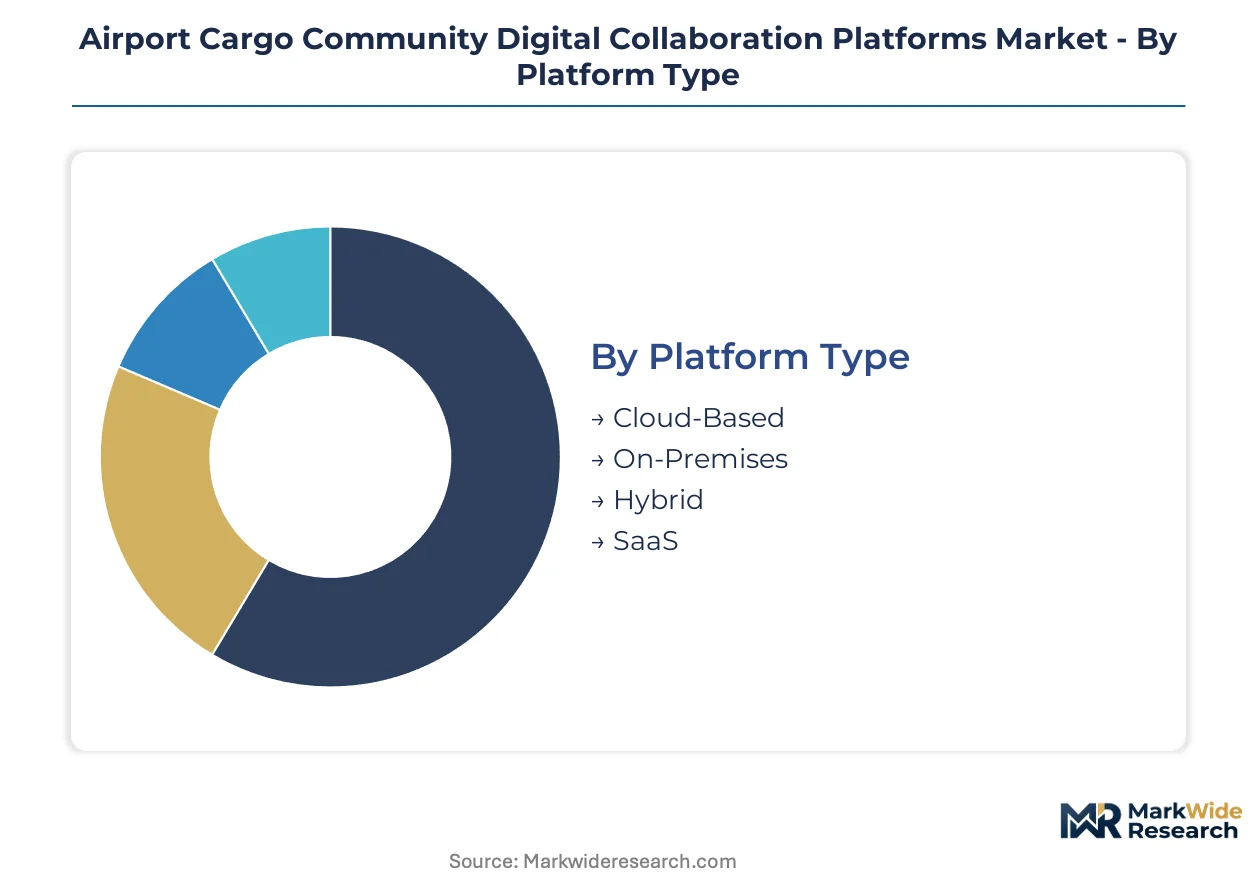
Platform segmentation in the airport cargo community market maps directly to procurement cycles and integration complexity. Deployment architecture choices determine capital commitment timelines, while feature prioritization separates compliance-driven buyers from efficiency-focused adopters.
Platform Type:
Cloud-based deployments turn over fastest among mid-tier airports seeking lower upfront burden, while hybrid architectures lock in longer refresh cycles at major hubs requiring localized customs data control.
- Cloud-Based:Fully managed infrastructure eliminates on-site server maintenance and accelerates onboarding for freight forwarders with distributed agent networks. Frankfurt Airport's cargo community leverages this model to synchronize handlers, carriers, and German customs authorities through centralized data exchange.
- Hybrid:Combines cloud scalability with on-premises sovereignty for sensitive customs processing, extending sales cycles but commanding premium positioning at regulated European hubs. Amsterdam Schiphol's dual-architecture deployment balances EU data residency rules with real-time carrier integration.
- On-Premises:Legacy installations persist at Asian hub airports with strict data localization mandates.
- SaaS:Consumption-based pricing compresses procurement approval timelines among Southeast Asian ground handlers.
On-premises dominates installed base. Cloud-based is where expansion concentrates.
Deployment Mode:
Cost tier separation shapes vendor selection, with public cloud targeting budget-constrained operators and managed services capturing buyers prioritizing operational outsourcing over capital ownership.
- Managed Services:Vendors assume full operational responsibility for platform uptime, security patching, and regulatory compliance updates, appealing to freight forwarders lacking dedicated IT infrastructure. Indian electronics exporters under the country's Production-Linked Incentive scheme favor this model to accelerate customs-technology deployment without captive engineering teams.
- Private Cloud:Dedicated tenant environments satisfy pharmaceutical cold-chain operators requiring audit-trail isolation for temperature-sensitive biologics traffic through Singapore and Amsterdam.
- Public Cloud:Shared infrastructure delivers lowest per-seat economics for small customs brokers.
- Hosted Environment:Single-tenant physical servers at vendor data centers bridge compliance and cost constraints.
Public cloud holds the broadest footprint. Managed services is climbing the fastest.
End User:
Application intensity varies sharply across stakeholder types, with freight forwarders driving transaction volume while ground handlers anchor platform stickiness through physical infrastructure integration.
- Freight Forwarders:Multi-stakeholder coordination requirements push these intermediaries toward API-first platforms that aggregate carrier schedules, customs filings, and ground handling slots into unified workflows. EU Customs Union Code pre-arrival data mandates force automated documentation adoption among forwarders operating through Rotterdam and Hamburg.
- Ground Handlers:Physical cargo terminal operations demand deep integration with warehouse management systems and equipment telematics, creating high switching costs once embedded. London Heathrow's concentrated handler market concentrates platform dependency among three dominant operators.
- Customs Brokers:Regulatory filing specialization drives demand for compliance-centric modules.
- Air Cargo Carriers:Fleet utilization optimization requires real-time capacity matching with forwarder bookings.
- Warehouse Operators:Yard management and cross-dock coordination needs expand with e-commerce parcel volumes.
Ground handlers dominate installed base. Freight forwarders is where expansion concentrates.
Key Feature:
Customer maturity separates basic visibility adopters from advanced users demanding predictive analytics and embedded compliance automation.
- Automated Documentation:Machine-readable customs filing and pre-arrival data submission eliminate paper-based clearance workflows, with EU Green Deal digital reporting requirements mandating emissions documentation integration. Pharmaceutical and automotive verticals face the steepest compliance ramps, driving premium pricing for pre-certified configurations.
- Real-Time Tracking:Granular shipment visibility comparable to parcel networks commands premium positioning as shippers unbundle tracking from execution, procuring specialized SaaS layers while retaining legacy platforms for customs filing.
- Data Analytics:Predictive demand forecasting and lane optimization attract large forwarders with sufficient data volume.
- Billing & Settlement:Multi-party invoice reconciliation reduces disputes in fragmented multimodal chains.
- Compliance Management:Embedded carbon calculators and REACH supply chain disclosure tools address emerging regulatory layers.
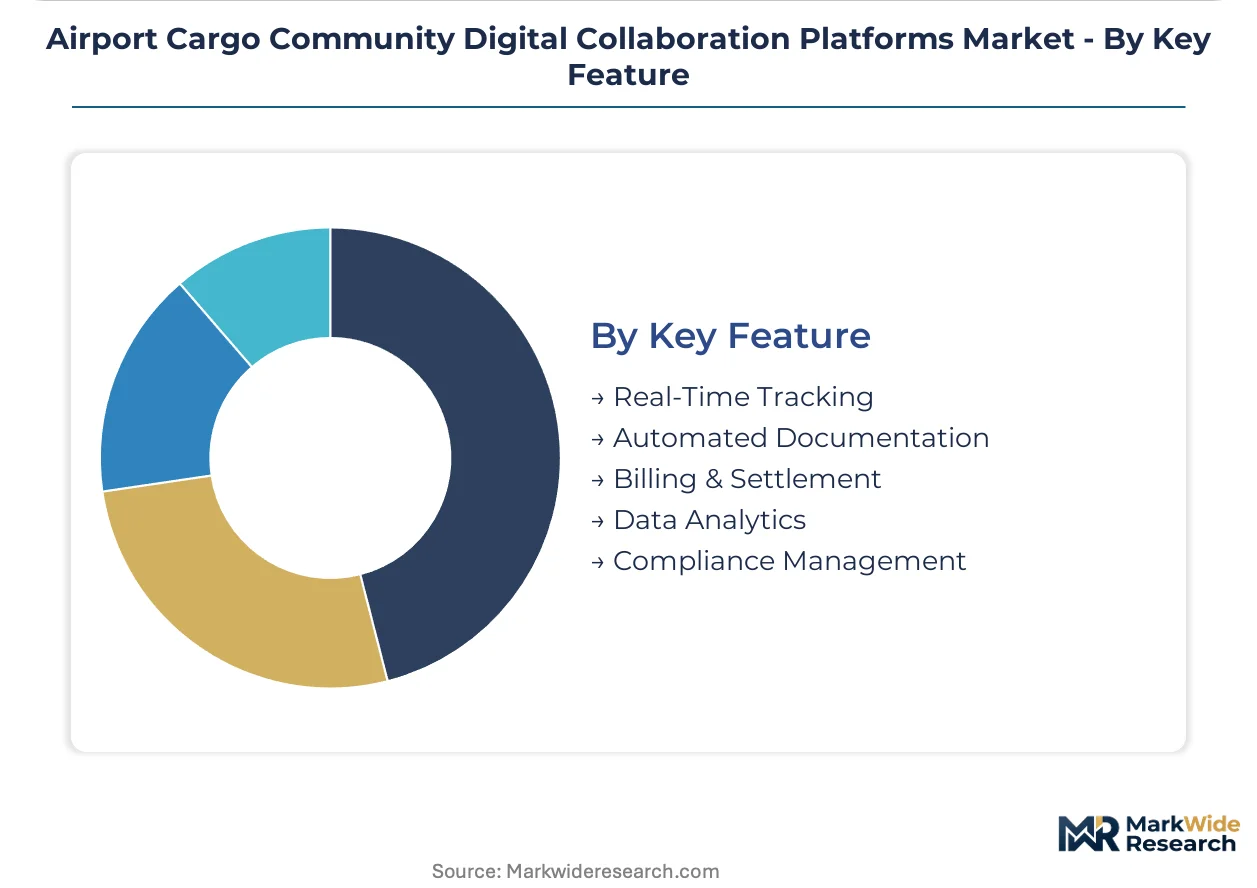
Real-time tracking dominates installed base. Automated documentation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes cargo community platforms through integrated hub coordination, while India adopts managed-service models to bypass legacy infrastructure. The United States prioritizes FAA-compliant security architectures. Saudi Arabia and Singapore represent greenfield deployment patterns absent entrenched systems.
Germany
Frankfurt Airport's cargo community pioneered digital handler-carrier-customs integration, creating reference architectures for EU-wide adoption. The EU Customs Union Code pre-arrival data mandates force freight forwarders onto automated documentation platforms. North Rhine-Westphalia's logistics corridor concentrates pharmaceutical cold-chain traffic requiring real-time IoT integration.
United States
FAA modernization directives reshape platform requirements for security screening and messaging standards at major hub airports. Customs and Border Protection's ACE system mandates machine-readable filing that community platforms must encode. Chicago O'Hare and Memphis cargo clusters anchor domestic adoption for e-commerce parcel networks.
India
Bangalore and Hyderabad airports deploy greenfield digitization under the Production-Linked Incentive scheme for electronics and pharmaceutical exports. DGFT's ICEGATE integration requirements push customs brokers toward API-first community platforms. Karnataka's aerospace and pharmaceutical manufacturing clusters generate concentrated demand for temperature-sensitive cargo tracking.
Saudi Arabia
King Salman International Airport's cargo city development offers first-mover positioning for cloud-native vendors without legacy entanglements. The General Authority of Civil Aviation's smart airport initiatives mandate unified data exchange between ground handlers and customs. Riyadh's logistics zone investments attract forwarders seeking GCC regional hub status.
Singapore
Changi Airport's pharmaceutical cold-chain expansion drives demand for real-time IoT integration within cargo community systems. The Infocomm Media Development Authority's digital trade corridor initiatives align with ONE Record standardization. The city-state's biologics traffic concentration commands premium platform configurations for temperature compliance.
Airport Cargo Community Digital Collaboration Platforms Market Competitive Landscape
Capability concentration sits with heritage messaging specialists; scale advantage sits with diversified IT conglomerates. The vendor base organizes around three strategic archetypes: airline-centric heritage platforms, customs-technology integrators, and cloud-native suite providers. Consolidation pressure intensifies as transaction-based revenue models displace perpetual licensing. Dominant competitive moves include strategic partnerships with airport authorities and modular portfolio extensions into adjacent cargo workflows.
Within the heritage platform tier, CHAMP Cargosystems and SITA occupy positions anchored in IATA messaging standards and airline industry lineage. Kale Logistics Solutions exemplifies the customs-technology integrator archetype, while IBS Software represents cloud-native suite providers extending into passenger-to-cargo conversion workflows. These three companies illustrate the competitive spectrum without exhausting the vendor landscape.
| Leading Market Players |
|---|
| CHAMP Cargosystems |
| Kale Logistics Solutions |
| IBS Software |
| Siemens Logistics |
| Wipro |
| Accelya |
| E2open |
| SITA |
| Descartes Systems Group |
| Others |
Pricing and Supply Chain Analysis
Frankfurt Airport's cargo corridor concentrates platform procurement among three dominant ground handlers, compressing contract negotiation leverage for freight forwarders while enabling tiered SaaS pricing that separates real-time tracking modules from basic customs filing tiers.
Pricing Analysis
Long-term managed service contracts anchor enterprise deployments at major European hubs, while consumption-based SaaS tiers capture mid-tier airports and Southeast Asian forwarders seeking lower capital commitment. Price differentiation rests on integration depth with customs single-window systems and IoT cold-chain certification tiers. Cost compression in the standard tier intensifies as open-source API frameworks reduce switching barriers. Small customs brokers exhibit highest price sensitivity, whereas pharmaceutical forwarders prioritize compliance-certified configurations over per-seat economics.
Supply Chain Analysis
Extended payment terms from European airport authorities to platform vendors now stretch 90-120 days, forcing supply-chain finance facilities to bridge working capital gaps. Engineering talent concentrates in Germany, India, and Singapore, where CHAMP Cargosystems, Kale Logistics Solutions, and IBS Software maintain development centers. Cloud infrastructure dependencies draw from hyperscaler regions in Ireland, Frankfurt, and Mumbai. Single-source vulnerability sits with IATA ONE Record standard implementation guidelines, which remain immature for customs-broker integration. Distribution runs through direct enterprise sales at hub airports and channel partnerships with regional system integrators in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward freight forwarders as handler consolidation at London Heathrow and Paris Charles de Gaulle limits vendor choice, fragmenting platform stickiness and opening negotiation leverage for multi-stakeholder coordination buyers.
For Market Incumbents: Build switching-cost moats through deeper warehouse management system integration and embedded carbon calculators that encode EU Green Deal compliance directly into booking workflows. Threats from API-first microservices vendors compress margins in the visibility tier. Capacity addition in Saudi Arabia's greenfield King Salman International Airport offers geographic diversification from entrenched European competition. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-linked cargo corridors at Bangalore and Hyderabad, where greenfield digitization bypasses legacy Cargo-IMP entrenchment. The most penetrable segment comprises mid-tier Southeast Asian ground handlers adopting low-code composable stacks. Go-to-market angle: consumption-based pricing with rapid onboarding timelines undercutting perpetual license incumbents. For Investors and Strategic Acquirers: Carve-out targets emerge from airline IT divisions and logistics conglomerates seeking to monetize non-core cargo technology assets. Long-term viability favors vendors with customs-technology integration depth and cloud-native architectures over heritage messaging specialists. Signal to watch: EU NIS2 cybersecurity certification timelines, which impose 12-18 month approval cycles and favor established vendors with compliance infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | ONE Record standardization with German customs authorities reduces bilateral API development costs. |
| Strategic Partnership | Frankfurt Airport's cargo community reference architecture accelerates EU-wide adoption timelines. |
| Product Launch | Embedded carbon calculators address EU Green Deal machine-readable emissions mandates. |
| Geographic Expansion | Saudi Arabia's King Salman International offers cloud-native deployment without legacy entanglement. |
| Acquisition of Specialist Firm | Customs-technology integrators deepen moats against API-first microservices competitors. |
Research Methodology
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings in this study. Stakeholder consultations spanned cargo community platform vendors, freight forwarder operations directors, ground handler IT managers, customs broker compliance leads, and airport authority procurement officers. Secondary sources included IATA ONE Record implementation guidelines, EU Customs Union Code regulatory texts, FAA modernization directives, and SEC filings from publicly traded logistics technology providers. Bottom-up segment sizing and top-down market triangulation were reconciled across deployment architecture, end-user category, and key feature dimensions.
Calibration against historical adoption curves at Frankfurt, Amsterdam Schiphol, and Singapore Changi informed growth trajectory assumptions across the projection horizon. Segmentation modeling incorporated platform type, deployment mode, end-user stakeholder, and key feature prioritization, with pharmaceutical cold-chain and automated documentation verticals receiving distinct treatment. CAGRs were derived from logistic diffusion curves fitted to greenfield digitization patterns and legacy migration timelines. Forecast inputs included EU NIS2 compliance timelines, India's PLI scheme cargo corridor investments, and Saudi Arabia's logistics zone development pace.
Stress conditions across regulatory enforcement intensity, cloud infrastructure cost inflation, and ONE Record interoperability gaps were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about customs mandate implementation schedules and handler market concentration stability. Macroeconomic contraction, accelerated data sovereignty fragmentation, or breakthrough distributed-ledger adoption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Airport Information Display System Market
Airport Technologies
Bird Detection System for Airports Market
Airport Technologies
Asia-Pacific Airport Ground Handling Systems Market
Airport Technologies
Airport Airside Service Market
Airport Technologies
Airport Interactive Kiosk Market
Airport Technologies
America Airport Ground Handling Systems Market
Airport Technologies
Smart Airport 3.0 Market
Airport Technologies
Aviation Beacons Technology Market
Airport Technologies
Smart Airport Market
Airport Technologies
Air Traffic Smart Tower Solutions Market
Airport Technologies
Airport RFID System Market
Airport Technologies
Middle-East and Africa Smart Airport Market
Airport Technologies
Smart Airport 2.0 Market
Airport Technologies
Middle-East and Africa Airport Baggage Handling Systems Market
Airport Technologies
Global Airport Baggage Handling System Market
Airport Technologies
Airport Runway Foreign Object Debris (FOD) Detection Systems Market