
 Air Freight Software Market | 2026-2036
Air Freight Software Market Size, Share, and Industry Trends Forecast 2026-2036
Air Freight Software Market Analysis
Modular unbundling of freight forwarding suites is repositioning buyer procurement patterns across the air cargo technology stack. The Descartes Systems Group leverages its customs-compliance modules to anchor North American carrier relationships. CargoWise sustains dominance in enterprise forwarding through deep workflow integration. Freightos competes on rate transparency, occupying the digital spot-market niche with real-time pricing engines.
Air freight software encompasses digital platforms that manage cargo booking, routing, documentation, and tracking across aviation logistics networks, typically integrating with airline operational databases and customs systems through standardized messaging protocols such as Cargo-IMP or ONE Record. These systems automate shipment lifecycle management from quotation through proof-of-delivery, reducing manual data entry and accelerating customs clearance for time-sensitive freight. Cloud-based deployment models now lead adoption among mid-tier forwarders seeking lower capital commitment and faster implementation cycles. Track & Trace functionality represents the fastest-expanding segment as pharmaceutical and perishable shippers mandate real-time visibility. On-premises installations retain share among flag carriers with stringent data-sovereignty requirements.
The EU's F-Gas Regulation and EASA airworthiness directives are mandating emissions documentation and sustainable aviation fuel traceability, directly shaping software procurement specifications for European operators. The US FAA and CBP enforce security filing deadlines and advance screening protocols that demand automated documentation workflows, tightening compliance windows for cross-border air freight. Stakeholders must weigh cloud migration timelines against evolving customs-data localization rules across multiple jurisdictions.
Market Dynamics
Pharmaceutical cold-chain mandates and emissions compliance obligations are forcing air freight software vendors to embed specialized tracking modules directly into core platforms, compressing implementation timelines from years to months.
Growth Catalysts
- EU F-Gas Regulation:Mandatory emissions documentation for fluorinated gases is driving carriers to adopt integrated carbon-tracking software across European routes.
- Perishable logistics:Temperature-sensitive pharmaceutical shipments now require real-time monitoring, expanding demand for sensor-integrated freight platforms.
- Cloud migration:Mid-tier forwarders are abandoning on-premise installations for SaaS deployment models, accelerating vendor market penetration.
Market Restraints
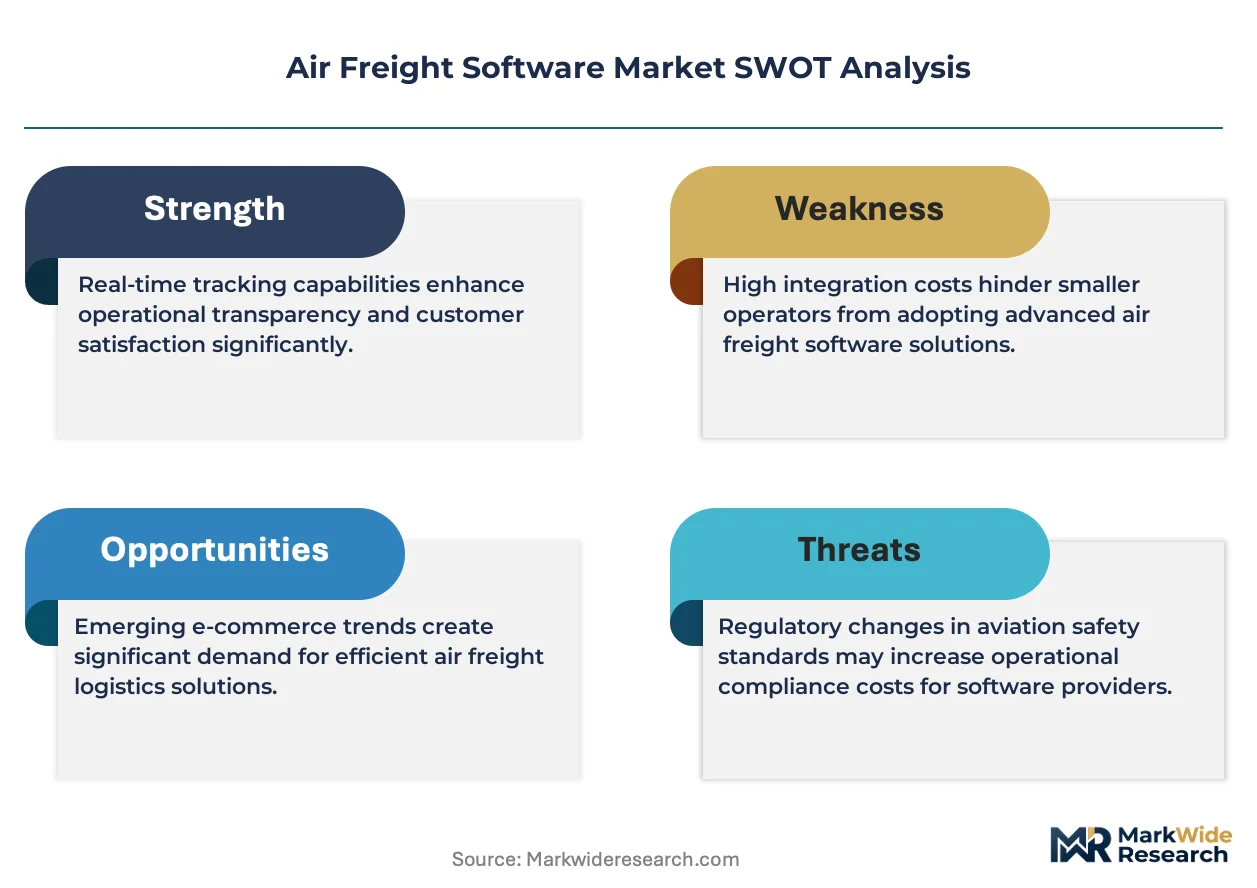
- Data sovereignty requirements:Flag carriers in Germany and France face jurisdictional restrictions that block full cloud migration, fragmenting vendor addressable markets.
- Legacy system entrenchment:Decades-old Cargo-IMP messaging infrastructure creates technical debt that slows API-based integration adoption.
- Skill scarcity:Shortages of developers fluent in both aviation EDI standards and modern cloud architecture inflate implementation costs.
Strategic Opportunities
- Sustainable aviation fuel traceability:Emerging EASA mandates for SAF documentation create white space for blockchain-anchored provenance modules.
- India pharmaceutical exports:Cold-chain software penetration remains below 15% among Indian freight forwarders serving temperature-controlled drug shipments.
- ONE Record standardization:IATA's data-sharing protocol convergence enables API-first platforms to displace traditional EDI-dependent vendors.
Industry Challenges
- Multi-jurisdiction compliance:Forwarders must simultaneously satisfy US CBP security filings, EU customs-data localization, and EASA airworthiness directives.
- Integration complexity:Connecting cloud platforms to airline operational databases requires bespoke middleware that extends deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Freight Software Market |
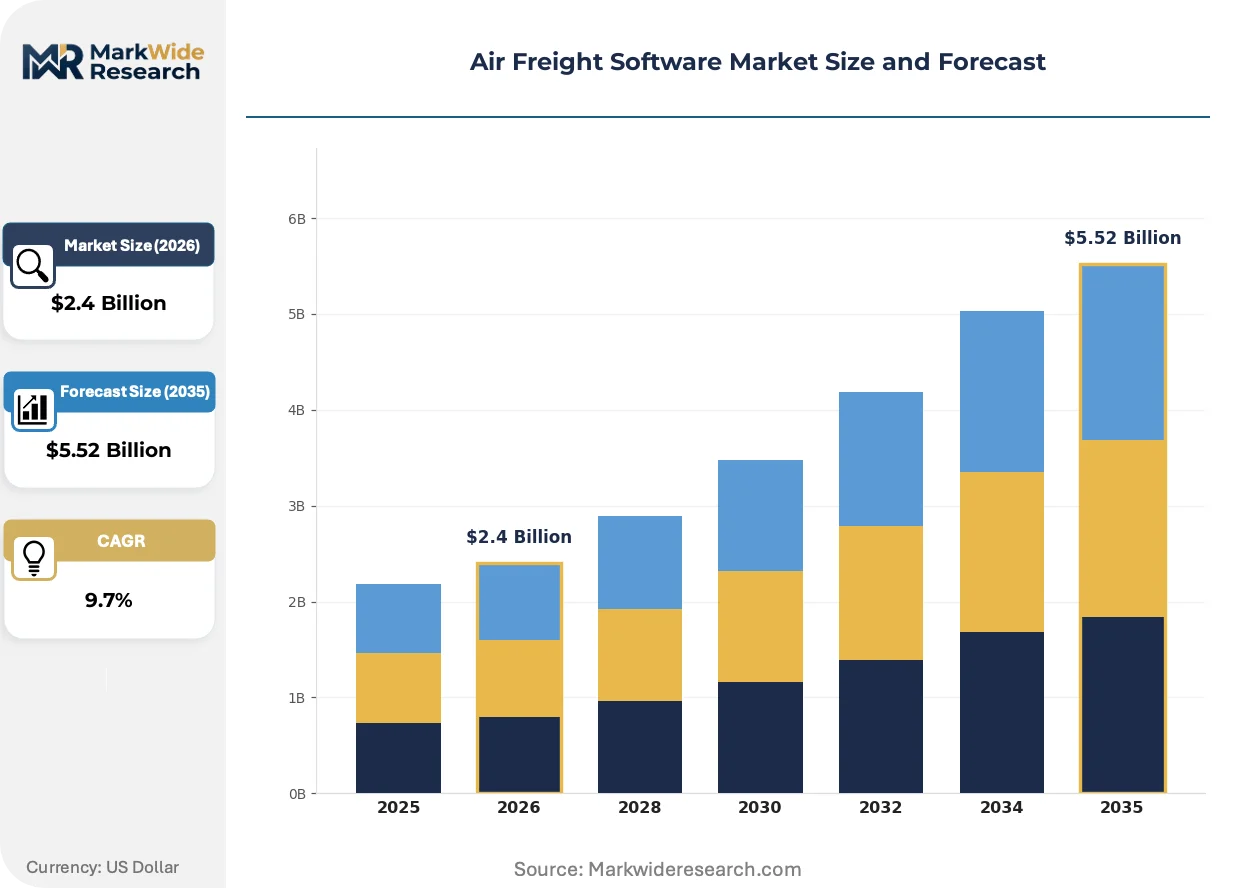
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.52 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Freight Forwarding, Track & Trace, Fleet Management, Cargo Management Deployment Model: Cloud-Based, On-Premises, Hybrid, SaaS End User: Logistics Companies, Airlines, Freight Carriers, Third-Party Providers Functionality: Cost Estimation, Shipment Tracking, Documentation Automation, Reporting Tools |
| Companies Covered | Champ Cargosystems, Freight Pop, Freightdata 2000, IBS, Inform Software, Magaya, The Descartes Systems Group, CargoWise, Freightos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Freight Software Market Emerging Trajectories
Real-time visibility infrastructure is becoming the primary battleground for vendor differentiation, with sensor networks and predictive analytics converging to compress dispute resolution timelines and insurance claim cycles.
API-first architecture is overtaking traditional EDI messaging as the dominant integration protocol for freight platforms. Pharmaceutical shippers in Germany and the Netherlands are demanding sub-minute latency for temperature alerts. This shift is compressing competitive moats around legacy vendors dependent on Cargo-IMP infrastructure.
REACH chemical safety documentation and the EU Green Deal's carbon-border adjustment mechanisms are forcing freight software to incorporate automated emissions calculators. European operators now face dual reporting obligations to EASA and national customs authorities. Forwarders serving Germany's chemical exporters are responding by procuring platforms with pre-built regulatory templates.
Subscription-based pricing models are displacing perpetual license structures among mid-market forwarders. Buyers now prioritize operational expenditure predictability over capital ownership, particularly in the Netherlands and Belgium. This preference shift is most visible among perishable specialists serving Rotterdam's flower and food export corridors.
Air Freight Software Market Segmentation
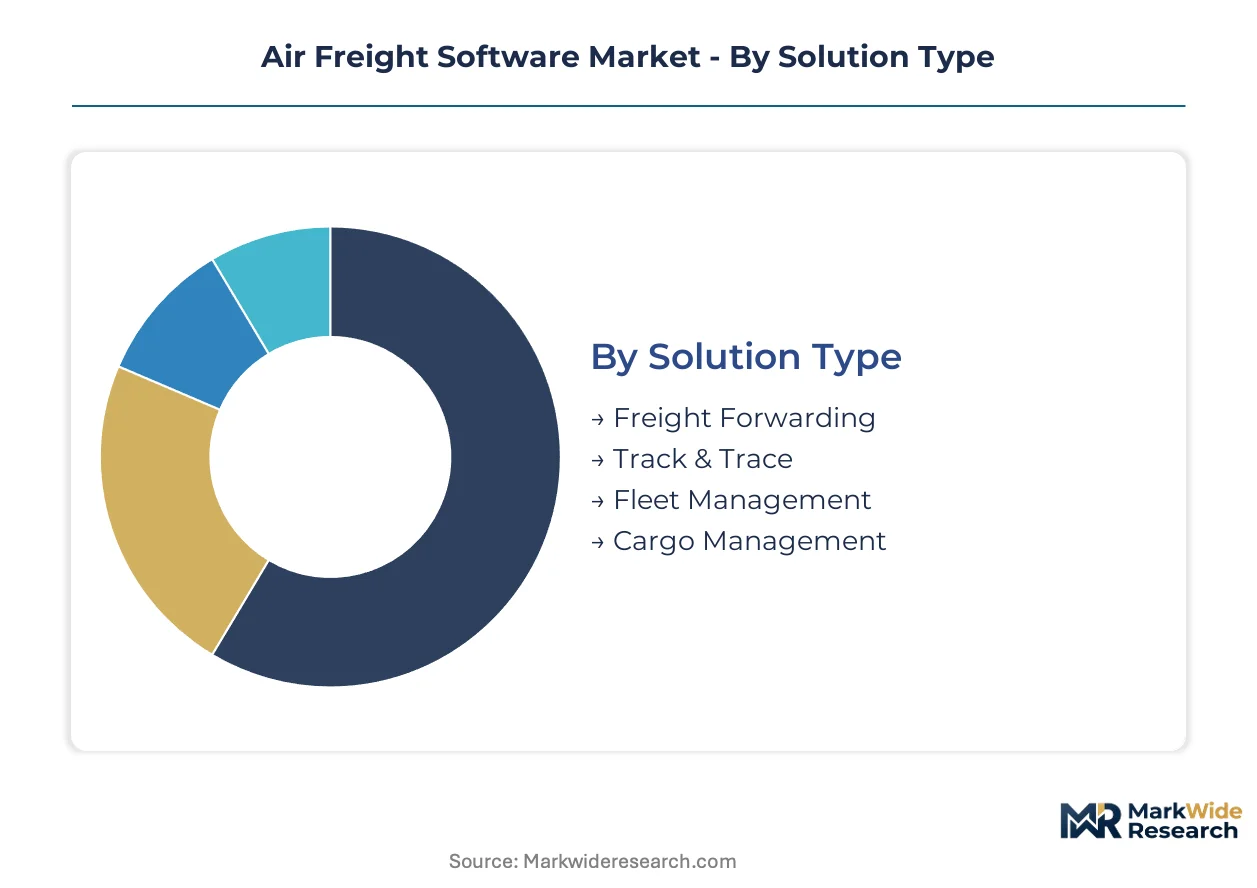
Segmentation in air freight software reveals how procurement priorities diverge across operational scale and regulatory exposure. Buyers select modules based on whether they manage owned fleets or broker third-party capacity, and whether their cargo faces temperature mandates or standard handling protocols.
Solution Type:
Customization intensity varies sharply across this category, with configurable workflow engines commanding premium pricing against standardized booking portals.
- Freight Forwarding:Comprehensive platforms automating quotation, booking, and customs documentation through multi-carrier aggregation. Demand concentrates among mid-tier forwarders in Germany and the Netherlands seeking to consolidate fragmented carrier relationships under single interfaces, pressured by EU F-Gas Regulation compliance deadlines.
- Track & Trace:Real-time visibility modules integrating IoT sensors, GPS telemetry, and predictive arrival algorithms. Pharmaceutical shippers in Frankfurt and Leipzig mandate sub-minute latency for temperature excursions, driving fastest adoption among cold-chain specialists serving perishable exports.
- Fleet Management:Aircraft utilization and maintenance scheduling systems for owned or wet-leased capacity.
- Cargo Management:Weight-and-balance optimization, load planning, and ULD tracking for airline ground operations.
Leading the category by volume: Freight Forwarding. Growing fastest: Track & Trace.
Deployment Model:
Capital commitment thresholds segment buyers, with opex-predictable SaaS contracts displacing perpetual licenses among mid-market operators.
- Cloud-Based:Fully hosted infrastructure with automatic updates and elastic compute scaling. Mid-tier forwarders in Belgium and the Netherlands prioritize operational expenditure predictability, abandoning on-premise installations to accelerate implementation cycles and reduce IT headcount.
- On-Premises:Local server installations with direct database control and customizable security layers. Flag carriers in Germany and France face data-sovereignty restrictions that block full cloud migration, preserving addressable market for legacy deployment specialists.
- Hybrid:Split architectures keeping sensitive customs data on-premise while routing commercial functions to cloud.
- SaaS:Subscription-native pricing with tiered feature access and usage-based scaling.
Cloud-Based captures the largest installed base. SaaS demonstrates the steepest expansion trajectory.
End User:
Control over physical assets versus brokered capacity determines functional requirements and integration complexity.
- Logistics Companies:Third-party forwarders coordinating multi-modal shipments across airline networks. Demand clusters in Rotterdam's perishable export corridors, where subscription pricing models displace capital ownership for flower and food specialists.
- Airlines:Flag and cargo carriers requiring direct operational system integration with flight planning and maintenance modules.
- Freight Carriers:Dedicated cargo operators managing owned freighter fleets and ACMI arrangements.
- Third-Party Providers:Niche handlers offering ground services, customs brokerage, or specialized packaging.
Logistics Companies lead procurement volume. Airlines show strongest pricing inelasticity for mission-critical modules.
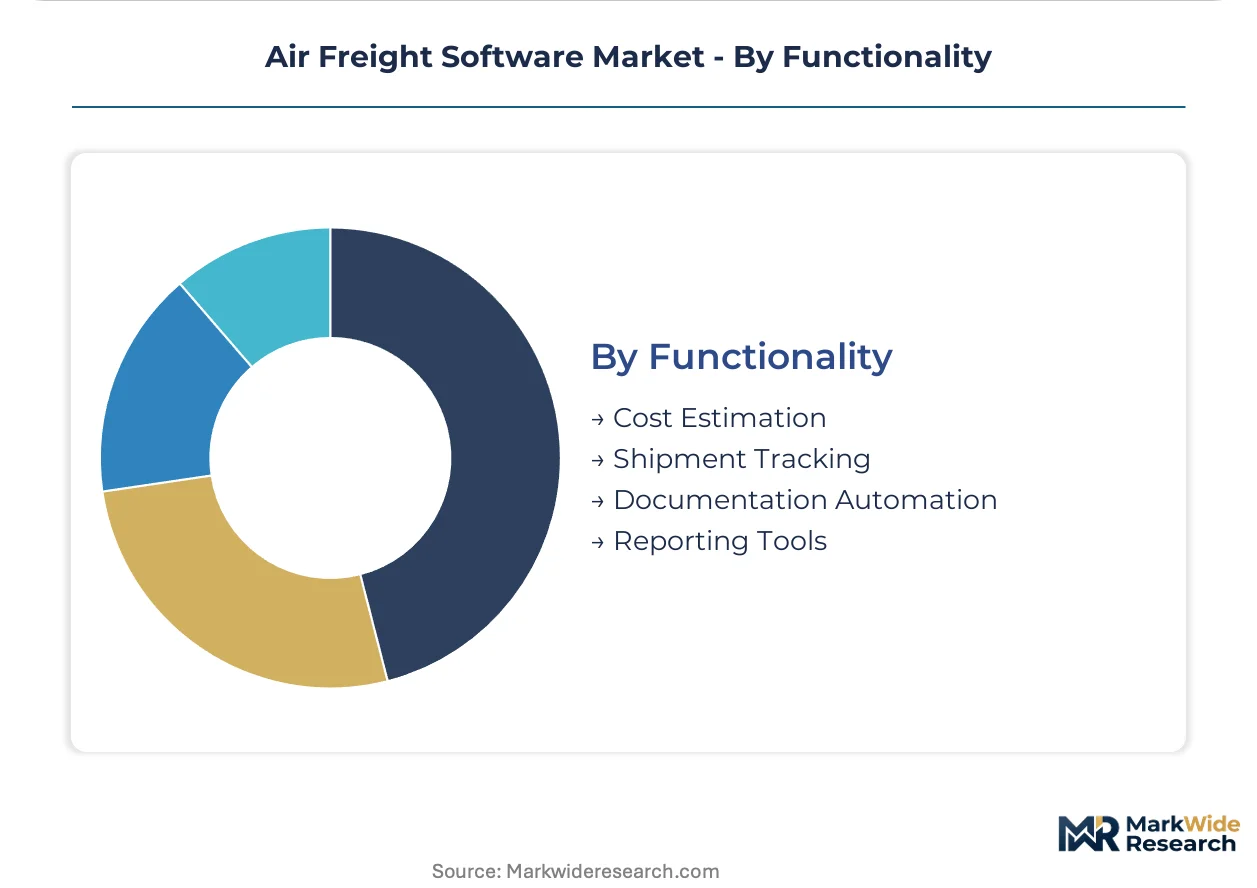
Functionality:
Regulatory automation features command premium positioning against operational efficiency tools.
- Cost Estimation:Dynamic pricing engines aggregating carrier rates, fuel surcharges, and customs fees. Digital spot-market platforms compete on transparency, with real-time quotation demand rising among small forwarders lacking direct airline contracts.
- Shipment Tracking:Multi-source event consolidation from airline EDI, GPS, and sensor feeds. Pharmaceutical cold-chain mandates in Germany accelerate sensor-integrated platform adoption, compressing implementation timelines from years to months.
- Documentation Automation:Customs filing, security screening, and certificate generation workflows.
- Reporting Tools:Emissions calculators, SLA dashboards, and audit trails for regulatory submission.
Documentation Automation leads by deployment frequency. Shipment Tracking climbs fastest on cold-chain investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software production concentrates in North American and European technology hubs, while consumption clusters around major air cargo gateways in Germany, the United States, and the Netherlands where pharmaceutical and perishable volumes drive platform procurement.
Germany
Frankfurt and Leipzig anchor Europe's densest air cargo hub network, generating concentrated demand for emissions-tracking and cold-chain modules. The EU F-Gas Regulation mandates fluorinated gas documentation, forcing carriers to integrate carbon calculators into core platforms. Bavarian forwarders serving chemical exporters now prioritize pre-built regulatory templates.
United States
FAA security filing deadlines and CBP advance screening protocols compress compliance windows for cross-border freight. Chicago and Memphis distribution clusters drive subscription SaaS adoption among mid-tier forwarders seeking operational expenditure predictability. Cloud migration accelerates despite ongoing data-localization tensions.
Netherlands
Rotterdam's perishable export corridors—flower, food, and pharmaceutical—generate specialized demand for sensor-integrated Track & Trace platforms. Dutch forwarders abandoned perpetual licenses fastest, prioritizing subscription models with tiered feature access. Amsterdam's logistics technology cluster incubates API-first integration specialists.
India
Pharmaceutical cold-chain software penetration remains below fifteen percent among freight forwarders serving temperature-controlled drug shipments. DGFT export documentation requirements and CDSCO quality mandates create compliance complexity. Mumbai and Hyderabad air cargo terminals see accelerating sensor-platform deployments.
United Kingdom
Post-Brexit customs-data localization rules fragment cloud migration timelines for flag carriers. London Heathrow's cargo handlers demand hybrid architectures keeping sensitive customs data on-premise while routing commercial functions to cloud. UK forwarders face dual reporting obligations to national customs and EU transit authorities.
Air Freight Software Market Vendor Landscape
The competitive structure tilts toward modular platform specialists over monolithic suite vendors. Tier-one providers anchor enterprise relationships through deep workflow integration, while mid-market SaaS vendors capture share via rapid deployment cycles. Two dominant competitive moves define positioning: API-first architecture migration displacing legacy EDI infrastructure, and vertical specialization into pharmaceutical cold-chain and emissions compliance modules.
Within the customs-compliance archetype, The Descartes Systems Group represents North American carrier relationship anchoring. CargoWise exemplifies enterprise forwarding dominance through workflow integration depth. Freightos occupies the digital spot-market niche, competing on rate transparency with real-time pricing engines.
| Leading Market Players |
|---|
| Champ Cargosystems |
| Freight Pop |
| Freightdata 2000 |
| IBS |
| Inform Software |
| Magaya |
| The Descartes Systems Group |
| CargoWise |
| Freightos |
| Others |
Supply Flow & Price Mechanics
Mid-tier freight forwarders in the Netherlands and Belgium cluster procurement decisions around subscription SaaS models, compressing vendor pricing power through demand predictability preferences and multi-tenant platform economics.
Pricing Analysis
Margin tightening in enterprise forwarding reflects workflow integration depth as the primary value anchor, separating CargoWise's premium positioning from rate-transparent spot-market alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by customization intensity and regulatory module bundling. Price differentiation hinges on EASA compliance certification and pharmaceutical cold-chain sensor integration. Small forwarders lacking direct airline contracts exhibit highest price sensitivity, while flag carriers in Germany demonstrate inelastic demand for mission-critical fleet management modules.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Leipzig, and Rotterdam anchor hub-and-spoke delivery of cloud-hosted freight platforms to European forwarders. Software development concentrates in the United States, Germany, and the Netherlands, with implementation services drawing from Indian technology hubs. Raw material dependencies include hyperscaler compute capacity, IoT sensor hardware, and aviation EDI protocol libraries. Single-source vulnerability sits with legacy Cargo-IMP infrastructure providers. Distribution runs through airline operational system integrators and customs-compliance channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API-first architecture is displacing EDI-dependent legacy stacks, compressing competitive moats and redistributing value capture toward integration specialists.
For Market Incumbents: Hedge against Cargo-IMP obsolescence by accelerating ONE Record standardization investments and acquiring sensor-telemetry specialists before API-native entrants capture pharmaceutical cold-chain accounts. Prioritize backward integration into IoT hardware partnerships to defend margin position against modular unbundling. For New Entrants and Emerging Players: The EU F-Gas Regulation in Germany opens a window for carbon-tracking module specialists to penetrate flag carrier procurement cycles before incumbent suite vendors embed emissions calculators. Target Indian pharmaceutical forwarders where cold-chain software penetration remains below fifteen percent, leveraging DGFT documentation requirements as entry wedge. For Investors and Strategic Acquirers: The window for entry favors API-first platform specialists with pre-built EASA and FDA compliance templates. Long-term viability hinges on regulatory automation depth rather than operational efficiency tools. Watch IATA ONE Record adoption velocity as inflection signal for EDI displacement timeline.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Migration | ONE Record standardization enables displacement of Cargo-IMP-dependent vendors across European routes. |
| Pharmaceutical Cold-Chain Integration | Sensor-embedded Track & Trace modules capture Frankfurt and Leipzig pharmaceutical export volumes. |
| Emissions Compliance Module Development | EASA SAF documentation mandates create white space for blockchain-anchored provenance platforms. |
| Strategic Partnership with Hyperscalers | Elastic compute scaling addresses mid-tier forwarder demand for operational expenditure predictability. |
| Acquisition of Customs Compliance Specialist | Pre-built regulatory templates accelerate penetration among Bavarian chemical exporters facing REACH obligations. |
Methodological Framework
Document review covered SEC filings, IATA operational statistics, and EU regulatory databases, complemented by interviews with freight forwarding executives, airline cargo operations managers, customs compliance officers, and pharmaceutical supply chain directors. Secondary validation drew from EASA airworthiness directives, DGFT export documentation frameworks, and hyperscaler capex disclosures. Bottom-up shipment volume modeling and top-down software spend estimates were triangulated against vendor-reported implementation timelines.
Historical adoption curves were cross-referenced against panel input from platform engineers and integration specialists. Segmentation dimensions modeled include deployment model, organization size, vertical specialization, integration complexity, and regional regulatory cluster. CAGRs were derived from shipment volume elasticity to software procurement ratios and cloud migration acceleration patterns across the analysis window. Forecast inputs incorporated pharmaceutical cold-chain mandate expansion and EASA emissions documentation timelines.
The model assumes a particular technology adoption path; alternative pathways for API-first architecture displacement would alter the outlook if Cargo-IMP infrastructure lock-in proves more persistent than projected. Forecasts reflect documented assumptions around regulatory enforcement intensity and cloud data localization rule evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Asia-Pacific less-Than Container Load (LCL) Market
Logistics and Shipping
Intra-Asia Freight Forwarding Market
Logistics and Shipping
Colombia Third-Party Logistics (3PL) Market
Logistics and Shipping
Repositioning and Offloading Market
Logistics and Shipping
Illinois Freight and Logistics Market
Logistics and Shipping
Asia Pacific Freight and Logistics Market
Logistics and Shipping
Asia-Pacific Cold Chain Logistics Market
Logistics and Shipping
China less than Truckload Road Freight Transport Market
Logistics and Shipping
Bangladesh Contract Logistics Market
Logistics and Shipping
Europe Courier Market
Logistics and Shipping
Europe Sea Freight Forwarding Market
Logistics and Shipping
Peru Road Freight Transport Market
Logistics and Shipping
Global Port Logistics Market
Logistics and Shipping
Nigeria Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Roll Trailer Market
Logistics and Shipping
Cold Chain Logistics Market