
 Colombia Third-Party Logistics (3PL) Market | 2026-2036
Colombia Third-Party Logistics (3PL) Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Third-Party Logistics (3PL) Market Outlook
Last-mile delivery networks in Colombia's mountain corridors is tilting toward consolidated hub-and-spoke models that bypass traditional municipal warehousing. DHL Supply Chain leverages its temperature-controlled infrastructure to anchor pharmaceutical and perishable lanes between Bogotá and Cali. Coordinadora Mercantil sustains dominance in domestic parcel distribution through proprietary rural route density that competitors struggle to replicate.
Third-party logistics encompasses the outsourcing of transportation, warehousing, and inventory management functions to specialized providers operating under service-level agreements with defined KPIs for order accuracy, damage rates, and transit time reliability. Its primary commercial purpose centers on converting fixed logistics costs into variable expenditures while accessing capabilities—cross-docking, bonded storage, reverse logistics—that individual shippers rarely maintain in-house. Transportation services currently generate the largest revenue pool within the Colombian market, though warehousing is expanding fastest as manufacturers seek multi-client facilities near Pacific port access. E-commerce client demand is reshaping segment priorities, with automation technology investments concentrated in picking systems and sortation equipment for high-velocity fulfillment.
DIAN, Colombia's national customs and tax authority, enforces electronic cargo manifests and anti-smuggling protocols that 3PL operators must integrate into their tracking systems for cross-border Andean trade. The Ministry of Transport regulates commercial fleet standards, including emissions compliance for trucks operating on primary corridors connecting Bogotá to Caribbean ports. Stakeholders must monitor how forthcoming carbon-footprint disclosure requirements for freight operators will reshape fleet investment timelines and contract pricing structures.
Market Dynamics
Electronic manifest mandates from DIAN are compressing customs clearance windows and forcing 3PL operators to rebuild tracking architectures around real-time data exchange with Colombian port authorities.
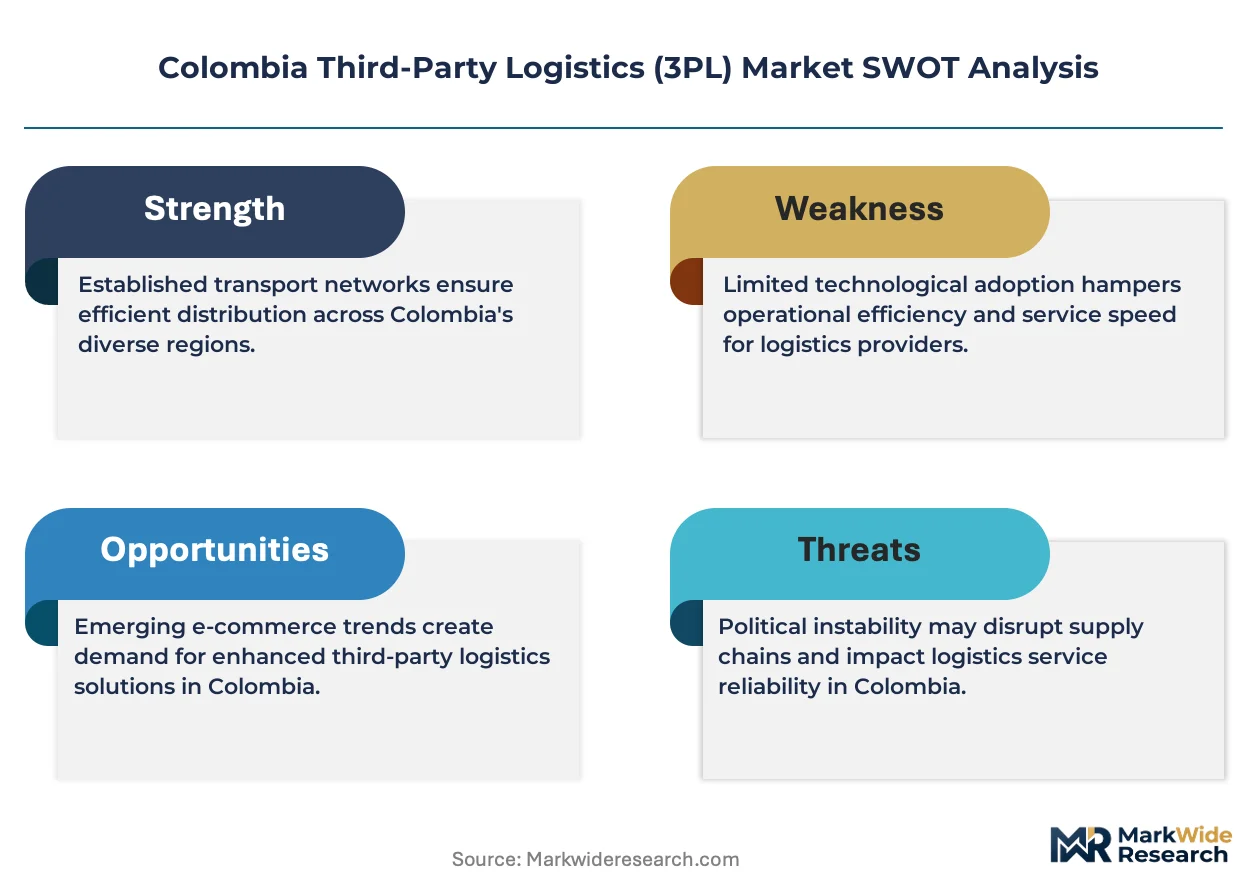
Growth Catalysts
- DIAN Electronic Manifest Requirements:The customs authority's digital filing protocols are accelerating technology upgrades among freight forwarders serving Pacific and Caribbean corridors. Operators integrating these systems capture preferential clearance slots.
- Pharmaceutical Cold Chain Expansion:Temperature-sensitive biologics distribution is deepening reliance on specialized 3PL infrastructure across Bogotá and Medellín. Vaccine logistics requirements are driving investment in validated cold storage.
- E-commerce Fulfillment Velocity:Urban consumer expectations for next-day delivery are reshaping warehouse location strategies toward last-mile proximity. Automated sortation systems are penetrating Andean fulfillment centers.
Market Restraints
- Fuel Price Volatility:Diesel cost fluctuations directly compress margins on long-haul trucking routes connecting interior production zones to coastal ports. Fuel surcharges fail to fully recover swings.
- Pacific Port Capacity Constraints:Container terminal congestion at Buenaventura creates vessel waiting times that cascade through inventory planning cycles. Alternative routing through Cartagena adds inland mileage.
- Driver Qualification Bottlenecks:Commercial licensing backlogs limit fleet expansion timelines for operators seeking to capture cross-border Andean trade volumes.
Strategic Opportunities
- Antioquia Coffee Corridor Logistics:Specialized handling infrastructure for high-value agricultural exports remains underdeveloped relative to volume potential. Temperature-controlled consolidation hubs could capture premium export margins.
- Reverse Logistics Services:E-commerce return volumes are outpacing dedicated processing capacity. Automated inspection and refurbishment workflows represent untapped service line expansion.
- Carbon Footprint Disclosure Alignment:Upcoming Ministry of Transport emissions reporting requirements will advantage early movers with telematics infrastructure. Green fleet certification may become a contract differentiator.
Industry Challenges
- Warehouse Automation Integration:Legacy WMS platforms require costly middleware development to connect with robotic picking systems. Talent scarcity in industrial automation engineering extends implementation timelines.
- Cross-Border Documentation Complexity:Andean Community customs harmonization remains incomplete, forcing redundant paperwork for freight moving between Colombia, Ecuador, and Peru.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Third-Party Logistics (3PL) Market |
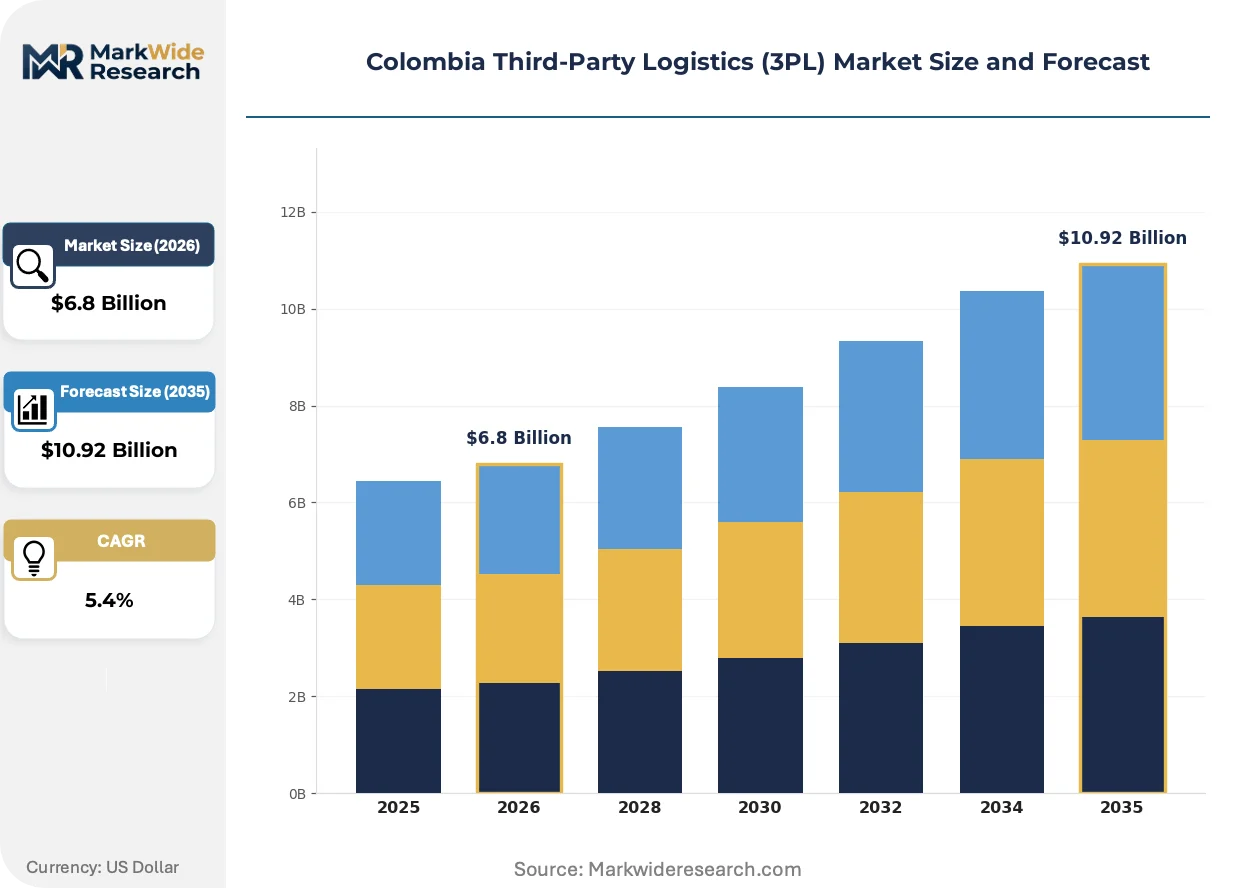
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Packaging, Distribution Client Type: Retailers, Manufacturers, E-commerce, Wholesalers Technology: Automation, Tracking Systems, Freight Management, ERP End User: Consumer Goods, Pharmaceuticals, Automotive, Electronics |
| Companies Covered | DHL Supply Chain, Kuehne + Nagel, Servientrega, Coordinadora Mercantil, Blu Logistics Colombia, XPO Logistics, DB Schenker, C.H. Robinson, Icoltrans, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Third-Party Logistics (3PL) Market Strategic Shifts
Technology migration and regulatory digitization are converging to compress operational timelines across Colombian logistics networks. Three developments are restructuring competitive capabilities.
Automated storage and retrieval systems are migrating from high-volume retail fulfillment toward mid-market pharmaceutical distribution. Cold chain operators in Bogotá corridors are adopting these systems to reduce picking errors in temperature-controlled environments. Labor cost pressures and accuracy requirements are accelerating deployment timelines beyond original adoption forecasts.
DIAN's advance cargo information regulations are mandating pre-arrival data submission for all maritime imports. This policy compresses customs clearance windows from days to hours for compliant operators. Bonded warehouse operators are restructuring inventory positioning to maintain flow velocity under tightened documentation requirements.
Shippers are unbundling transportation from warehousing contracts to optimize each function against specialized performance metrics. Apparel and consumer electronics verticals are driving this fragmentation, seeking dedicated e-commerce fulfillment while retaining flexibility on line-haul routing. Medellín-based manufacturers are most aggressive in disaggregating service procurement.
Colombia Third-Party Logistics (3PL) Market Segmentation
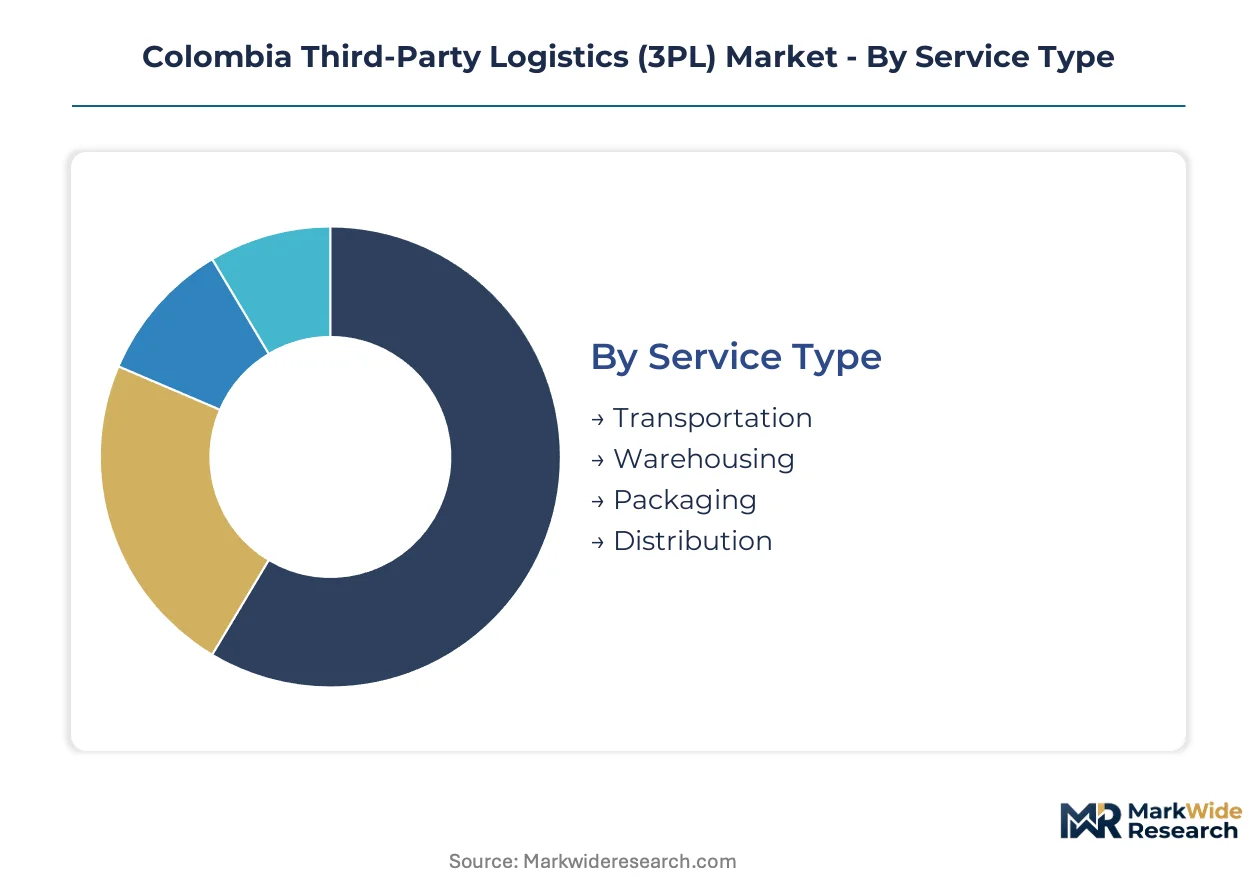
Colombia's 3PL market fragments across service capabilities, client procurement patterns, and technology maturity levels. Segment boundaries are blurring as e-commerce fulfillment demands compress transportation and warehousing into unified performance contracts.
Service Type:
Cost tier differentiation separates asset-heavy infrastructure plays from variable-cost brokerage models.
- Transportation:Full-truckload and less-than-truckload operations dominate revenue pools, with diesel-powered fleets connecting Bogotá production zones to Caribbean and Pacific ports. DIAN electronic manifest mandates are forcing real-time tracking upgrades on corridor operators serving Buenaventura.
- Warehousing:Multi-client facilities near urban clusters command premium rates for last-mile proximity. Cold storage infrastructure for pharmaceutical and perishable verticals is expanding fastest in Bogotá and Medellín corridors.
- Packaging:Value-added services include kitting, labeling, and returns processing for e-commerce clients. Automation penetration remains limited compared to regional peers.
- Distribution:Consolidated hub-and-spoke networks are displacing direct-to-store delivery in mountain corridors. Rural route density determines competitive position.
Transportation holds installed capacity. Warehousing is rotating up the share rankings.
Client Type:
Application focus varies sharply across procurement sophistication and volume predictability.
- E-commerce:Next-day delivery expectations are reshaping warehouse location strategies toward urban proximity. Automated sortation investments concentrate in Andean fulfillment centers serving Bogotá and Medellín metro areas.
- Manufacturers:Just-in-sequence supply chains for automotive and electronics verticals demand dedicated contract logistics with inventory visibility. Pacific port access drives site selection for export-oriented production.
- Retailers:Omnichannel fulfillment requires hybrid inventory positioning across stores and distribution centers. Store replenishment cycles are compressing under competitive pressure.
- Wholesalers:Batch-picking operations and cross-docking efficiency determine cost competitiveness. Traditional cash-and-carry channels are losing share to direct distribution.
Manufacturers retain contract tenure. E-commerce is climbing the fastest.
Technology:
Volume scalability separates legacy operators from digitally native competitors.
- Automation:Robotic picking and automated storage and retrieval systems are penetrating pharmaceutical cold chain facilities. Implementation timelines extend due to talent scarcity in industrial automation engineering.
- Tracking Systems:GPS-enabled fleet monitoring and electronic logging devices satisfy Ministry of Transport compliance requirements. Telematics infrastructure will advantage operators under forthcoming carbon disclosure mandates.
- Freight Management:Transportation management systems optimize load matching and route planning across fragmented carrier networks. Real-time visibility is becoming a table-stakes requirement.
- ERP:Warehouse management system integration with client enterprise platforms enables inventory synchronization. Legacy WMS platforms require costly middleware development.
Tracking Systems holds installed capacity. Automation is gaining share fastest.
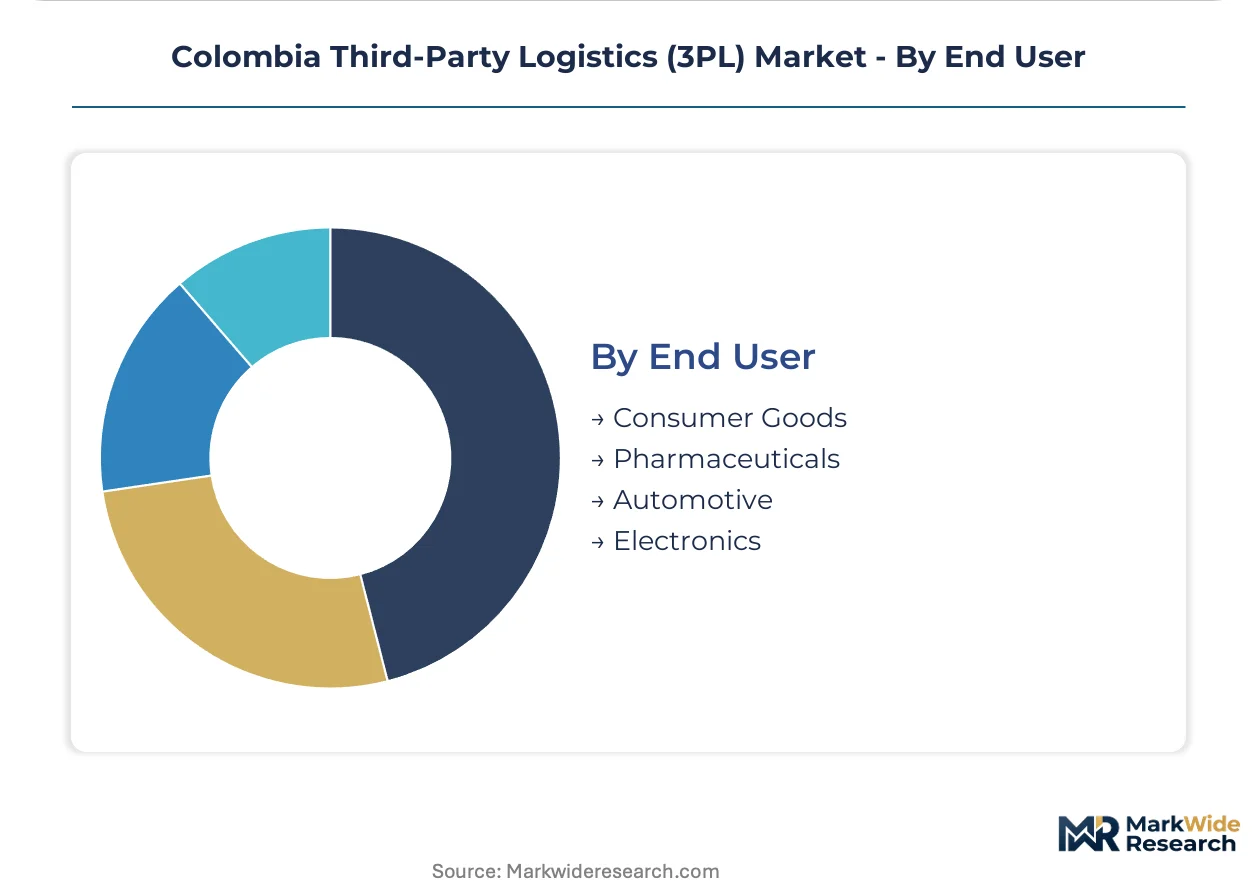
End User:
Customer type determines service level specifications and margin structure.
- Pharmaceuticals:Temperature-controlled distribution of biologics and vaccines demands validated cold chain infrastructure. DIAN customs protocols add complexity to import handling.
- Consumer Goods:High-velocity fulfillment and seasonal demand spikes stress capacity planning. Private label expansion is fragmenting shipment profiles.
- Electronics:High-value density and theft risk drive security requirements in warehousing and transit. Reverse logistics for returns processing represents service line expansion opportunity.
- Automotive:Just-in-time sequencing and production line feeding require precise timing and quality compliance. Parts distribution networks span Andean cross-border corridors.
Consumer Goods holds installed capacity. Pharmaceuticals is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the Andean corridor between Bogotá and Medellín, while Pacific port access commands premium logistics rates that interior corridors struggle to match.
Bogotá Capital District
E-commerce fulfillment demand and pharmaceutical cold chain requirements dominate procurement patterns. DIAN electronic manifest mandates compress customs clearance windows for cross-border freight. The Bogotá-Siberia industrial zone anchors automated warehousing investments serving national distribution networks.
Antioquia Department
Coffee export logistics and textile manufacturing supply chains drive specialized handling requirements. The Ministry of Transport enforces emissions compliance standards for trucks operating primary corridors. Medellín's Rionegro logistics cluster concentrates temperature-controlled consolidation facilities for agricultural exports.
Valle del Cauca Department
Pacific port connectivity and sugarcane agroindustry shape freight volume patterns. DIAN anti-smuggling protocols require real-time tracking integration for Buenaventura-bound cargo. The Yumbo industrial corridor hosts multi-client distribution centers serving Cali's consumer goods manufacturing base.
Caribbean Coast Region
Container terminal throughput at Cartagena and Barranquilla determines inventory positioning strategies for import-dependent manufacturers. The national customs authority's advance cargo information regulations mandate pre-arrival data submission. The Barranquilla free trade zone attracts bonded warehousing operators seeking preferential duty treatment.
Santander Department
Oilfield services logistics and cement distribution create project cargo demand distinct from consumer supply chains. Commercial fleet standards under national transport regulations govern heavy-haul equipment specifications. The Bucaramanga metropolitan area functions as a secondary distribution node for Andean north-south corridors.
Colombia Third-Party Logistics (3PL) Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in fragmented niches. The Colombian 3PL market structures around three distinct tiers: global network operators with bonded warehouse authority, domestic parcel specialists with rural route density, and regional freight brokers with corridor-specific carrier relationships. Strategic moves concentrate on warehouse automation partnerships and last-mile acquisition targets.
Among global network operators, DHL Supply Chain and Kuehne + Nagel exemplify the integrated platform archetype with temperature-controlled infrastructure anchoring pharmaceutical lanes. Domestic specialists Coordinadora Mercantil and Servientrega occupy positions defined by proprietary last-mile density that resists replication. Blu Logistics Colombia represents the mid-market regional broker segment with Pacific corridor concentration.
| Leading Market Players |
|---|
| DHL Supply Chain |
| Kuehne + Nagel |
| Servientrega |
| Coordinadora Mercantil |
| Blu Logistics Colombia |
| XPO Logistics |
| DB Schenker |
| C.H. Robinson |
| Icoltrans |
| Others |
Value Chain & Pricing Dynamics
Buenaventura's Pacific port congestion cascades into interior freight pricing, compressing margins on Bogotá-Cali corridors while elevating rates for operators with bonded warehouse bypass capacity. DIAN electronic manifest compliance costs are folding into contract pricing structures, widening spreads between technology-enabled and legacy operators.
Pricing Analysis
The customization-premium spread between configured-to-order cold chain contracts and standard dry freight pricing is widening as pharmaceutical clients demand validated temperature documentation. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Pricing pressure stems from diesel cost volatility that fuel surcharges fail to fully recover, with long-haul trucking margins tightening disproportionately. E-commerce fulfillment clients exhibit highest price sensitivity, while pharmaceutical distributors prioritize service reliability over rate negotiation.
Supply Chain Analysis
Tariff exposure between Colombia and Ecuador under incomplete Andean Community customs harmonization dominates cross-border documentation complexity, forcing redundant compliance costs on freight forwarders. Supply concentration rests on China for warehouse automation equipment, the United States for fleet telematics systems, and Brazil for commercial vehicle chassis. Single-source vulnerability in cold storage compressor technology feeds from concentrated European manufacturing. Distribution runs through consolidated hub-and-spoke networks that bypass traditional municipal warehousing in mountain corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Colombia's 3PL market sits in early-cycle expansion as e-commerce fulfillment penetration accelerates warehouse automation investment timelines beyond original forecasts.
For Market Incumbents: Insulate pharmaceutical cold chain margins by deepening vertical integration into temperature-controlled last-mile delivery, countering emerging regional specialists with rural route density. Prioritize telematics infrastructure investment ahead of Ministry of Transport carbon disclosure mandates to capture green fleet certification premiums. Defend against domestic parcel competitors by automating sortation capacity in Bogotá-Siberia industrial zones.
For New Entrants and Emerging Players: Establish a beachhead in Antioquia coffee corridor logistics, where specialized handling infrastructure for high-value agricultural exports remains underdeveloped relative to volume potential. Target reverse logistics services for e-commerce returns processing, where automated inspection workflows represent untapped white space. Deploy direct-to-manufacturer sales approaches emphasizing Pacific port proximity against incumbent hub concentration.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified conglomerates with captive logistics divisions lacking standalone technology infrastructure, particularly in temperature-controlled warehousing. Long-term viability hinges on automation integration capabilities and DIAN compliance architecture rather than pure asset scale. Monitor DIAN advance cargo information regulation enforcement intensity as inflection indicator for technology-enabled operator valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Warehouse Automation Partnership | Robotic picking integration with legacy WMS platforms reduces pharmaceutical fulfillment error rates in Bogotá corridors. |
| Last-Mile Acquisition | Rural route density in secondary Andean municipalities defends against Coordinadora Mercantil replication attempts. |
| Cold Chain Certification Investment | Validated vaccine storage infrastructure captures biologics distribution contracts from temperature-sensitive pharmaceutical manufacturers. |
| Telematics Infrastructure Deployment | GPS-enabled fleet monitoring satisfies Ministry of Transport emissions compliance ahead of carbon disclosure mandates. |
| Bonded Warehouse Expansion | Barranquilla free trade zone positioning enables preferential duty treatment for import-dependent consumer goods manufacturers. |
Study Parameters
The analysis maps transportation services, warehousing operations, value-added packaging, and distribution networks, each validated through logistics operations directors, fleet procurement managers, pharmaceutical supply chain leads, and e-commerce fulfillment executives. Primary interviews with 3PL contract managers and customs brokerage specialists combined with secondary validation against DIAN regulatory filings, Ministry of Transport fleet registration databases, and Pacific port authority throughput statistics. Bottom-up service segment sizing and top-down macroeconomic triangulation anchored volume estimates.
Assumptions held fixed include DIAN electronic manifest enforcement timelines and Pacific port capacity expansion schedules, while fuel price trajectories and e-commerce penetration rates varied across sensitivity scenarios. Segmentation dimensions modeled encompass service type, client vertical, technology maturity tier, and regional corridor cluster. CAGRs derived from trend-line extrapolation of historical service revenue flows adjusted for automation adoption curves and pharmaceutical cold chain expansion trajectories. Forecast inputs included commercial fleet growth permits and bonded warehouse licensing approvals.
Sensitivities concentrate around DIAN regulatory enforcement intensity, Pacific port congestion duration, and diesel price volatility bands. Forecasts reflect documented assumptions on customs modernization pace and automation engineering talent availability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
US Fourth-Party Logistics (4PL) Market
Logistics and Shipping
Hungary Third Party Logistics (3PL) Market
Logistics and Shipping
United States Courier, Express and Parcel (CEP) Market
Logistics and Shipping
Singapore Freight and Logistics Market
Logistics and Shipping
Asia Pacific Event Logistics Market
Logistics and Shipping
Italy Courier Market
Logistics and Shipping
High-Tech Logistics Market
Logistics and Shipping
Germany Last Mile Delivery Market
Logistics and Shipping
Air Cargo Market
Logistics and Shipping
Egypt Freight and Logistics Market
Logistics and Shipping
Real-Time Inventory-in-Transit Positioning Platforms Market
Logistics and Shipping
Global 5PL Solutions Market
Logistics and Shipping
India less than Truckload Road Freight Transport Market
Logistics and Shipping
Inbound Logistics Market
Logistics and Shipping
Cambodia Freight and Logistics Market
Logistics and Shipping
Florida Freight and Logistics Market