
 Intra-Asia Freight Forwarding Market | 2026-2036
Intra-Asia Freight Forwarding Market Size, Share, and Industry Trends Forecast 2026-2036
Intra-Asia Freight Forwarding Market Foresight
Cross-border customs brokerage revenue is rewriting profit allocation across the Intra-Asia corridor, pulling margin pools away from pure transport contracting. DHL Global Forwarding leverages its bonded warehouse network across ASEAN to capture higher-yield documentation and compliance services. Sinotrans anchors the China-ASEAN lane through its state-backed port concessions and rail-sea intermodal infrastructure. Kuehne + Nagel differentiates via proprietary visibility platforms that integrate ocean and air cargo tracking across fragmented Asian carrier networks.
Intra-Asia freight forwarding encompasses the coordination of multimodal cargo movement between origins and destinations within the Asian continent, encompassing ocean bill consolidation, air cargo space chartering, customs clearance, and inland distribution through temperature-controlled or standard container specifications. Its primary commercial purpose is to reduce landed costs for regional supply chains by optimizing modal shifts between short-sea shipping, cross-border trucking, and intra-Asia air freight across distances typically under 4,000 nautical miles. Ocean freight maintains the dominant volume position given the density of manufacturing clusters along coastal China, Vietnam, and Indonesia, though air freight claims disproportionate margin contribution from electronics and pharmaceutical shippers requiring speed. E-commerce businesses represent the fastest-growing customer type, driving demand for door-to-door delivery models that merge last-mile capabilities with first-mile consolidation.
China's SAMR enforces logistics data localization requirements that constrain foreign forwarders' cloud-based tracking architectures. Japan's METI mandates sulfur emission controls under its domestic shipping regulations, accelerating fleet upgrades on the Osaka-Busan and Tokyo-Shanghai lanes. South Korea's MFDS imposes cold-chain validation protocols for pharmaceutical transshipments through Incheon. Stakeholders must weigh regulatory compliance investments against the margin compression from digital freight platforms disintermediating traditional brokerage roles.
Market Dynamics
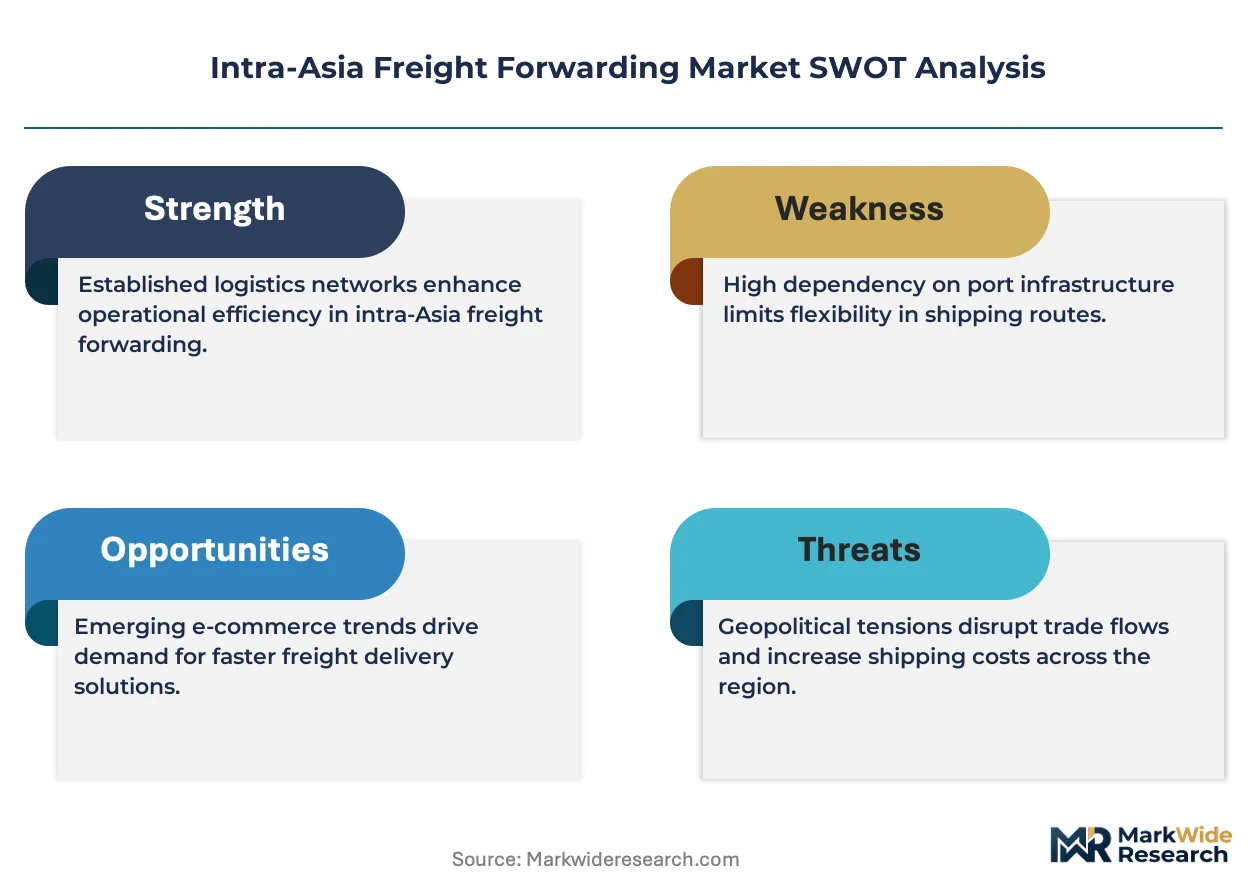
Cross-border data localization mandates from China's SAMR are fragmenting digital freight platforms across the Intra-Asia corridor, forcing operators to rebuild tracking architectures on sovereign cloud infrastructure.
Growth Catalysts
- Dual carbon goals:China's MEE enforcement of emission disclosure requirements for logistics providers is accelerating fleet electrification on the Shanghai-Ningbo corridor.
- Electronics vertical expansion:Vietnam and Thailand manufacturers are deepening regional component sourcing, generating multi-leg consolidation demand for forwarders with bonded warehouse networks.
- EU AI Act transparency mandates:Supply chain documentation requirements for AI hardware exports are pulling compliance service revenue toward specialized customs brokers.
Market Restraints
- Sulfur emission retrofit costs:Japan's METI regulations on the Osaka-Busan lane require scrubber installation or LNG conversion, compressing margins on short-sea routes.
- Port concentration risk:Overreliance on Singapore and Shanghai transshipment hubs creates vulnerability to congestion cascades during peak electronics export windows.
- Air cargo slot scarcity:Limited belly-hold capacity on intra-Asia passenger routes constrains pharmaceutical cold-chain expansion during peak seasons.
Strategic Opportunities
- Cambodia-Laos manufacturing zones:Greenfield electronics assembly investments are creating first-mover advantage for forwarders establishing cross-border trucking networks.
- Rail-sea intermodal convergence:China-ASEAN land bridge development enables 40-hour transit alternatives to pure ocean routing for time-sensitive components.
- MFDS cold-chain validation:South Korea's pharmaceutical transshipment protocols favor forwarders with temperature-certified warehouse infrastructure in Incheon.
Industry Challenges
- Customs digitization talent scarcity:Forwarders struggle to hire engineers capable of integrating legacy EDI systems with blockchain-based trade documentation platforms.
- Multi-modal liability fragmentation:Disputes over damage attribution between ocean carriers, trucking operators, and air cargo handlers complicate insurance structuring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intra-Asia Freight Forwarding Market |
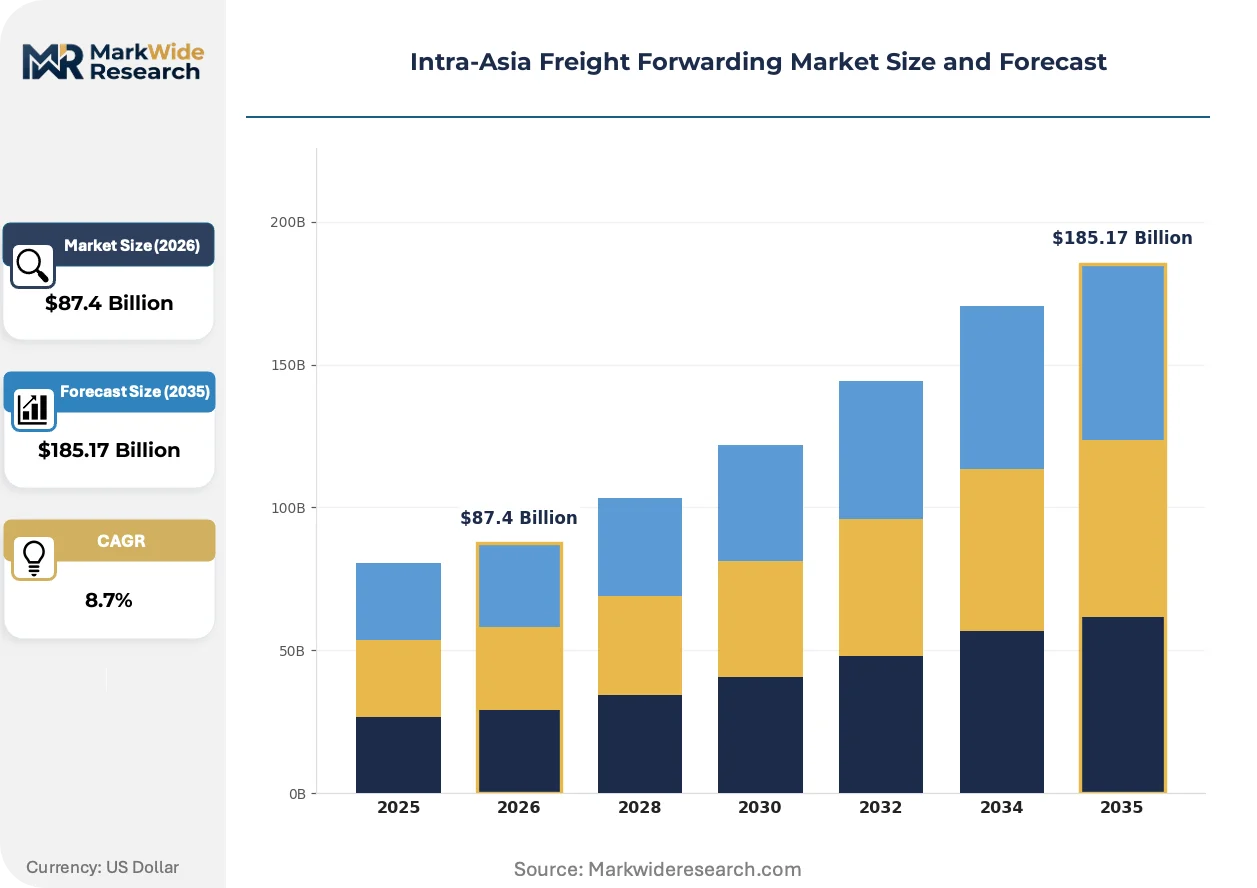
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $185.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Air Freight, Ocean Freight, Rail Freight, Road Freight Customer Type: Small and Medium Enterprises, Large Corporations, E-commerce Businesses, Government Agencies Product Type: Temperature-Controlled Cargo, Hazardous Materials, Consumer Goods, Industrial Equipment Delivery Model: Door-to-Door, Port-to-Port, Port-to-Door, Door-to-Port |
| Companies Covered | Sinotrans, UPS Supply Chain Solutions, DSV, Nippon Express, Expeditors International, DHL Global Forwarding, CEVA Logistics, GEODIS, Kuehne + Nagel, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intra-Asia Freight Forwarding Market Shifts & Advancements
Digital freight matching platforms are compressing brokerage margins while simultaneously creating demand for higher-value compliance and visibility services across fragmented Asian carrier networks.
Blockchain-enabled trade documentation is collapsing settlement cycles between Vietnamese electronics exporters and Japanese importers. Electronics manufacturers in the Vietnam-South Korea-Japan corridor are piloting smart bill-of-lading systems that auto-execute payment upon GPS-confirmed delivery. This compression is eliminating 3-5 days of working capital lockup per shipment, redistributing margin from traditional documentary credit banks to technology-integrated forwarders.
China's SAMR data localization requirements are forcing cloud architecture fragmentation for multi-national operators. Foreign forwarders must now maintain separate server instances within mainland China, duplicating IT infrastructure costs while creating compliance arbitrage opportunities for domestic players with sovereign data clearance. The regulation most affects electronics and pharmaceutical shippers requiring real-time temperature and location telemetry.
Shippers are consolidating vendor relationships around door-to-door service accountability. E-commerce platforms and industrial manufacturers are replacing fragmented point-to-point contracts with single-source forwarders liable for end-to-end performance. This concentration is most visible in the Vietnam-South Korea lane, where electronics exporters now prioritize forwarders with captive last-mile delivery capabilities over pure ocean or air specialists.
Intra-Asia Freight Forwarding Market Segmentation
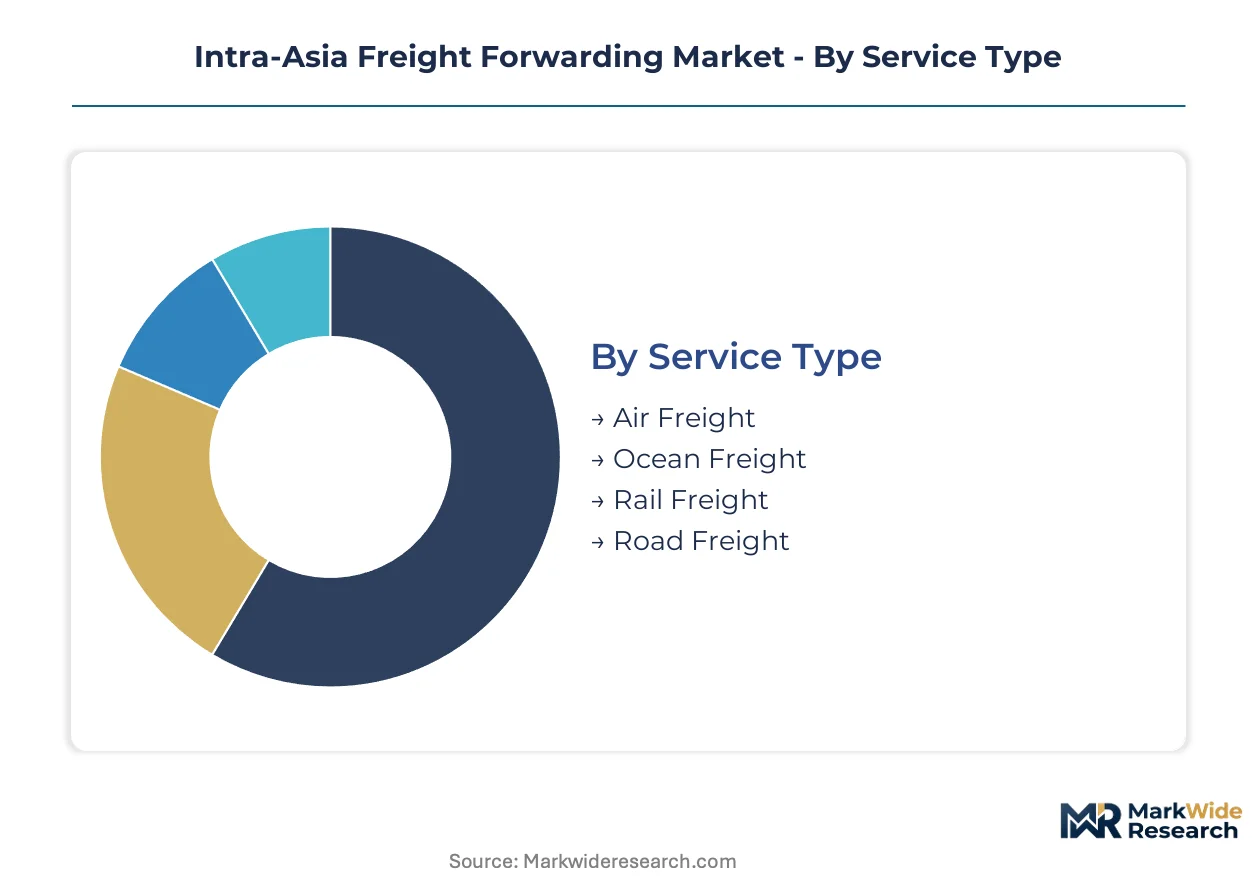
Intra-Asia freight forwarding demands granular segmentation because modal choices, compliance requirements, and margin structures vary sharply across service types and customer profiles. Electronics manufacturers in Vietnam require fundamentally different forwarding architectures than pharmaceutical shippers in South Korea or cross-border e-commerce platforms serving ASEAN consumers.
Service Type:
After-sales service intensity varies dramatically across transport modes, with air freight demanding 24/7 exception management and ocean freight requiring extended documentation support through port congestion events.
- Ocean Freight:Consolidates containerized cargo across short-sea routes under 4,000 nautical miles, with bill-of-lading consolidation serving Vietnam-Thailand-Japan manufacturing corridors. Demand concentrates from electronics assemblers seeking cost-efficient component flows, though sulfur emission retrofit costs on Japan's Osaka-Busan lane compress margins.
- Air Freight:Charters belly-hold and dedicated freighter capacity for time-sensitive pharmaceuticals and semiconductor components. South Korea's Incheon hub captures disproportionate yield from cold-chain validation requirements under MFDS protocols, with slot scarcity during peak seasons constraining expansion.
- Rail Freight:China-ASEAN land bridge alternatives offering 40-hour transit for electronics components bypassing pure ocean routing.
- Road Freight:Cross-border trucking networks serving Cambodia-Laos manufacturing zones with first-mile consolidation from greenfield assembly investments.
Ocean freight holds the largest share; momentum sits with rail freight as intermodal convergence accelerates.
Customer Type:
Cost tier differentiation separates price-sensitive transactional shippers from premium service buyers requiring integrated compliance and visibility platforms.
- E-commerce Businesses:Fastest-expanding customer category demanding door-to-door delivery models merging last-mile capabilities with first-mile consolidation. Platform sellers on Vietnam-South Korea lanes prioritize forwarders with captive last-mile networks over modal specialists.
- Large Corporations:Multinational electronics and pharmaceutical manufacturers consolidating vendor relationships around single-source accountability for end-to-end performance. These buyers drive demand for proprietary visibility platforms integrating ocean and air cargo tracking.
- Small and Medium Enterprises:Fragmented shippers dependent on digital freight matching platforms for spot market access.
- Government Agencies:Public procurement flows with specialized documentation requirements for aid and infrastructure materials.
Large corporations hold the largest share; e-commerce businesses are gaining share fastest.
Product Type:
Application-driven segmentation separates commodity flows from specialized cargo requiring certified handling infrastructure and regulatory compliance.
- Temperature-Controlled Cargo:Pharmaceutical cold chains and perishable electronics components requiring validated warehouse infrastructure. South Korea's MFDS transshipment protocols favor forwarders with temperature-certified facilities in Incheon, while China's SAMR data localization constrains real-time telemetry architectures.
- Consumer Goods:High-velocity e-commerce parcels and retail replenishment flows dominating volume on China-ASEAN lanes. These shipments prioritize speed-to-shelf over modal cost optimization.
- Hazardous Materials:Chemical and battery shipments subject to IMDG code and cross-border dangerous goods regulations.
- Industrial Equipment:Project cargo and machinery movements requiring specialized lifting and oversized routing.
Consumer goods hold the largest share; temperature-controlled cargo is climbing the fastest.
Delivery Model:
Geographic scope of liability determines forwarder margin capture, with door-to-door models commanding premium pricing over point-to-point contracting.
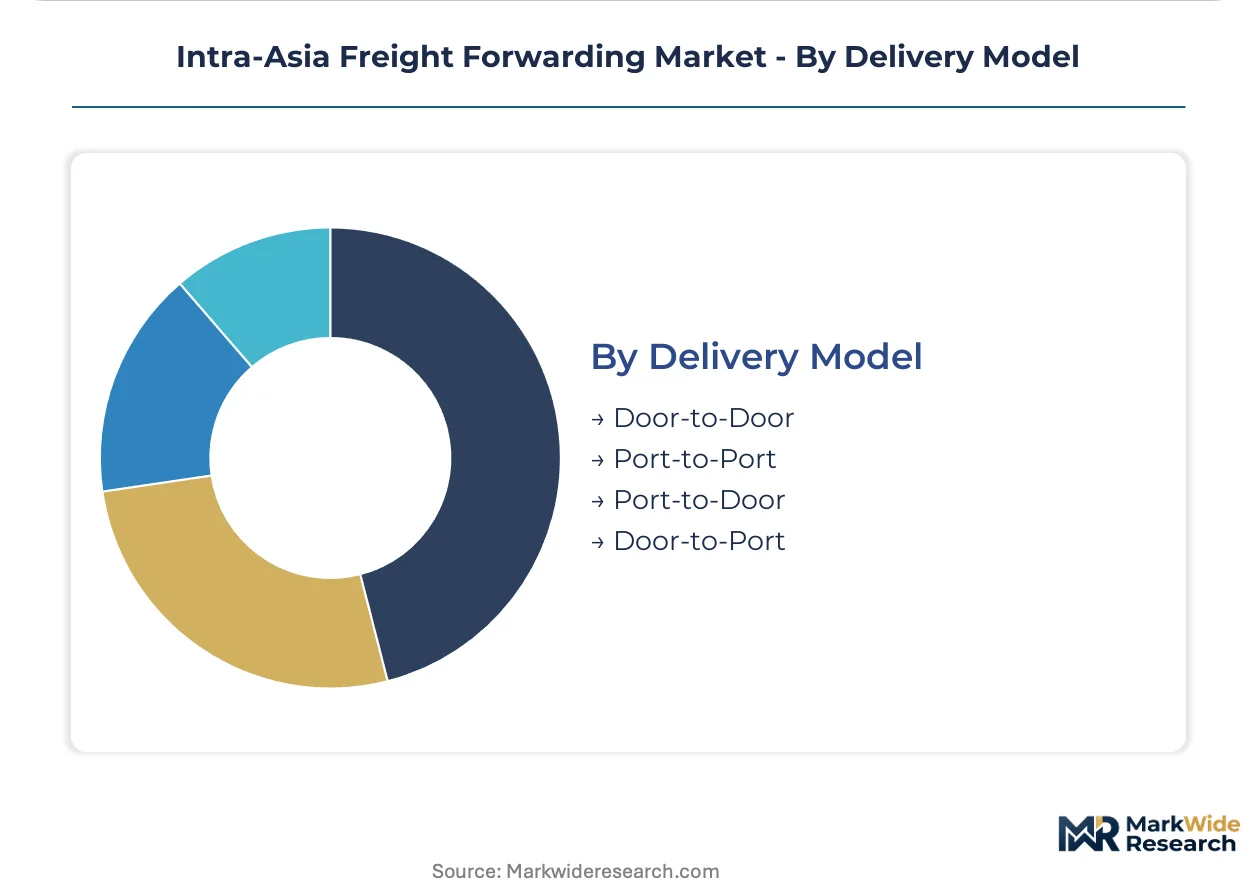
- Door-to-Door:End-to-end accountability covering first-mile pickup through final delivery, increasingly preferred by electronics manufacturers replacing fragmented contracts. This model merges customs brokerage, multimodal coordination, and last-mile distribution under single-source liability.
- Port-to-Port:Traditional ocean contracting with shipper responsibility for pre- and on-carriage, now losing share to integrated alternatives.
- Port-to-Door:Hybrid arrangements with forwarder control over import customs and inland distribution.
- Door-to-Port:Export-focused models common in origin-controlled supply chains.
Port-to-port holds the largest share; door-to-door shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Intra-Asia freight forwarding concentrates on manufacturing corridors linking coastal China with Vietnam, Thailand, and South Korea. Port infrastructure and bonded warehouse networks determine competitive positioning across these lanes.
China
Shanghai-Ningbo corridor electronics exporters drive consolidation demand for bonded warehouse services. SAMR data localization mandates force foreign forwarders to maintain sovereign cloud instances, raising IT infrastructure costs. Yangtze River Delta manufacturers are expanding Vietnam sourcing networks, generating multi-leg freight demand.
Vietnam
Electronics assemblers in Ho Chi Minh City and Hanoi deepen regional component sourcing from Thailand and South Korea. Dual carbon disclosure requirements from China's MEE affect cross-border documentation for exports to Chinese markets. Northern industrial zones attract greenfield investments requiring first-mile trucking networks.
South Korea
Semiconductor and pharmaceutical shippers at Incheon anchor premium air freight demand. MFDS cold-chain validation protocols favor forwarders with temperature-certified warehouse infrastructure. Busan port serves as transshipment hub for Japan-bound electronics components.
Thailand
Automotive and electronics manufacturers in Bangkok and Eastern Economic Corridor expand regional sourcing networks. Japan's METI sulfur emission controls on Osaka-Busan lanes affect Thai exporters using Japanese transshipment. Laem Chabang port congestion during peak electronics windows creates capacity bottlenecks.
Japan
Tokyo-Osaka manufacturers consolidate vendor relationships around single-source forwarders with end-to-end accountability. METI domestic shipping regulations mandate fleet upgrades on short-sea routes to South Korea. Yokohama and Kobe ports handle precision electronics requiring specialized handling protocols.
Intra-Asia Freight Forwarding Market Competitive Landscape
Asset-heavy state-backed operators and technology-integrated multinationals split the market along compliance capability lines. Consolidation pressure favors players with captive bonded warehouse networks and proprietary visibility platforms. Three archetypes dominate: state-affiliated port concessionaires, integrated logistics multinationals, and digital-native freight platforms. Competitive moves center on rail-sea intermodal partnerships and customs brokerage capability acquisitions.
Within the integrated multinational tier, DHL Global Forwarding and Kuehne + Nagel exemplify technology-forward positioning, while Sinotrans anchors the state-backed archetype with China-ASEAN infrastructure control. DHL leverages bonded warehouse networks across ASEAN for documentation yield. Kuehne + Nagel occupies a position defined by ocean-air tracking integration. Sinotrans represents rail-sea intermodal dominance through state port concessions.
| Leading Market Players |
|---|
| Sinotrans |
| UPS Supply Chain Solutions |
| DSV |
| Nippon Express |
| Expeditors International |
| DHL Global Forwarding |
| CEVA Logistics |
| GEODIS |
| Kuehne + Nagel |
| Others |
Supply & Pricing Matrix
Shanghai-Ningbo corridor capacity dynamics concentrate pricing power among bonded warehouse operators serving electronics exporters, while sulfur retrofit mandates on Japan's Osaka-Busan lane compress short-sea margins and redirect demand toward rail-sea alternatives.
Pricing Analysis
China's SAMR data localization dictates the pricing tier structure across compliance-heavy segments, separating forwarders with sovereign cloud infrastructure from those absorbing duplicated IT costs. Three-tier pricing stratifies across premium door-to-door, standard multimodal, and economy port-to-port service levels. Price differentiation rests on customs brokerage integration and real-time visibility certification. Cost compression in economy ocean freight is intensifying because digital freight platforms disintermediate spot brokerage. Small and medium enterprises exhibit highest price sensitivity, while large corporations prioritize single-source accountability over modal cost optimization.
Supply Chain Analysis
Extended payment terms from electronics assemblers in Vietnam and Thailand strain working capital for mid-tier forwarders without supply-chain finance facilities. Manufacturing inputs draw from semiconductor components in South Korea, precision parts in Japan, and raw materials in China. Supply chain risk centers on port concentration vulnerability at Singapore and Shanghai transshipment hubs during peak electronics export windows. Distribution runs through bonded warehouse networks in Ho Chi Minh City, Bangkok, and Incheon before final-mile injection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across China's SAMR, Japan's METI, and South Korea's MFDS creates specialized compliance niches that reward targeted capability investments over scale-based competition.
For Market Incumbents: Insulate documentation yield by deepening captive bonded warehouse networks across ASEAN, particularly in Vietnam and Thailand where electronics manufacturers consolidate vendor relationships. Acquire customs digitization talent capable of integrating legacy EDI with blockchain trade platforms before digital-native competitors capture compliance service margins. Prioritize rail-sea intermodal partnerships on the China-ASEAN land bridge as an alternative to sulfur-regulated short-sea lanes. For New Entrants and Emerging Players: Cambodia-Laos manufacturing zones offer first-mover advantage for cross-border trucking networks serving greenfield electronics assembly investments. Target pharmaceutical cold-chain validation services under South Korea's MFDS protocols, where temperature-certified warehouse infrastructure in Incheon remains undersupplied. Build proprietary visibility platforms integrating ocean and air cargo tracking across fragmented Asian carrier networks as the primary go-to-market wedge. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors forwarders with integrated compliance-visibility capabilities over pure transport contractors. Long-term viability hinges on regulatory arbitrage capture as data localization and emission disclosure mandates proliferate. Target acquisition archetypes include regional customs brokers with bonded warehouse concessions and digital freight platforms with proven carrier integration. Watch for inflection signals in China-ASEAN rail freight volume as a proxy for modal shift acceleration away from emission-controlled short-sea routes.| Strategic Initiative | Industry Significance |
|---|---|
| Rail-Sea Intermodal Partnership | China-ASEAN land bridge development enables 40-hour transit alternatives bypassing sulfur-regulated ocean lanes. |
| Bonded Warehouse Network Expansion | Captures higher-yield documentation and compliance services from Vietnam-South Korea-Japan electronics corridors. |
| Cold-Chain Infrastructure Certification | MFDS validation protocols in Incheon favor temperature-certified facilities for pharmaceutical transshipment yield. |
| Customs Digitization Acquisition | Blockchain-EDI integration talent scarcity creates defensive moat against platform disintermediation. |
| Last-Mile Capability Integration | Door-to-door accountability commands premium pricing from e-commerce platforms consolidating vendor relationships. |
Research Methodology
A standing panel of freight forwarding operations directors, customs brokerage managers, electronics supply chain planners, and pharmaceutical logistics coordinators provided ongoing calibration against market developments. Primary interview insights combined with secondary validation from customs trade databases, port authority throughput statistics, carrier fleet disclosure filings, and regulatory agency enforcement bulletins. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume and value estimates.
Scenario-bracketing around regulatory enforcement intensity and modal shift elasticity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, customer scale tier, product handling requirements, and delivery liability scope. CAGRs derived from trend extrapolation of electronics manufacturing relocation patterns and e-commerce penetration trajectories, cross-referenced with rail freight capacity expansion timelines and emission regulation phase-in schedules.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by state-backed port concessionaires or accelerated digital platform consolidation would shift outcomes. Macroeconomic deviation in Asian manufacturing export demand, regulatory enforcement intensity exceeding modeled thresholds, or breakthrough automation in customs clearance would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Colombia Freight and Logistics Market
Logistics and Shipping
Indonesia Cold Chain Logistics Market
Logistics and Shipping
Contract Logistics Market
Logistics and Shipping
Vehicle Routing and Scheduling Market
Logistics and Shipping
Mexico Freight Forwarding Market
Logistics and Shipping
Egypt 3PL Market
Logistics and Shipping
Latin America Logistics Market
Logistics and Shipping
Italy Apparel Logistics Market
Logistics and Shipping
Water Hauling Services Market
Logistics and Shipping
Georgia Freight and Logistics Market
Logistics and Shipping
Peru Freight and Logistics Market
Logistics and Shipping
Big Data in Logistics Market
Logistics and Shipping
Global Retail 3PL Market
Logistics and Shipping
United States Contract Logistics Market
Logistics and Shipping
ASEAN Cross Border Road Freight Transport Market
Logistics and Shipping
Middle East and Africa Courier Market