
 Roll Trailer Market | 2026-2036
Roll Trailer Market Size, Share, and Industry Trends Forecast 2026-2036
Roll Trailer Market Analytics
Software-defined fleet management and predictive maintenance contracts are repositioning how roll trailer value gets captured, shifting revenue from unit sales to uptime guarantees. Goldhofer leverages its engineering heritage in heavy-transport modules to sustain premium positioning in extra-heavy-duty segments. Faymonville anchors European project-cargo demand through specialized lowboy configurations for wind-energy components. TII Group competes across multiple load-capacity tiers with standardized platform architectures.
A roll trailer is a wheeled cargo platform designed for terminal hauling, port operations, and intermodal transfers, typically constructed from high-tensile steel with rated axle capacities spanning light-duty to extra-heavy-duty classifications. Its primary purpose is to bridge the gap between vessel, rail, and road modes without requiring crane lifting at each transfer node. Flatbed and container variants dominate volume due to standardization pressures from global shipping lines, while lowboy configurations command margin premiums in project-cargo niches. Steel remains the baseline material across heavy-duty applications, though aluminum and composite alternatives gain traction where tare-weight reduction directly improves payload economics for freight companies.
The EU's F-Gas Regulation and CE marking requirements shape refrigerant and braking-system specifications for trailers serving temperature-controlled logistics, while China's SAMR enforces GB axle-load standards that limit platform designs in domestic road fleets. Germany's KBA and the UAE's federal transport authority both mandate periodic structural inspections that accelerate replacement cycles in high-utilization corridors. Stakeholders must weigh material substitution economics against regulatory compliance costs when configuring regional product mixes.
Market Dynamics
Software-defined fleet management is compressing traditional equipment sales cycles into uptime-guarantee contracts, forcing manufacturers to restructure revenue recognition around asset availability rather than unit delivery.
Growth Catalysts
- EU F-Gas Regulation:Mandates on transport refrigeration are accelerating replacement demand for compliant roll trailer configurations across temperature-controlled logistics corridors serving pharmaceutical and perishable cargo flows.
- Wind-energy component logistics:Specialized lowboy configurations for turbine blade and nacelle transport are commanding sustained order volumes from European and North American project developers.
- China's GB axle-load standards:SAMR enforcement of stricter road weight limits is driving fleet modernization toward higher-capacity platform architectures that maximize legal payload efficiency.
Market Restraints
- High-tensile steel price volatility:Input cost swings for the baseline chassis material compress margin buffers for standardized platform producers without long-term supply contracts.
- Regional certification fragmentation:Divergent braking-system and structural inspection mandates between Germany's KBA, UAE federal transport authority, and China's SAMR inflate product adaptation costs for cross-border fleet operators.
- Aluminum substitution economics:Tare-weight reduction benefits from alternative materials remain constrained by upfront cost premiums and welding-process incompatibility with existing service networks.
Strategic Opportunities
- Predictive maintenance convergence:IoT sensor integration with axle-load monitoring systems is expanding into premium service contracts that capture recurring revenue from uptime guarantees.
- UAE Jebel Ali port zone:Terminal expansion and transshipment volume growth are creating concentrated demand for heavy-duty container variants with rapid intermodal transfer capability.
- India's logistics infrastructure push:Dedicated freight corridors and port modernization under the National Logistics Policy are opening fleet procurement channels previously dominated by manual handling equipment.
Industry Challenges
- Telematics integration complexity:Retrofitting legacy roll trailer fleets with real-time tracking and predictive diagnostics requires coordination between OEM firmware architectures and third-party fleet management platforms.
- Structural inspector certification gaps:Shortages of qualified assessors for KBA and SAMR-mandated periodic examinations extend equipment downtime and accelerate premature replacement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roll Trailer Market |
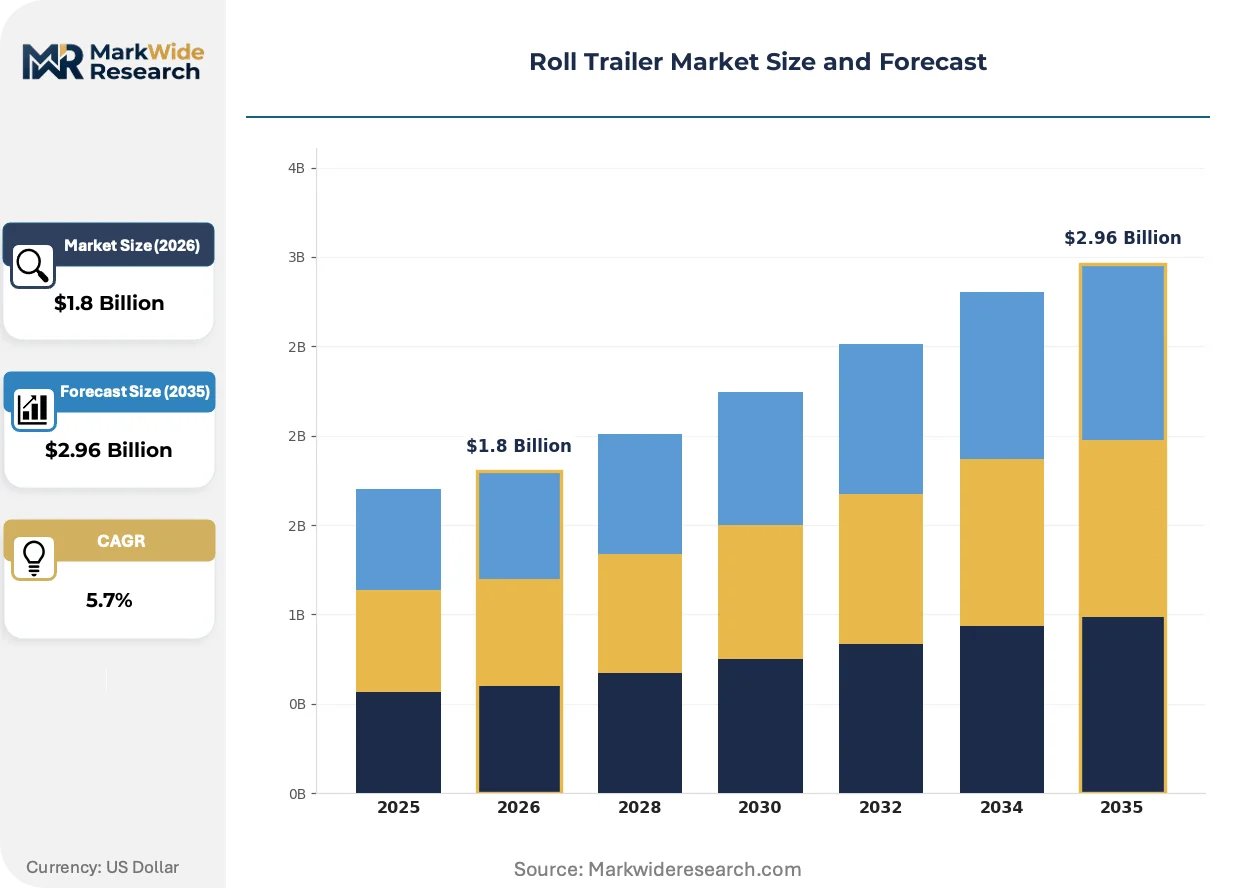
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flatbed, Container, Lowboy, Semi-Trailer End User: Logistics Providers, Freight Companies, Construction, Retailers Load Capacity: Light Duty, Medium Duty, Heavy Duty, Extra Heavy Duty Material: Steel, Aluminum, Composite, Others |
| Companies Covered | Goldhofer, Faymonville, TII Group, Tadano Ltd., Zorzi Group, Cargotec, Konecranes, Kalmar, Liebherr, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roll Trailer Market Evolving Landscape
Digitalization of asset tracking and predictive diagnostics is restructuring how fleet operators evaluate total cost of ownership, shifting specification priorities from upfront acquisition price toward lifecycle performance data.
Composite-reinforced chassis sections are expanding into extra-heavy-duty applications where weight reduction directly improves payload economics for freight companies operating at legal axle-load limits. European wind-energy logistics providers are adopting these configurations fastest, compressing the performance gap between steel baselines and advanced material alternatives. The technology is expanding into standardized platform architectures previously reserved for project-cargo niches.
REACH and RoHS compliance requirements for braking-system materials are forcing redesigns of hydraulic and pneumatic actuation components across EU-serving production lines. Component suppliers must requalify friction materials and sealing compounds, extending engineering timelines for new platform introductions. Container-variant manufacturers serving Rhine-Ruhr industrial corridors face the tightest certification deadlines.
Leasing and availability-based contracting are displacing outright equipment purchases among mid-sized freight operators seeking to offload residual-value risk. Third-party fleet management providers are capturing specification influence previously held by direct OEM relationships. This pattern concentrates in Germany's logistics clusters where capital efficiency metrics dominate procurement committee decisions.
Roll Trailer Market Segmentation
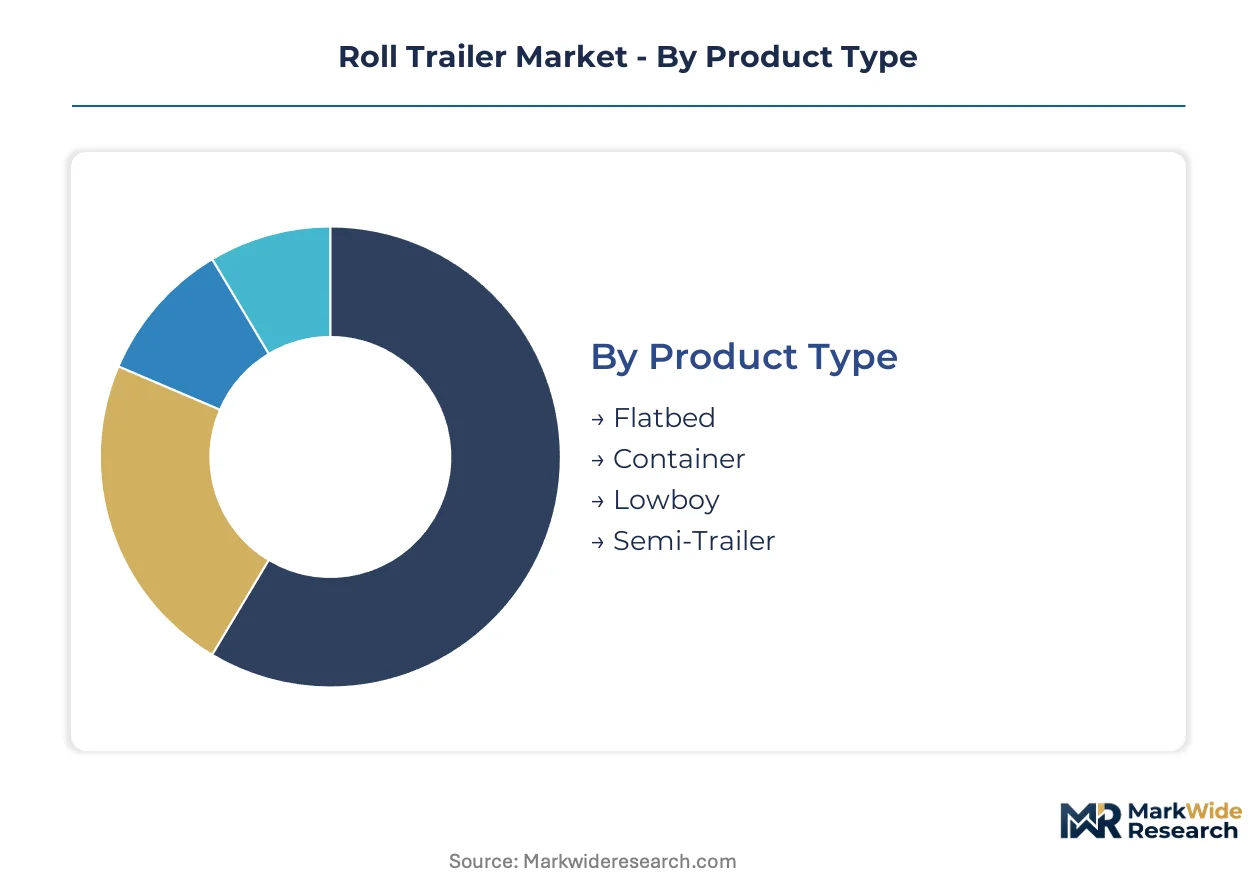
Roll trailer procurement decisions cascade through four interconnected dimensions: product architecture determines intermodal compatibility, end-use verticals dictate duty-cycle intensity, load-capacity ratings define regulatory compliance thresholds, and material selection governs payload economics. Fleet operators configure specifications against corridor-specific axle limits and terminal transfer requirements.
Product Type:
Terminal transfer velocity and crane-avoidance requirements drive specification priorities across port and inland depot networks.
- Flatbed:Open-deck platforms with standardized twist-lock positions accommodate breakbulk and project cargo without containerization. Rhine-Ruhr industrial clusters and UAE transshipment zones concentrate procurement for multi-modal flexibility.
- Container:ISO-dimensioned chassis with sliding bogie configurations maximize legal payload under China's GB axle-load standards. Demand concentrates among shipping lines serving Jebel Ali and European deepwater ports where rapid vessel-to-road transfer compresses dwell time.
- Lowboy:Drop-deck geometry with hydraulic gooseneck ramps enables wind-energy component transport.
- Semi-Trailer:Fifth-wheel coupling architectures dominate North American long-haul corridors.
Container variants lead on scale; lowboy configurations lead on momentum.
End User:
Asset utilization rates and maintenance integration capabilities separate high-volume procurement segments from sporadic replacement demand.
- Logistics Providers:Fleet-scale operators with dedicated maintenance depots prioritize uptime-guarantee contracts and telematics integration. Germany's KBA-mandated inspection cycles accelerate replacement decisions among multi-corridor operators.
- Freight Companies:Owner-operator networks and mid-sized carriers balance acquisition cost against residual value risk. Leasing penetration concentrates among this segment as third-party fleet managers capture specification influence.
- Construction:Project-based demand tied to infrastructure buildouts exhibits irregular procurement timing.
- Retailers:Private fleet operators serving distribution center networks favor standardized configurations.
Logistics providers dominate procurement volume; freight companies are expanding most quickly into availability-based contracting.
Load Capacity:
Regulatory enforcement intensity and corridor-specific weight limits determine fleet composition across operating territories.
- Heavy Duty:Multi-axle platforms rated for concentrated loads serve construction and industrial machinery segments. China's SAMR enforcement of stricter GB standards drives modernization toward architectures that maximize legal payload efficiency per axle group.
- Extra Heavy Duty:Modular axle configurations with hydraulic suspension accommodate transformer and turbine component transport. European wind-energy project developers sustain premium order volumes for Goldhofer-derived platform technologies.
- Light Duty:Single-axle and tandem configurations serve urban delivery and terminal yard operations.
- Medium Duty:Tri-axle platforms balance maneuverability against payload for regional freight.
Heavy duty configurations anchor fleet investment; extra heavy duty variants command the steepest expansion trajectory.
Material:
Tare-weight reduction economics and welding-process compatibility shape material substitution decisions across service network footprints.
- Steel:High-tensile grades remain the baseline for heavy-duty chassis construction. Price volatility compresses margin buffers for standardized platform producers lacking long-term supply contracts.
- Aluminum:Extruded alloy sections reduce unladen weight where payload economics justify upfront cost premiums. REACH and RoHS compliance requirements for braking-system integration constrain alloy selection for EU-serving production lines.
- Composite:Glass-reinforced polymer sections expand into extra-heavy-duty applications previously reserved for steel baselines.
- Others:Hybrid material configurations and experimental fiber-reinforced formulations occupy niche testing programs.
Steel dominates installed base; aluminum is gaining share fastest among temperature-controlled logistics operators seeking payload optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Ruhr logistics cluster generates heavier fleet turnover than China's Yangtze River Delta ports, yet both corridors face tightening axle-load enforcement that accelerates replacement cycles for heavy-duty container variants.
Germany
Industrial machinery exports and wind-energy component logistics sustain premium demand for extra-heavy-duty lowboy configurations. KBA-mandated structural inspection cycles compress equipment replacement timelines for multi-corridor operators. The Rhine-Ruhr logistics cluster concentrates procurement for flatbed and container variants serving transshipment terminals.
China
Port expansion along the Yangtze River Delta and Pearl River Delta drives container-variant orders with sliding bogie architectures. SAMR enforcement of GB axle-load standards limits platform designs and pushes fleet modernization toward higher-capacity configurations. Shanghai-Ningbo port complexes represent the densest procurement concentration for ISO-dimensioned chassis.
United Arab Emirates
Jebel Ali port expansion and transshipment volume growth create concentrated demand for rapid intermodal transfer equipment. Federal transport authority mandates on periodic structural inspections accelerate replacement decisions among terminal operators. Dubai's logistics free zones host the region's densest deployment of heavy-duty container roll trailers.
United States
Fifth-wheel coupling architectures dominate procurement for long-haul freight corridors serving Midwest manufacturing and Gulf Coast petrochemical clusters. NHTSA braking-system standards and state-level weight enforcement shape fleet specifications across interstate corridors. Texas and Louisiana industrial zones sustain demand for flatbed variants in energy-sector logistics.
India
Dedicated freight corridors and port modernization under the National Logistics Policy open fleet procurement channels previously served by manual handling equipment. BIS certification requirements for axle assemblies and braking systems extend product qualification timelines. Gujarat's Mundra port zone and Maharashtra's Jawaharlal Nehru Port Trust anchor initial heavy-duty roll trailer deployments.
Roll Trailer Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with engineering heritage commanding premium positioning in extra-heavy-duty niches while standardized platform producers compete on fleet-scale contracts and service network coverage. The vendor base organizes into three tiers: heritage engineering houses with modular axle technologies, diversified industrial equipment conglomerates with port-system integration capabilities, and regional fabricators serving price-sensitive replacement demand. Consolidation pressure concentrates among mid-scale producers lacking proprietary suspension or telematics architectures. Strategic moves center on predictive maintenance service contracts and composite material qualification programs that extend payload optimization into standardized product lines.
Within the heritage engineering tier, Goldhofer and Faymonville occupy positions defined by heavy-transport module specialization and project-cargo configuration expertise respectively. TII Group sits within the diversified equipment segment, competing across multiple load-capacity tiers with platform architectures that span terminal handling and road haulage applications. These three German-origin entities exemplify how engineering-intensive positioning sustains margin structures distinct from volume-driven competitors.
| Leading Market Players |
|---|
| Goldhofer |
| Faymonville |
| TII Group |
| Tadano Ltd. |
| Zorzi Group |
| Cargotec |
| Konecranes |
| Kalmar |
| Liebherr |
| Others |
Value Network & Pricing Analysis
Welder-certification density in Germany's Ruhr industrial basin anchors labor-cost differentials that widen pricing-tier spreads between heritage-engineering premium platforms and standardized container variants sourced from lower-skill manufacturing regions. KBA-mandated inspection protocols and SAMR axle-load enforcement compress replacement-cycle timing, shifting procurement committees toward lifecycle-cost evaluation over upfront unit pricing.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing zones are reshaping price floors for ISO-dimensioned container chassis serving Jebel Ali and European deepwater ports. Three-tier pricing structure across premium, standard, and economy levels separates Goldhofer-derived modular axle technologies from mass-market platform producers. Price differentiation hinges on telematics integration depth and KBA inspection-interval guarantees. Cost compression in standardized segments is intensifying because high-tensile steel input volatility erodes margin buffers for producers lacking long-term supply contracts. Freight companies and owner-operator networks exhibit the sharpest price sensitivity, while logistics providers with dedicated maintenance depots prioritize uptime-guarantee premiums.
Supply Chain Analysis
Regional distribution centers in Germany, China, and the UAE form a hub-and-spoke pattern that positions finished chassis inventory adjacent to Rhine-Ruhr, Shanghai-Ningbo, and Jebel Ali demand clusters. High-tensile steel plate from German and Chinese mills, hydraulic suspension modules from Italian suppliers, and telematics sensor arrays from South Korean manufacturers constitute critical input dependencies. Single-source vulnerability concentrates in advanced composite-reinforced chassis sections qualified for extra-heavy-duty wind-energy applications. Distribution runs through OEM-direct fleet contracts and third-party leasing platforms that capture specification influence among mid-sized freight operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The roll trailer market functions as a stable compounder anchored by port-expansion infrastructure cycles and regulatory-mandated fleet modernization that sustains replacement demand regardless of freight-rate cyclicality.
For Market Incumbents: Deepen predictive maintenance service-contract penetration to capture recurring revenue from logistics providers seeking to offload residual-value risk. Expand composite-material qualification programs into standardized platform architectures previously reserved for project-cargo niches. Defend against aluminum-substitution threats by emphasizing welding-process compatibility and existing service-network coverage that alternative materials cannot replicate. For New Entrants and Emerging Players: Fleet-management-software integration partnerships offer the lowest-friction entry path for challengers lacking heritage engineering credentials. India's dedicated freight corridors and port modernization under the National Logistics Policy represent the most penetrable geography for first-mover positioning. Target mid-sized freight operators transitioning from outright purchase to availability-based contracting, where specification influence has shifted away from established OEM relationships. For Investors and Strategic Acquirers: Port-system integrators with terminal-handling equipment portfolios are the most active acquirer in this space, seeking roll trailer capabilities to complete intermodal solution offerings. Over a multi-year holding window, fleet-scale logistics providers with embedded maintenance infrastructure present the most defensible acquisition profile. Watch for inflection signals in IoT sensor integration penetration rates among heavy-duty container variants, as predictive-maintenance adoption thresholds indicate when uptime-guarantee revenue models achieve critical mass.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Service Contracts | Captures recurring revenue from KBA-mandated inspection cycles that compress replacement timelines. |
| Composite Material Qualification Programs | Extends payload optimization into standardized platforms serving Rhine-Ruhr industrial corridors. |
| Telematics Platform Integration | Enables real-time axle-load monitoring for SAMR compliance across China's GB-standard fleets. |
| UAE Jebel Ali Port Zone Expansion | Concentrates demand for rapid intermodal transfer equipment in the region's densest deployment cluster. |
| India National Logistics Policy Alignment | Opens fleet procurement channels in Gujarat's Mundra and Maharashtra's Jawaharlal Nehru Port zones. |
Research Methodology
Bottom-up fleet-operator procurement modeling reconciled against top-down manufacturing-capacity tracking forms the analytical core of this study. Primary interviews with fleet maintenance directors, OEM procurement teams, terminal operations managers, and aftermarket service heads were cross-validated against customs trade records, KBA inspection-cycle statistics, SAMR enforcement bulletins, and EU F-Gas Regulation compliance databases. This dual-layer approach triangulates demand signals from logistics providers with supply-side constraints from steel mills and component suppliers.
Input-output matrices map product-type, load-capacity, material, and end-user segmentation dimensions across the projection horizon. CAGRs derive from corridor-specific fleet-turnover rates, regulatory-compliance deadlines, and infrastructure-expansion timelines. Forecast inputs incorporate Jebel Ali transshipment volume trajectories, China's GB axle-load enforcement intensity, and wind-energy component logistics demand from European project developers.
The model assumes a particular technology adoption path; alternative pathways for composite-reinforced chassis sections would alter the outlook if welding-process compatibility barriers resolve faster than baseline assumptions. Forecasts reflect documented assumptions around regulatory enforcement consistency and steel-price volatility bands. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
US Courier, Express, and Parcel Market
Logistics and Shipping
Vehicle Routing and Scheduling Market
Logistics and Shipping
Latin America Cold Chain Logistics Market
Logistics and Shipping
Middle East Freight Forwarding Market
Logistics and Shipping
Qatar Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Digital Logistics Market
Logistics and Shipping
France Parcel Market
Logistics and Shipping
Indonesia Cold Chain Logistics Market
Logistics and Shipping
Canada Freight and Logistics Market
Logistics and Shipping
South Korea Parcel Delivery Market
Logistics and Shipping
South America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Cambodia Freight and Logistics Market
Logistics and Shipping
Water Hauling Services Market
Logistics and Shipping
Global 5PL Solutions Market
Logistics and Shipping
Less-Than-Truckload Market
Logistics and Shipping
Asia-Pacific Pharmaceutical Logistics Market