
 US FTL Brokerage Market | 2026-2036
US FTL Brokerage Market Size, Share, and Industry Trends Forecast 2026-2036
US FTL Brokerage Market Insights
E-commerce fulfillment is rebalancing the US FTL Brokerage Market toward higher-velocity, smaller-lot movements that strain traditional carrier direct relationships. C.H. Robinson leverages its digital freight platform to aggregate fragmented carrier capacity across major freight corridors. Total Quality Logistics anchors its position through specialized account management teams serving mid-market shippers. Landstar System differentiates via its independent contractor agent model that reduces fixed asset exposure.
US FTL brokerage denotes the intermediation of full truckload freight capacity between shippers and for-hire motor carriers, typically involving loads exceeding ten thousand pounds that fill an entire trailer and move under negotiated rate agreements or spot market transactions. The practice coordinates dry van, refrigerated, and flatbed equipment types while managing pickup scheduling, transit tracking, and proof-of-delivery documentation. Standard and expedited service types capture the dominant volume flows, with temperature-controlled freight commanding premium rate structures due to specialized equipment scarcity. The hub-and-spoke delivery model retains share in retail replenishment networks, though direct delivery gains traction among manufacturers seeking reduced handling and faster transit.
The Federal Motor Carrier Safety Administration enforces hours-of-service rules and safety fitness determinations that constrain driver availability and elevate broker coordination value. The Surface Transportation Board maintains oversight of carrier rate reasonableness and service obligations that indirectly shape broker pricing transparency. Stakeholders must monitor emerging federal freight corridor designations and state-level truck parking infrastructure investments that will determine capacity accessibility across key origin-destination pairs.
Market Dynamics
The FMCSA's electronic logging device mandate and hours-of-service reforms have permanently tightened carrier capacity, amplifying the coordination value of broker intermediaries who aggregate fragmented truckload supply.
Growth Catalysts
- E-commerce fulfillment networks:Amazon, Walmart, and Target distribution centers are outsourcing dedicated truckload capacity to brokers rather than maintaining private fleets, creating sustained demand for intermediated capacity.
- FMCSA safety fitness reforms:Stricter carrier disqualification protocols are pushing shippers toward vetted broker networks with compliance infrastructure that individual carriers lack.
- Southeast manufacturing corridor:Automotive and appliance production clusters across Georgia, Tennessee, and South Carolina are generating concentrated outbound freight flows that brokers optimize through lane-specific carrier relationships.
Market Restraints
- Driver supply compression:The American Trucking Associations reports persistent shortages in qualified CDL-holders, constraining the underlying carrier base that brokers represent.
- Spot rate volatility:Diesel price swings and seasonal demand surges create margin compression for brokers locked into contracted shipper rates while paying variable spot market premiums.
- Carrier direct contracting:Large shippers including Procter & Gamble and Coca-Cola are building internal procurement teams to negotiate directly with national carriers, bypassing broker markups.
Strategic Opportunities
- Mexico cross-border lanes:Nearshoring of manufacturing to Nuevo León and Tamaulipas is creating northbound freight corridors where US brokers with customs brokerage capabilities capture premium margins.
- Refrigerated freight specialization:Food safety modernization rules and pharmaceutical cold chain requirements are segmenting the market toward temperature-certified broker networks.
- Digital freight matching platforms:Real-time pricing APIs and automated carrier onboarding are compressing transaction costs and enabling smaller brokers to compete against established load boards.
Industry Challenges
- Carrier onboarding compliance:Brokers must verify insurance, authority, and safety ratings across thousands of small carriers, with FMCSA audits imposing liability for negligent hiring.
- Legacy TMS integration:Shipper transportation management systems from Oracle and SAP require custom EDI connections that delay broker participation in automated tendering workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US FTL Brokerage Market |
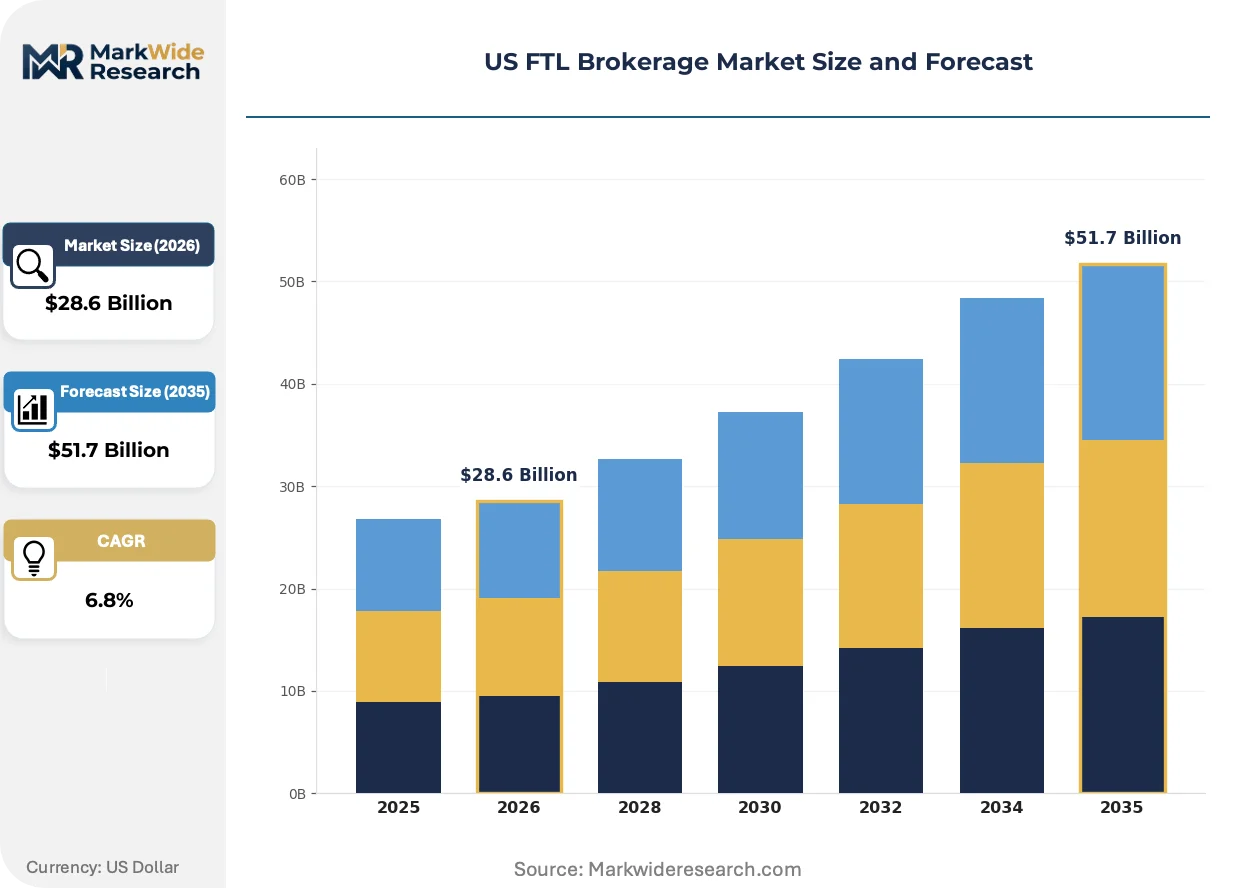
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard, Expedited, Temperature-Controlled, Hazmat End User: Retailers, Manufacturers, Wholesalers, E-Commerce Delivery Model: Direct Delivery, Hub-and-Spoke, Dock-to-Dock, Cross-Docking Pricing Model: Fixed Rate, Variable Rate, Spot Pricing, Subscription |
| Companies Covered | C.H. Robinson, Total Quality Logistics, XPO Logistics, Echo Global Logistics, Coyote Logistics, GlobalTranz Enterprises, Landstar System, Hub Group, Schneider, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US FTL Brokerage Market Trends and Innovations
Digital freight platforms are compressing the traditional broker-carrier matching cycle from hours to minutes, while regulatory data mandates and shipper sustainability requirements reshape competitive requirements.
Machine learning algorithms for dynamic pricing are integrating historical lane data, weather patterns, and port congestion signals to predict spot rates with precision that manual pricing teams cannot match. Mid-market shippers are adopting these tools fastest, seeking rate transparency that reduces their procurement overhead. The technology is integrating predictive analytics directly into broker operating systems, compressing the value of traditional relationships built on phone-based carrier recruitment.
The FMCSA's Drug and Alcohol Clearinghouse mandates pre-employment queries and annual checks that disqualify drivers with substance violations, reducing the eligible driver pool and elevating broker screening costs. Carriers with established compliance infrastructure gain preferential load access from risk-averse brokers. Refrigerated and hazmat segments face the steepest capacity constraints as qualified driver scarcity intensifies.
Shippers are consolidating freight procurement around outcome-based contracts that penalize late deliveries and reward carbon emissions reductions rather than accepting standard transit-time guarantees. Food and beverage manufacturers are driving this shift fastest, responding to retailer sustainability scorecards. The practice is most visible in California and the Pacific Northwest, where state-level clean freight rules and corporate net-zero commitments intersect.
US FTL Brokerage Market Segmentation
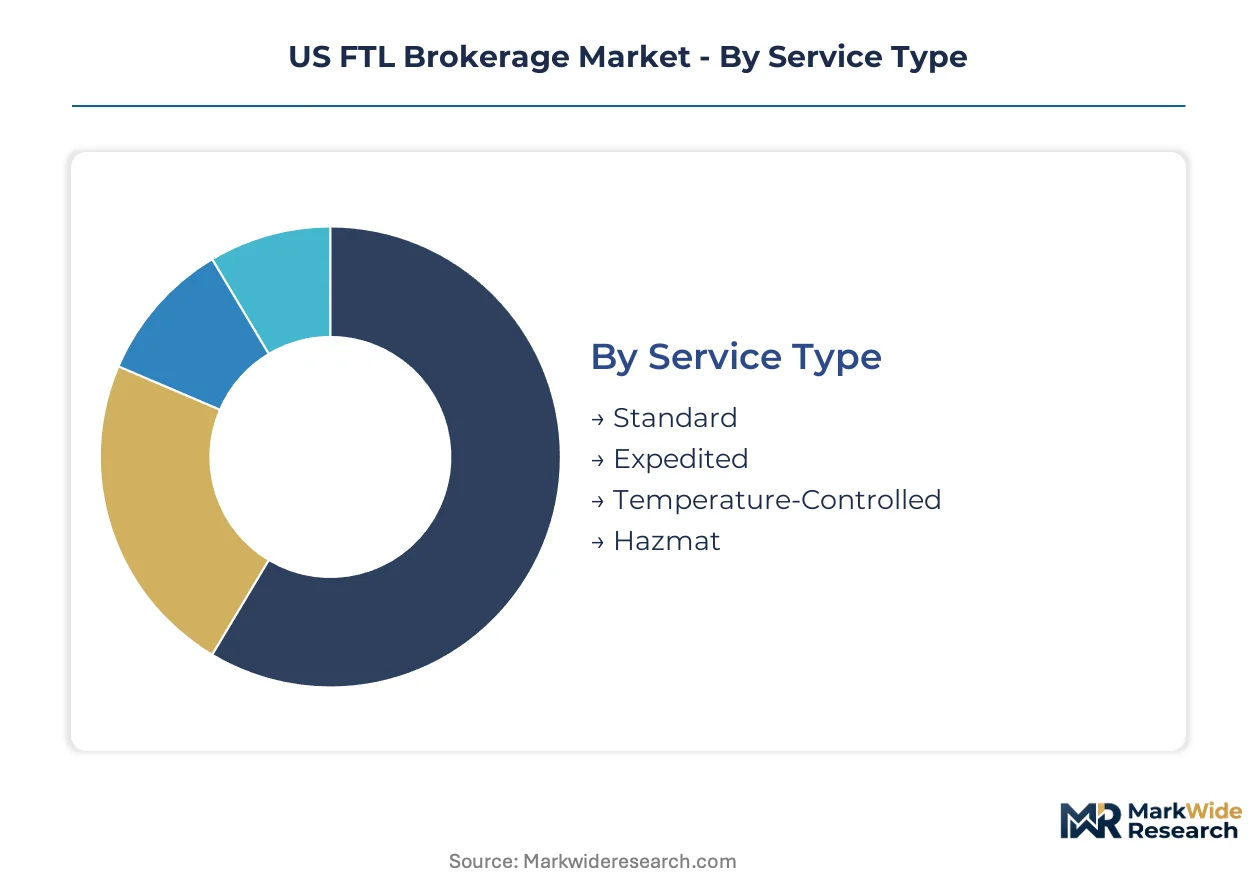
US FTL brokerage segmentation reflects how shippers prioritize speed, compliance, and cost containment when selecting intermediaries. Service type and delivery model choices directly determine carrier matching protocols and margin structures for broker networks.
Service Type:
Shipper urgency and cargo sensitivity drive service selection, with compliance requirements filtering available broker options.
- Standard:Dry van movements under conventional transit windows dominate contract freight volumes. Retail replenishment networks across Georgia, Tennessee, and the Carolinas rely on standard service for predictable inventory cycles.
- Expedited:Team-driver configurations and guaranteed delivery windows command premium positioning. Automotive manufacturers in South Carolina use expedited brokerage for just-in-sequence production support where assembly line stoppage costs dwarf freight premiums.
- Temperature-Controlled:Refrigerated units with continuous cold chain documentation serve food safety modernization requirements.
- Hazmat:Specialized carrier authority and driver endorsements restrict qualified capacity pools.
Volume sits with Standard; growth tilts toward Temperature-Controlled.
End User:
Procurement sophistication and shipment frequency separate customer tiers, with enterprise scale determining direct negotiation leverage versus broker dependence.
- Retailers:Big-box distribution centers generate recurring lane density that brokers optimize through dedicated carrier pools. Walmart and Target facilities in the Southeast corridor anchor contracted capacity commitments.
- Manufacturers:Production schedules with narrow delivery windows require broker flexibility that private fleets cannot match. Appliance producers across Tennessee depend on intermediated truckload for outbound finished goods.
- Wholesalers:Consolidated purchasing power yields mixed direct and broker-sourced capacity.
- E-Commerce:Fulfillment velocity demands strain traditional carrier relationships.
Retailers command volume leadership; E-Commerce climbs the fastest.
Delivery Model:
Handling intensity and transit time trade-offs shape network design, with damage risk and fuel efficiency competing for priority.
- Direct Delivery:Shipper-to-consignee movements without intermediate handling reduce damage exposure and transit time. Manufacturers seeking reduced touchpoints favor this model for high-value cargo.
- Hub-and-Spoke:Consolidation terminals enable density economies on lower-volume lanes. Retail replenishment networks retain this structure for predictable demand patterns.
- Dock-to-Dock:Facility-to-facility movements with shipper-loaded trailers.
- Cross-Docking:Rapid freight transfer without warehouse storage.
Hub-and-Spoke retains volume concentration; Direct Delivery gains share fastest.
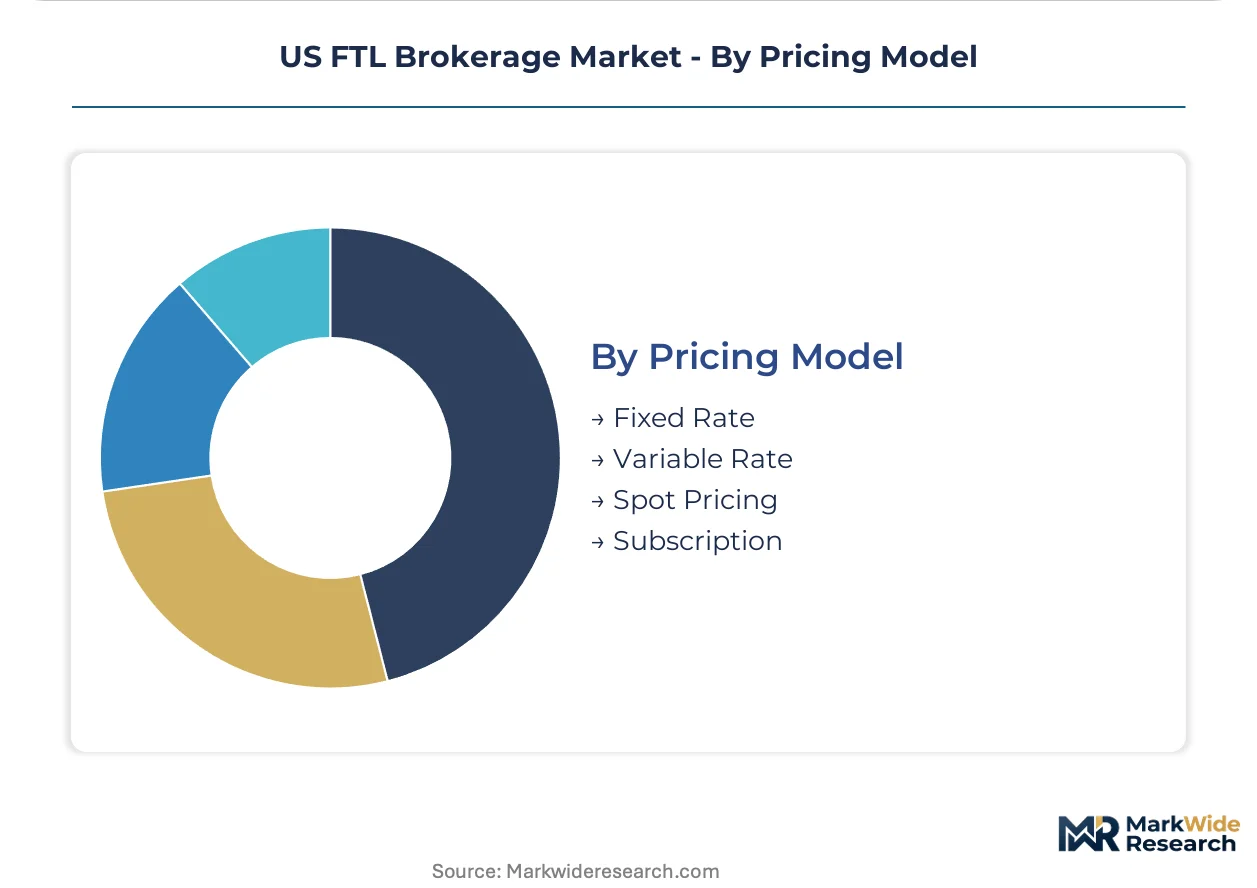
Pricing Model:
Rate certainty and market exposure allocation determine contract structures, with fuel volatility and capacity scarcity driving model selection.
- Fixed Rate:Contracted per-mile pricing insulates shippers from spot market swings. Consumer packaged goods producers prefer fixed structures for budget predictability.
- Variable Rate:Fuel surcharge-adjusted pricing transfers diesel cost exposure to shippers. Regional carriers accept variable terms to maintain lane commitment during price spikes.
- Spot Pricing:Real-time market clearing rates for unplanned movements.
- Subscription:Flat-fee capacity reservations with usage tiers.
Fixed Rate holds volume dominance; Spot Pricing shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foreign Trade Zone designations across the Southeast manufacturing corridor have concentrated FTL brokerage demand near automotive and appliance production clusters, with Georgia, Tennessee, and South Carolina anchoring the highest freight velocity corridors.
Southeast Manufacturing Belt
Automotive assembly plants and appliance manufacturing facilities generate dense outbound truckload volumes requiring intermediated capacity coordination. The FMCSA's Drug and Alcohol Clearinghouse mandates elevate broker screening costs for carriers operating across state lines. Savannah's port expansion and inland distribution hubs in Atlanta create multimodal freight convergence that brokers optimize through dedicated carrier pools.
Texas Triangle
Petrochemical complexes and energy sector supply chains demand specialized flatbed and hazmat brokerage services with strict carrier qualification protocols. The Texas Department of Transportation's freight corridor investments improve last-mile connectivity to industrial parks. Houston's energy logistics cluster and Dallas-Fort Worth's distribution center density attract broker offices seeking proximity to high-frequency shippers.
California Distribution Networks
Food safety modernization rules and pharmaceutical cold chain requirements segment brokerage toward temperature-certified carrier networks. The California Air Resources Board's clean freight regulations push shippers toward brokers with emissions-tracking capabilities. The Inland Empire's warehouse concentration and Los Angeles-Long Beach port drayage create intermodal brokerage demand for cross-country linehaul.
Midwest Industrial Corridor
Heavy machinery and agricultural equipment manufacturers rely on flatbed brokerage for oversized and project cargo movements. Illinois and Ohio state truck parking infrastructure investments address driver rest constraints that brokers must navigate in load planning. Chicago's rail intermodal terminals and Detroit's automotive supplier networks generate backhaul optimization opportunities for freight matching platforms.
Pacific Northwest
Timber, aerospace, and technology manufacturing supply chains require specialized equipment brokerage with seasonal demand fluctuations. Washington State's clean freight rules and Oregon's low-carbon fuel standards shape shipper procurement preferences. Seattle-Tacoma port traffic and Boise's distribution hub expansion create north-south lane density that regional brokers exploit through carrier relationship networks.
US FTL Brokerage Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with digital freight platforms consolidating mid-market brokerage while asset-light networks retain specialized verticals. The vendor base clusters around three strategic archetypes: technology-enabled aggregators with real-time pricing engines, relationship-driven account management firms serving enterprise shippers, and independent contractor networks minimizing fixed overhead. Dominant competitive moves include API-based TMS integration partnerships and cross-border customs brokerage capability expansion.
Within the technology-aggregator tier, C.H. Robinson and Echo Global Logistics exemplify platform-scale intermediation, while Landstar System occupies a position in the independent contractor model. Total Quality Logistics anchors the relationship-driven archetype through specialized account teams. These three patterns represent the structural alternatives available to capital deploying into freight intermediation.
| Leading Market Players |
|---|
| C.H. Robinson |
| Total Quality Logistics |
| XPO Logistics |
| Echo Global Logistics |
| Coyote Logistics |
| GlobalTranz Enterprises |
| Landstar System |
| Hub Group |
| Schneider |
| Others |
Pricing and Supply Chain Analysis
Horizontal integration across digital freight platforms anchors both supply aggregation and pricing power in the US FTL brokerage market. C.H. Robinson's Navisphere platform and Echo Global Logistics' proprietary systems consolidate fragmented carrier capacity while compressing transaction costs, creating margin structures that reward technology density over relationship scale.
Pricing Analysis
Short lead-time movements command premium positioning above standard contracted lanes, while spot inventory availability discounts reflect carrier desperation for backhaul utilization. Three-tier pricing structure across expedited, standard, and deferred service levels segments buyer willingness to pay, with automotive manufacturers least price-sensitive due to assembly line stoppage costs and retail replenishment networks most sensitive given thin merchandise margins. Cost compression in standard dry van brokerage is intensifying because digital freight matching platforms democratize carrier access and erode traditional markup structures.
Supply Chain Analysis
Reverse logistics flows—empty trailer repositioning, rejected load returns, and driver home-time routing—consume substantial broker coordination resources and inflate effective per-mile costs. Carrier supply concentrates in the Southeast manufacturing corridor, Texas Triangle, and California distribution networks, with equipment availability drawing from independent owner-operator pools, mid-sized fleet networks, and national carrier overflow capacity. Single-source vulnerability runs through the independent contractor driver pool, where Drug and Alcohol Clearinghouse disqualifications shrink qualified supply without warning. Distribution runs through hub-and-spoke consolidation terminals for retail replenishment and direct point-to-point movements for manufacturer finished goods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US FTL brokerage market functions as a vertical-integration race where platform players pursue captive carrier capacity through technology lock-in and compliance infrastructure ownership.
For Market Incumbents: Anchor market position through API-based TMS integration partnerships with Oracle and SAP shipper systems, closing automated tendering workflows that exclude smaller competitors. Deepen compliance infrastructure investment around FMCSA safety fitness monitoring and Drug and Alcohol Clearinghouse query automation, creating switching costs that protect contracted shipper relationships against digital-native challengers.
For New Entrants and Emerging Players: Regional freight broker networks represent the most penetrable channel partner type for platform technology licensing, particularly in Mexico cross-border lanes where customs brokerage capabilities remain scarce. Target temperature-controlled freight specialization as the fastest-climbing service segment, leveraging food safety modernization compliance gaps among incumbent generalists. Pursue white-label digital freight matching deployment for mid-market shippers seeking procurement transparency without enterprise TMS overhead.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by logistics conglomerates seeking technology augmentation and geographic densification. Long-term viability favors platforms with demonstrated carrier retention rates and shipper contract renewal velocity over pure transaction volume scale. Monitor FMCSA enforcement intensity and hours-of-service reform proposals as inflection indicators for broker intermediation value expansion or compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Freight Platform Integration | API connectivity with Oracle and SAP TMS systems automates tendering workflows for enterprise shippers. |
| Mexico Cross-Border Capability Expansion | Customs brokerage licensing in Nuevo León and Tamaulipas captures nearshoring freight flow premiums. |
| Temperature-Controlled Certification Investment | Food safety modernization compliance infrastructure segments broker networks toward pharmaceutical and perishable verticals. |
| Carrier Compliance Automation | FMCSA Drug and Alcohol Clearinghouse query integration reduces negligent hiring liability exposure. |
| Independent Contractor Agent Network | Asset-light capacity aggregation minimizes fixed overhead while retaining local market relationship density. |
Research Methodology
Multi-period observation of carrier capacity utilization, spot rate volatility, and broker margin compression anchored the trend analysis, supplemented by interviews with freight brokerage operations executives, shipper transportation procurement managers, carrier fleet owners, and FMCSA compliance officers. Secondary validation drew from FMCSA enforcement data, American Trucking Associations employment reports, Surface Transportation Board rate filings, and customs trade statistics. Bottom-up carrier capacity modeling and top-down shipper spend allocation triangulated market sizing across service type, delivery model, and regional corridor dimensions.
Segment-weighting approaches distributed volume and value projections across standard, expedited, temperature-controlled, and hazmat service types, with additional stratification by delivery model complexity and pricing mechanism rigidity. CAGRs were derived from regression analysis of historical freight demand elasticity against industrial production indices, retail inventory-to-sales ratios, and diesel price movements throughout the projection horizon. Forecast inputs incorporated e-commerce fulfillment network expansion trajectories, hours-of-service regulatory evolution scenarios, and driver supply demographic projections.
Caveats apply where FMCSA safety fitness reform implementation pace, autonomous truck deployment timelines, or macroeconomic inventory destocking cycles could materially shift the outlook. Practitioners should monitor carrier bankruptcy filing rates, shipper direct contracting announcements, and port congestion indices for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Flat Rack Containers Market
Logistics and Shipping
Global 3PL in Cold Chain Logistics Market
Logistics and Shipping
Global Port Logistics Market
Logistics and Shipping
Food Delivery Logistic Market
Logistics and Shipping
Digital Freight Forwarder Market
Logistics and Shipping
Canada Freight and Logistics Market
Logistics and Shipping
Thailand E-Commerce Logistics Market
Logistics and Shipping
Europe Automotive Logistics Market
Logistics and Shipping
Europe Courier, Express and Parcel (CEP) Market
Logistics and Shipping
Latin America Stevedoring and Marine Cargo Handling Market
Logistics and Shipping
Military Logistics Market
Logistics and Shipping
Tanker Cargo Ship Market
Logistics and Shipping
Global Load Planning Services and Solutions Market
Logistics and Shipping
Empty Container Repositioning Optimization Platforms Market
Logistics and Shipping
Digital Freight Matching Market
Logistics and Shipping
Inbound Logistics Market