
 Asia Pacific Freight and Logistics Market | 2026-2036
Asia Pacific Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Freight and Logistics Market Outlook
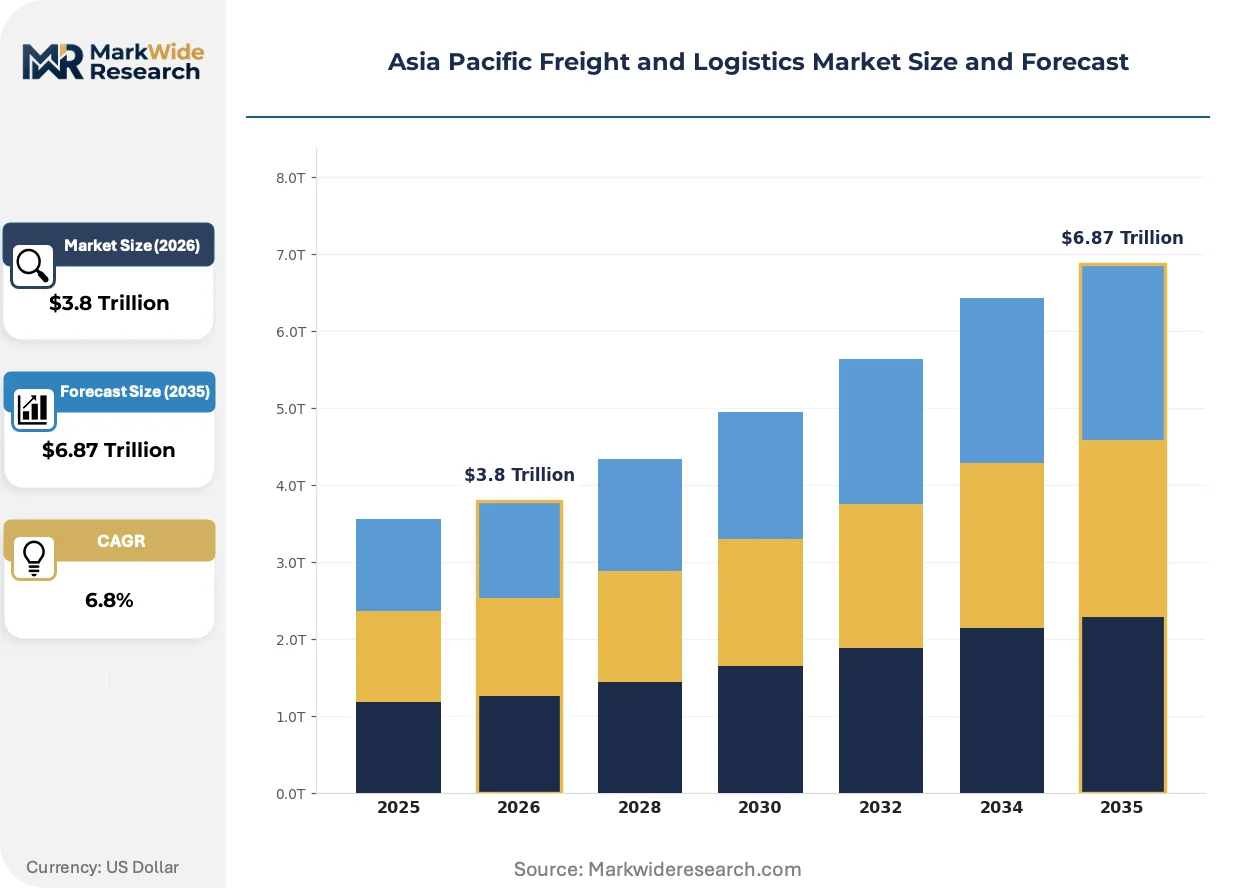
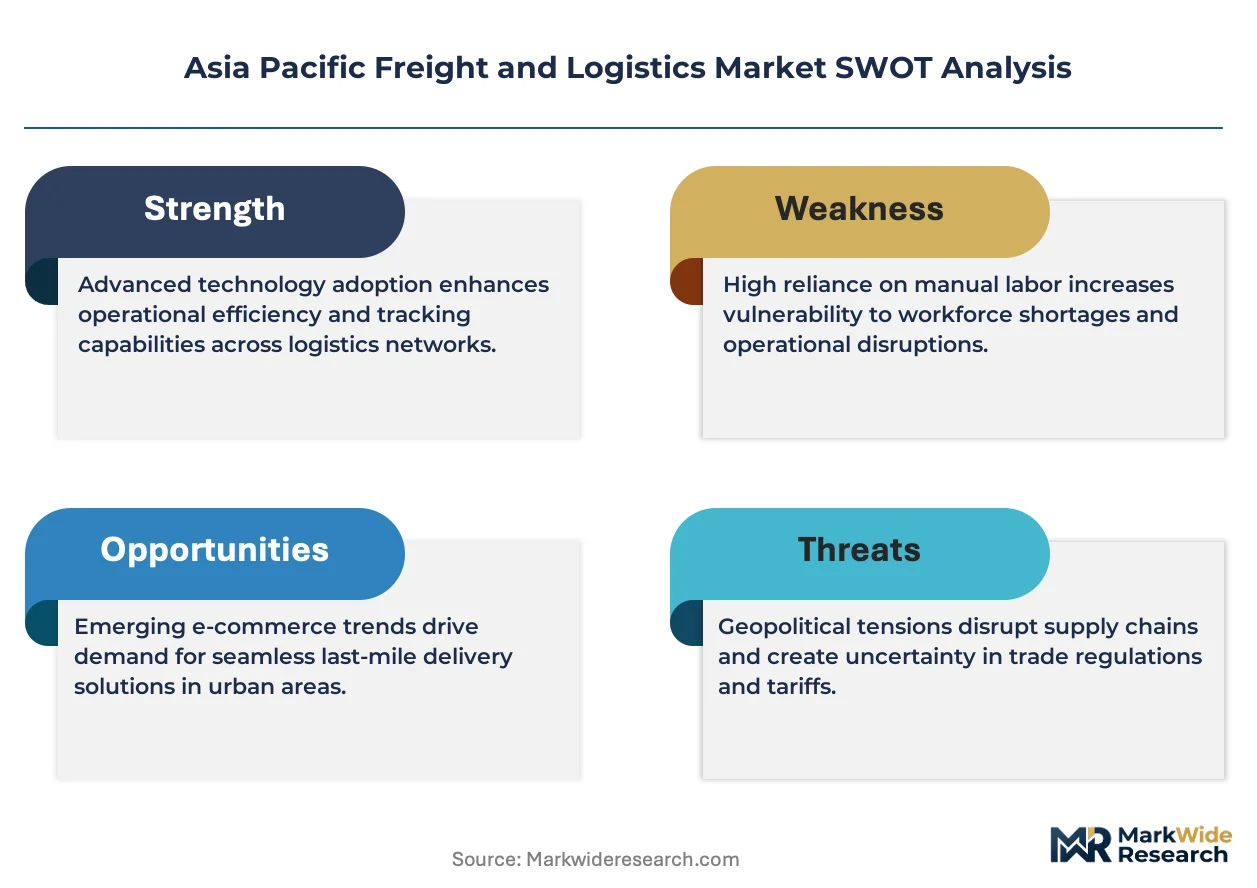
China's dual carbon goals is hardening emissions accountability across multimodal networks. DHL Group leverages its Asia-Pacific air freight hub network to sustain temperature-controlled pharmaceutical corridors. SF Express anchors intra-Asia express delivery through its integrated ground-air infrastructure.
Asia Pacific freight and logistics encompasses the physical movement, storage, and customs facilitation of goods across road, air, sea, and rail networks, typically operating through containerized units measured in twenty-foot equivalent units with tracking precision to the pallet level. The sector's primary commercial purpose is synchronizing inventory velocity with manufacturing takt times across extended supply chains. Transportation commands the largest revenue pool but carries thin margins, while warehousing absorbs capital as automated storage and retrieval systems reshape facility economics. E-commerce end users are pulling fastest growth as same-day and next-day service levels reconfigure last-mile node placement.
China's MEE enforces carbon intensity benchmarks on port and trucking operations, while India's CEA mandates renewable energy share targets for logistics parks above threshold consumption levels. Japan's METI guides modal shift policies that divert containerized freight from road to coastal shipping corridors. Stakeholders must monitor how fragmented national carbon accounting rules will interact with cross-border digital customs platforms.
Market Dynamics
China's MEE carbon intensity benchmarks and India's CEA renewable energy mandates are forcing multimodal operators to reconfigure fuel sourcing, fleet composition, and warehouse energy profiles across the region's busiest corridors.
Growth Catalysts
- E-commerce Fulfillment Density:Southeast Asian platforms are pulling automated sortation and micro-fulfillment center placement into secondary cities. Last-mile node expansion absorbs excess warehousing capacity in Indonesia and Vietnam.
- CEA Renewable Mandates:India's Central Electricity Authority requires logistics parks above threshold consumption to source specified renewable energy shares. This accelerates solar rooftop deployment across Delhi-Mumbai industrial freight corridors.
- Pharmaceutical Cold Chain Expansion:Temperature-controlled pharmaceutical corridors are multiplying as regional vaccine manufacturing and biologics distribution scale. Dedicated reefer container fleets and validated packaging protocols are proliferating.
Market Restraints
- Marine Fuel Cost Volatility:Low-sulfur fuel oil and LNG bunker price swings compress container shipping margins on intra-Asia routes. Carriers struggle to pass full cost recovery through annual contract structures.
- Trucking Fleet Fragmentation:Owner-operator dominance across India and Southeast Asia limits fleet standardization and telematics penetration. Emissions monitoring and driver hour compliance remain inconsistent.
- Cross-Border Customs Friction:ASEAN's incomplete digital customs harmonization creates documentation bottlenecks at Thailand-Myanmar and Vietnam-Cambodia border crossings. Physical inspection rates vary unpredictably.
Strategic Opportunities
- India's Dedicated Freight Corridors:The Eastern and Western Dedicated Freight Corridors are opening contract logistics capacity in manufacturing clusters around Pune, Chennai, and the Delhi-Mumbai Industrial Corridor. Rail-sea intermodal integration remains underdeveloped.
- EU AI Act Extraterritorial Reach:Supply chain transparency requirements for EU-bound exports are pulling traceability technology adoption into Asian supplier networks. Blockchain-anchored documentation systems are gaining traction.
- Autonomous Yard Operations:Convergence of lidar perception systems and 5G private networks is automating container terminal yard management. Port operators in Singapore and Busan are deploying pilot fleets.
Industry Challenges
- Warehouse Automation Talent Scarcity:Maintenance technicians for automated storage and retrieval systems and robotic picking cells are in short supply across Southeast Asian logistics markets. Technical training pipelines lag installation schedules.
- Legacy WMS Integration Complexity:Brownfield facilities struggle to overlay IoT sensor networks and AI-driven demand forecasting onto decades-old warehouse management architectures. Data standardization gaps persist between tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Freight and Logistics Market |
| Market Size in 2026 | $3.8 Trillion |
| Market Size in 2035 | $6.87 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Customs Brokerage End User: E-commerce, Retail, Manufacturing, Automotive Technology: IoT, Blockchain, AI, Automation Distribution Channel: Road, Air, Sea, Rail |
| Companies Covered | SF Express, United Parcel Service of America, Inc. (UPS), DHL Group, CJ Logistics Corporation, JD Logistics, Kuehne+Nagel, NYK (Nippon Yusen Kaisha) Line, SG Holdings Co., Ltd., Sinotrans, Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Freight and Logistics Market Strategic Shifts
Digital freight platforms and autonomous systems are compressing procurement cycles and reconfiguring asset ownership models across Asia Pacific's fragmented trucking and warehousing markets.
Automated storage and retrieval systems paired with autonomous mobile robots are automating e-commerce fulfillment operations in Southeast Asian markets. Third-party logistics providers in Indonesia and Thailand are deploying these technologies to meet same-day delivery service levels. The technology is automating pallet-to-person workflows and compressing labor dependency in high-turnover warehouse environments.
China's dual carbon goals enforced by MEE are hardening emissions accountability benchmarks across port and trucking operations. Multimodal operators must now document fuel consumption and carbon intensity at the lane level for regulatory compliance. Pharmaceutical and electronics exporters face the steepest documentation requirements as EU-bound shipments trigger supply chain transparency audits.
Consolidation of procurement authority among large e-commerce platforms is compressing logistics provider switching cycles and unbundling service components. Marketplace sellers increasingly source warehousing, last-mile delivery, and returns processing from separate specialized operators rather than integrated 3PLs. This pattern is most visible in India's tier-one cities where platform scale enables direct carrier negotiations.
Asia Pacific Freight and Logistics Market Segmentation
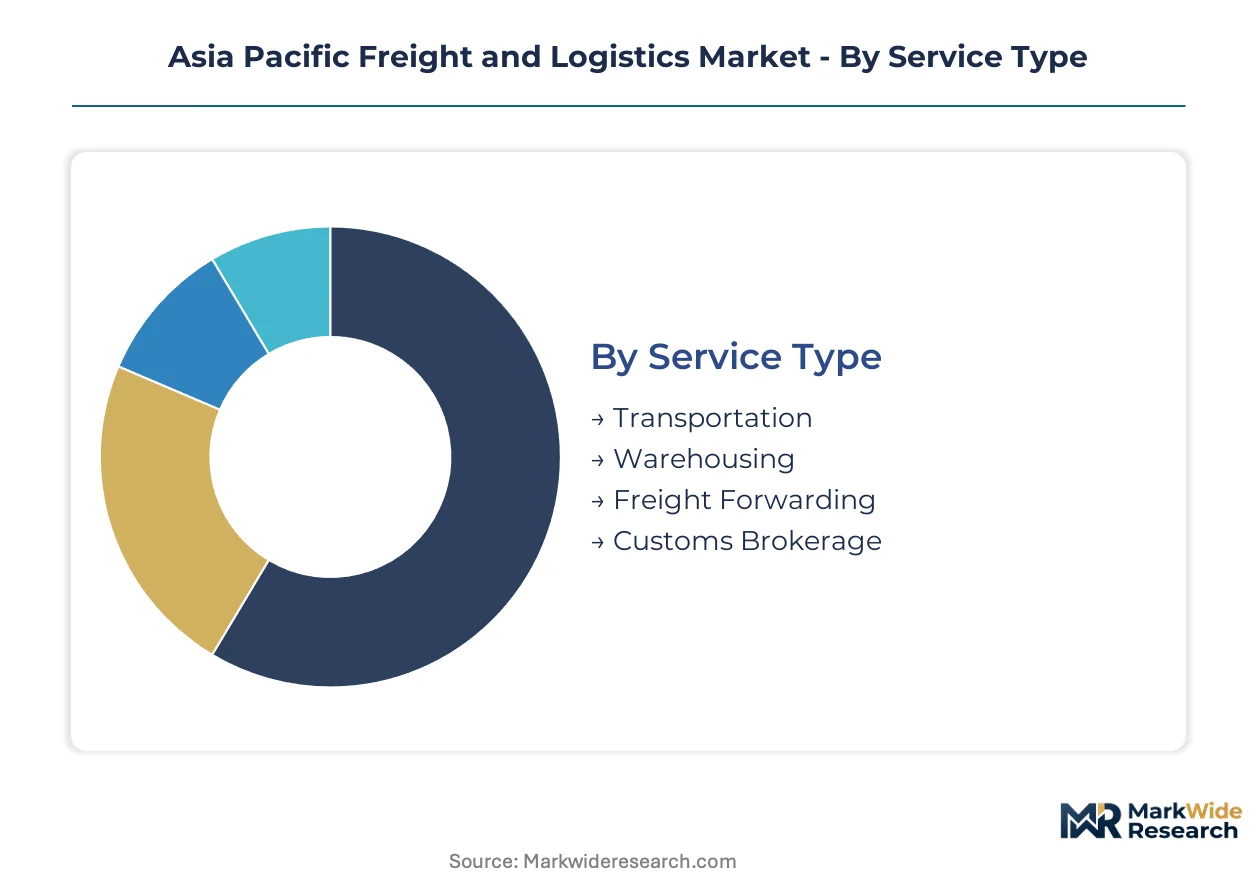
Segmentation across service types, technologies, and distribution channels reveals how capital allocation and regulatory pressure are splitting competitive advantage in Asia Pacific freight and logistics. Understanding these fault lines clarifies where margin pools concentrate and where infrastructure investments face the steepest payback periods.
Service Type:
Service type segmentation tracks how value migrates between asset-heavy transportation operations and capital-light coordination functions across multimodal networks.
- Transportation:Asset-intensive road, air, sea, and rail carriage commands the largest revenue pool but operates on thin margins. Fleet ownership in India and Southeast Asia concentrates among fragmented owner-operators, limiting standardization. China's MEE carbon intensity benchmarks are forcing fuel switching and telematics adoption on domestic trucking corridors.
- Warehousing:Automated storage and retrieval systems paired with autonomous mobile robots are reshaping facility economics. E-commerce fulfillment density in Indonesia and Vietnam is pulling micro-fulfillment center placement into secondary cities. India's CEA renewable energy mandates accelerate solar rooftop deployment across Delhi-Mumbai industrial freight corridors.
- Freight Forwarding:Non-asset-based coordination of multimodal shipments, documentation, and carrier procurement. Demand concentrates on EU-bound exports where the EU AI Act's supply chain transparency requirements trigger traceability technology adoption.
- Customs Brokerage:Documentation preparation, tariff classification, and regulatory compliance facilitation. ASEAN's incomplete digital customs harmonization creates bottlenecks at Thailand-Myanmar and Vietnam-Cambodia border crossings.
Transportation leads on scale; warehousing leads on momentum.
End User:
End user segmentation maps how inventory velocity requirements and service level specifications vary across demand clusters.
- E-commerce:Same-day and next-day service levels are reconfiguring last-mile node placement across Southeast Asian platforms. Consolidation of procurement authority among large marketplaces is compressing logistics provider switching cycles and unbundling service components.
- Manufacturing:Synchronization with takt times across extended supply chains drives demand for precision scheduling. India's Eastern and Western Dedicated Freight Corridors are opening contract logistics capacity in clusters around Pune, Chennai, and the Delhi-Mumbai Industrial Corridor.
- Automotive:Just-in-sequence delivery requirements and component traceability standards. Electrification transitions are reshaping inbound parts logistics toward battery cell and module transportation.
- Retail:Seasonal demand volatility and returns processing complexity. Traditional retail networks compete with platform-direct fulfillment models for warehousing space in tier-one cities.
Manufacturing anchors volume throughput; e-commerce commands the steepest expansion trajectory.
Technology:
Technology segmentation distinguishes between connectivity infrastructure, decision automation, and physical system autonomy.
- IoT:Sensor networks for real-time location tracking, environmental monitoring, and predictive maintenance. Deployment concentrates on pharmaceutical cold chains where temperature excursions trigger compliance failures.
- AI:Demand forecasting, route optimization, and warehouse labor allocation algorithms. Legacy WMS integration complexity in brownfield facilities limits deployment speed across Southeast Asian markets.
- Automation:Automated storage and retrieval systems, robotic picking cells, and autonomous mobile robots. Maintenance technician scarcity constrains installation schedules in Indonesia and Thailand.
- Blockchain:Immutable documentation for supply chain transparency and customs facilitation. EU AI Act extraterritorial reach is pulling adoption into Asian supplier networks for EU-bound shipments.
IoT dominates installed base; automation captures the fastest capital deployment.
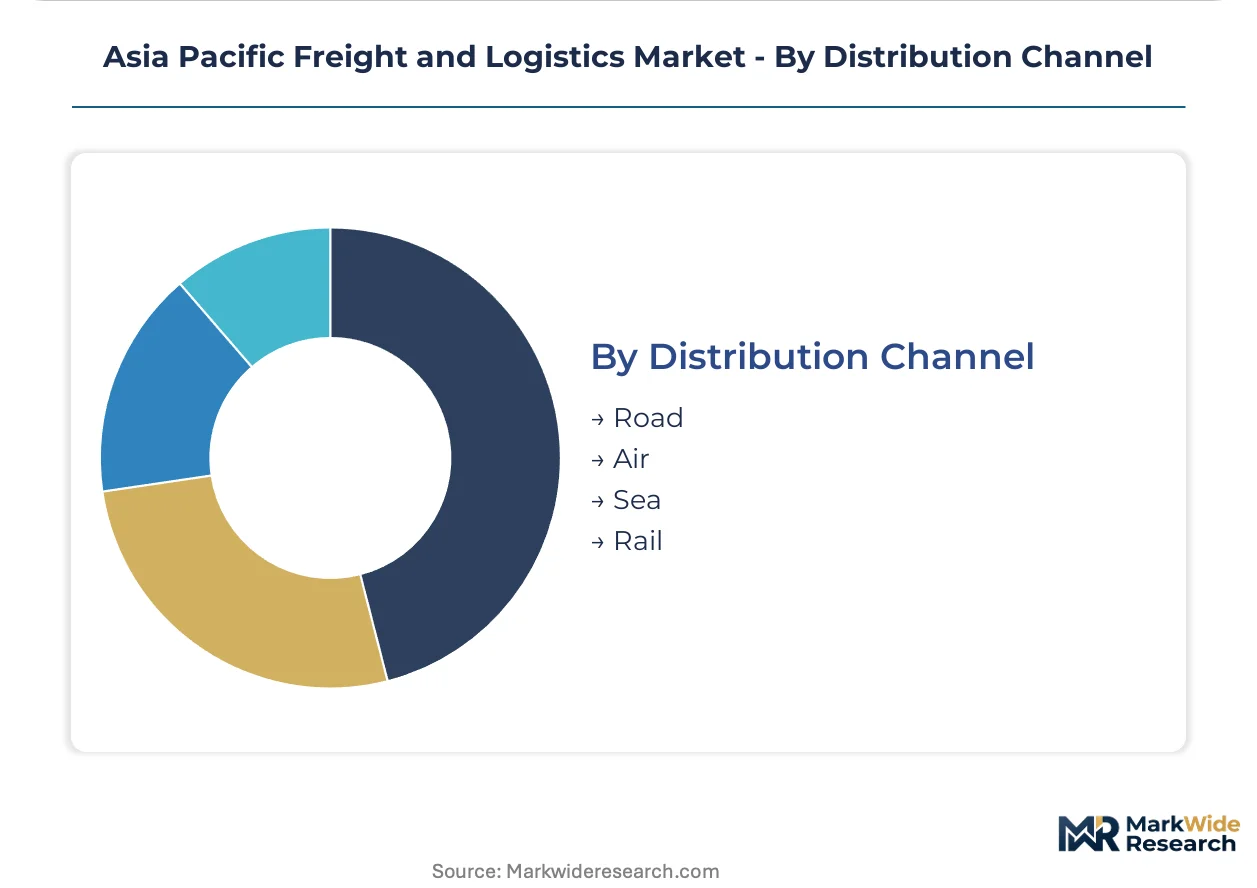
Distribution Channel:
Distribution channel segmentation reflects modal economics and infrastructure maturity across the region's geography.
- Road:Dominant mode for last-mile delivery and short-haul intercity freight. Owner-operator fragmentation across India and Southeast Asia limits emissions monitoring and driver hour compliance standardization.
- Sea:Containerized movement on intra-Asia and deep-sea routes. Low-sulfur fuel oil and LNG bunker price volatility compresses carrier margins on annual contract structures.
- Air:Time-critical and temperature-controlled cargo, particularly pharmaceuticals. DHL Group leverages its Asia-Pacific hub network to sustain dedicated pharmaceutical corridors.
- Rail:Bulk commodities and containerized freight on dedicated corridors. India's rail-sea intermodal integration remains underdeveloped despite Eastern and Western Dedicated Freight Corridor expansion.
Road holds volume dominance; rail offers the largest untapped efficiency gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asia Pacific freight and logistics traces its modern scaling to Japan's post-war port infrastructure development and Singapore's 1970s container terminal investments, which established the region's first multimodal transshipment capabilities.
China
E-commerce fulfillment density and pharmaceutical cold chain expansion drive warehouse automation investments in the Yangtze River Delta. MEE carbon intensity benchmarks enforce fuel switching and telematics adoption on domestic trucking corridors. Shanghai and Shenzhen container terminals are deploying autonomous yard management systems under 5G private networks.
India
Manufacturing corridor development and dedicated freight rail expansion absorb contract logistics capacity across industrial clusters. CEA renewable energy mandates accelerate solar rooftop deployment in logistics parks above threshold consumption levels. Pune and Chennai manufacturing hubs are integrating rail-sea intermodal services along the Delhi-Mumbai Industrial Corridor.
Japan
Automotive just-in-sequence delivery and electronics component traceability sustain precision logistics demand. METI modal shift policies divert containerized freight from road to coastal shipping corridors. Osaka and Nagoya industrial zones are consolidating pharmaceutical cold chain infrastructure for regional biologics distribution.
Singapore
Transshipment volume growth and bunkering hub status attract maritime service specialization. Port Authority mandates on low-carbon terminal operations align with EU-bound supply chain transparency requirements. Tuas Port development is integrating autonomous container handling with blockchain-anchored documentation systems.
Vietnam
Electronics manufacturing relocation and e-commerce platform expansion pull automated sortation into secondary cities. Customs modernization programs address ASEAN digital harmonization gaps at border crossings. Ho Chi Minh City and Hanoi logistics zones are deploying micro-fulfillment centers for same-day delivery service levels.
Asia Pacific Freight and Logistics Market Competitive Environment
Premium-margin players sit above commodity-margin players across service integration depth and technology deployment intensity. The market structures around three tiers: integrated express networks with owned air-ground infrastructure, asset-light freight forwarders with digital platform scale, and regional specialists with corridor-specific density. Consolidation pressure concentrates among forwarders seeking forward integration into contract logistics, while express operators defend position through last-mile node expansion.
Within the integrated express tier, SF Express and DHL Group exemplify archetypes of ground-air infrastructure control and pharmaceutical corridor specialization respectively. JD Logistics occupies a position between platform-captive and third-party service models. United Parcel Service of America, Inc. anchors the multinational integrator archetype with density across tier-one Asian markets.
| Leading Market Players |
|---|
| SF Express |
| United Parcel Service of America, Inc. (UPS) |
| DHL Group |
| CJ Logistics Corporation |
| JD Logistics |
| Kuehne+Nagel |
| NYK (Nippon Yusen Kaisha) Line |
| SG Holdings Co., Ltd. |
| Sinotrans, Ltd. |
| Others |
Value Chain & Pricing Dynamics
Low-sulfur fuel oil and LNG bunker price indices cascade through Asia Pacific freight networks, compressing container shipping margins and forcing carriers to renegotiate annual contract structures with manufacturing exporters. This cost volatility splits pricing power between asset-heavy operators with captive fuel hedging and fragmented owner-operators exposed to spot market swings.
Pricing Analysis
Contract-based long-term offtake with volume-tiered adjustments dominates Asia Pacific freight procurement, separating integrated express networks with guaranteed capacity from spot-market trucking brokers. Price differentiation rests on service level guarantees and carbon intensity documentation quality, with EU-bound pharmaceutical shipments commanding premiums for MEE-compliant traceability. Cost compression in coastal container routes is intensifying as low-sulfur fuel oil volatility erodes carrier margins. Small-scale Indonesian and Vietnamese logistics providers exhibit the highest price sensitivity, while multinational pharmaceutical cold chain operators absorb premium pricing with minimal volume elasticity.
Supply Chain Analysis
Reefer container manufacturing and lidar sensor production rest on concentrated Chinese and South Korean industrial bases, with secondary sourcing from Japanese precision optics suppliers. Automated sortation equipment and 5G private network hardware feed from these hubs into Southeast Asian fulfillment center deployments. Single-source vulnerability concentrates in pharmaceutical cold chain packaging validation protocols, where EU AI Act documentation requirements tether suppliers to certified providers. Distribution runs through tiered port-terminal-warehouse networks, with Singapore and Busan anchoring transshipment before last-mile fragmentation across India and Indonesia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific freight and logistics operates as a late-cycle quality story, with pharmaceutical cold chain specifications and carbon intensity documentation emerging as non-negotiable buyer criteria that filter out undifferentiated capacity providers.
For Market Incumbents: Anticipate margin compression from platform-direct procurement models by deepening captive renewable energy assets under India's CEA mandates and securing MEE-compliant telematics coverage across domestic China trucking fleets. Vertical integration into solar-roofed logistics parks offers defensive positioning against energy cost volatility.
For New Entrants and Emerging Players: Autonomous yard management systems present a technology-first wedge into Southeast Asian port automation, where 5G private network deployment lags Singapore and Busan benchmarks. Target Vietnam's electronics manufacturing corridors for micro-fulfillment center placement, leveraging customs modernization programs to bypass ASEAN digital harmonization gaps.
For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented owner-operator trucking markets meet renewable energy compliance thresholds, creating rollup opportunities for telematics-enabled fleet operators. Five-to-ten-year viability favors contract logistics providers with dedicated freight corridor density in India's Pune-Chennai manufacturing belt. Watch for EU AI Act enforcement intensity as the inflection signal for traceability technology valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Energy Integration | CEA-mandated solar deployment in Delhi-Mumbai logistics parks secures operating cost advantages. |
| Autonomous Terminal Operations | 5G-enabled yard management at Shanghai and Shenzhen ports reduces container dwell times. |
| Pharmaceutical Corridor Specialization | Temperature-validated reefer networks capture EU-bound vaccine and biologics distribution premiums. |
| Rail-Sea Intermodal Expansion | Eastern and Western Dedicated Freight Corridors unlock contract logistics capacity near manufacturing clusters. |
| Blockchain Documentation Systems | Immutable supply chain records satisfy EU AI Act transparency audits for electronics exporters. |
Study Parameters
Direct dialogue with fleet operations directors, port authority technology officers, pharmaceutical logistics procurement managers, and e-commerce platform supply chain leads grounded qualitative assessment, cross-referenced against customs trade databases, MEE enforcement disclosures, CEA renewable energy compliance filings, and dedicated freight corridor project documentation. Bottom-up carrier capacity modeling and top-down manufacturing output projections were triangulated against regional trade flow data.
Top-down macroeconomic indicators and bottom-up facility-level capacity assessments converged across the projection horizon, with segmentation modeling across service type, end user industry, technology deployment intensity, and distribution channel modal share. CAGRs were derived from trend extrapolation of e-commerce fulfillment density, pharmaceutical cold chain expansion rates, and regulatory compliance cost pass-through elasticity. Forecast inputs incorporated MEE carbon intensity benchmark enforcement trajectories and EU AI Act extraterritorial compliance adoption curves.
The model holds under stable regulatory enforcement intensity and bunker fuel price corridor assumptions; deviation in ASEAN digital customs harmonization progress or China dual carbon goal acceleration would shift capacity allocation timelines. A small set of named triggers—EU AI Act audit frequency, India dedicated freight corridor completion rates, and Indonesia warehouse automation talent pipeline expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Global 3PL Market
Logistics and Shipping
Global Sea Air Logistics Market
Logistics and Shipping
Australia Last Mile Delivery Market
Logistics and Shipping
Sustainable Logistics Market
Logistics and Shipping
Event Logistics Market
Logistics and Shipping
Latin America Cold Chain Logistics Market
Logistics and Shipping
Digital Freight Management Market
Logistics and Shipping
Multi-Enterprise Logistics Contract and SLA Performance Management Platforms Market
Logistics and Shipping
Japan Cross-Border E-Commerce Logistics Market
Logistics and Shipping
Chile Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
APAC Contract Logistics Market
Logistics and Shipping
North America Freight Brokerage Market
Logistics and Shipping
China Cold Chain Logistics Market
Logistics and Shipping
Halal Logistics Market
Logistics and Shipping
Switzerland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
GCC Automotive Logistics Market