
 Global Port Logistics Market | 2026-2036
Global Port Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Port Logistics Market Outlook
Asset-light port concession leasing is reconfiguring competitive entry barriers for mid-sized operators. A.P. Møller – Maersk A/S leverages its integrated logistics platform to control end-to-end container flows. COSCO Shipping Holdings anchors its position through state-backed terminal ownership across strategic chokepoints. DP World differentiates via automated stacking crane deployment at Jebel Ali and London Gateway.
Port logistics encompasses the coordinated movement of vessels, cargo, and information through maritime interfaces, requiring gantry cranes with 65-tonne lift capacity and terminal operating systems processing 30+ vessel exchanges daily. Its primary purpose is minimizing vessel turnaround time while maximizing throughput per hectare of quay. Container shipping commands the dominant application share as mega-vessel deployment concentrates volume at deepwater hubs. Bulk cargo handling retains stable margin pools in grain and ore trades where specialized grab unloaders create equipment moats. Project cargo represents the fastest-growing application segment as offshore wind component dimensions exceed standard container specifications.
The International Maritime Organization enforces carbon intensity indicators that mandate fleet efficiency improvements, while the EU Green Deal's FuelEU Maritime regulation shapes European terminal electrification investment timelines. China's MIIT coordinates domestic port automation standards through its smart port demonstration program. Stakeholders must monitor regulatory divergence between IMO baseline targets and regional unilateral measures when allocating capital across terminal networks.
Market Dynamics
The International Maritime Organization's carbon intensity regulations are compressing terminal operators' capital deployment timelines, forcing simultaneous electrification of cargo handling equipment and vessel fuel transitions while mega-vessel deployment concentrates throughput at deepwater hubs with sufficient quay depth and gantry crane capacity.
Growth Catalysts
- E-commerce fulfillment networks:Direct-to-consumer distribution models are intensifying demand for container throughput capacity at transshipment hubs serving last-mile distribution centers.
- IMO carbon intensity indicators:The regulatory mandate for fleet efficiency improvements is accelerating terminal electrification investments and creating equipment replacement cycles.
- Offshore wind component logistics:Project cargo dimensions exceeding standard container specifications are driving specialized heavy-lift quay investments at North Sea and Baltic port clusters.
Market Restraints
- Quay land scarcity:Coastal urbanization in China's Pearl River Delta and Rotterdam-Amsterdam-Antwerp corridor limits greenfield terminal expansion.
- Electrification capital intensity:Grid connection upgrades and battery-powered gantry crane deployments require sustained capex commitments without immediate throughput gains.
- Specialized equipment supplier concentration:Automated stacking crane and terminal operating system vendors cluster in Northern Europe and East Asia, creating procurement bottlenecks.
Strategic Opportunities
- India's Sagarmala port modernization:The national infrastructure program is unlocking concession opportunities for automated container terminal development at Visakhapatnam and Chennai.
- FuelEU Maritime regulatory tailwind:The EU Green Deal's bunkering infrastructure mandates are creating shore power and alternative fuel terminal upgrade demand across Mediterranean and North European ports.
- Blockchain-IoT convergence:Distributed ledger systems integrated with container tracking sensors are enabling real-time cargo visibility platforms that reduce documentation friction.
Industry Challenges
- Maritime automation engineering talent:Terminal operating system integration and predictive maintenance algorithm deployment require skill sets concentrated among Northern European and East Asian specialists.
- Legacy equipment interoperability:Electrified crane fleets must interface with existing terminal operating systems without disrupting vessel exchange schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Port Logistics Market |
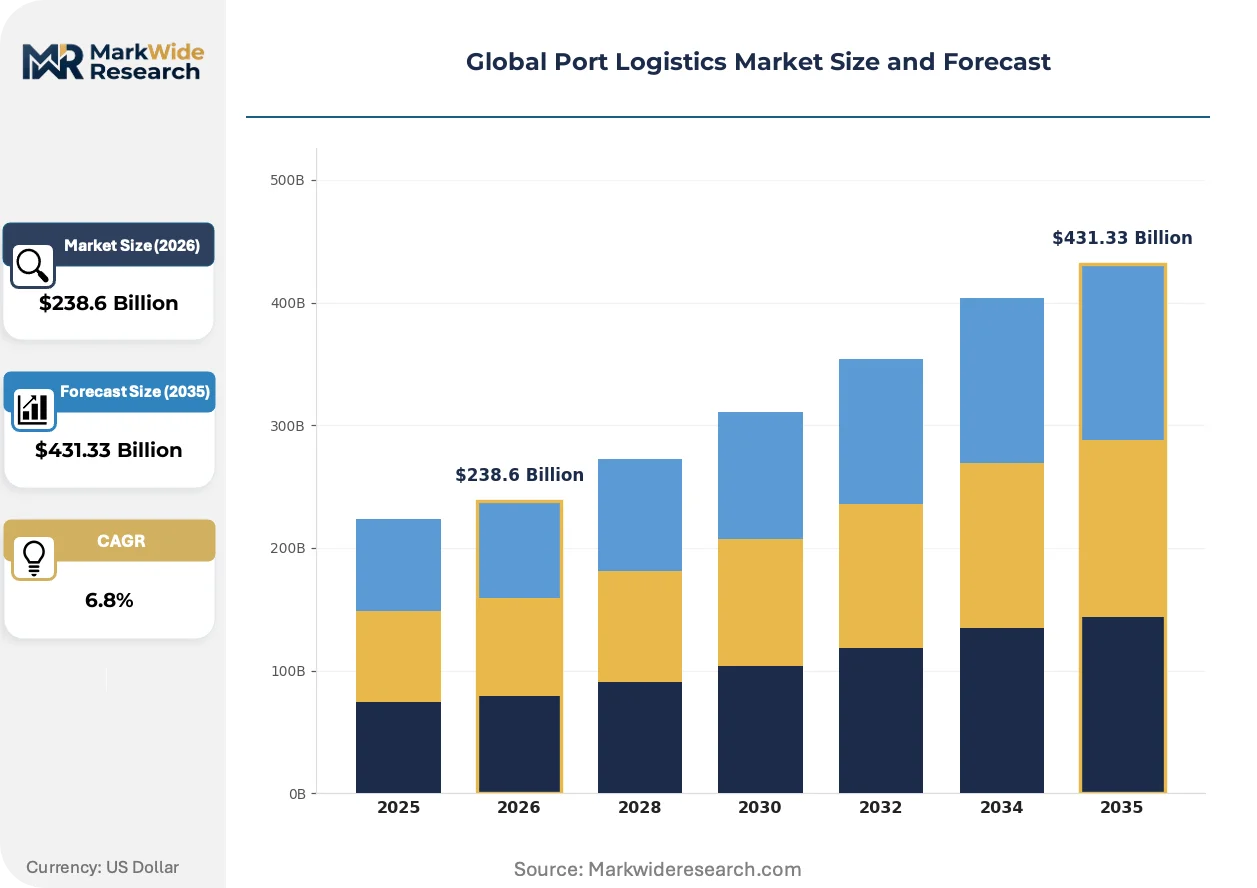
| Market Size in 2026 | $238.6 Billion |
| Market Size in 2035 | $431.33 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Loading Services, Unloading Services, Storage Solutions, Freight Forwarding End User: Shipping Lines, Importers, Exporters, Freight Brokers Technology: Automated Systems, Tracking Software, Cargo Handling Equipment, Robotic Process Automation Application: Container Shipping, Bulk Cargo Handling, Project Cargo, Ro-Ro Services |
| Companies Covered | CMA CGM Group, Evergreen Marine Corp., A.P. Møller – Maersk A/S, HMM Co. Ltd., Ocean Network Express, COSCO Shipping Holdings, Mediterranean Shipping Company, DP World, Hapag-Lloyd AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Port Logistics Market Strategic Shifts
Terminal automation and regulatory compliance requirements are converging to reshape capital allocation patterns across maritime infrastructure, with digital twins and predictive maintenance systems emerging as competitive differentiators alongside electrified cargo handling equipment.
Digital twin platforms are replicating physical terminal operations in real-time simulation environments. Rotterdam's Maasvlakte terminals and Singapore's Tuas megaport are deploying these systems to optimize vessel berthing sequences and crane deployment patterns. The technology is digitizing maintenance scheduling and reducing unplanned equipment downtime through predictive algorithm alerts.
The EU Green Deal's FuelEU Maritime regulation is mandating progressive greenhouse gas intensity reductions for vessel bunkering. Terminal operators at Hamburg, Algeciras, and Piraeus must install shore power connections and alternative fuel infrastructure by specified compliance deadlines. Container shipping lines with European service rotations are prioritizing port calls at terminals with certified low-carbon fuel availability.
Shippers are consolidating procurement relationships around integrated logistics providers capable of controlling container flows from origin factory to destination warehouse. This concentration is displacing fragmented freight forwarder networks in Asia-Europe and trans-Pacific trade lanes. The shift is most visible among consumer electronics and automotive component supply chains originating in China's manufacturing clusters.
Global Port Logistics Market Segmentation
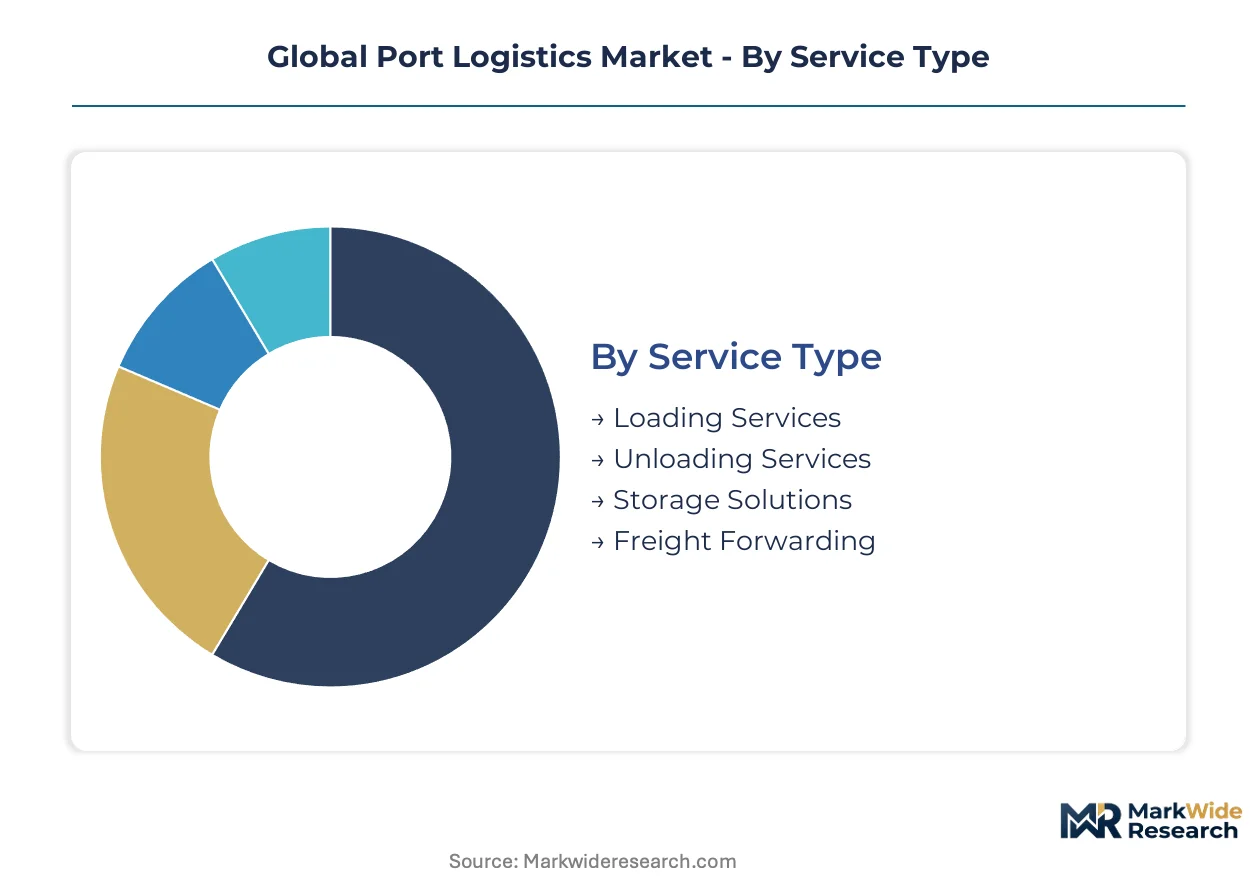
Port logistics segmentation reveals how service specialization, technology deployment, and cargo characteristics fragment capital allocation across terminal networks. Understanding these dimensions clarifies where automation investments concentrate and which customer relationships command premium pricing power.
Service Type:
Cost tier differentiation separates commoditized labor services from integrated solutions commanding long-term contracts.
- Loading Services:Gantry crane operations and vessel stowage planning coordinate container placement aboard mega-vessels. Demand concentrates at deepwater hubs in Rotterdam and Singapore where 24,000 TEU vessel calls require precision sequencing.
- Unloading Services:Quay crane discharge and yard transfer operations determine vessel turnaround metrics. Specialized grab unloaders for bulk commodities create equipment moats at grain and ore terminals in Brazil and Australia.
- Storage Solutions:Bonded warehousing and reefer container yards extend terminal revenue capture beyond vessel exchange windows.
- Freight Forwarding:Documentation and customs brokerage integration links maritime interfaces to inland distribution networks.
Loading and unloading services command the established base. The steepest expansion runs through storage solutions as e-commerce fulfillment extends dwell time monetization.
End User:
Customer type determines contract structure, with asset owners prioritizing throughput guarantees and intermediaries seeking flexibility.
- Shipping Lines:Ocean carriers negotiate terminal service agreements tied to vessel deployment schedules and volume commitments. MSC and CMA CGM anchor demand at transshipment hubs where alliance coordination requires dedicated berthing windows.
- Importers:Retail and manufacturing consignees procure port services through logistics platforms controlling inbound supply chains. Electronics and automotive manufacturers in Germany and South Korea drive demand for time-definite container availability.
- Exporters:Agricultural and industrial shippers require seasonal surge capacity and specialized equipment for oversized cargo.
- Freight Brokers:Intermediary networks aggregate fragmented shipper demand across non-vessel-operating common carrier relationships.
Shipping lines command the established base. The steepest expansion runs through importers as direct procurement displaces forwarder intermediation.
Technology:
Maturity gradients separate proven automation from experimental deployments requiring integration risk tolerance.
- Automated Systems:Automated stacking cranes and guided vehicle fleets reduce labor dependency and improve yard density. Rotterdam's Maasvlakte and Singapore's Tuas megaport anchor deployment at greenfield terminals where legacy equipment constraints are absent.
- Tracking Software:Terminal operating systems and vessel scheduling platforms digitize cargo visibility and berth allocation. Northern European and East Asian specialist vendors concentrate supply, creating procurement bottlenecks for mid-sized operators.
- Cargo Handling Equipment:Electrified gantry cranes and straddle carriers address IMO carbon intensity compliance requirements.
- Robotic Process Automation:Back-office document processing and customs declaration automation reduce administrative labor in documentation flows.
Cargo handling equipment commands the established base. The steepest expansion runs through automated systems as labor cost differentials and carbon regulations accelerate replacement cycles.
Application:
Volume characteristics and equipment specialization create distinct margin profiles across cargo categories.
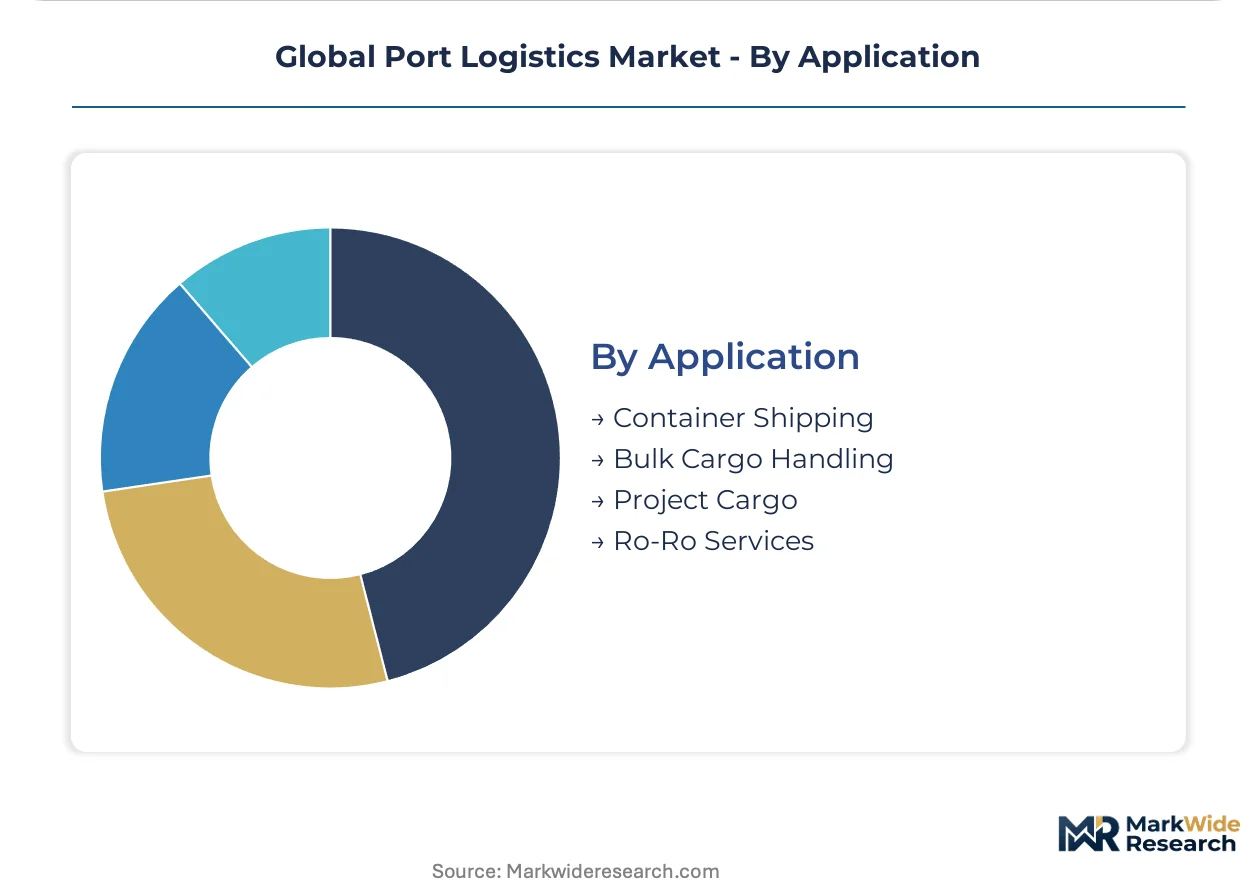
- Container Shipping:Standardized box movements enable automation scale and transshipment hub economics. Mega-vessel deployment concentrates throughput at deepwater ports in China, Singapore, and the Netherlands with sufficient quay depth and crane outreach.
- Bulk Cargo Handling:Grain, ore, and coal movements require specialized grab unloaders and conveyor systems. Stable margin pools persist at dedicated terminals in Australia and Brazil where mining and agricultural export volume underpins equipment utilization.
- Project Cargo:Offshore wind components and industrial modules exceed standard container dimensions. North Sea and Baltic port clusters are expanding heavy-lift quay capacity to capture renewable energy logistics demand.
- Ro-Ro Services:Vehicle and wheeled cargo movements require ramp infrastructure and deck sequencing distinct from container operations.
Container shipping commands the established base. Project cargo is climbing the fastest as offshore wind component dimensions drive specialized infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IMO carbon intensity regulations and national port modernization programs are redistributing container throughput investment across maritime chokepoints. Terminal operators face divergent compliance timelines between EU FuelEU Maritime mandates and China's MIIT smart port standardization.
China
E-commerce fulfillment networks and transshipment consolidation drive throughput expansion at Shenzhen and Guangzhou. MIIT coordinates domestic automation standards through its smart port demonstration program. The Pearl River Delta port cluster anchors volume concentration as mega-vessel deployment favors deepwater quay infrastructure.
United States
Reshoring manufacturing and intermodal rail connectivity intensify demand for West Coast and Gulf Coast container handling. No single federal regulator dominates maritime infrastructure policy, leaving port authorities to navigate state-level environmental compliance. The Los Angeles-Long Beach complex manages vessel queue backlogs through extended gate hours and chassis pool coordination.
Germany
Automotive component exports and renewable energy component imports sustain Hamburg and Bremerhaven throughput. The EU Green Deal's FuelEU Maritime regulation mandates shore power installation and alternative fuel bunkering infrastructure. Northern German port clusters are electrifying gantry crane fleets to meet carbon intensity reduction deadlines.
Singapore
Transshipment hub status and mega-vessel deployment concentrate container exchanges at Tuas megaport development. The Maritime and Port Authority coordinates terminal automation standards with IMO baseline targets. The Tuas facility deploys automated stacking cranes and guided vehicle fleets at greenfield sites without legacy equipment constraints.
Netherlands
Rotterdam's Maasvlakte terminals process Europe's largest container volumes through automated yard operations. EU Green Deal regulations compress electrification investment timelines for cargo handling equipment. The port cluster deploys digital twin platforms to optimize vessel berthing sequences and reduce unplanned equipment downtime.
Global Port Logistics Market Competitive Environment
On the supply side, the industry is consolidating around integrated logistics platforms and state-backed terminal ownership networks. Three strategic archetypes dominate: shipping lines with captive terminal assets, independent port operators with automation specialization, and diversified logistics conglomerates controlling end-to-end container flows. Competitive intensity centers on concession bidding for greenfield automated terminals and electrification capex commitments.
Among shipping-line terminal operators, A.P. Møller – Maersk A/S and COSCO Shipping Holdings exemplify divergent ownership structures. Maersk represents the integrated logistics archetype combining vessel operations with port asset control. COSCO occupies a position reflecting state-coordinated terminal ownership across strategic maritime chokepoints. DP World sits within the independent operator tier, differentiated by automated stacking crane deployment at flagship facilities.
| Leading Market Players |
|---|
| CMA CGM Group |
| Evergreen Marine Corp. |
| A.P. Møller – Maersk A/S |
| HMM Co. Ltd. |
| Ocean Network Express |
| COSCO Shipping Holdings |
| Mediterranean Shipping Company |
| DP World |
| Hapag-Lloyd AG |
| Others |
Value Chain & Pricing Dynamics
Rotterdam's Maasvlakte terminal cluster anchors European container handling capacity, and its electrification capex commitments are compressing margin structures across mid-tier operators unable to match equipment replacement cycles. This supply concentration at automated deepwater hubs translates into pricing power for integrated terminal operators while forcing smaller concessionaires into cost-pass-through negotiations with shipping lines.
Pricing Analysis
Certification level (ISO/CE-grade terminal operating systems) creates the primary spread between premium automated terminals and standard labor-dependent facilities. Contract-based long-term offtake agreements dominate, with volume commitments from MSC and CMA CGM anchoring revenue visibility. Price differentiation hinges on crane productivity metrics and shore power availability, with EU Green Deal compliance timelines intensifying cost compression in the standard tier. Asset-light freight brokers exhibit highest price sensitivity, while integrated shipping lines prioritize throughput guarantees over unit cost.
Supply Chain Analysis
Export-control regimes limiting automated stacking crane technology flows from Northern Europe and East Asia are constraining procurement options for mid-sized terminal operators. Equipment manufacturing concentrates in Germany, South Korea, and China, with specialized gantry crane components drawing from steel foundries and precision drive systems. Single-source vulnerability runs through terminal operating system vendors clustered in Scandinavia and Japan. Distribution runs through direct OEM relationships and regional equipment lessors serving concession-based port developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Terminal automation engineering talent scarcity is reshaping competitive boundaries, with predictive maintenance algorithm deployment and legacy system integration capabilities concentrated among Northern European and East Asian specialists. This capability gap favors operators with captive technical resources over asset-light concessionaires.
For Market Incumbents: Build captive automation engineering capabilities through targeted hiring in Hamburg and Singapore talent pools. Deepen backward integration into terminal operating system development to reduce vendor dependency. Electrification capex commitments at Jebel Ali and London Gateway demonstrate how equipment moats defend against mid-tier entrants lacking grid upgrade financing access. For New Entrants and Emerging Players: India's Sagarmala port modernization program at Visakhapatnam and Chennai represents the most penetrable entry point for automated container terminal concessions. Mid-sized transshipment hubs in Southeast Asia with shallow automation penetration offer secondary white-space. Partner with European equipment lessors to circumvent capital intensity barriers while building operational track records. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among terminal operators with long-term concession agreements and integrated logistics platform relationships. Long-term viability centers on electrification compliance positioning and digital twin deployment capabilities. Watch for IMO regulatory divergence between baseline carbon intensity targets and regional unilateral measures as a signal for terminal network revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Terminal Concession Bidding | Greenfield developments at Tuas and Visakhapatnam reward first-mover automation scale without legacy equipment constraints. |
| Electrification Capex Commitment | Battery-powered gantry crane deployment at Hamburg and Rotterdam satisfies EU FuelEU Maritime shore power mandates ahead of deadlines. |
| Terminal Operating System Integration | Predictive maintenance algorithms at Singapore's Tuas megaport reduce unplanned crane downtime through real-time equipment monitoring. |
| Heavy-Lift Quay Capacity Expansion | North Sea port clusters capture offshore wind component logistics as turbine dimensions exceed standard container specifications. |
| Blockchain-IoT Cargo Visibility Platform | Distributed ledger integration with container sensors reduces documentation friction for electronics manufacturers in China's Pearl River Delta. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with terminal operations directors, port authority concession managers, shipping line procurement leads, and maritime automation engineers; and secondary validation through IMO regulatory filings, EU Green Deal implementation documents, port authority annual reports, and customs trade statistics. Bottom-up equipment deployment tallies and top-down container throughput estimates were triangulated to anchor market sizing.
Forecast inputs across the projection horizon incorporated service type segmentation by loading, unloading, storage, and freight forwarding functions; technology deployment tiers from manual to fully automated systems; and application splits across container shipping, bulk cargo, and project cargo categories. CAGRs were derived from vessel deployment schedules, electrification investment pipelines, and e-commerce fulfillment network expansion trajectories. Mega-vessel deployment patterns and transshipment hub concentration metrics provided industry-specific forecast anchors.
Practitioners should monitor IMO regulatory divergence, EU FuelEU Maritime enforcement timelines, and China's MIIT smart port standardization progress for early signals requiring forecast reassessment. Material shifts in carbon intensity compliance deadlines or terminal automation technology export restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Air Freight Market
Logistics and Shipping
Europe Third Party Logistics Market
Logistics and Shipping
Peru Freight and Logistics Market
Logistics and Shipping
Digital Freight Forwarder Market
Logistics and Shipping
Qatar Freight and Logistics Market
Logistics and Shipping
Nordics Freight and Logistics Market
Logistics and Shipping
ASEAN Warehousing and Distribution Logistics Market
Logistics and Shipping
Netherlands Last Mile Delivery Market
Logistics and Shipping
Europe Sea Freight Forwarding Market
Logistics and Shipping
Hungary Third Party Logistics (3PL) Market
Logistics and Shipping
Japan Cross-Border E-Commerce Logistics Market
Logistics and Shipping
Malaysia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
United States Digital Freight Forwarding Market
Logistics and Shipping
Europe Chemical Logistics Market
Logistics and Shipping
US Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Asia-Pacific Container Drayage Market