
 Cold Chain Logistics Market | 2026-2036
Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Chain Logistics Market Analysis
Refrigerated warehousing as a subscription service layer is pivoting how cold chain operators monetize capacity, shifting from per-pallet storage fees to guaranteed temperature-band contracts with uptime penalties. Lineage Logistics leverages its automated warehouse network to sustain high-throughput frozen food distribution across North America. Americold Logistics anchors its competitive position through vertical integration into port-adjacent cold storage facilities near major import gateways. DHL International GmbH differentiates through pharmaceutical-certified lanes that meet EU GDP and US FDA standards for temperature-sensitive drug shipments.
Cold chain logistics encompasses the temperature-controlled supply chain infrastructure—maintaining ranges from deep frozen at minus 18 degrees Celsius to controlled ambient at 15 to 25 degrees Celsius—used to preserve product integrity from manufacture through final delivery. The system relies on vapor-compression refrigeration, phase-change materials, and real-time sensor telemetry to prevent thermal excursions that degrade pharmaceuticals, perishables, and sensitive chemicals. Pharmaceutical and frozen food segments command the deepest infrastructure investment, as biologics stability requirements and consumer expectations for fresh-frozen quality create durable margin pools. IoT Solutions within the technology dimension is expanding fastest, since wireless temperature logging and predictive analytics reduce spoilage liability and insurance costs for shippers. Retail and healthcare end users now specify thermal packaging performance in procurement contracts, pressuring logistics providers to certify packout designs against ISTA 7E profiles.
FDA enforcement of the Food Safety Modernization Act's sanitary transportation rule shapes US carrier equipment standards, while the EU's Good Distribution Practice guidelines mandate qualified storage and transport systems for pharmaceuticals across member states. The International Air Transport Association's CEIV Pharma certification creates a tiered access structure for air cargo lanes serving regulated drug markets. Stakeholders must monitor how refrigerant phase-down schedules under the Kigali Amendment interact with fleet replacement cycles and warehouse cooling system upgrades.
Market Dynamics
The FDA's Drug Supply Chain Security Act mandates unit-level traceability for pharmaceutical shipments, forcing cold chain operators to retrofit warehouse management systems with serialization layers and real-time environmental logging. This regulatory compression is accelerating capital deployment into IoT-enabled infrastructure while squeezing smaller carriers lacking compliance bandwidth.
Growth Catalysts
- Biologics Stability Requirements:Monoclonal antibodies and cell therapies require uninterrupted minus 70 to minus 80 degrees Celsius chains, creating dedicated infrastructure demand from CDMOs and specialty distributors.
- EU Good Distribution Practice:EMA-mandated temperature qualification for pharmaceutical transport is driving certified lane investments across Germany, France, and the Netherlands.
- Phase-Change Materials:Advanced PCM packouts with 96-hour thermal protection are displacing gel packs in last-mile vaccine delivery, reducing excursion rates in rural distribution.
Market Restraints
- Refrigerant Supply Concentration:Hydrofluoroolefin production concentrates among three chemical manufacturers, exposing fleet operators to price volatility during Kigali Amendment phase-down schedules.
- Last-Mile Cost Structure:Urban congestion and parking scarcity inflate per-stop delivery costs for temperature-controlled vans, compressing margins on small-parcel pharmaceutical shipments.
- Technical Limitation:Current battery-electric refrigeration units lack sufficient range for intercity frozen freight, constraining fleet electrification timelines.
Strategic Opportunities
- India Cold Storage Gap:FSSAI enforcement of food safety standards coincides with PLI scheme incentives for integrated cold chain infrastructure, opening greenfield warehouse development.
- Direct-to-Patient Pharma:Specialty pharmacy home infusion services require last-mile solutions with patient-facing temperature confirmation, creating service-layer premiums.
- Blockchain-IoT Convergence:Distributed ledger integration with wireless sensor networks enables immutable temperature records for insurance claims and regulatory audits.
Industry Challenges
- Refrigeration Technician Scarcity:Vapor-compression system maintenance requires EPA Section 608 certification, constraining fleet expansion for regional carriers.
- CEIV Pharma Certification Timeline:IATA's air cargo qualification demands 12-18 months of operational data collection, delaying carrier entry into pharmaceutical lanes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Chain Logistics Market |
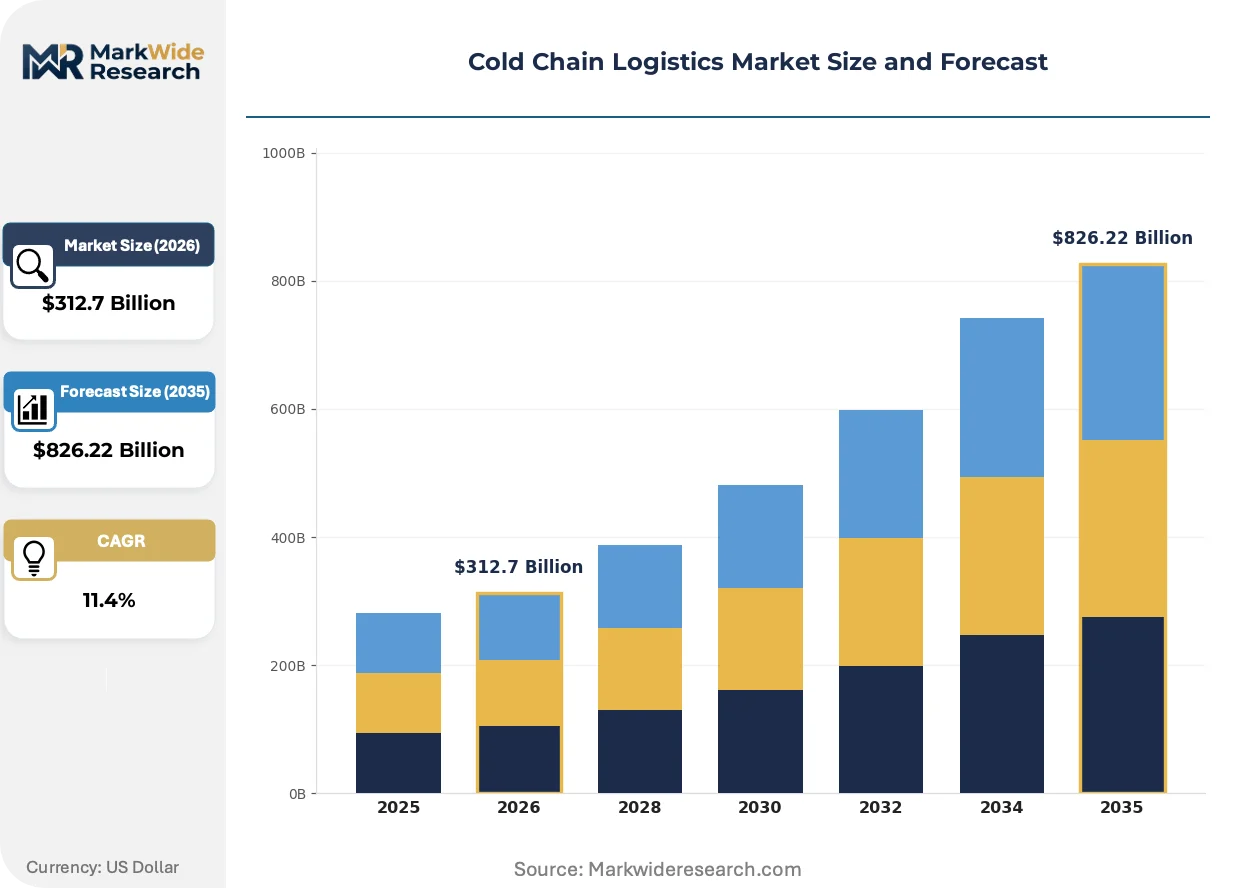
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $826.22 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Foods, Dairy Products, Pharmaceuticals, Temperature-Sensitive Chemicals End User: Retail, Healthcare, Food Service, Logistics Providers Technology: Refrigerated Transport, Temperature Monitoring, IoT Solutions, Thermal Packaging Service Type: Transportation, Warehousing, Packaging, Regulatory Compliance |
| Companies Covered | United Parcel Service, Kuehne + Nagel International AG, Americold Logistics, DB Schenker, Nippon Express Co., Ltd., Lineage Logistics, FedEx Corporation, XPO Logistics, Inc., DHL International GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Chain Logistics Market Emerging Trajectories
Digital twin modeling of warehouse thermal zones is compressing commissioning timelines for new cold storage facilities, while predictive algorithms preempt equipment failures before product exposure occurs.
Machine learning platforms trained on historical excursion data are absorbing variability in packout performance, enabling pharmaceutical shippers to reduce insulation mass by 15-20 percent without compromising protection. Large CDMOs deploy these models across their distribution networks, cutting freight costs per shipment. The technology is absorbing risk tolerance previously reserved for over-engineered thermal packaging.
The EU F-Gas Regulation's phasedown of high-GWP refrigerants is forcing warehouse operators to accelerate ammonia and CO2 cascade system retrofits. Industrial refrigeration contractors in Germany and the Netherlands report 18-month backlogs for qualified installation crews. Pharmaceutical-certified facilities face compressed compliance windows as member states tighten enforcement.
Hospital procurement teams now specify ISTA 7E thermal profile certification as a gate criterion for 3PL selection, displacing informal packout claims. This behavioral shift concentrates volume among logistics providers with in-house testing laboratories. The United Kingdom's NHS supply chain exhibits the strictest enforcement, with penalty clauses for temperature documentation gaps.
Cold Chain Logistics Market Segmentation
Cold chain logistics operators configure asset portfolios around thermal band requirements rather than generic cargo categories. Each segment demands distinct refrigeration specifications, compliance protocols, and capital intensity levels that reshape carrier economics.
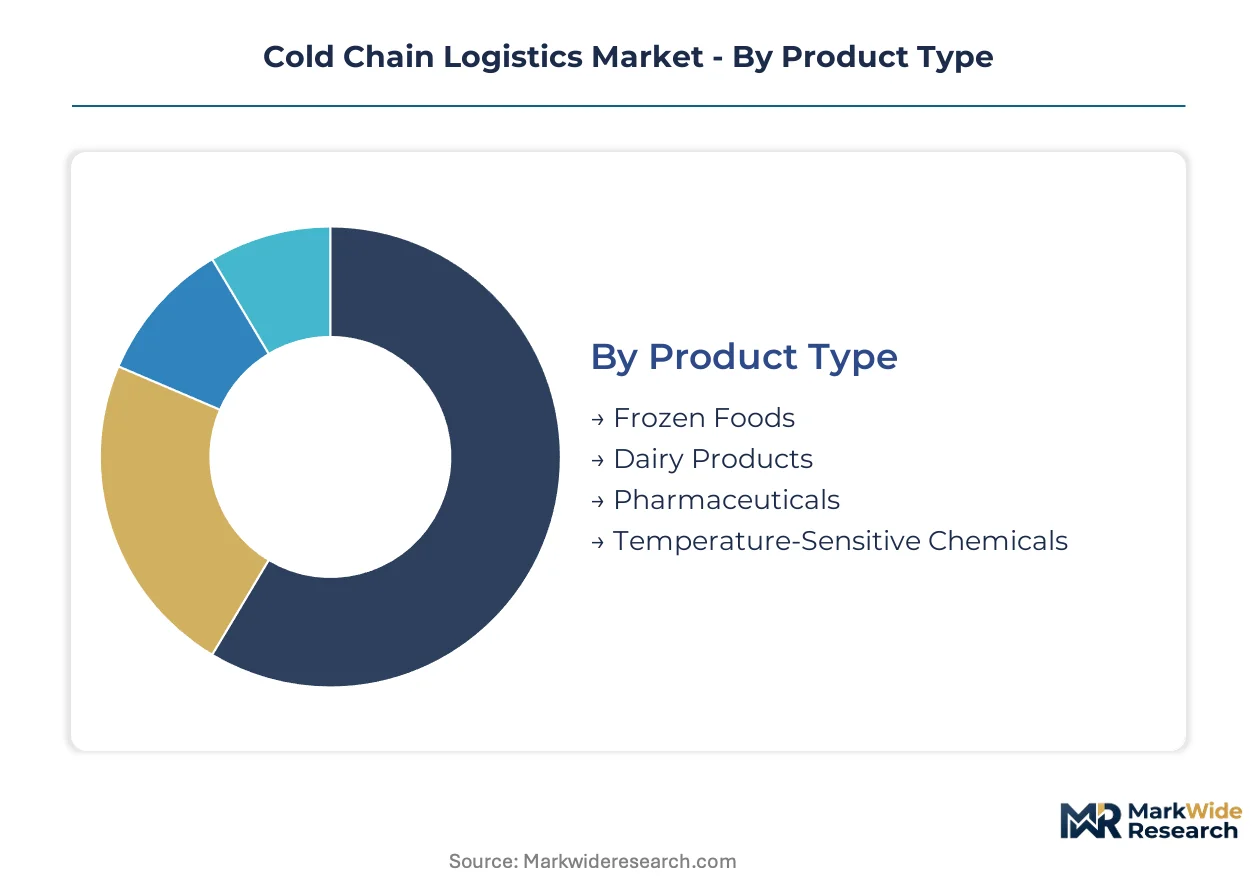
Product Type:
Upgrade cycles in product-specific cold chain infrastructure accelerate when regulatory thresholds tighten or biologics pipelines expand. Capital deployment follows stability requirements rather than commodity flow volumes.
- Frozen Foods:Deep-frozen chains at minus 18 degrees Celsius dominate North American retail distribution networks. US food processing corridors in the Midwest and California's Central Valley anchor warehouse demand, with grocers specifying 72-hour backup power for frozen inventory.
- Pharmaceuticals:Biologics and cell therapies require uninterrupted minus 70 to minus 80 degrees Celsius infrastructure, forcing CDMOs to commission dedicated ultra-low freezer farms. EU Good Distribution Practice mandates drive qualification costs higher than frozen food equivalents.
- Dairy Products:Chilled distribution at 2 to 4 degrees Celsius serves retail and food service channels with shorter shelf-life windows than frozen categories.
- Temperature-Sensitive Chemicals:Controlled ambient ranges of 15 to 25 degrees Celsius protect adhesives, coatings, and specialty polymers during transport.
Frozen Foods sits at the top of the volume ranking, with Pharmaceuticals climbing the fastest.
End User:
Customer procurement specifications fragment service requirements across temperature precision, documentation granularity, and penalty structures. Margin pools concentrate where liability exposure justifies premium pricing.
- Healthcare:Hospital systems and specialty pharmacies demand ISTA 7E-certified packouts with immutable temperature logs for insurance claims. The United Kingdom's NHS supply chain enforces strict penalty clauses for documentation gaps.
- Retail:Grocery chains negotiate guaranteed temperature-band contracts with uptime penalties, shifting risk to logistics providers. Automated warehouse networks sustain high-throughput frozen food distribution across North American markets.
- Food Service:Restaurant distribution requires flexible delivery windows and smaller lot sizes than retail channels.
- Logistics Providers:Third-party operators aggregate demand across end users, achieving scale economies in refrigerated asset utilization.
Healthcare commands the steepest expansion trajectory as direct-to-patient pharma services proliferate.
Technology:
Technology refresh cycles compress as sensor costs decline and predictive analytics mature. Operators replace legacy monitoring systems to reduce spoilage liability and insurance premiums.
- IoT Solutions:Wireless temperature logging and predictive analytics platforms reduce excursion rates and enable dynamic routing adjustments. Machine learning models trained on historical data absorb packout performance variability, cutting freight costs per pharmaceutical shipment.
- Temperature Monitoring:Real-time sensor telemetry prevents thermal excursions that degrade product integrity across pharmaceutical and perishable segments.
- Refrigerated Transport:Vapor-compression units dominate fleet equipment, with battery-electric alternatives constrained by intercity range limitations for frozen freight.
- Thermal Packaging:Phase-change materials with 96-hour protection displace gel packs in last-mile vaccine delivery, reducing rural distribution failures.
IoT Solutions gains share fastest as digital twin modeling and predictive maintenance reshape infrastructure economics.
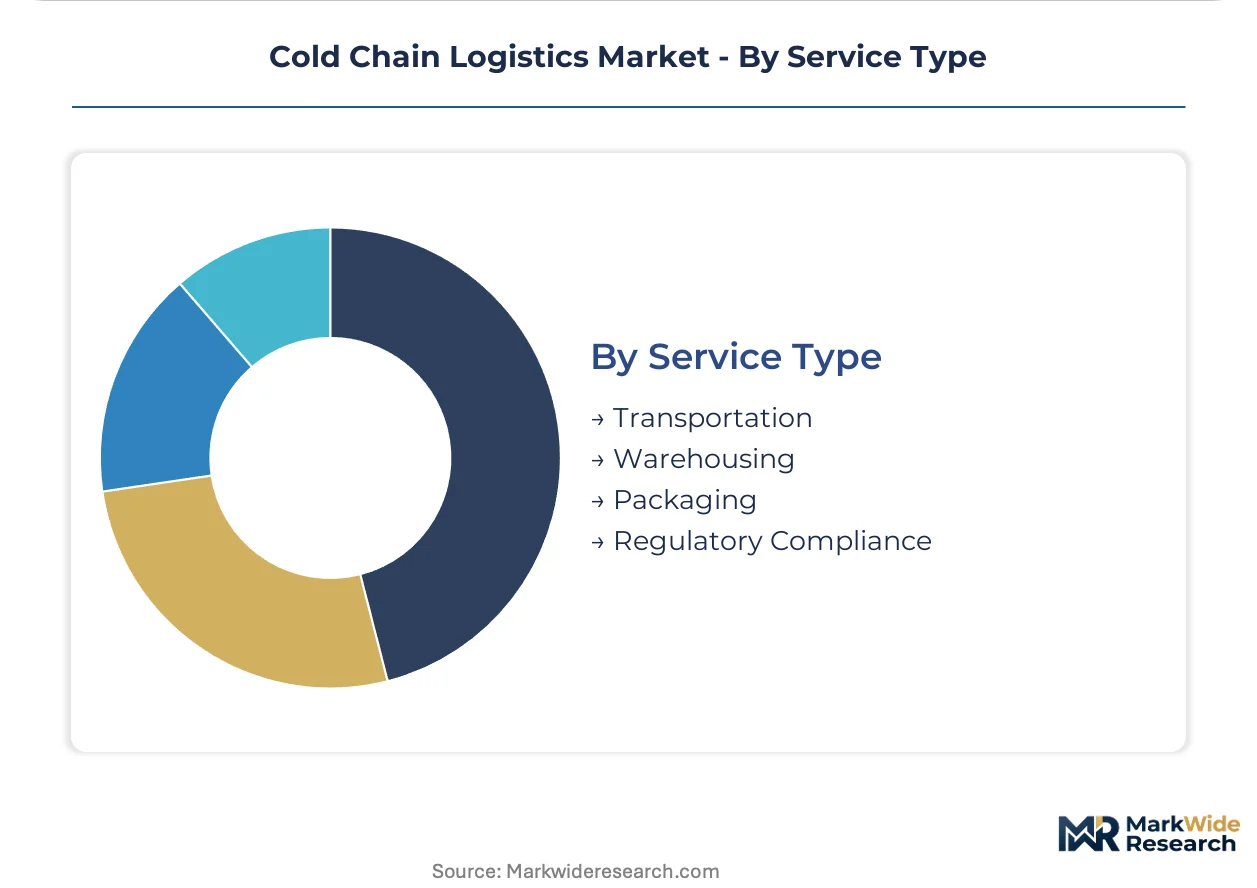
Service Type:
Service bundling patterns shift from transactional storage fees toward outcome-based contracts with guaranteed performance metrics. Regulatory compliance emerges as a discrete revenue layer.
- Regulatory Compliance:FDA Drug Supply Chain Security Act serialization requirements and EU GDP qualification protocols create specialized consulting and certification revenue streams. CEIV Pharma certification demands 12-18 months of operational data collection, delaying carrier entry.
- Warehousing:Refrigerated capacity as a subscription service layer monetizes guaranteed temperature bands rather than per-pallet fees.
- Transportation:Pharmaceutical-certified lanes meeting EU GDP and US FDA standards command premium rates over commodity frozen freight.
- Packaging:In-house testing laboratories become gate criteria for 3PL selection as procurement teams specify certified thermal profiles.
Transportation anchors revenue volume, with Regulatory Compliance expanding most quickly as enforcement tightens across jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are redirecting pharmaceutical cold chain investment toward jurisdictions with harmonized standards and subsidy programs, compressing margins in high-compliance markets while opening arbitrage opportunities in emerging qualification regimes.
United States
FDA enforcement of the Drug Supply Chain Security Act and Food Safety Modernization Act drives serialization and sanitary transport investments. The agency's unit-level traceability mandates force warehouse management system retrofits across pharmaceutical distribution. Cold storage clusters concentrate in Indianapolis and Memphis, where pharmaceutical hubs and overnight delivery infrastructure intersect.
Germany
EMA-mandated Good Distribution Practice qualification requirements attract CDMOs seeking centralized European distribution points. The EU F-Gas Regulation accelerates ammonia and CO2 cascade system retrofits in existing warehouse stock. Industrial refrigeration contractors in the Rhine-Ruhr and Bavaria report extended backlogs for certified installation crews.
India
FSSAI enforcement of food safety standards coincides with PLI scheme incentives for integrated cold chain infrastructure. The regulator's cold storage gap closure mandate opens greenfield warehouse development in agricultural procurement zones. Gujarat and Maharashtra anchor investment flows, with port-adjacent facilities serving pharmaceutical export corridors.
Japan
PMDA stability guidelines for biologics and cell therapies drive ultra-low temperature infrastructure deployment. METI subsidy programs for pharmaceutical logistics modernization compress payback periods for automated warehouse investments. The Kanto region around Tokyo maintains concentration of temperature-controlled distribution capacity serving domestic and export markets.
Netherlands
Rotterdam and Schiphol pharmaceutical-certified air cargo lanes leverage EU GDP alignment with US FDA standards for transatlantic drug shipments. The national government's logistics innovation vouchers accelerate IoT sensor deployment in existing warehouse networks. Port-adjacent cold storage facilities capture import volume from Asian manufacturing origins.
Cold Chain Logistics Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated asset owners commanding pharmaceutical lanes while asset-light brokers aggregate fragmented frozen food demand. Market structure tilts toward consolidation in ultra-low temperature infrastructure, where qualification costs erect barriers, while standard refrigerated transport remains fragmented across regional carriers. Two archetypes dominate: vertically integrated warehouse operators with automated networks, and pharmaceutical-certified lane specialists with regulatory compliance depth. Competitive moves concentrate on M&A for port-adjacent cold storage assets and strategic partnerships for last-mile temperature confirmation technology.
Among integrated warehouse operators, Lineage Logistics and Americold Logistics exemplify the automated-network archetype, while DHL International GmbH occupies a position representing pharmaceutical-certified lane specialization. These three anchors illustrate the strategic divergence between scale-driven frozen food distribution and compliance-intensive pharmaceutical logistics, with each archetype demanding distinct capital allocation patterns and technical workforce development.
| Leading Market Players |
|---|
| United Parcel Service |
| Kuehne + Nagel International AG |
| Americold Logistics |
| DB Schenker |
| Nippon Express Co., Ltd. |
| Lineage Logistics |
| FedEx Corporation |
| XPO Logistics, Inc. |
| DHL International GmbH |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up warehouse specialists have consolidated fragmented cold storage capacity across North America, tightening pricing discipline by shifting from transactional pallet rates to guaranteed temperature-band subscriptions with uptime penalties. This ownership concentration feeds into supply chain restructuring as carriers prioritize pharmaceutical-certified lanes over commodity frozen freight.
Pricing Analysis
Capacity additions in India are reshaping price floors for standard refrigerated warehousing, compressing margins in commodity storage while pharmaceutical-certified facilities in Germany and the United States maintain pricing power through EU GDP and FDA qualification barriers. Three-tier pricing structure across premium, standard, and economy levels separates CEIV Pharma-certified air cargo lanes from qualified ground transport and unqualified regional trucking. Cost compression in standard frozen food distribution is intensifying because grocery chains negotiate guaranteed performance contracts with penalty clauses. Small regional carriers exhibit the highest price sensitivity, while specialty pharmaceutical 3PLs serving biologics shippers command rate premiums with limited buyer pushback.
Supply Chain Analysis
Single-source vulnerability sits with hydrofluoroolefin refrigerant production concentrated among three chemical manufacturers, exposing fleet operators to price volatility during Kigali Amendment phase-down schedules. Manufacturing of vapor-compression refrigeration units centers on China, Germany, and the United States, while phase-change material packouts draw from South Korean and Japanese specialty chemical suppliers. Tariff exposure on refrigeration components and electric vehicle batteries constrains fleet electrification timelines. Distribution runs through pharmaceutical hubs in Indianapolis and Memphis, port-adjacent import gateways, and automated warehouse networks serving retail grocery consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA Drug Supply Chain Security Act's unit-level traceability mandate compounds infrastructure demand, creating durable revenue layers for compliance-capable operators.
For Market Incumbents: Anchor competitive position through backward integration into port-adjacent cold storage assets near major import gateways, defending against asset-light digital brokers aggregating fragmented demand. Invest in automated warehouse networks to sustain throughput advantages as labor scarcity intensifies. CEIV Pharma certification depth protects against regional carriers lacking the 12-18 month operational data collection bandwidth for pharmaceutical lane entry. For New Entrants and Emerging Players: Specialty pharmacy home infusion services represent the most penetrable white-space target, requiring last-mile solutions with patient-facing temperature confirmation that incumbent frozen food operators underserve. Direct-to-patient pharma distribution in rural United States corridors offers service-layer premiums absent from urban consolidated markets. Partner with hospital procurement teams specifying ISTA 7E-certified packouts as gate criteria for 3PL selection. For Investors and Strategic Acquirers: Pharmaceutical logistics divisions at integrated freight carriers are the most active acquirer in this space, consolidating temperature-controlled capacity to secure biologics distribution contracts. Target acquisition archetypes include regional cold storage operators with FDA-registered facilities and established pharmaceutical shipper relationships. Watch ammonia and CO2 cascade system retrofit backlogs in Germany as an inflection indicator for qualified installation crew scarcity spreading to other jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| CEIV Pharma Certification Investment | IATA qualification opens pharmaceutical air cargo lanes serving regulated drug markets with premium rate structures. |
| Automated Warehouse Network Expansion | Lineage Logistics-style robotics sustain high-throughput frozen distribution with labor cost advantages. |
| Port-Adjacent Cold Storage Acquisition | Americold Logistics model captures import volume from Asian manufacturing origins with vertical integration. |
| IoT Sensor Platform Deployment | Wireless temperature logging reduces spoilage liability and insurance premiums for pharmaceutical shippers. |
| Phase-Change Material Packout Development | 96-hour thermal protection displaces gel packs in last-mile vaccine delivery with lower excursion rates. |
Methodological Framework
Bottom-up pharmaceutical and frozen food end-use modeling reconciled against top-down refrigerated transport capacity tracking forms the analytical core of this study. Primary interviews with cold chain operations directors, pharmaceutical quality assurance leads, grocery category buyers, and refrigerated fleet procurement managers combined with secondary validation from FDA Drug Supply Chain Security Act guidance documents, EU Good Distribution Practice regulatory texts, IATA CEIV Pharma certification standards, and customs trade data on refrigeration equipment imports. Triangulation across stakeholder perspectives and documentary sources ensures segment-level consistency.
Input-output matrices map thermal band requirements, compliance protocol intensity, and capital deployment patterns across product type, end user, technology, and service type dimensions over the projection horizon. CAGRs derive from fitted growth curves incorporating biologics pipeline expansion, regulatory enforcement timelines, and infrastructure investment flows. Modeled inputs include Kigali Amendment refrigerant phase-down schedules, FSSAI cold storage gap closure mandates in India, and METI pharmaceutical logistics modernization subsidies in Japan.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery-electric refrigeration range improvements, ammonia system retrofit labor availability, and pharmaceutical shipper consolidation patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
ASEAN Cross Border Road Freight Transport Market
Logistics and Shipping
Air Cargo Market
Logistics and Shipping
Asia Pacific Sea Freight Forwarding Market
Logistics and Shipping
Freight Transport Management Market
Logistics and Shipping
Global 3PL in Cold Chain Logistics Market
Logistics and Shipping
UAE Logistics Market
Logistics and Shipping
Asia-Pacific less-Than Container Load (LCL) Market
Logistics and Shipping
Japan Dangerous Goods Logistics Market
Logistics and Shipping
South Africa Freight and Logistics Market
Logistics and Shipping
South Korea Parcel Delivery Market
Logistics and Shipping
Smart Container Market
Logistics and Shipping
Mexico Last Mile Delivery Market
Logistics and Shipping
Indonesia Cold Chain Logistics Market
Logistics and Shipping
Poland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
India Freight and Logistics Market
Logistics and Shipping
Global Dry Bulk Shipping Market