
 China less than Truckload Road Freight Transport Market | 2026-2036
China less than Truckload Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
China less than Truckload Road Freight Transport Market Outlook
Aluminum alloy cargo box construction is shifting product economics across the China less than Truckload Road Freight Transport sector as fleet operators seek weight reduction without sacrificing payload integrity. SF Express leverages its proprietary sorting infrastructure to sustain premium service tiers across tier-one and tier-two city networks. Deppon Logistics anchors its competitiveness through specialized handling of bulky manufactured goods, while ZTO Express dominates volume-driven parcel consolidation with automated hub operations.
China less than Truckload Road Freight Transport describes the aggregation of multiple shippers' partial loads into single vehicle movements, typically involving shipments between kilograms and several tons that do not require full truck capacity, with hub-and-spoke routing optimized through digital freight matching platforms. The primary commercial purpose centers on reducing per-unit logistics costs for small and medium enterprises while improving asset utilization across fragmented road networks. Expedited service commands premium positioning as manufacturers tighten just-in-time inventory windows, while refrigerated vehicle deployment expands alongside cold-chain pharmaceutical distribution and fresh agricultural product movement from western production bases to eastern consumption centers.
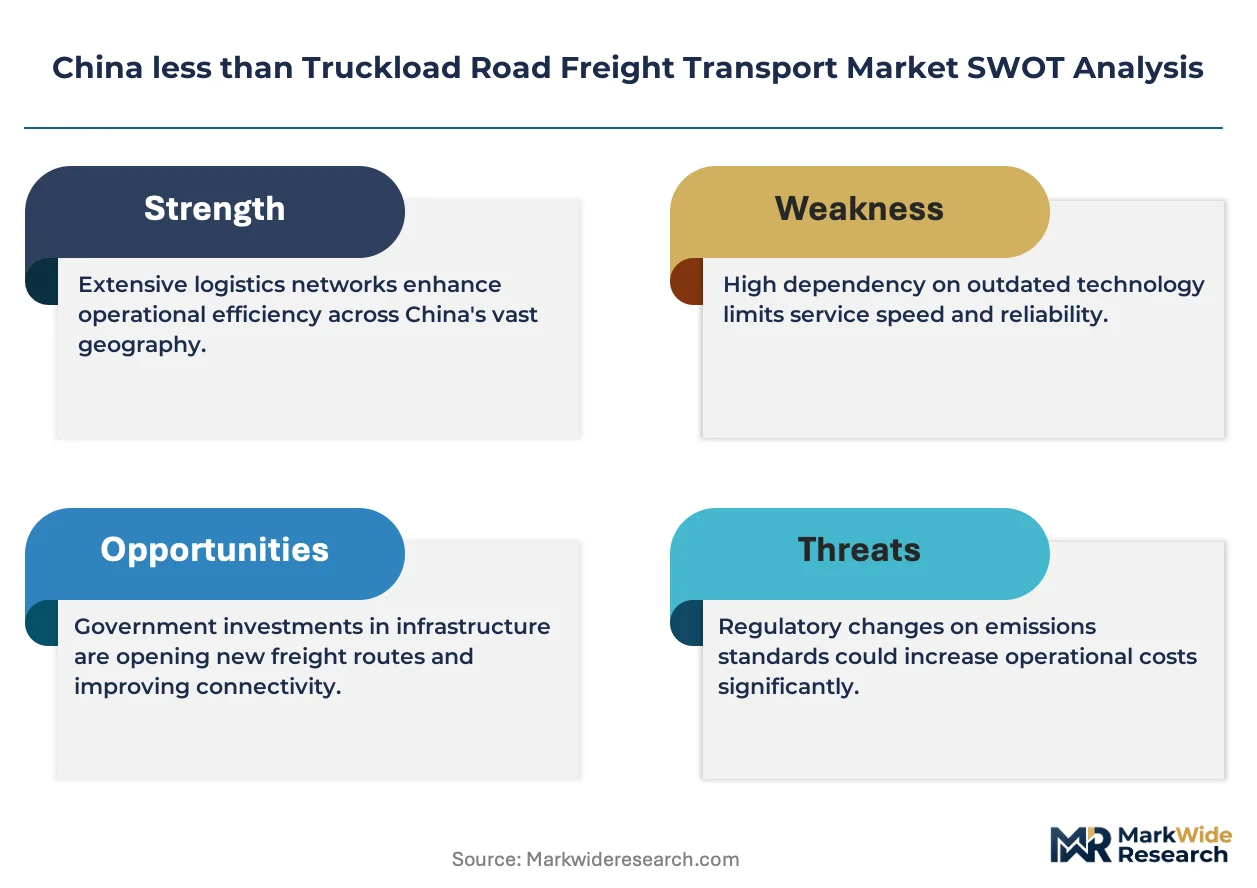
MIIT vehicle emission standards and MEE carbon intensity benchmarks are tightening compliance requirements for commercial diesel fleets operating on national trunk routes, directly influencing carrier capital allocation toward newer powertrain technologies. GB standards governing vehicle dimensions and axle loads constrain equipment procurement choices, while SAMR enforcement of platform economy regulations shapes pricing transparency across digital freight intermediaries. Stakeholders must evaluate how evolving NEV subsidy structures and charging infrastructure density along corridor routes will reshape total cost of ownership calculations for fleet renewal decisions.
Market Dynamics
Digital freight matching platforms are compressing carrier-shipper transaction cycles while MIIT emission standards force fleet renewal toward NEV powertrains across China's less than truckload networks.
Growth Catalysts
- E-commerce fulfillment density:Cross-border retail platforms are consolidating parcel volumes through automated hub infrastructure in the Yangtze River Delta corridor.
- Dual carbon policy enforcement:MEE carbon intensity benchmarks are accelerating diesel fleet phase-outs and redirecting capital toward battery-electric and hydrogen fuel cell vehicle procurement.
- Cold-chain pharmaceutical distribution:Temperature-controlled vehicle deployment is expanding alongside biologics logistics requirements from western production bases to eastern consumption centers.
Market Restraints
- Lithium-ion battery cost volatility:Raw material price swings for cathode metals are compressing margins on electric commercial vehicle acquisitions.
- Charging infrastructure gaps:Ultra-fast charging station density remains insufficient along national expressway corridors connecting inland provinces to coastal demand clusters.
- GB standards compliance burden:Dimensional and axle load regulations constrain equipment flexibility, forcing redundant fleet configurations for mixed cargo categories.
Strategic Opportunities
- Western agricultural export corridors:Xinjiang and Sichuan production bases lack integrated cold-chain consolidation capacity for fresh produce movement to eastern markets.
- NEV subsidy restructuring:Revised fiscal incentive frameworks favor commercial vehicle categories with higher payload ratings and longer daily utilization cycles.
- Blockchain-IoT convergence:Immutable cargo documentation combined with real-time telematics is enabling parametric insurance products and freight financing instruments.
Industry Challenges
- Telematics integration complexity:Legacy fleet management systems resist seamless data exchange with digital freight platforms, forcing expensive middleware development.
- Certified technician scarcity:High-voltage powertrain maintenance requires specialized training that vocational programs have not scaled to match NEV fleet penetration rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China less than Truckload Road Freight Transport Market |
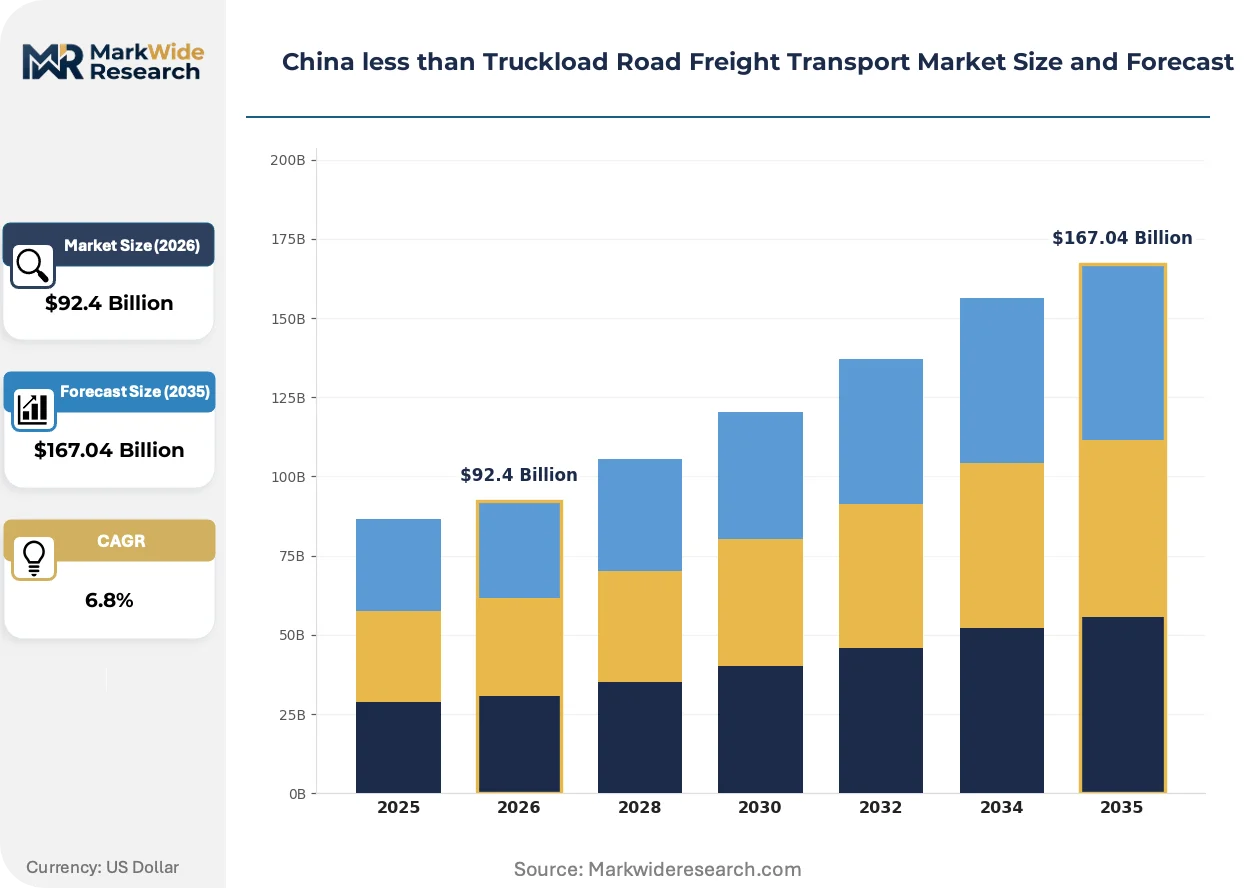
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $167.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard, Expedited, Dedicated, Intermodal Delivery Model: Door-to-Door, Terminal-to-Terminal, Cross-Docking, Pickup & Delivery Vehicle Type: Flatbed, Refrigerated, Box Truck, Cargo Van Customer Type: Manufacturers, Distributors, Retailers, E-Commerce |
| Companies Covered | Changjiu Logistics, CMA CGM Group, Deppon Logistics, SF Express, Shanghai Aneng Juchuang Supply Chain Management, STO Express, YTO Express, ZTO Express, SINOTRUK, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China less than Truckload Road Freight Transport Market Strategic Shifts
Automation of sorting and routing decisions is displacing manual dispatch workflows while regulatory pressure on carbon intensity accelerates powertrain diversification across Chinese road freight networks.
Automated dimensioning and weighing systems are automating cargo classification at hub terminals. Tier-one carriers are deploying these units at sorting facilities in Jiangsu and Zhejiang provinces. The technology is automating freight billing accuracy and reducing manual inspection labor requirements.
MIIT Phase VI emission standards are tightening particulate matter limits for diesel commercial vehicles operating on national trunk routes. Engine manufacturers must deploy selective catalytic reduction and diesel particulate filter systems to maintain type approval. Long-haul carriers serving Shanghai-Beijing corridors face accelerated asset retirement timelines.
Shippers are consolidating vendor relationships around carriers with integrated warehousing capabilities. Traditional pure-transport providers are losing share to operators offering origin consolidation and destination deconsolidation services. This pattern concentrates procurement decisions among manufacturers in Guangdong and Fujian with just-in-time inventory requirements.
China less than Truckload Road Freight Transport Market Segmentation
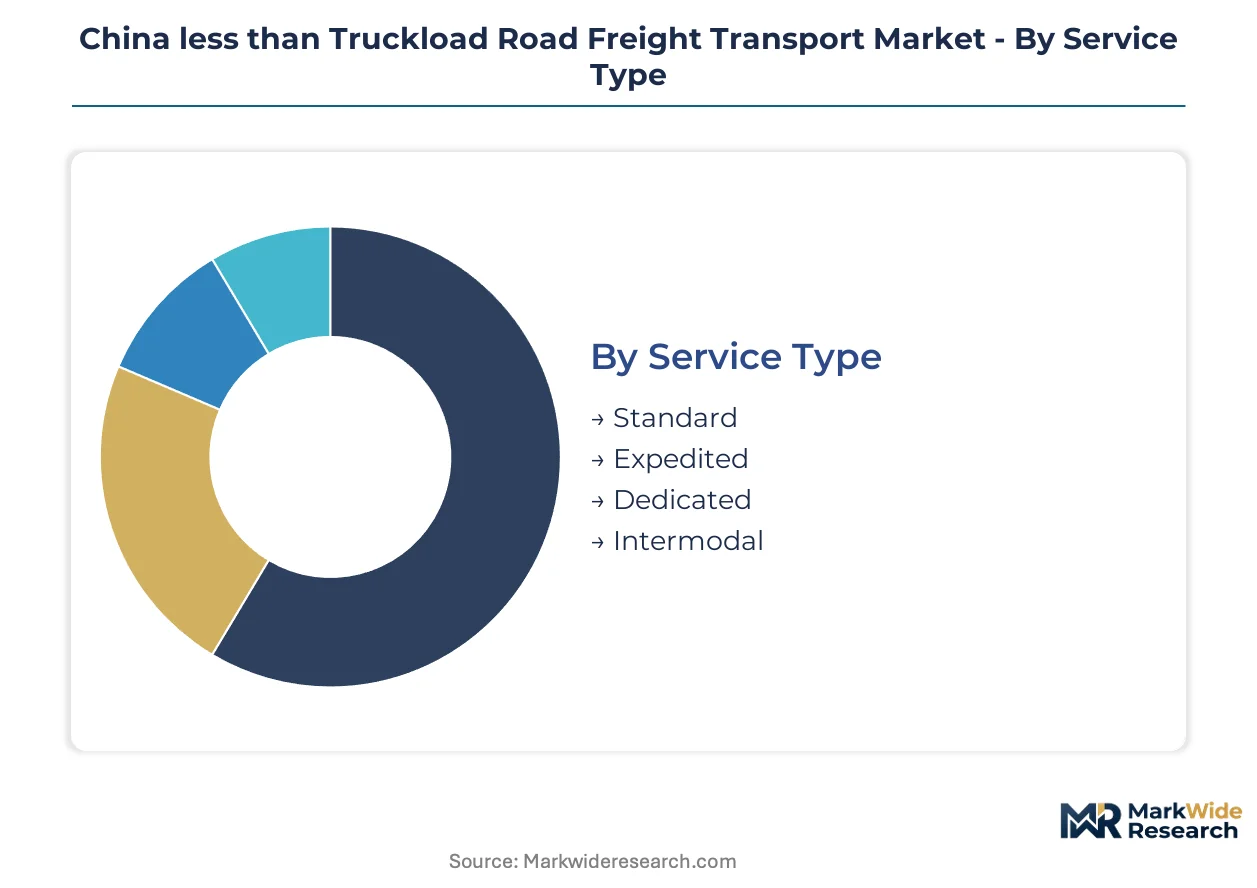
Segmentation in China's less than truckload sector reveals how carriers align asset configurations with divergent service economics. Equipment choices and routing protocols vary sharply across service tiers, customer scale, and temperature requirements.
Service Type:
Upgrade cycles for service tier capabilities are shortening as e-commerce platforms demand more granular delivery windows from their contracted carriers.
- Standard:Consolidated shipments moving through hub-and-spoke networks with 48-72 hour transit commitments. Demand concentrates among small manufacturers in Jiangsu and Zhejiang seeking cost-efficient distribution to tier-two cities, constrained by MIIT emission standards forcing fleet renewal investments.
- Expedited:Time-definite delivery with dedicated line-haul scheduling and minimal intermediate handling. Pharmaceutical distributors in Shanghai command premium positioning for temperature-sensitive biologics, tightening just-in-time inventory windows.
- Dedicated:Exclusive vehicle allocation for single-shipper volumes on recurring lanes. Automotive component suppliers in Guangdong favor this model for production line feed sequences.
- Intermodal:Rail-truck combinations for long-haul corridors exceeding 800 kilometers. Xinjiang agricultural exporters leverage this for cost control on transcontinental routes.
Standard service sits at the top of the volume ranking, with Expedited climbing the fastest.
Delivery Model:
Cost tier differentiation shapes how carriers structure last-mile handoffs and intermediate handling economics.
- Door-to-Door:Complete origin-to-destination service including residential and commercial access. E-commerce fulfillment centers in the Yangtze River Delta anchor volume concentration, though rising labor costs in Shanghai compress margins on final-mile legs.
- Terminal-to-Terminal:Shipper and consignee responsible for collection and delivery at carrier facilities. Small distributors in inland provinces select this for bulk cost reduction.
- Cross-Docking:Direct transfer between inbound and outbound vehicles without intermediate storage. Fresh produce consolidators in Sichuan deploy this for perishable velocity.
- Pickup & Delivery:Hybrid model with carrier-managed collection and customer-arranged final delivery. Third-party logistics providers in Fujian favor this for flexibility.
Door-to-Door commands the widest carrier participation, with Cross-Docking expanding most quickly on cold-chain corridors.
Vehicle Type:
Application-specific equipment requirements are fragmenting fleet procurement strategies across temperature and cargo security dimensions.
- Refrigerated:Insulated cargo compartments with mechanical or electric cooling systems maintaining 2-8°C or frozen lanes. Pharmaceutical distribution from western production bases to eastern consumption centers drives deployment, with MEE carbon intensity benchmarks accelerating diesel unit phase-out.
- Box Truck:Enclosed dry van construction with aluminum alloy or steel cargo boxes. General merchandise flows through Jiangsu-Zhejiang corridors concentrate demand, though GB axle load regulations constrain payload optimization.
- Flatbed:Open deck configuration for oversized or irregularly shaped manufactured goods. Construction equipment manufacturers in Shandong specify this for project cargo.
- Cargo Van:Light commercial vehicles under 3.5 tonnes gross vehicle weight. Urban parcel consolidation in tier-one city centers favors maneuverability over capacity.
Box Truck configurations dominate fleet composition, with Refrigerated units gaining share fastest on pharmaceutical and fresh produce lanes.
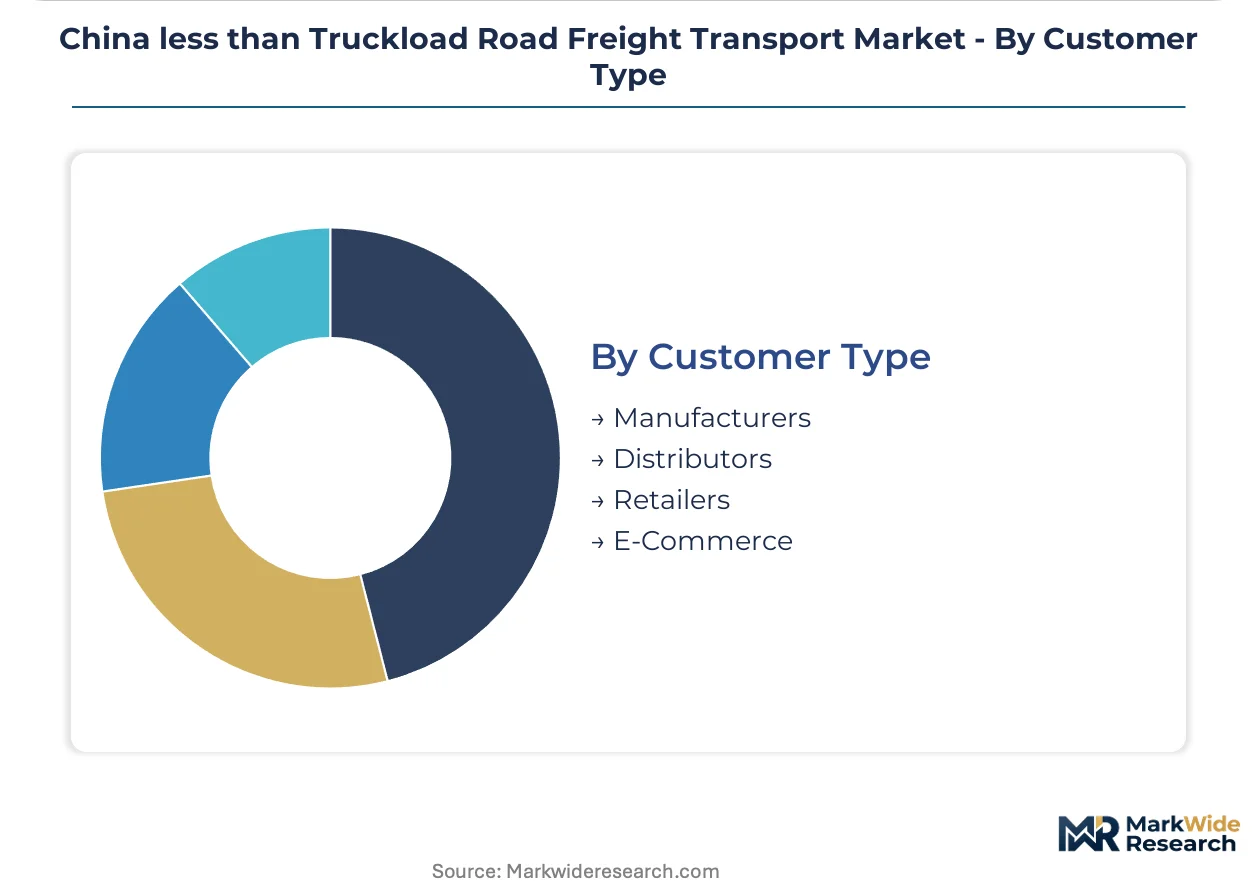
Customer Type:
Customer scale and purchasing sophistication determine contract structures and technology integration depth.
- E-Commerce:Platform-operated or merchant-fulfilled parcel volumes with automated sortation requirements. Cross-border retail consolidation through Yangtze River Delta hubs anchors volume, driving carrier investment in dimensioning and weighing automation.
- Manufacturers:Industrial shippers with scheduled production rhythms and vendor-managed inventory programs. Electronics assemblers in Guangdong demand integrated warehousing alongside transport.
- Distributors:Intermediate wholesalers managing multi-brand product portfolios. FMCG networks in Fujian prioritize lane density over speed.
- Retailers:Brick-and-mortar chains with store replenishment schedules. Regional supermarket operators in Sichuan concentrate procurement on cost per case.
E-Commerce sits at the top of the volume ranking, with Manufacturers climbing the fastest as just-in-time requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta corridor anchors freight consolidation density across China, concentrating automated hub infrastructure and cold-chain pharmaceutical flows between Shanghai, Jiangsu, and Zhejiang provinces.
Yangtze River Delta
E-commerce fulfillment centers and biologics distributors drive expedited service demand through Shanghai, Suzhou, and Hangzhou. MIIT Phase VI emission standards force diesel fleet phase-outs along the Shanghai-Beijing expressway corridor. Zhejiang-based carriers are deploying aluminum alloy cargo boxes to optimize payload compliance under GB axle load regulations.
Pearl River Delta
Electronics manufacturers in Shenzhen and Dongguan command dedicated vehicle allocations for just-in-time production line feeds. SAMR platform economy regulations tighten pricing transparency requirements for digital freight intermediaries. Guangdong's integrated warehousing operators are absorbing pure-transport market share through origin consolidation services.
Beijing-Tianjin-Hebei
Automotive component suppliers and pharmaceutical distributors concentrate demand for temperature-controlled and expedited lanes. MEE carbon intensity benchmarks accelerate battery-electric vehicle procurement for fleets serving the capital region. Tianjin port-linked carriers are expanding intermodal rail-truck combinations for long-haul corridors exceeding 800 kilometers.
Sichuan-Chongqing
Fresh agricultural producers in Sichuan lack integrated cold-chain consolidation capacity for eastern market access. Dual carbon policy enforcement redirects fleet renewal capital toward hydrogen fuel cell trials on Chengdu-Chongqing expressways. Chongqing-based consolidators are deploying cross-docking infrastructure to reduce perishable handling time.
Shandong Peninsula
Construction equipment manufacturers and chemical distributors generate flatbed and specialized handling requirements. GB standards governing vehicle dimensions constrain equipment flexibility for mixed cargo categories. Qingdao-linked carriers are investing in automated dimensioning systems to streamline freight billing accuracy at hub terminals.
China less than Truckload Road Freight Transport Market Competitive Environment
Global container lines compete with domestic express giants across integrated logistics capabilities, while specialized regional operators defend niche positions in temperature-controlled and project cargo segments. The vendor base stratifies into three tiers: national networks with proprietary sorting infrastructure, regional specialists with lane density advantages, and asset-light platform intermediaries. Strategic moves concentrate on automated hub expansion and NEV fleet renewal to satisfy tightening emission benchmarks.
Among the integrated express networks, SF Express, Deppon Logistics, and ZTO Express occupy distinct positioning archetypes within the competitive structure. SF Express represents the premium service tier through proprietary infrastructure investments across tier-one and tier-two city networks. Deppon Logistics exemplifies specialization in bulky manufactured goods handling with differentiated equipment configurations. ZTO Express anchors the volume-driven consolidation segment through automated hub operations and density economics on parcel lanes. These three operators collectively illustrate how scale, specialization, and service tier differentiation fragment competitive positioning across China's less than truckload landscape.
| Leading Market Players |
|---|
| Changjiu Logistics |
| CMA CGM Group |
| Deppon Logistics |
| SF Express |
| Shanghai Aneng Juchuang Supply Chain Management |
| STO Express |
| YTO Express |
| ZTO Express |
| SINOTRUK |
| Others |
Value Chain & Pricing Dynamics
Diesel fuel costs cascade through China's less than truckload networks from upstream energy markets into tiered freight rates, with MIIT emission compliance adding a regulatory premium that carriers pass to shippers through fuel surcharge mechanisms and equipment recovery fees.
Pricing Analysis
Input-cost pass-through dominates pricing structures across Chinese LTL carriers, with diesel price volatility and lithium-ion battery procurement costs feeding directly into rate cards. Three-tier pricing separates expedited pharmaceutical lanes from standard hub-and-spoke consolidation and economy terminal-to-terminal service, with differentiation resting on transit reliability and temperature certification. Pricing pressure stems from e-commerce volume concentration in the Yangtze River Delta, where SF Express and ZTO Express compress margins through scale economies. Small inland distributors exhibit highest price sensitivity, while Shanghai-based biologics shippers absorb premiums for cold-chain integrity.
Supply Chain Analysis
Regional distribution centers anchor hub-and-spoke patterns across Jiangsu, Zhejiang, and Guangdong provinces, with automated sorting facilities clustering within 200 kilometers of Shanghai and Shenzhen consumption basins. Vehicle chassis production draws from Shandong and Hubei manufacturing bases, while telematics hardware sources from Shenzhen electronics clusters. Single-source vulnerability concentrates in high-voltage battery cell supply from CATL and BYD facilities. Distribution runs through tier-one carrier-owned terminals with cross-docking velocity prioritized on pharmaceutical and fresh produce corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's less than truckload road freight transport market compounds steadily through e-commerce fulfillment density and cold-chain pharmaceutical expansion, with regulatory emission mandates ensuring continuous fleet renewal demand.
For Market Incumbents: Extend automated hub infrastructure into western agricultural corridors before regional specialists capture Xinjiang and Sichuan consolidation volume. Defend against asset-light platform intermediaries by deepening proprietary sorting technology in Jiangsu and Zhejiang, where SAMR pricing transparency rules erode traditional rate opacity. Prioritize NEV fleet renewal to lock in MEE carbon intensity compliance ahead of diesel phase-out deadlines. For New Entrants and Emerging Players: Blockchain-IoT cargo documentation offers a technology-first wedge into parametric insurance and freight financing instruments underserved by legacy carriers. Target western cold-chain gaps where Sichuan fresh produce exporters lack integrated consolidation capacity for eastern market access. Build go-to-market around cross-docking velocity guarantees with automated dimensioning partnerships. For Investors and Strategic Acquirers: Consolidation pressure builds where telematics integration complexity fragments mid-tier carriers unable to bridge legacy fleet management with digital freight platforms. The market reads as a 5-10 year infrastructure compounder with acquisition value concentrating in regional cold-chain specialists with lane density in pharmaceutical corridors. Watch NEV subsidy restructuring announcements as inflection signals for fleet renewal capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Hub Expansion | ZTO Express deploys dimensioning systems across Jiangsu terminals to compress sortation labor costs. |
| NEV Fleet Procurement | Deppon Logistics acquires battery-electric tractors to satisfy MEE carbon benchmarks on Shanghai-Beijing lanes. |
| Cold-Chain Infrastructure Buildout | SF Express extends refrigerated vehicle deployment for biologics distribution from Sichuan production bases. |
| Digital Freight Platform Integration | Changjiu Logistics embeds telematics APIs to enable real-time cargo visibility for pharmaceutical shippers. |
| Intermodal Rail-Truck Partnership | Tianjin port carriers combine rail trunking with last-mile truck delivery for Xinjiang agricultural exporters. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fleet operations directors, logistics procurement managers at e-commerce platforms, pharmaceutical distribution executives, and MIIT regulatory specialists with secondary validation. Customs trade data, MIIT vehicle registration databases, SAMR platform economy filings, and carrier financial disclosures anchored bottom-up volume estimates. Top-down triangulation cross-checked against NEV subsidy expenditure records and expressway freight traffic indices.
Segment-weighting approaches distributed value and volume across service type, delivery model, vehicle configuration, and customer archetype dimensions throughout the forecast period. CAGRs derived from trend extrapolation of e-commerce penetration curves, pharmaceutical cold-chain expansion rates, and emission compliance-driven fleet replacement cycles. Modeling incorporated GB standards evolution timelines and MEE carbon intensity benchmark trajectories as structural constraints.
The model holds under stable dual carbon policy enforcement and continued e-commerce growth; deviation in NEV subsidy cancellation or lithium supply disruption would shift fleet renewal economics and carrier margin structures. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Cambodia Freight and Logistics Market
Logistics and Shipping
United States Freight and Logistics Market
Logistics and Shipping
United Kingdom Freight and Logistics Market
Logistics and Shipping
Mexico Freight and Logistics Market
Logistics and Shipping
US Courier, Express, and Parcel Market
Logistics and Shipping
Vietnam Express Delivery Services Market
Logistics and Shipping
Asia Pacific Freight and Logistics Market
Logistics and Shipping
South America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Indonesia Freight and Logistics Market
Logistics and Shipping
Cold Chain Logistics Market
Logistics and Shipping
Turkey Freight and Logistics Market
Logistics and Shipping
Inland Container Depot and Dry Port Market
Logistics and Shipping
GCC Finished Vehicle Logistics Market
Logistics and Shipping
India Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Sweden Cold Chain Logistics Market
Logistics and Shipping
UAE Contract Logistics Market