
 Middle East Freight Forwarding Market | 2026-2036
Middle East Freight Forwarding Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Freight Forwarding Market Insights
Composite container flooring is hardening as a cost-efficient alternative to traditional tropical hardwoods in reefer and dry-cargo units across Middle East trade lanes. Kuehne + Nagel leverages its Swiss-origin pharmaceutical certification to dominate temperature-controlled forwarding from Basel to Riyadh. Aramex anchors last-mile distribution networks across the Levant and North Africa through owned gateway facilities. DP World extends port-centric logistics via its Jebel Ali Free Zone integration, controlling container flows from vessel to inland depot.
Freight forwarding encompasses the coordination of cargo movement across multiple transport modes, involving documentation, customs brokerage, carrier negotiation, and cargo consolidation with specifications such as temperature-controlled handling for pharmaceuticals and hazardous materials protocols for petrochemicals. Its primary commercial purpose is to reduce shipper logistics costs while ensuring regulatory compliance across international borders. Ocean freight forwarding generates the deepest revenue pools given sustained crude and petrochemical export volumes from Saudi Arabia and Kuwait, while air freight forwarding captures premium margins from Dubai's perishables and pharma corridors. E-commerce end users represent the fastest-growing demand segment as Saudi and UAE consumers shift toward cross-border online purchasing.
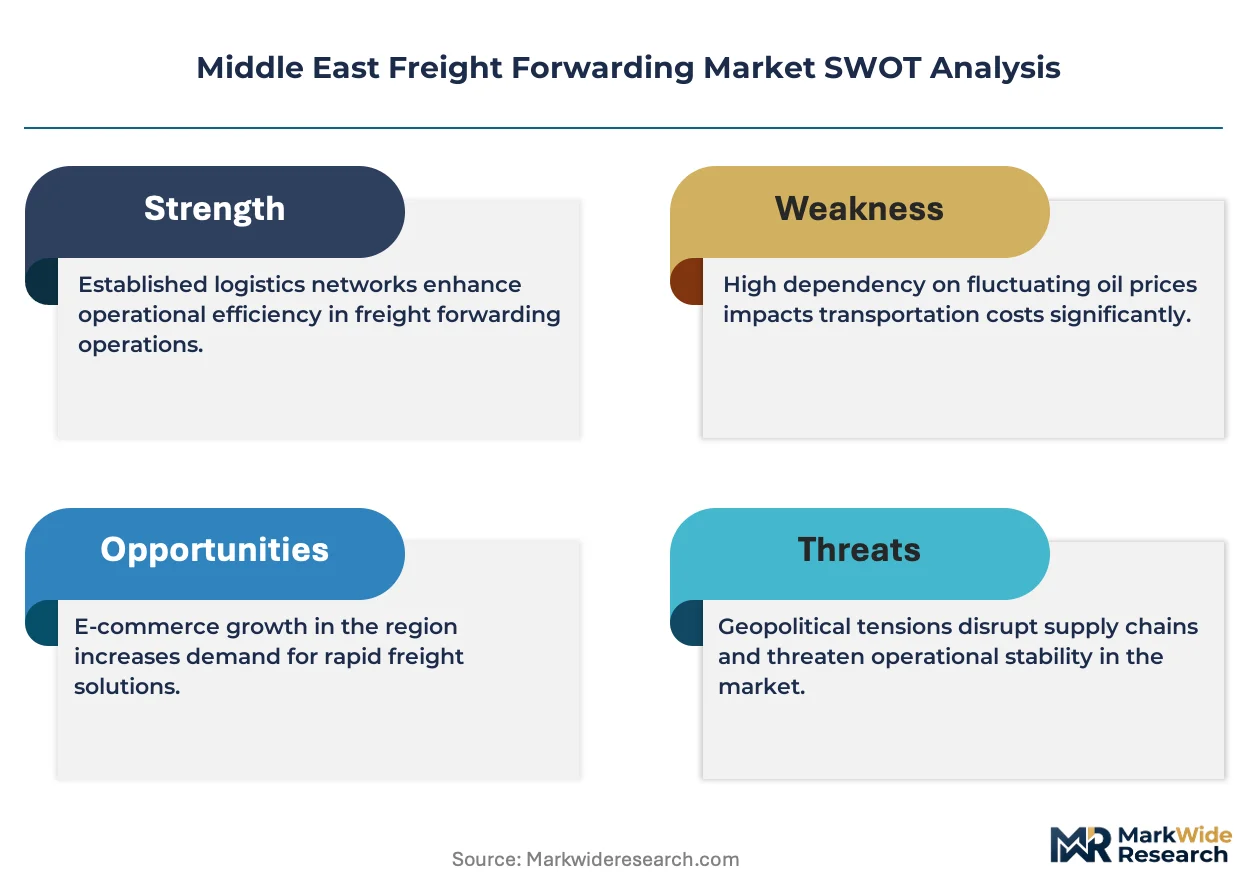
Saudi Arabia's SFDA enforces cold-chain integrity standards for pharmaceutical imports, compelling forwarders to deploy validated thermal packaging and real-time tracking systems. The UAE's customs authority and DP World collaborate on blockchain-based trade documentation, streamlining clearance at Jebel Ali and reducing dwell times for transshipment cargo. Stakeholders must monitor how Iraq's port modernization and Qatar's LNG expansion reshape routing decisions and carrier alliance deployments across the Gulf.
Market Dynamics
Pharmaceutical cold-chain mandates from Saudi Arabia's SFDA are compressing operational margins while forcing capital deployment into validated thermal infrastructure across Gulf forwarding networks.
Growth Catalysts
- SFDA Cold-Chain Mandates:Saudi Arabia's pharmaceutical regulator enforces temperature integrity documentation for all imported medicines, compelling forwarders to invest in real-time tracking and qualified packaging systems.
- E-commerce Warehousing Expansion:Gulf online retailers are scaling bonded warehouse footprints to support cross-border fulfillment, driving demand for integrated customs brokerage and last-mile handoffs.
- Jebel Ali Multimodal Connectivity:DP World's port-centric logistics integration creates captive container flows from vessel to inland depot, anchoring transshipment volume through the UAE.
Market Restraints
- Composite Flooring Input Costs:Resin and fiber supply volatility for container flooring alternatives compresses equipment procurement budgets for reefer and dry-cargo unit fleets.
- Carrier Alliance Concentration:Ocean freight forwarding depends on three major carrier alliances controlling Asia-Gulf capacity, limiting rate negotiation leverage for independent forwarders.
- Documentation Fragmentation:Inconsistent customs data standards between Saudi Arabia, UAE, and Kuwait create clearance friction and dwell time penalties at border crossings.
Strategic Opportunities
- Iraq Port Modernization:Umm Qasr expansion and Basra gateway development offer first-mover positioning for forwarders establishing overland corridors into Iraqi manufacturing zones.
- Blockchain Trade Documentation:UAE customs authority collaboration with port operators creates regulatory tailwind for paperless clearance systems reducing transshipment processing cycles.
- Perishables Air Freight Corridors:Dubai's temperature-controlled cargo infrastructure supports expansion into premium-margin pharmaceutical and fresh produce segments from East Africa and South Asia.
Industry Challenges
- Thermal Packaging Certification Timelines:SFDA validation protocols for pharmaceutical shipping containers extend qualification periods, delaying revenue recognition on new lane launches.
- Reefer Technician Scarcity:Gulf-wide shortage of certified refrigeration mechanics constrains fleet maintenance capacity and equipment uptime guarantees.
- Legacy Customs System Integration:Forwarders face API incompatibility when connecting operational platforms to Saudi ZATCA and UAE FTA electronic filing portals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Freight Forwarding Market |
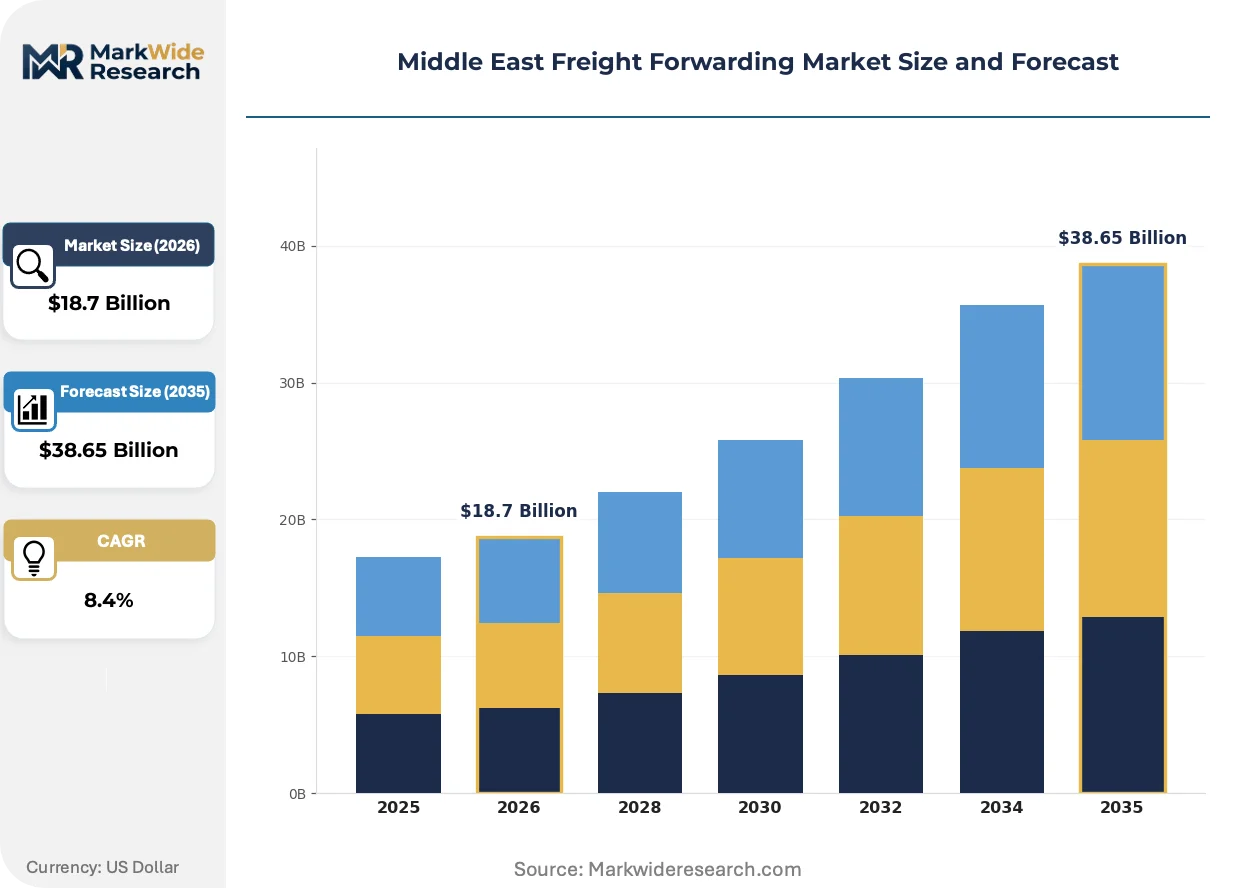
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Air Freight, Ocean Freight, Land Freight, Customs Clearance End User: Manufacturers, Retailers, E-commerce Companies, Distributors Technology: Tracking Systems, Warehouse Management Systems, Automated Booking, Freight Exchange Platforms Delivery Method: Door-to-Door, Port-to-Port, Airport-to-Airport, Cross-Docking |
| Companies Covered | Almajdouie Logistics, Kuehne + Nagel, DHL Group, DB Schenker, CEVA Logistics, Aramex, Al-Futtaim Logistics, Gulf Agency Company, DP World, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Freight Forwarding Market Trends and Innovations
Digital documentation and equipment material substitution are compressing cost structures while regulatory pressure on pharmaceutical integrity is elevating service tier differentiation across Gulf forwarding markets.
Composite container flooring is overtaking tropical hardwoods as the standard substrate for reefer and dry-cargo units. Petrochemical exporters and pharmaceutical shippers specify these panels for moisture resistance and weight reduction. Equipment lessors report accelerated adoption timelines as sustainability procurement criteria harden in European destination markets.
SFDA cold-chain integrity standards now require validated thermal packaging with continuous data logging for all temperature-sensitive pharmaceutical imports. Forwarders must deploy IATA CEIV Pharma-certified infrastructure or forfeit Saudi market access. The regulation compresses competitive positioning to certified operators while marginalizing uncertified regional players.
Cross-border e-commerce purchasing from Saudi and UAE consumers is fragmenting shipment profiles toward smaller parcel volumes with higher frequency. Traditional FCL consolidation models face displacement by bonded warehouse injection and direct-to-consumer last-mile networks. This pattern concentrates demand growth in Dubai South and Riyadh logistics zones with integrated customs clearance capability.
Middle East Freight Forwarding Market Segmentation
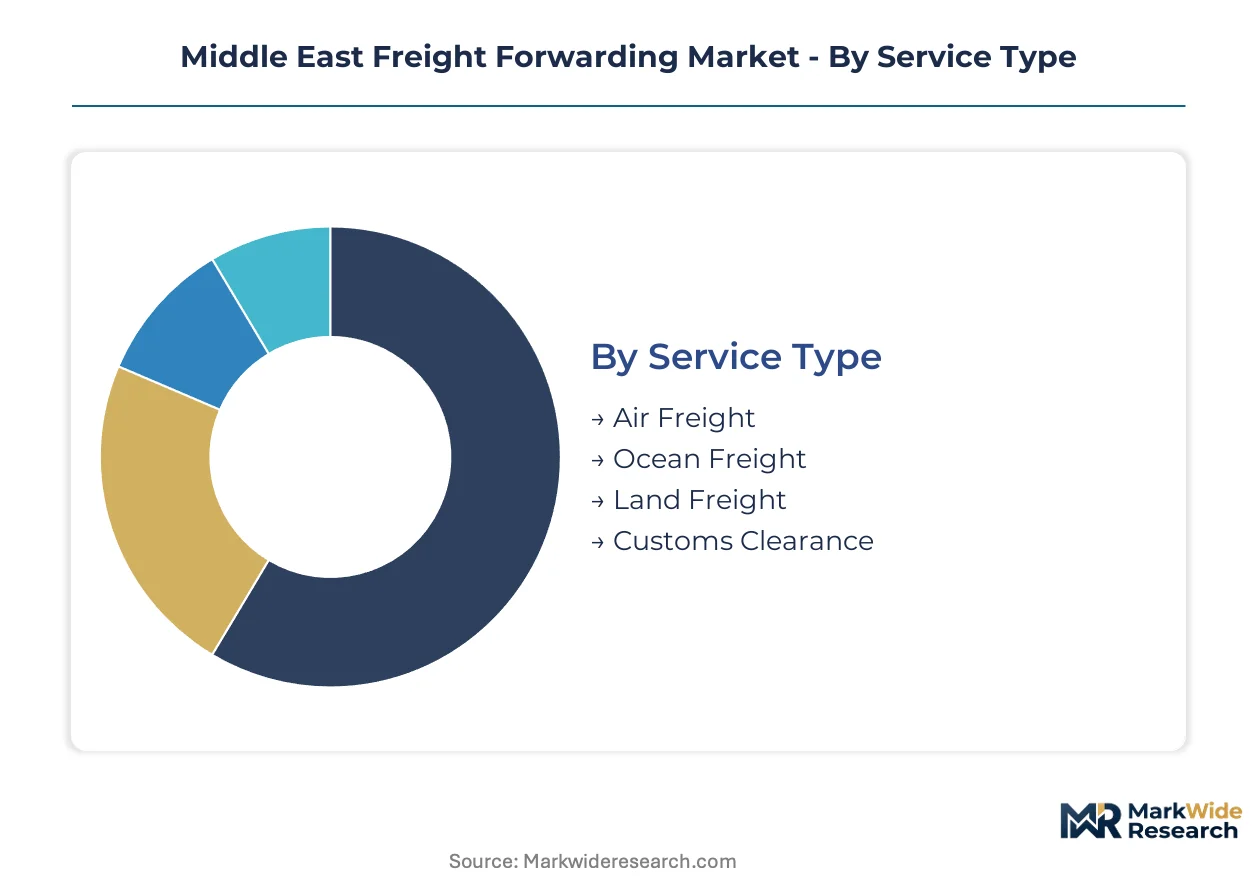
Forwarders in the Middle East compete across service modalities, customer sophistication levels, and technology maturity tiers. Segmentation reveals where capital deployment concentrates and which capability gaps create arbitrage opportunities for specialized operators.
Service Type:
Ocean freight commands the deepest revenue pools due to sustained crude and petrochemical export volumes from Saudi Arabia and Kuwait, while air freight captures premium margins from Dubai's perishables and pharma corridors. Buyers differentiate by cargo value density, regulatory complexity, and modal flexibility requirements.
- Ocean Freight:Full-container and breakbulk coordination for hydrocarbon exports, industrial machinery, and construction materials. Demand concentrates at Jebel Ali and King Abdulaziz Port where DP World and Saudi Global Ports anchor transshipment flows. SFDA cold-chain mandates for pharmaceutical imports are compressing operational margins while forcing capital deployment into validated thermal infrastructure.
- Air Freight:Temperature-controlled and time-critical cargo movement through Dubai International and King Khalid International. Perishables and pharmaceutical shipments from Basel, Mumbai, and Nairobi drive premium pricing. Emirates SkyCargo and Saudia Cargo dominate belly-hold capacity, constraining independent forwarder rate leverage.
- Land Freight:Cross-border trucking and rail coordination across GCC customs unions, with concentration on the Saudi-UAE corridor and overland routes into Jordan and Iraq.
- Customs Clearance:Documentation brokerage and duty optimization services, increasingly bundled with real-time tracking and bonded warehouse integration.
Volume sits with Ocean Freight; growth tilts toward Air Freight.
End User:
Customer scale determines service bundling complexity and contract tenure, with large manufacturers demanding integrated control towers while e-commerce players prioritize velocity over cost optimization.
- E-commerce Companies:Cross-border fulfillment networks requiring bonded warehouse injection, last-mile handoffs, and returns processing. Saudi and UAE consumers shifting toward online purchasing are fragmenting shipment profiles toward smaller parcel volumes with higher frequency. This pattern concentrates demand growth in Dubai South and Riyadh logistics zones with integrated customs clearance capability.
- Manufacturers:Industrial shippers of petrochemicals, automotive components, and construction materials with high-volume, predictable routing requirements. Aramex and Kuehne + Nagel compete for multi-year contracts anchored by dedicated lane pricing.
- Retailers:Department stores and grocery chains importing consumer goods from South and East Asia, with seasonal demand spikes around Ramadan and year-end holidays.
- Distributors:Wholesale intermediaries serving fragmented downstream customers, typically purchasing forwarding services on spot markets with limited contract coverage.
Revenue concentrates with Manufacturers; margin expansion favors E-commerce Companies.
Technology:
Digital maturity separates tier-one operators with API-integrated platforms from legacy brokers dependent on manual documentation and phone-based carrier negotiation.
- Tracking Systems:Real-time visibility platforms combining GPS, RFID, and temperature logging for pharmaceutical and high-value cargo. SFDA validation protocols require continuous data logging with audit trails, extending qualification periods for new lane launches.
- Warehouse Management Systems:Inventory control and order orchestration software for bonded facilities, increasingly integrated with customs electronic filing portals.
- Automated Booking:Direct carrier capacity reservation through forwarder-facing APIs, reducing quote-to-book latency from hours to minutes.
- Freight Exchange Platforms:Digital marketplaces matching spot capacity with ad-hoc demand, penetrating fastest among mid-market distributors with irregular shipping patterns.
Adoption concentrates in Tracking Systems; capability gaps persist in Automated Booking.
Delivery Method:
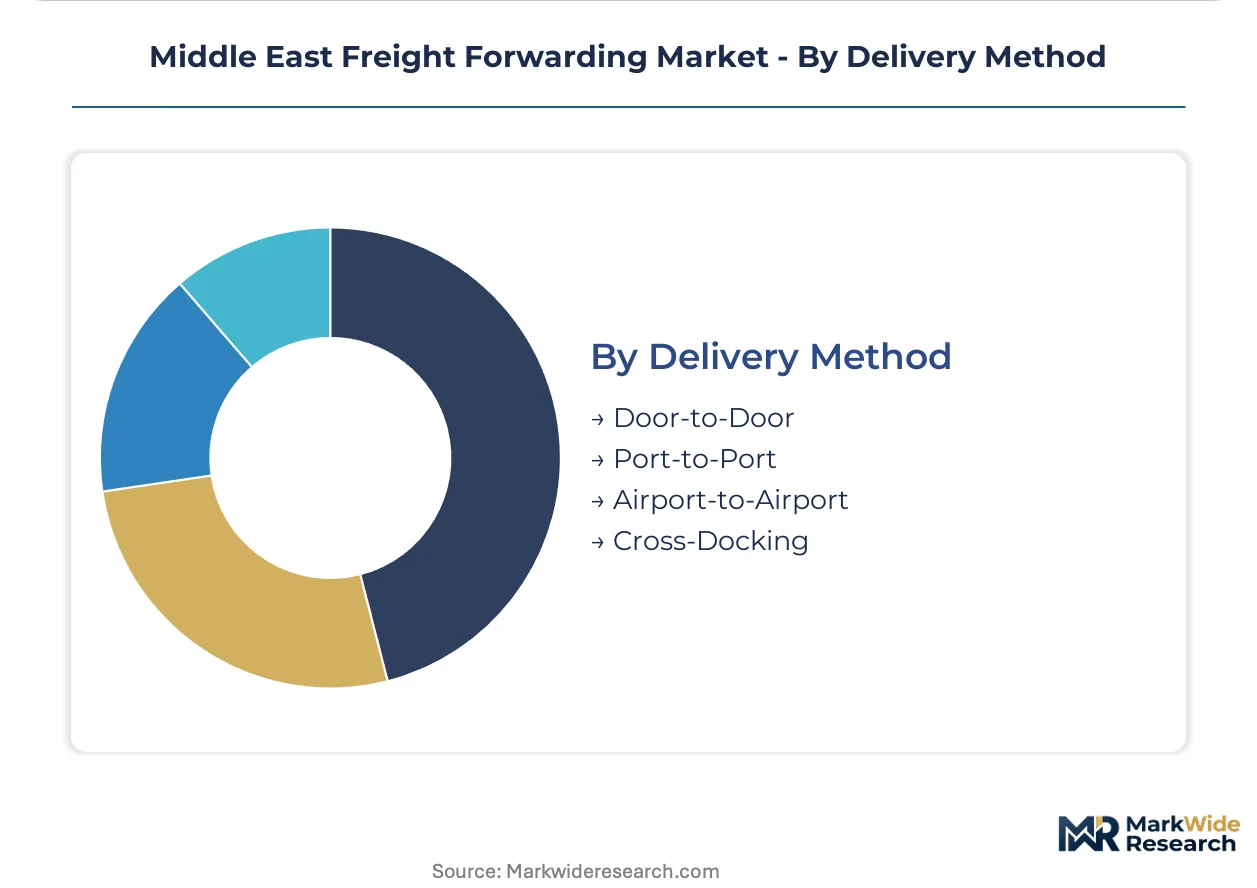
Service level commitments range from asset-light coordination to asset-heavy control, with door-to-door offerings commanding price premiums over terminal-to-terminal alternatives.
- Door-to-Door:End-to-end custody from shipper facility to consignee premises, requiring owned or contracted last-mile fleets. Aramex anchors these networks across the Levant and North Africa through owned gateway facilities.
- Port-to-Port:Ocean terminal-to-terminal coordination, the default for bulk commodity exporters with inland logistics handled separately.
- Airport-to-Airport:Air cargo terminal handoffs, common for pharmaceutical shippers with validated cold-chain infrastructure at both origin and destination.
- Cross-Docking:Rapid freight consolidation and deconsolidation without warehouse storage, serving time-critical retail replenishment cycles.
Contract value concentrates in Door-to-Door; operational complexity favors Cross-Docking for high-velocity retail flows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UAE and Saudi Arabia concentrate forwarding demand through Jebel Ali and King Abdulaziz Port, where petrochemical exports and pharmaceutical imports drive modal preferences. SFDA cold-chain mandates and DP World's port-centric logistics reshape competitive positioning across Gulf trade lanes.
United Arab Emirates
Dubai International and Jebel Ali anchor air and ocean freight flows for perishables and pharma corridors. MOHAP collaborates with DP World on blockchain-based trade documentation to streamline customs clearance. Dubai South logistics zone integrates bonded warehousing with last-mile networks for e-commerce fulfillment.
Saudi Arabia
King Khalid International and King Abdulaziz Port handle temperature-controlled pharmaceutical imports and crude export volumes. SFDA enforces validated thermal packaging with continuous data logging for all imported medicines. Riyadh logistics zones attract bonded warehouse investment from cross-border e-commerce operators.
Kuwait
Shuwaikh Port and Kuwait International Airport serve regional petrochemical and construction material flows. The country's customs authority maintains electronic filing portals with API connectivity requirements for forwarders. Al Ahmadi industrial area concentrates hydrocarbon processing and related logistics demand.
Qatar
Hamad International and Hamad Port support LNG expansion-related project cargo and specialized equipment imports. The national logistics regulator enforces safety protocols for hazardous materials handling in petrochemical corridors. Ras Laffan Industrial City generates heavy-lift and oversized cargo forwarding requirements.
Iraq
Umm Qasr port expansion and Basra gateway development create overland corridor opportunities into Iraqi manufacturing zones. The country's port modernization program targets reduced dwell times and improved customs efficiency. Baghdad and Basra metropolitan areas concentrate consumer goods import demand.
Middle East Freight Forwarding Market Competitive Landscape
Capacity expansion dominates the current landscape as port operators and forwarders deploy validated cold-chain infrastructure to meet SFDA mandates. The market structures around three tiers: global integrators with pharmaceutical certifications, regional specialists with owned gateway networks, and asset-light brokers serving spot markets. Swiss-origin certification holders and UAE-based port operators occupy distinct strategic positions. Competitive moves center on bonded warehouse scaling and multimodal integration from vessel to last-mile.
Among global logistics integrators, Kuehne + Nagel and DHL Group represent the certified pharmaceutical forwarding tier with temperature-controlled infrastructure. DP World anchors port-centric logistics through Jebel Ali Free Zone integration. Regional specialists including Aramex and Almajdouie Logistics occupy positions across Levant and North Africa gateway networks. These archetypes illustrate how certification requirements and asset control separate competitive positioning across Gulf forwarding markets.
| Leading Market Players |
|---|
| Almajdouie Logistics |
| Kuehne + Nagel |
| DHL Group |
| DB Schenker |
| CEVA Logistics |
| Aramex |
| Al-Futtaim Logistics |
| Gulf Agency Company |
| DP World |
| Others |
Pricing and Supply Chain Analysis
Certified reefer technician scarcity across the Gulf states widens labor-cost differentials between premium cold-chain operators and standard freight brokers, compressing margin spreads at the economy tier while elevating pricing power for SFDA-validated service providers.
Pricing Analysis
Volume concentrates in ocean freight contract structures while margins concentrate in air freight pharmaceutical corridors. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and real-time tracking capability. Cost compression in standard ocean forwarding is intensifying because carrier alliance concentration limits rate negotiation leverage for independent brokers. E-commerce distributors exhibit highest price sensitivity; pharmaceutical manufacturers show lowest sensitivity given regulatory compliance requirements.
Supply Chain Analysis
Hub-and-spoke distribution through Jebel Ali and Dubai South handles transshipment flows into Saudi Arabia, Kuwait, and Qatar. Equipment sourcing draws from China, South Korea, and Germany for reefer container manufacturing. Resin and fiber supply volatility for composite flooring alternatives creates raw material cost uncertainty. Single-source vulnerability sits with Emirates SkyCargo and Saudia Cargo belly-hold capacity dominance on East Africa and European pharma lanes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where SFDA cold-chain mandates force capital-starved regional brokers toward acquisition or exit.
For Market Incumbents: Deploy blockchain-integrated documentation platforms to defend against DP World's port-centric logistics integration. Acquire certified reefer technician training programs to address Gulf-wide workforce scarcity. Lock multi-year pharmaceutical contracts before CEIV Pharma certification deadlines marginalize uncertified competitors. For New Entrants and Emerging Players: The premium-to-economy price gap in Iraqi overland corridors offers white-space positioning before Umm Qasr modernization completes. Target bonded warehouse operations in Riyadh logistics zones where e-commerce fulfillment demand outstrips integrated customs clearance supply. Lead with digital freight exchange platforms serving mid-market distributors with irregular shipping patterns. For Investors and Strategic Acquirers: Re-rating potential sits with Swiss-origin certified pharmaceutical forwarders given SFDA validation protocol acceleration. Long-term viability favors operators with captive cold-chain infrastructure across the 5-to-10-year regulatory tightening horizon. Monitor Iraq port modernization completion rates as inflection indicator for overland corridor investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| CEIV Pharma Certification Investment | SFDA mandates now require validated thermal infrastructure for Saudi market access. |
| Bonded Warehouse Scale-Up | Dubai South and Riyadh zones capture e-commerce fulfillment fragmentation toward smaller parcel volumes. |
| Blockchain Trade Documentation | MOHAP collaboration with DP World streamlines customs clearance at Jebel Ali transshipment hub. |
| Iraq Overland Corridor Development | Umm Qasr expansion creates first-mover positioning into Baghdad and Basra manufacturing zones. |
| Composite Container Fleet Conversion | Sustainability procurement criteria in European destination markets accelerate tropical hardwood substitution. |
Research Methodology
Document review covered customs authority filings, carrier alliance capacity disclosures, and pharmaceutical regulator guidance documents, complemented by interviews with freight forwarding operations directors, cold-chain compliance officers, bonded warehouse managers, and e-commerce logistics procurement leads. Secondary validation drew from SFDA import documentation requirements, UAE Federal Tax Authority electronic filing protocols, and DP World port throughput statistics. Bottom-up volume modeling and top-down market sizing were triangulated against trade flow data.
Historical volume trajectories were cross-referenced against expert panel input on regulatory implementation timelines and carrier deployment schedules. Segmentation modeling covered service modality, end-user sophistication tier, technology adoption stage, and delivery method commitment level across the projection horizon. CAGRs were derived from regression analysis of modal share shifts and pharmaceutical import growth patterns, incorporating reefer fleet expansion rates and customs automation penetration assumptions.
Inputs from Saudi ZATCA and UAE FTA electronic filing portals were available through the study window; gaps in real-time reefer utilization data introduce uncertainty bands around temperature-controlled volume estimates. Forecasts reflect assumptions about SFDA enforcement consistency and Iraq port modernization progress. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Europe Chemical Logistics Market
Logistics and Shipping
US Express Delivery Market
Logistics and Shipping
Turkey Freight and Logistics Market
Logistics and Shipping
Freight Forwarding Market
Logistics and Shipping
Turkey Third Party Logistics (3PL) Market
Logistics and Shipping
Fifth-Party Logistics Market
Logistics and Shipping
Cambodia Freight and Logistics Market
Logistics and Shipping
Georgia Freight and Logistics Market
Logistics and Shipping
US Mexico Cross Border FTL Freight Transport Market
Logistics and Shipping
Europe Refrigerated Container Shipping Market
Logistics and Shipping
Empty Container Repositioning Optimization Platforms Market
Logistics and Shipping
US Retail Logistics Market
Logistics and Shipping
Latin America Container Terminal Operations Market
Logistics and Shipping
Europe Full Container Load (FCL) Market
Logistics and Shipping
Peru Road Freight Transport Market
Logistics and Shipping
Australia Last Mile Delivery Market