
 Repositioning and Offloading Market | 2026-2036
Repositioning and Offloading Market Size, Share, and Industry Trends Forecast 2026-2036
Repositioning and Offloading Market Analytics
Buyer concentration among integrated health networks is hardening as hospital systems consolidate vendor contracts for pressure injury prevention equipment. Stryker leverages its bed-therapy integration platform to capture bundled procurement decisions. Medline Industries, LP sustains private-label positioning across mid-tier acute care facilities. Mölnlycke Health Care AB anchors its presence through advanced wound care adjacencies that reinforce offloading product pull-through.
Repositioning and offloading encompasses mechanical and powered devices engineered to redistribute body weight, maintain tissue perfusion above 32 mmHg threshold, and prevent ischemic pressure damage in immobilized patients. These systems integrate load-cell sensors, low-air-loss surfaces, or lateral rotation mechanisms to achieve continuous microclimate control and positional change automation. Logistics services dominate revenue flow by managing equipment deployment cycles and reverse logistics for rental fleets. IoT-enabled asset tracking represents the fastest-expanding technology segment as facilities demand real-time utilization metrics and predictive maintenance alerts. Cold chain applications remain nascent but carry premium margin potential for temperature-sensitive therapeutic surfaces.
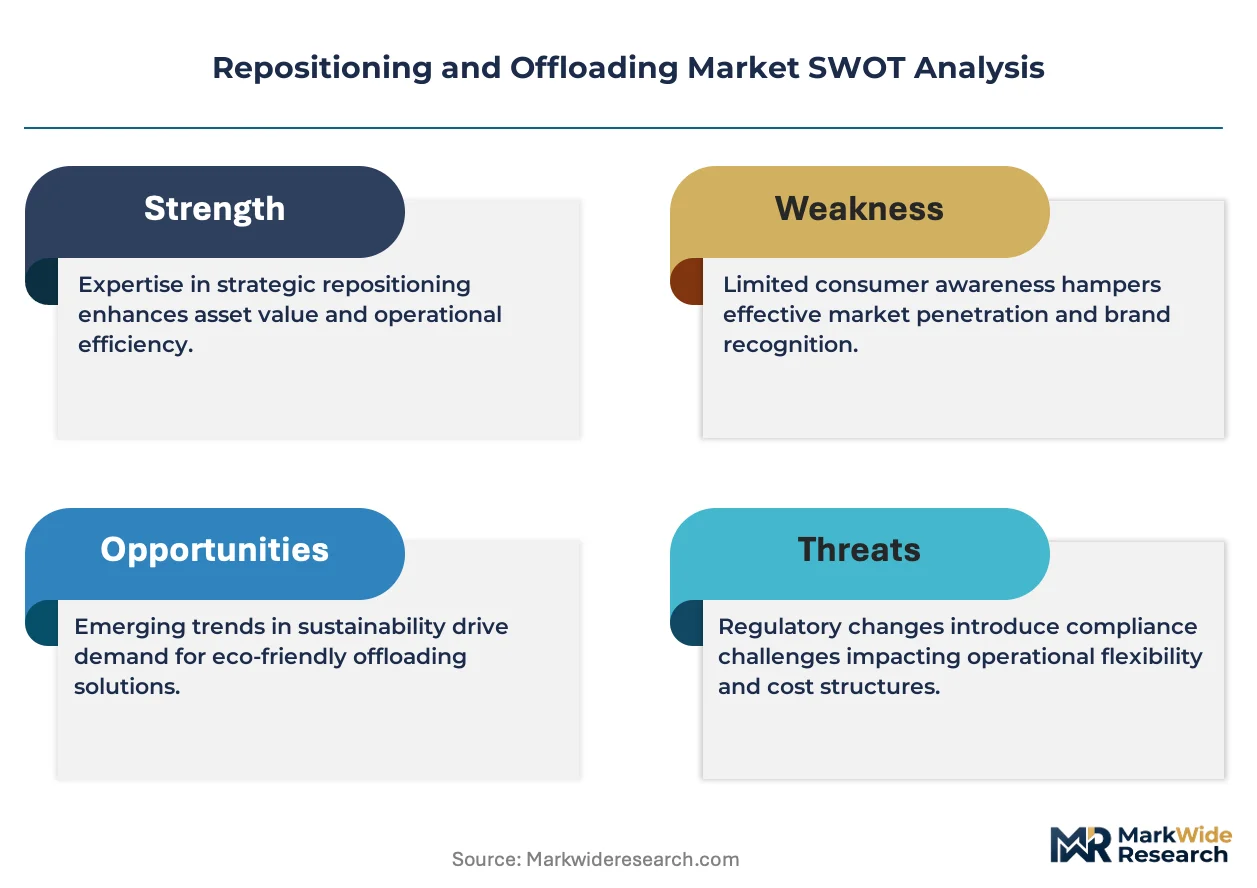
FDA 510(k) premarket notification requirements govern powered surface classifications, while EU MDR technical documentation demands intensify conformity assessment burdens for European market access. The EU AI Act and FDA software-as-medical-device guidance increasingly intersect with algorithmic repositioning protocols, creating dual compliance exposure for smart surface manufacturers. Stakeholders must monitor evolving software validation standards and reimbursement code granularity to secure favorable coverage decisions for automated repositioning interventions.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins and privileging integrated platform suppliers who can bundle repositioning surfaces with bed frames, patient monitoring, and service contracts under single-source agreements.
Growth Catalysts
- Aging demographics in Germany:Federal reimbursement clarity for powered repositioning systems accelerates clinical adoption in acute and long-term care facilities.
- FDA 510(k) pathway streamlining:Predicate device availability for low-air-loss surfaces shortens time-to-market for incremental innovations in pressure injury prevention.
- IoT sensor integration:Real-time load-cell monitoring and predictive maintenance alerts are converting rental fleet operators toward connected asset management platforms.
Market Restraints
- EU MDR documentation burden:Intensified conformity assessment timelines for powered surfaces delay European market entry and strain smaller manufacturers' regulatory resources.
- Specialized polymer supply concentration:Medical-grade polyurethane foam production clusters in select Asian manufacturing hubs, exposing finished goods producers to freight volatility and input cost swings.
- Manual repositioning protocols:Low-tech turning schedules and caregiver labor arbitrage in underfunded long-term care facilities substitute for automated systems in price-sensitive segments.
Strategic Opportunities
- Home care transition acceleration:Post-acute discharge protocols in the United States are creating demand for portable offloading cushions and rental-to-purchase conversion models.
- EU AI Act compliance premium:Algorithmic repositioning protocols that meet software-as-medical-device validation standards command favorable reimbursement positioning and procurement preference.
- Cold chain therapeutic surfaces:Temperature-sensitive wound healing adjacencies represent untapped margin expansion for logistics providers with existing rental infrastructure.
Industry Challenges
- Biomedical technician shortage:Skilled labor gaps in preventive maintenance for powered rotation systems extend equipment downtime and erode fleet utilization metrics.
- Legacy EHR integration friction:Proprietary data protocols from incumbent bed manufacturers block seamless flow of repositioning compliance data into hospital quality dashboards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Repositioning and Offloading Market |
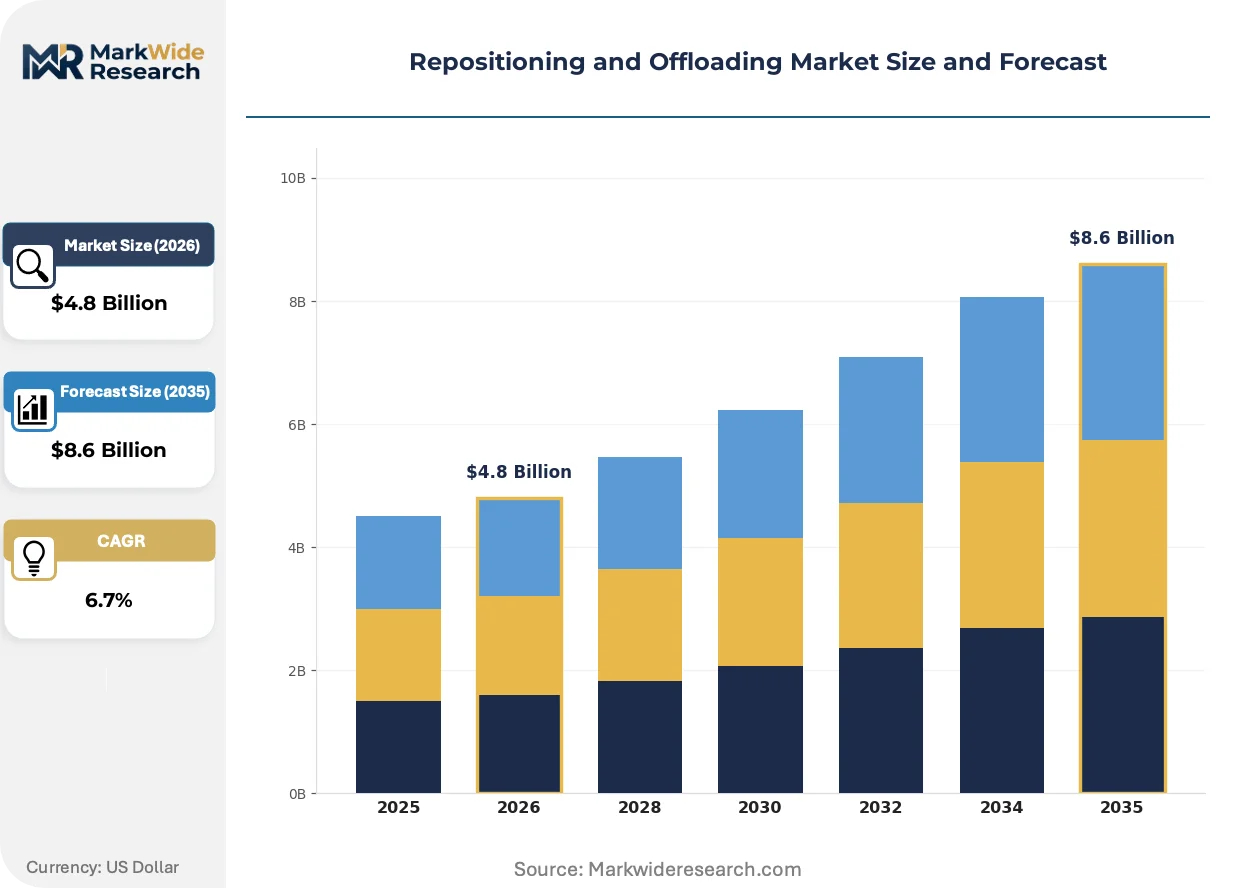
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
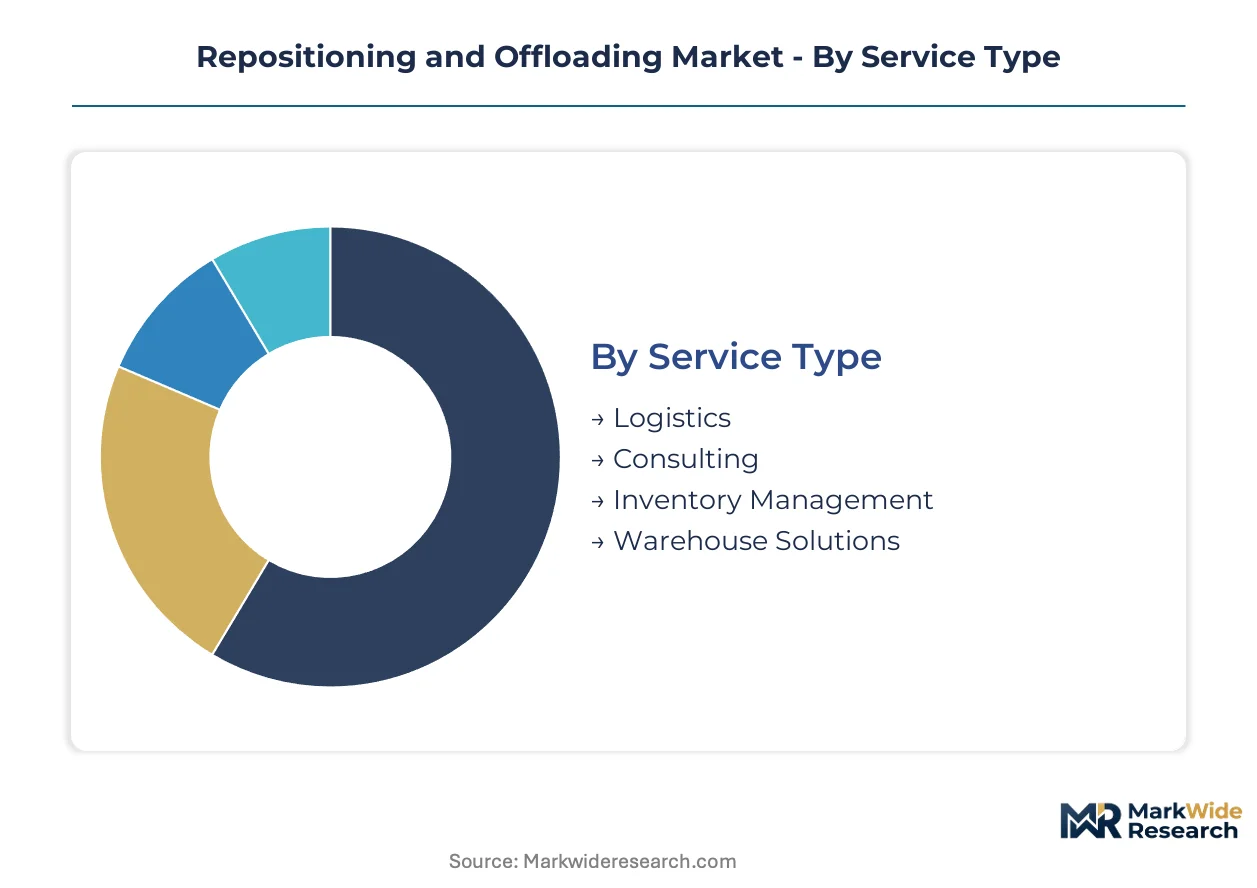
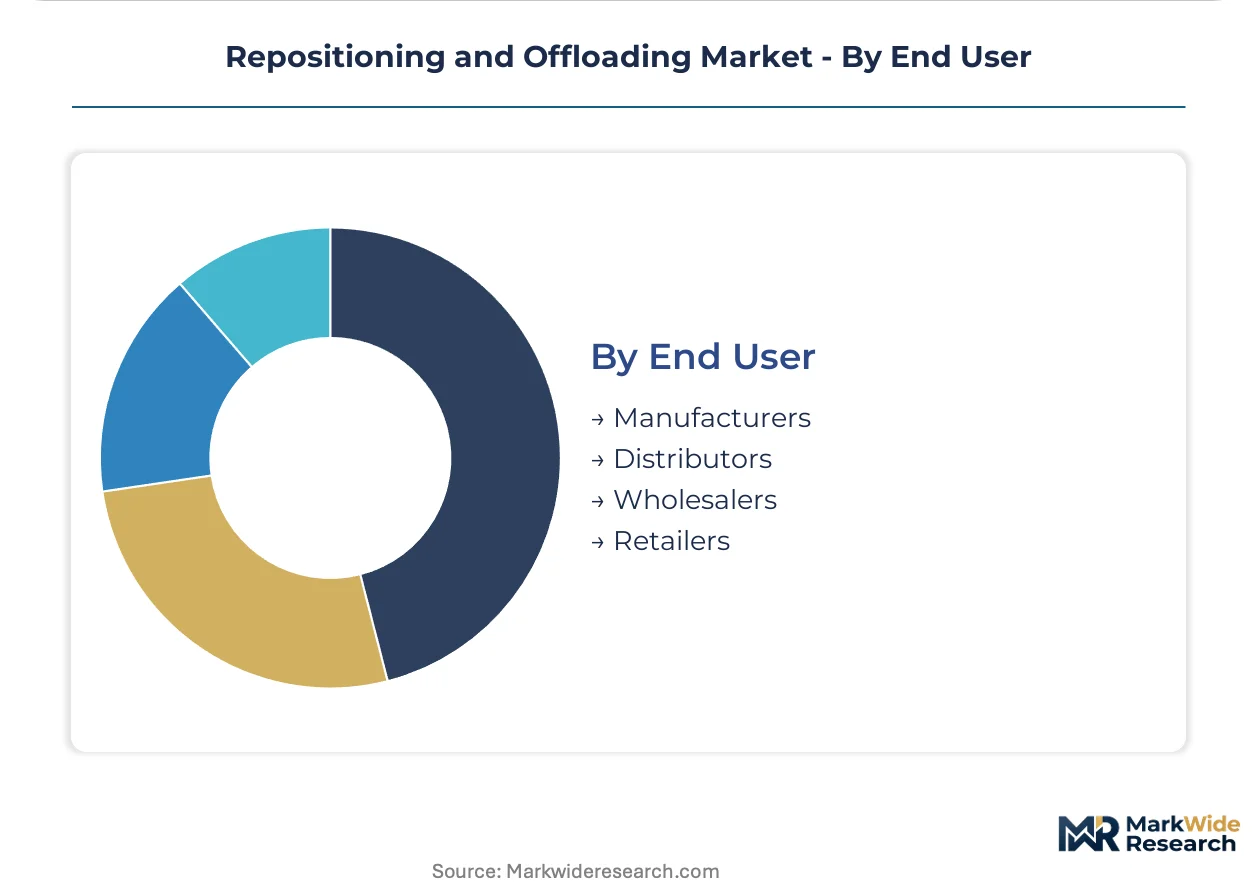
| Segmentation | Service Type: Logistics, Consulting, Inventory Management, Warehouse Solutions Application: Retail, E-commerce, Transportation, Supply Chain Management Technology: Automation, IoT, Data Analytics, Cold Chain End User: Manufacturers, Distributors, Wholesalers, Retailers |
| Companies Covered | Stryker, Medline Industries, LP, Hill-Rom Services, Inc., Mölnlycke Health Care AB, Arjo Group, Permobil AB, Guldmann A/S, Sage Products LLC, Frontier Medical Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Repositioning and Offloading Market Evolving Landscape
Automation of positional change protocols is absorbing capital investment across acute care settings, while regulatory software validation requirements and procurement model compression reshape competitive differentiation.
Predictive load-sensing algorithms embedded in mattress surfaces is absorbing clinical workflow design as nursing leadership seeks to reduce documentation burden for turn compliance. Academic medical centers in the United States pilot these systems fastest, though community hospitals lag in capital allocation. The technology is absorbing budget share from standalone pressure mapping devices by integrating surveillance and intervention into single platforms.
The EU AI Act's risk classification framework for algorithmic medical devices is forcing manufacturers to restructure software development lifecycle documentation before 2026 enforcement deadlines. Technical file requirements now encompass training data provenance and post-market performance monitoring plans. Powered surface developers with European market exposure are responding by segregating AI-enabled and non-AI product variants to manage compliance cost stratification.
Integrated delivery networks are consolidating equipment procurement decisions at system-level committees, displacing individual facility purchasing autonomy. Regional GPOs and direct manufacturer contracts are replacing distributor intermediaries for high-volume surface categories. This concentration is most advanced in the United States, where three national hospital systems now control a disproportionate share of acute care bed capacity and standardize on single-vendor platforms.
Repositioning and Offloading Market Segmentation
Repositioning and offloading equipment serves heterogeneous care settings with divergent technical requirements and procurement pathways. Segment boundaries reflect how supply chain configuration, clinical workflow integration, and regulatory burden stratify vendor economics across acute, post-acute, and home-based deployments.
Service Type:
Equipment deployment cycles concentrate revenue in logistics operators with reverse logistics capabilities for rental fleet rotation. Smaller consultancies and inventory platforms compete on implementation speed rather than asset scale.
- Logistics:Fleet rotation, preventive maintenance scheduling, and depot refurbishment absorb the majority of contract value in rental-dominated procurement models. Demand clusters in Germany's long-term care networks where federal reimbursement clarity supports multi-year service agreements.
- Consulting:Workflow design and pressure injury prevention protocol implementation command premium pricing in academic medical centers pursuing turn compliance automation. US hospital systems bundle these services with capital equipment purchases to reduce nursing documentation burden.
- Inventory Management:Real-time asset tracking and utilization optimization for surface fleets.
- Warehouse Solutions:Centralized depot operations for equipment staging and refurbishment.
Today's leader: Logistics. Tomorrow's challenger: Consulting.
Application:
Clinical settings impose divergent performance specifications on surface technologies, with acute care demanding continuous microclimate control and post-acute facilities prioritizing portability.
- Retail:Direct-to-consumer sales of offloading cushions and portable positioning devices through durable medical equipment channels. E-commerce platforms accelerate access for home care transitions in the United States.
- E-commerce:Digital procurement portals for hospital systems consolidating vendor contracts under single-source agreements. Integrated delivery networks leverage volume concentration to extract service bundling concessions.
- Transportation:Mobile surface solutions for emergency medical services and inter-facility patient transfer.
- Supply Chain Management:Vendor-managed inventory programs for pressure injury prevention equipment.
E-commerce is gaining share fastest as procurement centralization hardens buyer concentration.
Technology:
Regulatory software validation requirements and predictive maintenance economics are reshaping R&D allocation across hardware and algorithmic development teams.
- Automation:Powered rotation mechanisms and algorithmic repositioning protocols redistribute body weight without caregiver intervention. FDA software-as-medical-device guidance and EU AI Act risk classifications impose dual compliance burdens on developers.
- IoT:Load-cell sensors and real-time utilization tracking convert rental fleets toward connected asset management platforms. Predictive maintenance alerts reduce biomedical technician dispatch frequency and extend equipment uptime.
- Data Analytics:Turn compliance dashboards and quality metric integration for hospital EHR systems.
- Cold Chain:Temperature-sensitive therapeutic surfaces for wound healing adjacencies.
Automation commands current R&D budgets. IoT carries the steepest expansion trajectory as fleet operators retrofit existing assets.
End User:
Procurement authority concentration varies sharply across end-user categories, with integrated health networks displacing individual facility purchasing autonomy.
- Manufacturers:Medical-grade polyurethane foam producers and surface assembly operations in select Asian manufacturing hubs. Freight volatility and input cost swings expose finished goods producers to margin compression.
- Distributors:Regional equipment lessors and service providers managing deployment cycles for acute care facilities. Consolidating hospital procurement is compressing intermediary margins and privileging direct manufacturer contracts.
- Wholesalers:Bulk procurement intermediaries for mid-tier long-term care chains.
- Retailers:Durable medical equipment suppliers serving post-acute discharge and home care segments.
Manufacturers anchor upstream supply. Distributors face the most acute margin pressure from procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled biomedical technician pools in Germany and the United States anchor the highest concentration of powered repositioning system deployments. Regulatory clarity in these markets accelerates clinical adoption timelines.
United States
Integrated delivery networks in Texas and Florida drive procurement consolidation for pressure injury prevention equipment. FDA 510(k) premarket notification pathways streamline predicate-based clearances for low-air-loss surface innovations. The Southeast corridor clusters rental fleet operations serving post-acute discharge protocols.
Germany
Federal reimbursement codes for powered repositioning systems accelerate clinical adoption in Bavarian and North Rhine-Westphalian long-term care networks. EU MDR technical documentation requirements intensify conformity assessment burdens for surface manufacturers. The Baden-Württemberg medical technology corridor hosts refurbishment depots for rental fleet rotation.
Japan
Aging demographics in Kanto and Kansai regions sustain demand for automated patient mobility solutions. PMDA software-as-medical-device guidance intersects with algorithmic repositioning protocol validation. The Nagoya medical device cluster concentrates polyurethane foam sourcing for therapeutic surface assembly.
United Kingdom
NHS procurement frameworks centralize equipment purchasing decisions across integrated care systems in England. MHRA post-Brexit regulatory alignment with EU MDR extends conformity assessment timelines. The Midlands manufacturing belt hosts contract assembly operations for European market-bound surfaces.
China
Hospital infrastructure expansion in Yangtze River Delta and Pearl River Delta regions absorbs imported powered repositioning technologies. NMPA Class II medical device registration requirements govern surface classifications for domestic market entry. The Suzhou medical technology zone attracts joint ventures for localized therapeutic surface production.
Repositioning and Offloading Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across repositioning and offloading market tiers. Hospital procurement consolidation privileges integrated platform suppliers who bundle surfaces, bed frames, and service contracts under single-source agreements. Three archetypes dominate: diversified medical technology conglomerates with bed-therapy integration platforms, private-label distributors serving mid-tier acute care facilities, and wound care specialists leveraging adjacency pull-through. Competitive moves center on direct manufacturer contracting with consolidating health networks and IoT-enabled asset tracking platform development.
Among diversified medical technology conglomerates, Stryker and Hill-Rom Services, Inc. exemplify platform integration strategies that capture bundled procurement decisions. Medline Industries, LP occupies a position within private-label distribution archetypes serving price-sensitive facility segments. Mölnlycke Health Care AB anchors the wound care adjacency tier where offloading products reinforce broader clinical portfolio pull-through.
| Leading Market Players |
|---|
| Stryker |
| Medline Industries, LP |
| Hill-Rom Services, Inc. |
| Mölnlycke Health Care AB |
| Arjo Group |
| Permobil AB |
| Guldmann A/S |
| Sage Products LLC |
| Frontier Medical Group |
| Others |
Value Network & Pricing Analysis
Captive control over medical-grade polyurethane foam production in select Asian manufacturing hubs anchors both supply security and pricing leverage for finished goods producers. This backward integration into polymer sourcing buffers margin erosion while exposing non-integrated competitors to freight volatility and input cost swings.
Pricing Analysis
Capacity additions in China's Yangtze River Delta medical technology zones are reshaping price floors for therapeutic surface assemblies. Contract-based long-term offtake agreements dominate procurement between German long-term care networks and fleet operators, with price differentiation hinging on FDA 510(k) certification tier and bundled service scope. Cost compression in mid-tier acute care segments is intensifying because hospital procurement consolidation extracts volume concessions. Price sensitivity peaks among underfunded long-term care facilities substituting manual turning protocols, while academic medical centers absorb premium pricing for algorithmic repositioning systems.
Supply Chain Analysis
Reverse logistics flows for rental fleet rotation concentrate refurbishment capacity in Germany's Baden-Württemberg corridor and the US Southeast. Medical-grade polyurethane foam production clusters in China and Japan, while surface assembly operations draw from Taiwanese electronics components for IoT sensor integration. Single-source vulnerability in specialized polymer supply exposes finished goods producers to freight volatility and input cost swings. Distribution runs through regional equipment lessors managing deployment cycles, with direct manufacturer contracts displacing intermediary channels as hospital procurement consolidates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The repositioning and offloading market reads as a late-cycle quality story, with demand shifting toward powered systems featuring algorithmic repositioning protocols and predictive maintenance capabilities.
For Market Incumbents: To counter margin compression from procurement consolidation, Stryker and Hill-Rom Services must deepen captive supply of medical-grade polyurethane foam through backward integration into Asian manufacturing hubs. Certification investment in EU AI Act software validation standards creates procurement preference among German long-term care networks pursuing reimbursement clarity. For New Entrants and Emerging Players: Begin with portable offloading cushions for US post-acute discharge protocols, where rental-to-purchase conversion models remain underpenetrated. Home care transitions offer the most penetrable segment, with e-commerce direct-to-consumer channels providing lower customer acquisition costs than hospital system contracting. For Investors and Strategic Acquirers: Roll-up economics work for regional equipment lessors with reverse logistics capabilities because hospital procurement consolidation privileges scale in fleet management and preventive maintenance scheduling. Watch EU MDR enforcement timelines as inflection indicators for compliance cost stratification between AI-enabled and non-AI product variants.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Predicate device pathways accelerate time-to-market for low-air-loss surface innovations in acute care. |
| EU AI Act Compliance Pathway | Software validation documentation secures favorable reimbursement positioning in German long-term care networks. |
| Hospital System Partnership | Single-source agreements with integrated delivery networks in Texas and Florida capture bundled procurement decisions. |
| Software Companion Development | Predictive load-sensing algorithms reduce nursing documentation burden and displace standalone pressure mapping devices. |
| Reimbursement Strategy | Federal code clarity for powered repositioning systems accelerates clinical adoption in Bavarian care facilities. |
Research Methodology
Multiple input streams — primary interviews with biomedical engineers, GPO contracts managers, and hospital purchasing committees; secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, and hospital procurement records; plus customs trade data for medical-grade polyurethane foam — were reconciled through bottom-up and top-down triangulation.
Historical shipment data for powered and manual surface categories were cross-referenced against panel input from fleet operators and refurbishment depot managers across the analysis window. Segmentation dimensions modeled include service type, application, technology, and end user, with CAGRs derived from regression analysis of equipment deployment cycles and rental fleet rotation patterns. EU MDR documentation timelines and FDA software-as-medical-device guidance evolution served as regulatory scenario inputs.
Several conditions sit outside the modeled scope, including geopolitical disruptions to Asian polymer supply chains and abrupt shifts in US Medicare reimbursement codes. Forecasts reflect assumptions about continued hospital procurement consolidation and EU AI Act enforcement sequencing. Practitioners should monitor biomedical technician labor pool tightness and legacy EHR integration friction for early signals of fleet utilization erosion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Colombia Freight and Logistics Market
Logistics and Shipping
Malaysia Freight and Logistics Market
Logistics and Shipping
Food Delivery Logistic Market
Logistics and Shipping
Netherlands Freight and Logistics Market
Logistics and Shipping
Inbound Logistics Market
Logistics and Shipping
United Arab Emirates (UAE) Third-Party Logistics (3PL) Market
Logistics and Shipping
Peru Freight and Logistics Market
Logistics and Shipping
South Korea Third-Party Logistics (3PL) Market
Logistics and Shipping
Mexico Road Freight Transport Market
Logistics and Shipping
Peru Logistics Market
Logistics and Shipping
Egypt Freight and Logistics Market
Logistics and Shipping
China Same Day Delivery Market
Logistics and Shipping
Nordics Freight and Logistics Market
Logistics and Shipping
Singapore Shipping Agency Services Market
Logistics and Shipping
GCC Warehousing and Distribution Logistics Market
Logistics and Shipping
Finished Vehicle Logistics Market