
 Nigeria Courier, Express, and Parcel (CEP) Market | 2026-2036
Nigeria Courier, Express, and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Courier, Express, and Parcel (CEP) Market Insights
Same-day service tier is bifurcating the competitive landscape between premium-positioned operators and volume-focused ground networks. DHL Group leverages its international gateway infrastructure to sustain cross-border express dominance. GIG Logistics anchors domestic last-mile density through proprietary hub-and-spoke configurations. Red Star Express PLC differentiates via specialized document and pharmaceutical cold-chain handling.
Courier, Express, and Parcel services constitute time-definite logistics solutions utilizing standardized consignment tracking, weight-tiered tariff structures, and multimodal dispatch protocols to facilitate commercial goods movement. The sector's primary purpose centers on reducing inventory cycle times for trade-dependent enterprises. Next-day and scheduled delivery segments command premium margin pools as reliability-sensitive industries prioritize predictability over cost minimization. E-commerce customer type is expanding fastest, though ground delivery method retains volume leadership due to infrastructure economics across Nigeria's road network.
Nigeria's postal regulator and the country's national standards body shape market access through licensing classifications and vehicle safety mandates for commercial fleet operators. Central Bank of Nigeria payment system integration requirements further influence cash-on-delivery versus digital settlement workflows. Stakeholders must monitor regulatory harmonization between federal transport authorities and state-level motor licensing boards to anticipate compliance cost trajectories.
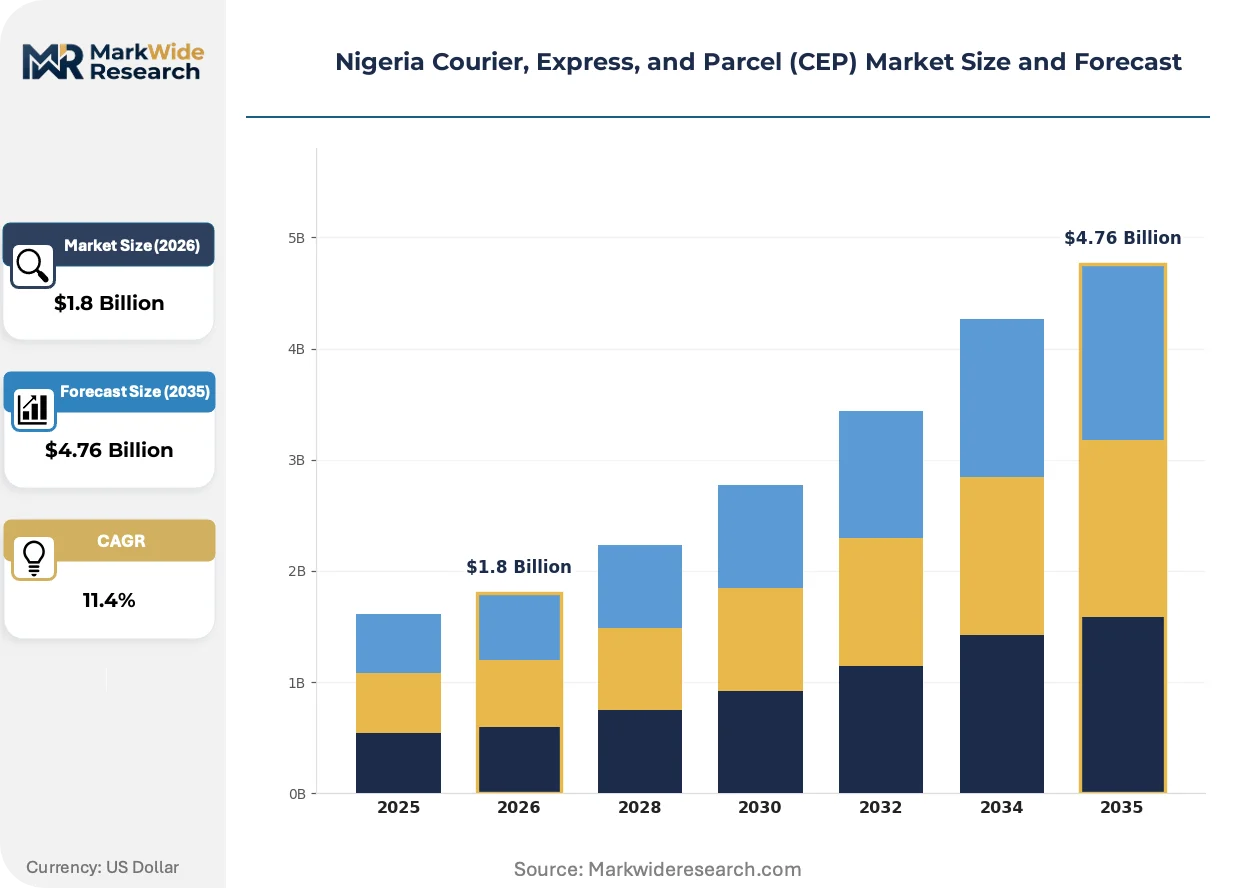
Market Dynamics
The Nigerian CEP sector is restructuring around same-day service tiering, as premium operators and volume-ground networks diverge on capital deployment and network density strategies.
Growth Catalysts
- E-commerce merchant expansion:Digital retail platforms in Lagos and Abuja are generating parcel volume surges that strain legacy postal infrastructure. Fulfillment center buildouts in southwestern urban corridors accelerate last-mile density requirements.
- Nigerian Postal Service modernization:The postal regulator's revised licensing frameworks for digital logistics providers are lowering market entry barriers for technology-enabled dispatch platforms. New classifications recognize multimodal operators distinct from traditional mail carriers.
- Central Bank payment integration:Settlement infrastructure mandates are shifting cash-on-delivery workflows toward digital payment rails. This reduces reconciliation friction for cross-border express shipments and domestic scheduled deliveries alike.
Market Restraints
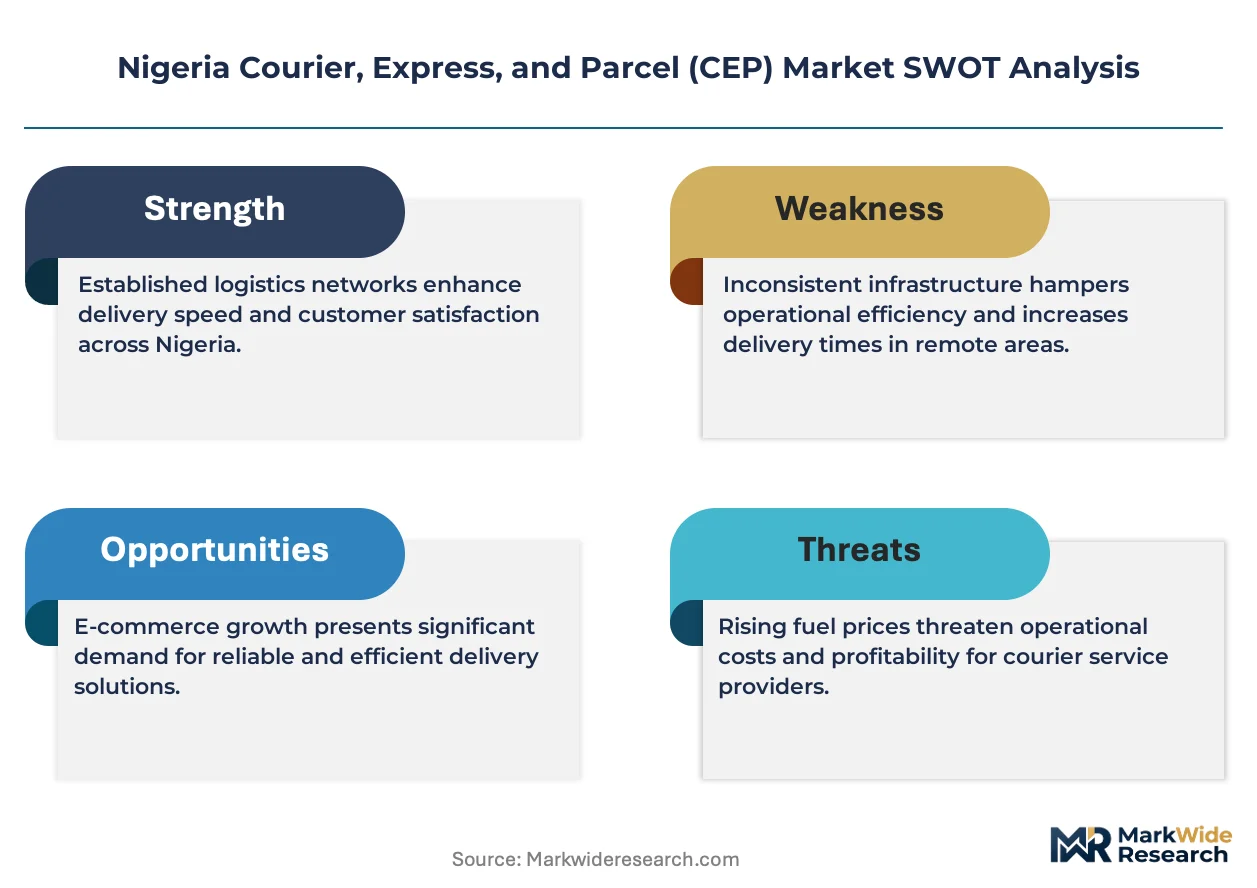
- Fuel cost volatility:Diesel price fluctuations directly compress ground delivery margins across Nigeria's road-dependent network. Fleet operators lack fuel surcharge mechanisms that protect international gateway carriers.
- State-level licensing fragmentation:Motor vehicle licensing boards across Nigerian states impose inconsistent commercial fleet documentation requirements. Interstate operators face compliance cost multiplication.
- Road infrastructure degradation:Federal highway maintenance gaps extend transit times between hub-and-spoke nodes. Predictability erosion undermines next-day service guarantees outside major urban corridors.
Strategic Opportunities
- Northern Nigeria corridor development:Kano and Kaduna urban clusters remain underpenetrated by integrated express networks. Proprietary sorting facilities in these nodes would capture agricultural commodity reverse logistics.
- Pharmaceutical cold-chain specialization:Temperature-controlled last-mile capabilities for vaccines and biologics represent uncrowded service tier. Nigerian drug manufacturers currently rely on fragmented third-party cold storage.
- Mobile-first tracking convergence:Integration of USSD interfaces with GPS telemetry is miniaturizing customer-facing visibility tools. This enables feature-phone penetration in rural delivery zones.
Industry Challenges
- Commercial driver certification gaps:Heavy goods vehicle licensing lacks standardized safety training modules. Fleet operators absorb accident liability exposure that international competitors transfer to contracted partners.
- Hub automation capex requirements:Sortation robotics deployment demands capital commitments that domestic operators struggle to finance. Foreign exchange scarcity complicates equipment importation timelines.
- Legacy IT integration friction:Enterprise shippers require API connectivity that smaller ground networks cannot support. Middleware development costs concentrate contract wins among technology-capable incumbents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Courier, Express, and Parcel (CEP) Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same Day, Next Day, Scheduled Delivery, International Shipping Delivery Method: Ground, Air, Sea, Bicycle Customer Type: Individuals, Businesses, E-Commerce, Retailers Packaging Type: Boxes, Envelopes, Pallets, Crates |
| Companies Covered | DHL Group, Nipost, United Parcel Service of America, Inc. (UPS), Red Star Express PLC, GIG Logistics, Rousy International Ltd., ABC Transport PLC, SkyNet Worldwide Express, FedEx, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Courier, Express, and Parcel (CEP) Market Trends and Innovations
Digital tracking infrastructure and regulatory digitization are compressing service-level differentiation windows. Operators now compete on data transparency rather than transit speed alone.
GPS-telemetry integration with mobile payment platforms is miniaturizing proof-of-delivery verification. E-commerce merchants in Lagos are adopting this at scale for high-value consignments. The structural consequence is collapsing insurance premium differentials between established carriers and emerging dispatch networks.
Nigerian Postal Service licensing digitization is mandating real-time consignment data submission from all commercial operators. This regulatory shift enables regulator-led market transparency dashboards. Domestic ground networks face compliance system investments that cross-border express operators already absorbed through international gateway requirements.
Buyer procurement patterns are compressing contract renewal cycles from annual to quarterly terms. Mid-sized retailers in Abuja are unbundling express services from integrated logistics contracts. This behavior is most visible among fashion and electronics verticals where inventory turnover velocity dictates delivery reliability premiums.
Nigeria Courier, Express, and Parcel (CEP) Market Segmentation
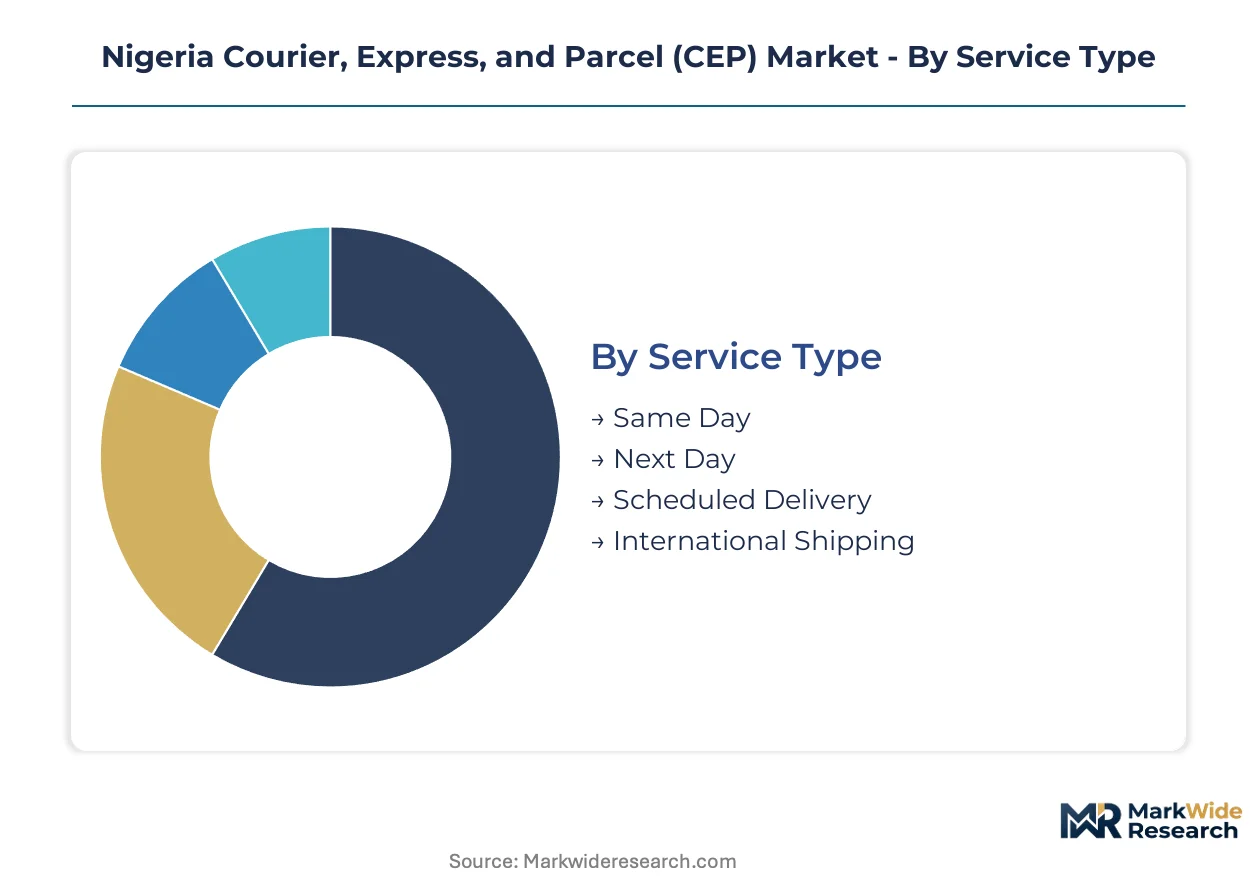
Service tiering across Nigeria's CEP market determines capital deployment intensity and margin capture potential. Channel configuration varies sharply between premium express corridors and cost-optimized ground networks.
Service Type:
Same-day and next-day tiers flow through proprietary hub infrastructure, while scheduled delivery consolidates through third-party ground partnerships.
- Same Day:Time-critical consignments requiring dedicated dispatch capacity and real-time GPS telemetry. Lagos-Abuja corridors concentrate demand as e-commerce merchants compete on fulfillment speed.
- Next Day:Reliability-sensitive shipments utilizing overnight sorting at primary hubs. Pharmaceutical distributors and financial document exchanges prioritize this tier for inventory cycle compression.
- Scheduled Delivery:Pre-allocated slot logistics for recurring B2B volumes. Manufacturing supply chains in southwestern industrial zones anchor this segment's density.
- International Shipping:Cross-border express utilizing gateway customs clearance at Lagos and Abuja airports. Central Bank settlement integration is reshaping documentation workflows.
By volume, Scheduled Delivery leads. By growth pace, Same Day is ahead.
Delivery Method:
Ground networks absorb capital-efficient volume as air freight captures premium perishables and time-definite documentation.
- Ground:Diesel-dependent road haulage across Nigeria's federal highway network. Fleet operators face margin compression from fuel price volatility absent surcharge mechanisms.
- Air:Gateway-constrained express utilizing Murtala Muhammed International Airport sorting facilities. Cross-border pharmaceutical cold-chain requirements concentrate in this tier.
- Sea:Containerized pallet movements for non-urgent bulk freight. Port congestion at Apapa and Tin Can terminals extends transit predictability windows.
- Bicycle:Last-mile micro-fulfillment in Lagos Island and Abuja Central Business District dense zones. Traffic gridlock renders this method cost-competitive for sub-5kg consignments.
Ground dominates absolute volume. Air freight claims the steepest expansion trajectory among premium service tiers.
Customer Type:
E-commerce platforms are unbundling logistics contracts, while traditional retailers consolidate procurement across fewer integrated providers.
- Individuals:Document and personal effects shipments through retail service points. Cash-on-delivery preferences persist outside Lagos digital payment corridors.
- Businesses:Corporate account logistics with quarterly contract renewal cycles. Abuja government procurement offices and financial institutions anchor this segment.
- E-Commerce:Digital merchant fulfillment requiring API-integrated tracking and returns management. Fashion and electronics verticals in Lagos generate the densest parcel flows.
- Retailers:Brick-and-mortar inventory replenishment with scheduled delivery requirements. Southwestern supermarket chains utilize this tier for distribution center coordination.
E-Commerce is expanding most quickly. Businesses retain the largest contract value concentration.
Packaging Type:
Dimensional weight pricing and sortation automation compatibility drive packaging standardization across Nigerian CEP networks.
- Boxes:Corrugated fiberboard containers for general merchandise protection. E-commerce fulfillment centers in Lagos specify standardized dimensions for automated sortation compatibility.
- Envelopes:Lightweight document pouches for financial and legal correspondence. Central Bank payment system mandates are digitizing volumes historically carried in this format.
- Pallets:Unitized freight for B2B manufacturing inputs. Kano and Kaduna industrial clusters generate agricultural processing equipment movements in this category.
- Crates:Reusable rigid packaging for high-value electronics and pharmaceutical cold-chain. Temperature-controlled crate pools remain underdeveloped outside Lagos express corridors.
Boxes command the highest shipment frequency. Crates deliver the strongest margin per consignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nigeria's trade corridors favor import-heavy CEP flows, with Lagos and Abuja absorbing cross-border express volumes while agricultural exports from northern hubs generate underdeveloped return logistics.
Lagos State
E-commerce fulfillment centers and port-adjacent warehousing drive parcel density. Nigerian Postal Service licensing digitization mandates real-time data submission from Murtala Muhammed International Airport operators. Apapa port congestion extends sea freight transit windows, compressing margins for containerized movements.
Federal Capital Territory (Abuja)
Government procurement offices and financial institutions anchor B2B document exchange volumes. Central Bank payment system integration requirements reshape cash-on-delivery workflows toward digital settlement. Central Business District traffic gridlock elevates bicycle courier competitiveness for sub-5kg consignments.
Kano State
Agricultural commodity processing generates palletized freight demand lacking integrated express coverage. State-level motor licensing boards impose documentation requirements distinct from federal standards. Kano urban cluster remains underpenetrated by proprietary hub-and-spoke networks despite reverse logistics potential.
Kaduna State
Industrial equipment imports for agricultural processing create scheduled delivery requirements. Federal highway maintenance gaps between Kaduna and Lagos extend transit predictability windows. Kaduna manufacturing zones currently rely on fragmented third-party logistics for temperature-sensitive pharmaceutical inputs.
Rivers State (Port Harcourt)
Oil sector procurement generates time-definite documentation and spare parts movements. Port Harcourt International Airport lacks dedicated express sorting infrastructure present at Lagos gateway. Onne port container traffic competes with Lagos for non-urgent bulk freight volumes.
Nigeria Courier, Express, and Parcel (CEP) Market Competitive Landscape
Concentration sits with international gateway operators leveraging established customs clearance infrastructure. Domestic ground networks fragment across state-level licensing jurisdictions. Three archetypes dominate: cross-border express specialists with global hub access, proprietary last-mile operators with southwestern density, and diversified transport conglomerates with intermodal assets. Competitive moves center on hub automation investments and API integration capabilities for enterprise shipper contracts.
Within the international express tier, DHL Group and FedEx exemplify gateway-dependent positioning. Among domestic specialists, GIG Logistics and Red Star Express PLC occupy distinct density and specialization vectors. United Parcel Service of America, Inc. bridges both tiers through hybrid international-domestic service configurations. Nipost represents legacy postal infrastructure transitioning toward digital logistics licensing compliance.
| Leading Market Players |
|---|
| DHL Group |
| Nipost |
| United Parcel Service of America, Inc. (UPS) |
| Red Star Express PLC |
| GIG Logistics |
| Rousy International Ltd. |
| ABC Transport PLC |
| SkyNet Worldwide Express |
| FedEx |
| Others |
Pricing and Supply Chain Analysis
Next-day inventory compression cycles of 18-24 hours concentrate pricing power among operators with proprietary Lagos-Abuja hub infrastructure, while diesel-dependent ground networks absorb margin erosion from fuel volatility. E-commerce merchants in southwestern urban corridors negotiate quarterly contract terms that unbundle express services from integrated logistics, compressing price premiums for reliability-sensitive shipments.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across scheduled delivery tiers, with pharmaceutical distributors and financial institutions commanding premium positioning through certification-grade service guarantees. Price differentiation hinges on GPS-telemetry integration density and Central Bank payment system compliance status, with volume scale discounts penetrating mid-sized retailer segments. Pricing pressure stems from fuel cost volatility that ground networks cannot pass through surcharge mechanisms, rendering bicycle courier methods cost-competitive for sub-5kg consignments in Lagos Island dense zones. E-commerce platforms exhibit highest price sensitivity as they unbundle logistics contracts quarterly, while government procurement offices in Abuja retain lowest sensitivity due to reliability prioritization over cost minimization.
Supply Chain Analysis
Apapa port congestion underwrites supply chain risk concentration for containerized sea freight movements, with sorting automation equipment importation timelines extending due to foreign exchange scarcity. Geographic supply concentration centers on China for sortation robotics and GPS telemetry hardware, South Africa for commercial fleet vehicle assemblies, and UAE for cross-border express gateway coordination. Raw material dependencies encompass diesel fuel hedging instruments, corrugated fiberboard packaging from domestic mills, and temperature-controlled crate pools for pharmaceutical cold-chain. Single-source vulnerability persists in automated sortation technology procurement where domestic operators lack financing alternatives. Distribution runs through proprietary hub-and-spoke configurations in southwestern urban corridors, with third-party ground partnerships filling northern Nigeria coverage gaps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nigeria's CEP sector represents early-cycle expansion anchored by e-commerce merchant penetration in Lagos and Abuja, with Nigerian Postal Service licensing digitization accelerating technology-enabled dispatch platform adoption.
For Market Incumbents: Consolidate proprietary hub density in southwestern urban corridors against emerging API-integrated dispatch platforms that threaten enterprise shipper contracts. Acquire automated sortation capabilities through equipment financing partnerships that circumvent foreign exchange scarcity constraints. Deepen backward integration into temperature-controlled crate pools for pharmaceutical cold-chain specialization. For New Entrants and Emerging Players: Lead with mobile-first tracking convergence targeting rural delivery zones through USSD-GPS telemetry integration for feature-phone penetration. Target Kano and Kaduna urban clusters where agricultural commodity reverse logistics lacks integrated express coverage. Pursue pharmaceutical cold-chain specialization as uncrowded service tier with Nigerian drug manufacturers currently relying on fragmented third-party cold storage. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified transport conglomerates with underutilized intermodal assets in northern Nigeria corridors. Long-term viability favors operators with regulatory compliance systems already absorbing Nigerian Postal Service real-time data submission mandates. Monitor Central Bank payment integration penetration as inflection indicator for cash-on-delivery displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Hub Automation Investment | Sortation robotics deployment at Lagos-Abuja nodes compresses per-parcel handling costs for next-day tier reliability. |
| API Integration Development | Middleware connectivity captures enterprise shipper contracts from fragmented ground networks lacking IT capabilities. |
| Pharmaceutical Cold-Chain Buildout | Temperature-controlled last-mile capabilities address vaccine and biologics distribution gaps outside Lagos express corridors. |
| Northern Corridor Expansion | Proprietary sorting facilities in Kano and Kaduna capture agricultural commodity reverse logistics currently served by fragmented providers. |
| Mobile-First Tracking Convergence | USSD-GPS telemetry miniaturization enables feature-phone penetration in rural delivery zones beyond smartphone-dependent platforms. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through primary interviews with e-commerce logistics directors, fleet operations managers at ground networks, Nigerian Postal Service regulatory affairs leads, pharmaceutical distribution procurement heads, and Central Bank payment system integration specialists. Secondary validation drew from Nigerian Customs Service trade records, Federal Road Safety Corps commercial vehicle licensing data, Central Bank of Nigeria payment system reports, and industry association freight volume disclosures. Bottom-up parcel flow modeling triangulated against top-down macroeconomic consumption indicators.
Across the analysis window, volume and value outputs segmented by service tier, delivery method, customer type, and packaging format, with additional dimensioning by state-level regulatory cluster. CAGRs derived from trend extrapolation of e-commerce penetration rates, fleet capacity expansion timelines, and diesel price elasticity assumptions. Forecast inputs incorporated Nigerian Postal Service licensing digitization implementation pace and Central Bank real-time gross settlement adoption curves.
Underlying assumptions cover regulatory harmonization between federal transport authorities and state-level motor licensing boards, with deviation risk concentrated in fuel price volatility trajectories and foreign exchange availability for equipment importation. Practitioners should keep alternative scenarios live as Nigerian Postal Service compliance deadlines and Central Bank payment mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Philippines Freight and Logistics Market
Logistics and Shipping
North America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
India Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Cargo Shipping Market
Logistics and Shipping
India Freight and Logistics Market
Logistics and Shipping
South America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
United States Apparel Logistics Market
Logistics and Shipping
Mexico Freight Forwarding Market
Logistics and Shipping
Italy Freight and Logistics Market
Logistics and Shipping
US Retail Logistics Market
Logistics and Shipping
India less than Truckload Road Freight Transport Market
Logistics and Shipping
GCC Warehousing and Distribution Logistics Market
Logistics and Shipping
Less-Than-Truckload Market
Logistics and Shipping
Global Courier Market
Logistics and Shipping
US Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
GCC Air Freight and Logistics Market