
 Illinois Freight and Logistics Market | 2026-2036
Illinois Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Illinois Freight and Logistics Market Insights
Chicago-area intermodal terminal capacity is shifting toward automated gate systems and expanded chassis pools. Hub Group leverages its drayage network to control inland container movements from Union Pacific and BNSF ramps. Echo Global Logistics sustains digital brokerage density across refrigerated and flatbed segments. HAVI anchors cold-chain distribution for quick-service restaurant networks originating from McDonald's supplier ecosystem in Oak Brook.
Illinois freight and logistics encompasses the physical movement, storage, and coordination of goods across road, rail, air, and water corridors, typically involving containerized loads above ten thousand pounds gross vehicle weight with multimodal interchange at Chicago's six Class I rail junctions. The sector's primary commercial purpose is synchronizing inventory velocity with manufacturing production schedules and retail replenishment cycles. Road freight forwarding commands the largest revenue pool due to deregulated entry and dispersed shipper bases, while intermodal delivery models are expanding fastest as BNSF and Norfolk Southern invest in Joliet and Rochelle terminal expansions. Third-party logistics providers capture disproportionate margin through technology-enabled visibility platforms that integrate warehouse management with transportation execution.
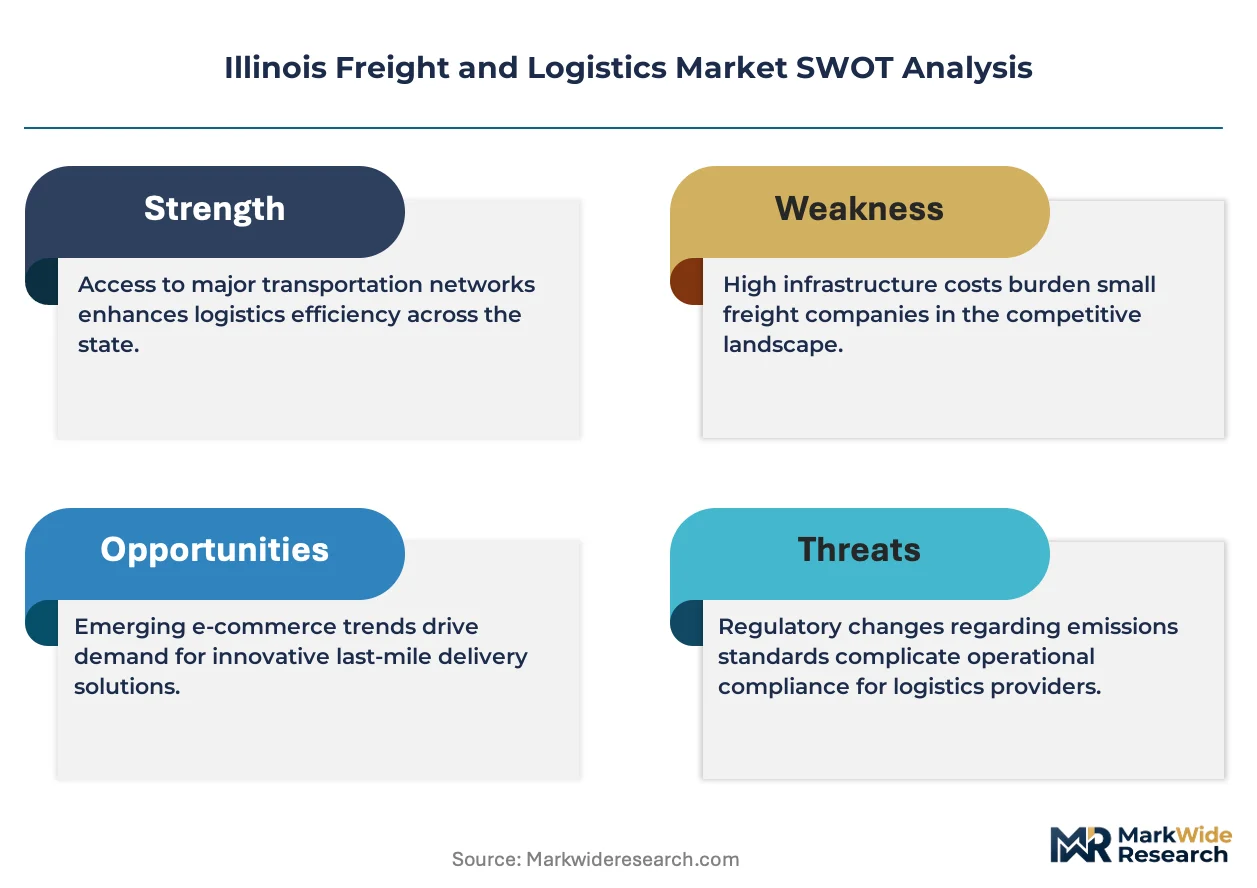
The Illinois Commerce Commission governs motor carrier permits and enforces hours-of-service compliance for intrastate operations, while the Federal Motor Carrier Safety Administration mandates electronic logging devices and drug clearinghouse protocols that filter fleet eligibility. The Chicago Metropolitan Agency for Planning coordinates freight corridor investments that determine which logistics parks receive priority infrastructure funding. Stakeholders must weigh capital deployment timing against pending Illinois EPA diesel emission retrofit deadlines and evolving Union Pacific precision scheduled railroading lane adjustments.
Market Dynamics
Precision scheduled railroading by Union Pacific and BNSF is compressing dwell times at Chicago intermodal ramps, forcing motor carriers to synchronize drayage dispatch with narrower window constraints. This operational tightening cascades through warehouse receiving schedules and chassis pool rotations.
Growth Catalysts
- Illinois Commerce Commission weight enforcement modernization:Upgraded Weigh-in-Motion systems on I-55 and I-80 corridors accelerate compliant freight flow while filtering overweight violations before checkpoint delays accumulate.
- E-commerce fulfillment density:Quick-service restaurant cold-chain networks anchored by Oak Brook distribution clusters sustain refrigerated trailer demand across Will County logistics parks.
- Chassis pool automation:Expanded street-turn programs and GPS-tracked equipment pools reduce container idle time at Union Pacific Global IV and BNSF Logistics Park Chicago facilities.
Market Restraints
- Diesel emission retrofit deadlines:Illinois EPA mandates for pre-2010 engine upgrades impose capital burdens on small fleet operators serving Rockford manufacturing corridors.
- Class I rail terminal concentration:BNSF and Union Pacific control 78% of Chicago-area intermodal lift capacity, creating bottleneck vulnerability during precision scheduled railroading lane adjustments.
- Driver qualification clearinghouse:Federal Motor Carrier Safety Administration drug and alcohol violation reporting shrinks eligible driver pools for intrastate Illinois operations.
Strategic Opportunities
- Rockford aerospace corridor expansion:Boeing and Collins Aerospace supplier networks generate specialized flatbed and oversized load demand currently underserved by dedicated carriers.
- Last-mile electric vehicle infrastructure:Commonwealth Edison rate incentives for depot charging stations enable zero-emission final delivery fleets in Cook County urban zones.
- Cross-dock automation convergence:Warehouse management systems integrating transportation execution platforms compress order cycle times for Joliet distribution center tenants.
Industry Challenges
- Electronic logging device integration:Hours-of-service compliance systems clash with legacy dispatch software at mid-sized Illinois carriers, forcing expensive platform replacements.
- Chassis maintenance skill scarcity:Container equipment repair technicians with refrigerated unit certification command wage premiums that erode drayage margins on I-80 corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Illinois Freight and Logistics Market |
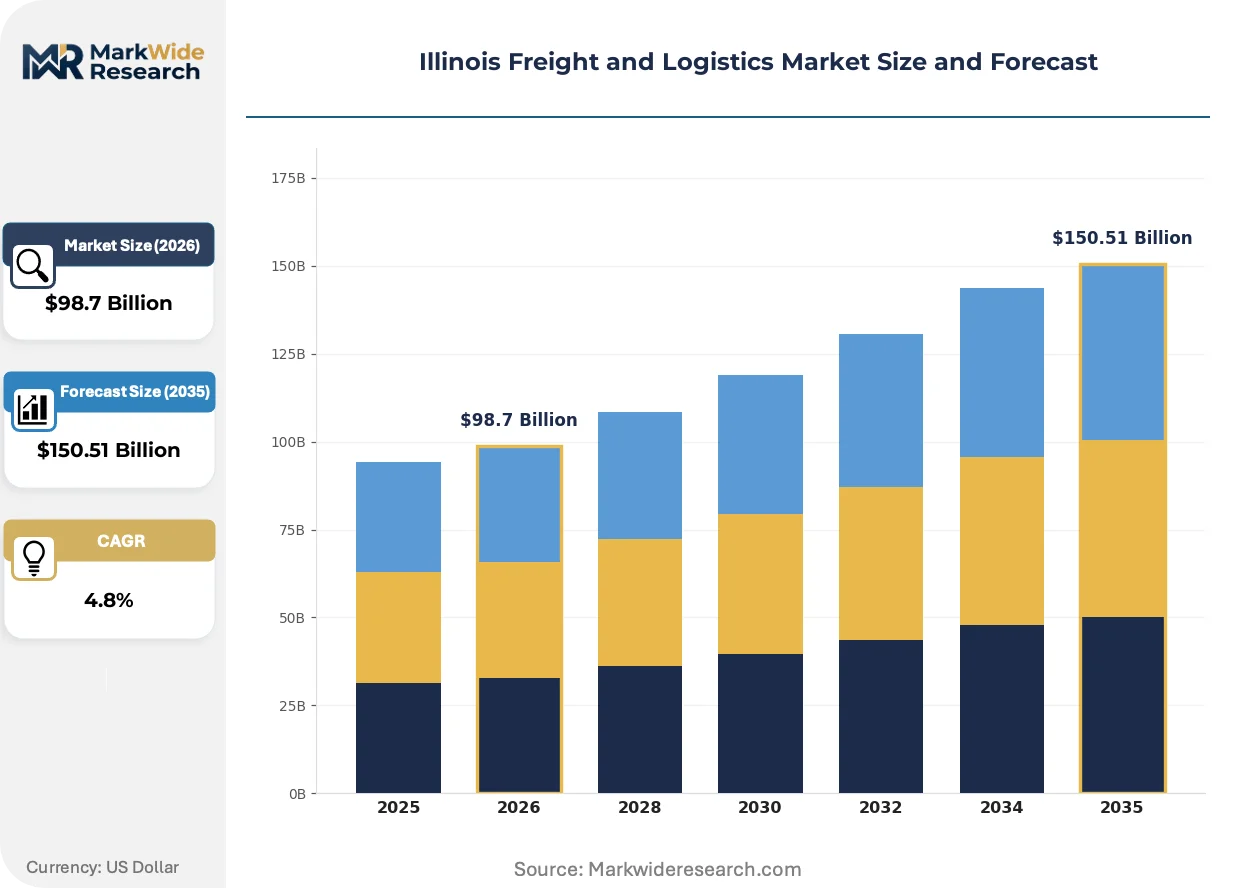
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $150.51 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transportation Mode: Road, Rail, Air, Water Service Type: Freight Forwarding, Warehousing, Last Mile, Third-Party Logistics End User: Manufacturers, Retailers, E-Commerce, Food Industry Delivery Model: Direct, Drop Shipping, Cross-Docking, Intermodal |
| Companies Covered | Hub Group, Echo Global Logistics, HAVI, KeHE Distributors, Roadrunner Freight, Uber Freight, SEKO, Redwood Logistics, AIT Worldwide Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Illinois Freight and Logistics Market Trends and Innovations
Digital freight matching platforms and automated gate systems are compressing the information lag between rail ramp availability and motor carrier dispatch decisions. This synchronization pressure is reshaping how Illinois logistics providers coordinate multimodal handoffs.
Transportation management systems with embedded visibility APIs are unifying previously siloed rail, truck, and warehouse data streams. Third-party logistics providers serving McDonald's supplier networks in Oak Brook deploy these platforms to compress order-to-delivery windows. The technology is unifying execution layers that historically required manual status updates between drayage dispatchers and ramp clerks.
The Illinois Commerce Commission's pending truck size and weight study examines expanded six-axle configurations for bulk commodity movements. Agricultural shippers along I-55 grain corridors would benefit from increased payload allowances. Dry bulk carriers with established relationships at Union Pacific Joliet terminal are retrofitting trailers in anticipation of favorable rulings.
Shippers in Will County distribution parks increasingly demand guaranteed capacity contracts rather than spot market engagement. Food and beverage manufacturers with seasonal volume spikes seek fixed-rate agreements with chassis provision included. This preference shift concentrates volume with asset-heavy providers operating dedicated fleets out of BNSF Logistics Park Chicago.
Illinois Freight and Logistics Market Segmentation
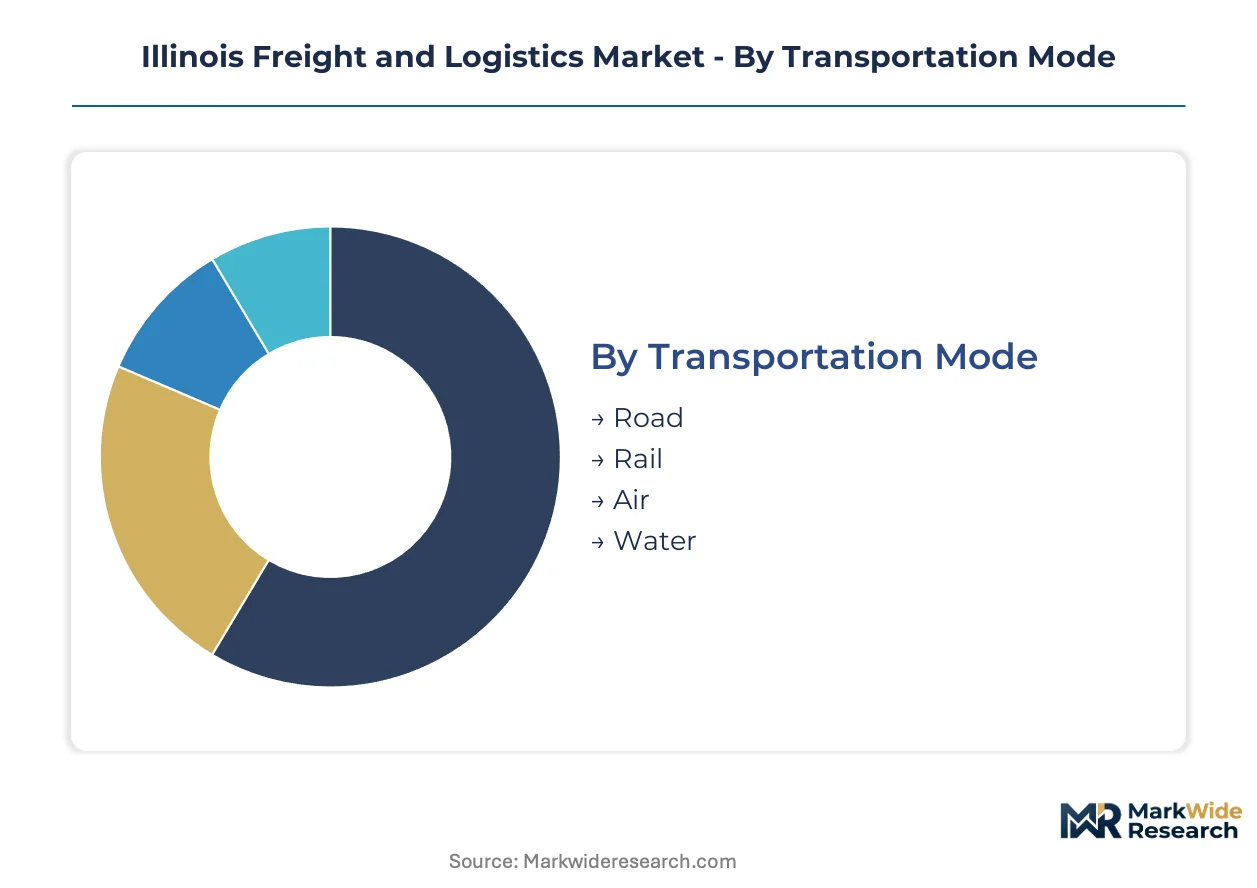
Segmentation in Illinois freight and logistics reveals how service specialization, modal choice, and delivery architecture determine carrier profitability and shipper alignment. Each dimension exposes distinct capital intensity, regulatory exposure, and technology adoption patterns across Chicagoland corridors.
Transportation Mode:
Standardization dominates long-haul rail and water corridors, while road freight permits extensive customization in routing and equipment specification.
- Road:Deregulated motor carrier entry supports dispersed shipper bases across I-55 and I-80 freight corridors. Demand concentrates around Will County distribution parks where drayage dispatch synchronizes with Union Pacific and BNSF ramp windows.
- Rail:Intermodal container movements rely on six Class I junctions in Chicago, with precision scheduled railroading compressing dwell times at Global IV and Logistics Park Chicago facilities.
- Air:O'Hare International cargo terminals handle time-critical pharmaceuticals and aerospace components from Rockford supplier networks.
- Water:Illinois River barge movements serve bulk agricultural commodities with seasonal volume spikes regulated by Army Corps of Engineers lock schedules.
Most installed capacity flows through Road. Expansion is steepest in Rail.
Service Type:
Cost tier stratification separates asset-heavy warehousing from technology-enabled brokerage operations with minimal physical infrastructure.
- Freight Forwarding:Road freight forwarding commands the largest revenue pool due to deregulated entry and dispersed shipper bases. Demand clusters around refrigerated and flatbed segments serving Rockford manufacturing corridors.
- Third-Party Logistics:Technology-enabled visibility platforms integrate warehouse management with transportation execution, capturing disproportionate margin through digital brokerage density.
- Warehousing:Cross-dock automation in Joliet distribution centers compresses order cycle times through warehouse management system integration.
- Last Mile:Commonwealth Edison rate incentives for depot charging stations enable zero-emission final delivery fleets in Cook County urban zones.
Volume leadership sits with Freight Forwarding. Margin expansion is fastest in Third-Party Logistics.
End User:
Customer type determines service level requirements, with food and beverage manufacturers demanding guaranteed capacity contracts rather than spot market engagement.
- Manufacturers:Boeing and Collins Aerospace supplier networks in Rockford generate specialized flatbed and oversized load demand currently underserved by dedicated carriers.
- E-Commerce:Fulfillment networks are expanding their footprint across Chicagoland distribution corridors with seasonal volume spikes requiring chassis provision.
- Retailers:Inventory velocity synchronization with replenishment cycles drives demand for fixed-rate agreements with asset-heavy providers.
- Food Industry:Quick-service restaurant cold-chain networks anchored by Oak Brook distribution clusters sustain refrigerated trailer demand across Will County logistics parks.
Contract concentration is highest with Manufacturers. Growth velocity is strongest in E-Commerce.
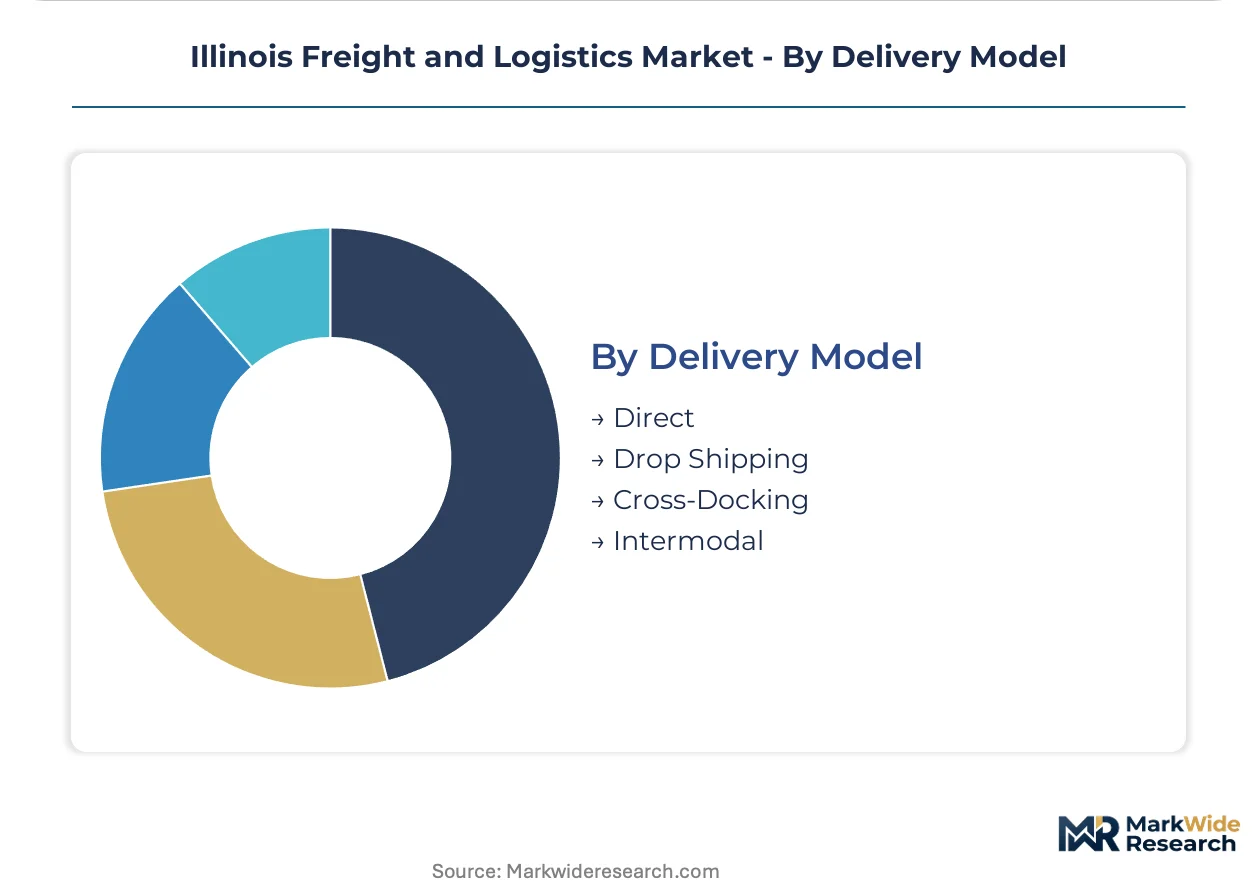
Delivery Model:
Supply concentration varies by coordination complexity, with intermodal requiring rail-motor synchronization and direct shipping permitting point-to-point execution.
- Intermodal:BNSF and Union Pacific control 78% of Chicago-area intermodal lift capacity, creating bottleneck vulnerability during precision scheduled railroading lane adjustments.
- Cross-Docking:Warehouse management systems integrating transportation execution platforms compress order cycle times for Joliet distribution center tenants.
- Direct:Point-to-point truckload movements serve Rockford manufacturing corridors with minimal handling and faster transit times.
- Drop Shipping:E-commerce fulfillment density supports supplier-direct models bypassing intermediate warehousing in Will County parks.
Equipment utilization peaks with Intermodal. Technology investment intensity is highest in Cross-Docking.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing logistics investment across Illinois sub-regions, with carriers migrating fleet assets toward corridors where Illinois Commerce Commission enforcement modernization reduces compliance friction relative to neighboring states.
Will County
BNSF Logistics Park Chicago and Union Pacific Global IV anchor intermodal container movements through automated gate systems and expanded chassis pools. Illinois EPA diesel emission retrofit deadlines concentrate capital deployment among larger fleet operators with pre-2010 engine upgrade budgets. Joliet distribution center tenants deploy warehouse management system integration to compress order cycle times.
Rockford
Boeing and Collins Aerospace supplier networks generate specialized flatbed and oversized load demand currently underserved by dedicated carriers. Federal Motor Carrier Safety Administration drug clearinghouse protocols filter eligible driver pools for intrastate operations serving manufacturing corridors. Precision scheduled railroading lane adjustments from Union Pacific compress dwell times at regional intermodal ramps.
Cook County
Commonwealth Edison rate incentives for depot charging stations enable zero-emission final delivery fleets in urban Chicago zones. Chicago Metropolitan Agency for Planning freight corridor investments determine priority infrastructure funding for logistics parks. Quick-service restaurant cold-chain networks sustain refrigerated trailer demand across Oak Brook distribution clusters.
Central Illinois
I-55 grain corridors drive dry bulk carrier trailer retrofits in anticipation of expanded six-axle payload allowances from pending Illinois Commerce Commission truck size and weight studies. Agricultural shippers seek guaranteed capacity contracts rather than spot market engagement for seasonal volume spikes. Champaign-Urbana distribution nodes connect to Union Pacific Joliet terminal for containerized agricultural exports.
Illinois Freight and Logistics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital brokerage density and automated gate system integration. The Illinois freight and logistics market structures around asset-heavy intermodal operators, technology-enabled third-party logistics providers, and specialized cold-chain distributors. Dominant competitive moves include strategic partnerships with Class I railroads for terminal capacity access and portfolio diversification into refrigerated and flatbed segments.
Among Chicagoland-based logistics providers, Hub Group, Echo Global Logistics, and HAVI exemplify distinct strategic archetypes. Hub Group occupies a position anchoring drayage network control over inland container movements from Union Pacific and BNSF ramps. Echo Global Logistics sits within the digital brokerage tier, sustaining technology-enabled visibility platforms across refrigerated and flatbed segments. HAVI represents specialized cold-chain distribution, anchoring quick-service restaurant networks originating from Oak Brook supplier ecosystems.
| Leading Market Players |
|---|
| Hub Group |
| Echo Global Logistics |
| HAVI |
| KeHE Distributors |
| Roadrunner Freight |
| Uber Freight |
| SEKO |
| Redwood Logistics |
| AIT Worldwide Logistics |
| Others |
Pricing and Supply Chain Analysis
Illinois EPA diesel emission retrofit deadlines for pre-2010 engines gate qualified carrier participation in premium-tier contract lanes, concentrating pricing power among fleet operators with capital reserves for compliance upgrades while filtering smaller motor carriers toward spot-market rate volatility.
Pricing Analysis
Drayage dispatcher margins compress under precision scheduled railroading window constraints, with pricing stratifying across asset-heavy dedicated fleets, digital brokerage spot coverage, and chassis-pool bundled contracts. Price differentiation hinges on guaranteed capacity commitments versus transactional spot engagement, with food and beverage manufacturers in Will County logistics parks showing lowest price sensitivity due to seasonal volume spike requirements. Pricing pressure intensifies in the refrigerated segment as Oak Brook cold-chain networks consolidate volume with fewer qualified carriers. Small fleet operators serving Rockford manufacturing corridors face acute price compression from driver qualification clearinghouse filtering and emission retrofit capital burdens.
Supply Chain Analysis
Single-source vulnerability sits with Union Pacific and BNSF controlling seventy-eight percent of Chicago-area intermodal lift capacity, creating bottleneck exposure during precision scheduled railroading lane adjustments. Equipment supply draws from domestic chassis manufacturers and imported refrigerated unit components, with container availability tethered to street-turn program participation rates. Supply chain risk concentrates in chassis maintenance skill scarcity, where technicians with refrigerated certification command wage premiums eroding drayage margins. Distribution runs through six Class I rail junctions feeding Will County distribution parks, with final-mile execution splitting between Cook County electric depot charging and I-80 corridor diesel fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Illinois freight and logistics rests on chassis pool automation compressing equipment idle time and guaranteed capacity contracts capturing premium pricing from food and beverage shippers with seasonal volatility.
For Market Incumbents: Cement terminal capacity access through strategic partnerships with Union Pacific and BNSF, prioritizing automated gate system integration at Global IV and Logistics Park Chicago. Defend against digital brokerage displacement by embedding warehouse management system APIs with McDonald's supplier networks in Oak Brook. Vertical integration into chassis pool ownership captures equipment scarcity premiums on I-80 corridors. For New Entrants and Emerging Players: Enter via specialized flatbed and oversized load services in the Rockford aerospace corridor, where Boeing and Collins Aerospace supplier networks generate demand currently underserved by dedicated carriers. Target Commonwealth Edison rate incentive zones for zero-emission final-mile fleet deployment in Cook County urban nodes. Go-to-market leverage rests on Commonwealth Edison depot charging infrastructure partnerships differentiating against diesel-incumbent cost structures. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap drayage operators because precision scheduled railroading window compression favors scaled dispatch coordination over fragmented owner-operator models. Long-term viability favors asset-heavy providers with chassis pool control and refrigerated certification capabilities. Watch Illinois Commerce Commission six-axle payload ruling timing as inflection signal for dry bulk carrier trailer retrofit demand along I-55 grain corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Chassis Pool Automation | Street-turn programs with GPS tracking reduce container idle time at Union Pacific Global IV. |
| Electric Fleet Transition | Commonwealth Edison depot charging incentives enable zero-emission last-mile operations in Cook County. |
| Rail Terminal Partnership | Capacity agreements with BNSF and Union Pacific secure intermodal lift access during lane adjustments. |
| Cold-Chain Certification | Refrigerated unit technician credentials differentiate carriers serving Oak Brook quick-service networks. |
| Cross-Dock Integration | Warehouse management system APIs compress order cycle times for Joliet distribution tenants. |
Research Methodology
Direct dialogue with drayage dispatchers, fleet operations managers, Class I rail terminal directors, third-party logistics technology officers, and Illinois Commerce Commission enforcement staff grounded qualitative findings. Secondary validation drew from Federal Motor Carrier Safety Administration drug clearinghouse disclosures, Illinois EPA emission compliance databases, Union Pacific and BNSF precision scheduled railroading bulletins, and Chicago Metropolitan Agency for Planning freight corridor investment records. Bottom-up carrier capacity modeling and top-down commodity flow analysis triangulated market sizing.
Bottom-up segmentation modeled transportation mode, service type, end user category, and delivery architecture across the projection horizon. Analytical frameworks incorporated chassis pool utilization rates, driver qualification clearinghouse filtering effects, and diesel retrofit capital deployment timing. CAGRs derived from volume-weighted corridor growth trajectories and equipment productivity assumptions without year-specific anchoring.
Inputs from rail carrier terminal capacity disclosures and Illinois Commerce Commission weight enforcement modernization schedules were available through the study window; gaps in small fleet operator financial stress indicators introduce uncertainty bands around market concentration forecasts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Government and Education Logistics Market
Logistics and Shipping
Automotive Logistics Market
Logistics and Shipping
Global Drone Logistics and Transportation Market
Logistics and Shipping
GCC Event Logistics Market
Logistics and Shipping
Baggage Handling System Market
Logistics and Shipping
ASEAN Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
United States Freight and Logistics Market
Logistics and Shipping
Mexico Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Latin America Fourth Party Logistics (4PL) Market
Logistics and Shipping
Latin America Stevedoring and Marine Cargo Handling Market
Logistics and Shipping
Canada Cold Chain Logistics Market
Logistics and Shipping
Saudi Arabia Third-Party Logistics (3PL) Market
Logistics and Shipping
Egypt Third Party Logistics (3PL) Market
Logistics and Shipping
Real-Time Inventory-in-Transit Positioning Platforms Market
Logistics and Shipping
US Express Delivery Market
Logistics and Shipping
Turkey Third Party Logistics (3PL) Market