
 Middle East and Africa General Aviation Market | 2026-2036
Middle East and Africa General Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa General Aviation Market Foresight
Carbon fiber reinforced polymer is consolidating as the primary fuselage material across light business jets, displacing conventional aluminum alloys and reducing airframe weight by substantial margins. Bombardier Inc. leverages its Challenger platform heritage to sustain manufacturing economies in the mid-size cabin segment. Gulfstream Aerospace anchors ultra-long-range product credibility through the G700 certification pathway. Leonardo S.p.A competes in the rotorcraft tier with AW139 deployments across offshore energy corridors from Angola to Qatar.
General aviation encompasses all civil aviation operations excluding scheduled commercial air transport, spanning aircraft with maximum takeoff weights below certain thresholds and operating under visual or instrument flight rules with piston, turboprop, or turbofan propulsion systems. Fixed-wing aircraft dominate value generation across the Middle East and Africa, while rotorcraft captures disproportionate utilization in oil-and-gas logistics and medical evacuation missions. Charter operators represent the fastest-expanding end-user channel as fractional ownership models penetrate Gulf Cooperation Council economies. Maintenance services concentrate margin pools through regulatory-mandated airworthiness directives and aging fleet requirements.
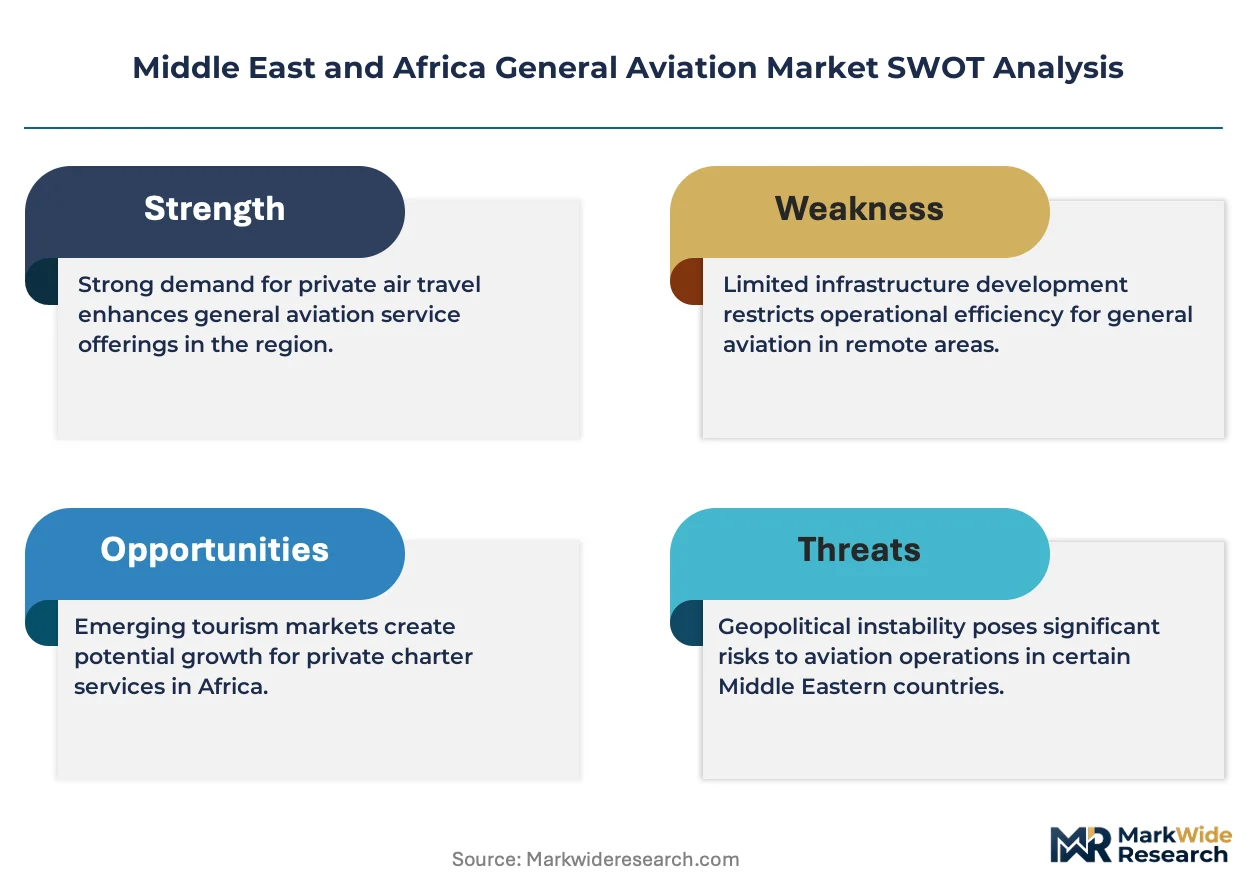
GCAA in the UAE, NCAA in Nigeria, and SACAA in South Africa enforce divergent certification timelines that fragment type-approval pathways for imported aircraft and components. EASA technical harmonization initiatives progressively align Middle Eastern standards, though African regulators maintain sovereign discretion over operational specifications. Stakeholders must monitor bilateral aviation safety agreements and local content requirements as determinants of fleet procurement strategy and service network placement.
Market Dynamics
Fleet modernization across Saudi Arabia and the UAE is compressing replacement cycles as GCAA-aligned noise mandates force early retirement of Stage II aircraft, while Nigerian offshore operators accelerate twin-turbine helicopter procurement to meet insurance requirements.
Growth Catalysts
- GCAA Stage III noise mandates:UAE operators face airworthiness directive deadlines that accelerate fleet turnover and stimulate new aircraft deliveries across the light and mid-size jet segments.
- Offshore energy logistics:Nigerian and Angolan deepwater oil production sustains demand for twin-engine rotorcraft configured for crew transport and search-and-rescue standby duties.
- Carbon fiber airframe adoption:Composite fuselage construction reduces operating empty weight and extends range-payload performance, attracting charter operators seeking fuel efficiency gains.
Market Restraints
- Jet A1 fuel price volatility:Regional supply disruptions and currency fluctuations compress operating margins for high-utilization charter fleets across sub-Saharan Africa.
- Import duty structures:Nigerian customs tariffs on complete aircraft and spare parts inflate delivered costs and extend procurement timelines for domestic operators.
- Pilot certification bottlenecks:SACAA and NCAA examination backlogs restrict available flight crew supply, capping fleet expansion rates for established operators.
Strategic Opportunities
- Medical evacuation services:South Africa's private healthcare networks and remote mining installations generate underpenetrated demand for dedicated air ambulance rotorcraft with intensive care configurations.
- Fractional ownership penetration:Gulf Cooperation Council family offices and mid-market enterprises represent nascent demand for structured access programs replacing whole-aircraft acquisition.
- EASA technical harmonization:Progressive alignment of UAE and Saudi certification pathways reduces type-approval duplication costs for European OEMs entering Middle Eastern markets.
Industry Challenges
- Maintenance technician scarcity:ATR and Embraer type-rated mechanics concentrate in Johannesburg and Dubai, leaving secondary markets dependent on fly-in support with extended aircraft-on-ground exposure.
- Airworthiness directive compliance:Aging piston fleets in East Africa face structural inspection mandates that exceed residual aircraft values, forcing uneconomic retirement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa General Aviation Market |
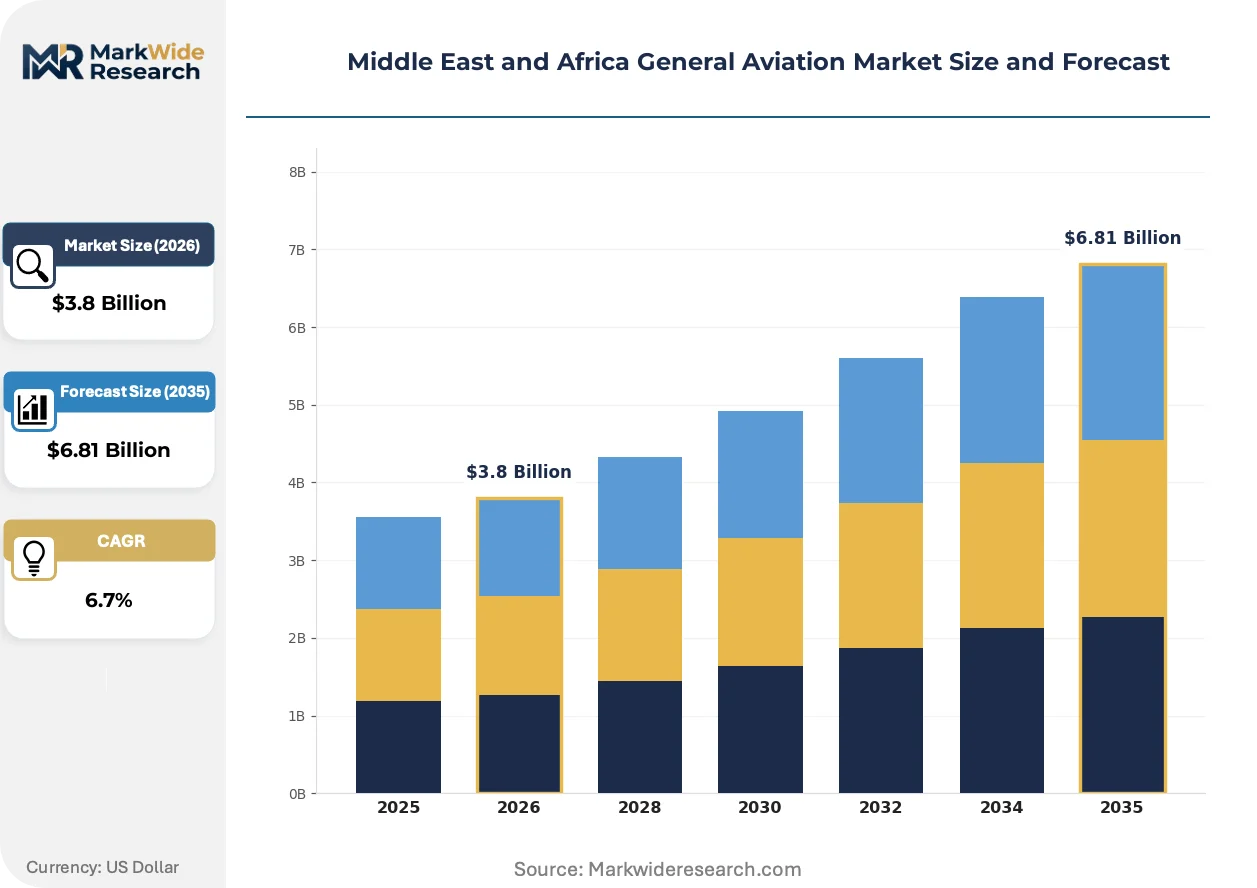
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Fixed-Wing, Rotorcraft, Gliders, Airships End User: Private Owners, Charter Operators, Business Aviation, Government Service Type: Maintenance, Flight Training, FBO Services, Landing Rights Application: Freight Transportation, Aerial Surveying, Medical Evacuation, Tourism |
| Companies Covered | Airbus SE, Bombardier Inc., Dassault Aviation, General Dynamics Corporation, Leonardo S.p.A, Lockheed Martin Corporation, Gulfstream Aerospace, Textron Aviation, Embraer, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa General Aviation Market Shifts & Advancements
Digital connectivity integration and sustainable aviation fuel infrastructure are reconfiguring operator priorities across the Middle East and Africa, while regulatory harmonization efforts compress certification friction for imported platforms.
Avionics retrofit programs are consolidating glass cockpit architectures across legacy turboprop fleets, replacing electromechanical instruments with integrated flight displays and synthetic vision systems. East African safari operators and South African charter fleets are adopting these upgrades to meet insurance-mandated minimum equipment specifications. The technology is consolidating operational capability gaps between aging airframes and modern light jets, extending economic service life for high-cycle aircraft.
EASA technical harmonization initiatives are progressively aligning UAE and Saudi Arabian airworthiness standards, reducing duplicate certification requirements for European-manufactured aircraft entering Gulf markets. GCAA has adopted EASA maintenance organization approval frameworks, enabling reciprocal recognition of repair station qualifications. Light business jet imports into Dubai and Riyadh are encountering streamlined type-acceptance timelines as bilateral aviation safety agreements mature.
Charter brokerage platforms are fragmenting traditional operator-client relationships across the Middle East, replacing direct contract negotiations with digital marketplaces that aggregate aircraft availability and transparent pricing. High-net-worth individuals and corporate travel managers in the UAE are adopting these channels for ad-hoc executive transport bookings. The shift is most visible in Dubai's point-to-point leisure and business corridors, where on-demand access displaces fractional share commitments for sub-fifty-hour annual users.
Middle East and Africa General Aviation Market Segmentation
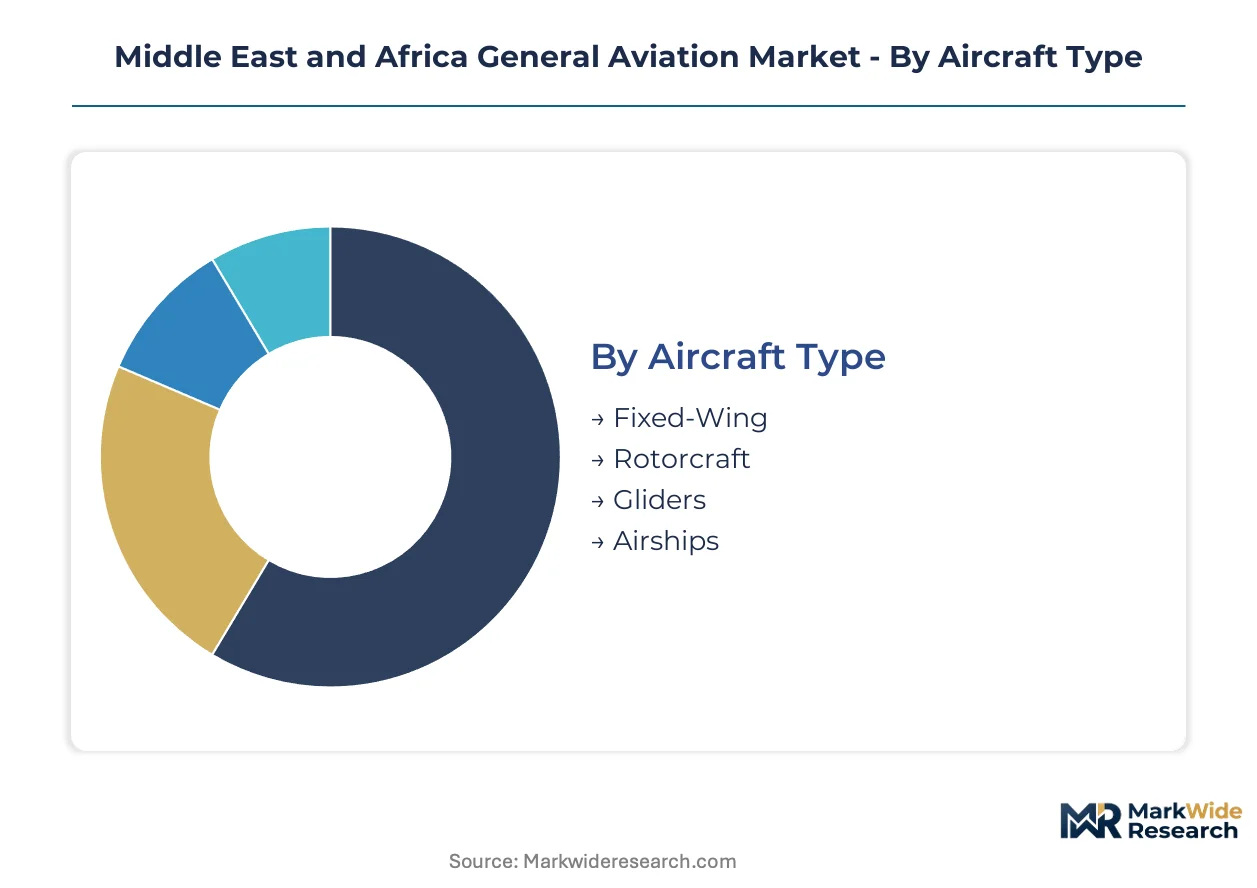
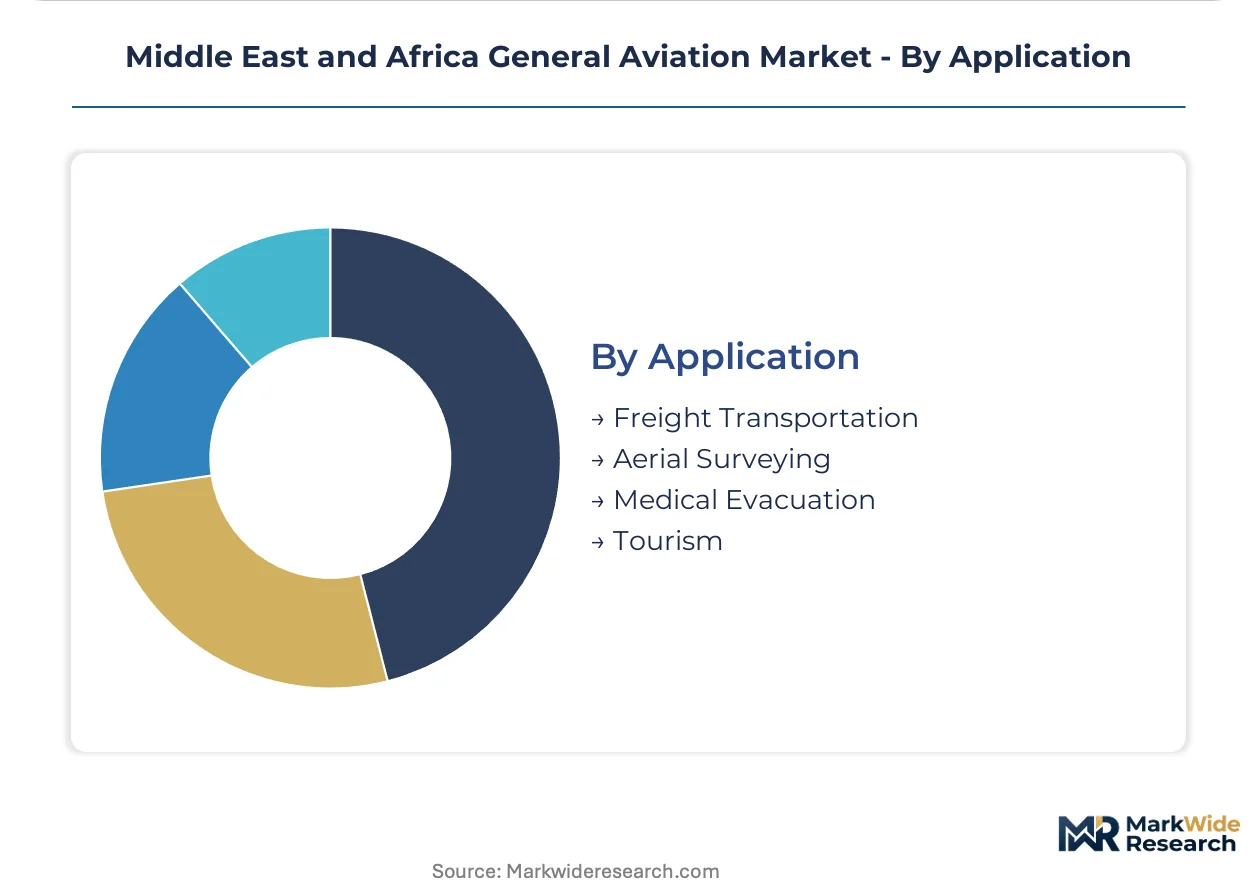
Segmentation across the Middle East and Africa General Aviation Market reveals how operational requirements, regulatory environments, and economic infrastructure shape procurement patterns. Understanding these divisions enables stakeholders to align fleet composition, service networks, and certification strategies with localized demand drivers across diverse aviation ecosystems.
Aircraft Type:
Propulsion configuration and airframe architecture determine operational envelope, certification pathway, and infrastructure compatibility across regional markets.
- Fixed-Wing:Piston, turboprop, and turbofan-powered aircraft with rigid lifting surfaces dominate executive transport and regional connectivity. Demand concentrates in Saudi Arabia and the UAE for business aviation missions, driven by GCAA Stage III noise mandates accelerating fleet replacement cycles.
- Rotorcraft:Single and twin-engine helicopters with powered rotary wings enable vertical lift operations without runway dependency. Nigerian and Angolan offshore oil corridors sustain twin-turbine procurement for crew transport and search-and-rescue standby duties.
- Gliders:Unpowered fixed-wing aircraft relying on thermal currents and tow launch for sustained flight. South African recreational aviation clubs and training academies represent the primary deployment base.
- Airships:Lighter-than-air platforms with buoyant gas envelopes and vectored thrust for low-speed, long-endurance missions. Surveillance and tourism applications in Dubai and Cape Town constitute emerging evaluation programs.
Mature deployment sits with Fixed-Wing platforms across established business aviation corridors. Newer deployment is concentrated in Rotorcraft configurations for energy logistics and medical evacuation missions.
End User:
Ownership structure and utilization intensity create divergent procurement criteria, from capital-intensive whole-aircraft acquisition to variable-cost access models.
- Private Owners:Individual or family entities acquiring aircraft for personal transport and leisure operations. High-net-worth individuals in the UAE and Saudi Arabia are expanding light jet ownership, responding to fractional ownership program availability and FBO infrastructure maturation.
- Charter Operators:Commercial entities providing on-demand aircraft access without ownership transfer. Digital brokerage platforms are fragmenting traditional client relationships across Dubai and Riyadh, aggregating availability and transparent pricing for ad-hoc bookings.
- Business Aviation:Corporate flight departments and dedicated executive transport divisions. Fleet modernization compresses replacement cycles as EASA-aligned airworthiness mandates force early retirement of Stage II aircraft.
- Government:State agencies utilizing general aviation for surveillance, VIP transport, and public service missions. Nigerian and South African government contracts for medical evacuation and border patrol sustain dedicated rotorcraft procurement.
Charter Operators are climbing the fastest as fractional ownership models penetrate Gulf Cooperation Council economies. Private Owners retain the largest installed base but face utilization efficiency pressures.
Service Type:
Post-delivery support infrastructure generates recurring revenue pools through regulatory-mandated maintenance and operational enablement services.
- Maintenance:Airframe, engine, and component overhaul services ensuring continued airworthiness. Technician scarcity for ATR and Embraer types concentrates capability in Johannesburg and Dubai, leaving secondary markets dependent on fly-in support.
- Flight Training:Pilot certification programs for private, commercial, and instrument ratings. SACAA and NCAA examination backlogs restrict available flight crew supply, capping fleet expansion rates for established operators.
- FBO Services:Fixed-base operator facilities providing fueling, hangarage, and passenger amenities. Premium FBO networks in Dubai and Riyadh are expanding to capture growing business aviation traffic.
- Landing Rights:Regulatory permissions and slot allocations for airport access. Fragmented bilateral agreements across African states complicate cross-border operational planning for charter fleets.
Maintenance commands the highest margin concentration through aging fleet requirements and directive compliance. Flight Training is expanding most quickly in response to pilot certification bottlenecks.
Application:
Mission profile determines aircraft specification, regulatory classification, and revenue model across specialized operational niches.
- Freight Transportation:Cargo carriage on dedicated or combi-configured aircraft. East African perishable exports and humanitarian logistics sustain turboprop freighter utilization.
- Aerial Surveying:Geospatial data collection through photogrammetry, LiDAR, and multispectral imaging. Mining concessions in South Africa and infrastructure planning in Saudi Arabia drive sensor-equipped platform demand.
- Medical Evacuation:Patient transport with intensive care configurations and aeromedical crews. South Africa's private healthcare networks and remote mining installations generate underpenetrated demand for dedicated air ambulance rotorcraft.
- Tourism:Scenic flights, safari access, and leisure experience provisioning. Kenyan and Tanzanian safari operators are adopting avionics retrofits to meet insurance-mandated minimum equipment specifications.
Medical Evacuation shows the steepest expansion trajectory as healthcare infrastructure extends into remote territories. Freight Transportation maintains the deepest operational history across established trade corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai South's aviation district concentrates MRO infrastructure and business aviation services, drawing fleet operators seeking proximity to the Al Maktoum International Airport free zone incentives.
United Arab Emirates
GCAA Stage III noise mandates accelerate light jet replacement cycles across Dubai and Abu Dhabi charter fleets. The regulator's EASA-aligned maintenance organization approvals enable reciprocal repair station qualifications for European OEMs. Dubai South's aviation free zone hosts expanding FBO networks serving fractional ownership growth.
Saudi Arabia
Business aviation operators expand executive transport fleets under Vision 2030 diversification programs. The General Authority of Civil Aviation enforces progressively stringent emissions benchmarks aligned with Gulf harmonization initiatives. Riyadh and Jeddah corridors concentrate new aircraft deliveries as corporate flight departments modernize.
South Africa
Private healthcare networks and remote mining installations drive medical evacuation rotorcraft procurement. SACAA examination backlogs restrict pilot certification throughput, capping fleet expansion for established charter operators. Johannesburg concentrates ATR and Embraer type-rated maintenance capability.
Nigeria
Deepwater oil production sustains twin-turbine helicopter demand for crew transport and search-and-rescue standby duties. NCAA certification timelines fragment type-approval pathways for imported aircraft. Lagos and Port Harcourt anchor offshore logistics operator bases facing customs tariff inflation on spare parts.
Angola
Offshore energy corridors sustain AW139 deployments for petroleum sector logistics. The national civil aviation authority maintains sovereign discretion over operational specifications distinct from regional harmonization efforts. Luanda clusters helicopter services supporting Cabinda and Kwanza basin production platforms.
Middle East and Africa General Aviation Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated OEMs commanding premium positioning in long-range business jets while regional service providers capture maintenance margin pools. The vendor base organizes around three archetypes: airframe manufacturers with certified production type certificates, rotorcraft specialists with offshore energy credentials, and aftermarket service networks with regulator-approved repair station designations. Consolidation pressures favor M&A activity among MRO providers seeking geographic coverage, while technology licensing agreements proliferate between established OEMs and emerging market assembly ventures.
Within the integrated OEM tier, Bombardier Inc. and Gulfstream Aerospace anchor mid-size and ultra-long-range product positioning respectively. Leonardo S.p.A occupies a distinct rotorcraft specialization serving energy logistics corridors from Angola to Qatar. These three manufacturers exemplify divergent competitive vectors: Challenger platform heritage sustaining manufacturing economies, G700 certification pathways establishing range benchmarks, and AW139 deployments penetrating offshore vertical lift markets.
| Leading Market Players |
|---|
| Airbus SE |
| Bombardier Inc. |
| Dassault Aviation |
| General Dynamics Corporation |
| Leonardo S.p.A |
| Lockheed Martin Corporation |
| Gulfstream Aerospace |
| Textron Aviation |
| Embraer |
| Others |
Supply & Pricing Matrix
Family-owned charter operators across the Gulf Cooperation Council anchor pricing discipline through long-dated aircraft financing arrangements that tether fleet renewal cycles to sovereign wealth-backed credit facilities. This ownership concentration compresses procurement timelines for European OEMs while insulating delivered pricing from spot-market volatility in Jet A1 fuel.
Pricing Analysis
Short lead-time premiums dominate aircraft procurement across Dubai and Riyadh corridors, with buyers paying markups for immediate G650ER or Challenger 350 availability versus discounted contracting for twelve-month delivery windows. Three-tier pricing structure across premium long-range, standard mid-size, and economy light-jet levels separates EASA-certified platforms from GCAA-parallel imports and aging Stage II trade-ins. Cost compression in the light-jet tier is intensifying because Nigerian and Angolan operators face currency-driven import duty inflation. Charter brokerage platforms exhibit highest price sensitivity, while sovereign flight departments demonstrate lowest elasticity due to non-commercial mission requirements.
Supply Chain Analysis
Avionics and engine component supply rests on specialist manufacturing clusters in the United States, France, and Canada, with Honeywell and Safran systems anchoring glass cockpit retrofits across legacy turboprop fleets. Carbon fiber prepreg draws from Japanese and German specialty chemical producers, while aluminum-lithium alloys source from Russian and American smelters now facing trade restriction exposure. Single-source vulnerability concentrates in FADEC engine control modules for Pratt & Whitney Canada turboprops. Distribution runs through Dubai South free-zone consolidators serving sub-Saharan African operators with fly-in spare parts logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCAA Stage III noise mandates are forcing uneconomic retirements of aging Stage II fleets, consolidating market share among capitalized operators capable of accelerated replacement cycles.
For Market Incumbents: Extend maintenance organization approvals into secondary African markets before EASA technical harmonization matures, capturing SACAA and NCAA examination backlog arbitrage. Deepen backward integration into avionics retrofit capabilities to offset OEM pricing power in glass cockpit upgrades. Defensive positioning against digital brokerage platforms requires direct channel investment in on-demand booking infrastructure. For New Entrants and Emerging Players: Begin with medical evacuation rotorcraft configurations serving South African private healthcare networks and remote mining installations, where underpenetrated demand exceeds established operator capacity. Target Nigerian offshore logistics corridors for twin-turbine helicopter procurement, leveraging insurance-mandated equipment specifications that reset competitive baselines. Go-to-market execution should emphasize EASA-aligned certification pathways to compress GCAA type-acceptance timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor MRO specialists with regulator-approved repair station designations in Johannesburg and Dubai, where technician scarcity concentrates margin pools. Long-term viability across the analysis window hinges on bilateral aviation safety agreement maturation between European and Gulf regulators. Monitor EASA-GCAA reciprocal recognition protocols as the inflection signal for accelerated European OEM market penetration.| Strategic Initiative | Industry Significance |
|---|---|
| EASA Technical Harmonization Investment | GCAA-aligned certification pathways reduce duplicate approval costs for Challenger and G700 deliveries into Dubai. |
| Carbon Fiber Airframe Retrofit Program | Composite fuselage upgrades extend range-payload performance for East African safari operators facing fuel cost pressure. |
| Digital Charter Brokerage Platform Launch | Transparent pricing aggregation fragments traditional operator-client relationships across UAE leisure corridors. |
| Medical Evacuation Fleet Expansion | Intensive care rotorcraft configurations capture underpenetrated demand from South African mining installations. |
| Maintenance Organization Geographic Extension | SACAA and NCAA approval capture addresses examination backlog constraints capping fleet expansion rates. |
Research Methodology
Independent corroboration across GCAA regulatory filings, NCAA certification databases, and EASA bilateral safety agreements underwrites the qualitative findings on type-approval pathway fragmentation. Primary interviews with Dubai-based FBO operators, Johannesburg MRO technical directors, and Lagos offshore logistics fleet managers combined with secondary validation from customs trade records, business aviation registration databases, and sovereign aviation authority annual reports. Bottom-up aircraft delivery tracking and top-down regional fleet size estimates triangulate market sizing.
Rate-of-change decomposition across the projection horizon segments growth by fixed-wing versus rotorcraft propulsion configuration, charter operator versus private owner end-use structure, and maintenance versus flight training service revenue pools. CAGRs derive from fitted trend extrapolation adjusted for regulatory mandate deadlines and fleet age distribution analysis. Forecast inputs incorporate Jet A1 fuel price volatility assumptions and pilot certification throughput constraints from SACAA and NCAA examination data.
Underlying measurement precision varies by segment; UAE and Saudi Arabian business aviation deliveries carry tighter precision than sub-Saharan African piston fleet estimates due to registration transparency differentials. Forecasts reflect documented assumptions on EASA-GCAA harmonization pace and sovereign wealth financing availability. Regulatory mandate delay, currency crisis in Nigerian naira or Angolan kwanza, and aviation fuel supply disruption constitute the trigger set warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Mobility
North America Offshore Helicopter Services Market
Air Mobility
Middle-East and Africa Military Aviation Market
Air Mobility
Off-Shore Helicopters Market
Air Mobility
Global Flying Cars Market
Air Mobility
Global Aerial Firefighting Market
Air Mobility
Airborne Pods Market
Air Mobility
Air Transport Modifications Market
Air Mobility
Air Crane Helicopter Market
Air Mobility
China Chartered Air Transport Market
Air Mobility
Flying Taxi Market
Air Mobility
Offshore Helicopter Services Market
Air Mobility
Asia-Pacific Military Aviation Market
Air Mobility
Advanced Aerial Mobility Market
Air Mobility
North Sea Offshore Helicopter Services Market
Air Mobility
South America Offshore Helicopter Services Market
Air Mobility
Advanced Air Mobility Market