
 Air Transport USM Market | 2026-2036
Air Transport USM Market Size, Share, and Industry Trends Forecast 2026-2036
Air Transport USM Market Analysis
Cargo handling is repositioning within the Air Transport USM Market as e-commerce logistics operators expand freighter fleets and seek cost-effective component sourcing. Boeing Company leverages its OEM data archives to authenticate part provenance and control residual value streams. AAR Corp. competes through its integrated supply chain infrastructure spanning component repair and redistribution. GA Telesis, LLC dominates engine and landing gear teardown activity, anchoring its position in high-value USM categories.
Air Transport USM encompasses used serviceable materials—airworthy components recovered from retired or parted-out aircraft, refurbished to OEM or DER-approved standards for reinstallation on active fleets. These parts undergo functional testing, non-destructive inspection, and traceability documentation to meet airworthiness requirements while delivering cost savings versus new production units. Aircraft product type segments command the deepest USM pools given narrow-body and wide-body retirement waves, though helicopter USM is gaining traction as offshore energy operators manage operating economics. Airlines end users represent the largest procurement volume, yet government agencies are emerging as disciplined buyers through defense logistics modernization programs. Electric propulsion technology segments remain nascent for USM given limited fleet penetration, but hybrid systems are creating early secondary component flows as regional operators trial retrofit configurations.
The FAA governs USM eligibility through 14 CFR Part 43 maintenance standards and Airworthiness Directive compliance tracking, while the EPA oversees hazardous material handling in teardown operations. EASA's Part 145 regulations create parallel certification pathways for European-registered fleet USM, shaping cross-border parts mobility. Stakeholders must monitor evolving digital traceability mandates and engine OEM residual value strategies as fleet transitions accelerate.
Market Dynamics
Fleet retirement waves are compressing USM availability timelines as Boeing 737 NG and Airbus A320ceo platforms reach end-of-life cycles simultaneously, forcing buyers into earlier sourcing commitments and reshaping residual value negotiations across the teardown ecosystem.
Growth Catalysts
- 14 CFR Part 43 Documentation Standards:The FAA's enhanced traceability mandates are legitimizing previously gray-market components and expanding the addressable pool of certifiable USM for commercial operators.
- E-commerce Freighter Conversions:Cargo carriers are accelerating narrow-body passenger-to-freighter programs, creating sustained demand for engine and landing gear USM from retired single-aisle fleets.
- DER-Approved Repair Development:Designated Engineering Representative pathways are proliferating alternative certification routes that reduce OEM dependency and broaden supplier bases for critical airframe components.
Market Restraints
- Titanium Alloy Input Volatility:Aerospace-grade titanium sponge pricing fluctuations are compressing teardown economics and narrowing the cost gap between USM and new production parts.
- OEM Residual Value Control:Engine manufacturers are tightening PBH and V2500 maintenance agreements to capture end-of-life component value, restricting independent teardown access to high-value modules.
- EASA-US Regulatory Divergence:Differing Part 145 and 14 CFR documentation requirements are fragmenting cross-border USM liquidity and increasing compliance overhead for multi-registry operators.
Strategic Opportunities
- India Defense Logistics Modernization:The country's military aviation upgrade programs are creating first-mover advantages for USM suppliers establishing DER-capable repair stations under CDSCO-aligned quality frameworks.
- Blockchain Traceability Convergence:Distributed ledger integration with existing MRO software is enabling real-time provenance verification that satisfies both FAA and EASA audit requirements simultaneously.
- Hybrid-Electric Retrofit Component Flows:Regional operators trialing Safran and MagniX propulsion systems are generating early secondary markets for power electronics and thermal management USM.
Industry Challenges
- NDT Technician Scarcity:Qualified ultrasonic and eddy-current inspection specialists are concentrated at legacy teardown facilities, constraining capacity expansion for emerging USM processors.
- Airworthiness Directive Synchronization:Multi-registry operators face conflicting compliance timelines when installing USM across FAA- and EASA-registered subfleets, complicating fleet standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Transport USM Market |
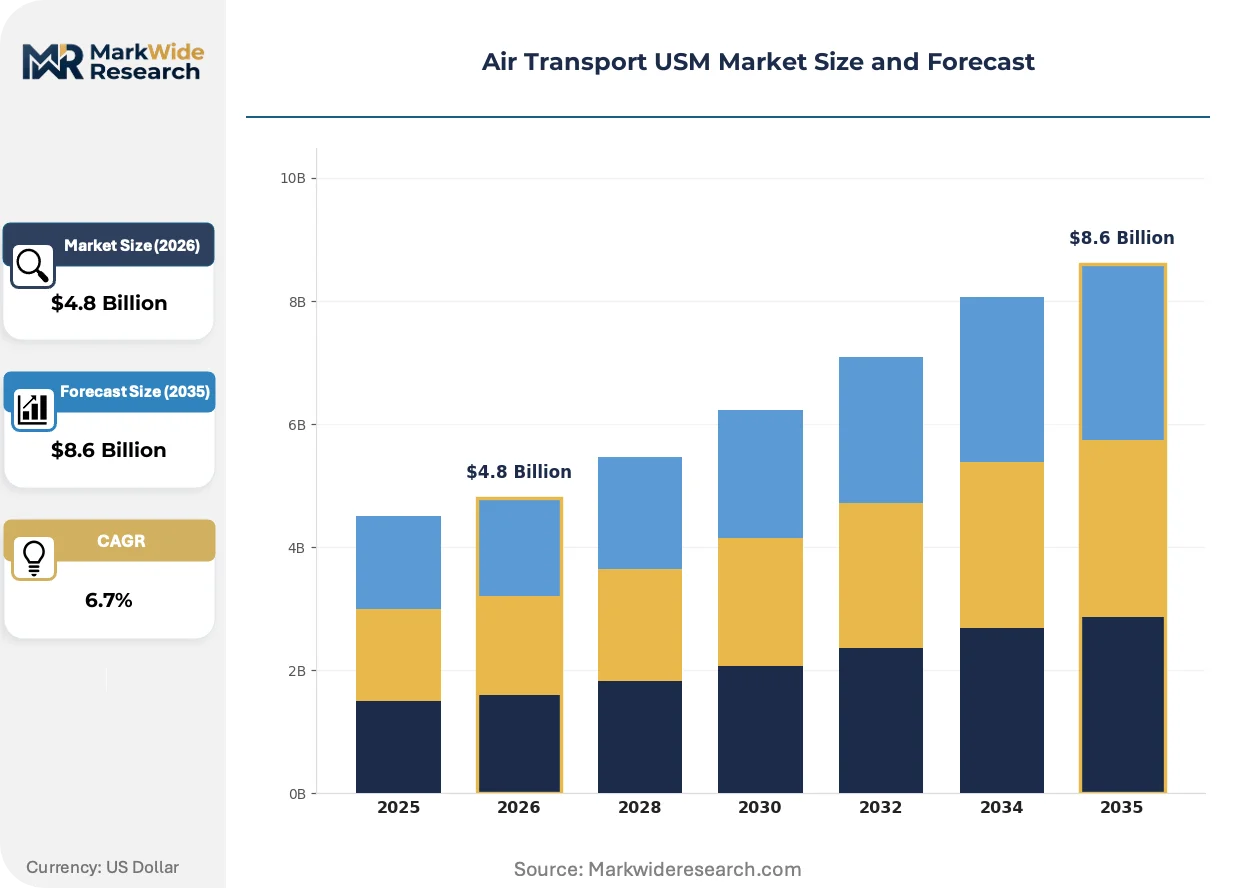
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aircraft, Drones, Helicopters, Gliders Application: Passenger Transport, Cargo Handling, Aerial Surveying, Emergency Services End User: Aerospace Manufacturers, Airlines, Charter Services, Government Agencies Technology: Electric Propulsion, Hybrid Systems, Avionics, Navigation Systems |
| Companies Covered | Delta TechOps, Boeing Company, AAR Corp., A J Walter Aviation Limited, General Electric, AerSale Inc., HEICO Corporation, AJ Walter Aviation Limited, GA Telesis, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Transport USM Market Emerging Trajectories
Digital authentication infrastructure is displacing paper-based chain-of-custody systems across the USM value chain, while regulatory pressure on carbon intensity is accelerating component life extension methodologies previously considered uneconomical.
Blockchain-enabled part provenance tracking is overtaking traditional document-based traceability as the default authentication layer for high-value USM transactions. Major cargo carriers and lessors are mandating distributed-ledger verification for engine and landing gear purchases, compressing due diligence cycles from weeks to hours and reducing title defect exposure in secondary markets.
REACH substance restrictions on hexavalent chromium coatings are forcing European MROs to adopt alternative surface treatments for refurbished components. The regulation is redirecting repair capacity toward plasma-spray and HVOF technologies, with German and French stations investing in new thermal spray cells to maintain Part 145 certification scope.
Airline procurement departments are consolidating USM buying through integrated supply agreements that bundle component sourcing with teardown services and logistics management. This model is displacing spot-market purchasing for narrow-body fleets, with North American network carriers leading the shift toward multi-year, volume-committed arrangements that lock in availability and reduce administrative overhead.
Air Transport USM Market Segmentation
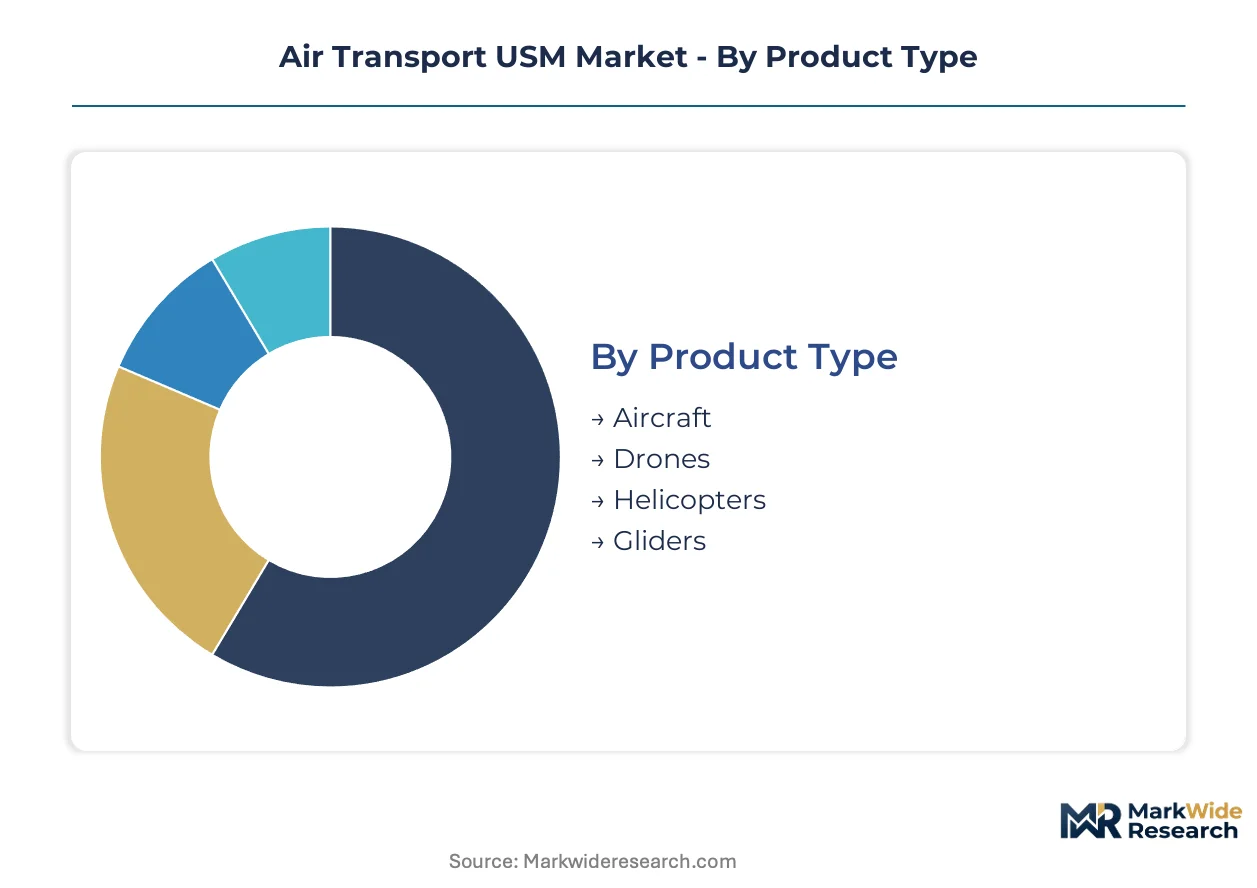
USM procurement patterns diverge sharply across aircraft categories and operational roles. Capital deployment, regulatory exposure, and teardown economics vary by segment, forcing suppliers to specialize rather than compete across all dimensions.
Product Type:
Capital intensity peaks with wide-body platforms requiring specialized teardown infrastructure and extended documentation chains.
- Aircraft:Narrow-body and wide-body airframes generate the deepest USM pools, with 737 NG and A320ceo retirements compressing availability timelines. Fleet renewal cycles in the United States are accelerating parts reuse as MRO consolidation reduces spot-market liquidity.
- Helicopters:Rotorcraft USM concentrates in engine and transmission modules, with offshore energy operators in the Gulf of Mexico managing operating economics through refurbished dynamic components. FAA 14 CFR Part 43 documentation requirements apply with equal stringency despite smaller lot sizes.
- Drones:Unmanned aerial vehicle USM remains nascent given limited fleet scale and rapid technology obsolescence.
- Gliders:Sailplane component recovery operates at the margins of commercial viability, serving recreational and training fleet segments.
Aircraft absorbs the bulk of installed capacity; helicopters are expanding most quickly.
Application:
Operational tempo and component stress profiles determine which applications generate reusable inventory at viable economics.
- Cargo Handling:Freighter conversions and e-commerce logistics expansion are sustaining demand for engine and landing gear USM from retired single-aisle fleets. Narrow-body passenger-to-freighter programs concentrate in the United States, where integrators seek cost-effective component sourcing.
- Passenger Transport:Network carriers dominate procurement volume, consolidating USM buying through integrated supply agreements that bundle teardown services with logistics management.
- Emergency Services:Medical and search-and-rescue operators prioritize reliability over cost, limiting USM penetration in critical mission systems.
- Aerial Surveying:Specialized sensor platforms generate intermittent demand for avionics and structural components with unique configuration requirements.
Cargo handling commands the steepest expansion trajectory as freighter fleet growth outpaces passenger capacity additions.
End User:
Procurement sophistication and compliance capacity separate institutional buyers from fragmented operators.
- Airlines:Network and low-cost carriers represent the largest procurement volume, with North American operators leading the shift toward multi-year, volume-committed arrangements that lock in availability.
- Government Agencies:Defense logistics modernization programs are emerging as disciplined buyers, with military aviation upgrade initiatives creating structured demand for DER-capable repair stations.
- Aerospace Manufacturers:OEM residual value strategies tighten access to high-value modules through power-by-the-hour agreements and controlled teardown participation.
- Charter Services:Fractional and on-demand operators lack scale for integrated supply agreements, remaining dependent on spot-market sourcing.
Airlines retain dominant procurement share; government agencies are gaining share fastest through defense modernization.
Technology:
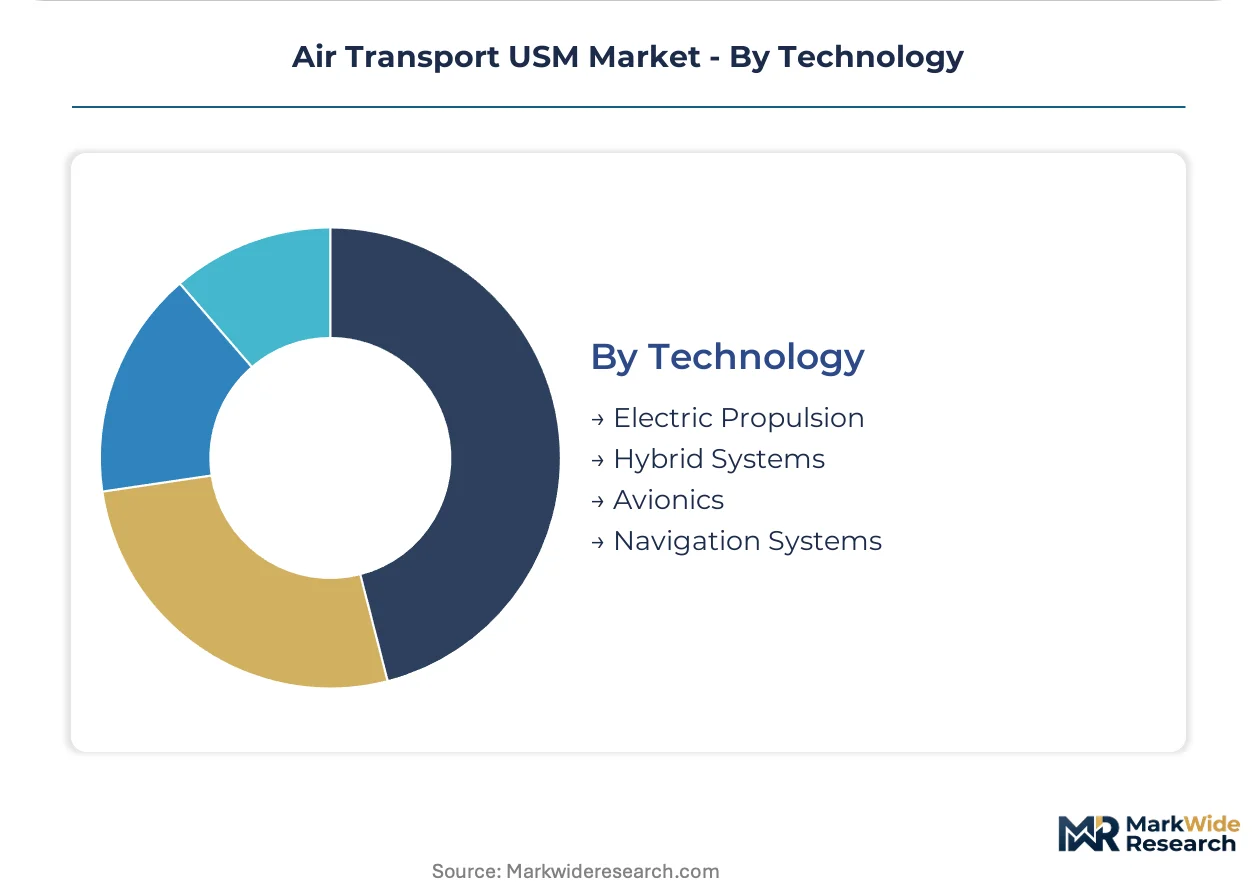
Technology segmentation reveals a bifurcation between mature systems with established USM channels and emerging propulsion architectures with limited secondary flows.
- Avionics:Flight control and communication systems face rapid obsolescence cycles, yet demand persists for backward-compatible units supporting legacy fleet configurations. FAA airworthiness directive synchronization challenges complicate multi-registry deployment.
- Hybrid Systems:Regional operators trialing Safran and MagniX propulsion configurations are generating early secondary markets for power electronics and thermal management components.
- Electric Propulsion:Battery and motor USM channels remain undeveloped given limited fleet penetration and manufacturer-controlled service ecosystems.
- Navigation Systems:GPS and inertial reference unit refurbishment operates within established MRO networks, with traceability documentation satisfying both FAA and EASA requirements.
Avionics captures the deepest existing liquidity; hybrid systems are climbing the fastest as retrofit programs multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in the United Arab Emirates concentrate teardown infrastructure serving cross-border USM flows. Singapore's Seletar Aerospace Park anchors Southeast Asian component redistribution. Germany's MRO clusters handle European regulatory complexity for Part 145 certification.
United States
Fleet renewal cycles at American Airlines and United Airlines accelerate 737 NG part-out activity. FAA 14 CFR Part 43 documentation mandates tighten traceability requirements for resold components. Miami and Phoenix host teardown specialists processing narrow-body retirements from desert storage facilities.
Germany
Lufthansa Technik's Hamburg facility drives wide-body engine module refurbishment demand. EASA Part 145 regulations create parallel certification pathways distinct from FAA frameworks. The country's REACH compliance requirements redirect repair capacity toward hexavalent chromium alternatives.
United Arab Emirates
Emirates' fleet expansion sustains demand for certified engine and landing gear USM. Dubai South free zone incentives attract teardown operators serving African and South Asian carriers. Jebel Ali logistics infrastructure enables rapid component redistribution across Middle Eastern registries.
India
Defense logistics modernization programs under CDSCO-aligned frameworks create structured procurement channels. The country's military aviation upgrade initiatives demand DER-capable repair station certification. Hyderabad and Bangalore emerging as teardown processing hubs for regional narrow-body retirements.
Singapore
ST Engineering's Seletar operations anchor Asia-Pacific component redistribution networks. The Civil Aviation Authority of Singapore enforces documentation standards matching FAA and EASA stringency. Changi cargo handling expansion sustains freighter conversion USM demand from retired passenger fleets.
Air Transport USM Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with OEM-affiliated teardown operations controlling high-value engine modules while independent processors dominate airframe components. Market structure concentrates around three strategic archetypes: airline-captive MRO divisions, diversified aerospace conglomerates, and pure-play USM traders. Competitive positioning hardens through power-by-the-hour agreement restructuring and blockchain traceability infrastructure deployment.
Among airline-affiliated operators, Delta TechOps exemplifies the captive MRO archetype leveraging fleet scale for component recovery economics. Boeing Company and AAR Corp. occupy positions spanning OEM authentication services and integrated supply chain management. GA Telesis, LLC anchors the independent teardown specialist tier focused on engine and landing gear module extraction.
| Leading Market Players |
|---|
| Delta TechOps |
| Boeing Company |
| AAR Corp. |
| A J Walter Aviation Limited |
| General Electric |
| AerSale Inc. |
| HEICO Corporation |
| AJ Walter Aviation Limited |
| GA Telesis, LLC |
| Others |
Supply Flow & Price Mechanics
Network carrier procurement consolidation across North America and Western Europe concentrates buying power around multi-year volume commitments, anchoring contract-based long-term offtake as the dominant pricing structure for narrow-body USM. This buyer concentration compresses spot-market liquidity while elevating premium tiers for documented provenance and reduced lead times.
Pricing Analysis
Short lead-time availability commands premium pricing across engine and landing gear modules, while spot inventory from desert storage facilities trades at discounted rates reflecting extended documentation cycles. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and traceability completeness, with FAA 14 CFR Part 43 documentation tiers separating price bands. Cost compression in standard-grade airframe components is intensifying because titanium alloy input volatility narrows the cost gap with new production parts. Charter services and fractional operators exhibit highest price sensitivity due to limited procurement scale, whereas defense logistics programs demonstrate lowest sensitivity given mission-critical reliability requirements.
Supply Chain Analysis
Freight costs from Arizona and California desert storage facilities to Miami teardown processors represent a material cost layer, with specialized heavy-lift logistics for engine modules commanding premium rates. Supply concentration centers on the United States, Germany, and the United Arab Emirates, with teardown infrastructure clustering around free trade zones and MRO hubs. The supply chain draws from aerospace-grade titanium sponge, nickel-based superalloys, and composite precursor materials, with pricing volatility in titanium alloy inputs compressing teardown economics. Single-source vulnerability around qualified NDT technician pools constrains capacity expansion for emerging processors. Distribution runs through integrated supply agreements bundling teardown services with logistics management, displacing spot-market purchasing for narrow-body fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Air Transport USM Market sits at a technology-transition inflection as blockchain-enabled provenance tracking displaces paper-based chain-of-custody systems, forcing legacy documentation processes into obsolescence.
For Market Incumbents: Anchor market position through backward integration into teardown infrastructure and captive MRO capacity, securing engine module access before OEM residual value control tightens further. Invest in blockchain traceability infrastructure to satisfy emerging carrier mandates for distributed-ledger verification, while consolidating DER-capable repair station networks to defend against independent processor expansion. For New Entrants and Emerging Players: Launch via specialized teardown processing for helicopter engine and transmission modules, where offshore energy operator demand exceeds qualified supplier capacity. Target India defense logistics modernization programs as the most penetrable procurement channel, establishing CDSCO-aligned quality frameworks before first-mover advantages solidify. For Investors and Strategic Acquirers: The window for entry favors pure-play USM traders with established Part 145 certification scope and documented OEM authentication relationships. Long-term viability hinges on digital provenance infrastructure deployment rather than physical inventory scale. Monitor EASA-US regulatory divergence resolution as the critical inflection signal for cross-border USM liquidity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Deployment | Enables real-time provenance verification satisfying FAA and EASA audit requirements simultaneously. |
| DER-Capable Repair Station Expansion | Reduces OEM dependency for critical airframe component certification under 14 CFR Part 43. |
| Integrated Supply Agreement Structuring | Locks multi-year volume commitments from North American network carriers reducing administrative overhead. |
| Helicopter Module Teardown Specialization | Captures offshore energy operator demand for refurbished dynamic components in Gulf of Mexico operations. |
| India Defense Logistics Partnership | Positions suppliers for structured procurement channels under military aviation upgrade initiatives. |
Methodological Framework
Independent corroboration across teardown facility operators, MRO procurement directors, and airline fleet planning executives underwrites the qualitative findings presented in this analysis. Primary interviews with DER-certified repair station managers, component redistribution specialists, and regulatory compliance officers were combined with secondary validation from FAA airworthiness directive filings, EASA Part 145 certification databases, and customs trade data for aerospace component flows. Bottom-up teardown economics modeling and top-down fleet retirement projections were triangulated to establish market sizing boundaries.
Rate-of-change decomposition across the projection horizon separates volume drivers from value capture mechanisms, with segmentation dimensions spanning aircraft product type, application category, end-user procurement sophistication, and technology maturity tier. CAGRs were derived from installed base evolution, retirement wave timing, and USM penetration rate assumptions. Industry-specific forecast inputs incorporate power-by-the-hour agreement restructuring patterns and engine OEM residual value strategy shifts.
Fleet retirement timing acceleration, titanium alloy pricing volatility, and regulatory documentation requirement divergence are the dominant revision risks that could shift market trajectories. Stakeholders should weight assumptions against their own operating context and supply chain exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Mobility
Global Aerodynamics Market
Air Mobility
Off-Shore Helicopters Market
Air Mobility
Helicopter-Based Transportation Market
Air Mobility
North Sea Offshore Helicopter Services Market
Air Mobility
Asia-Pacific Military Aviation Market
Air Mobility
Hang Glider Market
Air Mobility
Advanced Air Mobility Market
Air Mobility
Urban Autonomous Air Mobility Market
Air Mobility
Air Crane Helicopter Market
Air Mobility
Asia Pacific Helicopter Services Market
Air Mobility
Parabolic Flight Tourism Market
Air Mobility
Middle East and Africa General Aviation Market
Air Mobility
Flying Taxi Market
Air Mobility
Flying Motorbikes Market
Air Mobility
Flying Jetpacks Market
Air Mobility
Asia-Pacific Charter Jet Service Market