
 Hang Glider Market | 2026-2036
Hang Glider Market Size, Share, and Industry Trends Forecast 2026-2036
Hang Glider Market Analysis
The capability gap between capital-heavy composite manufacturers and fabric-focused assemblers is collapsing as shared supply chains for carbon fiber and aluminum tubing democratize production inputs. Wills Wing Inc. leverages its California manufacturing base to sustain domestic distribution density against import competition. Moyes Delta Gliders anchors its position through Australian labor integration and coastal testing corridors. Aeros Company competes via Ukrainian engineering density and Eastern European cost structures.
A hang glider is an unpowered, foot-launched heavier-than-air craft with a fabric or rigid wing surface spanning 8 to 18 meters, designed to exploit rising air currents for sustained flight. The craft serves recreational aviation, competitive cross-country racing, and tourism operations requiring minimal infrastructure beyond hillsides and trained pilots. Flex-wing configurations dominate unit volumes due to lower entry costs and transportability, while rigid-wing designs command premium positioning among competitive pilots seeking glide ratio advantages. Composite materials are displacing aluminum in high-performance segments as fabric sail technologies advance durability ratings. Tandem use cases generate outsized revenue per unit given commercial certification requirements and operator liability structures.
FAA Part 103 ultralight regulations in the United States, EASA CS-LSA frameworks in Europe, and Civil Aviation Safety Authority certificates in Australia collectively shape airworthiness testing, pilot training mandates, and commercial operational permissions. These bodies enforce structural load limits, reserve parachute carriage rules, and instructor qualification tiers that filter market access and product liability exposure. Stakeholders must monitor harmonization pressures between national ultralight categories and emerging electric-assisted propulsion classifications that could redraw segment boundaries.
Market Dynamics
Carbon fiber pre-preg sourcing consolidation among three Japanese and German suppliers is compressing margins for mid-tier assemblers while elevating barriers to high-performance certification.
Growth Catalysts
- FAA Part 103 ultralight framework:The United States maintains minimal airworthiness barriers for single-place recreational craft, sustaining entry-level participation and fleet turnover among hobbyist pilots.
- Tourism operator fleet expansion:Coastal adventure destinations in Australia and Brazil are procuring tandem-certified gliders to serve experiential travel packages.
- Pre-impregnated composite layup:Automated cutting and vacuum-bagging processes are reducing sail cell variability and extending airframe fatigue life ratings.
Market Restraints
- Carbon fiber supply concentration:Toray and SGL Carbon control aerospace-grade tow pricing, exposing assemblers to yen-euro volatility and allocation rationing during automotive demand surges.
- EASA CS-LSA certification timeline:European commercial operators face 18-24 month approval cycles for new airframe designs, freezing product refresh cadences.
- Powered paraglider substitution:Foot-launched paramotors with two-stroke engines are capturing price-sensitive recreational pilots seeking self-launch independence from ridge lift dependence.
Strategic Opportunities
- Swiss alpine tourism corridors:Interlaken and Verbier operators lack sufficient tandem inventory to meet summer booking demand, creating white space for certified commercial fleet deployment.
- Electric sustainer motor integration:Lithium-polymer battery packs paired with foldable propeller units are enabling self-launch capability in rigid-wing competition segments.
- Direct-to-pilot digital channels:Manufacturers are bypassing regional distributor markups through configuration tools and containerized shipping to established flying sites.
Industry Challenges
- Master rigger certification scarcity:The FAA and Civil Aviation Safety Authority maintain divergent practical examination standards, fragmenting instructor mobility across English-speaking markets.
- Airframe-sail integration testing:Load frame validation for new batten configurations requires expensive multiaxial fatigue rigs concentrated in German and Australian laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hang Glider Market |
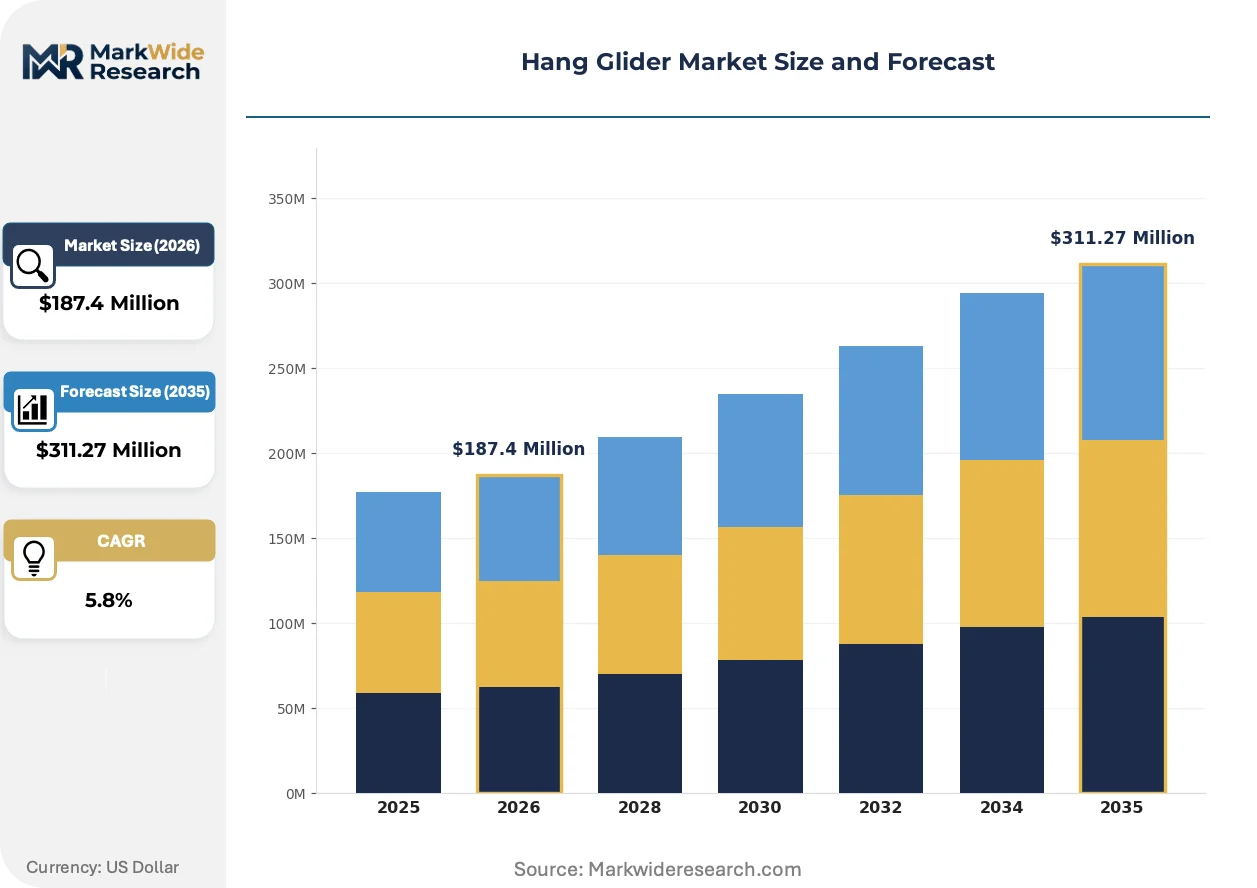
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid-Wing, Flex-Wing, Speed Wing, Paramotor Material: Aluminum, Composite, Fabric, Plastic Use Case: Recreational, Competitive, Training, Tandem End User: Enthusiasts, Schools, Clubs, Tour Operators |
| Companies Covered | Wills Wing Inc., Moyes Delta Gliders, Aeros Company, North Wing, Airborne Windsports Pty Ltd., Apco Aviation, ICARO 2000 srl, QUASAR, Charly Produkte, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hang Glider Market Emerging Trajectories
Material substitution and regulatory recalibration for electric-assisted propulsion are redrawing performance categories and certification boundaries simultaneously.
Pre-impregnated carbon fiber fabric is supplanting hand-laid wet layup construction in high-aspect-ratio rigid wings. Competition pilots operating in the FAI Class 1 category are adopting these airframes to exploit glide ratios exceeding 15:1. The shift is compressing production lead times for premium manufacturers while raising repair skill requirements at service centers.
EASA is drafting updated CS-LSA annexes to accommodate electric sustainer motors under 25 kilowatts output. The proposed framework would permit self-launch capability without reclassifying gliders as powered ultralights. German and Austrian manufacturers are pre-submitting structural load cases to secure first-mover certification slots.
Adventure tourism operators are consolidating procurement through lease-finance structures rather than outright purchase. Brazilian and South African coastal resorts now source tandem gliders through three-year operating leases with maintenance-included terms. The model shifts balance-sheet risk to lessors and accelerates fleet refresh cycles.
Hang Glider Market Segmentation
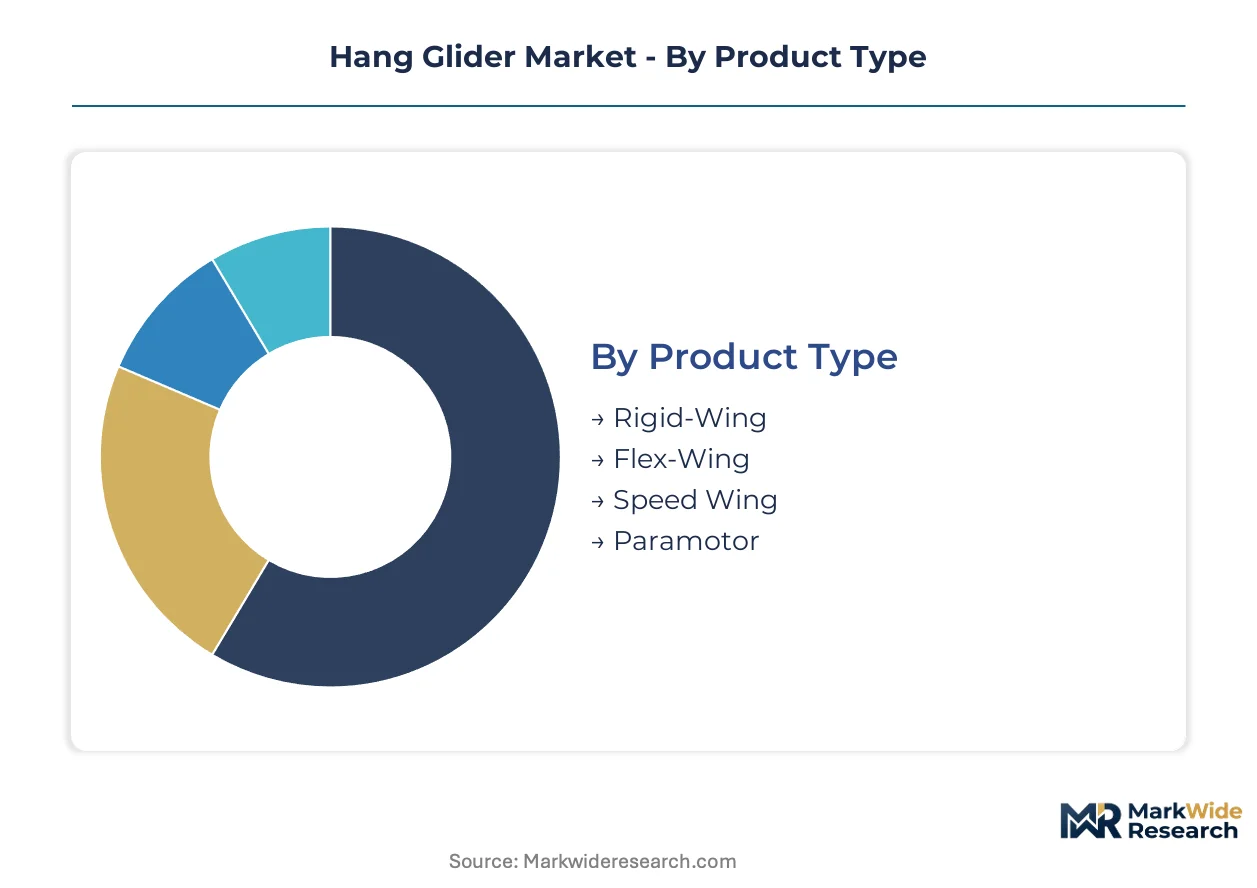
Hang glider segmentation reveals how substitution pressures and certification tiers fragment purchasing decisions across pilot skill levels and operational models. Understanding these divides exposes where margin pools concentrate and which configurations face erosion from powered alternatives.
Product Type:
Flex-wing configurations face the most acute substitution pressure from powered paragliders, while rigid-wing designs maintain defensible positioning through performance gaps that paramotors cannot bridge.
- Flex-Wing:Fabric sail tensioned over aluminum or composite frame delivers packable, transportable flight. Demand clusters in Australian coastal tourism corridors and US ridge-soaring sites where entry-level pilots prioritize logistics over glide efficiency. FAA Part 103 ultralight certification sustains low barrier participation.
- Rigid-Wing:Molded composite shell with integrated control surfaces achieves glide ratios exceeding 15:1. Competitive cross-country pilots in Switzerland and Austrian alpine regions drive procurement, with EASA CS-LSA certification requirements filtering supplier access.
- Speed Wing:Compressed wing area optimized for descent control in mountain environments. Swiss and French alpine operators deploy for steep-slope access where conventional gliders face terrain limitations.
- Paramotor:Powered frame with two-stroke engine enabling flat-ground launch independence. Recreational pilots in Brazil and South Africa substitute for ridge-dependent hang gliders, eroding flex-wing volume in price-sensitive segments.
Flex-wing retains volume leadership; rigid-wing holds the steepest expansion curve.
Material:
Cost tier stratification separates premium composite airframes from commoditized aluminum and fabric assemblies, with supply chain concentration in carbon fiber pre-preg reshaping competitive access.
- Composite:Pre-impregnated carbon fiber layup with vacuum-bagged curing achieves strength-to-weight ratios enabling high-aspect-ratio designs. German and Austrian manufacturers dominate rigid-wing production, leveraging Toray and SGL Carbon supply relationships.
- Aluminum:Extruded 6061-T6 tubing with bolted joint construction dominates flex-wing frames. Australian and US assemblers source from regional metal distributors, maintaining cost positioning against import competition.
- Fabric:Woven polyester or nylon sailcloth with UV-stabilized coatings provides primary lift surface. Coastal operators in Brazil prioritize durability ratings for salt-air exposure.
- Plastic:Molded polycarbonate or ABS components for control bars and fairings. Entry-level manufacturers in Eastern Europe integrate for cost reduction.
Aluminum dominates unit shipments; composite commands revenue per unit premiums.
Use Case:
Application maturity varies sharply, with commercial tandem operations generating outsized revenue per airframe against fragmented recreational participation.
- Tandem:Reinforced airframe with dual-harness configuration certified for commercial passenger carriage. Australian and Swiss tourism operators face inventory shortages against summer booking demand, with liability structures elevating procurement standards.
- Recreational:Single-place configuration for solo hobbyist flight. US participation sustains fleet turnover through FAA minimal-barrier framework.
- Competitive:FAI Class 1 certified designs for cross-country racing and aerobatic precision. German and Austrian pilots drive specification evolution.
- Training:Durable construction with forgiving stall characteristics for school environments. US and Australian instructor networks standardize on specific models.
Tandem captures highest revenue per unit; recreational sustains absolute volume.
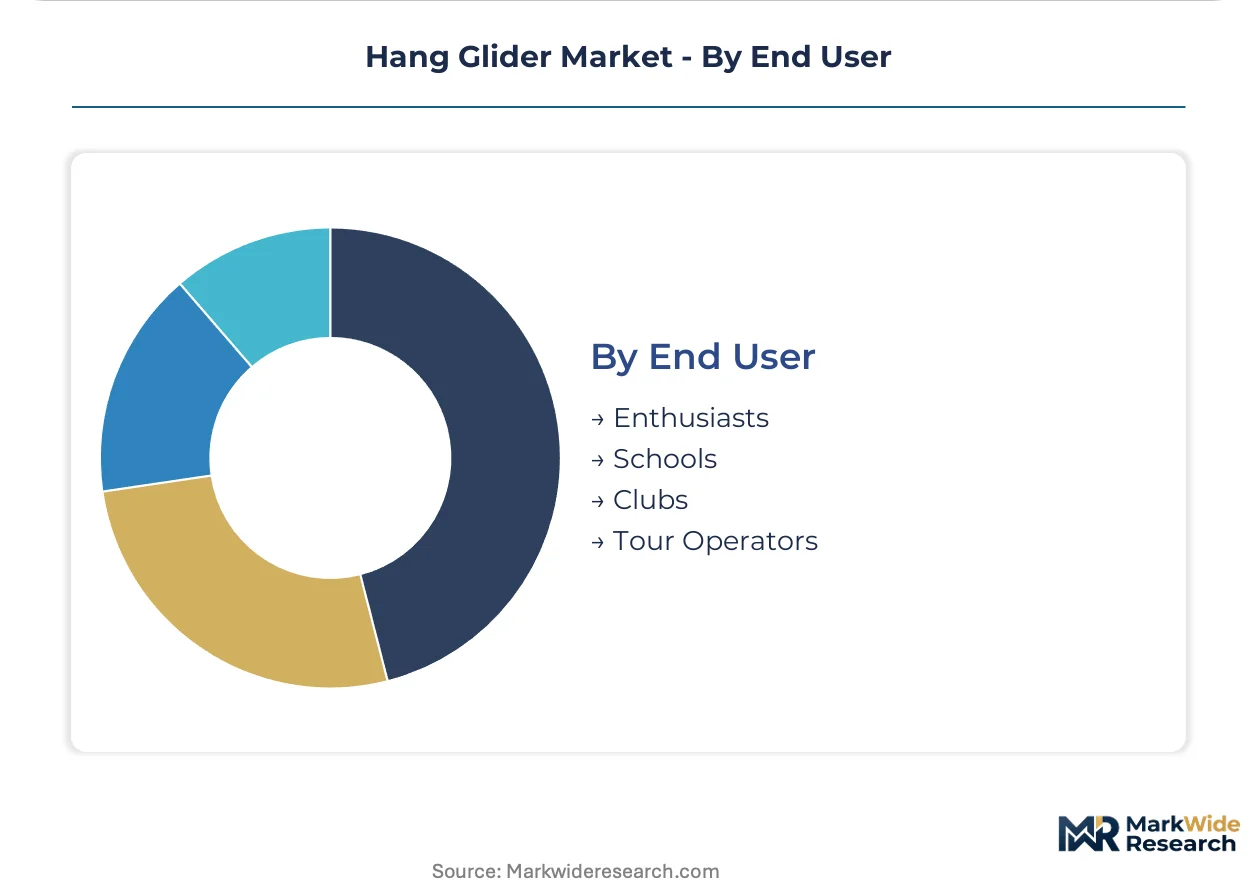
End User:
Customer type concentration shifts procurement patterns, with institutional buyers consolidating fleet decisions against fragmented enthusiast purchasing.
- Tour Operators:Commercial adventure providers in Interlaken, Verbier, and Rio de Janeiro source through lease-finance structures. Three-year operating leases with maintenance-included terms accelerate refresh cycles.
- Schools:Certified training organizations in the US and Australia require durable, standardized fleets. Civil Aviation Safety Authority instructor qualification tiers filter equipment selection.
- Clubs:Member-owned cooperatives at established flying sites in California and New South Wales aggregate purchasing power for fleet acquisitions.
- Enthusiasts:Individual hobbyists purchasing through direct-to-pilot digital channels. Manufacturers bypass regional distributor markups with containerized shipping to established sites.
Tour operators drive commercial specification; enthusiasts sustain aftermarket service demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive recreational pilots in Brazil and South Africa gravitate toward aluminum-framed flex-wings, while competitive pilots in Switzerland and Austria absorb premium rigid-wing pricing without volume elasticity. This demand bifurcation shapes regional procurement patterns and manufacturer positioning strategies.
United States
FAA Part 103 ultralight regulations sustain minimal-barrier entry for hobbyist pilots across California and Florida coastal ridges. The framework exempts single-place recreational craft from airworthiness certification, accelerating fleet turnover among enthusiast-owned fleets. Wills Wing Inc. leverages its California manufacturing base to defend domestic distribution density against import competition.
Australia
Civil Aviation Safety Authority certificates filter commercial tandem operations along Queensland and New South Wales coastal tourism corridors. Instructor qualification tiers standardize equipment selection for training fleets. Moyes Delta Gliders anchors its position through Australian labor integration and coastal testing corridors serving adventure operators.
Switzerland
EASA CS-LSA frameworks govern commercial passenger carriage across Interlaken and Verbier alpine destinations. Tandem inventory shortages persist against summer booking demand, elevating procurement standards for reinforced airframes. Swissmedic-adjacent safety culture reinforces liability-conscious operator behavior.
Brazil
Rio de Janeiro coastal resorts source tandem gliders through three-year operating leases with maintenance-included terms. Salt-air exposure prioritizes fabric durability ratings over performance optimization. ANVISA-aligned operational safety expectations filter equipment selection for tourism fleet deployment.
Ukraine
Eastern European cost structures enable competitive positioning for composite engineering output. Aeros Company competes via Ukrainian engineering density, serving price-sensitive segments across adjacent markets. Regulatory alignment pressures with EASA frameworks shape export certification strategies.
Hang Glider Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with composite pre-preg specialists commanding premium positioning while aluminum fabricators defend volume tiers. The vendor base spans California-based domestic defenders, Australian integrated producers, and Eastern European cost-optimized engineering houses. Three archetypes dominate: integrated coastal manufacturers with testing corridor control, composite specialists with Toray supply relationships, and regional assemblers leveraging distributor bypass. Competitive moves concentrate on direct-to-pilot digital channels and lease-finance fleet structures for tourism operators.
Among California-based fabricators, Wills Wing Inc. represents the domestic defender archetype, sustaining distribution density through regional manufacturing presence. Moyes Delta Gliders exemplifies the integrated coastal producer model, leveraging Australian labor and testing infrastructure. Aeros Company occupies the Eastern European cost-engineering position, competing on structural load case optimization.
| Leading Market Players |
|---|
| Wills Wing Inc. |
| Moyes Delta Gliders |
| Aeros Company |
| North Wing |
| Airborne Windsports Pty Ltd. |
| Apco Aviation |
| ICARO 2000 srl |
| QUASAR |
| Charly Produkte |
| Others |
Supply Flow & Price Mechanics
Eighteen-to-twenty-four-month EASA CS-LSA certification cycles compress inventory turns for European commercial operators while amplifying pricing power for certified manufacturers serving tandem tourism fleets. This lead-time band concentrates procurement leverage among pre-certified suppliers who capture premium positioning through airworthiness validation, while uncertified assemblers face margin erosion in recreational segments.
Pricing Analysis
After-market service revenue from annual inspections, sail replacement, and reserve parachute repacking drives lifetime value per airframe beyond initial unit economics. Three-tier pricing structure across premium composite rigid-wings, standard aluminum flex-wings, and economy fabric-focused entry models stratifies procurement decisions. Certification grade under EASA CS-LSA versus FAA Part 103 frameworks creates the steepest price differentiation, with Swiss and Austrian operators absorbing premiums unavailable to US hobbyists. Cost compression in mid-tier flex-wing segments intensifies as Brazilian and South African tourism operators shift to lease-finance structures that transfer balance-sheet risk to lessors.
Supply Chain Analysis
Japan and Germany anchor aerospace-grade carbon fiber pre-preg production through Toray and SGL Carbon supply relationships that filter competitive access. Australian and US aluminum tubing fabrication feeds flex-wing frame assembly, while Ukrainian engineering houses exploit Eastern European cost structures for composite load-case optimization. Raw material dependencies on Japanese tow pricing, German resin systems, and Australian 6061-T6 extrusions expose assemblers to yen-euro volatility and ocean freight allocation pressures. Distribution runs through direct-to-pilot digital channels and regional flying-site containerized shipping that bypasses traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Australian and Swiss tourism operators consolidating fleet procurement through lease-finance structures, fragmenting price-setting autonomy for smaller recreational assemblers.
For Market Incumbents: Secure Toray and SGL Carbon supply allocations through multi-year offtake agreements before automotive demand surges ration aerospace-grade tow availability. Invest in EASA pre-submission for electric sustainer motor integration to capture first-mover certification slots as CS-LSA annexes evolve. Channel control through direct-to-pilot configuration tools defends margin position against import competition in California and Florida ridge-soaring corridors.
For New Entrants and Emerging Players: After-sales service capacity gaps in Swiss alpine tourism corridors present white-space opportunities where established manufacturers under-serve rapid fleet refresh demand. Target tandem-certified rigid-wing deployment in Interlaken and Verbier through lease-finance partnerships with local operators. Go-to-market positioning as maintenance-included fleet lessors accelerates penetration against purchase-focused incumbents.
For Investors and Strategic Acquirers: Long-term, this sits as a certification-moat play because EASA CS-LSA approval timelines and FAA instructor qualification fragmentation create durable barriers against commoditization. Acquisition targets center on integrated coastal manufacturers with captive testing corridors and established Civil Aviation Safety Authority relationships. Signal to watch: harmonization pressures between national ultralight categories and emerging electric-assisted propulsion classifications that redraw segment boundaries.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Sustainer Motor Certification | EASA pre-submission secures first-mover positioning as CS-LSA annexes accommodate self-launch capability. |
| Direct-to-Pilot Digital Channel Expansion | Configuration tools and containerized shipping bypass regional distributor markups at established flying sites. |
| Lease-Finance Fleet Structuring | Three-year operating leases shift balance-sheet risk to lessors and accelerate refresh cycles for tourism operators. |
| Carbon Fiber Supply Allocation Agreements | Multi-year Toray and SGL Carbon offtakes defend against yen-euro volatility and automotive demand surges. |
| Master Rigger Certification Standardization | FAA and Civil Aviation Safety Authority alignment reduces instructor mobility fragmentation across English-speaking markets. |
Methodological Framework
Initial hypotheses were tested against primary input from hang glider manufacturing executives, tourism fleet procurement managers, certified flight instructors, and airworthiness testing laboratory directors, then refined through secondary validation. FAA Part 103 exemption frameworks, EASA CS-LSA submission databases, Civil Aviation Safety Authority certificate registries, and customs trade records provided triangulation anchors. Bottom-up unit shipment modeling across flex-wing and rigid-wing configurations reconciled against top-down tourism operator fleet surveys.
Variance decomposition across product type, material tier, use case certification level, and end-user concentration shaped analytical framework construction throughout the projection horizon. CAGRs derived from segment-level volume trajectories and value-per-unit premiums, with specific inputs including coastal tourism booking data from Queensland and Rio de Janeiro, ridge-soaring participation rates from California and New South Wales, and composite pre-preg pricing indices from Japanese and German suppliers.
Underlying assumptions cover sustained EASA-FAA regulatory divergence, carbon fiber supply concentration persistence, and electric sustainer motor adoption curves, with deviation risk concentrated in harmonization pressures between ultralight categories and powered paraglider substitution rates. Recalibration cycles align with material shifts in certification timeline announcements, supply allocation rationing events, and tourism operator consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Mobility
Flying Taxi Market
Air Mobility
Air Transport USM Market
Air Mobility
Flying Motorbikes Market
Air Mobility
Asia Pacific Helicopter Services Market
Air Mobility
Advanced Aerial Mobility Market
Air Mobility
Middle East and Africa General Aviation Market
Air Mobility
Global Aerodynamics Market
Air Mobility
South America Offshore Helicopter Services Market
Air Mobility
Advanced Air Mobility Market
Air Mobility
Global Flying Cars Market
Air Mobility
North America Offshore Helicopter Services Market
Air Mobility
Urban Air Mobility (UAM) Market
Air Mobility
Helicopter-Based Transportation Market
Air Mobility
Air Transport Modifications Market
Air Mobility
Urban Autonomous Air Mobility Market
Air Mobility
Middle-East and Africa Military Aviation Market