
 Global Flying Cars Market | 2026-2036
Global Flying Cars Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flying Cars Market Analysis
Urban air mobility operators is reorganizing fleet procurement priorities around certified electric VTOL platforms. Joby Aviation leverages extensive flight-test data to anchor its position in FAA certification pathways. Volocopter GmbH dominates European urban air taxi concessions through early operational partnerships with airport authorities. EHang specializes in autonomous frame architecture that competes on pilot-elimination economics for intra-city routes.
Flying cars are electric or hybrid vertical take-off and landing vehicles designed to operate in controlled airspace below 5,000 feet, utilizing distributed electric propulsion and fly-by-wire control systems to transport passengers or cargo between urban nodes. Electric VTOL configurations lead current development pipelines due to battery energy density improvements and simplified mechanical architecture. Commercial Transport end users command the largest near-term revenue pool as aerial taxi operators pre-order certifiable platforms, while AI Navigation technology represents the fastest-growing capability segment as autonomy thresholds determine operational economics.
The FAA's powered-lift SFAR, EASA's SC-VTOL certification framework, and the UAE's GCAA urban air mobility operational guidelines collectively shape airworthiness standards and route access. These regulatory bodies enforce battery thermal-runaway containment protocols, noise-abatement flight corridors, and pilot-autonomy transition requirements that directly determine which platforms achieve commercial deployment. Stakeholders must monitor certification reciprocity agreements between regulators to anticipate which vehicle designs unlock multi-jurisdictional revenue streams.
Market Dynamics
Certification reciprocity negotiations between the FAA, EASA, and GCAA are compressing type-approval timelines and determining which electric VTOL architectures achieve multi-jurisdictional deployment first.
Growth Catalysts
- Battery Energy Density Gains:Solid-state lithium-metal cells are extending electric VTOL range envelopes beyond 150 kilometers, unlocking inter-city corridor economics previously reserved for combustion platforms.
- Dubai's Aerial Taxi Commitment:The RTA's commercial corridor designation is creating demand visibility that anchors fleet pre-orders and attracts infrastructure capital into vertiport networks.
- FAA Powered-Lift SFAR:This Special Federal Aviation Regulation establishes streamlined certification pathways for electric VTOL aircraft, reducing regulatory uncertainty for developers targeting US airspace entry.
Market Restraints
- Lithium Supply Concentration:Cathode precursor refining concentrates in China, creating input cost volatility and geopolitical exposure for battery-dependent propulsion systems.
- Pilot-Autonomy Transition Requirements:The FAA and EASA mandate graduated autonomy thresholds that extend operational certification timelines and inflate flight-test hour requirements.
- Noise-Abatement Corridor Restrictions:Urban flight paths face decibel ceilings below 65 dB at 100 meters, limiting rotor disk loading options and compressing payload-range tradeoffs.
Strategic Opportunities
- Saudi Arabia's NEOM Development:The giga-project's integrated mobility blueprint designates aerial taxi networks as primary inter-district connectors, creating greenfield deployment without legacy infrastructure conflicts.
- Autonomous Cargo Last-Mile:Pilot-elimination economics are converging with medical supply and e-commerce fulfillment demand in dense urban cores.
- Japan's 2025 Osaka Expo:METI's urban air mobility demonstration mandate is accelerating temporary operational certificates that convert to permanent route authority post-event.
Industry Challenges
- Flight Control Software Certification:Fly-by-wire systems require DO-178C compliance documentation that consumes 40% of engineering hours and creates schedule risk.
- Vertiport Grid Electrification:Megawatt-scale charging infrastructure demands utility interconnection upgrades that lag vehicle certification timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flying Cars Market |
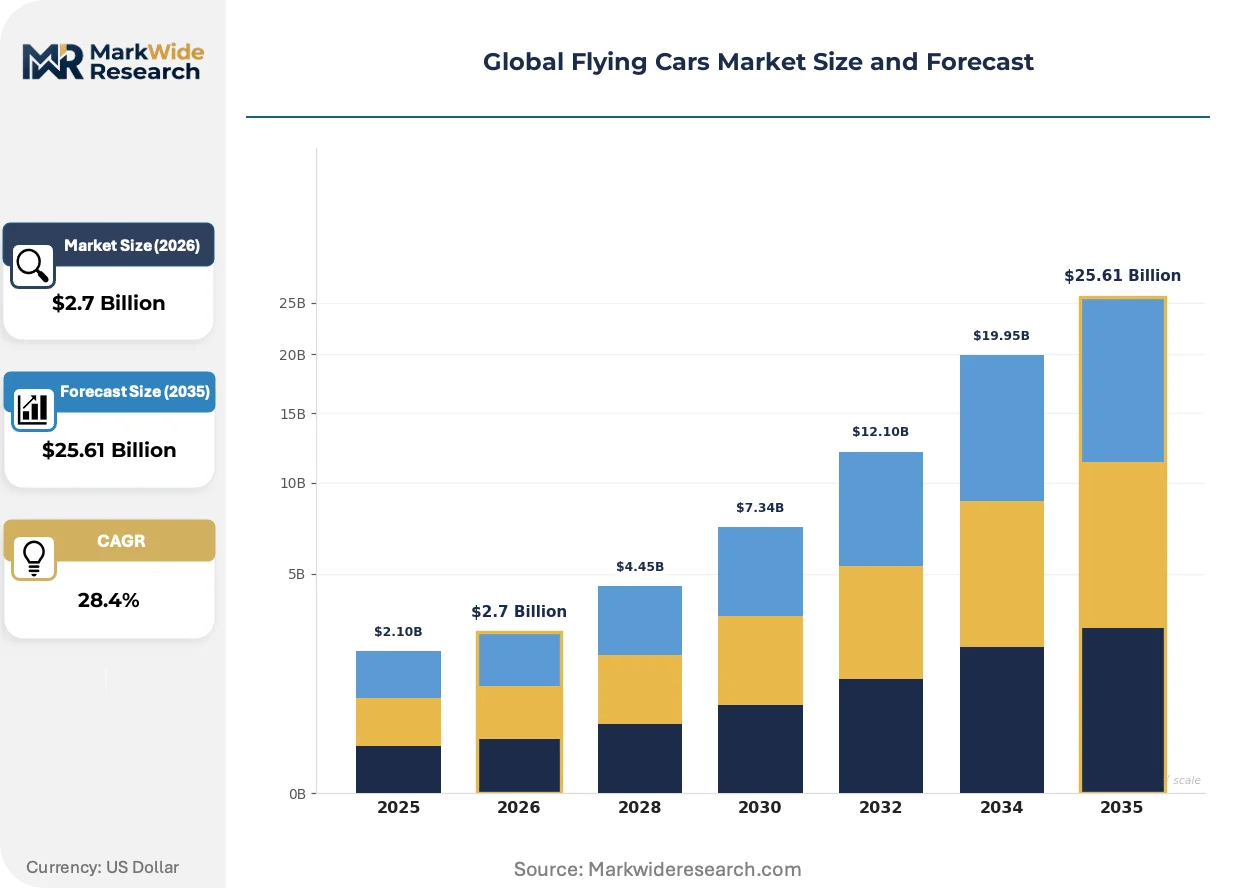
| Market Size in 2026 | $2.7 Billion |
| Market Size in 2035 | $25.61 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric VTOL, Hybrid VTOL, Traditional Aircraft, Autonomous Drones End User: Personal Use, Commercial Transport, Emergency Services, Military Applications Technology: Battery Technology, AI Navigation, Aerospace Materials, Advanced Propulsion Regulatory Framework: Airspace Regulations, Safety Standards, Certification Processes, Operational Guidelines |
| Companies Covered | Joby Aviation, AeroMobil, Volocopter GmbH, Lilium, Archer Aviation, EHang, PAL-V, Airbus, Kitty Hawk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flying Cars Market Emerging Trajectories
Distributed electric propulsion architectures are fragmenting into competing certification strategies, with tilt-rotor, lift-plus-cruise, and multicopter designs pursuing divergent regulatory pathways.
Hybrid-electric range extenders are bifurcating platform development pipelines. Long-haul operators favor turbine-electric architectures for 300-kilometer missions, while intra-city services commit to pure-electric frames for operational cost minimization. This split is compressing battery supplier negotiation leverage and forcing cell manufacturers to segment product roadmaps by mission profile.
EASA's SC-VTOL certification framework is mandating fault-tolerant flight control redundancy that exceeds FAA powered-lift requirements. European developers are absorbing 15-20% airframe weight penalties to satisfy these standards, while US-focused platforms optimize for lighter certification burdens. The divergence is fragmenting global platform compatibility and complicating fleet standardization for multinational operators.
Aerial taxi operators are consolidating procurement authority into centralized fleet management entities that bypass OEM direct sales channels. These aggregators negotiate multi-platform contracts spanning vertiport access, maintenance, and pilot training, compressing manufacturer margin capture. The shift is most visible in the United Arab Emirates, where RTA-coordinated procurement pools are displacing individual operator negotiations.
Global Flying Cars Market Segmentation
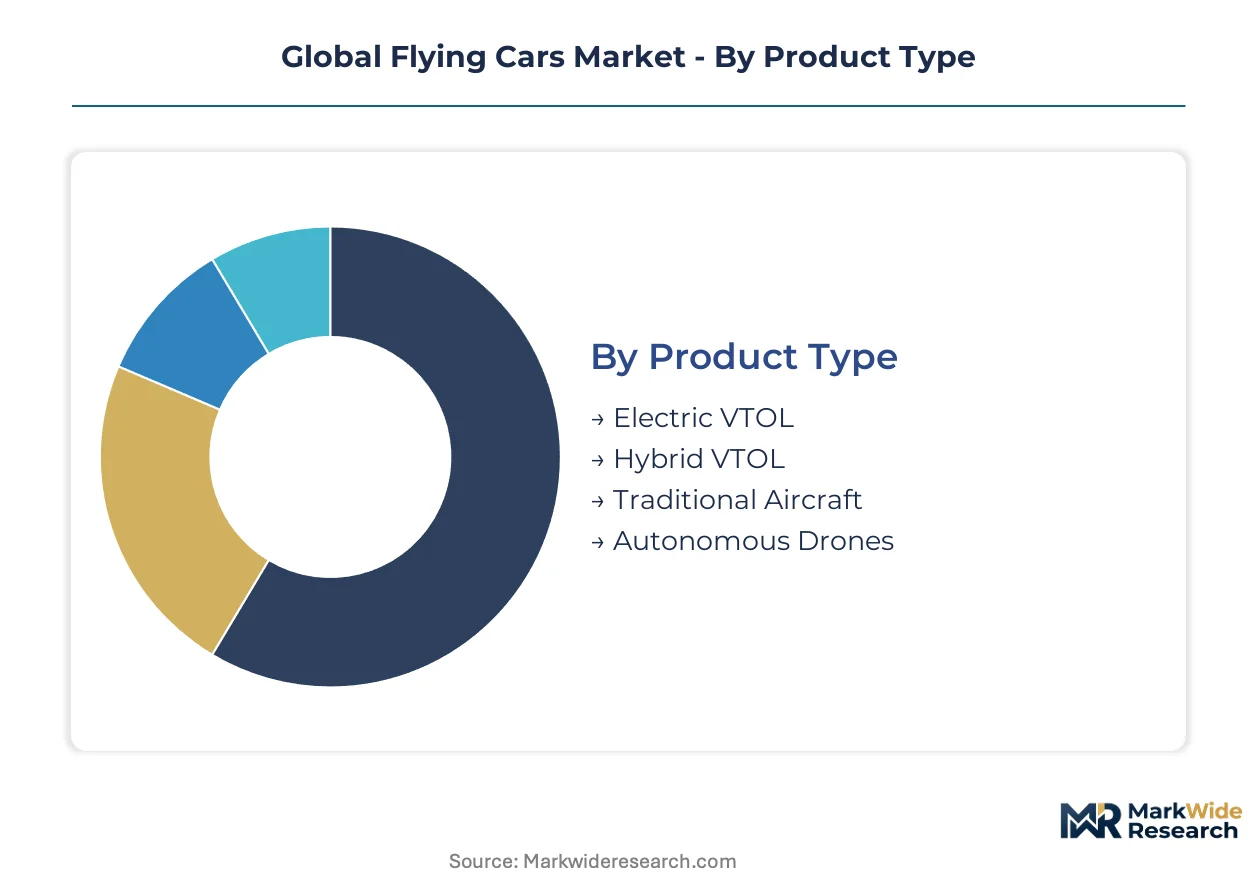
Segmentation in the flying cars market reveals how certification pathways, autonomy thresholds, and energy architectures partition revenue pools across radically different operational economics. Understanding these divisions exposes where capital deployment concentrates and which technology bets carry the highest commercial risk.
Product Type:
Margin pools concentrate in configurations that balance certification speed against operational flexibility, with electric architectures capturing premium pricing from fleet operators seeking predictable cost structures.
- Electric VTOL:Pure-electric distributed propulsion systems leverage solid-state lithium-metal cells for missions under 150 kilometers. Fleet operators in Dubai and Saudi Arabia pre-order these platforms for intra-city corridors where vertiport density supports frequent charging cycles.
- Hybrid VTOL:Turbine-electric range extenders enable 300-kilometer inter-city routes that pure batteries cannot serve. Long-haul aerial taxi networks in Japan and the UAE favor this architecture for connecting secondary cities without ground infrastructure dependency.
- Traditional Aircraft:Conventional fixed-wing platforms with VTOL modifications serve markets where regulatory grandfathering accelerates airworthiness approval. These configurations dominate early military and cargo applications requiring proven flight control systems.
- Autonomous Drones:Pilot-elimination frames below 600 kilograms target last-mile medical supply and e-commerce fulfillment in dense urban cores. METI's Osaka Expo demonstration mandate is accelerating temporary operational certificates for these platforms.
The dominant share belongs to Electric VTOL, while Hybrid VTOL is closing the gap fastest as inter-city route economics mature.
End User:
Customer-type segmentation tracks how procurement authority consolidates around fleet managers versus fragmented individual buyers, reshaping sales channel economics.
- Commercial Transport:Aerial taxi operators aggregate multi-platform contracts spanning vertiport access, maintenance, and pilot training. RTA-coordinated procurement pools in the UAE displace individual operator negotiations and compress manufacturer margins.
- Emergency Services:Medical evacuation and search-and-rescue missions demand fault-tolerant redundancy exceeding standard certification. EASA's SC-VTOL framework mandates 15-20% airframe weight penalties for these applications, limiting platform choices.
- Personal Use:Individual ownership remains constrained by pilot licensing requirements and vertiport scarcity. Wealthy early adopters in Switzerland and Monaco represent the primary addressable pool pending autonomy threshold relaxations.
- Military Applications:Defense procurement prioritizes electronic warfare resilience and logistics flexibility over civilian noise-abatement standards. These programs fund technology maturation that later transfers to commercial platforms.
Commercial Transport commands the largest revenue concentration, though Emergency Services is expanding most quickly as healthcare systems integrate aerial networks.
Technology:
Technology segmentation exposes where engineering hour allocation determines competitive moats, with software certification consuming disproportionate development resources.
- AI Navigation:Autonomy systems require DO-178C compliance documentation that absorbs 40% of engineering schedules. FAA and EASA graduated thresholds for pilot-autonomy transition extend certification timelines but unlock operational cost advantages for intra-city routes.
- Battery Technology:Cell chemistry roadmaps segment by mission profile, with solid-state lithium-metal extending range envelopes. Cathode precursor refining concentration in China creates input cost volatility for European and US developers.
- Aerospace Materials:Composite airframes reduce weight penalties from EASA's fault-tolerance mandates. Material suppliers face bifurcated demand between lightweight civilian platforms and hardened military specifications.
- Advanced Propulsion:Distributed electric motor architectures compete across tilt-rotor, lift-plus-cruise, and multicopter designs. Each configuration pursues divergent regulatory pathways that fragment global platform compatibility.
AI Navigation attracts the steepest investment trajectory, while Battery Technology remains the critical path item for range extension.
Regulatory Framework:
Compliance segmentation tracks how jurisdictional divergence fragments platform standardization and determines multi-market revenue potential.
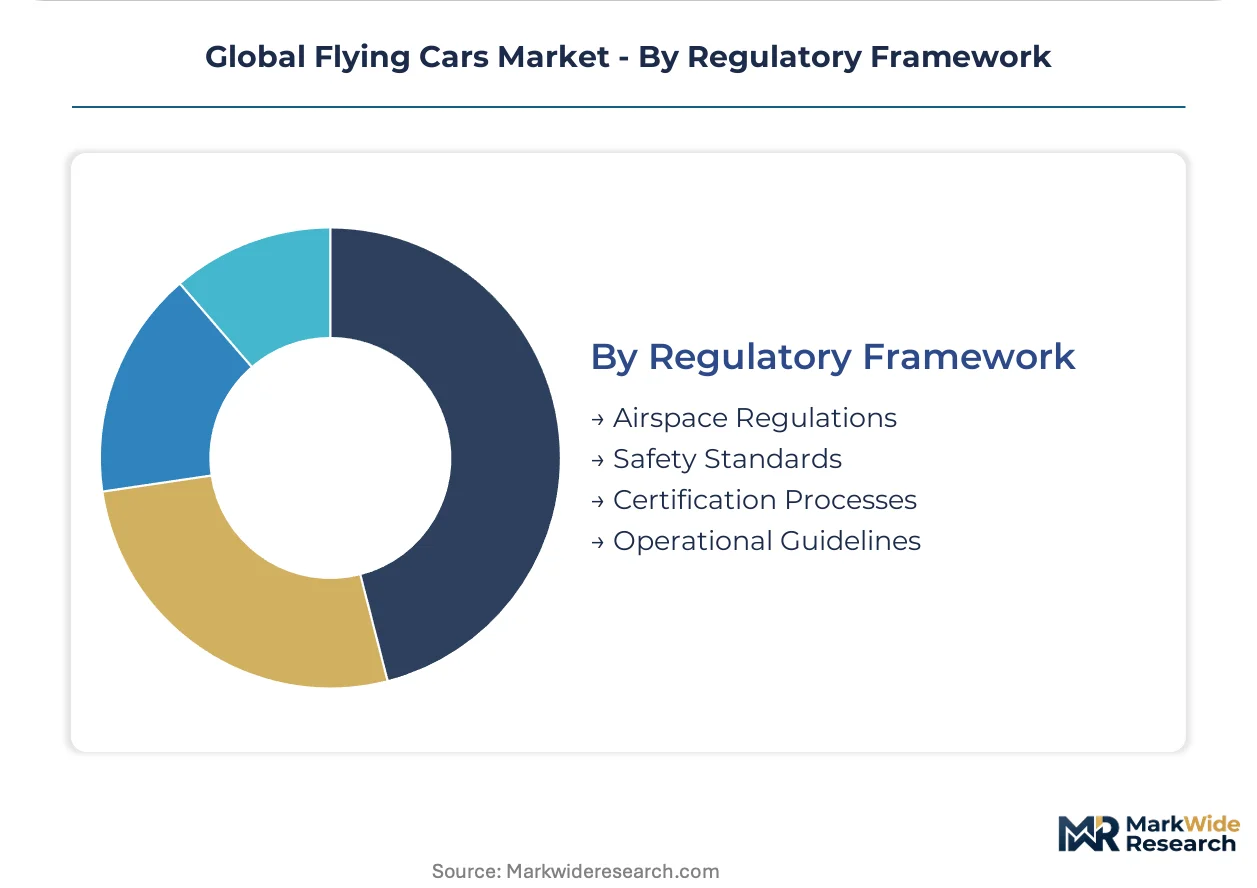
- Certification Processes:FAA's powered-lift SFAR establishes streamlined pathways for US airspace entry. Reciprocity negotiations with EASA and GCAA compress timelines for platforms achieving multi-jurisdictional approval.
- Airspace Regulations:Controlled airspace below 5,000 feet requires integration with existing traffic management systems. Dubai's RTA corridor designation creates demand visibility that anchors fleet pre-orders.
- Safety Standards:Battery thermal-runaway containment and noise-abatement protocols below 65 dB at 100 meters constrain rotor disk loading. These requirements compress payload-range tradeoffs for urban flight paths.
- Operational Guidelines:Pilot training mandates and vertiport electrification standards lag vehicle certification by 18-24 months. Utility interconnection upgrades for megawatt-scale charging create deployment bottlenecks.
Certification Processes dominate strategic attention, with Operational Guidelines generating the fastest-evolving compliance burden as infrastructure scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports engineering-intensive certification services to UAE fleet operators, while Japan supplies advanced battery management systems to US airframe developers. This trade-flow pattern concentrates development capital in jurisdictions with regulatory clarity.
United States
FAA's powered-lift SFAR accelerates type certification for electric VTOL platforms targeting commercial air taxi deployment. The regulator's streamlined pathway reduces flight-test hour requirements for distributed electric propulsion architectures. California's Silicon Valley hosts Joby Aviation and Archer Aviation flight-test facilities anchoring West Coast certification campaigns.
Germany
EASA's SC-VTOL framework mandates fault-tolerant flight control redundancy exceeding FAA standards, absorbing 15-20% airframe weight penalties. Volocopter GmbH leverages early operational partnerships with Frankfurt and Munich airport authorities to secure urban air taxi concessions. Baden-Württemberg's aerospace cluster supplies composite airframe components to European VTOL developers.
United Arab Emirates
Dubai's RTA corridor designation creates demand visibility anchoring fleet pre-orders from aerial taxi operators. The GCAA urban air mobility operational guidelines shape vertiport electrification standards and pilot training mandates. Abu Dhabi's sovereign wealth vehicles channel infrastructure capital into megawatt-scale charging networks.
Japan
METI's Osaka Expo 2025 demonstration mandate accelerates temporary operational certificates converting to permanent route authority post-event. The regulator prioritizes autonomy threshold relaxations for intra-city medical supply networks. Osaka's Kansai region concentrates battery thermal-management testing facilities serving domestic eVTOL programs.
China
EHang anchors autonomous frame development targeting pilot-elimination economics for dense urban cores. The country's dual carbon goals accelerate electric propulsion adoption while MIIT standards govern distributed motor certification. Shenzhen's Pearl River Delta electronics cluster supplies fly-by-wire control systems to regional airframe integrators.
Global Flying Cars Market Vendor Landscape
Listed leaders compete with private specialists across certification pathway access, creating a tiered structure where public equity financing accelerates flight-test hour accumulation. The vendor base clusters around three strategic archetypes: pure-play eVTOL developers pursuing FAA powered-lift certification, diversified aerospace incumbents leveraging grandfathered airworthiness expertise, and autonomy-first specialists targeting pilot-elimination economics. Dominant competitive moves include strategic partnerships with vertiport operators and technology licensing agreements spanning battery management systems.
Within the pure-play developer tier, Joby Aviation and Archer Aviation exemplify US-focused certification strategies, while Volocopter GmbH anchors European regulatory engagement through EASA SC-VTOL compliance. These three entities represent divergent geographic positioning rather than competing technological approaches, with each occupying a distinct regulatory jurisdiction that fragments global fleet standardization.
| Leading Market Players |
|---|
| Joby Aviation |
| AeroMobil |
| Volocopter GmbH |
| Lilium |
| Archer Aviation |
| EHang |
| PAL-V |
| Airbus |
| Kitty Hawk |
| Others |
Supply Flow & Price Mechanics
Vertiport electrification scale economies concentrate battery procurement leverage among UAE and Saudi fleet operators, compressing cell manufacturer margins while establishing price floors for certified electric VTOL platforms. This dynamic ties supply concentration in cathode precursor refining directly to OEM pricing power across certification tiers.
Pricing Analysis
Next-generation solid-state lithium-metal configurations command 40-50% premiums over current-generation lithium-ion packs, while prior-generation nickel-manganese-cobalt cells face rapid price erosion. Pricing stratifies across FAA-certified premium tiers, EASA fault-tolerant standard tiers, and pre-certified economy tiers awaiting operational approval. Cost compression in economy-tier platforms intensifies as Chinese cell manufacturers flood the spot market. Commercial transport fleet operators exhibit highest price sensitivity, while emergency services buyers prioritize redundancy over unit economics.
Supply Chain Analysis
Inventory lead times for solid-state electrolyte materials stretch 18-24 months, forcing OEMs to pre-commit capacity before certification completion. Supply concentrates in China for cathode precursors, South Korea for separator membranes, and Japan for electrolyte additives. The chain rests on lithium carbonate from Chile and Australia, carbon fiber from Japan and Germany, and rare-earth magnets from China's processing facilities. Single-source vulnerability in lithium refining exposes European and US developers to geopolitical disruption. Distribution runs through RTA-coordinated procurement pools in the UAE, bypassing traditional OEM direct sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks the cyclical recovery pattern of aerospace certification cycles, with FAA powered-lift SFAR implementation serving as the demand inflection driver.
For Market Incumbents: Compound certification reciprocity advantages by accelerating EASA SC-VTOL compliance ahead of competitors, securing multi-jurisdictional deployment rights. Deepen backward integration into battery thermal-management systems to defend margins against cell manufacturer price volatility. Prioritize vertiport operator partnerships in Dubai and Riyadh to lock in corridor access before infrastructure saturation.
For New Entrants and Emerging Players: Anchor in autonomous cargo last-mile applications where pilot-elimination economics bypass the steepest certification barriers. Target Japan's Osaka Expo demonstration window for temporary operational certificates converting to permanent authority. Pursue METI's medical supply network procurement as the most penetrable near-term revenue pool, leveraging pre-certified sub-600kg frames.
For Investors and Strategic Acquirers: Pure-play autonomy software specialists with DO-178C compliance documentation represent the highest-conviction acquisition archetype, given engineering-hour scarcity in fly-by-wire certification. Frame long-term viability around 5-10 year autonomy threshold relaxation timelines rather than near-term passenger transport scale. Monitor FAA-EASA reciprocity agreement announcements as the critical signal for platform standardization inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Reciprocity Investment | FAA-EASA alignment unlocks multi-jurisdictional revenue for tilt-rotor developers. |
| Vertiport Infrastructure Partnership | RTA corridor access in Dubai anchors fleet pre-orders for electric VTOL operators. |
| Battery Supply Agreement | Solid-state lithium-metal offtake contracts secure 150km range envelope leadership. |
| Autonomy Software Licensing | DO-178C compliant fly-by-wire systems reduce OEM engineering-hour burdens. |
| Regional Manufacturing Footprint | Baden-Württemberg composite cluster proximity accelerates EASA SC-VTOL compliance. |
Methodological Framework
Desk research of FAA SFAR documentation, EASA SC-VTOL certification filings, and GCAA urban air mobility guidelines preceded structured interviews with electric VTOL program directors, vertiport infrastructure planners, battery procurement leads at fleet operators, and regulatory affairs specialists at aviation authorities. Secondary validation drew from SEC S-1 filings of listed developers, patent databases for distributed propulsion architectures, and utility interconnection records for megawatt-scale charging projects. Bottom-up platform deployment forecasts triangulated against top-down aerial taxi addressable market estimates.
Variance decomposition across the projection horizon isolates battery energy density improvements, autonomy threshold relaxations, and certification timeline compression as the primary forecast drivers. Segmentation modeling spans propulsion architecture, operational range envelope, pilot-autonomy configuration, and regional regulatory cluster. CAGRs derive from logistic adoption curves fitted to pre-order backlogs and infrastructure investment commitments. Forecast inputs incorporate vertiport electrification lag estimates and solid-state cell commercialization roadmaps.
Decision-makers should treat outputs as directional under assumptions of continued FAA-EASA regulatory convergence and lithium supply chain stability; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Mobility
Air Transport Modifications Market
Air Mobility
Asia Pacific Helicopter Services Market
Air Mobility
North Sea Offshore Helicopter Services Market
Air Mobility
Air Crane Helicopter Market
Air Mobility
China Chartered Air Transport Market
Air Mobility
Hang Glider Market
Air Mobility
Advanced Aerial Mobility Market
Air Mobility
North America Offshore Helicopter Services Market
Air Mobility
Global Aerial Firefighting Market
Air Mobility
Helicopter-Based Transportation Market
Air Mobility
Global Aerodynamics Market
Air Mobility
Middle East and Africa General Aviation Market
Air Mobility
Urban Air Mobility (UAM) Market
Air Mobility
Advanced Air Mobility Market
Air Mobility
Flying Jetpacks Market
Air Mobility
Offshore Helicopter Services Market