
 Helicopter-Based Transportation Market | 2026-2036
Helicopter-Based Transportation Market Size, Share, and Industry Trends Forecast 2026-2036
Helicopter-Based Transportation Market Analysis
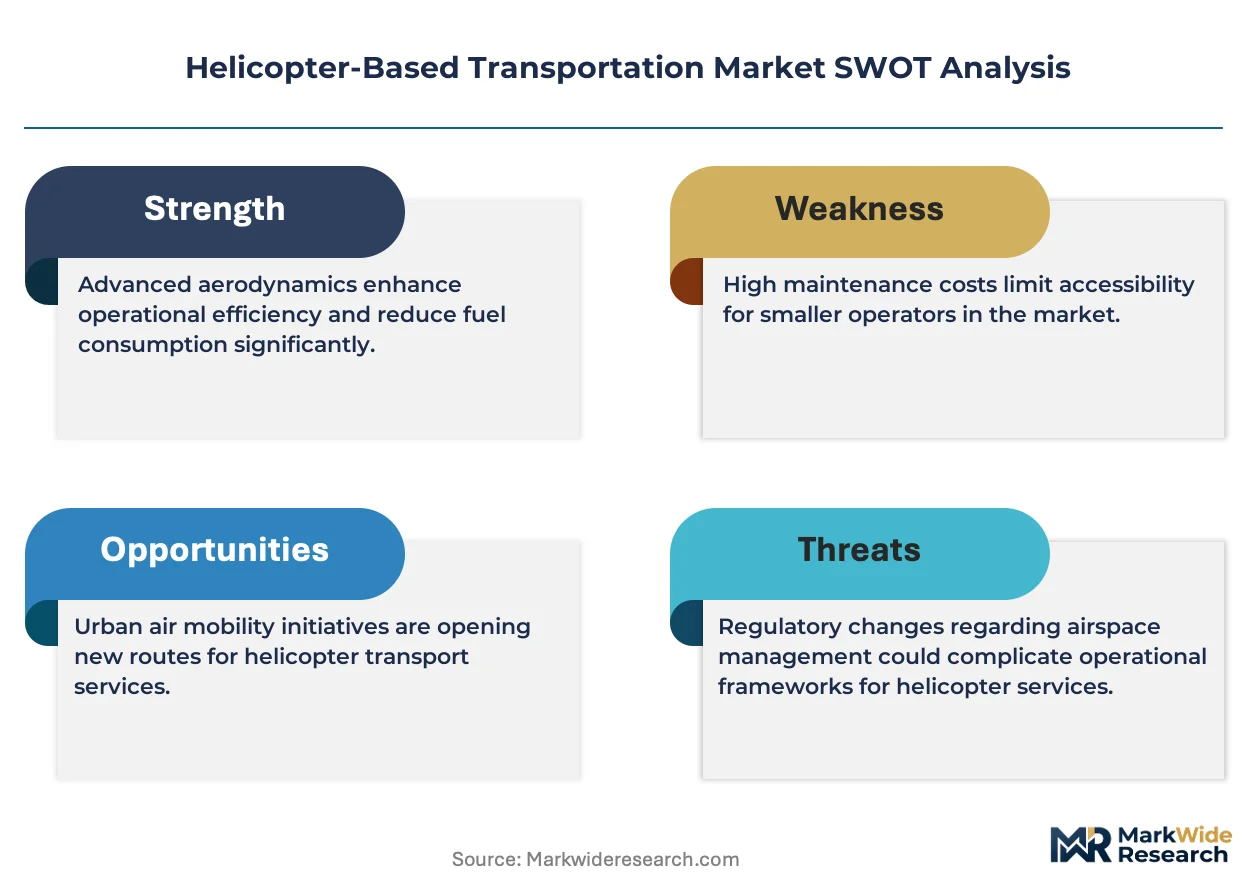
IFR-certified twin-engine specifications are bifurcating the competitive landscape between premium safety-tier operators and legacy single-engine fleets. Bristow Group Inc. leverages its global offshore logistics network to sustain long-term contracts with energy majors. CHC Group LLC anchors its position through specialized SAR and medevac capabilities across harsh-environment basins. PHI, Inc. differentiates via deep vertical integration into pilot training and maintenance infrastructure along the Gulf of Mexico.
Helicopter-based transportation denotes rotary-wing aviation services utilizing turbine or piston-powered vertical-lift aircraft with operational ceilings typically spanning 10,000 to 25,000 feet, designed for point-to-point mobility without fixed runway dependency. Conventional turbine technology dominates current revenue pools due to proven endurance and payload metrics, while electric helicopter prototypes are attracting R&D capital for intra-urban routes under 100 nautical miles. Emergency medical services and offshore transport represent the most structurally entrenched application segments, with charter services exhibiting faster growth trajectory among high-net-worth mobility buyers.
FAA Part 135 operating certificates and EASA Air Operator Certificate standards govern commercial entry, while OSHA offshore worker evacuation rules mandate twin-engine redundancy for Gulf of Mexico energy missions. ICAO Annex 6 provisions on flight data monitoring and EASA's evolving CS-29 certification requirements for larger rotorcraft are tightening compliance thresholds for fleet operators. Stakeholders must weigh capital allocation between conventional fleet modernization and emerging autonomous navigation platforms before regulatory frameworks crystallize for pilot-reduced operations.
Market Dynamics
FAA Part 135 certification upgrades and IFR capability mandates are forcing fleet renewal decisions across North American operators, splitting the competitive landscape between safety-tier premium providers and legacy single-engine fleets.
Growth Catalysts
- Offshore Energy Logistics:Gulf of Mexico crew change missions are driving twin-engine rotary-wing procurement. OSHA offshore evacuation rules mandate redundant powerplants for energy sector contracts.
- EASA CS-29 Certification Evolution:Stricter airworthiness standards for larger rotorcraft are accelerating replacement cycles. Operators pursuing European routes must modernize to maintain Air Operator Certificate validity.
- Urban Air Mobility R&D:Electric vertical-takeoff prototypes under 100 nautical miles are attracting development capital. Battery-electric architectures promise reduced operating costs for intra-urban shuttle services.
Market Restraints
- Aviation Fuel Price Volatility:Jet-A and avgas cost fluctuations compress margins on fixed-rate contracts. Fuel represents 25-35% of direct operating costs for turbine helicopter fleets.
- Pilot Training Pipeline Bottleneck:Certified flight instructor scarcity extends qualification timelines. The FAA's reduced flight hour requirements for military transition pilots have not offset civilian training capacity constraints.
- Airframe OEM Concentration:Airbus Helicopters and Leonardo dominate medium-heavy turbine production. Limited alternative suppliers extend delivery lead times for fleet expansion programs.
Strategic Opportunities
- Emergency Medical Services Expansion:Hospital-based helicopter emergency medical service networks in Texas and Louisiana are adding bases. Trauma center catchment area competition drives dedicated airframe deployment.
- Autonomous Navigation Platforms:Pilot-reduced operation frameworks under ICAO Annex 6 guidance promise labor cost restructuring. Early movers in flight data monitoring integration position for regulatory crystallization.
- Maintenance Infrastructure Captive Supply:In-house production of component overhaul capabilities locks in availability. Gulf Coast operators with owned Part 145 repair stations reduce third-party dependency.
Industry Challenges
- Airframe-Engine Certification Synchronization:Powerplant upgrades require coordinated FAA type certificate amendments. Mismatched approval timelines delay fleet modernization programs.
- Legacy Avionics Integration Complexity:Glass cockpit retrofits on aging airframes encounter wiring harness incompatibility. Analog-to-digital conversion costs often exceed residual airframe value.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Helicopter-Based Transportation Market |
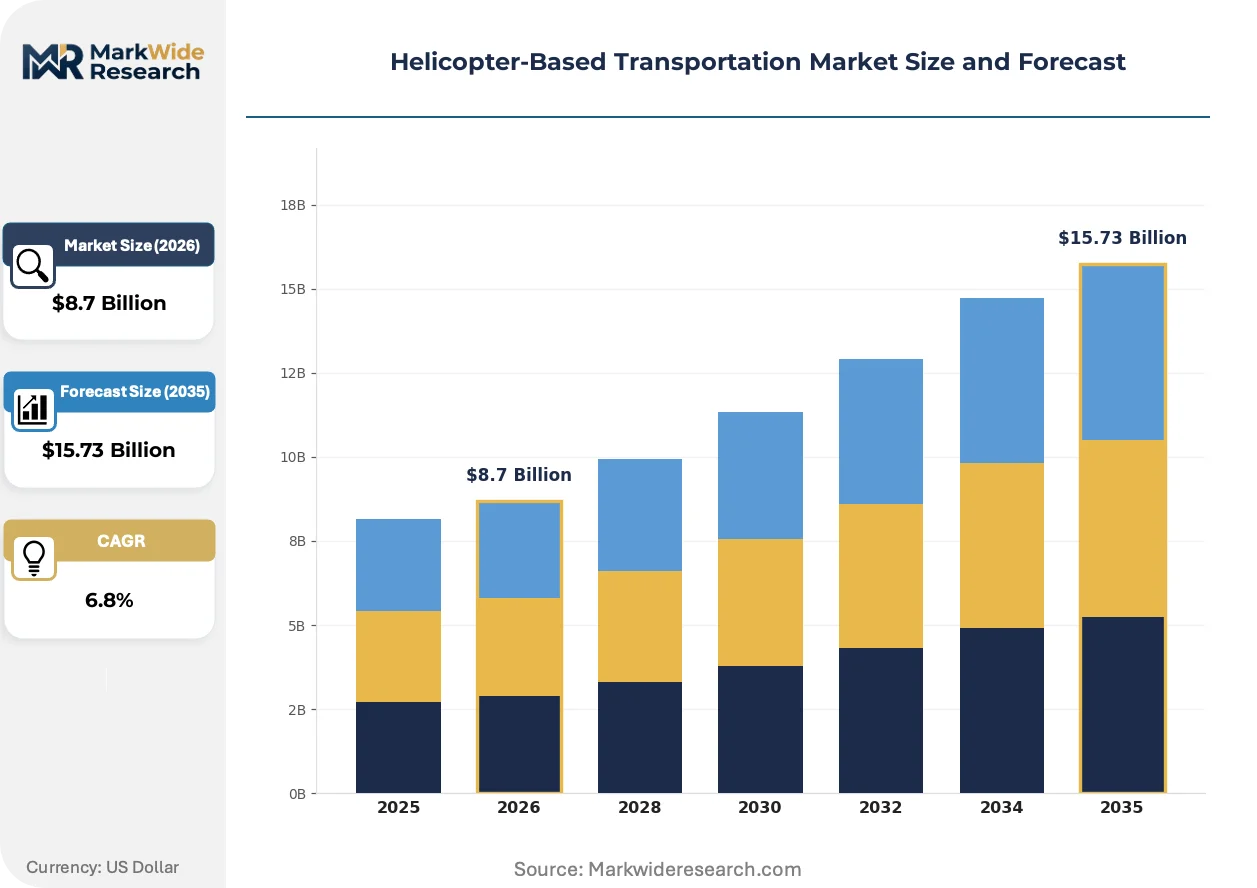
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Charter Services, Emergency Medical Services, Offshore Transport, Tourism Services End User: Government Agencies, Corporate Clients, Private Individuals, Healthcare Providers Service Type: Scheduled Flights, On-Demand Services, Cargo Transport, Aerial Surveying Technology: Electric Helicopters, Conventional Turbine, Hybrid Systems, Autonomous Navigation |
| Companies Covered | Gulf Helicopters Company, Omni Helicopters International, Bristow Group Inc., Babcock International Group PLC, CITIC Offshore Helicopter Co., Ltd., CHC Group LLC, NHV Group, Era Group Inc., PHI, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Helicopter-Based Transportation Market Emerging Trajectories
Rotary-wing aviation is experiencing fundamental capability divergence as conventional turbine endurance confronts electric propulsion economics, while regulatory frameworks simultaneously tighten safety thresholds and open experimental operational categories.
Hybrid-electric propulsion architectures are fragmenting the traditional single-powerplant paradigm. Offshore logistics operators are testing turbine-electric range extenders for reduced fuel burn on long-distance crew change routes. This technology is fragmenting fleet standardization as operators pilot mixed-powerplant configurations before full electrification commitment.
EASA's evolving CS-29 certification requirements for larger rotorcraft are compressing design flexibility for new market entrants. Airframe manufacturers must demonstrate enhanced crashworthiness and systems redundancy. The offshore oil and gas segment in the North Sea is responding with accelerated lease-versus-buy analysis to transfer certification risk.
Search-and-rescue agencies are consolidating procurement under multi-mission framework agreements. Traditional single-service contracts for medevac or offshore transport are yielding to bundled emergency response mandates. Norway's Joint Rescue Coordination Centre exemplifies this shift, requiring operators to demonstrate cross-certified pilot pools and interchangeable airframe configurations.
Helicopter-Based Transportation Market Segmentation
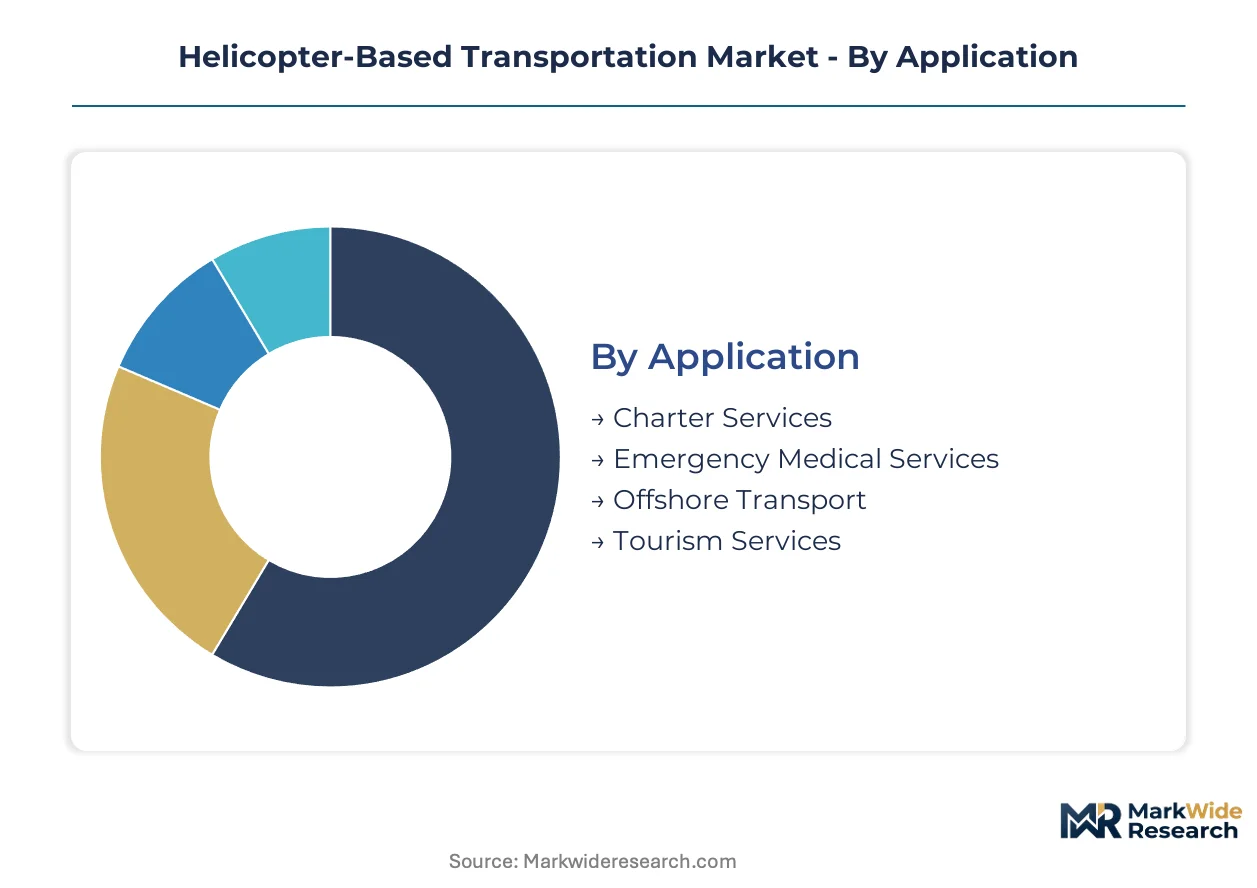
Segmentation in rotary-wing aviation reveals how mission profiles dictate equipment specifications, certification requirements, and pricing power. Each dimension—application, end user, service model, and propulsion technology—carries distinct margin structures and regulatory burdens that reshape operator strategy.
Application:
Substitution pressure from fixed-wing alternatives and ground transport varies sharply across mission types, with some segments facing imminent disruption while others remain structurally protected.
- Offshore Transport:Twin-engine turbine configurations dominate crew change logistics to energy platforms. OSHA evacuation mandates in the United States Gulf Coast corridor lock in rotary-wing dependency despite high operating costs.
- Emergency Medical Services:Hospital-based helicopter emergency networks require IFR-certified airframes with specialized medical interiors. Trauma center catchment competition in Texas and Louisiana drives dedicated base deployment.
- Charter Services:High-net-worth mobility buyers seek point-to-point flexibility without fixed runway dependency.
- Tourism Services:Scenic flight operators concentrate around natural attractions with restricted ground access.
Offshore Transport retains volume leadership; Charter Services holds the steepest expansion curve among application segments.
End User:
Procurement authority and contract duration diverge significantly across customer types, with some buyers optimizing for unit economics while others prioritize mission assurance over cost.
- Corporate Clients:Energy majors and infrastructure operators negotiate multi-year framework agreements with penalty clauses for availability shortfalls. Gulf of Mexico logistics contracts typically span 3-5 years with fuel adjustment mechanisms.
- Government Agencies:Search-and-rescue and law enforcement procurement consolidates under multi-mission mandates. Norway's Joint Rescue Coordination Centre exemplifies bundled emergency response contracting.
- Healthcare Providers:Hospital systems operate dedicated airframes or contract with regional air ambulance networks.
- Private Individuals:Wealthy travelers purchase block hours or membership programs for on-demand access.
Corporate Clients anchor contract value; Government Agencies are climbing the fastest as procurement frameworks consolidate.
Service Type:
Operational model selection determines fleet utilization rates, pilot scheduling complexity, and the viability of autonomous technology insertion.
- On-Demand Services:Ad-hoc charter and medevac dispatch require flexible crew rotations and rapid response positioning. United States Gulf Coast operators maintain forward-staged aircraft near Houston and New Orleans.
- Scheduled Flights:Recurring crew change routes to offshore platforms enable predictable block hour utilization. Fixed schedules support higher aircraft productivity versus ad-hoc dispatch.
- Cargo Transport:External load and internal freight missions serve remote construction and logistics needs.
- Aerial Surveying:Pipeline inspection and geophysical mapping demand specialized sensor integration.
On-Demand Services command premium pricing; Scheduled Flights are gaining share fastest through energy sector contract renewal.
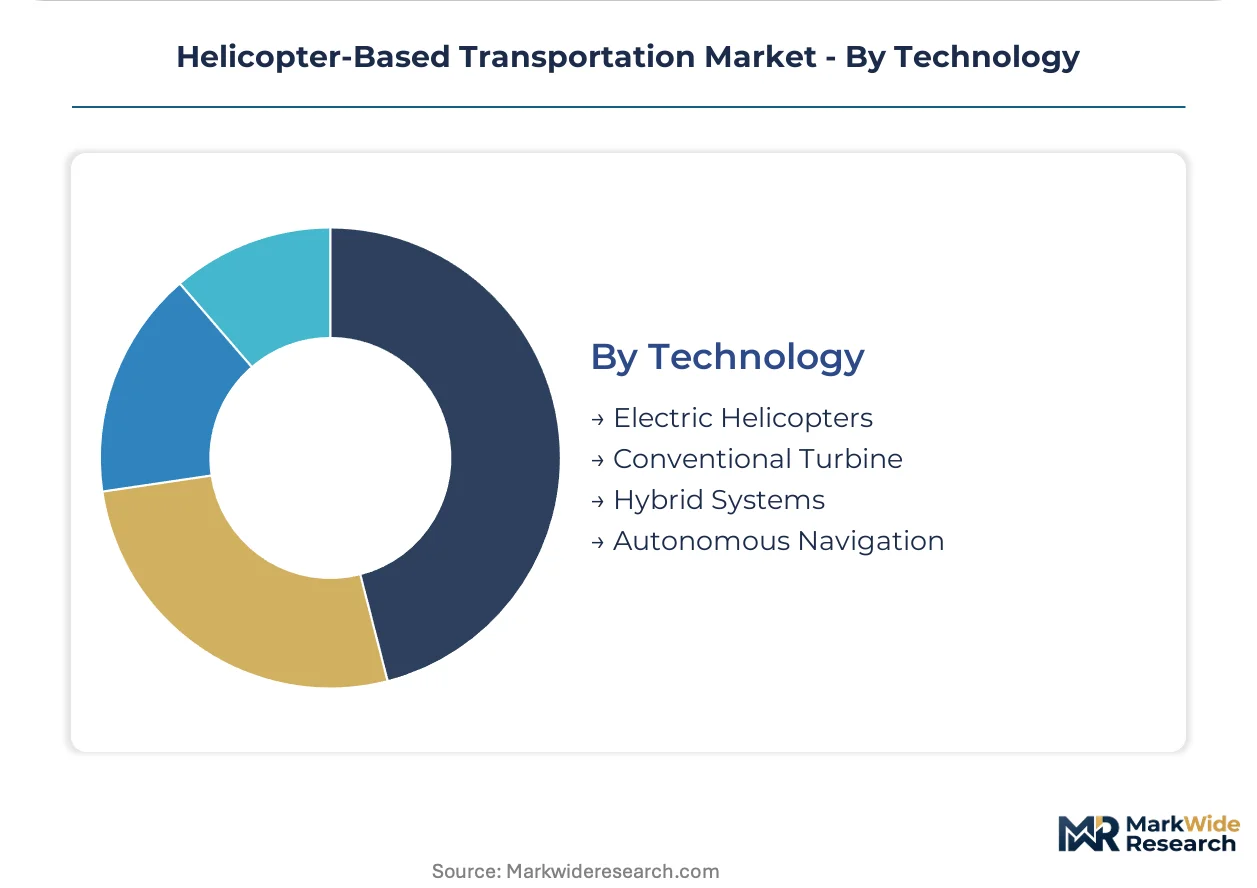
Technology:
Propulsion architecture choices fragment the competitive landscape as operators weigh proven endurance against emerging cost structures and regulatory positioning.
- Conventional Turbine:Proven endurance and payload metrics sustain dominance in offshore and heavy-lift missions. Jet-A fuel availability and maintenance infrastructure maturity reinforce incumbent position.
- Hybrid Systems:Turbine-electric range extenders are piloting on long-distance crew change routes for reduced fuel burn. Mixed-powerplant configurations test operational viability before full electrification commitment.
- Electric Helicopters:Battery-electric prototypes target intra-urban routes under 100 nautical miles with reduced operating cost profiles.
- Autonomous Navigation:Pilot-reduced operation frameworks under ICAO Annex 6 guidance promise labor cost restructuring for cargo and survey missions.
Conventional Turbine retains volume leadership; Hybrid Systems hold the steepest expansion curve as operators trial mixed configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in rotary-wing aviation favor net-importing jurisdictions with mature offshore energy infrastructure, while manufacturing concentration in France and Germany shapes fleet renewal patterns across import-dependent markets.
United States
Gulf of Mexico crew change missions and emergency medical networks drive turbine helicopter procurement. FAA Part 135 certification upgrades and IFR capability mandates force fleet modernization decisions. The Houston-to-New Orleans corridor concentrates offshore logistics operators under OSHA twin-engine redundancy rules.
Norway
North Sea oil platform access and search-and-rescue consolidation underpin rotary-wing demand. EASA CS-29 certification evolution accelerates replacement cycles for larger rotorcraft. Stavanger and Bergen anchor bundled emergency response contracting under the Joint Rescue Coordination Centre framework.
United Kingdom
Offshore energy logistics and multi-mission government procurement sustain turbine helicopter utilization. EASA Air Operator Certificate standards govern commercial entry for North Sea routes. Aberdeen serves as the primary hub for crew change missions to continental shelf platforms.
Brazil
Pre-salt basin development and coastal logistics networks expand rotary-wing service requirements. ANAC certification aligns with ICAO Annex 6 flight data monitoring provisions. Rio de Janeiro and Macaé cluster offshore operators serving Petrobras-contracted production facilities.
United Arab Emirates
Luxury charter demand and energy sector logistics support premium helicopter services. GCAA regulations incorporate EASA-equivalent airworthiness standards for commercial operations. Dubai and Abu Dhabi concentrate high-net-worth mobility buyers and offshore support contracts.
Helicopter-Based Transportation Market Vendor Landscape
Concentration sits with integrated offshore logistics specialists holding multi-year energy contracts. Three to five operators control framework agreements across major basins, while regional specialists fragment ad-hoc charter and emergency medical segments. Strategic archetypes split between safety-tier premium providers with IFR-certified twin-engine fleets and legacy single-engine operators facing renewal pressure. Competitive moves center on fleet standardization around common airframe types and backward integration into maintenance infrastructure.
Among North American offshore specialists, Bristow Group Inc., CHC Group LLC, and PHI, Inc. exemplify the integrated logistics archetype. Bristow represents the global network model spanning multiple energy basins. CHC occupies a position anchored in search-and-rescue and harsh-environment capabilities. PHI sits within the vertical integration tier through captive pilot training and Part 145 repair station ownership along the Gulf Coast.
| Leading Market Players |
|---|
| Gulf Helicopters Company |
| Omni Helicopters International |
| Bristow Group Inc. |
| Babcock International Group PLC |
| CITIC Offshore Helicopter Co., Ltd. |
| CHC Group LLC |
| NHV Group |
| Era Group Inc. |
| PHI, Inc. |
| Others |
Supply Flow & Price Mechanics
Hybrid-electric propulsion trials are displacing conventional turbine specifications on select crew change routes, simultaneously fragmenting supplier geography toward battery-cell manufacturing clusters and compressing fuel-cost pass-through premiums in contract bidding.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across Gulf of Mexico energy logistics. Three-tier pricing structure across IFR-certified twin-engine, single-engine IFR, and VFR-only tiers reflects FAA Part 135 certification grade and OSHA compliance status. Cost compression in legacy single-engine segments is intensifying because energy majors are mandating twin-engine redundancy for new awards. Corporate energy clients show lowest price sensitivity due to operational risk transfer requirements, while ad-hoc charter buyers exhibit highest elasticity.
Supply Chain Analysis
Port congestion at Houston and New Orleans elevates inbound logistics costs for airframe components and engine modules arriving from France, Germany, and Italy. Airbus Helicopters and Leonardo production draws from specialized titanium forging suppliers in Germany and avionics integration facilities in France. Single-source vulnerability concentrates in medium-heavy turbine engine supply from Safran and Pratt & Whitney Canada. Distribution runs through OEM-authorized service centers and operator-owned Part 145 repair stations along the Gulf Coast corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Helicopter-based transportation is entering a cyclical recovery phase as offshore energy capital expenditure resumes following upstream investment contraction. Fleet renewal mandates tied to IFR certification upgrades provide the cyclical impetus.
For Market Incumbents: Shield long-term contract portfolios from rate erosion by accelerating captive maintenance infrastructure deployment along the Houston-New Orleans corridor. Lock in airframe availability through forward-positioned Part 145 repair stations before OEM delivery queues extend. Retrofit legacy fleets with glass cockpit architectures to defer full replacement capital outlay while satisfying FAA operational requirements.
For New Entrants and Emerging Players: Electric vertical-takeoff service gaps in intra-urban shuttle routes under 100 nautical miles present white-space opportunities where incumbents under-serve. Target hospital-based emergency medical networks in Texas and Louisiana trauma corridors lacking dedicated IFR-certified airframes. Pursue partnership structures with energy sector subcontractors seeking tier-two supplier status under major framework agreements.
For Investors and Strategic Acquirers: EASA CS-29 certification evolution reshapes the acquisition landscape toward operators with modernized larger-rotorcraft fleets and European Air Operator Certificate validity. Five-to-ten year viability favors integrated logistics specialists holding multi-year energy contracts with fuel-adjustment mechanisms. Monitor FAA pilot-reduced operation rulemaking as the signal indicating autonomous technology inflection timing.
| Strategic Initiative | Industry Significance |
|---|---|
| IFR Certification Investment | FAA Part 135 compliance secures access to Gulf of Mexico energy contracts requiring instrument flight rules capability. |
| Hybrid-Electric Fleet Pilot | Turbine-electric range extenders test operational viability on long-distance crew change routes before full electrification commitment. |
| Part 145 Repair Station Acquisition | Captive maintenance infrastructure locks in component availability and reduces third-party dependency for fleet operators. |
| Multi-Mission Framework Bidding | Bundled search-and-rescue and medevac contracts consolidate procurement under Norway's Joint Rescue Coordination Centre model. |
| Pilot Training Pipeline Investment | In-house flight instruction capacity addresses certified flight instructor scarcity extending civilian qualification timelines. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FAA certification databases, EASA airworthiness directives, and offshore energy contract registries. Interviews with rotary-wing fleet managers, Part 135 certificate holders, oil and gas logistics procurement leads, and helicopter OEM regional sales directors informed operational assumptions. Secondary validation drew from OSHA offshore evacuation rule filings, ICAO Annex 6 guidance documents, and energy sector framework agreement disclosures. Bottom-up airframe deployment counts triangulate against top-down energy sector flight hour estimates.
Segmentation dimensions modeled span application type, end-user procurement authority, service delivery model, and propulsion technology architecture across the projection horizon. Conventional turbine, hybrid-electric, and battery-electric configurations receive distinct utilization and cost assumptions. CAGRs derive from fleet replacement cycle analysis tied to regulatory mandate timelines and energy sector capital expenditure patterns. Offshore platform count trajectories and trauma center catchment expansion rates provide helicopter-specific forecast inputs.
Forecasts assume regulatory continuity in FAA Part 135 and EASA CS-29 regimes; material policy shifts would require re-modeling. Battery-electric certification pathways, autonomous navigation rulemaking, and upstream oil and gas investment volatility represent specific revision risks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Mobility
Middle-East and Africa Military Aviation Market
Air Mobility
Flying Taxi Market
Air Mobility
Flying Jetpacks Market
Air Mobility
Global Aerial Firefighting Market
Air Mobility
China Chartered Air Transport Market
Air Mobility
Asia-Pacific Charter Jet Service Market
Air Mobility
Asia-Pacific Military Aviation Market
Air Mobility
Offshore Helicopter Services Market
Air Mobility
Asia Pacific Helicopter Services Market
Air Mobility
Urban Air Mobility (UAM) Market
Air Mobility
Air Transport Modifications Market
Air Mobility
Air Crane Helicopter Market
Air Mobility
Middle East and Africa General Aviation Market
Air Mobility
Advanced Air Mobility Market
Air Mobility
Hang Glider Market
Air Mobility
North America Offshore Helicopter Services Market