
 Aircraft Micro Turbine Engine Market | 2026-2036
Aircraft Micro Turbine Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Micro Turbine Engine Market Analysis
The aftermarket parts channel is rewriting how micro turbine engine manufacturers reach fleet operators. Williams International Co. leverages captive repair networks to sustain aftermarket revenue across its installed base of small turbofan powerplants. Honeywell International Inc. anchors its position through integrated auxiliary power unit portfolios that span commercial and military platforms. Turbotech SARL competes on regenerative cycle technology leadership, offering efficiency advantages in the light aircraft segment.
Aircraft micro turbine engines are compact gas turbine powerplants typically producing thrust or shaft power below 1,000 horsepower, utilizing centrifugal compressors and single-stage turbines machined from nickel-based superalloys for thermal tolerance. These systems serve as primary propulsion for unmanned aerial vehicles, auxiliary power units for larger aircraft, and range-extender generators in hybrid-electric architectures. Turbofan configurations command the largest product type position due to their noise and fuel efficiency advantages in manned general aviation applications. The UAV end user category registers the fastest structural expansion, driven by defense procurement and commercial inspection missions requiring extended endurance. Hybrid technology architectures attract concentrated engineering investment as manufacturers integrate micro turbines with battery-electric systems for propulsion.
FAA Part 33 airworthiness standards govern type certification of small turbine engines in the United States, dictating design validation, endurance testing, and emissions thresholds that shape product development timelines. EPA aircraft engine emission regulations under 40 CFR Part 87 impose nitrogen oxide and hydrocarbon limits that influence combustor design choices and fuel system architecture. EASA CS-E certification requirements in Europe establish parallel conformity pathways for manufacturers seeking dual-continent market access. Stakeholders must monitor evolving sustainable aviation fuel compatibility mandates across FAA, EASA, and CAAC jurisdictions to align product roadmaps with regulatory trajectories.
Market Dynamics
Regenerative cycle architectures are compressing thermal efficiency gaps between micro turbines and piston engines, forcing incumbents to accelerate R&D timelines or cede light aircraft propulsion contracts to specialized European challengers.
Growth Catalysts
- Defense UAV procurement:Military unmanned platforms in the United States and Israel are specifying micro turbine endurance modules for missions exceeding 24 hours, creating dedicated production lines at specialized suppliers.
- FAA Part 33 certification pathways:Streamlined type certification procedures for engines below 1,000 shaft horsepower are reducing validation timelines for new market entrants.
- Hybrid-electric architecture convergence:Battery pack integration with micro turbine range extenders is opening air taxi and urban mobility segments previously inaccessible to pure turbine solutions.
Market Restraints
- Nickel superalloy supply concentration:Precision casting capacity for high-temperature turbine components clusters in a handful of specialized foundries, creating single-source vulnerability for critical rotating hardware.
- EPA 40 CFR Part 87 compliance costs:Nitrogen oxide and hydrocarbon emission thresholds for small turbine engines are forcing expensive combustor redesigns that disproportionately burden sub-500 horsepower product lines.
- Piston engine substitution:Advanced diesel aero-engines from Thielert and Austro Engine are capturing price-sensitive general aviation retrofit demand that micro turbines cannot match on fuel burn economics.
Strategic Opportunities
- Indian defense modernization:The country's unmanned aerial vehicle procurement programs under Make in India initiatives are creating localized assembly opportunities for foreign turbine manufacturers willing to establish joint ventures.
- Sustainable aviation fuel mandates:European Union Green Deal compatibility requirements are favoring turbine architectures with demonstrated multi-fuel capability over piston alternatives locked to avgas formulations.
- Direct-to-fleet digital channels:Predictive maintenance platforms are enabling manufacturers to bypass traditional distributor networks and capture aftermarket parts margins previously allocated to regional service centers.
Industry Challenges
- Aero-thermodynamics specialist scarcity:Experienced combustion engineers capable of optimizing small-scale annular combustors command premium compensation and limited geographic mobility, constraining product development velocity.
- EASA CS-E dual certification timelines:Parallel validation requirements for European market access are extending time-to-revenue by 18-24 months for US-centric manufacturers lacking established notified body relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Micro Turbine Engine Market |
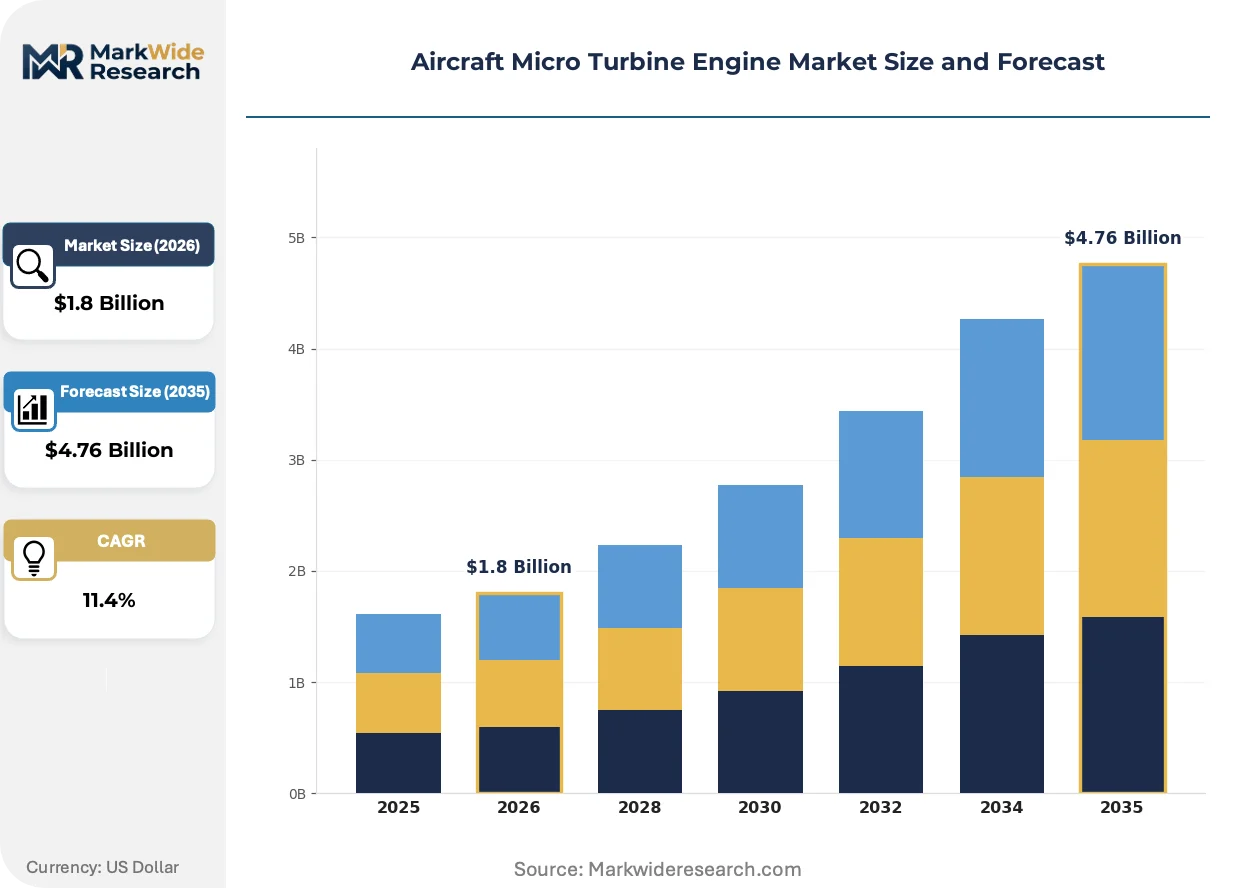
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Turbojet, Turbofan, Turboprop, Auxiliary Power Unit End User: Commercial Aviation, Military Aviation, UAVs, General Aviation Application: Power Generation, Propulsion, Auxiliary Services, Research Technology: Hybrid, Electric, Conventional, Advanced Fuel |
| Companies Covered | Williams International Co., Bladon Jets Limited, Honeywell International Inc., Turbotech SARL, JetCat GmbH, Safran Helicopter Engines, Advanced Microturbine Technology B.V., Kratos Defense & Security Solutions, Inc., Collins Aerospace Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Micro Turbine Engine Market Emerging Trajectories
Additive manufacturing of nickel superalloy turbine wheels is collapsing lead times for complex cooling geometries, enabling rapid iteration cycles that were previously uneconomical at micro turbine production volumes.
Directed energy deposition techniques are rendering obsolete conventional five-axis machining for impeller fabrication, allowing Honeywell and Williams International to prototype centrifugal compressor stages in weeks rather than months. Defense contractors evaluating propulsion options for next-generation loitering munitions are specifying additively manufactured hot-section components as baseline requirements, compressing supplier qualification windows and favoring in-house metallurgy capabilities over outsourced casting.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluorocarbon refrigerant displacement in aircraft environmental control systems, indirectly pressuring micro turbine auxiliary power unit manufacturers to redesign bleed air architectures. The regulation's industrial consequence is a forced migration toward electrically driven vapor compression cycles that reduce turbine load profiles and extend maintenance intervals. European regional jet operators are demanding APU specifications that demonstrate F-Gas compliance through 2040, filtering supplier selection toward integrated system architects with environmental control expertise.
Aftermarket service unbundling is fragmenting traditional power-by-the-hour contracts into component-level subscription tiers, with fleet operators in Arizona and Florida test corridors negotiating separate agreements for hot-section refurbishment, line-replaceable unit logistics, and digital health monitoring. This procurement model evolution is compressing margins for full-service incumbents while creating entry points for specialized MRO providers with narrow technical competencies. The shift is most visible among US-based general aviation charter operators managing mixed turbine-piston fleets who prioritize cash-flow predictability over integrated warranty coverage.
Aircraft Micro Turbine Engine Market Segmentation
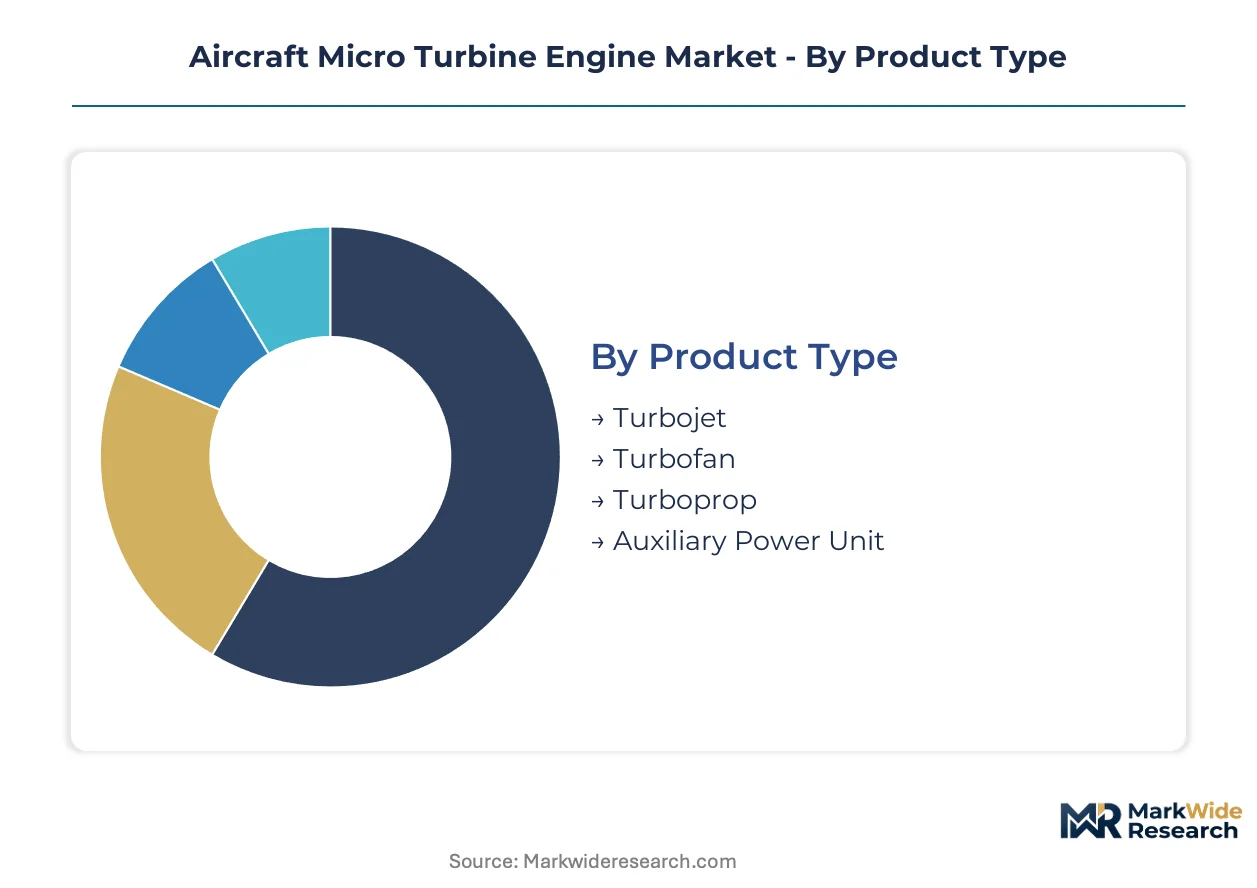
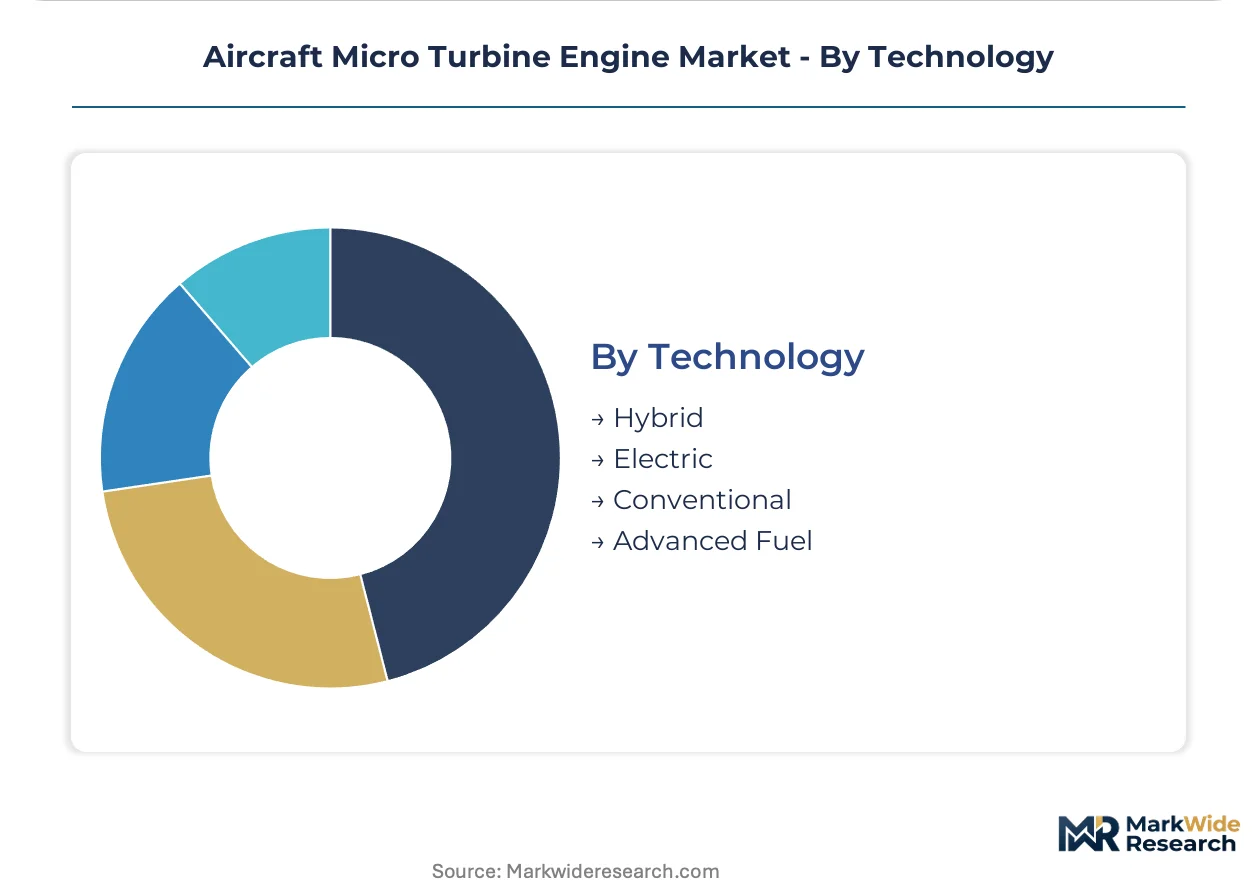
Segmentation in the aircraft micro turbine engine market reveals how propulsion architectures, mission profiles, and energy systems fragment demand across divergent certification requirements and operational envelopes. Understanding these divisions exposes where R&D investment concentrates and where procurement budgets flow.
Product Type:
Mature turbofan configurations dominate general aviation while emerging regenerative cycles challenge thermal efficiency assumptions.
- Turbojet:Single-spool designs with axial or centrifugal compressors deliver thrust-to-weight ratios exceeding 4:1 for high-speed unmanned platforms. Demand clusters in Israeli and US defense loitering munitions programs where compact packaging outweighs fuel economy.
- Turbofan:Bypass configurations with geared or direct-drive fans suppress noise signatures below 75 dB at 500 meters, enabling manned general aviation operations near noise-sensitive communities. FAA Part 36 Stage 5 compliance drives selection for single-pilot business aircraft retrofit programs in Arizona and Florida corridors.
- Turboprop:Free-turbine architectures with reduction gearboxes convert gas generator output to shaft power for 400-800 horsepower applications. Agricultural and surveillance operators in Australia's Outback favor turboprop reliability over piston alternatives for high-cycle dispatch.
- Auxiliary Power Unit:Self-contained turbine modules provide bleed air and electrical power for main engine starting and cabin environmental control. Regional jet manufacturers specify APUs with 90 kVA electrical output to support glass cockpit avionics suites.
Turbofan configurations handle the majority of throughput; regenerative turboprop architectures are expanding most quickly on share.
End User:
Defense procurement channels operate on cost-plus contracting while commercial operators prioritize total cost of ownership metrics.
- Commercial Aviation:Regional airlines and corporate fleets specify micro turbine APUs for 50-100 seat aircraft where main engine bleed extraction proves inefficient. EASA CS-25 certification pathways for supplemental type certificates extend retrofit timelines.
- Military Aviation:Armed forces procurement offices in the United States, Israel, and India issue firm-fixed-price contracts for unmanned platform propulsion with 10,000-hour mean time between overhauls. Foreign military sales agreements require offset manufacturing commitments.
- UAVs:Tactical and strategic unmanned systems spanning Group 3-5 weight classes demand endurance modules sustaining 24-40 hour missions. Hybrid-electric architectures with turbine range extenders capture development funding for next-generation medium-altitude long-endurance programs.
- General Aviation:Owner-flown aircraft and charter operators evaluate turbofan retrofits against advanced diesel piston alternatives for 4-6 seat airframes. Avgas availability constraints at remote airfields tilt preference toward Jet-A compatible turbine solutions.
UAV end-use categories capture the steepest expansion trajectory; commercial aviation maintains the largest installed base requiring aftermarket support.
Application:
Primary propulsion systems command premium pricing while auxiliary services compete on reliability metrics and dispatch availability.
- Power Generation:Ground-based mobile turbine generators deliver 30-150 kW for forward operating base electrical requirements. US Marine Corps expeditionary energy programs specify multi-fuel capability across diesel, JP-8, and sustainable aviation fuel formulations.
- Propulsion:Thrust-producing installations for manned and unmanned aircraft require FAA Part 33 or EASA CS-E type certification with full envelope flight testing. Noise and emissions compliance drives combustor redesign cycles extending development schedules.
- Auxiliary Services:Bleed air-driven environmental control systems and hydraulic pumps reduce main engine parasitic losses. EU F-Gas Regulation phase-down schedules force migration toward electrically driven vapor compression cycles.
- Research:University and government laboratory test cells utilize micro turbines for hypersonic inlet research and combustion instability studies. NASA Glenn Research Center operates multiple test stands for small turbine aerodynamic validation.
Propulsion applications absorb the dominant share of manufacturer engineering resources; power generation for expeditionary military use is climbing the fastest.
Technology:
Conventional thermodynamic cycles retain certification advantages while hybrid architectures attract venture capital for urban air mobility platforms.
- Hybrid:Battery-turbine integrated systems enable electric vertical takeoff and landing aircraft with turbine range extension for mission segments exceeding battery endurance. Joby Aviation and Archer Aviation specifications drive demand for 500 kW-class turbine generators.
- Electric:All-electric propulsion eliminates turbine components entirely for short-range urban missions under 100 nautical miles. Battery energy density limitations constrain adoption to air taxi segments with ground-based rapid charging infrastructure.
- Conventional:Brayton cycle turbines with single-spool or two-spool configurations utilizing nickel superalloy hot sections dominate certified aircraft propulsion. Decades of operational data support residual value calculations for financing institutions.
- Advanced Fuel:Combustor designs optimized for 100% sustainable aviation fuel or hydrogen blends address EU Green Deal and ICAO Carbon Offsetting and Reduction Scheme mandates. Multi-fuel capability requires variable geometry fuel injection and modified control algorithms.
Conventional technology retains the majority of installed fleet hours; hybrid architectures are gaining share fastest as air taxi programs advance toward type certification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States manufacturers command pricing premiums against European competitors due to streamlined FAA Part 33 certification pathways and concentrated defense procurement budgets. Israeli and Indian markets extract value through technology transfer requirements and localized assembly mandates.
United States
Defense UAV procurement programs and general aviation retrofit demand concentrate around Arizona and Florida test corridors. FAA Part 33 certification requirements for small turbine engines below 1,000 shaft horsepower reduce validation timelines for domestic manufacturers. Williams International and Honeywell anchor production networks in Michigan and Arizona, supplying turbofan powerplants for manned and unmanned platforms.
Israel
Military loitering munitions programs specify micro turbine endurance modules for missions exceeding 24 hours. The country's national defense procurement office issues firm-fixed-price contracts with 10,000-hour mean time between overhaul requirements. Israeli defense contractors cluster around Tel Aviv and Haifa, driving dedicated production lines at specialized turbine suppliers.
India
Make in India initiatives for unmanned aerial vehicle procurement create localized assembly opportunities for foreign manufacturers establishing joint ventures. The Directorate General of Foreign Trade mandates offset manufacturing commitments under foreign military sales agreements. Defense modernization programs concentrate in Bangalore and Hyderabad, where HAL and private sector partners evaluate turbine range-extender modules.
Germany
JetCat GmbH anchors European micro turbine production for model aircraft and tactical UAV applications. EASA CS-E certification requirements establish parallel conformity pathways for manufacturers seeking dual-continent market access. Precision engineering clusters in Bavaria and Baden-Württemberg support centrifugal compressor fabrication and single-stage turbine machining.
France
Turbotech SARL competes on regenerative cycle technology leadership for light aircraft propulsion. EU F-Gas Regulation phase-down schedules pressure auxiliary power unit manufacturers to redesign bleed air architectures toward electrically driven vapor compression cycles. Aerospace research concentrates in Toulouse and Paris-Saclay, where Turbotech develops efficiency-optimized turboprop configurations.
Aircraft Micro Turbine Engine Market Vendor Landscape
Integrated system architects and specialized cycle technology developers split the market between full-service portfolios and narrow technical competencies. The vendor base concentrates among incumbent aerospace conglomerates with captive repair networks and European challengers exploiting regenerative thermodynamic advantages. Three strategic archetypes dominate: defense-anchored suppliers with foreign military sales relationships, commercial aviation incumbents leveraging auxiliary power unit integration, and technology specialists pursuing hybrid-electric architecture convergence. Competitive moves center on additive manufacturing qualification for nickel superalloy hot-section components and predictive maintenance platform deployment to capture aftermarket parts margins.
Within the defense-anchored tier, Kratos Defense & Security Solutions, Inc. and Safran Helicopter Engines exemplify contrasting geographic origins and structural approaches. Kratos represents US-based public company positioning toward unmanned platform propulsion, while Safran occupies a position as French S.A.-format aerospace conglomerate with helicopter engine heritage. Among technology specialists, Turbotech SARL anchors French regenerative cycle development, and JetCat GmbH exemplifies German GmbH-format precision engineering for small-scale turbine applications.
| Leading Market Players |
|---|
| Williams International Co. |
| Bladon Jets Limited |
| Honeywell International Inc. |
| Turbotech SARL |
| JetCat GmbH |
| Safran Helicopter Engines |
| Advanced Microturbine Technology B.V. |
| Kratos Defense & Security Solutions, Inc. |
| Collins Aerospace Inc. |
| Others |
Supply Flow & Price Mechanics
Precision casting capacity for nickel-based superalloy turbine wheels clusters in specialized foundries across the United States, Germany, and Japan, concentrating margin pools downstream with OEMs possessing captive metallurgy capabilities or long-term offtake agreements with these single-source suppliers.
Pricing Analysis
Configured-to-order pricing for FAA Part 33 certified turbofan configurations commands substantial premiums over standard auxiliary power unit modules, with price differentiation driven by certification grade and customization level for specific airframe integration. Three-tier pricing structure across premium, standard, and economy levels stratifies around hot-section material specifications and mean time between overhaul guarantees. Cost compression in sub-500 horsepower product lines is intensifying because EPA 40 CFR Part 87 compliance redesigns disproportionately burden smaller displacement engines. General aviation charter operators managing mixed fleets exhibit the highest price sensitivity, while defense procurement offices prioritize performance guarantees over unit economics.
Supply Chain Analysis
Upstream feedstock for nickel superalloy castings draws from primary nickel producers in Indonesia, Russia, and Canada, with secondary refining and vacuum induction melting concentrated in the United States, Germany, and Japan. Critical dependencies span cobalt for high-temperature creep resistance, rhenium for single-crystal turbine blade coatings, and specialized ceramic cores for internal cooling geometry fabrication. Single-source vulnerability for precision investment casting capacity represents the dominant structural risk, with qualified suppliers numbering fewer than ten globally for flight-critical rotating components. Distribution runs through captive repair networks at major OEMs and authorized service centers clustered around Arizona and Florida test corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: FAA Part 33 and EASA CS-E certification timelines create 18-24 month barriers that insulate validated incumbents from rapid competitive displacement.
For Market Incumbents: Harden aftermarket parts channel control by deploying predictive maintenance platforms that bypass traditional distributor networks and capture margins previously allocated to regional service centers. Deepen upstream control over nickel superalloy precision casting capacity through exclusive offtake agreements or qualified second-source development, as single-source vulnerability for hot-section components threatens production continuity. Accelerate additive manufacturing qualification for turbine wheels to compress prototyping cycles and defend against European regenerative cycle challengers. For New Entrants and Emerging Players: Build out hybrid-electric architecture capabilities for urban air mobility platforms where battery-turbine integration specifications remain unsettled and venture capital funding flows toward air taxi development. Target Indian defense modernization programs under Make in India initiatives, where localized assembly requirements and offset manufacturing commitments create entry points for foreign manufacturers willing to establish joint ventures with HAL or private sector partners. Lead with multi-fuel combustor demonstrations to differentiate against piston alternatives locked to avgas formulations. For Investors and Strategic Acquirers: Capital is best deployed toward technology specialists with demonstrated regenerative cycle expertise or additive manufacturing capabilities for nickel superalloy hot-section components, as these competencies command scarcity premiums across the projection horizon. Long-term viability favors integrated system architects over narrow component suppliers, given the convergence of auxiliary power unit and environmental control system specifications under EU F-Gas Regulation phase-down schedules. Watch for inflection signals in sustainable aviation fuel mandate acceleration across FAA, EASA, and CAAC jurisdictions, which would revalue multi-fuel capable turbine architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Additive Manufacturing Qualification | Collapses lead times for nickel superalloy turbine wheels and compresses supplier qualification windows for defense contractors. |
| Predictive Maintenance Platform Deployment | Enables manufacturers to capture aftermarket parts margins previously allocated to regional distributor networks. |
| Multi-Fuel Combustor Development | Addresses EU Green Deal compatibility requirements and ICAO Carbon Offsetting mandates favoring Jet-A alternatives. |
| Joint Venture Localization | Satisfies Indian DGFT offset manufacturing commitments under foreign military sales agreements for UAV programs. |
| Regenerative Cycle Patent Portfolio | Secures efficiency advantages in light aircraft propulsion against conventional Brayton cycle incumbents. |
Methodological Framework
Desk research of FAA type certification databases, EASA CS-E conformity documentation, and defense procurement contract filings preceded structured interviews with propulsion system engineers at unmanned platform manufacturers, aftermarket service directors at general aviation charter operators, procurement leads at regional jet OEMs, and metallurgy specialists at precision investment casting foundries. Secondary validation drew from EPA 40 CFR Part 87 emission compliance records, EU F-Gas Regulation implementation guidance, and customs trade data for nickel superalloy component flows. Bottom-up unit economics for turbine manufacturing and top-down defense budget allocation analysis were triangulated against installed base estimates.
Assumptions regarding FAA Part 33 certification timeline stability, nickel superalloy supply concentration persistence, and defense UAV procurement growth trajectories were held fixed across the modeling period, while sustainable aviation fuel mandate acceleration and hybrid-electric architecture adoption curves were varied as sensitivity inputs. Segmentation dimensions modeled included propulsion architecture, end-use application, and technology type alongside geographic regulatory cluster. CAGRs were derived from production volume build-ups validated against OEM capacity disclosures and procurement contract award patterns.
Stress conditions across nickel price volatility, precision casting capacity constraints, and defense budget reallocation scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and acknowledge that regulatory timeline compression or additive manufacturing disruption could materially revise trajectory. Cross-checking against FAA type certification backlog data and defense procurement pipeline disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Military Power Solutions Market
Aircraft Power Systems
Electrified Aircraft Propulsion Market
Aircraft Power Systems
Aviation High Speed Motor Market
Aircraft Power Systems
Aircraft Electrical Systems Market
Aircraft Power Systems
Liquid Hydrogen-Powered Aircraft Market
Aircraft Power Systems
Space Power System Hardware-in-the-Loop Test Platforms Market
Aircraft Power Systems
Global Aircraft Micro Turbine Market
Aircraft Power Systems
Aircraft Generators Market
Aircraft Power Systems
Aircraft Battery Market
Aircraft Power Systems
Aircraft Auxiliary Power Unit Gearbox Market
Aircraft Power Systems
Aircraft Thrust Reverser Actuation Systems Market
Aircraft Power Systems
Aircraft Turboprop Propeller System Market
Aircraft Power Systems
Aerospace Electrical Inserts Market
Aircraft Power Systems
Aircraft Propulsion System Market
Aircraft Power Systems
Commercial Aircraft Propeller Systems Market
Aircraft Power Systems
Aircraft Electronic Ignition System Market