
 Urban Air Mobility (UAM) Market | 2026-2036
Urban Air Mobility (UAM) Market Size, Share, and Industry Trends Forecast 2026-2036
Urban Air Mobility (UAM) Market Intelligence
FAA Part 23 powered-lift certification is collapsing the barrier between experimental prototypes and commercial passenger operations. Joby Aviation leverages extensive flight-test data to sustain its lead in range and payload validation. Lilium competes through its proprietary ducted-electric-vector-thrust architecture, while Beta Technologies anchors the cargo-use segment with its Alia platform and integrated charging infrastructure.
Urban Air Mobility denotes electric and hybrid-electric aircraft operating within metropolitan airspace at altitudes below conventional commercial aviation corridors, typically utilizing distributed propulsion with six to twelve rotors and battery energy densities exceeding 250 watt-hours per kilogram. The primary purpose is to decongest surface transportation networks through point-to-point aerial mobility for passengers and time-critical goods. eVTOL configurations dominate current development pipelines due to their elimination of runway dependency and mechanical simplicity relative to vectored-thrust alternatives. Air taxi services command the largest projected revenue pool among use cases, though cargo delivery segments exhibit faster regulatory clearance cycles in jurisdictions with permissive beyond-visual-line-of-sight frameworks.
FAA Part 135 operational certificates, EASA's SC-VTOL special condition framework, and the UAE's GCAA vertiport technical specifications collectively determine which platforms achieve revenue service and where. These standards shape everything from battery thermal-runaway containment to pilot training minima and noise footprint limits at terminal locations. Stakeholders must monitor which regulator first certifies fully autonomous passenger operations without onboard safety pilots, as that jurisdiction will likely attract the initial wave of scaled commercial deployment.
Market Dynamics
FAA Part 23 powered-lift certification is compressing the timeline between prototype validation and commercial passenger service, forcing manufacturers to front-load flight-test data collection and airworthiness documentation.
Growth Catalysts
- Emergency medical services:Hospitals and first responders are expanding aerial patient transport networks to bypass ground congestion. The UAE's GCAA vertiport technical specifications provide operational templates for rapid deployment.
- Battery energy density thresholds:Cells exceeding 250 watt-hours per kilogram enable practical range for urban missions. Distributed propulsion architectures leverage these gains through six-to-twelve rotor configurations.
- Dubai's dedicated corridors:The Roads and Transport Authority has established operational frameworks linking vertiport locations. This infrastructure pre-positioning attracts fleet operators seeking early-mover advantages.
Market Restraints
- Certification timeline friction:FAA Part 23 powered-lift pathways remain novel, creating interpretive uncertainty that extends validation schedules and burns development capital.
- Pilot training infrastructure gaps:EASA's SC-VTOL special condition framework lacks harmonized simulator standards, forcing operators to build bespoke training programs.
- Ground transport substitution:Autonomous road vehicles and congestion pricing schemes compete for the same decongestion mandate at lower unit economics.
Strategic Opportunities
- Time-critical cargo corridors:Jurisdictions with permissive beyond-visual-line-of-sight frameworks are clearing cargo operations faster than passenger services. Beta Technologies anchors this segment with integrated charging infrastructure.
- Autonomous certification race:The first regulator to approve fully autonomous passenger operations without onboard safety pilots will concentrate scaled deployment. Stakeholders are monitoring FAA, EASA, and GCAA progress.
- Vertiport real estate arbitrage:Urban core locations with heliport grandfather rights offer faster zoning clearance than greenfield sites. Dubai, Singapore, and São Paulo present concentration opportunities.
Industry Challenges
- Air traffic integration complexity:Unmanned traffic management systems must coordinate with legacy radar networks. FAA and EASA timelines for harmonized protocols remain unspecified.
- Thermal-runaway containment engineering:Battery pack architectures require redundant suppression systems that add weight and certification burden. Manufacturers trade range against safety margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urban Air Mobility (UAM) Market |
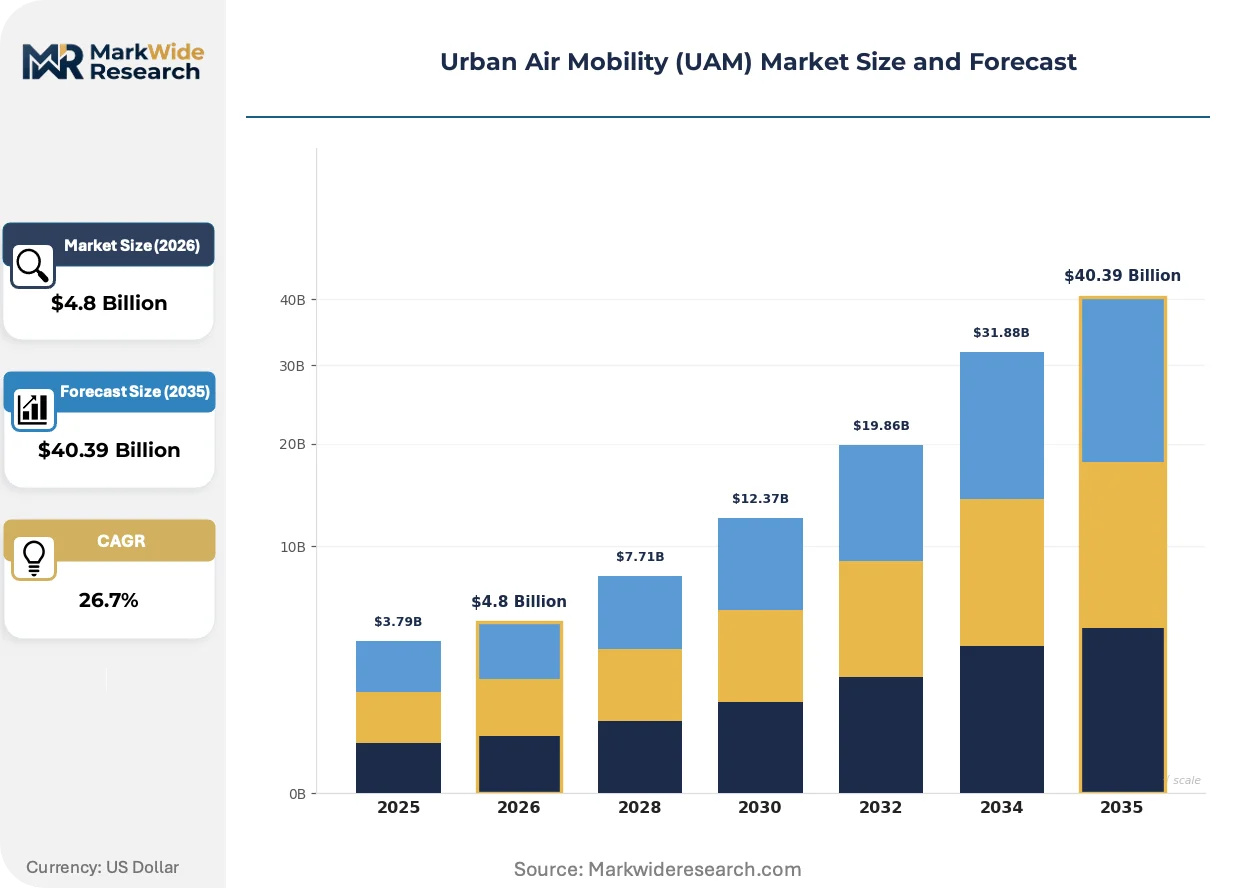
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $40.39 Billion |
| CAGR (2026 – 2036) | 26.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: eVTOL, eCTOL, Hybrids, Jet Aircraft, Multirotor Propulsion System: Electric Motor, Turbine Engine, Hybrid Electric, Battery Powered, Hydrogen Fuel Cell Use Case: Passenger Transport, Air Taxi, Cargo Delivery, Emergency Services, Tourism End User: Urban Commuters, Corporate Fleets, Public Safety Agencies, Logistics Providers, Event Management |
| Companies Covered | Lilium, Beta Technologies, Joby Aviation, Wisk Aero, Vertical Aerospace, Archer Aviation, Volocopter, Eve Air Mobility, EHang, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urban Air Mobility (UAM) Market Strategic Shifts & Innovations
Distributed electric propulsion is collapsing the mechanical complexity barrier that historically constrained rotorcraft economics, enabling new entrants to challenge incumbent aerospace suppliers.
Silicon carbide power electronics are miniaturizing inverter packaging for high-torque electric motors. eVTOL manufacturers are adopting these components to reduce powertrain mass and extend thermal operating envelopes. The structural consequence is compressing the performance gap between experimental prototypes and certifiable production systems.
EASA's SC-VTOL special condition framework is establishing noise footprint limits at terminal locations that exceed conventional helicopter standards. Urban operators must redesign rotor acoustics to comply. European air taxi services face stricter site approval timelines than cargo counterparts.
Hospital procurement departments are unbundling traditional air ambulance contracts to source eVTOL capacity through dedicated service agreements. Fixed-wing charter operators are losing exclusive relationships to platform-agnostic fleet managers. This shift concentrates in the United Arab Emirates where Dubai's health authority has issued performance-based tender specifications.
Urban Air Mobility (UAM) Market Segmentation
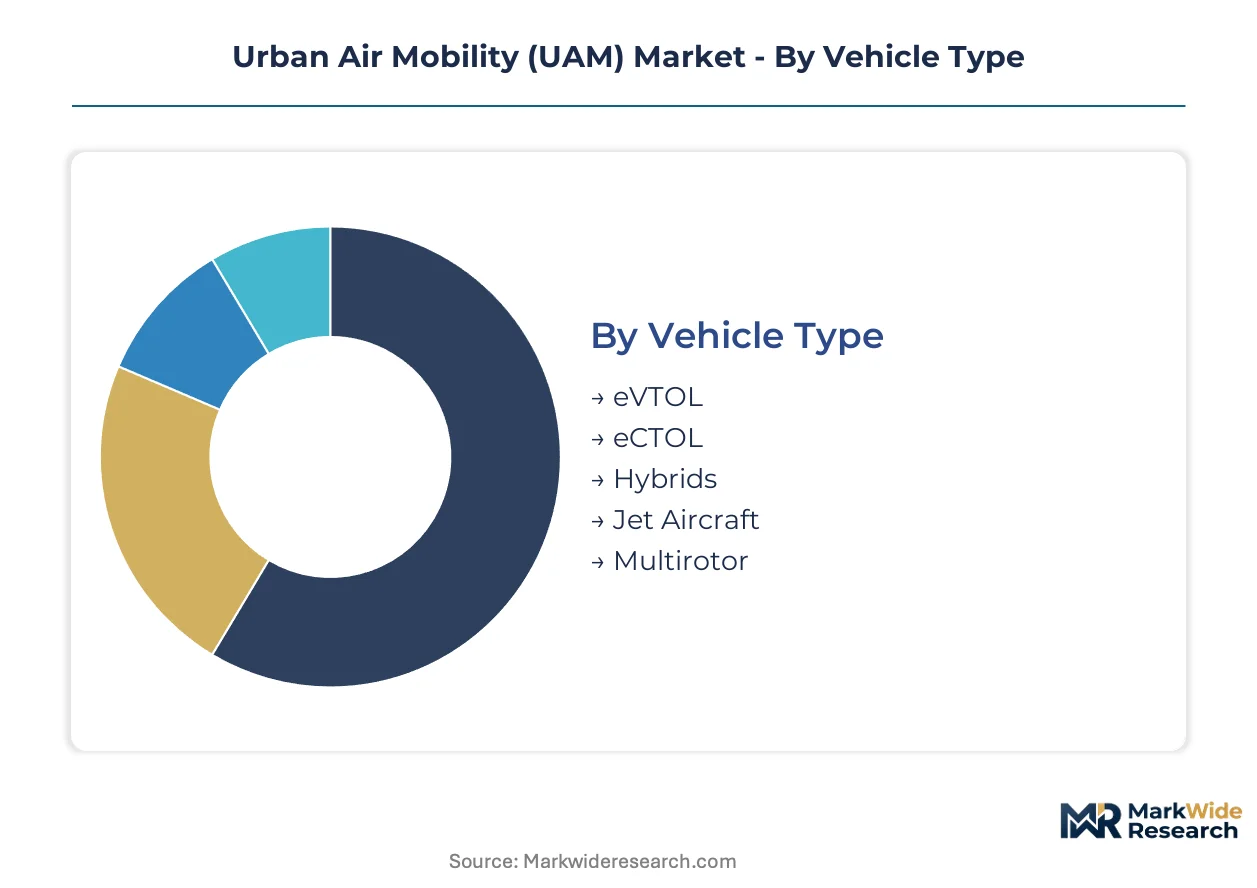
Segmentation in Urban Air Mobility reveals how regulatory clearance timelines and infrastructure readiness create divergent commercialization paths across vehicle configurations and operational models. Manufacturers prioritize segments with the shortest certification bridges to revenue service.
Vehicle Type:
Multirotor and vectored-thrust architectures face divergent substitution pressures from conventional helicopters and fixed-wing charter services depending on range requirements and vertiport availability.
- eVTOL:Electric vertical take-off and landing configurations eliminate runway dependency through distributed propulsion with six to twelve rotors. Demand concentrates in Dubai where the Roads and Transport Authority has established dedicated corridors linking vertiport locations.
- Multirotor:Simpler mechanical architectures reduce certification burden and maintenance complexity relative to tilt-rotor alternatives. Logistics providers in jurisdictions with permissive beyond-visual-line-of-sight frameworks are adopting these platforms for cargo corridors.
- eCTOL:Electric conventional take-off and landing designs retain wing-borne efficiency for longer-range missions but require runway access that limits urban core penetration.
- Hybrids:Series-hybrid architectures extend range through onboard turbine generation while maintaining electric distributed propulsion for hover phases.
- Jet Aircraft:Conventional turbofan configurations serve inter-city routes above urban air mobility altitudes with higher speeds but greater noise footprints.
eVTOL retains volume leadership; Multirotor holds the steepest expansion curve.
Propulsion System:
Energy density thresholds differentiate practical commercial viability from experimental performance, with battery thermal-runaway containment engineering adding certification weight that compresses effective range.
- Battery Powered:Lithium-ion cells exceeding 250 watt-hours per kilogram enable practical urban missions. FAA Part 23 powered-lift certification pathways are compressing timelines for domestic manufacturers leveraging extensive flight-test data.
- Electric Motor:Silicon carbide power electronics miniaturize inverter packaging for high-torque applications. EASA's SC-VTOL special condition framework is establishing noise footprint limits that exceed conventional helicopter standards.
- Hybrid Electric:Turbine-electric architectures bridge the range gap for markets without dense vertiport networks.
- Hydrogen Fuel Cell:Proton-exchange-membrane systems offer higher specific energy than batteries but face infrastructure and storage certification gaps.
- Turbine Engine:Conventional turboshaft powertrains persist in hybrid configurations and transitional platforms seeking Part 23 equivalence.
Battery Powered dominates current development pipelines; Electric Motor is climbing the fastest as silicon carbide adoption accelerates.
Use Case:
Regulatory risk tolerance varies sharply between passenger and non-passenger operations, with cargo services clearing operational frameworks faster in permissive jurisdictions.
- Emergency Services:Hospitals and first responders are expanding aerial patient transport networks to bypass ground congestion. The UAE's GCAA vertiport technical specifications provide operational templates for rapid deployment.
- Cargo Delivery:Time-critical goods segments exhibit faster regulatory clearance cycles. Beta Technologies anchors this use case with integrated charging infrastructure and the Alia platform.
- Air Taxi:Point-to-point passenger services command the largest projected revenue pool but face extended certification timelines for autonomous operations.
- Passenger Transport:Scheduled inter-vertiport services target urban commuters with premium pricing relative to surface alternatives.
- Tourism:Scenic flight operations leverage lower regulatory barriers and existing heliport infrastructure in coastal and alpine destinations.
Emergency Services retains volume leadership; Cargo Delivery gains share fastest through permissive beyond-visual-line-of-sight frameworks.
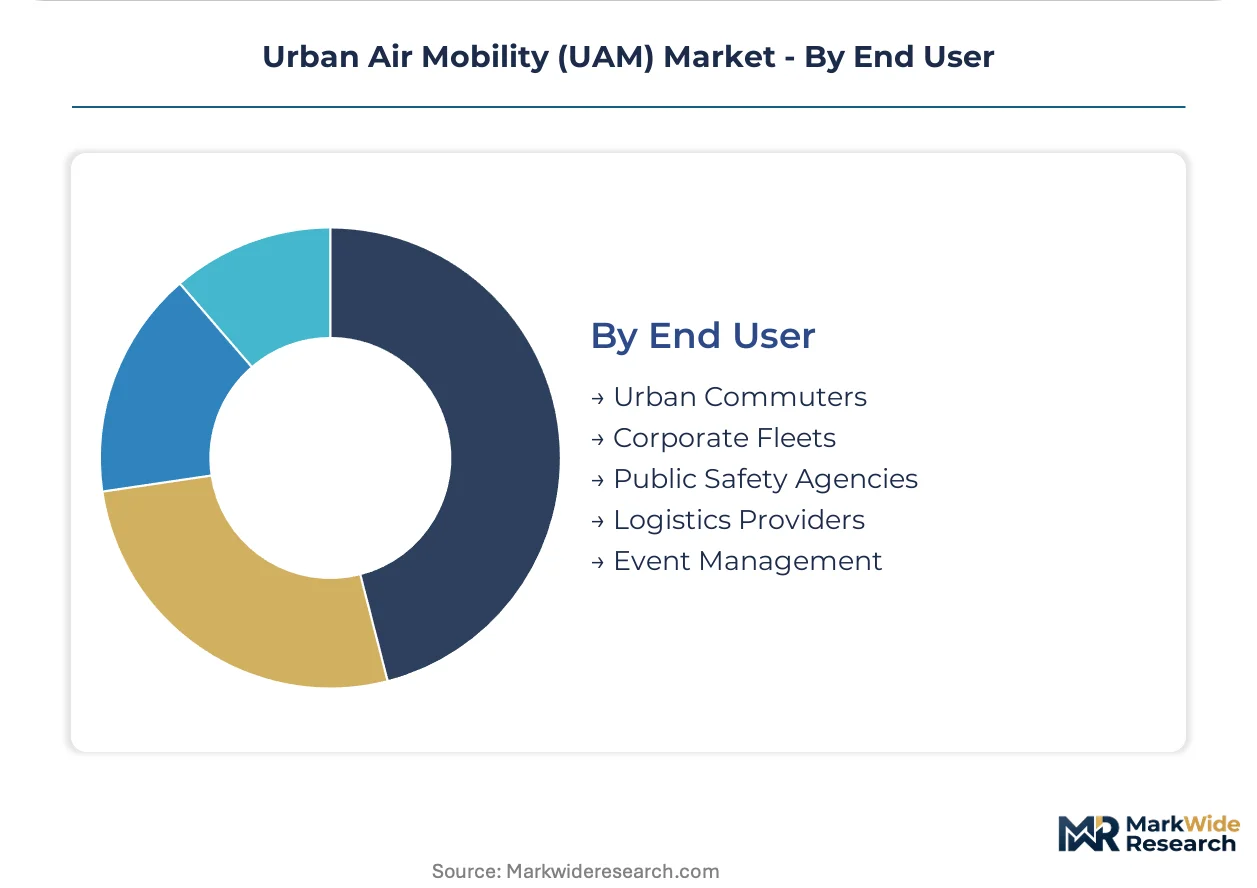
End User:
Procurement authority fragmentation across public safety and commercial logistics creates divergent sales cycles and contract structures for fleet operators.
- Logistics Providers:E-commerce and time-critical freight operators are unbundling traditional air charter contracts to source dedicated eVTOL capacity through performance-based service agreements.
- Public Safety Agencies:Police, fire, and emergency medical departments issue tenders specifying response-time metrics that favor distributed vertiport networks over centralized heliports.
- Corporate Fleets:Large employers with dispersed facilities are evaluating shuttle services to reduce ground transport time for executive and technical staff.
- Urban Commuters:Individual passenger demand remains price-sensitive and dependent on autonomous certification removing pilot cost structures.
- Event Management:Temporary vertiport deployments for sports and entertainment venues test operational frameworks without permanent infrastructure commitment.
Logistics Providers retains volume leadership; Public Safety Agencies holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UAE federal incentives for vertiport infrastructure deployment are attracting fleet operators seeking early-mover positioning. Singapore and Saudi Arabia have issued complementary regulatory guidance. Germany and the United States maintain parallel certification frameworks.
United Arab Emirates
Dubai's Roads and Transport Authority operates dedicated eVTOL corridors linking healthcare facilities and commercial districts. The GCAA vertiport technical specifications provide operational templates for rapid deployment. Abu Dhabi is constructing integrated charging infrastructure at existing heliport locations.
Germany
EASA's SC-VTOL special condition framework establishes noise footprint limits exceeding conventional helicopter standards. The country's automotive supply base is pivoting toward electric propulsion components for aerial platforms. Munich and Stuttgart host engineering clusters developing distributed propulsion architectures.
United States
FAA Part 23 powered-lift certification is compressing development timelines for domestic manufacturers. Joby Aviation leverages extensive flight-test data to sustain range and payload validation. California and Texas concentrate flight-test facilities and pilot training infrastructure.
Singapore
The Civil Aviation Authority of Singapore has published urban air mobility regulatory guidelines permitting beyond-visual-line-of-sight cargo operations. The city-state's dense maritime logistics network creates demand for time-critical aerial freight. Changi Airport precinct hosts vertiport planning for intermodal connectivity.
Saudi Arabia
NEOM's linear city design incorporates dedicated aerial mobility corridors from initial master planning. The General Authority of Civil Aviation is harmonizing standards with EASA frameworks. Riyadh and Jeddah are evaluating heliport conversion programs for eVTOL compatibility.
Urban Air Mobility (UAM) Market Key Industry Players
Player mix skews toward venture-backed aerospace startups with automotive supply chain partnerships. Market structure remains fragmented across pre-revenue developers, with consolidation pressure intensifying as certification timelines compress. Two strategic archetypes dominate: integrated platform manufacturers controlling propulsion and airframe design, and vertiport infrastructure operators securing real estate ahead of fleet deployment. Competitive moves center on flight-test data accumulation for regulatory submissions and strategic partnerships with battery cell suppliers.
Within the integrated platform tier, Joby Aviation and Lilium represent divergent technical approaches to powered-lift certification. Beta Technologies anchors the cargo-use segment through integrated charging infrastructure development. These three companies exemplify how early flight-test investment correlates with regulatory pathway progression across FAA, EASA, and GCAA jurisdictions.
| Leading Market Players |
|---|
| Lilium |
| Beta Technologies |
| Joby Aviation |
| Wisk Aero |
| Vertical Aerospace |
| Archer Aviation |
| Volocopter |
| Eve Air Mobility |
| EHang |
| Others |
Cost & Logistics Intelligence
Ninety-day battery cell lead times from Korean suppliers concentrate pricing power among vertically integrated airframe manufacturers while forcing smaller developers toward spot-market premiums. This inventory compression tightens margins across the certification pipeline and rewards early offtake commitments with tier-one cell producers.
Pricing Analysis
Certification level creates the primary spread between experimental prototypes and revenue-ready platforms. Three-tier pricing structure across FAA-certificated, EASA-SC-VTOL, and pre-certification development units reflects validation risk and insurance cost differentials. Pricing pressure stems from automotive battery suppliers redirecting capacity toward EV contracts, squeezing aerial mobility offtake. Logistics providers exhibit highest price sensitivity due to thin cargo margins, while emergency medical services accept premium positioning for response-time guarantees.
Supply Chain Analysis
South Korean cathode production chokepoints tether cell output to regional chemical processing capacity. China, South Korea, and Japan dominate lithium-ion supply for aviation-grade energy densities. Silicon carbide wafer fabrication draws from Taiwan and Germany for power electronics. Single-source vulnerability concentrates in aerospace-qualified battery management systems. Distribution runs through Tier 1 aerospace integrators with captive vertiport partnerships.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Urban Air Mobility operates as a substitution defense against autonomous road networks and congestion pricing schemes that threaten the decongestion value proposition. Incumbents must navigate this modal competition while securing certification timelines that preserve first-mover economics.
For Market Incumbents: Consolidate flight-test data assets into unified FAA Part 23 submission packages to compress validation schedules. Acquire vertiport real estate with heliport grandfather rights in Dubai and Singapore before zoning premiums materialize. Defensive positioning against autonomous road vehicle subsidies requires demonstrating aerial time savings in corridor-specific tenders. For New Entrants and Emerging Players: Differentiate on beyond-visual-line-of-sight cargo corridors where regulatory clearance cycles run shorter than passenger pathways. Target Saudi Arabia's NEOM linear city and UAE healthcare networks as white-space geographies with pre-positioned infrastructure. Go-to-market leverage rests on integrated charging hardware rather than airframe performance alone. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because jurisdiction-first certification will concentrate scaled deployment and platform economics. Acquisition profiles favor vertiport operators with urban core zoning clearance over pre-revenue airframe developers. The signal to watch is FAA or EASA approval of fully autonomous passenger operations without onboard safety pilots.| Strategic Initiative | Industry Significance |
|---|---|
| Vertiport Infrastructure Partnership | Secures zoning-cleared real estate in Dubai, Singapore, and São Paulo ahead of fleet deployment. |
| Battery Cell Offtake Agreement | Locks aviation-qualified lithium-ion supply from Korean producers against automotive diversion. |
| FAA Part 23 Certification Submission | Compresses timeline between prototype validation and commercial passenger revenue service. |
| Autonomous Operations Regulatory Engagement | Positions for first-mover advantage in jurisdiction approving pilotless passenger flights. |
| Cargo Corridor Operational Clearance | Generates revenue through permissive beyond-visual-line-of-sight frameworks while awaiting passenger certification. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FAA certification filings, EASA SC-VTOL documentation, GCAA vertiport specifications, and trade customs data for electric propulsion components. Primary interviews engaged eVTOL program directors, vertiport infrastructure planners, battery procurement leads at aerospace integrators, and regulatory affairs specialists at aviation authorities. Bottom-up platform deployment modeling triangulates against top-down metropolitan congestion economics across the analysis window.
Segmentation dimensions modeled include vehicle configuration, propulsion architecture, use case category, and end-user procurement authority across the projection horizon. CAGRs derive from installed base accumulation curves and corridor-specific operational clearance timelines. Forecast inputs incorporate battery energy density improvement trajectories and vertiport construction permitting velocity by metropolitan jurisdiction.
Forecasts assume regulatory continuity in FAA Part 23, EASA SC-VTOL, and UAE GCAA frameworks; material policy shifts in autonomous operations approval or battery thermal-runaway standards would require re-modeling. Practitioners should keep alternative scenarios live as autonomous road vehicle deployment and congestion pricing adoption evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Mobility
Asia-Pacific Charter Jet Service Market
Air Mobility
Advanced Aerial Mobility Market
Air Mobility
Urban Autonomous Air Mobility Market
Air Mobility
Flying Jetpacks Market
Air Mobility
Global Aerodynamics Market
Air Mobility
Airborne Pods Market
Air Mobility
Air Crane Helicopter Market
Air Mobility
Off-Shore Helicopters Market
Air Mobility
Advanced Air Mobility Market
Air Mobility
Air Transport Modifications Market
Air Mobility
Global Flying Cars Market
Air Mobility
Middle East and Africa General Aviation Market
Air Mobility
Global Aerial Firefighting Market
Air Mobility
China Chartered Air Transport Market
Air Mobility
Offshore Helicopter Services Market
Air Mobility
Parabolic Flight Tourism Market