
 Asia-Pacific Charter Jet Service Market | 2026-2036
Asia-Pacific Charter Jet Service Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Charter Jet Service Market Outlook
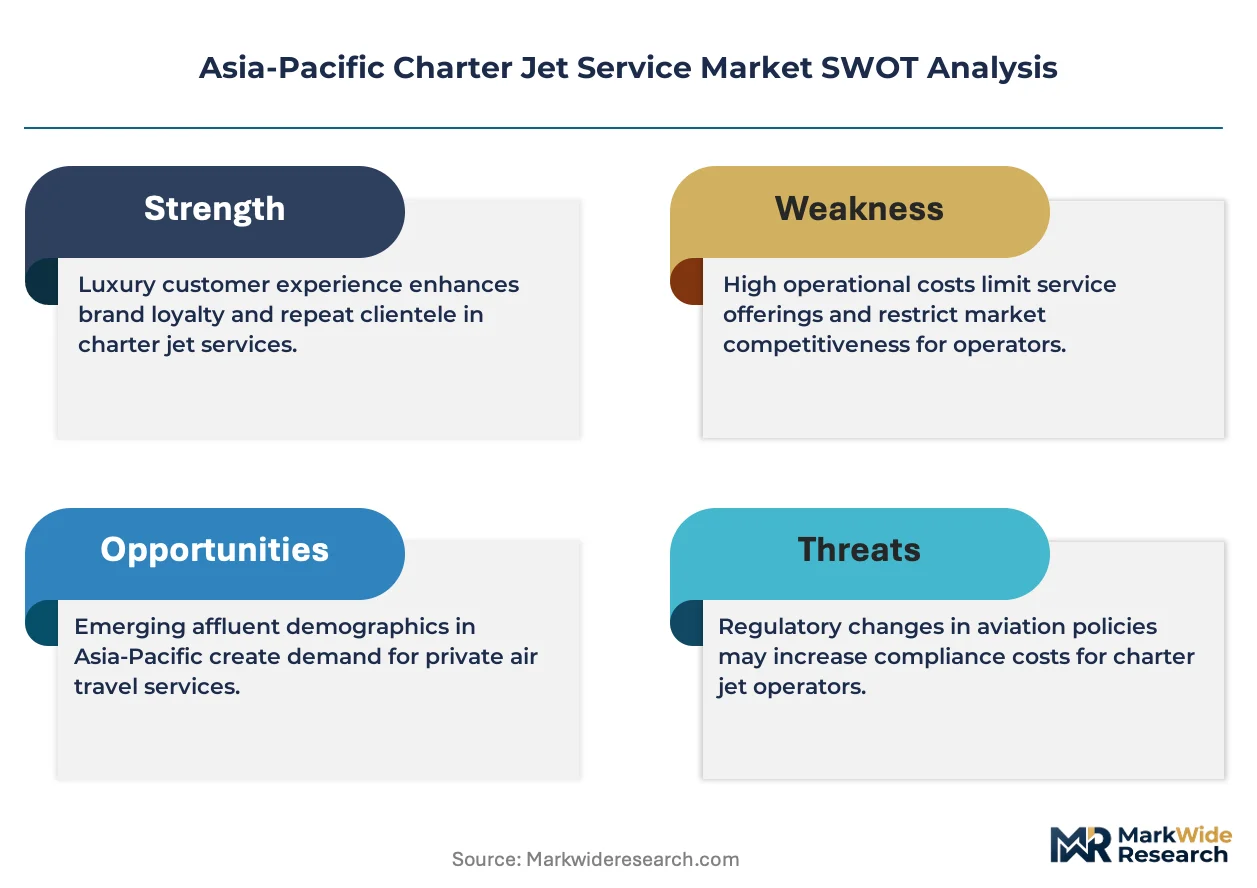
IS-BAO Stage III certification is redrawing competitive boundaries across the Asia-Pacific charter jet landscape. VistaJet leverages its Malta AOC structure to sustain seamless intra-regional positioning without repeated customs delays. ExecuJet Aviation Group anchors its Singapore and Hong Kong bases with dedicated maintenance capabilities that competitors struggle to replicate. Deer Jet (Beijing) Co., Ltd. dominates ultra-long-haul heavy jet missions between Chinese tier-one cities and European financial centers.
Asia-Pacific charter jet service denotes the commercial provision of non-scheduled aircraft operations where clients contract entire aircraft capacity on a per-flight or block-hour basis, typically utilizing jets certified under ICAO Annex 6 Part II standards with minimum cabin altitudes of 6,000 feet for passenger comfort on sectors exceeding four hours. The primary purpose centers on time-sensitive executive mobility, medical evacuation, and government transport where scheduled airline networks prove inadequate. On-demand service captures the dominant revenue share as fractional ownership models lose traction among Asian family offices seeking asset-light alternatives. Heavy jets command premium positioning for trans-Pacific routes, while light jets experience fastest volume growth on intra-ASEAN business corridors below three hours.
CAAC's operational specifications for foreign-registered aircraft, Australia's CASA Part 135 requirements, and Singapore CAAS air operator certification collectively determine market access and fleet eligibility across the region's three largest aviation jurisdictions. These frameworks impose minimum crew rest provisions, maintenance interval mandates, and route-specific insurance thresholds that directly shape operator cost structures and available aircraft pools. Stakeholders must monitor evolving bilateral aviation safety agreements between ASEAN member states and third-country regulators to anticipate fleet redeployment opportunities.
Market Dynamics
IS-BAO Stage III certification is compressing competitive margins across the Asia-Pacific charter jet landscape, forcing operators to absorb compliance costs while defending positioning against certified rivals.
Growth Catalysts
- Ultra-high-net-worth expansion:Southeast Asian family offices are converting from fractional ownership to on-demand charter models, eliminating asset-heavy commitments while preserving flight-hour flexibility.
- CAAC operational specifications:China's tightened certification requirements for foreign-registered aircraft are redirecting demand toward locally AOC-structured operators with established intra-regional positioning rights.
- Medical evacuation infrastructure:Australia's east coast corridor is deploying dedicated air ambulance fleets with ICU-equipped heavy jets, creating anchor demand for 24/7 operational bases in Sydney and Melbourne.
Market Restraints
- Pilot certification scarcity:DGCA and CAAC reciprocal recognition limitations are constricting qualified crew pools, inflating salary premiums for dual-rated captains across Indian and Chinese registries.
- Jet fuel price volatility:Singapore jet kerosene benchmarks directly transmit to per-flight-hour pricing, compressing margins on fixed-rate block-hour contracts during supply shocks.
- Maintenance concentration risk:ExecuJet's Singapore and Hong Kong MRO capabilities create single-point dependencies for competing operators lacking in-house airframe expertise.
Strategic Opportunities
- Indonesia archipelago connectivity:Underpenetrated routes linking Jakarta to secondary islands present white-space demand for light jets configured for sub-three-hour ASEAN corridors.
- Sustainability-linked block-hour pricing:Singapore CAAS carbon offset mandates are enabling premium positioning for operators with verified SAF procurement pipelines.
- Telemedicine-cabin integration:Converging satellite connectivity and remote patient monitoring is opening high-yield air ambulance contracts with Australian private hospital networks.
Industry Challenges
- IS-BAO Stage III audit timelines:Eighteen-month certification cycles are delaying market entry for new entrants despite capital deployment, privileging incumbents with existing audit histories.
- Legacy FMS integration complexity:Next-generation navigation performance requirements are forcing expensive avionics retrofits on mid-life heavy jets serving trans-Pacific routes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Charter Jet Service Market |
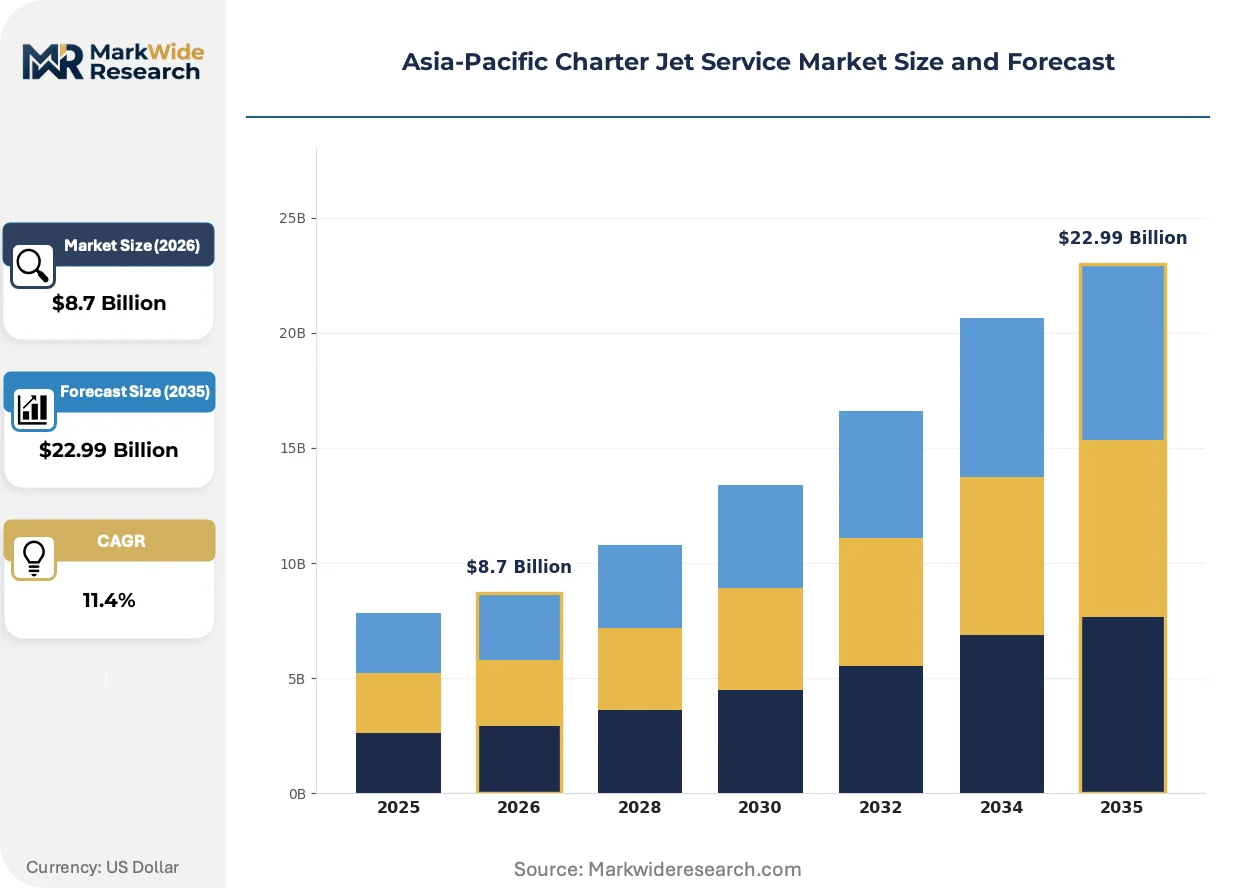
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: On-Demand, Scheduled, Empty Leg, Private Charter Aircraft Type: Light Jets, Midsize Jets, Heavy Jets, Turboprop Customer Segment: Corporate Clients, Private Individuals, Government Agencies, Travel Agencies Booking Method: Online Booking, Travel Agent, Direct Call, Mobile App |
| Companies Covered | Deer Jet (Beijing) Co., Ltd., Club One Air, Revesco Aviation Pty Ltd., Global Jet International, Executive Jets Asia Pte Ltd., VistaJet, Air Charter Service, TAG Aviation Asia, ExecuJet Aviation Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Charter Jet Service Market Strategic Shifts
Digital flight management and sustainability mandates are actively compressing operational paradigms across Asia-Pacific charter operations, rewarding early adopters with regulatory preferencing and contract access.
Advanced satellite connectivity suites are miniaturizing cabin communication hardware while expanding bandwidth capacity for real-time teleconferencing. Ultra-high-net-worth principals now mandate seamless video capability as a baseline procurement criterion, displacing legacy voice-only systems. This compression is enabling single-aircraft substitution for previously multi-stop itineraries, directly reducing crew duty limitations and repositioning costs.
Singapore CAAS carbon offset mandates are imposing verified emissions reporting on all air operator certificate holders serving Changi-based clients. Operators must document fuel burn per sector and procure certified offsets through approved registries, adding administrative overhead but unlocking preferential slot access. Heavy jet fleets serving European financial center routes face the steepest compliance burden given sector length and fuel volume exposure.
Family office procurement patterns are fragmenting away from long-term management contracts toward dynamic booking platforms with transparent instantaneous pricing. Australian and Hong Kong-based buyers now compare live availability across competing operators via aggregated interfaces, compressing loyalty premiums and forcing real-time rate competitiveness. This disintermediation is most visible in Sydney-Melbourne-Brisbane triangle demand, where corridor density supports platform liquidity.
Asia-Pacific Charter Jet Service Market Segmentation
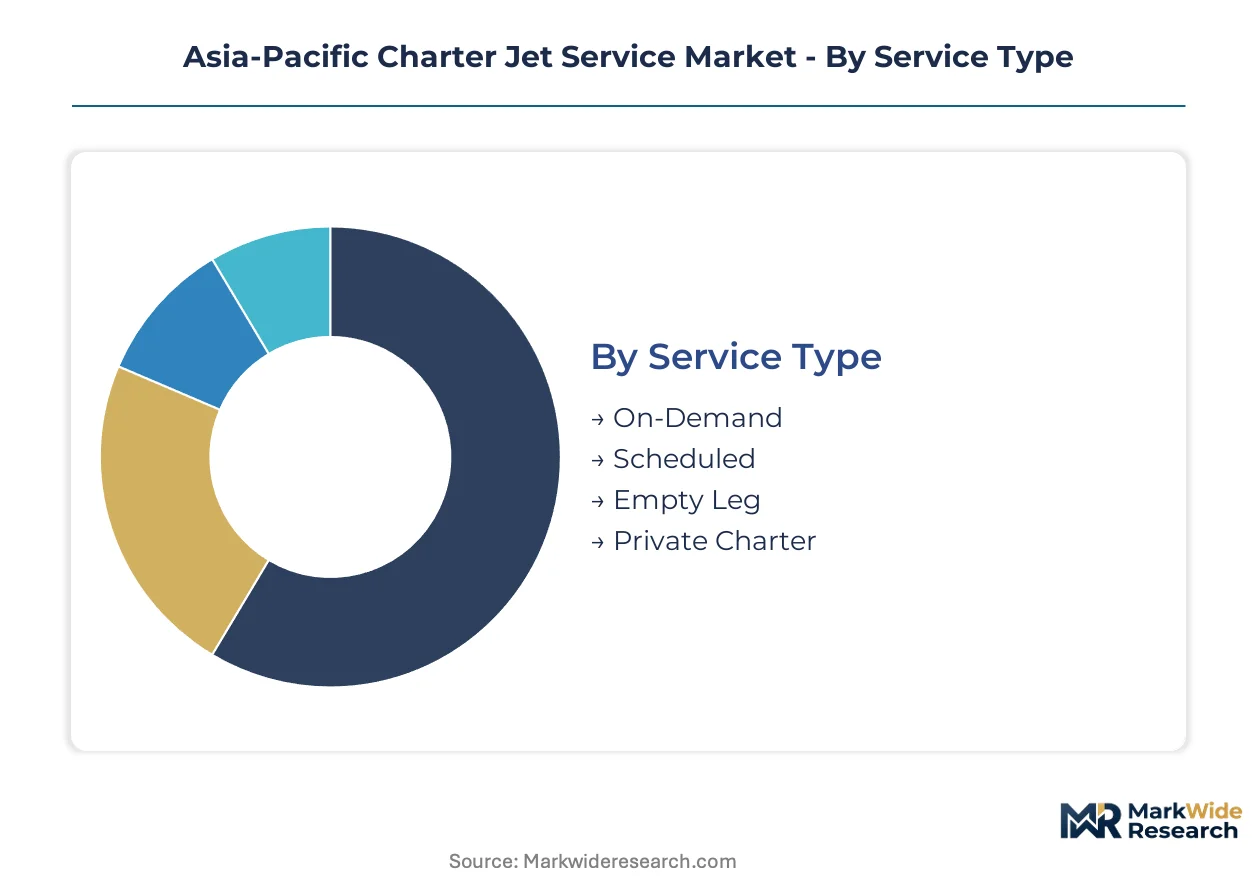
Charter jet service segmentation in Asia-Pacific reflects divergent regulatory treatment across service models and aircraft categories. CAAC, CASA, and CAAS each impose distinct certification burdens that reshape competitive economics by segment.
Service Type:
Regulatory differentiation separates on-demand operations from scheduled services through operational specification requirements under CAAC and CASA Part 135 frameworks.
- On-Demand:Per-flight or block-hour contracting with immediate dispatch flexibility. Demand concentrates among Southeast Asian family offices seeking asset-light alternatives to fractional ownership, constrained by IS-BAO Stage III audit timelines for new entrants.
- Scheduled:Recurring route commitments with fixed departure windows. Australian east coast corridor operators leverage this structure for 24/7 air ambulance bases in Sydney and Melbourne, though crew rest provisions under CASA compress aircraft utilization rates.
- Empty Leg:Repositioning flights offered at discounted rates. Singapore-based platforms aggregate live availability for Sydney-Melbourne-Brisbane triangle demand.
- Private Charter:Exclusive aircraft dedication for single-client missions. Chinese tier-one city routes to European financial centers dominate ultra-long-haul deployment.
On-Demand handles the majority of throughput; Empty Leg is expanding most quickly on share.
Aircraft Type:
Cost tier differentiation aligns with route distance and cabin altitude requirements for passenger comfort on sectors exceeding four hours.
- Light Jets:Aircraft certified for sub-three-hour sectors with ICAO Annex 6 Part II compliance. Indonesia archipelago routes from Jakarta to secondary islands present white-space demand, though limited MRO infrastructure outside Singapore and Hong Kong constrains fleet expansion.
- Heavy Jets:Ultra-long-haul platforms with minimum cabin altitudes of 6,000 feet. Trans-Pacific corridors face steepest Singapore CAAS carbon offset compliance burden given sector length and fuel volume exposure.
- Midsize Jets:Intermediate range capability for intra-ASEAN business corridors. Australian private hospital networks drive air ambulance configuration demand.
- Turboprop:Short-field performance for secondary airfields. Lower fuel burn appeals to operators under SAF procurement pressure.
Heavy Jets generate premium revenue concentration; Light Jets are gaining share fastest on volume expansion.
Customer Segment:
Application-based procurement patterns fragment contract structures and loyalty dynamics across buyer types.
- Corporate Clients:Time-sensitive executive mobility where scheduled networks prove inadequate. Dynamic booking platform adoption is highest among Australian and Hong Kong-based buyers comparing live operator availability.
- Private Individuals:Ultra-high-net-worth principals mandating seamless video capability as baseline procurement criterion. Fragmentation away from long-term management contracts accelerates.
- Government Agencies:Diplomatic and official transport with security protocol requirements. DGCA and CAAC reciprocal recognition limitations constrain crew pool flexibility.
- Travel Agencies:Intermediary aggregation for leisure and corporate accounts. Platform liquidity depends on corridor density for competitive rate transparency.
Corporate Clients anchor contract volume; Private Individuals show the steepest expansion trajectory.
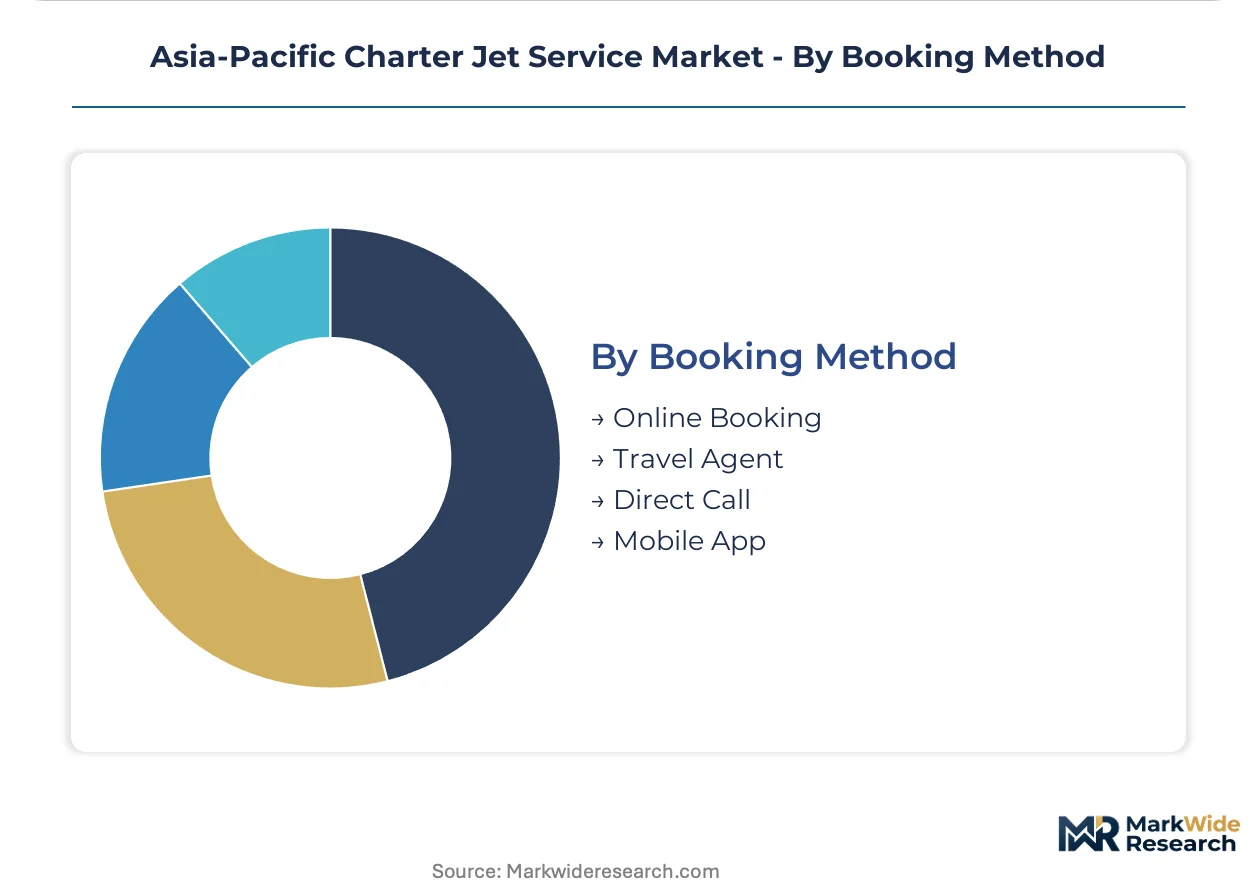
Booking Method:
Volume concentration and margin structure diverge sharply between digital and traditional reservation channels.
- Online Booking:Aggregated interfaces with instantaneous pricing transparency. Sydney-Melbourne-Brisbane corridor density supports platform liquidity unavailable in thinner markets.
- Mobile App:Native application interfaces with push notification availability. Fastest adoption among Southeast Asian family office demographics.
- Travel Agent:Intermediary relationships preserving loyalty premiums in fragmented markets. Indonesia and Philippines maintain higher penetration than mature hubs.
- Direct Call:Voice reservation for complex multi-leg itineraries or security-sensitive missions. Government and medical evacuation clients retain preference.
Online Booking commands the dominant transaction share; Mobile App shows the fastest climb on adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore CAAS carbon offset mandates and Australia's CASA Part 135 requirements are redrawing operational economics across Asia-Pacific charter corridors, privileging certified operators with established intra-regional positioning rights.
China
CAAC operational specifications for foreign-registered aircraft redirect demand toward locally AOC-structured operators. China's dual carbon goals impose escalating fuel efficiency benchmarks on heavy jet fleets serving European financial center routes. Beijing and Shanghai anchor ultra-long-haul mission deployment for tier-one city connectivity.
Australia
CASA Part 135 crew rest provisions compress aircraft utilization rates while driving 24/7 operational base establishment. The country's national aviation regulator mandates route-specific insurance thresholds that reshape operator cost structures. Sydney, Melbourne, and Brisbane form the dominant east coast corridor for air ambulance and executive mobility demand.
Singapore
CAAS air operator certification requirements determine market access for regional fleet eligibility. Verified SAF procurement pipelines unlock preferential slot access at Changi for compliant operators. The city-state's MRO capabilities create single-point dependencies for competing operators lacking in-house airframe expertise.
India
DGCA tightened operational certification requirements constrict qualified crew pools for foreign-registered charter aircraft. Reciprocal recognition limitations with CAAC inflate salary premiums for dual-rated captains across Indian and Chinese registries. Mumbai and Delhi concentrate ultra-high-net-worth principal demand among family offices converting from fractional ownership.
Indonesia
Underpenetrated routes linking Jakarta to secondary islands present white-space demand for light jets configured for sub-three-hour ASEAN corridors. The country's national aviation regulator imposes maintenance interval mandates that constrain fleet expansion beyond Singapore and Hong Kong MRO hubs. Archipelago geography fragments scheduled airline network adequacy, elevating charter substitution economics.
Asia-Pacific Charter Jet Service Market Competitive Environment
Player mix skews toward integrated operators with Malta AOC structures and dedicated maintenance capabilities. Market structure concentrates around three strategic archetypes: heavy jet specialists dominating trans-Pacific corridors, light jet operators capturing intra-ASEAN volume expansion, and platform-aggregators disintermediating traditional loyalty premiums. Competitive dynamics center on IS-BAO Stage III certification acquisition and SAF procurement pipeline establishment.
Within the integrated operator tier, VistaJet leverages its Malta AOC structure to sustain seamless intra-regional positioning, while ExecuJet Aviation Group anchors Singapore and Hong Kong bases with maintenance capabilities that competitors struggle to replicate. Deer Jet (Beijing) Co., Ltd. occupies a position exemplifying heavy jet specialization for ultra-long-haul missions between Chinese tier-one cities and European financial centers.
| Leading Market Players |
|---|
| Deer Jet (Beijing) Co., Ltd. |
| Club One Air |
| Revesco Aviation Pty Ltd. |
| Global Jet International |
| Executive Jets Asia Pte Ltd. |
| VistaJet |
| Air Charter Service |
| TAG Aviation Asia |
| ExecuJet Aviation Group |
| Others |
Value Chain & Pricing Dynamics
IS-BAO Stage III certification gates both fleet qualification and rate premiums across Asia-Pacific charter corridors, compressing uncertified operators into discount positioning while rewarding compliant rivals with preferential contract access. Singapore CAAS carbon offset mandates layer additional cost burdens onto heavy jet operations, forcing operators to absorb compliance overhead or pass through to corporate clients with lower price elasticity.
Pricing Analysis
Block-hour contracts indexed to Singapore jet kerosene benchmarks dominate Asia-Pacific charter pricing, transmitting fuel volatility directly to per-flight costs. Price differentiation hinges on IS-BAO certification tier and aircraft cabin altitude capability, with Stage III operators commanding substantial premiums over uncertified rivals. Pricing pressure intensifies as dynamic booking platforms aggregate live availability across Sydney-Melbourne-Brisbane corridors, compressing loyalty premiums and forcing real-time rate competitiveness. Corporate clients exhibit lowest price sensitivity for trans-Pacific heavy jet missions, while family offices converting from fractional ownership drive volume growth in light jet segments with higher elasticity.
Supply Chain Analysis
Just-in-time positioning strategies prevail for intra-ASEAN light jet operations, though ultra-long-haul heavy jet fleets require strategic stockpiling of maintenance components given Singapore and Hong Kong MRO concentration. Aircraft manufacturing supply chains draw from the United States, Brazil, and Canada for airframe platforms, while avionics suites source from specialized suppliers in the United States and European Union. Single-source vulnerability concentrates in ExecuJet's Singapore and Hong Kong maintenance capabilities, where competing operators lacking in-house airframe expertise face dependency risk. Distribution runs through direct operator relationships for government and medical evacuation clients, while digital platforms disintermediate traditional travel agent channels in corridor-dense markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across Asia-Pacific charter jet service creates niche opportunities as family office procurement patterns fragment away from long-term management contracts toward asset-light on-demand models.
For Market Incumbents: Compound positioning advantages by accelerating IS-BAO Stage III certification coverage across remaining fleet units before audit timelines extend further. Establish captive SAF procurement pipelines to satisfy Singapore CAAS carbon offset mandates and unlock preferential slot access at Changi. Defend margin structure against platform disintermediation by embedding exclusive maintenance capabilities that competitors cannot replicate without eighteen-month certification cycles. For New Entrants and Emerging Players: Empty leg aggregation platforms represent the most penetrable service-layer gap, as incumbents under-invest in dynamic pricing transparency for repositioning flights. Target Indonesia archipelago connectivity linking Jakarta to secondary islands, where scheduled airline network inadequacy elevates charter substitution economics. Deploy mobile-first booking interfaces with push notification availability to capture Southeast Asian family office demographics fastest. For Investors and Strategic Acquirers: IS-BAO Stage III audit completion reshapes the acquisition landscape by privileging operators with existing certification histories over capital-rich entrants facing eighteen-month delays. Long-term viability concentrates on integrated operators with Malta AOC structures and established intra-regional positioning rights. Monitor CAAC operational specification enforcement as the critical inflection signal indicating demand redirection toward locally AOC-structured operators.| Strategic Initiative | Industry Significance |
|---|---|
| IS-BAO Stage III Certification Acceleration | Stage III audit completion unlocks preferential contract access with Singapore CAAS and CASA Part 135 operators. |
| SAF Procurement Pipeline Establishment | Verified sustainable aviation fuel sourcing satisfies Singapore carbon offset mandates and enables premium positioning. |
| Malta AOC Structure Expansion | Malta air operator certificate structures sustain seamless intra-regional positioning without repeated customs delays. |
| Telemedicine-Cabin Integration | Satellite-enabled remote patient monitoring opens high-yield air ambulance contracts with Australian hospital networks. |
| Dynamic Booking Platform Development | Real-time availability aggregation captures family office demand fragmentation across Sydney-Melbourne-Brisbane corridors. |
Study Parameters
Cross-validation between operator flight-hour disclosures and regulatory certification databases anchors the qualitative findings across this study. Primary interviews with charter operations directors, CAAS compliance officers, family office wealth managers, and MRO facility managers combine with secondary validation from DGCA and CAAC regulatory filings, ICAO Annex 6 Part II standards documentation, and Singapore jet kerosene benchmark data. Bottom-up fleet deployment analysis triangulates against top-down revenue estimates from block-hour contracting patterns.
Sensitivity analysis across fuel price volatility scenarios and certification timeline variations shapes the analytical framework over the projection horizon. Segmentation dimensions modeled include service type, aircraft category, customer application, and booking channel, with additional granularity on CAAC versus CASA versus CAAS regulatory jurisdiction. CAGRs derive from historical flight-hour growth trajectories and penetration rate assumptions for on-demand versus fractional ownership substitution. Industry-specific forecast inputs incorporate IS-BAO audit completion rates and SAF procurement pipeline development timelines.
Underlying assumptions cover sustained ultra-high-net-worth expansion across Southeast Asia and stable enforcement of CAAC operational specifications for foreign-registered aircraft, with deviation risk concentrated in jet fuel supply shocks and pilot certification scarcity inflating crew costs. Forecasts reflect these assumptions with acknowledged uncertainty around bilateral aviation safety agreement evolution. Revision becomes warranted when CAAC reciprocity recognition with DGCA crosses thresholds that materially expand qualified crew pools.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Mobility
Helicopter-Based Transportation Market
Air Mobility
Global Aerodynamics Market
Air Mobility
Flying Jetpacks Market
Air Mobility
Global Flying Cars Market
Air Mobility
Offshore Helicopter Services Market
Air Mobility
North America Offshore Helicopter Services Market
Air Mobility
China Chartered Air Transport Market
Air Mobility
Urban Air Mobility (UAM) Market
Air Mobility
Air Crane Helicopter Market
Air Mobility
Asia Pacific Helicopter Services Market
Air Mobility
Air Transport USM Market
Air Mobility
Off-Shore Helicopters Market
Air Mobility
South America Offshore Helicopter Services Market
Air Mobility
Global Aerial Firefighting Market
Air Mobility
Middle-East and Africa Military Aviation Market
Air Mobility
Advanced Air Mobility Market