
 China Chartered Air Transport Market | 2026-2036
China Chartered Air Transport Market Size, Share, and Industry Trends Forecast 2026-2036
China Chartered Air Transport Market Insights
Subscription-style jet card programs and block-hour memberships are restructuring how charter capacity gets sold in China. Deerjet leverages its Hainan-based fleet to anchor VIP services for resort and MICE corridors. Sino Jet specializes in Greater Bay Area routes, sustaining a network density that competitors struggle to replicate. Air China extends its scheduled airline infrastructure into charter operations, controlling gate access and slot allocation at congested hubs.
Chartered air transport denotes the non-scheduled commercial carriage of passengers or cargo under contract, typically employing aircraft with 6 to 150 seats operating on demand-driven routings with block speeds between 400 and 850 knots. Business charter commands the largest revenue pool among service types as corporate clients prioritize schedule autonomy over commercial airline frequencies. Luxury flights represent the fastest-expanding segment as ultra-high-net-worth households in Shenzhen and Hangzhou seek bespoke cabin configurations and concierge-ground integration.
The Civil Aviation Administration of China governs operator certificates and airworthiness standards while MIIT coordinates low-altitude airspace reform trials across Hunan, Jiangxi, and Anhui provinces. These frameworks shape fleet modernization timelines and determine which regional airports gain charter infrastructure investment. Stakeholders must monitor airspace liberalization pilots and cross-border business aviation treaty negotiations to anticipate where operational margins will widen or compress.
Market Dynamics
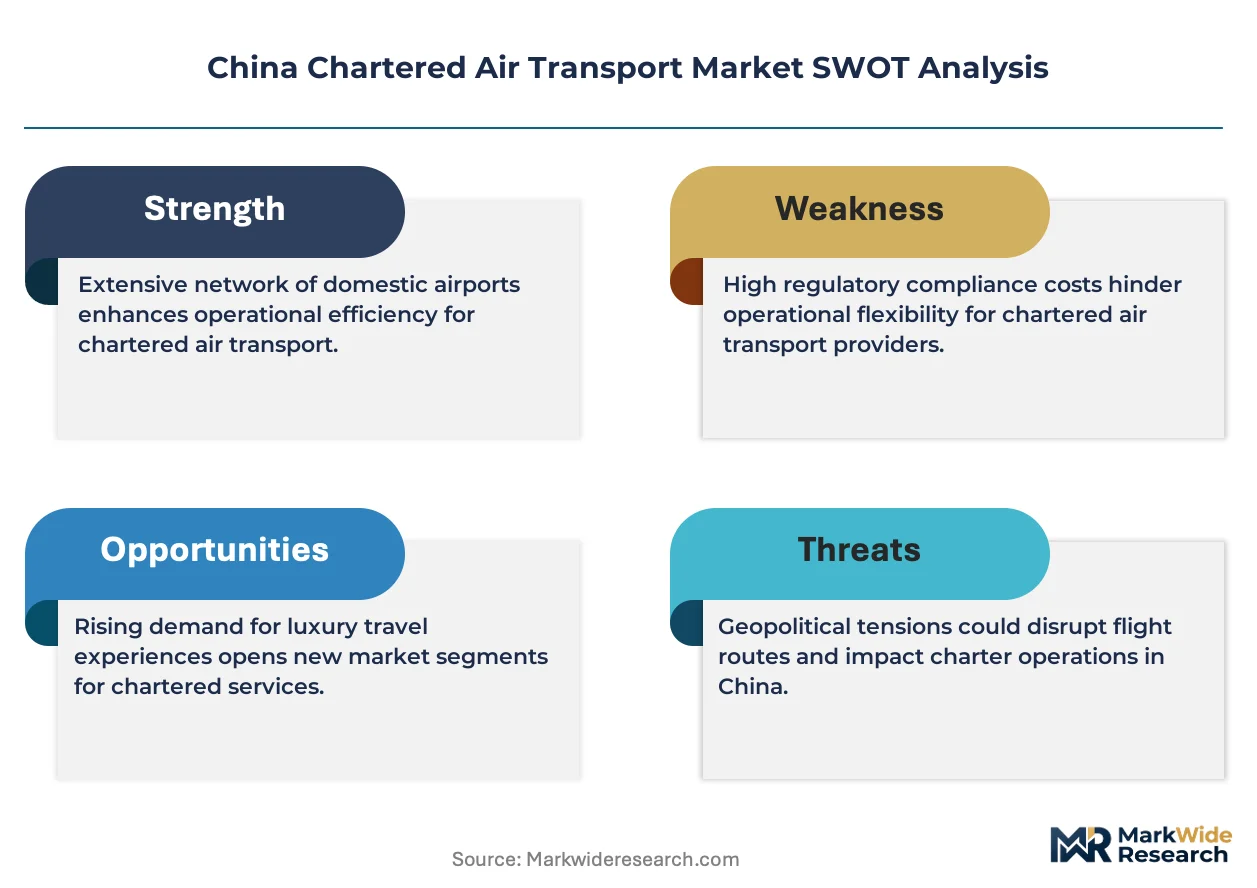
Low-altitude airspace reform trials coordinated by MIIT are fragmenting operational control across provincial aviation authorities, forcing charter operators to navigate competing regulatory interpretations while competing for limited slot allocations at tier-one airports.
Growth Catalysts
- General aviation policy liberalization:CAAC's revised route approval frameworks are reducing lead times for private operators seeking cross-provincial clearances, particularly benefiting the Yangtze River Delta corridor.
- Ultra-high-net-worth household formation:Wealth concentration in Shenzhen and Hangzhou is generating sustained demand for bespoke cabin configurations and integrated concierge-ground services.
- Resort-MICE corridor development:Hainan's duty-free zone expansion and conference infrastructure investments are anchoring VIP charter demand across southern coastal routes.
Market Restraints
- Slot scarcity at congested hubs:Beijing Capital and Shanghai Pudong gate access constraints limit fleet utilization rates for non-scheduled operators competing against state-owned carriers.
- Pilot certification bottlenecks:CAAC's type-rating requirements for business jet aircraft create multi-month crew qualification timelines that compress operational flexibility.
- Jet fuel price volatility:Import-dependent kerosene supply exposed to Brent crude fluctuations erodes block-hour margin predictability for fixed-price contract holders.
Strategic Opportunities
- Greater Bay Area network density:Underdeveloped inter-city connectivity between Zhuhai, Dongguan, and Macau presents whitespace for point-to-point shuttle services bypassing congested Hong Kong airspace.
- Carbon-neutral aviation fuels:China's dual carbon goals are accelerating SAF blending mandates that early-adopting operators can leverage for corporate ESG contract premiums.
- Subscription membership models:Block-hour jet card programs are displacing traditional ad-hoc charter bookings among manufacturing headquarters clusters in Jiangsu province.
Industry Challenges
- Maintenance technician scarcity:Specialized airframe and avionics expertise for Gulfstream and Dassault fleets concentrates in Beijing and Shanghai, straining regional MRO coverage.
- Legacy air traffic management integration:New entrants must interface with CAAC's fragmented radar and communication systems that prioritize scheduled commercial traffic.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Chartered Air Transport Market |
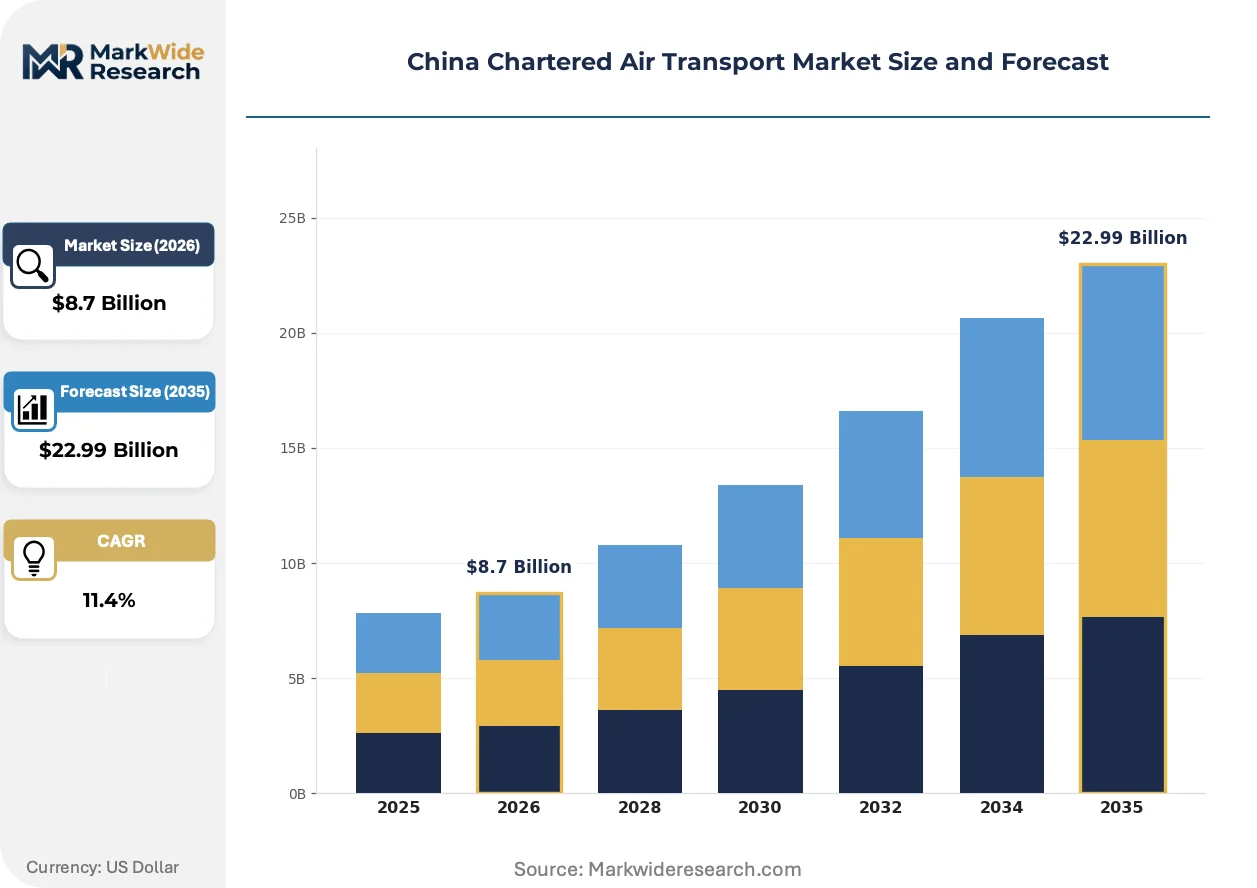
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Luxury Flights, Cargo Transport, Medical Evacuations, Business Charter Customer Type: Corporate Clients, Government Agencies, Private Individuals, Non-Profit Organizations Aircraft Type: Jet Aircraft, Turboprop, Helicopters, Regional Jets Booking Channel: Online Platforms, Travel Agencies, Direct Booking, Brokers |
| Companies Covered | Amber Aviation, Baa Jet Management Ltd., Beijing Airlines, China Southern Airlines General Aviation, Deerjet, Sino Jet, Metrojet, Asia Jet, Air China, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Chartered Air Transport Market Trends and Innovations
Digital booking platforms and predictive demand algorithms are compressing charter procurement cycles while reshaping how fleet capacity gets allocated across seasonal demand peaks in China's coastal economic zones.
Artificial intelligence-driven route optimization is rewriting how operators schedule empty-leg positioning flights. Corporate travel managers at manufacturing headquarters in Suzhou and Ningbo are adopting these tools to reduce deadhead ratios. The technology is compressing yield management cycles from weekly to daily adjustments, forcing traditional brokers to automate or exit.
MIIT's low-altitude airspace reform trials across Hunan, Jiangxi, and Anhui provinces are redrawing operational boundaries for sub-6,000-meter flights. Charter operators must now secure dual clearances from military and civil aviation authorities, extending pre-flight preparation timelines. The policy is hitting light-jet segments hardest, as these aircraft depend on flexible routing through previously restricted corridors.
Corporate procurement departments are consolidating preferred operator relationships into multi-year framework agreements with volume guarantees. Travel managers at private equity firms and technology conglomerates are displacing spot-market charter bookings with negotiated rate cards. This concentration is most visible in Shanghai, where headquarters clustering allows operators to achieve daily minimum utilization thresholds across shared aircraft pools.
China Chartered Air Transport Market Segmentation
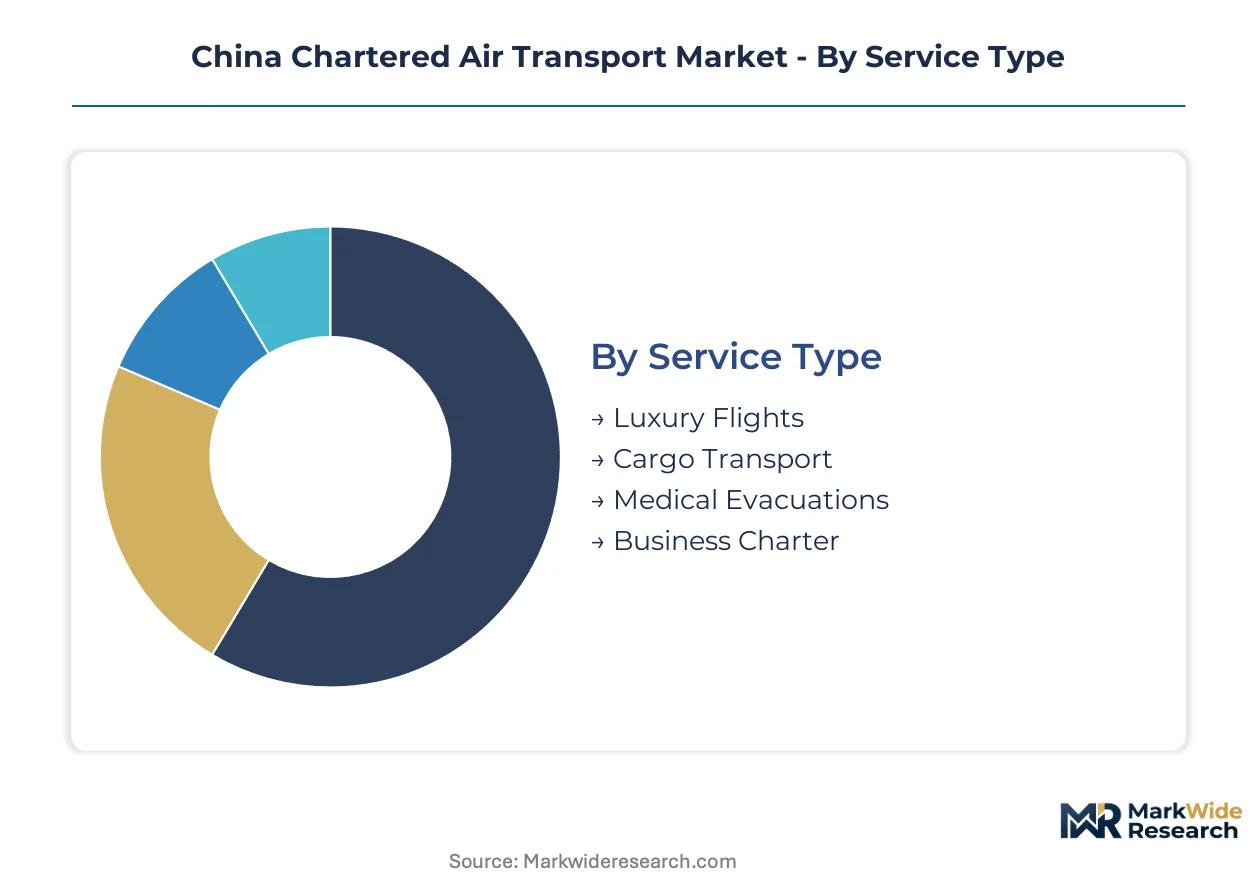
Segmentation reveals how CAAC certification burdens and MIIT airspace classifications fragment operational economics across China's chartered aviation ecosystem. Distinct regulatory pathways govern each service tier, aircraft category, and customer channel, creating divergent margin profiles and capital intensity requirements.
Service Type:
Business Charter demands CAAC Part 135 operator certificates with enhanced pilot experience minimums, while Medical Evacuations require dual approvals from health and aviation regulators. Luxury Flights face lighter certification loads but heavier cabin customization inspections.
- Business Charter:Non-scheduled commercial carriage employing 6-150 seat aircraft operating on demand-driven routings with block speeds between 400 and 850 knots. Corporate headquarters clusters in Suzhou and Ningbo sustain daily minimum utilization thresholds across shared aircraft pools, prioritizing schedule autonomy over commercial airline frequencies.
- Luxury Flights:Bespoke cabin configurations with concierge-ground integration serving ultra-high-net-worth households. Shenzhen and Hangzhou wealth concentration generates sustained demand for personalized interiors and dedicated ground handling, expanding most quickly as duty-free zone development in Hainan anchors southern coastal VIP corridors.
- Cargo Transport:Contractual freight carriage under Part 135 variants with specialized airworthiness directives for payload configurations.
- Medical Evacuations:Air ambulance operations requiring CAAC medical crew certifications and hospital landing zone clearances.
Business Charter sits at the top of the volume ranking, with Luxury Flights climbing the fastest.
Customer Type:
Cost tier stratification separates procurement patterns: corporate clients negotiate multi-year framework agreements with volume guarantees, while private individuals purchase ad-hoc or through subscription memberships.
- Corporate Clients:Manufacturing headquarters and private equity firms consolidating preferred operator relationships into negotiated rate cards. Travel managers at technology conglomerates displace spot-market bookings with framework agreements, achieving price predictability through committed block-hour structures.
- Private Individuals:High-net-worth households purchasing through jet card programs or direct operator relationships. Yangtze River Delta wealth concentration drives subscription-style membership adoption, with block-hour structures restructuring how charter capacity gets sold across Jiangsu-Zhejiang corridors.
- Government Agencies:State-owned enterprise travel departments and provincial officials requiring priority slot allocations at congested hubs.
- Non-Profit Organizations:Humanitarian and diplomatic missions operating under bilateral aviation treaties with simplified clearance protocols.
Corporate Clients dominate committed revenue streams, with Private Individuals gaining share fastest through membership model proliferation.
Aircraft Type:
Volume concentration and margin profiles diverge sharply: Jet Aircraft command premium positioning yields while Turboprop segments absorb regulatory friction from MIIT low-altitude airspace trials.
- Jet Aircraft:Business jets and narrow-body configurations with 400-850 knot cruise speeds requiring type-rated flight crews under CAAC standards. Gulfstream and Dassault fleets concentrate specialized MRO expertise in Beijing and Shanghai, straining regional maintenance coverage for operators outside tier-one hubs.
- Helicopters:Rotary-wing operations below 6,000 meters navigating dual military-civil clearances under MIIT reform trials. Light-jet dependency on flexible routing through previously restricted corridors hits this segment hardest as provincial aviation authorities fragment operational control.
- Turboprop:Propeller-driven aircraft serving short-haul routes with lower fuel burn but extended pre-flight preparation timelines.
- Regional Jets:50-100 seat configurations bridging charter and scheduled service economics with shared crew type ratings.
Jet Aircraft anchor fleet investment priorities, with Helicopters steepest expansion trajectory as urban air mobility concepts mature.
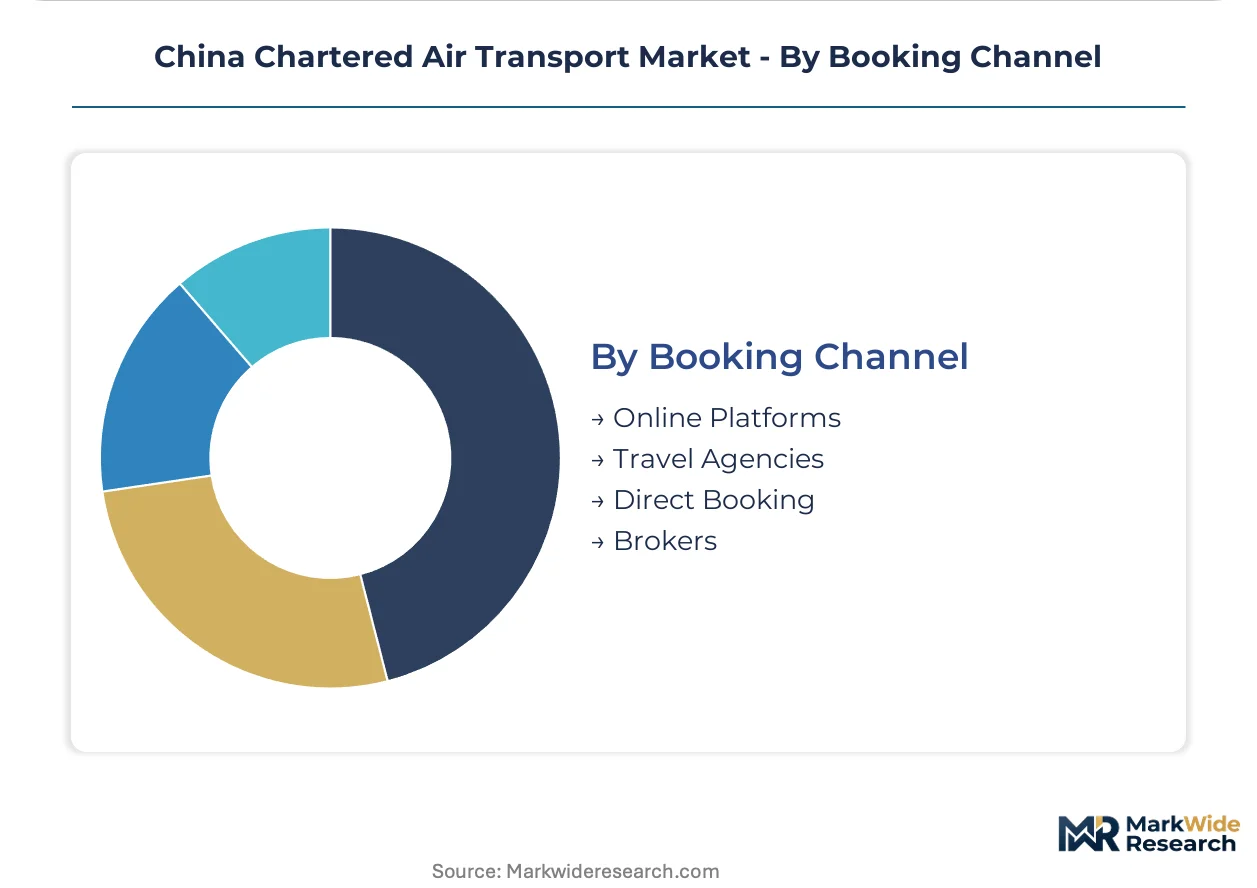
Booking Channel:
Digital penetration and customer acquisition economics separate channel economics: online platforms compress procurement cycles while broker networks retain complex itinerary coordination.
- Online Platforms:Digital booking interfaces with predictive demand algorithms allocating fleet capacity across seasonal peaks. AI-driven route optimization tools reduce deadhead ratios for corporate travel managers, compressing yield management cycles from weekly to daily adjustments.
- Brokers:Intermediary networks coordinating multi-leg itineraries and cross-operator capacity pooling. Traditional brokers face automation pressure as platform adoption displaces manual procurement workflows across manufacturing headquarters clusters.
- Direct Booking:Operator-owned sales channels capturing full margin on repeat corporate relationships.
- Travel Agencies:Consolidators packaging charter with ground services for MICE and resort corridor demand.
Online Platforms lead transaction volume growth, with Direct Booking retaining the highest margin capture on established accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between coastal and interior provinces is redistributing chartered aviation capacity as operators chase lower compliance costs and faster airspace clearances outside Beijing-Shanghai regulatory orbits.
Yangtze River Delta
Corporate headquarters clustering in Suzhou and Ningbo sustains daily minimum utilization thresholds across shared aircraft pools. CAAC's revised Part 135 operator certificates apply streamlined cross-provincial clearances here. Shanghai Pudong slot scarcity forces operators to reposition through satellite airports in Hangzhou and Nanjing.
Pearl River Delta
Ultra-high-net-worth household formation in Shenzhen generates sustained demand for bespoke cabin configurations. MIIT low-altitude airspace reform trials fragment operational control between Guangdong provincial authorities and military coordinators. Zhuhai and Dongguan present whitespace for point-to-point shuttle services bypassing congested Hong Kong airspace.
Beijing-Tianjin-Hebei
Government agencies and state-owned enterprise travel departments anchor priority slot allocations at congested hubs. CAAC's type-rating requirements for business jet aircraft create multi-month crew qualification timelines. Beijing Capital gate access constraints limit fleet utilization rates for non-scheduled operators competing against Air China's scheduled infrastructure.
Hainan Island
Duty-free zone expansion and conference infrastructure investments anchor VIP charter demand across southern coastal routes. MIIT coordinates low-altitude airspace reform trials with simplified military-civil clearance protocols here. Sanya and Haikou resort-MICE corridors concentrate Deerjet's Hainan-based fleet deployment.
Sichuan-Chongqing
Manufacturing headquarters clusters in Chengdu drive subscription-style jet card program adoption among corporate procurement departments. Provincial aviation authorities interpret CAAC general aviation policies with varying stringency. Chongqing Jiangbei International Airport gains charter infrastructure investment as operators seek alternatives to coastal slot scarcity.
China Chartered Air Transport Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with state-affiliated carriers leveraging scheduled airline infrastructure while independent operators build niche density in underserved corridors. The vendor base concentrates around three strategic archetypes: legacy flag carriers extending into charter operations, Hainan-based resort specialists, and Greater Bay Area network builders. Consolidation pressure favors multi-year framework agreements with volume guarantees over spot-market brokerage. Geographic expansion into interior provinces and vertical integration into ground handling services represent the dominant competitive moves.
Among state-affiliated operators, Air China exemplifies the infrastructure-leverage archetype through gate access and slot allocation control at congested hubs. Deerjet occupies a position within the resort-corridor specialist tier, anchoring VIP services through Hainan-based fleet positioning. Sino Jet represents the regional-density archetype, sustaining network concentration in Greater Bay Area routes that competitors struggle to replicate. These three patterns illustrate how regulatory relationships and geographic anchoring shape competitive positioning across China's fragmented charter aviation ecosystem.
| Leading Market Players |
|---|
| Amber Aviation |
| Baa Jet Management Ltd. |
| Beijing Airlines |
| China Southern Airlines General Aviation |
| Deerjet |
| Sino Jet |
| Metrojet |
| Asia Jet |
| Air China |
| Others |
Pricing and Supply Chain Analysis
Captive fleet ownership by state-affiliated carriers anchors supply-side pricing power while compressing margin capture for independent operators dependent on third-party MRO networks and fuel procurement. CAAC's slot allocation frameworks at Beijing Capital and Shanghai Pudong reinforce this asymmetry, allowing infrastructure-controlling incumbents to command premium positioning yields while non-scheduled competitors absorb higher deadhead costs.
Pricing Analysis
Direct-to-corporate contract structures dominate revenue capture, with multi-year framework agreements displacing spot-market brokerage across manufacturing headquarters clusters. Price differentiation rests on CAAC certification tier and dedicated ground handling bundling, with Part 135 operators capturing premium yields over ad-hoc charter brokers. Cost compression in light-jet segments is intensifying because MIIT's dual-clearance requirements extend pre-flight preparation timelines. Corporate procurement departments demonstrate lowest price sensitivity, while private individual jet card subscribers exhibit highest elasticity to block-hour rate adjustments.
Supply Chain Analysis
Jet fuel logistics costs from import-dependent kerosene supply expose operators to Brent crude volatility, eroding margin predictability for fixed-price contract holders. Aircraft manufacturing concentrates in USA, France, and Brazil, with Gulfstream and Dassault fleets drawing from specialized MRO expertise pools in Beijing and Shanghai. Single-source vulnerability concentrates in avionics and engine component supply chains. Distribution runs through operator-owned sales channels and digital booking platforms, with broker networks retaining complex itinerary coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's chartered air transport market compounds steadily as ultra-high-net-worth household formation in Shenzhen and Hangzhou generates durable demand for bespoke cabin configurations and concierge-ground integration.
For Market Incumbents: Acquire dedicated MRO capabilities to reduce dependency on Beijing and Shanghai technical expertise pools. Secure long-term slot lease arrangements at satellite airports to bypass congestion at tier-one hubs. Emerging digital booking platforms threaten traditional broker margins, necessitating automation investment or partnership. Backward integration into fuel hedging instruments protects against kerosene price volatility eroding block-hour contract profitability. For New Entrants and Emerging Players: Online platform penetration offers the lowest customer acquisition cost route into corporate procurement departments. Target Greater Bay Area point-to-point shuttle services between Zhuhai, Dongguan, and Macau as the most penetrable whitespace. Manufacturing headquarters clusters in Jiangsu province present subscription membership model opportunities. Deploy AI-driven route optimization tools to compress yield management cycles and displace incumbent broker relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where CAAC certification burdens and pilot type-rating bottlenecks create operational scale advantages. The market supports long-term viability for operators achieving daily minimum utilization thresholds across shared aircraft pools. Acquisition targets should demonstrate regional network density in underserved corridors. Monitor MIIT low-altitude airspace reform trial expansions as the inflection signal for light-jet segment margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Network Density Buildout | Sino Jet's Greater Bay Area concentration demonstrates how corridor-specific scale defends against infrastructure-leveraged competitors. |
| Backward Integration into MRO Services | Captive maintenance capabilities reduce dependency on Beijing-Shanghai technical expertise concentration and compress turnaround times. |
| Subscription Membership Model Launch | Block-hour jet card programs restructure procurement patterns across Jiangsu-Zhejiang manufacturing headquarters clusters. |
| Sustainable Aviation Fuel Certification | Early SAF adoption positions operators for corporate ESG contract premiums under China's dual carbon goals. |
| Satellite Airport Slot Securement | Hangzhou and Nanjing repositioning capacity bypasses Shanghai Pudong congestion constraints limiting fleet utilization. |
Research Methodology
Direct dialogue with charter operations directors, CAAC regulatory affairs specialists, corporate travel managers at manufacturing headquarters, and MRO technical directors grounded qualitative insights. Secondary validation drew from CAAC operator certificate filings, MIIT airspace reform trial documentation, Civil Aviation Administration statistical yearbooks, and customs jet fuel import records. Bottom-up fleet deployment analysis and top-down revenue pool estimation were triangulated against cross-referenced primary interview transcripts.
Segmentation outputs across service type, customer channel, aircraft category, and regional corridor were generated through structured demand modeling. CAGRs were derived from trend extrapolation adjusted for policy intervention timing and airspace liberalization pilot expansion schedules. Forecast inputs incorporated CAAC Part 135 certification queue lengths, MIIT low-altitude clearance timeline assumptions, and ultra-high-net-worth household formation trajectories across coastal economic zones.
The model assumes a particular technology adoption path for AI-driven route optimization and digital booking platforms; alternative pathways for automation deployment would alter the competitive dynamics between incumbent operators and platform-based entrants. Forecasts reflect assumptions regarding CAAC regulatory enforcement consistency and military-civil aviation coordination frameworks. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Mobility
Asia-Pacific Charter Jet Service Market
Air Mobility
Advanced Air Mobility Market
Air Mobility
Urban Autonomous Air Mobility Market
Air Mobility
Flying Taxi Market
Air Mobility
Parabolic Flight Tourism Market
Air Mobility
Flying Jetpacks Market
Air Mobility
Global Flying Cars Market
Air Mobility
Airborne Pods Market
Air Mobility
Hang Glider Market
Air Mobility
Helicopter-Based Transportation Market
Air Mobility
Air Transport USM Market
Air Mobility
North America Offshore Helicopter Services Market
Air Mobility
Urban Air Mobility (UAM) Market
Air Mobility
Global Aerodynamics Market
Air Mobility
Middle-East and Africa Military Aviation Market
Air Mobility
Middle East and Africa General Aviation Market