
 UK Aviation Market | 2026-2036
UK Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
UK Aviation Market Outlook
Next-generation engine efficiency standards are redrawing procurement priorities across UK aviation. Rolls-Royce anchors the widebody propulsion segment through its Trent family R&D intensity. BAE Systems dominates military aerospace with sovereign manufacturing scale across Warton and Samlesbury. GKN Aerospace specializes in composite wing structures and engine components, extending its supplier footprint into multiple OEM tier-one positions.
UK aviation encompasses the design, manufacture, operation, and servicing of fixed-wing and rotary-wing aircraft with maximum take-off weights exceeding 5,700 kg for commercial certification, incorporating airframe structures, propulsion systems, and integrated avionics for passenger transport, freight movement, and defence applications. Commercial aircraft occupies the largest value pool given narrowbody and widebody renewal cycles, while business jets generate premium margins through bespoke cabin configurations and long-range performance specifications. Engine technologies within the technology dimension is concentrating investment as OEMs pursue hybrid-electric architectures and hydrogen combustion pathways to meet emissions benchmarks.
The UK Civil Aviation Authority enforces airworthiness certification and operational safety standards that shape product development timelines for domestic manufacturers. The Jet Zero Council framework and corresponding SAF mandates from the Department for Transport are restructuring fuel supply chains and fleet transition planning. EASA alignment post-Brexit continues influencing design approval reciprocity and cross-border maintenance protocols. Stakeholders must weigh sovereign capability investment against EU market access integration as regulatory divergence risk evolves.
Market Dynamics
Jet Zero Council decarbonisation mandates are restructuring UK aviation capital allocation, forcing fleet operators and OEMs to accelerate sustainable fuel infrastructure and hybrid-electric propulsion R&D timelines ahead of 2040 net-zero commitments.
Growth Catalysts
- SAF Mandate Expansion:The Department for Transport's blending requirements are pulling investment into domestic sustainable aviation fuel production facilities at Immingham and Stanlow.
- Narrowbody Renewal Cycles:Airlines are retiring aging A320ceo and 737NG fleets, creating replacement demand for next-generation single-aisle aircraft with 15% fuel efficiency gains.
- Composite Manufacturing Scale-Up:Automated fibre placement technologies are reducing wing structure production costs at Bristol and Broughton aerospace clusters.
Market Restraints
- SAF Feedstock Competition:Limited UK waste oil and agricultural residue supply is constraining sustainable aviation fuel output volumes against mandated targets.
- Propulsion Supplier Concentration:Widebody engine sourcing depends on a single domestic manufacturer, creating vulnerability in Trent family delivery schedules.
- Skills Pipeline Compression:Aerospace engineering apprenticeship completions have lagged retirement rates across Lancashire and South West manufacturing bases.
Strategic Opportunities
- Scottish Hydrogen Aviation:Highlands and Islands Airports Limited is positioning remote airfields as testbeds for hydrogen combustion and fuel-cell regional aircraft operations.
- Military-Commercial Technology Transfer:BAE Systems' Tempest programme is creating spillover opportunities in advanced materials and thermal management for civil applications.
- Maintenance Digitalisation:Predictive analytics platforms are enabling unbundled engine health monitoring services sold separately from traditional MRO contracts.
Industry Challenges
- Certification Timeline Compression:Novel propulsion architectures face extended validation periods at the UK Civil Aviation Authority as airworthiness standards evolve for electric and hydrogen systems.
- Legacy Fleet Stranding Risk:Operators must balance accelerated retirement schedules against residual asset values and financing covenant renegotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Aviation Market |
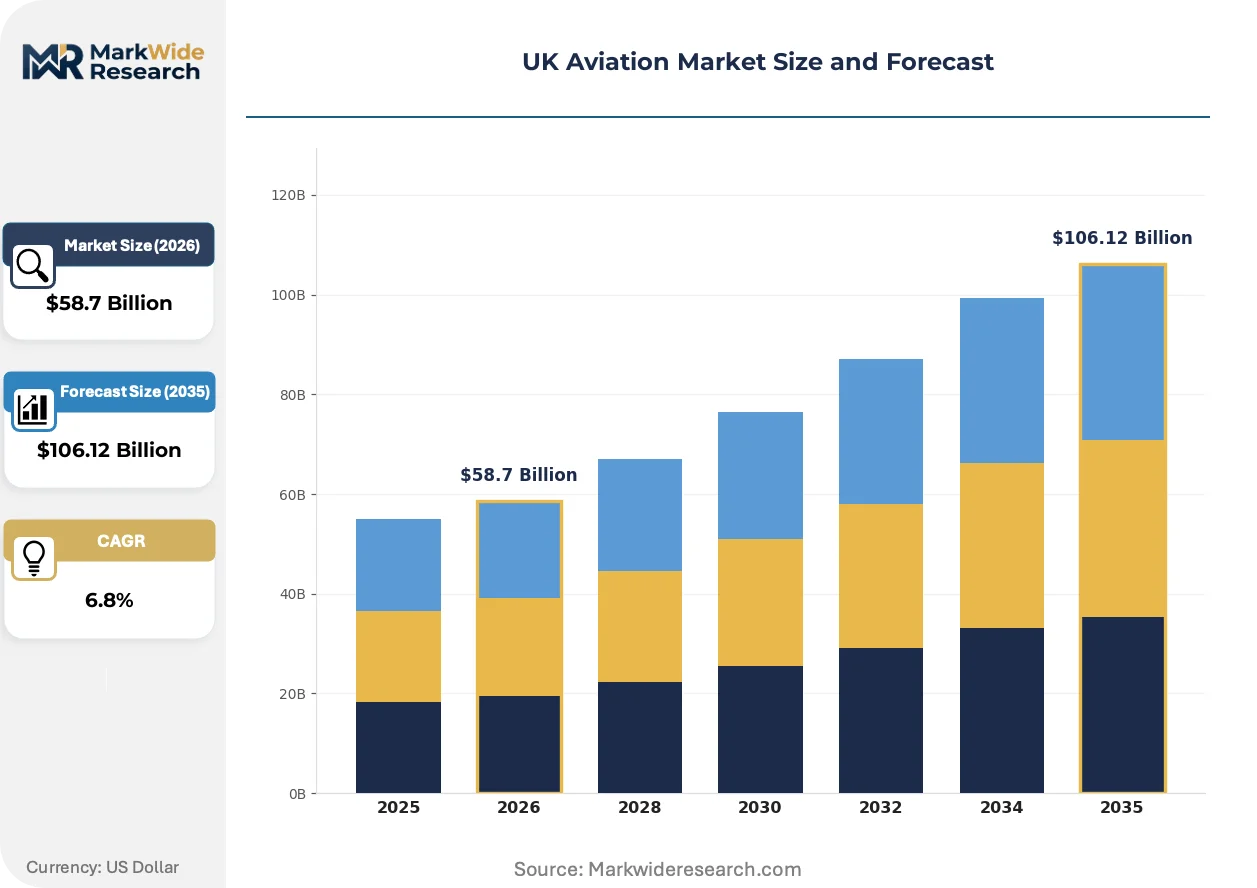
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial Aircraft, Cargo Aircraft, Business Jets, Helicopters End User: Airlines, Charter Services, Government Agencies, Private Owners Technology: Avionics Systems, Flight Management Systems, Engine Technologies, Airframe Structures Service Type: Maintenance, Repair, and Overhaul, Ground Services, Flight Training, Consulting |
| Companies Covered | Airbus SE, BAE Systems plc, Rolls-Royce, Leonardo S.p.A, The Boeing Company, Lockheed Martin Corporation, GKN Aerospace, GE Aviation, Thales, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Aviation Market Strategic Shifts
Technology trajectories in UK aviation are converging on propulsion system transformation, with regulatory pressure and supply chain reconfiguration acting as simultaneous accelerants and constraints on product development cycles.
Open-rotor engine architectures are decomposing conventional turbofan dominance in narrowbody propulsion. Rolls-Royce and its UltraFan programme partners are testing geared fan systems with 25% efficiency improvement potential. This technology is decomposing the installed base of legacy Trent and BR700 powerplants across short-haul operator fleets.
The Jet Zero Council framework is mandating 10% sustainable aviation fuel blending by 2030, compelling fuel suppliers to secure waste-based feedstock contracts. Refineries at Humber and Merseyside are retooling for hydroprocessed esters and fatty acids production. Domestic airlines are pre-purchasing SAF volumes to hedge against anticipated certificate price premiums.
Engine aftermarket contracts are fragmenting from bundled power-by-the-hour arrangements toward component-level service unbundling. Lessors and low-cost carriers are negotiating separate line replaceable unit coverage and labour provision agreements. This restructuring is most pronounced among England-based narrowbody operators managing mixed OEM fleets.
UK Aviation Market Segmentation
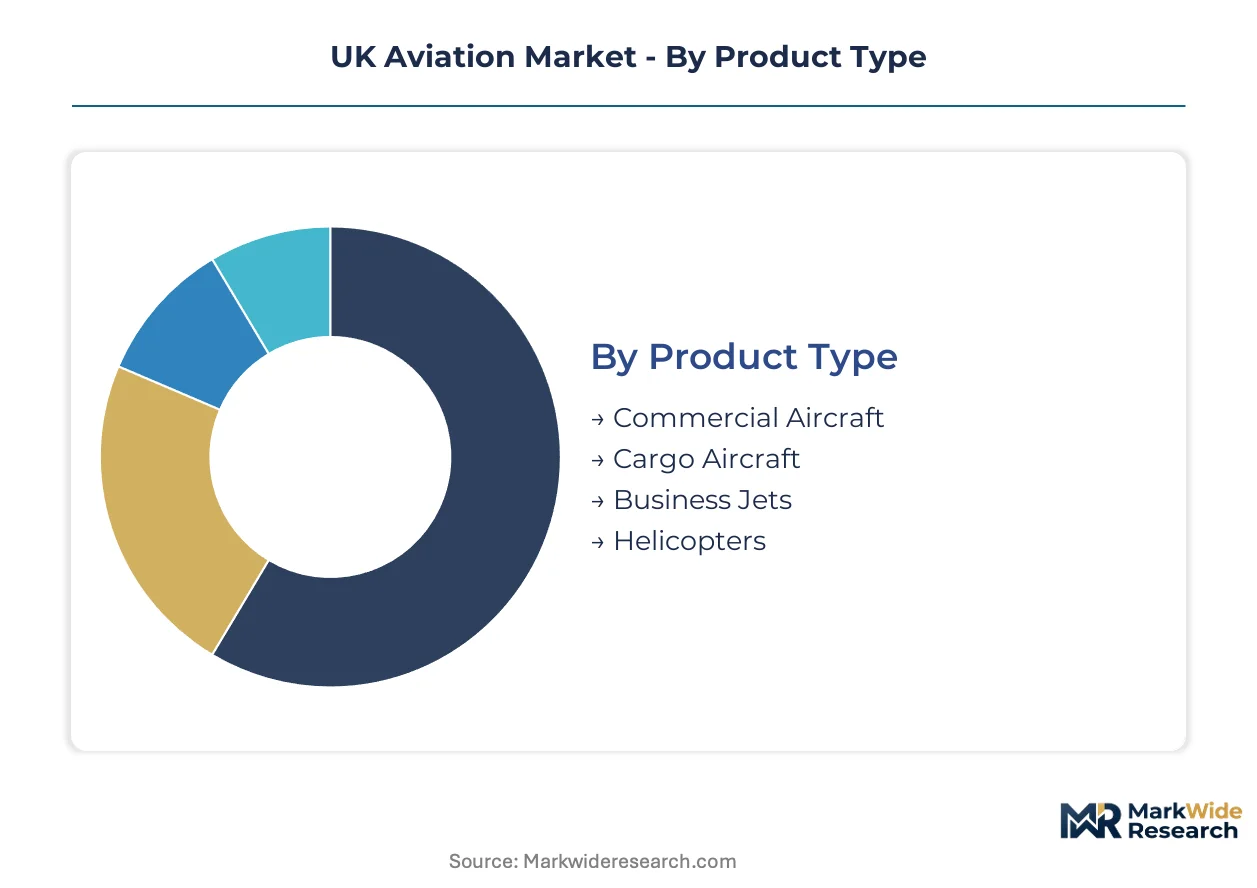
Segmentation in UK aviation reveals how procurement priorities split between domestic fleet renewal and export manufacturing contracts. Each dimension tracks different value capture mechanisms across Bristol's aerospace corridor, Lancashire's military production bases, and London's charter service hubs.
Product Type:
Domestic demand concentrates on narrowbody replacements for England-based carriers, while export manufacturing dominates widebody and defence platforms. Scotland's remote connectivity needs sustain rotary-wing production at Prestwick.
- Commercial Aircraft:Narrowbody configurations account for the majority of UK operator procurement, driven by Jet Zero Council efficiency mandates and slot-constrained airport operations. Airlines at Heathrow and Gatwick prioritize single-aisle replacements with 15% fuel burn improvements.
- Business Jets:Long-range cabin configurations serve London's charter services and private ownership base. Bespoke interiors and transatlantic capability specifications command premium positioning in Farnborough's service ecosystem.
- Cargo Aircraft:Freighter conversions support East Midlands and Stansted cargo operators handling e-commerce volume growth.
- Helicopters:North Sea energy logistics and Scottish island connectivity sustain rotary-wing demand at Aberdeen and Inverness bases.
Commercial aircraft commands the established base. The steepest expansion runs through business jets as charter services modernize fractional ownership fleets.
End User:
Procurement scale and technology requirements diverge sharply between volume-driven airline operators and specification-sensitive private clients. Government defence contracts impose sovereign manufacturing clauses distinct from commercial terms.
- Airlines:Fleet standardization pressures dominate procurement, with narrowbody commonality reducing training and inventory costs. British Airways and EasyJet drive renewal cycles through sale-leaseback structures.
- Charter Services:Flexibility specifications outweigh unit economics, with cabin reconfiguration capability and rapid deployment readiness as core requirements. London's premium charter market sustains bespoke completions demand.
- Government Agencies:Royal Air Force procurement through BAE Systems maintains sovereign combat air capability at Warton and Samlesbury.
- Private Owners:Fractional ownership models concentrate demand among high-net-worth individuals in Southeast England.
Airlines anchor volume procurement. Charter services are gaining share fastest as post-pandemic corporate travel patterns shift toward on-demand models.
Technology:
Investment intensity clusters on propulsion and avionics, where regulatory mandates and operational efficiency converge. Airframe manufacturing retains scale advantages in composite wing production.
- Engine Technologies:Hybrid-electric architectures and hydrogen combustion pathways absorb the majority of UK aviation R&D expenditure. Rolls-Royce's UltraFan programme targets 25% efficiency gains over current turbofan installations.
- Avionics Systems:Integrated flight deck upgrades dominate retrofit demand as operators extend legacy fleet service lives. CAA certification timelines for synthetic vision and connected aircraft systems shape product roadmaps.
- Flight Management Systems:Trajectory optimization software reduces fuel burn on transatlantic routes from Heathrow and Manchester.
- Airframe Structures:Automated fibre placement at Bristol and Broughton lowers composite wing production costs for Airbus programmes.
Engine technologies command the established base. Avionics systems are climbing the fastest as retrofit demand accelerates ahead of next-generation platform introductions.
Service Type:
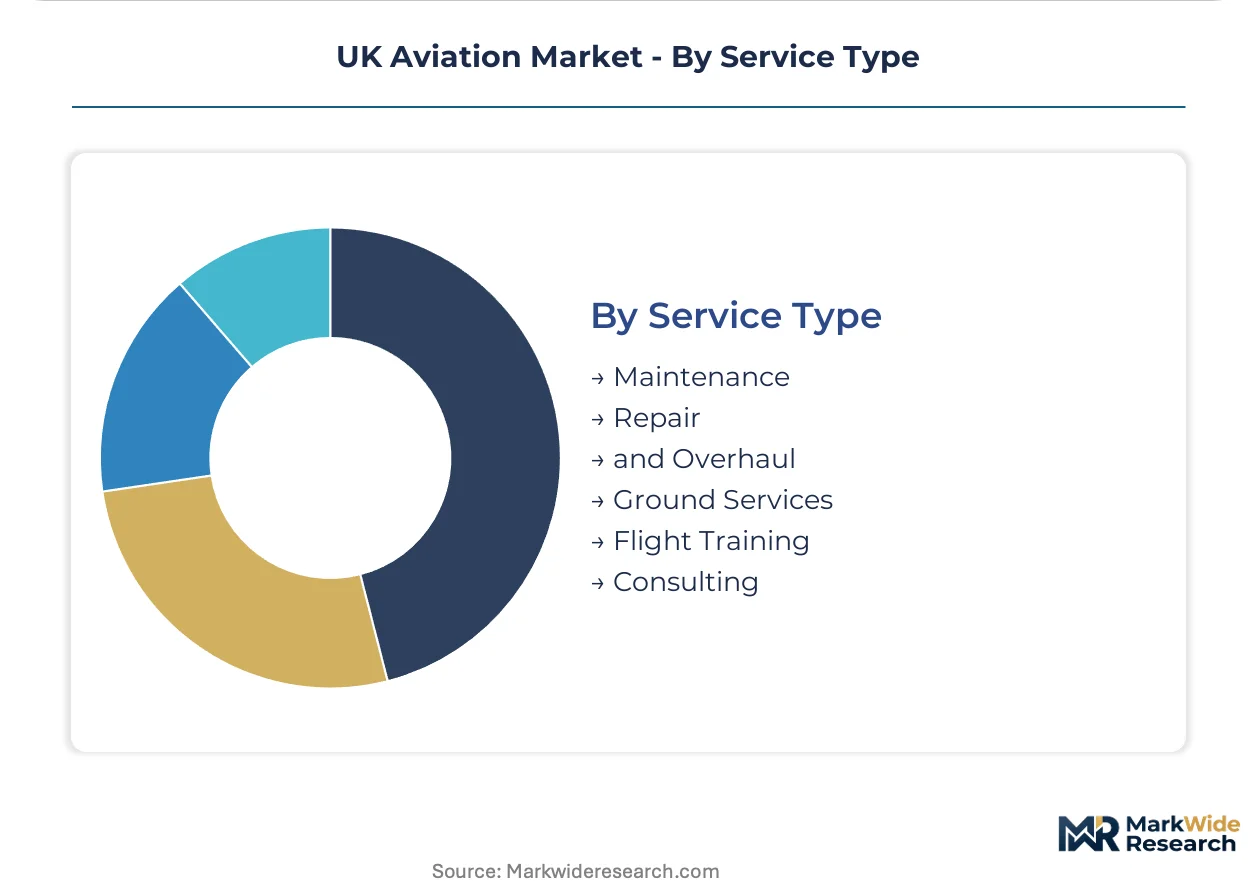
Maintenance contracts fragment from bundled power-by-the-hour arrangements toward component-level unbundling. Training capacity constraints limit expansion at Cranfield and L3 Harris academies.
- Maintenance, Repair, and Overhaul:Engine overhaul concentration at Derby and Cardiff facilities supports Trent family installed base. Predictive analytics platforms enable unbundled health monitoring services sold separately from labour provision.
- Ground Services:Turnaround efficiency investments at Heathrow and Gatsted handle slot-constrained operations. Electric ground support equipment mandates reshape equipment procurement.
- Flight Training:Simulator capacity at Crawley and Southampton struggles against pilot demand recovery timelines.
- Consulting:Fleet transition planning services expand as operators navigate SAF procurement and carbon offset strategies.
Maintenance, repair, and overhaul commands the established base. Consulting is expanding most quickly as fleet decarbonisation complexity drives advisory demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scottish island operators show the highest price elasticity, deferring fleet renewal until SAF costs normalize, while London charter clients absorb premium pricing for bespoke cabin configurations without volume reduction.
London and Southeast England
Heathrow slot constraints drive narrowbody procurement with 15% fuel efficiency specifications. The UK Civil Aviation Authority enforces airworthiness certification timelines that shape product development for domestic manufacturers. Farnborough's service ecosystem concentrates long-range business jet completions and fractional ownership management.
South West England
Bristol's aerospace corridor anchors composite wing production through automated fibre placement scale-up. Jet Zero Council mandates pull investment into sustainable aviation fuel infrastructure at regional facilities. GKN Aerospace extends its supplier footprint across multiple OEM tier-one positions from Bristol manufacturing bases.
North West England
Lancashire's military production bases sustain sovereign combat air capability through BAE Systems procurement. Skills pipeline compression challenges aerospace engineering apprenticeship completions against retirement rates. Warton and Samlesbury manufacturing facilities concentrate advanced materials and thermal management R&D.
Scotland
Highlands and Islands Airports Limited positions remote airfields as hydrogen combustion testbeds for regional aircraft operations. North Sea energy logistics and island connectivity sustain rotary-wing demand at Aberdeen and Inverness bases. Prestwick maintains rotary-wing production capacity for remote connectivity applications.
Wales
BAE Systems' Broughton facility anchors Airbus wing assembly with composite manufacturing scale-up. The Department for Transport's SAF blending requirements reshape fuel supply chain investments. Welsh aerospace clusters concentrate on engine component production and airframe structure assembly.
UK Aviation Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across UK aviation, with propulsion specialists commanding R&D premiums while airframe fabricators compete on production scale. The market structure consolidates around sovereign defence contractors and multinational OEM tier-one suppliers. Three archetypes dominate: integrated defence-aerospace conglomerates, specialist propulsion engineers, and composite structure manufacturers. Competitive moves concentrate on strategic partnerships for hybrid-electric architectures and vertical integration into sustainable fuel supply chains.
Among UK-based defence-aerospace conglomerates, BAE Systems plc and Rolls-Royce occupy positions spanning military procurement and commercial propulsion respectively. GKN Aerospace represents the specialist tier-one supplier archetype, anchoring composite wing structures across multiple OEM programmes. These three entities exemplify how sovereign capability investment competes against EU market access integration as regulatory divergence risk evolves.
| Leading Market Players |
|---|
| Airbus SE |
| BAE Systems plc |
| Rolls-Royce |
| Leonardo S.p.A |
| The Boeing Company |
| Lockheed Martin Corporation |
| GKN Aerospace |
| GE Aviation |
| Thales |
| Others |
Value Chain & Pricing Dynamics
Composite wing manufacturing scale at Bristol and Broughton generates 15-20% unit cost advantages that simultaneously concentrate supplier power and establish price floors for Airbus procurement contracts. This scale dynamic locks tier-two fabricators out of narrowbody wing structures while forcing charter operators to absorb premium pricing for bespoke cabin completions where automated production offers no leverage.
Pricing Analysis
The UK Civil Aviation Authority's airworthiness certification timelines dictate the pricing tier structure across aftermarket services, separating predictive analytics-enabled unbundled contracts from traditional power-by-the-hour bundles. Three-tier pricing structure across premium, standard, and economy levels tracks engine health monitoring sophistication, with Rolls-Royce's Trent family commanding brand premiums at Derby overhaul facilities. Cost compression in narrowbody MRO is intensifying because low-cost carriers negotiate component-level labour provision separately from parts coverage. Regional airlines operating Scottish island routes show highest price sensitivity, deferring avionics retrofits until CAA mandates force compliance.
Supply Chain Analysis
Inventory buffers for titanium alloy forgings and carbon fibre prepregs now stretch 8-12 months beyond pre-pandemic baselines, exposing just-in-time wing assembly lines at Broughton to schedule volatility. UK aviation draws from US titanium sponge, Japanese carbon fibre, and German machine tool controllers as anchor inputs. Single-source vulnerability concentrates in widebody engine castings where Derby's foundry capacity limits Trent family output expansion. Distribution runs through Heathrow and East Midlands cargo hubs for inbound aerospace components, with final assembly concentrated at Bristol, Broughton, and Samlesbury manufacturing clusters.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK aviation market is recovering through narrowbody fleet renewal cycles, with Jet Zero Council efficiency mandates accelerating replacement demand ahead of residual value depreciation curves.
For Market Incumbents: Secure long-term sustainable aviation fuel offtake agreements at Immingham and Stanlow refineries before feedstock competition intensifies against Department for Transport blending mandates. Lock in composite wing supply contracts at Bristol through capacity reservation deposits, defending against emerging Asian tier-one suppliers pursuing Airbus tier-one qualification. Vertical integration into automated fibre placement equipment maintenance preserves proprietary process knowledge at GKN Aerospace facilities. For New Entrants and Emerging Players: Anchor in Scottish hydrogen aviation testbeds at Highlands and Islands Airports Limited remote airfields, where regulatory sandbox status lowers certification barriers for fuel-cell regional aircraft. Target predictive analytics platforms for unbundled engine health monitoring as incumbent MRO providers cling to bundled power-by-the-hour legacy structures. Pursue consulting-led fleet transition planning engagements with regional carriers navigating SAF procurement complexity. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among engine aftermarket specialists with installed-base lock-in at Derby and Cardiff overhaul facilities. Long-term viability over the next decade rests on exposure to narrowbody renewal cycles rather than widebody platform dependency. Acquisition focus should centre on composite structure manufacturers with Airbus tier-one positions and transferable automated fibre placement capabilities. The signal to watch is CAA certification timeline compression for novel propulsion architectures, which would accelerate stranded asset risk in legacy engine portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| SAF Production Facility Investment | Immingham and Stanlow refineries secure feedstock access ahead of Department for Transport blending mandates. |
| Composite Manufacturing Scale-Up | Automated fibre placement at Bristol and Broughton lowers wing structure costs for Airbus narrowbody programmes. |
| Hydrogen Aviation Testbed Development | Highlands and Islands Airports Limited positions remote Scottish airfields for fuel-cell regional aircraft certification. |
| Predictive Analytics Platform Launch | Unbundled engine health monitoring separates from traditional MRO contracts at Derby overhaul facilities. |
| Military-Commercial Technology Transfer | BAE Systems' Tempest programme spills advanced materials and thermal management into civil applications. |
Study Parameters
The analysis maps narrowbody procurement, widebody manufacturing, business jet completions, and engine aftermarket services, each validated through airline fleet planners, MRO procurement directors, and aerospace manufacturing executives. Primary interviews with Rolls-Royce programme managers, GKN Aerospace supply chain leads, and CAA certification specialists combined with secondary validation against CAA airworthiness directives, Department for Transport SAF policy frameworks, and Airbus production forecasts. Bottom-up triangulation across operator procurement data and top-down reconciliation against OEM delivery schedules ensured segmentation integrity.
Consistency checks against IATA traffic projections and Airbus order backlogs validated volume and value outputs across the analysis window. Segmentation dimensions modeled include product type, end user archetype, technology category, and service type, with regional production cluster as an aviation-specific overlay. CAGRs derived from fleet renewal cycle timing, SAF infrastructure buildout pace, and propulsion technology transition curves, incorporating Jet Zero Council mandate compliance costs as a forecast input.
Material uncertainties — feedstock supply constraints, CAA certification timeline extensions for novel propulsion, and Brexit-related regulatory divergence — sit outside the modeled envelope. Forecasts reflect documented assumptions about narrowbody replacement rates and SAF blending cost pass-through to operators. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Seals Market
Aircraft
Supersonic Jet Market
Aircraft
Southeast Asia Business Jet Market
Aircraft
Helicopter Flight Control Systems Market
Aircraft
Flap Track Fairing Drag Reduction Upgrade Kits Market
Aircraft
Global Business Aircraft Market
Aircraft
Latin America Commercial Aircraft Market
Aircraft
Aircraft Jack Market
Aircraft
Commercial Aircraft Lavatory System Market
Aircraft
Anti Rolling Gyro (ARG) Market
Aircraft
Search and Rescue Helicopter Market
Aircraft
Utility Aircraft Market
Aircraft
Electric VTOL (Evtol) Aircraft Market
Aircraft
Asia-Pacific General Aviation Market
Aircraft
Southeast Asia Aviation Market
Aircraft
India Winglets Market