
 India Aviation Infrastructure Market | 2026-2036
India Aviation Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
India Aviation Infrastructure Market Foresight
Aftermarket service revenue is tilting toward integrated facility management contracts as airports seek single-point accountability for terminal operations. GMR Infrastructure Limited leverages its Hyderabad and Delhi aerotropolis experience to dominate design-build-operate frameworks. Tata Projects anchors large-scale runway and airside engineering through its construction conglomerate resources. Adani Airports Holdings Ltd competes aggressively in brownfield privatization rounds across Mumbai, Ahmedabad, and Lucknow.
India aviation infrastructure encompasses the physical and technological systems enabling aircraft movement, passenger processing, and cargo flow across civilian aerodromes, including runway pavements with 60-90 PCN ratings, ILS Category II/III precision approach systems, and automated baggage handling conveyors processing 4,000-6,000 bags per hour. Terminal construction claims the dominant capital share as passenger throughput strains existing apron and concourse capacity at metro hubs. Surveillance systems and navigation aids represent the fastest-expanding technology category as DGCA mandates upgrade legacy radar networks to multilateration and ADS-B coverage. Maintenance services and ground handling constitute mature, margin-compressed segments where labor arbitrage still sustains profitability.
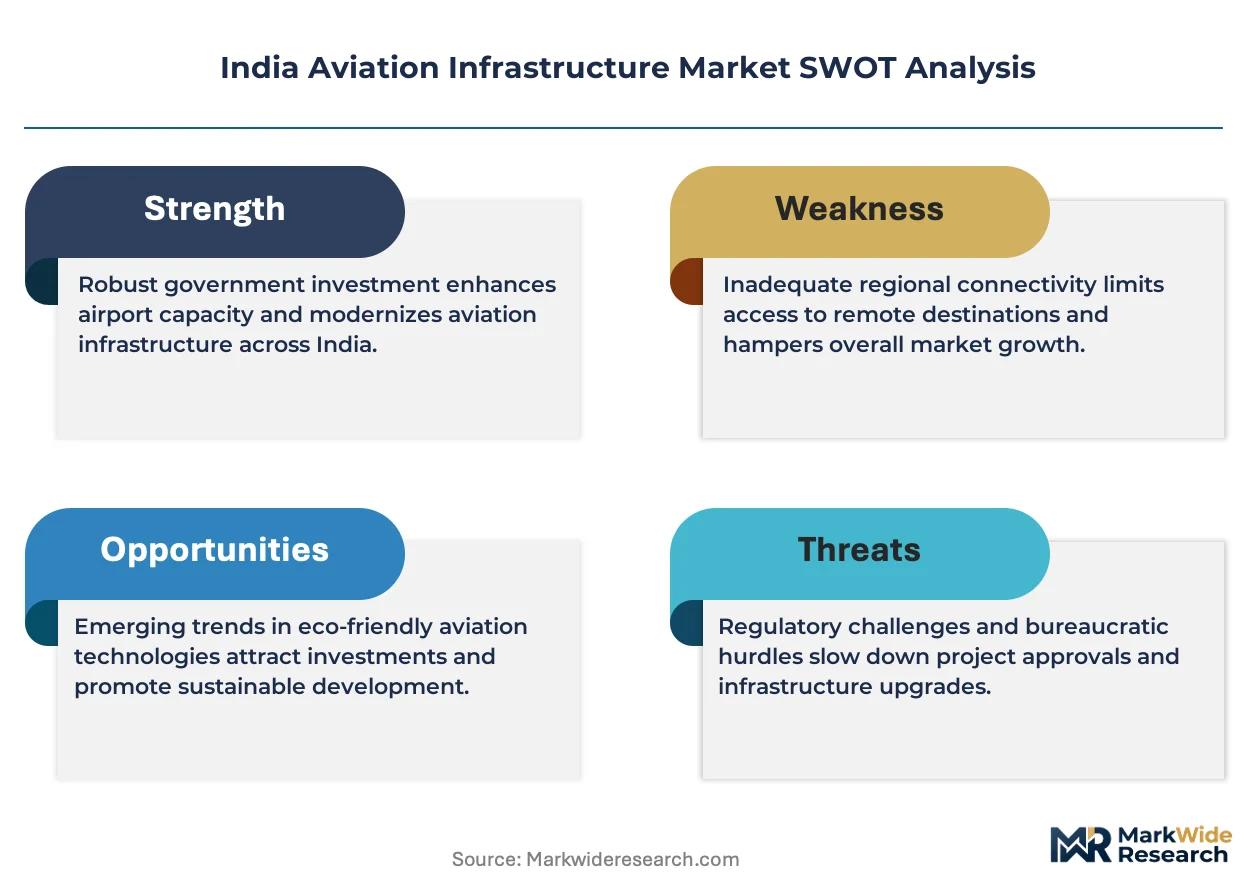
BIS certification governs structural materials and electrical installations at airport facilities, while DGCA aerodrome licensing enforces obstacle limitation surfaces and rescue firefighting categories. The Airports Authority of India retains regulatory oversight alongside operational responsibilities, creating institutional tension in privatization transitions. State-level aviation departments in Gujarat and Maharashtra now compete with central agencies for project approvals, fragmenting permitting timelines. Stakeholders must monitor how the proposed Aircraft Bill reshapes regulator independence and whether state aviation corporations gain concurrent licensing authority.
Market Dynamics
The UDAN regional connectivity scheme is redirecting capital flows toward Tier-2 and Tier-3 aerodromes, fragmenting procurement authority between the Airports Authority of India and emerging state aviation corporations.
Growth Catalysts
- UDAN Regional Connectivity Scheme:Central government viability gap funding de-risks greenfield airport development in underserved states. State governments in Uttar Pradesh and Maharashtra now actively lease land for aerotropolis development.
- Low-Cost Carrier Expansion:Budget airlines drive terminal expansion requirements across secondary cities. Passenger throughput strains existing apron and concourse capacity at metro hubs.
- Multilateration Mandates:DGCA upgrade requirements for legacy radar networks to ADS-B and multilateration coverage accelerate surveillance system procurement. This technology category claims the fastest-expanding capital allocation.
Market Restraints
- Land Acquisition Friction:State-level aviation departments in Gujarat and Maharashtra compete with central agencies for project approvals, fragmenting permitting timelines and extending development cycles.
- Specialized Construction Inputs:Runway pavement materials meeting 60-90 PCN ratings face supply concentration among domestic cement and asphalt producers with airport-grade certification.
- Institutional Overlap:The Airports Authority of India retains regulatory oversight alongside operational responsibilities, creating governance ambiguity during privatization transitions.
Strategic Opportunities
- Karnataka Aerotropolis Development:State government land-banking around Bengaluru and Mysuru creates integrated logistics and aerospace manufacturing zones adjacent to airport perimeters.
- Integrated Facility Management Contracts:Airports seek single-point accountability for terminal operations, tilting aftermarket service revenue toward design-build-operate frameworks.
- Automated Baggage Handling:Conveyors processing 4,000-6,000 bags per hour represent underpenetrated upgrade potential at Tier-2 terminals with constrained capital budgets.
Industry Challenges
- Rescue Firefighting Certification:DGCA aerodrome licensing enforces obstacle limitation surfaces and RFF category upgrades that demand specialized training infrastructure and equipment procurement.
- Legacy System Integration:Brownfield privatization rounds require seamless handover of ILS Category II/III precision approach systems between public operators and private concessionaires.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Aviation Infrastructure Market |
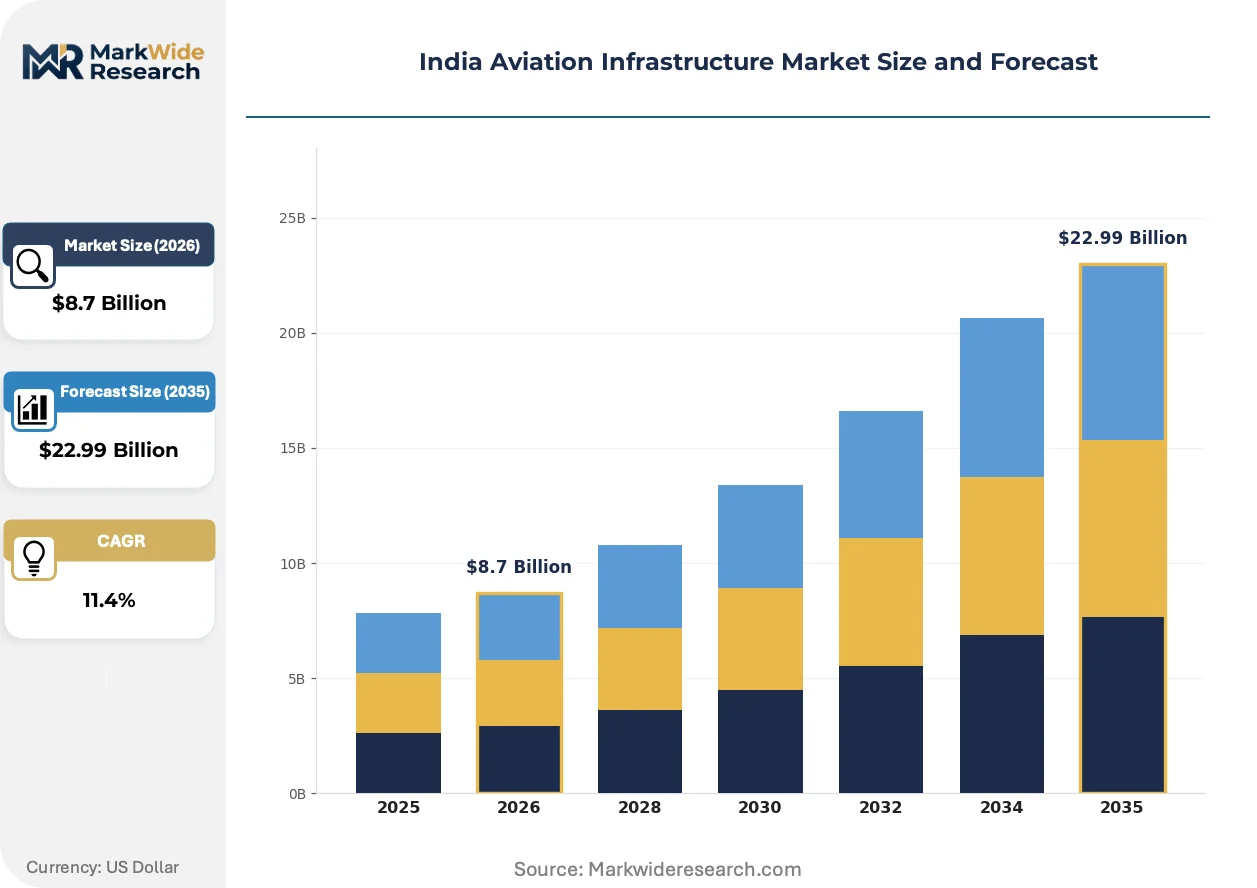
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Facility Type: Terminals, Runways, Hangars, Control Towers End User: Airlines, Government Entities, Cargo Operators, Private Operators Service Type: Maintenance Services, Ground Handling, Air Traffic Control, Security Services Technology: Surveillance Systems, Baggage Handling, Navigation Aids, Communication Systems |
| Companies Covered | Tata Projects, AIC Infrastructures Pvt. Ltd., GMR Infrastructure Limited, Tarmat Ltd., Airports Authority of India, Adani Airports Holdings Ltd, GVK Industries Limited, Gujarat State Aviation Infrastructure Company Ltd., L&T Construction, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Aviation Infrastructure Market Shifts & Advancements
Technology convergence between civil aviation and smart city infrastructure is collapsing traditional procurement boundaries, while regulatory mandates accelerate equipment refresh cycles across the installed base.
Multilateration surveillance technology is collapsing the cost-performance tradeoff that previously favored legacy primary radar networks. DGCA mandates for ADS-B coverage expansion are driving adoption among airport operators managing mixed air traffic environments. The structural consequence is compressing maintenance budgets for rotating radar hardware while redirecting capital toward software-defined surveillance platforms.
BIS certification requirements for structural materials and electrical installations at airport facilities are tightening compliance thresholds. The Bureau of Indian Standards now governs concrete specifications for runway pavements and fire-resistant cabling for terminal buildings. Airport developers in Maharashtra and Karnataka are responding by front-loading certification timelines and engaging accredited testing laboratories earlier in design phases.
Buyer concentration among low-cost carriers is reshaping terminal design specifications toward rapid turnaround configurations. Airlines now specify apron layouts and gate positions that minimize taxi times and passenger walking distances, displacing legacy hub-and-spoke architectural templates. This pattern is most visible in Lucknow and Ahmedabad, where privatized terminals prioritize LCC operational efficiency over full-service carrier amenities.
India Aviation Infrastructure Market Segmentation
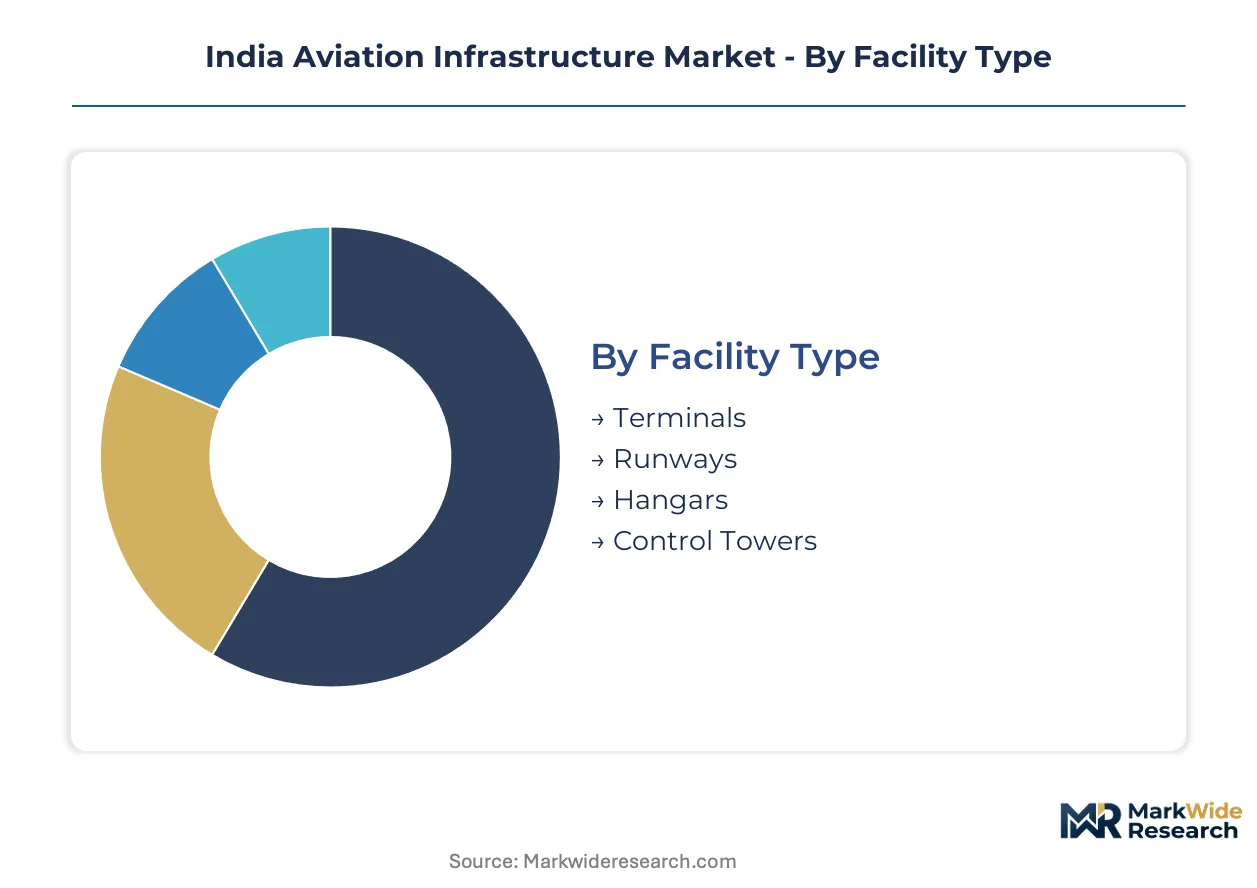
Segmentation reveals how capital allocation splits across physical assets, operational services, and regulatory mandates. Each category exposes distinct procurement rhythms and stakeholder control points that shape vendor positioning.
Facility Type:
Use cases span passenger processing throughput, aircraft movement surfaces, maintenance shelter, and airspace coordination infrastructure.
- Terminals:Concourse and apron configurations process passenger flows exceeding design capacity at metro hubs. Uttar Pradesh and Maharashtra state governments lease land for aerotropolis-integrated terminal complexes, compressing development timelines where viability gap funding applies.
- Runways:Pavement structures rated 60-90 PCN accommodate narrow-body and wide-body aircraft loads. Supply concentrates among domestic cement and asphalt producers holding BIS certification for airport-grade materials, extending procurement cycles for specialized inputs.
- Hangars:Maintenance and storage shelters for fleet overnighting and heavy checks. MRO demand clusters around Bengaluru and Hyderabad aerotropolis zones.
- Control Towers:Visual and electronic surveillance coordination structures. DGCA aerodrome licensing mandates obstacle limitation surface compliance, dictating siting and height restrictions.
The dominant share belongs to Terminals, while Runways is closing the gap fastest as brownfield privatization accelerates airside expansion.
End User:
Customer concentration tilts toward entities controlling route authority, regulatory compliance, and cargo throughput economics.
- Airlines:Low-cost carriers drive terminal design specifications toward rapid turnaround configurations. Budget operators in Lucknow and Ahmedabad now specify apron layouts minimizing taxi times and passenger walking distances, displacing legacy hub-and-spoke templates.
- Government Entities:Airports Authority of India and state aviation corporations retain procurement authority over greenfield developments. Institutional overlap between regulatory oversight and operational responsibilities creates governance ambiguity during privatization handovers.
- Cargo Operators:Dedicated freighter infrastructure and perishable handling facilities. Demand concentrates in Karnataka integrated logistics zones adjacent to airport perimeters.
- Private Operators:Concession holders in Mumbai, Ahmedabad, and Lucknow brownfield rounds. Single-point accountability requirements tilt contracts toward design-build-operate frameworks.
Airlines command the largest procurement volume, though Government Entities is expanding most quickly through UDAN-scheme greenfield allocations.
Service Type:
Operational maturity and margin compression vary sharply across labor intensity, certification requirements, and technology substitution potential.
- Maintenance Services:Runway pavement preservation, lighting system upkeep, and structural rehabilitation. Labor arbitrage sustains profitability despite margin compression in this mature segment.
- Ground Handling:Aircraft servicing, baggage transfer, and passenger boarding bridge operations. Tier-2 terminals with constrained capital budgets underpenetrate automated equipment upgrades.
- Air Traffic Control:Separation assurance and flow management services. DGCA mandates for ADS-B and multilateration coverage accelerate surveillance technology procurement, compressing rotating radar maintenance budgets.
- Security Services:Passenger screening, perimeter monitoring, and access control. BIS certification governs electrical installations and fire-resistant cabling specifications.
Ground Handling retains the deepest revenue base, yet Air Traffic Control is gaining share fastest on regulatory-mandated equipment refresh cycles.
Technology:
Technology procurement splits between software-defined surveillance platforms and mechanical handling systems at diverging investment trajectories.
- Surveillance Systems:Multilateration and ADS-B networks replacing legacy primary radar. DGCA upgrade requirements collapse the cost-performance tradeoff that previously favored rotating hardware, redirecting capital toward software-defined platforms.
- Baggage Handling:Automated conveyor systems processing 4,000-6,000 bags per hour. Tier-2 terminals in secondary cities present underpenetrated upgrade potential where capital budgets constrain full automation deployment.
- Navigation Aids:ILS Category II/III precision approach systems for low-visibility operations. Brownfield privatization requires seamless handover between public operators and private concessionaires.
- Communication Systems:Voice and data networks linking tower, apron, and airline operations centers. Integration complexity rises with smart city infrastructure convergence.
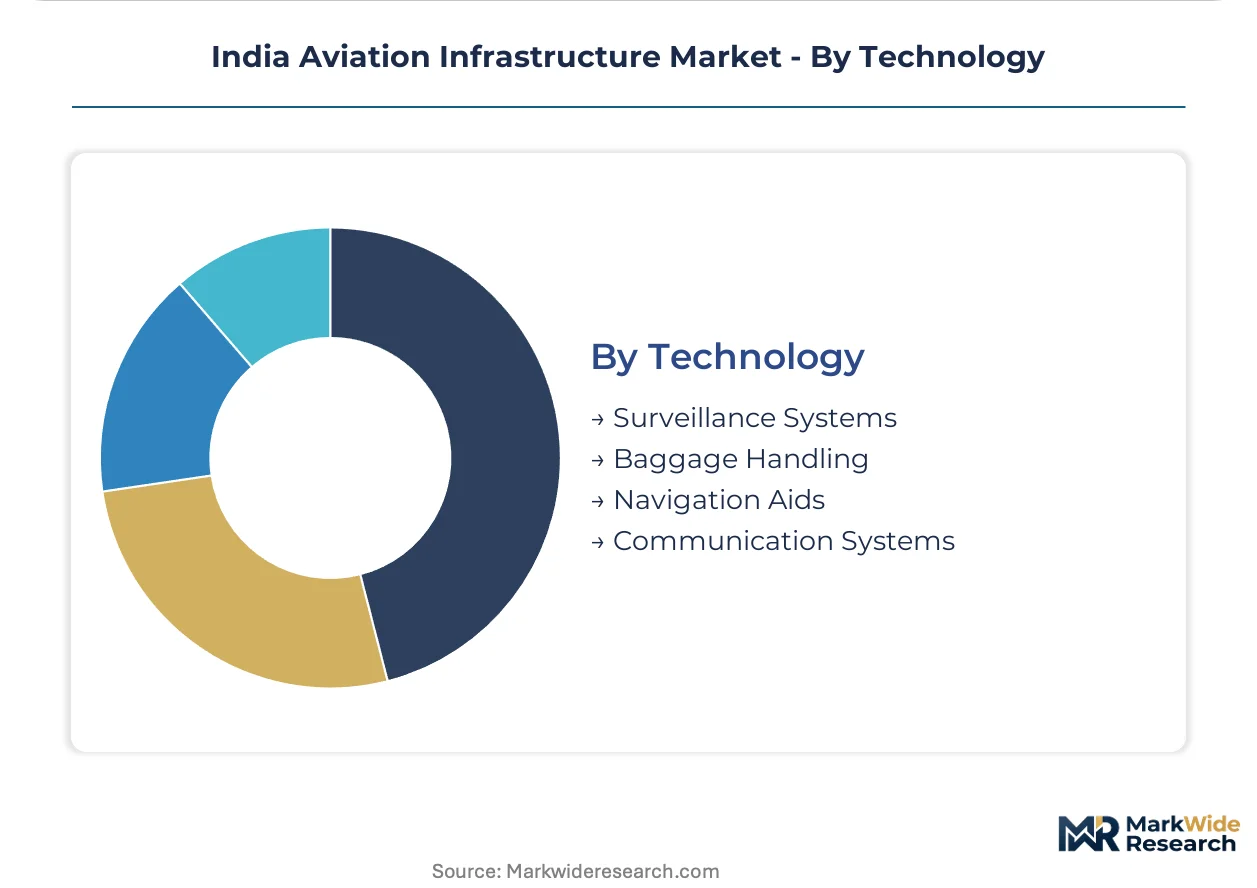
Surveillance Systems holds the steepest expansion trajectory, while Baggage Handling is climbing fastest as Tier-2 airport modernization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Indian states. Tier-1 metro airports face capacity-constrained inelastic demand where passenger throughput exceeds design limits, while Tier-2 and Tier-3 greenfield developments operate in price-sensitive territory where UDAN viability gap funding determines project viability.
Maharashtra
Mumbai's Chhatrapati Shivaji Maharaj International Airport anchors western India passenger flows, with privatized terminals prioritizing low-cost carrier turnaround efficiency. The Maharashtra Airport Development Company actively leases land for aerotropolis development around Pune and Nagpur. MRO infrastructure clusters in the Mumbai-Pune corridor where GMR Infrastructure Limited and Adani Airports Holdings Ltd compete for brownfield concession renewals.
Uttar Pradesh
Lucknow's Chaudhary Charan Singh International Airport drives North India terminal expansion as India's most populous state adds aviation capacity. The Uttar Pradesh government has designated Noida International Airport as a greenfield priority with dedicated cargo and aerospace manufacturing zones. Jewar aerotropolis development attracts integrated logistics operators seeking land-banked industrial parcels adjacent to runway perimeters.
Karnataka
Bengaluru Kempegowda International Airport strains apron and concourse capacity as India's third-busiest passenger hub. The Karnataka State Industrial Infrastructure Development Corporation leases airport-adjacent land for aerospace manufacturing and maintenance clusters. Mysuru airport modernization exemplifies Tier-2 terminal automation upgrades where baggage handling systems processing 4,000-6,000 bags per hour remain underpenetrated.
Gujarat
Ahmedabad's Sardar Vallabhbhai Patel International Airport serves as Adani Airports Holdings Ltd's western anchor following brownfield privatization. The Gujarat State Aviation Infrastructure Company competes with central agencies for project approvals, fragmenting permitting timelines for Surat and Rajkot greenfield developments. Dahej and Mundra port connectivity positions Gujarat airports for dedicated freighter infrastructure expansion.
Telangana
Hyderabad's Rajiv Gandhi International Airport operates under GMR Infrastructure Limited's design-build-operate framework, India's first fully privatized greenfield airport. The Telangana State Industrial Infrastructure Corporation has zoned Shamshabad-adjacent land for aerospace precision manufacturing and flight training academies. DGCA multilateration mandates accelerate surveillance system procurement across the airport's mixed air traffic environment.
India Aviation Infrastructure Market Competitive Landscape
Capability concentration sits with integrated infrastructure conglomerates possessing design-build-operate credentials; scale advantage sits with construction majors leveraging parent-company balance sheets. The market structures around three tiers: privatized airport operators managing concession assets, engineering-procurement-construction contractors executing airside and landside projects, and state aviation corporations retaining greenfield procurement authority. Dominant competitive moves include concession bidding for brownfield assets and consortium formation to meet single-point accountability requirements for integrated facility management contracts.
Within the privatized operator tier, GMR Infrastructure Limited and Adani Airports Holdings Ltd exemplify contrasting geographic strategies. GMR anchors southern and central India through its Hyderabad and Delhi aerotropolis experience, while Adani competes aggressively in western and northern brownfield rounds. Tata Projects occupies a position among construction-centric players, drawing on Tata Group resources for large-scale runway and airside engineering. The Airports Authority of India retains dual regulatory and operational roles, creating institutional tension as state aviation corporations in Gujarat and Maharashtra fragment procurement authority.
| Leading Market Players |
|---|
| Tata Projects |
| AIC Infrastructures Pvt. Ltd. |
| GMR Infrastructure Limited |
| Tarmat Ltd. |
| Airports Authority of India |
| Adani Airports Holdings Ltd |
| GVK Industries Limited |
| Gujarat State Aviation Infrastructure Company Ltd. |
| L&T Construction |
| Others |
Supply & Pricing Matrix
Mumbai-Pune corridor cement and asphalt producers with BIS airport-grade certification command premium positioning in runway pavement contracts, translating supply scarcity into pricing leverage for 60-90 PCN rated materials. Tier-2 terminal developers face cost compression where automated baggage handling and multilateration mandates compete for limited capital budgets.
Pricing Analysis
Integrated facility management contracts now drive lifetime value as airports seek single-point accountability for terminal operations. Three-tier pricing structure across design-build-operate frameworks, construction-only engagements, and pure maintenance contracts differentiates vendors by capability depth. Cost compression in ground handling services intensifies as labor arbitrage sustains profitability despite margin pressure. Government entities under UDAN schemes exhibit highest price sensitivity, while privatized metro hub operators prioritize performance guarantees over unit cost.
Supply Chain Analysis
Tariff exposure between specialized construction input suppliers and domestic airport developers dominates procurement risk planning. Supply concentrates among domestic cement and asphalt producers holding BIS certification, with critical navigation aids and surveillance hardware drawing from South Korea, Germany, and USA. Runway pavement materials, ILS Category II/III systems, and automated baggage conveyors represent core dependencies. Single-source vulnerability in airport-grade electrical installations creates procurement bottlenecks. Distribution runs through Airports Authority of India and state aviation corporation tendering platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated facility management contracts expand faster than hardware procurement as airports outsource terminal operations accountability. Aftermarket service revenue layers including runway preservation, lighting upkeep, and surveillance system maintenance outpace capital equipment growth.
For Market Incumbents: Build design-build-operate credential moats through concession renewal performance at Hyderabad and Delhi aerotropolis zones. Deepen backward integration into BIS-certified construction materials to defend margin position against state aviation corporation procurement fragmentation. Counter Adani Airports Holdings Ltd's brownfield aggression with integrated facility management bundling that locks in long-term service revenue. For New Entrants and Emerging Players: Pursue Tier-2 terminal automation where baggage handling systems processing 4,000-6,000 bags per hour remain underpenetrated. Target Karnataka and Uttar Pradesh state aviation corporations for greenfield surveillance system mandates under DGCA multilateration requirements. Lead with software-defined surveillance platforms that collapse legacy radar maintenance budgets. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors engineering-procurement-construction contractors with parent-company balance sheet scale. Long-term viability across the projection horizon rests on design-build-operate framework penetration. Acquisition focus: integrated facility management specialists with active terminal operations contracts. Signal to watch: state aviation corporation licensing authority expansion under proposed Aircraft Bill provisions.| Strategic Initiative | Industry Significance |
|---|---|
| Concession Bidding for Brownfield Assets | Adani Airports Holdings Ltd and GMR Infrastructure Limited compete for Mumbai, Ahmedabad, and Lucknow privatization rounds. |
| Integrated Facility Management Contracting | Single-point accountability requirements tilt terminal operations procurement toward design-build-operate frameworks. |
| Surveillance Technology Refresh | DGCA multilateration mandates accelerate ADS-B coverage procurement across mixed air traffic environments. |
| Aerotropolis Land Banking | Maharashtra and Karnataka state corporations lease airport-adjacent parcels for aerospace manufacturing clusters. |
| BIS Certification Front-Loading | Developers engage accredited testing laboratories earlier to compress runway pavement material approval timelines. |
Research Methodology
Operator-level perspectives from airport project directors, state aviation corporation procurement leads, DGCA regulatory affairs officers, and integrated facility management contract managers anchored the qualitative base. Primary interviews combined with secondary validation against Airports Authority of India tender records, BIS certification databases, Ministry of Civil Aviation policy circulars, and state industrial infrastructure corporation land lease disclosures. Bottom-up project pipeline assessment triangulated with top-down macroeconomic scenario modeling.
Scenario-bracketing across base, optimistic, and conservative demand assumptions structured the analytical framework. Segmentation dimensions modeled include facility type, end user category, service maturity tier, and technology substitution trajectory. CAGRs derived from weighted average of historical execution rates and announced project pipelines. Forecast inputs incorporated UDAN viability gap funding allocations and brownfield privatization round schedules.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by state aviation corporations or accelerated Aircraft Bill passage would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
Airport Stands Equipment Market
Airport Infrastructure
Aerobridge Market
Airport Infrastructure
Airport Lighting Market
Airport Infrastructure
Europe Airport Baggage Handling Systems Market
Airport Infrastructure
Ground Handling Systems Market
Airport Infrastructure
Fixed-Base Operator Market
Airport Infrastructure
Telescopic Masts Market
Airport Infrastructure
Europe, Middle-East and Africa Aviation Infrastructure Market
Airport Infrastructure
Aircraft Catering Vehicle Market
Airport Infrastructure
Aviation Infrastructure Market
Airport Infrastructure
Airport Ground Support Equipment Market
Airport Infrastructure
Aerotropolis Market
Airport Infrastructure
Middle-East and Africa Aviation Infrastructure Market
Airport Infrastructure
Airport Logistics Systems Market
Airport Infrastructure
Runway Lighting System Market
Airport Infrastructure
Aircraft Tow Tractors Market