
 Mechanical Testing Equipment Market | 2026-2036
Mechanical Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Mechanical Testing Equipment Market Foresight
Aftermarket service revenue is fragmenting across calibration contracts, remote diagnostics subscriptions, and on-site technician deployments. Instron leverages its North American installed base to dominate premium service tiers. ZwickRoell anchors European demand through deep ties with German automotive OEMs and their tier-one suppliers. MTS Systems Corporation specializes in high-force structural testing systems for aerospace customers requiring multi-axis simulation capabilities.
Mechanical testing equipment comprises instruments that apply controlled forces to materials and components to measure properties including yield strength, elastic modulus, fracture toughness, and fatigue life under cyclic loading. These systems serve as gatekeeping tools for product qualification across industries where structural failure carries catastrophic liability. Tensile testers command the largest product-type revenue pool due to universal applicability across metals, polymers, and composites. Fatigue testers represent the fastest-expanding segment as electric vehicle powertrain components and wind turbine blades face extended operational-life specifications. Automated solutions within the technology dimension are capturing margin from mechanical systems through reduced operator variability and higher throughput in quality-control environments.
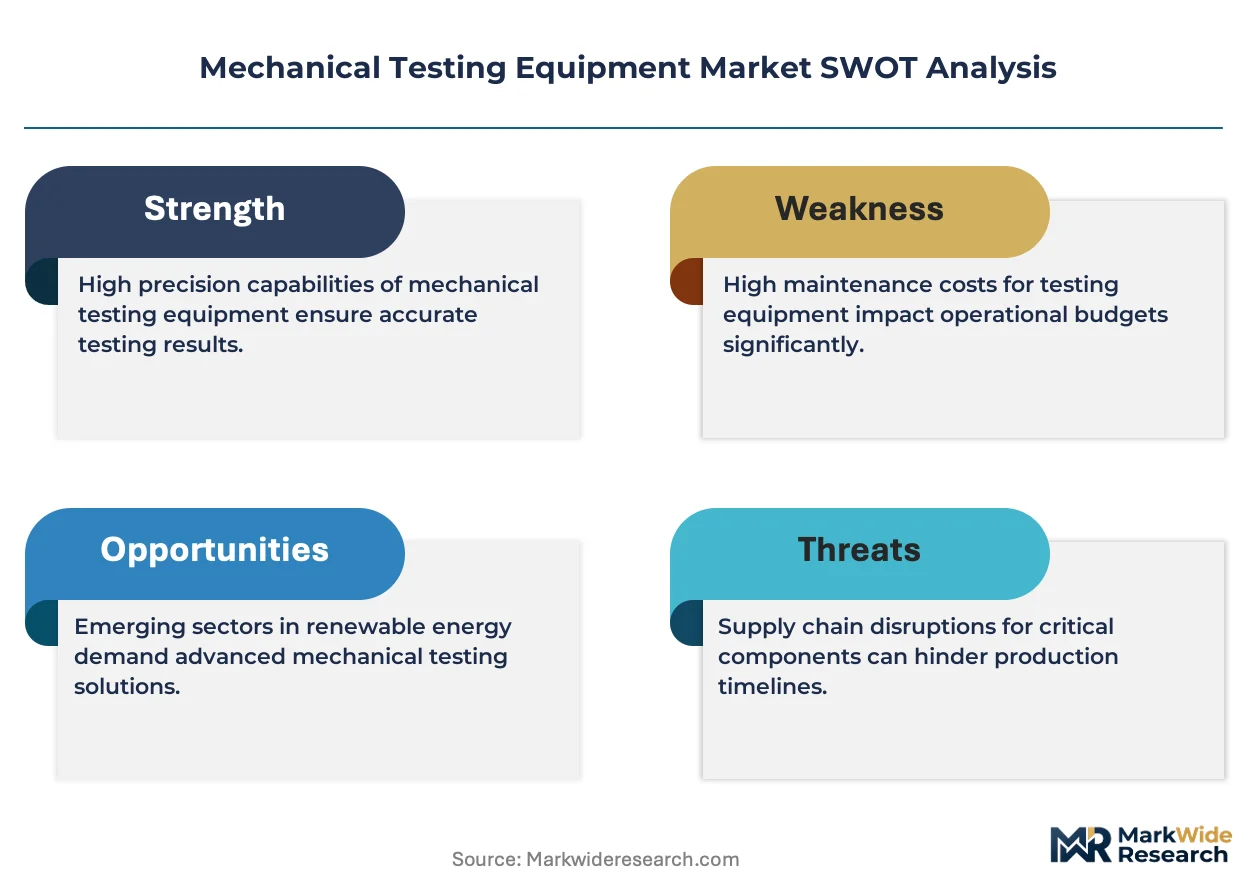
FAA airworthiness directives, EPA material certification protocols for emissions-critical components, and ISO 17025 laboratory accreditation requirements collectively elevate the compliance burden for testing equipment purchasers. Germany's KBA enforces component-level validation for automotive suppliers exporting into European markets, while Japan's METI promotes JIS-standard alignment for domestic machinery exports. Stakeholders must weigh capital deployment between universal testing platforms and application-specific systems as end-user consolidation reshapes procurement leverage.
Market Dynamics
Aviation regulators in Germany, Japan, and the United States are compressing fatigue-testing replacement cycles through stricter airworthiness mandates, forcing capital redeployment toward multi-axis structural simulation systems.
Growth Catalysts
- FAA Fatigue-Testing Mandates:The FAA's updated airworthiness directives require expanded cyclic loading validation for lightweight composite airframes, compelling aerospace manufacturers to upgrade legacy hydraulic systems.
- China's Industrial Corridors:Domestic certification labs in Shanghai, Tianjin, and Chongqing are scaling tensile and compression testing capacity to serve automotive and construction material validation demand.
- Electric Vehicle Powertrains:Extended operational-life specifications for battery housings and motor mounts are accelerating fatigue tester procurement across EV supply chains.
Market Restraints
- High-Force Hydraulic Component Costs:Specialized servo valves and precision load cells face price volatility from concentrated German and Japanese supplier bases, elevating total system costs.
- ISO 17025 Accreditation Burden:Laboratory accreditation requirements impose multi-year compliance timelines and recurring audit costs that deter mid-tier testing facility expansion.
- Mechanical System Obsolescence:Automated electromechanical testing platforms are displacing legacy hydraulic configurations, stranding capital in installed bases with limited retrofit pathways.
Strategic Opportunities
- Wind Turbine Blade Validation:Offshore wind installations in Denmark and the Netherlands require specialized fatigue testers capable of simulating decades of cyclic stress on 100-meter-plus composite structures.
- Remote Diagnostics Subscriptions:Equipment vendors can unbundle predictive maintenance software from hardware sales, capturing recurring revenue from distributed automotive supplier networks.
- India's PLI-Driven Manufacturing:Production-linked incentive schemes for specialty steel and automotive components are spurring greenfield testing lab investments in Pune and Chennai industrial zones.
Industry Challenges
- Multi-Axis Simulation Expertise Gap:Aerospace customers require technicians proficient in coordinating six-degree-of-freedom structural testing, a skill set concentrated among retiring specialist cohorts.
- Legacy System Integration Friction:New automated platforms must interface with decades-old data acquisition infrastructure in established automotive and materials testing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mechanical Testing Equipment Market |
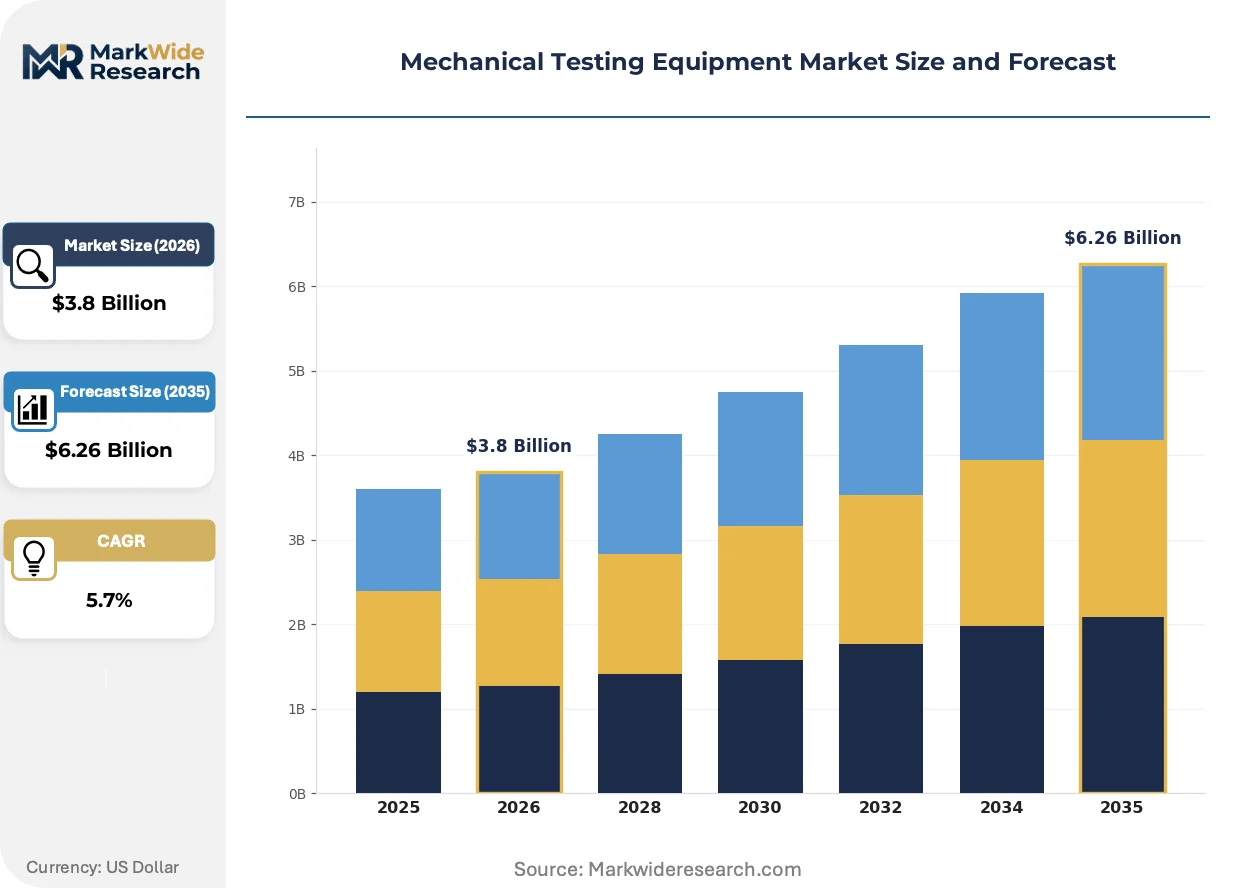
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tensile Testers, Compression Testers, Hardness Testers, Fatigue Testers Application: Aerospace, Automotive Components, Medical Devices, Construction Materials End User: Manufacturers, Research Labs, Quality Control, Educational Institutions Technology: Digital Systems, Mechanical Systems, Automated Solutions, Computerized Equipment |
| Companies Covered | Instron, ZwickRoell, MTS Systems Corporation, Shimadzu Corporation, Tinius Olsen, Hegewald & Peschke, Hounsfield Test Equipment, ADMET, LabTest Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mechanical Testing Equipment Market Shifts & Advancements
Testing instrumentation is converging with industrial IoT architectures and cloud-native data pipelines, compressing the gap between raw force measurement and real-time quality intelligence.
Electromechanical load frames are migrating from niche polymer testing into high-force metals and composites applications previously dominated by hydraulic systems. Automotive OEMs in Germany and Japan are adopting these platforms for production-line quality control. The shift is compressing maintenance intervals and enabling floor-space reductions in crowded manufacturing facilities.
REACH compliance protocols for emissions-critical automotive components are expanding material certification documentation requirements across European supply chains. Tier-one suppliers must now validate recycled content percentages and restricted substance thresholds through traceable mechanical testing records. This regulatory layer is elevating demand for automated specimen handling and LIMS-integrated data management.
Service unbundling is fragmenting how testing equipment buyers contract for post-sale support. Automotive and aerospace procurement teams are separating calibration, spare parts, and technical training into discrete purchase orders rather than bundled maintenance agreements. This pattern is most pronounced in North American and German markets where centralized fleet management functions exercise granular spend control.
Mechanical Testing Equipment Market Segmentation
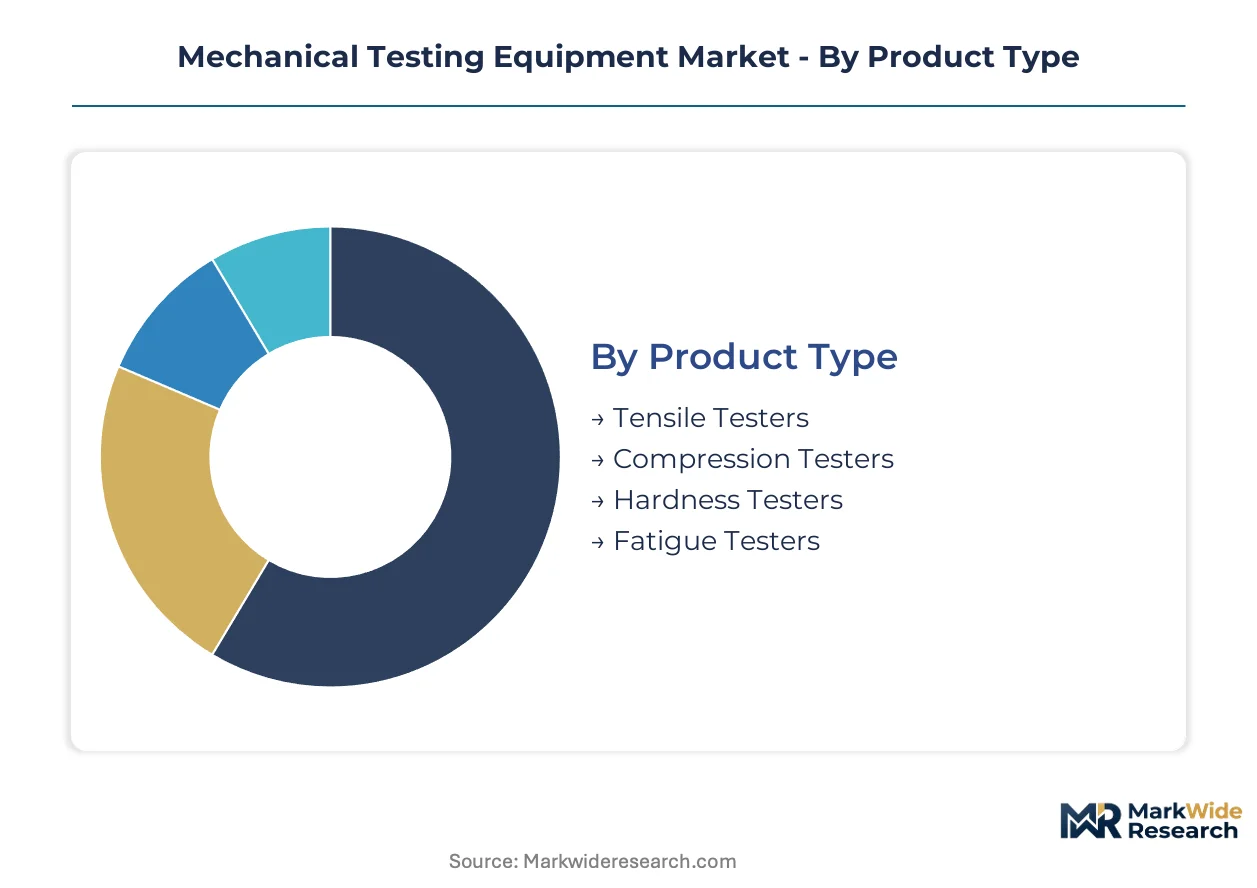
Mechanical testing equipment serves divergent validation requirements across materials science, production quality control, and regulatory compliance. Segmentation reveals how capital deployment priorities shift between universal platforms and specialized systems as end-users consolidate procurement leverage.
Product Type:
Use-case spectrum spans routine quality checks in metals processing through multi-decade fatigue simulation for composite airframes.
- Tensile Testers:Apply uniaxial load to specimens until fracture, measuring yield strength and elastic modulus across metals, polymers, and fiber-reinforced composites. Demand concentrates in China's industrial corridors where domestic certification labs scale capacity for automotive and construction material validation.
- Fatigue Testers:Subject components to cyclic loading regimes simulating operational stress over extended service life. Aerospace manufacturers in Germany, Japan, and the United States are expanding procurement as FAA and KBA mandates compress replacement cycles for composite airframe validation.
- Compression Testers:Evaluate buckling resistance and crush characteristics in structural foams and concrete specimens.
- Hardness Testers:Deploy rapid indentation methods for production-line metallurgical verification in automotive powertrain manufacturing.
The dominant share belongs to tensile testers, while fatigue testers are closing the gap fastest.
Application:
Cost tier separation distinguishes capital-intensive aerospace qualification from high-volume automotive quality control.
- Aerospace:Multi-axis structural simulation systems validate lightweight composite airframes under combined loading conditions. German, Japanese, and US aviation regulators enforce expanded cyclic testing protocols that force equipment upgrades.
- Automotive Components:Production-line electromechanical platforms verify battery housing integrity and motor mount durability for extended EV operational life. OEM procurement in Germany and Japan favors automated systems enabling floor-space reduction.
- Construction Materials:Compression and flexural testing of concrete, steel reinforcement, and engineered timber for infrastructure certification.
- Medical Devices:Biocompatibility and fatigue validation for orthopedic implants and cardiovascular stents under ISO and FDA protocols.
Aerospace commands premium pricing tiers, with automotive components gaining share through EV supply chain expansion.
End User:
Volume concentration varies between centralized manufacturing quality departments and distributed research infrastructure.
- Manufacturers:In-house testing departments integrate electromechanical platforms directly into production lines for real-time quality gates. REACH compliance documentation requirements across European supply chains elevate demand for automated specimen handling.
- Research Labs:Academic and government facilities pursue fundamental materials characterization with versatile universal testing platforms. India's PLI-driven manufacturing incentives spur greenfield lab investments in Pune and Chennai industrial zones.
- Quality Control:Third-party certification bodies serving tier-one automotive and construction material suppliers.
- Educational Institutions:Training laboratories requiring robust mechanical systems with simplified operator interfaces.
Manufacturers hold the installed base majority, though research labs are expanding capacity most aggressively.
Technology:
Margin structure diverges between maintenance-intensive hydraulic legacy systems and software-enabled electromechanical platforms.
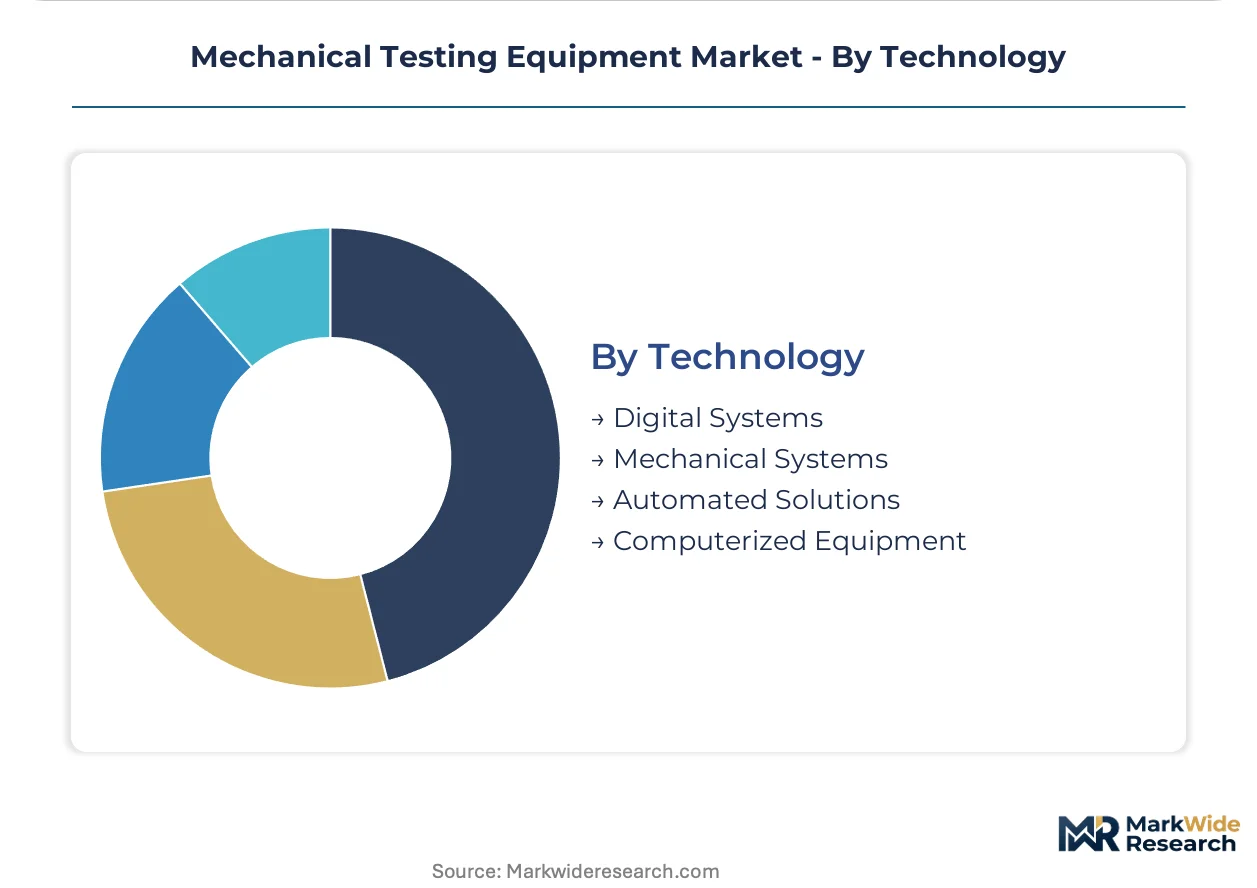
- Automated Solutions:Integrate robotic specimen handling with cloud-native data pipelines, compressing cycle times and eliminating operator variability. Automotive OEMs in Germany and Japan adopt these platforms for crowded manufacturing facilities.
- Digital Systems:Modern load frames with precision servo control and real-time force-displacement acquisition. Offshore wind installations in Denmark and the Netherlands drive specialized demand for 100-meter-plus blade fatigue simulation.
- Computerized Equipment:Legacy data acquisition architectures requiring integration with decades-old infrastructure in established testing facilities.
- Mechanical Systems:Conventional hydraulic configurations facing obsolescence as electromechanical platforms migrate into high-force applications.
Automated solutions capture expanding margin pools, while mechanical systems retreat to price-sensitive replacement markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fragments sharply across geographies: buyers in China's industrial corridors prioritize capital efficiency, while aerospace manufacturers in Germany and the United States absorb premium pricing for multi-axis validation systems. This elasticity divide shapes vendor deployment strategies and service-tier unbundling patterns.
United States
FAA airworthiness directives are compressing fatigue-testing replacement cycles among domestic aerospace manufacturers. The agency's expanded cyclic loading mandates for composite airframes force capital redeployment toward structural simulation systems. Testing equipment demand concentrates in Seattle and Wichita aerospace clusters, where tier-one suppliers upgrade legacy hydraulic configurations.
Germany
German automotive OEMs and their supplier networks anchor European demand for automated electromechanical platforms. The KBA enforces component-level validation requirements for automotive suppliers exporting into European markets. Equipment procurement localizes around Stuttgart and Munich industrial zones, where production-line quality control integration drives floor-space optimization priorities.
China
Domestic certification labs in Shanghai, Tianjin, and Chongqing are scaling tensile and compression testing capacity for automotive and construction material validation. The country's national standardization administration promotes GB standard alignment for machinery exports. State-backed industrial corridor investments concentrate testing infrastructure in Yangtze River Delta manufacturing hubs.
Japan
Japanese automotive and machinery manufacturers are adopting automated solutions for crowded manufacturing facilities. METI promotes JIS-standard alignment for domestic machinery exports through technical harmonization programs. Equipment demand clusters in Nagoya and Osaka industrial basins, where tier-one automotive suppliers validate battery housing integrity for extended EV operational life.
India
Production-linked incentive schemes for specialty steel and automotive components are spurring greenfield testing lab investments. The Bureau of Indian Standards enforces certification protocols for construction materials and industrial machinery. Pune and Chennai industrial zones are emerging as validation hubs for automotive export supply chains.
Mechanical Testing Equipment Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another, producing a bifurcated structure where premium-system engineering and high-volume platform deployment follow distinct economic logics. The vendor base organizes around three archetypes: full-line universal testing platform suppliers, specialized high-force structural simulation providers, and regional electromechanical system fabricators. Consolidation pressure operates through vertical capability acquisition and geographic service network expansion.
Within the full-line tier, Instron and ZwickRoell exemplify divergent geographic anchoring strategies, with the former representing North American installed-base leverage and the latter occupying a position defined by German automotive OEM integration. MTS Systems Corporation sits within the specialized structural simulation segment, anchoring high-force multi-axis capability for aerospace validation requirements. These three companies collectively represent the capability-scale spectrum that defines competitive positioning in this market.
| Leading Market Players |
|---|
| Instron |
| ZwickRoell |
| MTS Systems Corporation |
| Shimadzu Corporation |
| Tinius Olsen |
| Hegewald & Peschke |
| Hounsfield Test Equipment |
| ADMET |
| LabTest Instruments |
| Others |
Supply & Pricing Matrix
Stuttgart's precision engineering cluster shapes downstream pricing power for German automotive OEMs demanding automated electromechanical platforms with integrated calibration contracts. Equipment vendors serving this corridor capture premium lifetime value through service-tier unbundling that separates hardware from predictive maintenance subscriptions.
Pricing Analysis
Aftermarket service revenue tiers—spanning calibration contracts, remote diagnostics subscriptions, and on-site technician deployments—drive lifetime value capture across installed bases. Three-tier pricing structure across premium, standard, and economy levels separates aerospace multi-axis systems from automotive production-line units and educational laboratory configurations. Cost compression in economy tiers intensifies as Chinese domestic certification labs prioritize capital efficiency over bundled service agreements. Automotive OEMs in Germany and Japan exhibit least price sensitivity for floor-space-optimized automated solutions, while India's emerging greenfield labs demonstrate highest sensitivity to upfront capital expenditure.
Supply Chain Analysis
Extended payment terms from German and Japanese precision component suppliers strain working capital for system integrators assembling high-force hydraulic configurations. Manufacturing concentration in Germany, Japan, and the United States anchors servo valve and precision load cell production. Supply chains draw from specialized steel forgings, ceramic strain gauges, and high-pressure hydraulic seals. Single-source vulnerability concentrates in German servo valve fabricators serving aerospace structural simulation demand. Distribution runs through direct OEM relationships for premium tiers and regional distributor networks for standard economy configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechanical testing equipment is approaching a platform-economics inflection as cloud-native data pipelines and industrial IoT architectures enable outcome-based service models that decouple revenue from hardware shipment cycles.
For Market Incumbents: Build switching-cost moats through LIMS-integrated data management platforms that lock in automotive tier-one suppliers facing REACH compliance documentation requirements. Deepen captive supply of precision load cells to offset German and Japanese component price volatility. Acquire remote diagnostics software capabilities to defend against emerging electromechanical platform entrants unbundling predictive maintenance from hardware sales. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-driven manufacturing corridors where greenfield testing lab investments lack legacy data acquisition infrastructure integration burdens. Target Pune and Chennai industrial zones with automated specimen handling solutions priced below European incumbent tiers. Deploy cloud-native subscription pricing to bypass capital-intensive upfront procurement cycles that deter mid-tier facility expansion. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized high-force structural simulation providers with aerospace certification relationships over full-line universal platform suppliers facing mechanical system obsolescence. Long-term viability hinges on electromechanical migration capture and aftermarket service revenue attachment rates. Watch for FAA airworthiness directive acceleration as inflection signal indicating replacement cycle compression and multi-axis system demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Cloud-native data pipelines compress quality intelligence latency for automotive OEMs adopting Industry 4.0 architectures. |
| Backward Integration | In-house production of precision load cells reduces exposure to concentrated German and Japanese supplier price volatility. |
| Geographic Expansion | Greenfield service networks in India's Pune and Chennai industrial zones capture PLI-driven manufacturing validation demand. |
| Acquisition of Specialist Firm | Remote diagnostics software targets unbundled recurring revenue from distributed automotive supplier networks. |
| Strategic Partnership | Hospital system partnerships for orthopedic implant fatigue validation open medical device certification pathways. |
Research Methodology
A standing panel of plant engineers, OEM procurement managers, aftermarket service directors, and certification laboratory technical leads provided ongoing calibration against market sizing assumptions. Primary interviews with maintenance directors at aerospace manufacturers and tier-one automotive suppliers combined with secondary validation from FAA airworthiness directive filings, KBA component validation protocols, and ISO 17025 accreditation databases. Bottom-up equipment shipment analysis and top-down end-user spending surveys were triangulated to anchor volume and value estimates.
Scenario bracketing around regulatory mandate timing and electromechanical technology migration pace bounded forecast uncertainty across the projection horizon. Segmentation dimensions modeled include product type, application sector, end-user category, and technology platform, with regional regulatory cluster and certification tier as cross-cutting variables. CAGRs were derived from installed base replacement cycle analysis and greenfield capacity addition tracking, with EV powertrain operational-life specifications and offshore wind blade validation demand as industry-specific demand drivers.
Stress conditions across FAA mandate acceleration, Chinese industrial corridor investment pace, and hydraulic component supply disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology substitution rates and regulatory enforcement intensity. Macroeconomic contraction, trade restriction escalation, or breakthrough electromechanical force-range extension would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Compression Testers Market
Test and Measurement
Oscilloscope Market
Test and Measurement
Hybrid Supercapacitor Lifetime and Safety Test Equipment Market
Test and Measurement
Leak Testing Market
Test and Measurement
Vibration Analyzer Market
Test and Measurement
Global Video Extensometer Market
Test and Measurement
Electromagnetic NDT Market
Test and Measurement
Global Inspection Machines Market
Test and Measurement
Handheld Digital Multimeter Market
Test and Measurement
Global General Purpose Test Equipment (GPTE) Market
Test and Measurement
Video Measuring System Market
Test and Measurement
High Rate Discharge Test Machine Market
Test and Measurement
Power Electronics GaN and SiC Device Reliability Test Systems Market
Test and Measurement
Non-Destructive Testing (NDT) Software Market
Test and Measurement
Battery CT Inspection Market
Test and Measurement
Shock Test Machines Market