
 Smart Fan Market | 2026-2036
Smart Fan Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Fan Market Analysis
Buyer concentration across the residential segment is broadening as smart home ecosystems pull in first-time adopters alongside traditional premium purchasers. Hunter Fan Company leverages its heritage craftsmanship to anchor brand loyalty in North American specialty retail channels. Orient Electric competes aggressively on cost-engineered Wi-Fi ceiling platforms tailored to Indian voltage conditions. Panasonic extends its sensor-integration capabilities from adjacent HVAC portfolios into voice-controlled residential units.
A smart fan integrates brushless DC motors, wireless communication modules, and environmental sensors into an electromechanical air-circulation device controllable through digital interfaces. These systems typically operate at 15–35 watts for ceiling configurations, enabling programmable airflow modulation for demand-responsive thermal comfort in conditioned spaces. Ceiling fan variants dominate volume shipments across tropical and subtropical climates where baseline air movement substitutes for compressor-based cooling. Wi-Fi-enabled technology segments capture expanding margin pools as consumers prioritize whole-home automation interoperability over standalone Bluetooth units. Voice control methods are gaining fastest in hospitality and premium residential settings where hands-free operation aligns with service-experience standards.
FCC certification governs radio-frequency emissions for connected fan products sold in the United States, while EU CE marking and REACH compliance constrain material selection and electromagnetic compatibility for European market access. India's BIS mandatory registration scheme for electronic products enforces safety and performance benchmarks that shape domestic manufacturing investment patterns. Stakeholders must monitor evolving interoperability standards between proprietary smart home ecosystems and open protocols as platform exclusivity risks fragmenting addressable demand.
Market Dynamics
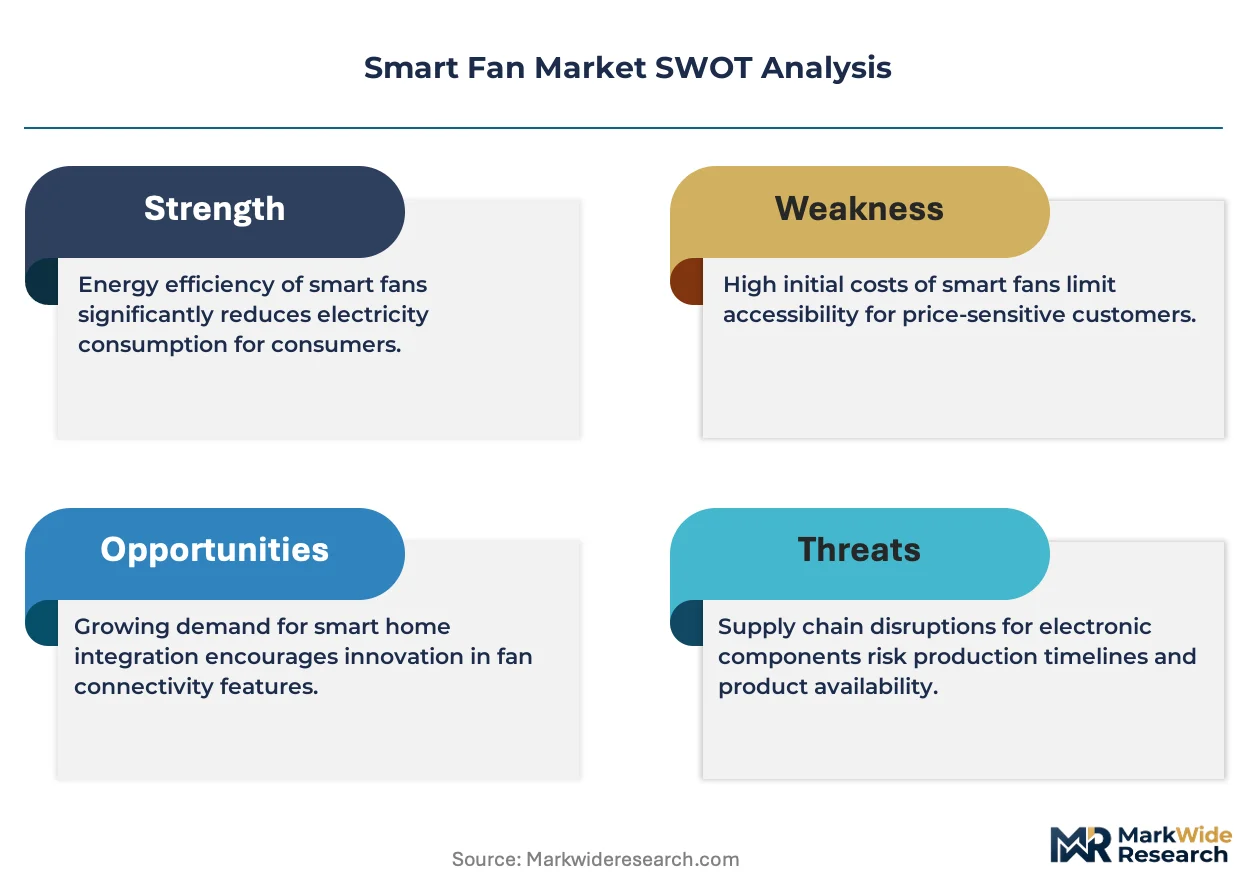
Residential smart home ecosystems are pulling smart fans from standalone appliances into integrated climate nodes, forcing manufacturers to prioritize interoperability protocols over proprietary control architectures.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for electronic manufacturing are attracting component suppliers to set up brushless DC motor facilities near final assembly hubs.
- Wi-Fi 6 mesh penetration:Whole-home network coverage eliminates dead zones that previously limited ceiling fan connectivity in multi-story residences.
- Hospitality retrofit cycles:Hotel operators are specifying voice-controlled units to reduce housekeeping touchpoints and align with post-pandemic service protocols.
Market Restraints
- Copper and rare-earth magnet costs:Brushless DC motor production remains exposed to NdFeB magnet price volatility from concentrated Chinese refining capacity.
- FCC certification timelines:Radio-frequency testing queues for Wi-Fi modules extend product launch windows by eight to fourteen weeks.
- Ceiling retrofit labor intensity:Smart fan installation requires electrical box upgrades that generalist contractors often refuse, constraining replacement demand.
Strategic Opportunities
- Tier-2 Indian cities:BIS-certified affordable Wi-Fi platforms can capture first-time smart home adopters before ecosystem lock-in solidifies.
- Agricultural outbuilding climate control:Livestock ventilation and greenhouse humidity management represent untapped demand for sensor-enabled circulation systems.
- Matter protocol adoption:Cross-platform interoperability standards are reducing development overhead for manufacturers previously forced into multiple certification tracks.
Industry Challenges
- Firmware security maintenance:Connected devices require ongoing patch cycles that strain legacy appliance manufacturers without established software operations.
- Integration complexity with proprietary HVAC systems:Nest, Ecobee, and Carrier control architectures use non-standard APIs that complicate unified climate automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Fan Market |
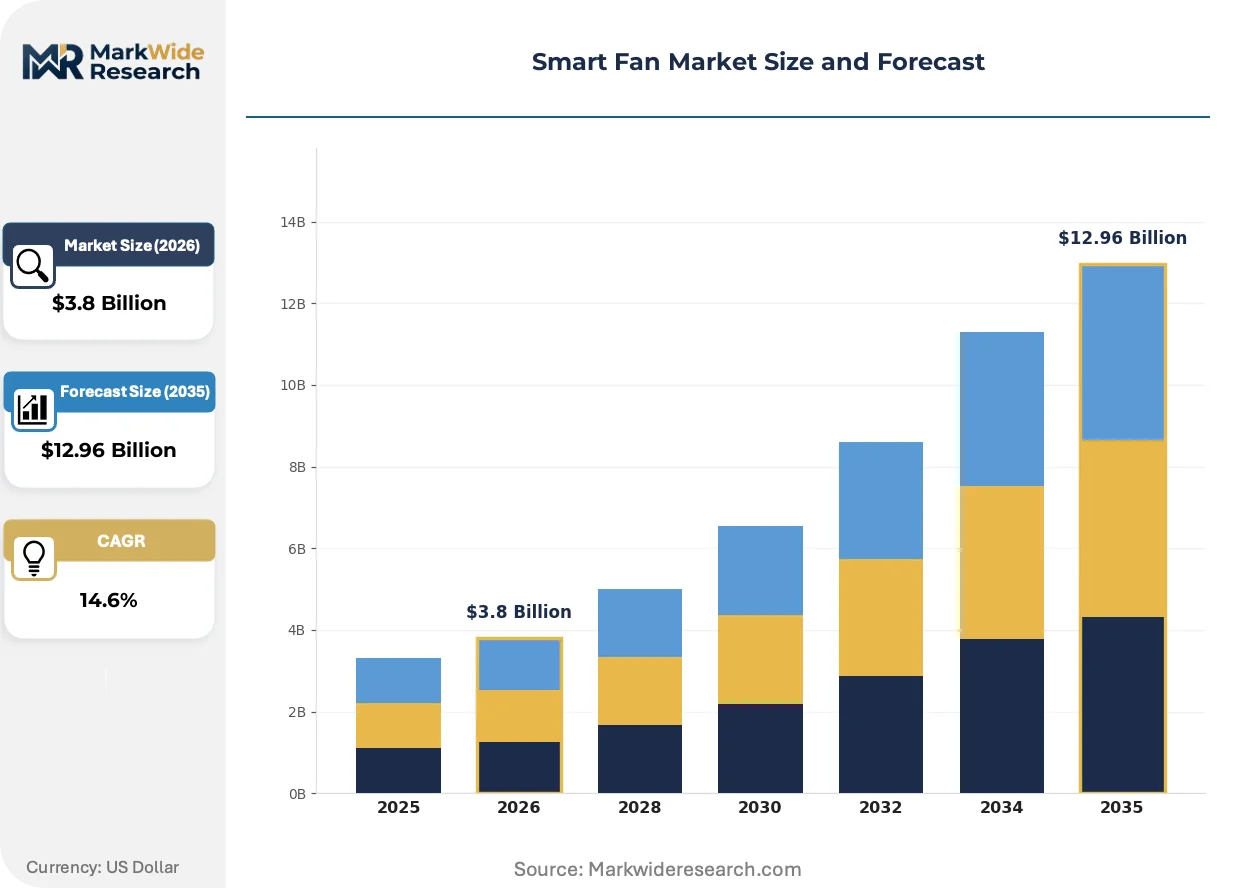
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceiling Fan, Table Fan, Wall-Mounted Fan, Pedestal Fan Technology: Wi-Fi, Bluetooth, Zigbee, Infrared Control Method: Remote Control, Mobile App, Voice Control, Sensor-Based End User: Residential, Commercial, Industrial, Hospitality |
| Companies Covered | Hunter Fan Company, Orient Electric, Havells, Panasonic, Emerson Electric, Big Ass Fans, Fanimation, Minka-Aire, Delta T, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Fan Market Emerging Trajectories
Smart fan development is converging on three vectors: sensor fusion for autonomous operation, regulatory pressure on material composition, and procurement model evolution toward ecosystem bundling rather than standalone sales.
Environmental sensing arrays are integrating particulate matter, volatile organic compound, and humidity detection into ceiling-mounted platforms. Hospitality operators and premium residential developers are specifying these units at accelerating rates. The technology is integrating air quality management with thermal comfort, compressing the addressable market for standalone purifiers.
India's BIS mandatory registration scheme for electronic products is tightening electromagnetic compatibility testing requirements for Wi-Fi-enabled fans. Domestic manufacturers are redesigning power supply architectures to meet revised surge immunity benchmarks. Smaller importers without in-country testing partnerships are exiting rather than absorbing compliance costs.
Builder procurement patterns are shifting from unit-by-unit specification toward master agreements with smart home platform providers. Lennar, PulteGroup, and regional Indian developers are pre-installing ecosystem-compatible fans as standard rather than upgrade options. This channel compression is most visible in US Sun Belt master-planned communities and Bangalore tech corridor residential towers.
Smart Fan Market Segmentation
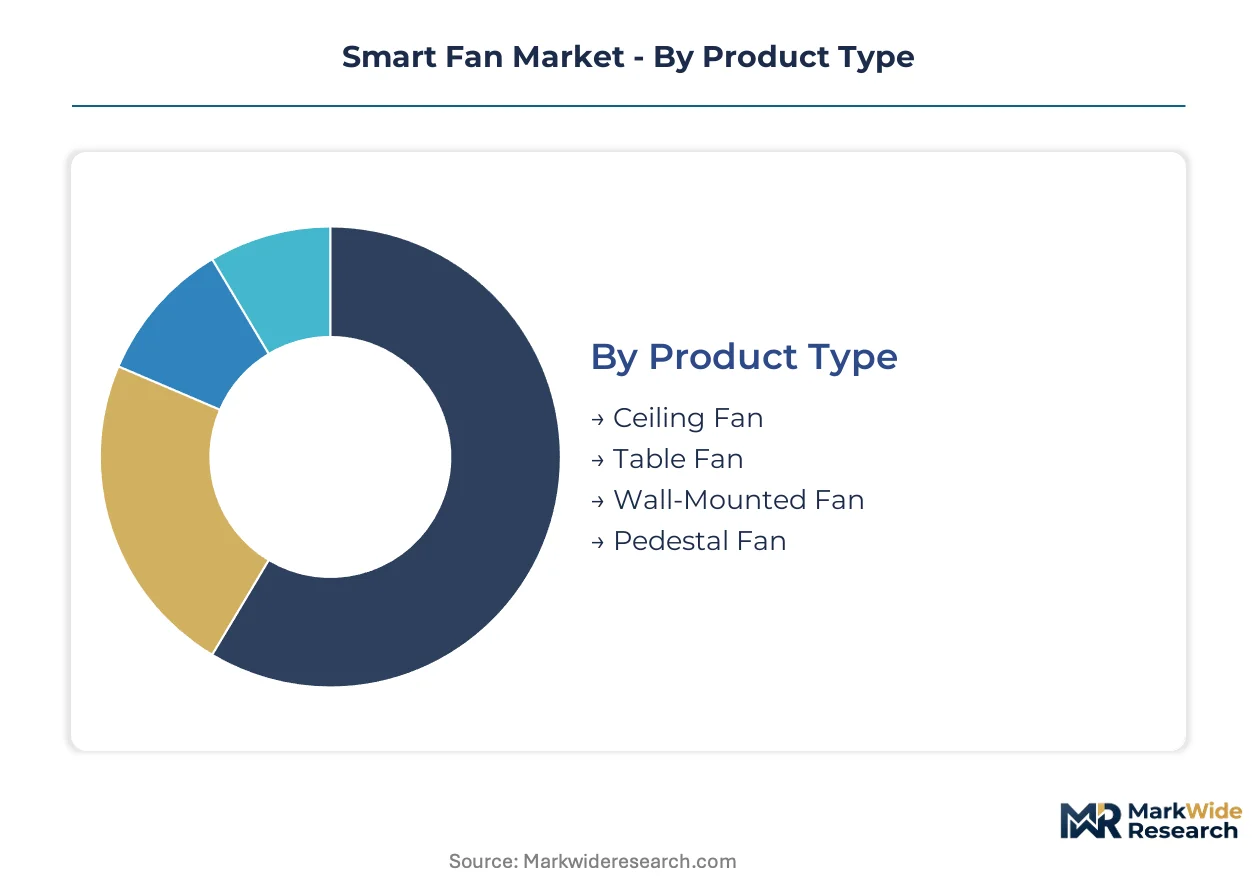
Smart fan manufacturers engineer product portfolios around four intersecting dimensions that determine both unit economics and ecosystem compatibility. Each segmentation axis carries distinct margin profiles, certification requirements, and channel access rules that shape competitive positioning.
Product Type:
Ceiling configurations dominate unit shipments across tropical markets where air circulation substitutes for compressor-based cooling, while portable formats command premium positioning in developed economies.
- Ceiling Fan:Integrates brushless DC motors with wireless modules into overhead electromechanical platforms operating at 15–35 watts. Demand concentrates in Indian tier-1 cities and tech corridors where BIS certification mandates and PLI scheme incentives are accelerating domestic manufacturing investment.
- Table Fan:Compact portable units with rechargeable battery options and USB-C power delivery. North American specialty retail channels and European apartment dwellings prioritize these for localized airflow control without installation infrastructure.
- Wall-Mounted Fan:Space-constrained circulation solutions for commercial kitchens, workshops, and agricultural outbuildings. Indian and Southeast Asian small commercial facilities specify these for directed ventilation.
- Pedestal Fan:Height-adjustable floor-standing platforms with oscillation mechanics. Hospitality retrofit cycles in post-pandemic service environments are specifying voice-controlled variants to reduce housekeeping touchpoints.
Today's leader: Ceiling Fan. Tomorrow's challenger: Table Fan.
Technology:
Connectivity protocols determine interoperability scope, with whole-home automation compatibility commanding margin premiums over standalone operation.
- Wi-Fi:Direct cloud connectivity enabling remote operation and firmware updates without hub dependency. Wi-Fi 6 mesh penetration is eliminating dead zones that previously constrained ceiling fan connectivity in multi-story residences.
- Bluetooth:Point-to-point pairing with limited range requiring proximity control. Budget-conscious first-time adopters in price-sensitive markets accept this constraint for lower hardware cost.
- Zigbee:Low-power mesh networking optimized for battery-operated sensors and coordinated multi-device scenes. Matter protocol adoption is reducing development overhead for manufacturers previously forced into multiple certification tracks.
- Infrared:Legacy line-of-sight control from dedicated remotes without smartphone integration. Declining specification rates as consumers prioritize whole-home automation interoperability.
Wi-Fi captures expanding margin pools. Zigbee gains fastest through ecosystem bundling.
Control Method:
Interface design determines user adoption curves and support cost structures, with hands-free operation commanding premium positioning in service-oriented environments.
- Remote Control:Physical handheld units with tactile feedback for basic speed and timer functions. Remains standard specification in Indian mass-market channels where smartphone penetration lags among older demographics.
- Mobile App:Smartphone-based interfaces enabling scheduling, energy monitoring, and scene creation. Builder procurement patterns are shifting from unit-by-unit specification toward master agreements with smart home platform providers.
- Voice Control:Hands-free operation through Alexa, Google Assistant, or Siri integration. Hospitality operators and premium residential developers are specifying these units at accelerating rates to align with service-experience standards.
- Sensor-Based:Autonomous operation triggered by occupancy detection, temperature thresholds, or air quality readings. Environmental sensing arrays are integrating particulate matter and humidity detection into ceiling-mounted platforms.
Mobile App anchors current volume. Voice Control climbs fastest in premium segments.
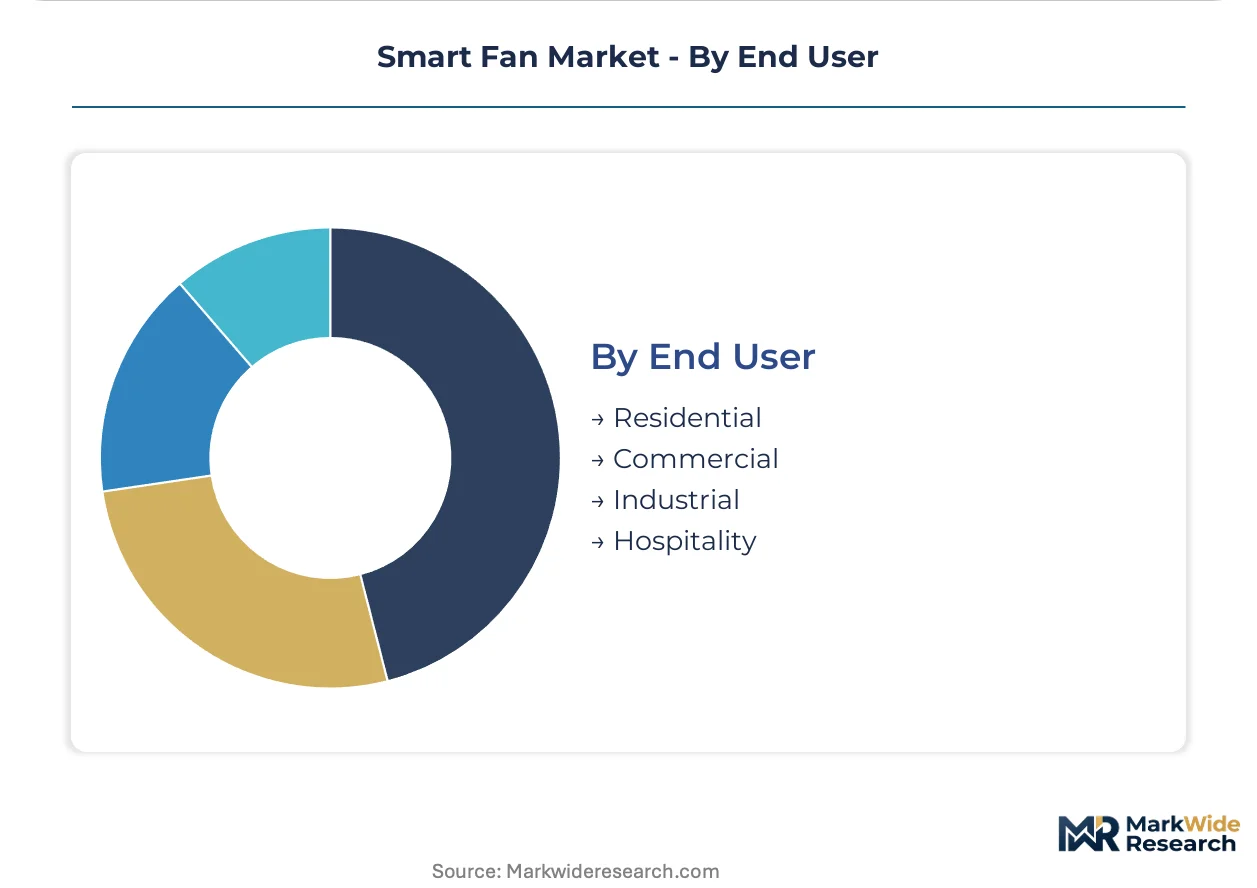
End User:
Application context determines performance specifications, duty cycles, and procurement authority structures.
- Residential:Individual consumer purchases for climate comfort and smart home ecosystem integration. India's tier-2 cities represent untapped demand for BIS-certified affordable Wi-Fi platforms before ecosystem lock-in solidifies.
- Commercial:Office, retail, and institutional installations prioritizing energy management and centralized control. FCC certification timelines for Wi-Fi modules extend product launch windows, constraining rapid specification turnover.
- Industrial:High-velocity circulation for manufacturing floors, warehouses, and logistics facilities. Copper and rare-earth magnet cost volatility from concentrated Chinese refining capacity pressures motor production economics.
- Hospitality:Hotel, restaurant, and entertainment venue specifications emphasizing guest experience and operational efficiency. Post-pandemic service protocols are accelerating voice-controlled unit adoption to reduce housekeeping touchpoints.
Residential drives absolute volume. Hospitality delivers steepest expansion trajectory through retrofit cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrical engineering talent pools in Bangalore and Shenzhen anchor smart fan development clusters, while manufacturing workforce concentrations in Gujarat and Guangdong Province drive component assembly scale.
United States
Post-pandemic hospitality retrofit cycles and Sun Belt residential construction are accelerating voice-controlled ceiling fan specifications. FCC certification governs radio-frequency emissions for Wi-Fi-enabled products, with testing queues extending launch timelines. Dallas-Fort Worth and Phoenix master-planned communities are pre-installing ecosystem-compatible units as standard builder offerings.
India
Tier-1 cities and emerging tech corridors in tier-2 markets are prioritizing energy-efficient climate control solutions. BIS mandatory registration enforces electromagnetic compatibility and safety benchmarks, while PLI scheme incentives attract brushless DC motor suppliers to Gujarat and Tamil Nadu assembly hubs. Ahmedabad and Coimbatore manufacturing clusters are scaling domestic production capacity.
Germany
Premium residential developers and commercial building retrofits are specifying sensor-integrated climate systems. CE marking and REACH compliance constrain material selection and electromagnetic compatibility for market access. Munich and Stuttgart engineering centers are advancing environmental sensing arrays for autonomous operation.
China
Component supply concentration for rare-earth magnets and brushless DC motor production shapes global cost structures. GB standards and MIIT regulations govern wireless communication modules and energy efficiency labeling. Shenzhen and Dongguan electronics manufacturing clusters are integrating Wi-Fi 6 modules into ceiling platform designs.
Japan
High-end residential and hospitality segments are demanding air quality-integrated circulation systems. METI efficiency standards and JIS certification requirements shape product development cycles. Osaka and Nagoya industrial corridors are advancing particulate matter and humidity detection integration into overhead platforms.
Smart Fan Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across a fragmented vendor base where no single participant commands dominant share. Tiered competition separates heritage craftsmanship anchors, cost-engineered volume producers, and sensor-technology integrators. Strategic moves concentrate on ecosystem partnership formations and certification track consolidation as Matter protocol adoption reduces multi-platform development overhead.
Among North American heritage manufacturers, Hunter Fan Company and Big Ass Fans occupy positions emphasizing brand equity and specialty channel relationships. Orient Electric exemplifies the cost-engineered Wi-Fi platform archetype tailored to emerging market voltage conditions. Panasonic anchors the sensor-integration vector, extending capabilities from adjacent climate control portfolios.
| Leading Market Players |
|---|
| Hunter Fan Company |
| Orient Electric |
| Havells |
| Panasonic |
| Emerson Electric |
| Big Ass Fans |
| Fanimation |
| Minka-Aire |
| Delta T |
| Others |
Supply Flow & Price Mechanics
Electrical engineering talent pools in Shenzhen and Bangalore anchor development cost structures that widen spreads between premium sensor-integrated units and economy Wi-Fi platforms. Labor-cost differentials between these clusters and assembly hubs in Gujarat and Guangdong Province enable tiered pricing architectures that separate voice-controlled hospitality specifications from mass-market residential offerings.
Pricing Analysis
Bundled ecosystem procurement through builder master agreements commands premium positioning against unbundled retail transactions. Three-tier pricing structure across premium, standard, and economy levels separates Matter-certified voice-control units from basic Wi-Fi platforms and legacy infrared models. Cost compression in the economy tier is intensifying because Indian PLI scheme incentives are attracting brushless DC motor suppliers to domestic assembly hubs. Mass-market residential buyers in India's tier-2 cities exhibit highest price sensitivity, while hospitality procurement officers prioritize interoperability over unit cost.
Supply Chain Analysis
Rare-earth magnet supply rests on concentrated Chinese refining capacity for NdFeB materials essential to brushless DC motor production. Component sourcing draws from China for wireless communication modules, India for final assembly labor, and Japan for precision sensor arrays. Single-source vulnerability in magnet refining creates exposure to export restriction shocks. Distribution runs through North American specialty retail channels, Indian multi-brand outlets, and European electrical wholesale networks serving contractor specification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart fan economics favor margin expansion through sensor-integrated premium tiers displacing standalone air purifiers, while PLI scheme cost-down support in India compresses economy-tier landed costs.
For Market Incumbents: Acquire firmware development capabilities to address security maintenance burdens that strain legacy appliance operations. Secure BIS certification partnerships in India before smaller importers exit, locking in tier-2 city channel access. Matter protocol adoption reduces multi-platform development overhead, but ecosystem exclusivity risks fragmenting addressable demand if proprietary HVAC APIs remain non-standard. For New Entrants and Emerging Players: Launch via agricultural outbuilding channels targeting livestock ventilation and greenhouse humidity management with sensor-enabled circulation systems. Tier-2 Indian cities represent the most penetrable geography before ecosystem lock-in solidifies, accessible through BIS-certified affordable Wi-Fi platforms. Voice-controlled hospitality retrofit cycles offer fastest payback through reduced housekeeping touchpoints. For Investors and Strategic Acquirers: Diversified HVAC conglomerates are the most active acquirer in this space, seeking sensor-integration capabilities to extend adjacent climate control portfolios. Long-term viability hinges on software operations maturity for firmware security cycles. Watch Matter protocol adoption rates as inflection indicator for development overhead reduction and platform consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Manufacturing | PLI scheme incentives in Gujarat and Tamil Nadu enable captive brushless DC production. |
| Matter Protocol Certification | Cross-platform interoperability reduces multi-ecosystem development overhead for manufacturers. |
| Sensor Fusion Platform Launch | Particulate matter and humidity detection integration compresses standalone purifier addressable markets. |
| Builder Master Agreement Formation | Lennar and PulteGroup procurement patterns favor pre-installed ecosystem-compatible specifications. |
| Tier-2 India Distribution Expansion | BIS-certified Wi-Fi platforms capture first-time smart home adopters before ecosystem lock-in. |
Methodological Framework
Multiple input streams — primary interviews with smart home platform engineers, electrical contractor procurement heads, and hospitality facilities managers; secondary validation through BIS registration databases, FCC equipment authorization filings, and PLI scheme disbursement records — were reconciled through bottom-up unit shipment modeling and top-down value aggregation. Primary fieldwork captured installation labor constraints and retrofit cycle timing. Secondary sources included customs trade data for rare-earth magnet flows, SEC 10-K disclosures from diversified HVAC conglomerates, and builder procurement contract announcements.
Data-stream reconciliation anchored volume projections to Wi-Fi 6 mesh penetration curves, BIS certification timeline trajectories, and hospitality retrofit cycle frequencies across the analysis window. Segmentation dimensions modeled include product type, connectivity protocol, control interface, and end-use application, with regional regulatory cluster overlays for certification requirement variations. CAGRs were derived from installed base growth rates and replacement demand elasticity. Forecast inputs incorporated brushless DC motor cost curves and voice-control integration adoption slopes.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rare-earth export restriction shocks or Matter protocol adoption delays. Projections reflect assumptions on PLI scheme continuation, BIS electromagnetic compatibility test queue lengths, and hospitality capital expenditure recovery trajectories. Material deviation in NdFeB magnet pricing or Wi-Fi module FCC certification timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Porcelain Insulators Market
Electrical Equipment
Electric Control Panel Market
Electrical Equipment
High Voltage PTC Heater Market
Electrical Equipment
High Voltage Switchboard Market
Electrical Equipment
North America Low Voltage Induction Motors Market
Electrical Equipment
Electrical Fuses Market
Electrical Equipment
Europe Circuit Breakers Market
Electrical Equipment
Global Electrical Steel Market
Electrical Equipment
Electrical Measuring Instrument Market
Electrical Equipment
MCB and MCCB Market
Electrical Equipment
Europe Electrical Bushing Market
Electrical Equipment
Electrical Sub Panels Market
Electrical Equipment
Industrial Plugs and Sockets Market
Electrical Equipment
Medium Voltage Circuit Breakers Market
Electrical Equipment
Magnetic Contactors Market
Electrical Equipment
Waveguide Market