
 Axial Fans Market | 2026-2036
Axial Fans Market Size, Share, and Industry Trends Forecast 2026-2036
Axial Fans Market Analysis
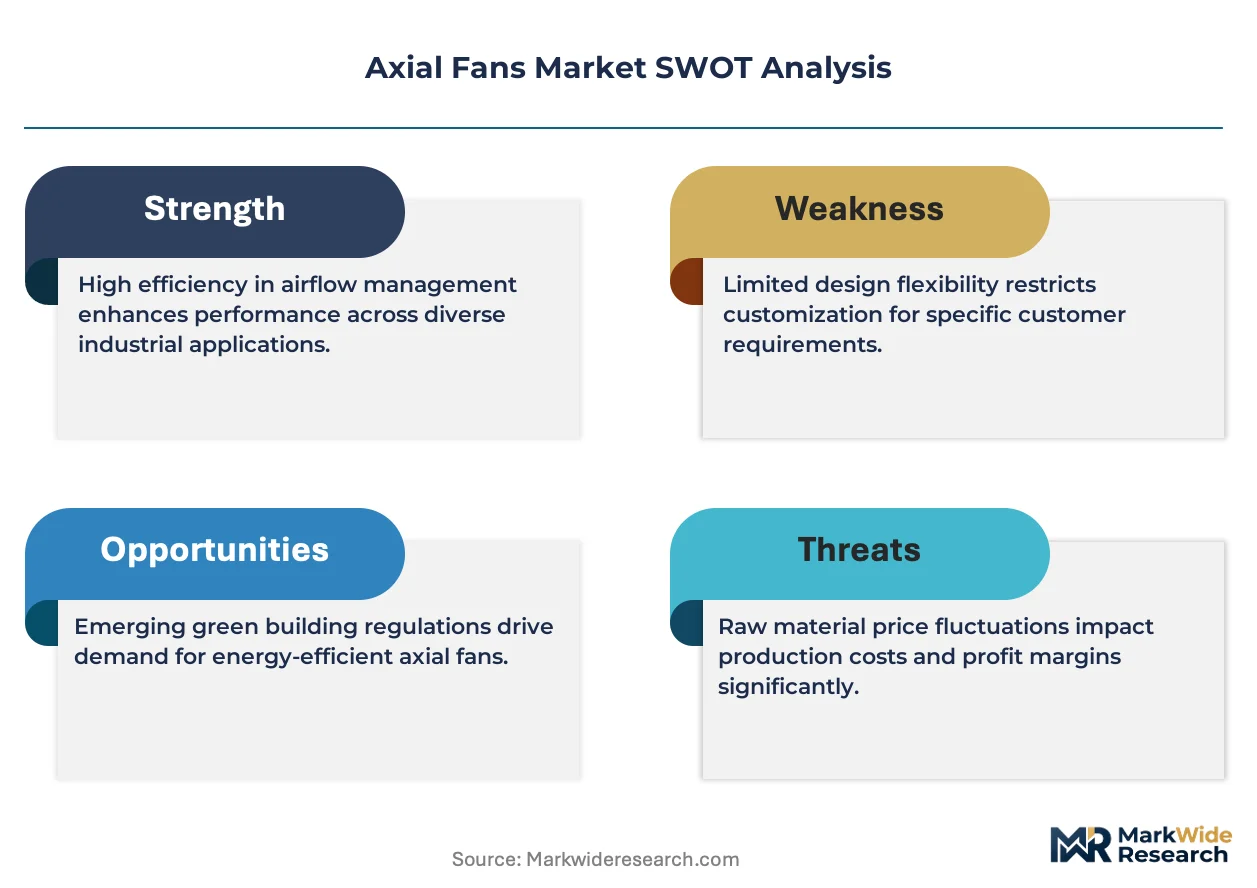
The capital-intensity divergence between fully integrated motor-fan manufacturers and assembly-only suppliers is bifurcating competitive returns across the Axial Fans Market. Greenheck Fan Corporation leverages domestic foundry and fabrication assets to sustain margin control across commercial HVAC specifications. FläktGroup Holding GmbH anchors European project engineering capabilities, competing on custom air-handling configurations for industrial clients. Zhejiang Langdi Group Co., Ltd. dominates cost-optimized volume production, positioning its mixed-flow units for Asian infrastructure tenders.
Axial fans move air parallel to the impeller shaft using blade-generated pressure differentials, typically achieving static efficiencies between 40% and 65% depending on blade pitch and hub-to-tip ratio. Their primary purpose spans forced ventilation, process cooling, and combustion air supply across commercial and industrial facilities. Electric motor technology leads installed base value, though solar-powered units represent the fastest-expanding niche for off-grid agricultural and remote construction applications. Industrial ventilation applications command the deepest margin pools due to corrosion-resistant materials and explosion-proof certification requirements, while HVAC systems occupy the highest unit volume tier.
EPA efficiency mandates under the Energy Policy and Conservation Act tighten motor performance thresholds, compelling manufacturers to redesign impeller-motor pairings. ISO 13350 and AMCA 210 testing standards govern certified airflow and acoustic ratings, creating compliance barriers for unvalidated imports. REACH substance restrictions in Europe limit certain blade coatings and bearing lubricants, reshaping material selection across export-oriented suppliers. Stakeholders must monitor regulatory harmonization between efficiency codes and chemical safety frameworks as these dual compliance layers determine market access trajectories.
Market Dynamics
Data center thermal loads from AI training clusters are compressing fan replacement cycles and forcing redesigns of blade geometries and motor pairings across the Axial Fans Market. This demand shock is restructuring procurement priorities toward high-static-pressure configurations.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants is accelerating demand for direct air-cooling architectures in commercial refrigeration and HVAC retrofits across Germany, France, and Italy.
- Data center construction:Hyperscale facility buildouts in Northern Virginia, Frankfurt, and Singapore are specifying redundant axial fan arrays for aisle containment and hot-aisle exhaust systems.
- Permanent magnet synchronous motors:Rare-earth magnet motor integration is cutting energy consumption by 15-30% in continuous-duty ventilation applications, satisfying tightening efficiency mandates.
Market Restraints
- Copper and steel price volatility:Stator windings and stamped impeller housings face input cost swings that compress assembler margins, particularly for mid-tier suppliers without captive metalworking.
- Foundry concentration in China:Gray iron and aluminum die-casting capacity clusters in Shandong and Jiangsu provinces create geographic supply risk for motor housings and fan casings.
- Acoustic performance ceilings:Blade pass frequency noise limits in ISO 13350 testing constrain maximum rotational speeds for large-diameter units, capping airflow density in compact footprints.
Strategic Opportunities
- India industrial corridors:The Delhi-Mumbai Industrial Corridor and Chennai-Bengaluru corridor are tendering large-scale ventilation infrastructure with localization requirements favoring domestic assembly partnerships.
- Solar-direct DC fans:Off-grid agricultural drying and remote telecom shelter cooling are opening volume niches for photovoltaic-coupled axial units with integrated maximum power point tracking.
- US Inflation Reduction Act:Commercial building efficiency tax credits are subsidizing HVAC upgrades, creating retrofit demand for electronically commutated motor-fan packages in Class B and C office stock.
Industry Challenges
- Computational fluid dynamics talent scarcity:Optimizing blade profiles for specific pressure-flow curves requires specialized simulation expertise that competes with automotive and aerospace sectors for hiring.
- Multi-certification timelines:Simultaneous pursuit of AMCA 210, UL 705, and ATEX approvals extends product launch cycles by 8-14 months for explosion-proof industrial specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Axial Fans Market |
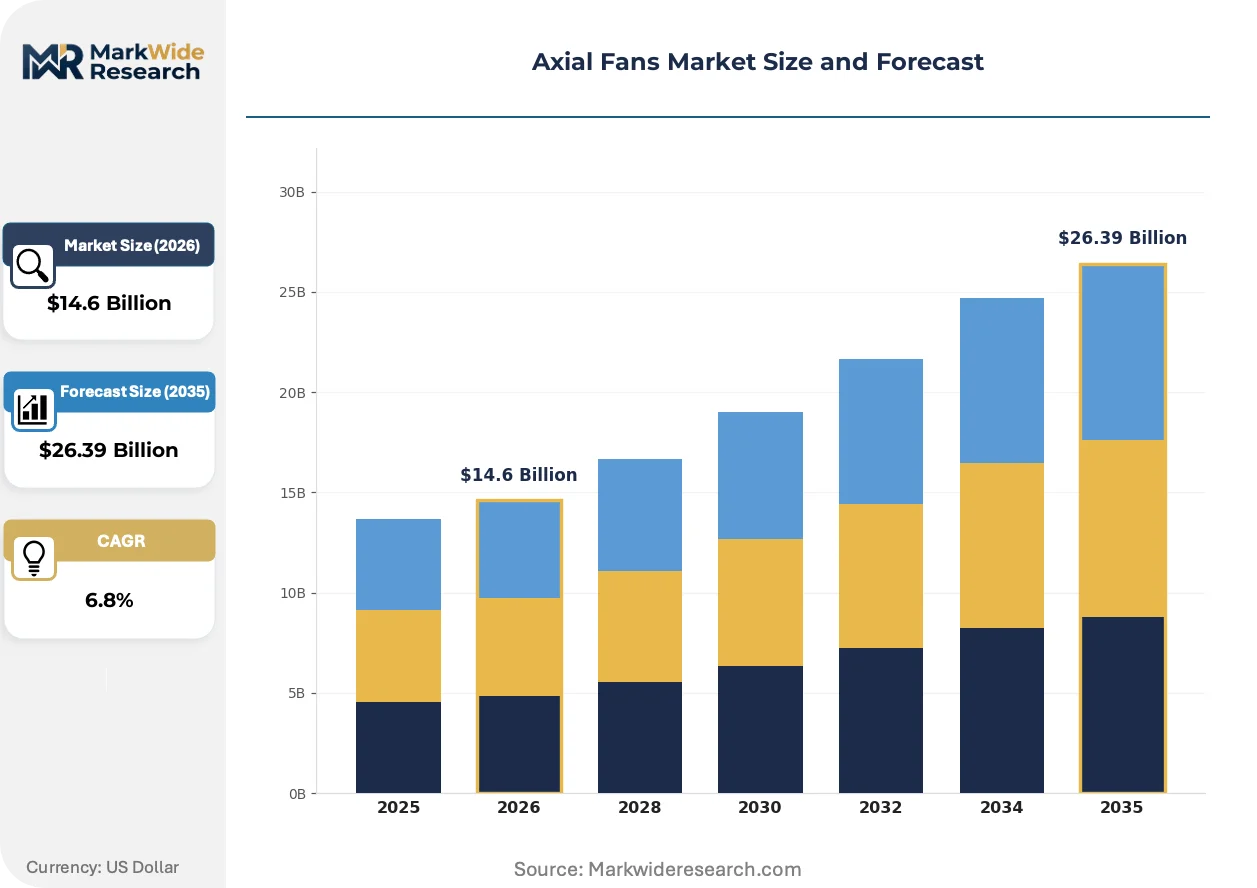
| Market Size in 2026 | $14.6 Billion |
| Market Size in 2035 | $26.39 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Axial Flow, Mixed Flow, Roof Extractor, Multi-Blade Application: Industrial Ventilation, HVAC Systems, Cooling Towers, Power Generation Technology: Electric, Mechanical, Solar, Propeller End User: Manufacturing, Construction, Shipping, Agriculture |
| Companies Covered | Greenheck Fan Corporation, FläktGroup Holding GmbH, Zhejiang Langdi Group Co., Ltd., Systemair AB, Panasonic Corporation, ebm-papst Group, Nidec Corporation, Zhejiang Yilida Ventilator Co. Ltd, Delta Electronics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Axial Fans Market Emerging Trajectories
Active noise cancellation and predictive maintenance integration are repositioning axial fans from commodity airflow hardware to intelligent building infrastructure nodes. These embedded capabilities are altering value capture toward software-enabled service models.
Variable pitch blade systems with electromechanical actuation are bifurcating the market between fixed-geometry commodity units and adaptive-performance premium tiers. Data center operators in Singapore and the Netherlands are specifying these for dynamic load matching. The technology is bifurcating procurement patterns, with hyperscalers paying 40-60% premiums for tunable airflow while standard commercial buyers consolidate on fixed-pitch SKUs.
REACH substance restrictions on perfluorinated compounds and certain epoxy formulations are forcing reformulation of blade coatings and motor potting compounds. European suppliers are qualifying water-based alternatives and ceramic-filled polymers ahead of 2025 enforcement windows. Industrial ventilation segments with corrosion-resistant specifications face the steepest compliance costs and longest validation timelines.
Direct-to-facility procurement through manufacturer-configured online platforms is displacing traditional distribution for standardized commercial HVAC fans. Mechanical contractors in Texas and Florida are specifying units through digital configurators that bypass wholesaler markup. This channel compression is most visible in replacement markets where performance specifications are pre-validated and installation labor is decoupled from equipment sourcing.
Axial Fans Market Segmentation
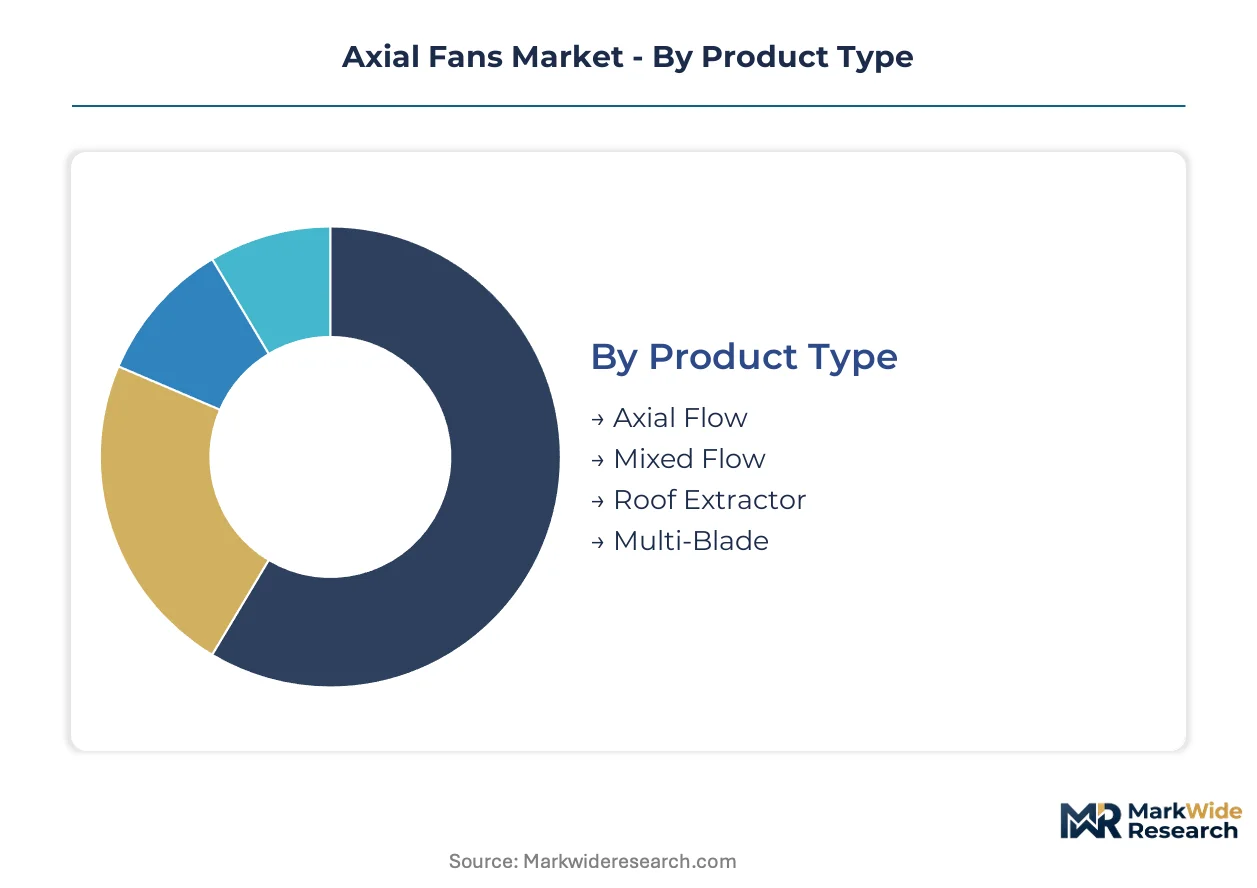
Axial fan procurement patterns diverge sharply across product architectures and duty cycles, with efficiency mandates and thermal load profiles reshaping specification priorities. Regulatory pressure on motor performance and refrigerant phaseouts is forcing buyers to rebalance first-cost against lifecycle operating expenditure.
Product Type:
REACH substance restrictions and EPA efficiency thresholds split certification pathways across blade geometries and housing materials.
- Axial Flow:Straight-blade impellers generate pressure differentials parallel to the shaft axis, achieving 40-65% static efficiency depending on hub-to-tip ratio. Data center cooling in Northern Virginia and Frankfurt specifies high-static-pressure variants for hot-aisle containment, with AI training clusters compressing replacement cycles.
- Mixed Flow:Diagonal blade configurations merge axial and centrifugal pressure characteristics, enabling higher pressure rises in compact footprints. Zhejiang Langdi Group dominates cost-optimized production for Asian infrastructure tenders, positioning units where space constraints override pure axial efficiency.
- Roof Extractor:Weather-hardened housings with gravity dampers exhaust process heat and combustion byproducts from commercial kitchens and light manufacturing.
- Multi-Blade:Forward-curved impeller arrays prioritize low-noise operation over peak efficiency, serving residential and institutional HVAC retrofits.
Established volume favors Axial Flow; emerging adoption favors Mixed Flow.
Application:
Margin pools concentrate where corrosion resistance and explosion-proof certification raise technical barriers to entry.
- Industrial Ventilation:Chemical-resistant coatings and ATEX-rated motor enclosures command premium pricing for petrochemical, mining, and waste processing facilities. Multi-certification timelines for AMCA 210, UL 705, and ATEX approvals extend launch cycles by 8-14 months, capping supplier participation.
- HVAC Systems:Electronically commutated motor-fan packages dominate unit volume, with US Inflation Reduction Act tax credits accelerating Class B and C office retrofits. Procurement is shifting toward manufacturer-configured digital platforms that displace traditional distribution channels in Texas and Florida replacement markets.
- Cooling Towers:Large-diameter units with fiberglass-reinforced polymer housings serve evaporative heat rejection in power plants and industrial process loops.
- Power Generation:Forced-draft and induced-draft configurations handle combustion air supply and flue gas extraction across gas turbine and combined-cycle installations.
Industrial Ventilation captures the deepest margin tier; HVAC Systems anchor the highest unit throughput.
Technology:
Energy conversion architecture determines compliance positioning against tightening efficiency mandates.
- Electric:Permanent magnet synchronous motors with rare-earth magnet integration cut consumption 15-30% in continuous-duty applications. EPA Energy Policy and Conservation Act thresholds compel impeller-motor pairing redesigns across the installed base.
- Solar:Photovoltaic-coupled DC units with integrated maximum power point tracking serve off-grid agricultural drying and remote telecom shelters, expanding most quickly among technology categories.
- Mechanical:Belt-drive and direct-drive configurations persist in heavy-industrial duty cycles where motor replaceability outweighs integrated efficiency.
- Propeller:Unshrouded blade arrays for low-pressure, high-volume agricultural and warehouse ventilation.
Electric dominates specification compliance; Solar gains share fastest in distributed energy applications.
End User:
Capital expenditure cycles and localization requirements reshape procurement channel structures.
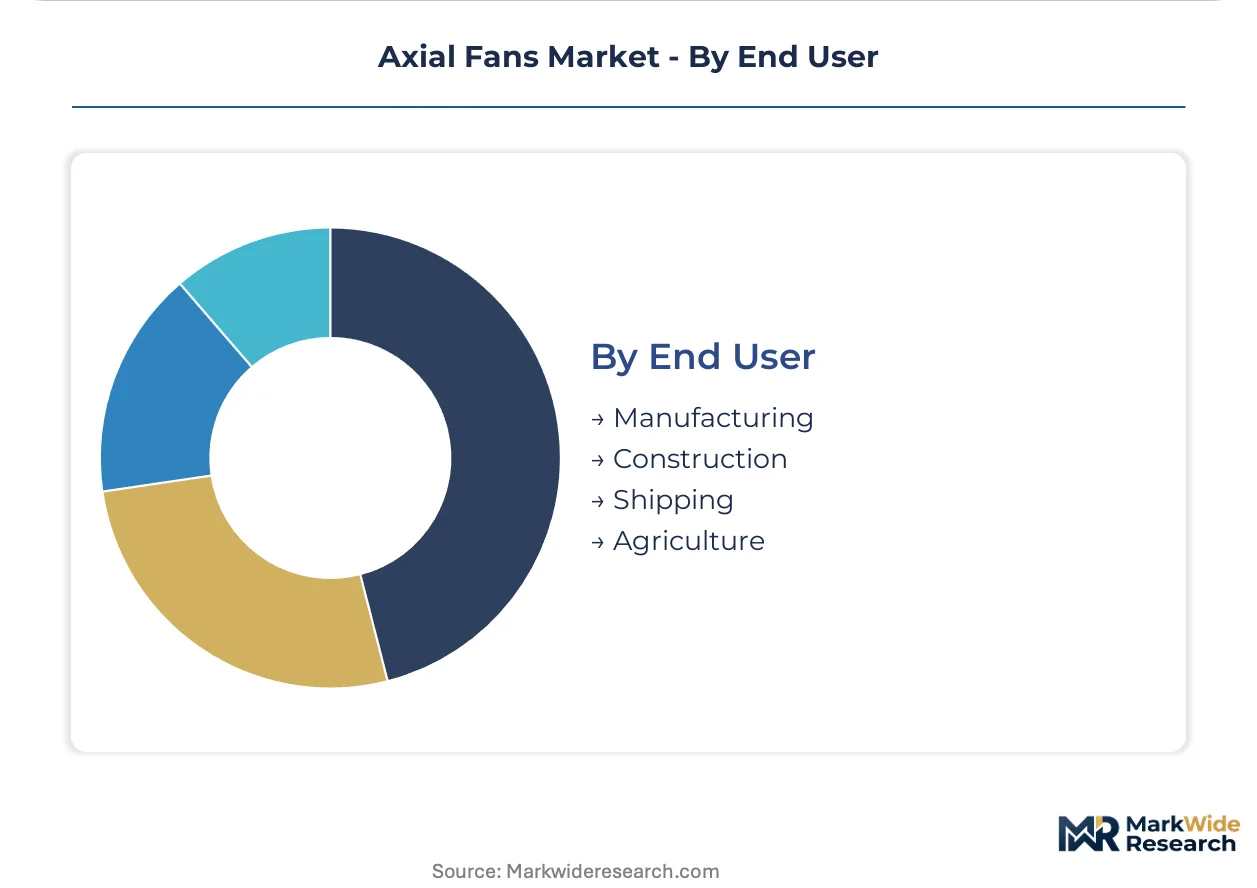
- Manufacturing:Process cooling and fume extraction demand ISO 13350-certified acoustic ratings and corrosion-resistant materials. India’s Delhi-Mumbai Industrial Corridor tenders specify domestic assembly partnerships, favoring joint-venture structures over direct import.
- Construction:Temporary ventilation for tunneling, high-rise concrete curing, and confined-space work drives rental fleet demand with rapid deployment specifications.
- Shipping:Marine engine room ventilation and cargo hold climate control require salt-spray-resistant coatings and compact footprints for engine-limited spaces.
- Agriculture:Grain drying, livestock ventilation, and greenhouse climate control specify moisture-resistant motors and variable-speed drives for humidity-responsive operation.
Manufacturing anchors equipment value; Agriculture shows steepest expansion trajectory in solar-direct configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement contexts, with hyperscale data center operators absorbing 40-60% premiums for tunable airflow while commercial HVAC buyers consolidate on fixed-pitch units. Infrastructure tenders in emerging economies prioritize first-cost minimization, whereas European industrial buyers weight lifecycle operating expenditure under tightening efficiency mandates.
China
Industrial capacity expansion and infrastructure buildout concentrate the highest volume demand globally. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate motor efficiency upgrades across manufacturing facilities. Foundry and fabrication capacity clusters in Shandong and Jiangsu provinces supply gray iron and aluminum die-castings for motor housings and fan casings.
United States
Hyperscale data center construction in Northern Virginia specifies redundant axial fan arrays for aisle containment and hot-aisle exhaust systems. The EPA enforces Energy Policy and Conservation Act efficiency mandates that tighten motor performance thresholds and compel impeller-motor pairing redesigns. Texas and Florida mechanical contractors increasingly specify units through manufacturer-configured digital platforms that displace traditional distribution channels.
Germany
Commercial refrigeration and HVAC retrofits accelerate under the EU F-Gas Regulation phasedown of hydrofluorocarbon refrigerants, driving direct air-cooling architectures. The KBA and federal efficiency frameworks align with EU Green Deal targets for building energy performance. Frankfurt's hyperscale facility buildouts specify high-static-pressure configurations for thermal management of AI training clusters.
India
The Delhi-Mumbai Industrial Corridor and Chennai-Bengaluru corridor tender large-scale ventilation infrastructure with localization requirements favoring domestic assembly partnerships. The BIS and CEA enforce efficiency standards that reshape procurement specifications for process cooling and fume extraction. Manufacturing investment concentrates in Maharashtra and Gujarat where joint-venture structures displace direct import channels.
Singapore
Data center operators specify variable pitch blade systems with electromechanical actuation for dynamic load matching in tropical climates with high ambient temperatures. The national building authority enforces Green Mark certification standards that prioritize energy-efficient ventilation architectures. Island-wide facility buildouts compress fan replacement cycles as AI workloads expand thermal management requirements.
Axial Fans Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the Axial Fans Market. Fully integrated motor-fan manufacturers with captive foundry and fabrication assets sustain margin control, while assembly-only suppliers face compressed returns from copper and steel price volatility. Three archetypes dominate: domestic integrated manufacturers with upstream metalworking, European project engineering specialists with custom air-handling capabilities, and Asian volume producers with cost-optimized mixed-flow platforms. Capacity expansion and strategic partnerships represent the dominant competitive moves, with joint-venture structures proliferating in markets with localization mandates.
Among the integrated manufacturing tier, Greenheck Fan Corporation and FläktGroup Holding GmbH exemplify divergent geographic anchoring strategies, with the former representing North American vertical integration and the latter occupying European project engineering positioning. Zhejiang Langdi Group Co., Ltd. sits within the cost-optimized volume production archetype, its mixed-flow units targeting Asian infrastructure tenders where space constraints override pure axial efficiency. These three entities collectively illustrate how capital-intensity divergence bifurcates competitive returns across specification tiers.
| Leading Market Players |
|---|
| Greenheck Fan Corporation |
| FläktGroup Holding GmbH |
| Zhejiang Langdi Group Co., Ltd. |
| Systemair AB |
| Panasonic Corporation |
| ebm-papst Group |
| Nidec Corporation |
| Zhejiang Yilida Ventilator Co. Ltd |
| Delta Electronics Inc. |
| Others |
Supply Flow & Price Mechanics
AMCA 210 and ISO 13350 certification requirements gate both supplier qualification and price differentiation simultaneously, bifurcating procurement between validated premium tiers and unvalidated economy imports. Compliance costs compress assembler margins while creating pricing power for integrated manufacturers with captive testing facilities.
Pricing Analysis
After-sales service contracts and spare parts revenue drive lifetime value capture across the installed base. Three-tier pricing structure across premium, standard, and economy levels separates ATEX-certified industrial units from commercial HVAC packages and unbranded replacement imports. Price differentiation hinges on certification grade and motor efficiency tier, with EPA Energy Policy and Conservation Act thresholds widening spreads between compliant and non-compliant offerings. Pricing pressure stems from copper and steel input volatility, compressing mid-tier assembler returns. Commercial HVAC buyers exhibit highest price sensitivity, while hyperscale data center operators absorb premiums for tunable airflow configurations.
Supply Chain Analysis
Strategic stockpiling of rare-earth magnets and gray iron castings prevails over just-in-time preferences given foundry concentration risks. Supply concentrates in China, Germany, and the United States for motor assemblies, blade fabrications, and control electronics respectively. Raw material dependencies center on copper windings, aluminum die-castings, and neodymium magnets. Single-source vulnerability in Shandong and Jiangsu foundry clusters creates geographic concentration risk for motor housings. Distribution runs through manufacturer-configured digital platforms displacing traditional wholesaler channels in Texas and Florida replacement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computational fluid dynamics expertise scarcity constrains blade optimization capabilities, with automotive and aerospace sectors competing for simulation talent. This capability gap determines competitive positioning across high-static-pressure and variable-pitch product tiers.
For Market Incumbents: Fortify upstream control over foundry and fabrication assets to defend margin position against copper price volatility. Expand captive metalworking capacity in domestic markets to insulate from Shandong and Jiangsu supply concentration. Deepen certification investment across AMCA 210, UL 705, and ATEX portfolios to extend compliance barriers for unvalidated imports. For New Entrants and Emerging Players: Lead with solar-direct DC configurations targeting off-grid agricultural drying and remote telecom shelter cooling where incumbents lack dedicated product lines. Penetrate India's Delhi-Mumbai Industrial Corridor through domestic assembly joint ventures satisfying localization mandates. Deploy manufacturer-configured digital platforms to bypass traditional distribution markups in replacement markets. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across permanent magnet synchronous motor integration as rare-earth magnet content raises working capital requirements. Long-term viability favors fully integrated motor-fan manufacturers with backward integration into metalworking over assembly-only suppliers. Target acquisition archetypes include European project engineering specialists with custom air-handling capabilities and Asian volume producers with cost-optimized mixed-flow platforms. Watch hyperscale data center capex announcements as inflection indicator for high-static-pressure demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Captive foundry investment in domestic markets insulates margin from Shandong supply concentration. |
| Backward Integration | In-house production of stator windings and impeller housings compresses cost structure against steel volatility. |
| Joint Venture | Domestic assembly partnerships in India satisfy Delhi-Mumbai Industrial Corridor localization requirements. |
| Product Launch | Variable pitch blade systems with electromechanical actuation capture 40-60% premiums from hyperscale operators. |
| Strategic Partnership | Computational fluid dynamics collaborations with automotive simulation houses address talent scarcity constraints. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade data, and industry technical standards. Primary interviews engaged plant engineers, OEM procurement teams, aftermarket service heads, and HVAC contractors across commercial and industrial installation bases. Secondary validation drew from EPA efficiency mandate documentation, EU F-Gas Regulation implementation guidance, AMCA certification databases, and customs records for motor-fan trade flows. Bottom-up unit economics triangulated against top-down market sizing across product architectures and duty cycles.
Segmentation dimensions modeled include blade geometry configuration, application thermal load profile, motor technology architecture, and end-user capital expenditure cycle. CAGRs derived from installed base replacement dynamics, efficiency mandate compliance timelines, and infrastructure tender pipelines across the projection horizon. Forecast inputs incorporated data center construction permits, industrial corridor investment announcements, and agricultural drying electrification rates.
The analysis sits within stated boundaries; outcomes outside EPA efficiency threshold enforcement or EU F-Gas Regulation phasedown schedules would require recalibration. Forecasts reflect assumptions regarding rare-earth magnet supply continuity and foundry capacity expansion in Shandong and Jiangsu provinces. Revision becomes warranted when copper price volatility crosses thresholds that compress mid-tier assembler viability or when hyperscale data center thermal load specifications diverge from current blade geometry optimization targets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Busbar Trunking System Market
Electrical Equipment
Electric Wall Heaters Market
Electrical Equipment
United Kingdom Thermal Protector Market
Electrical Equipment
Global Capacitor Bank Controllers Market
Electrical Equipment
South America High Voltage Switchgear Market
Electrical Equipment
Soft Starter Market
Electrical Equipment
Europe Electrical Bushing Market
Electrical Equipment
Magnetic Contactors Market
Electrical Equipment
Wire Splicing Kits Market
Electrical Equipment
Hermetic Reciprocating Refrigerator Compressor Market
Electrical Equipment
Europe Electric Insulator Market
Electrical Equipment
Electrical Enclosures Market
Electrical Equipment
Ground Fault Circuit Interrupter Market
Electrical Equipment
Consumer Electronics High Voltage Electric Capacitor Market
Electrical Equipment
Low Voltage Circuit Breakers Market
Electrical Equipment
India Electrical Enclosures Market