
 Ultra High Voltage (UHV) Appliances Market | 2026-2036
Ultra High Voltage (UHV) Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra High Voltage (UHV) Appliances Market Insights
A shift from single-source to multi-source procurement is recalibrating how grid operators secure UHV switchgear and transformer assemblies. Hyundai Electric & Energy leverages its Korean manufacturing base to compete for Middle East and Southeast Asian contracts. ABB anchors its position through technology leadership in gas-insulated systems for dense urban substations. Mitsubishi Electric specializes in hybrid UHV solutions that reduce footprint in land-constrained Japanese and Taiwanese installations.
Ultra High Voltage appliances encompass electrical equipment engineered to operate at alternating current ratings of 800 kV or above, with direct current systems reaching 800 kV to 1100 kV, utilizing sulfur hexafluoride gas insulation, composite bushings, and advanced composite materials to minimize corona discharge and dielectric losses over distances exceeding 1000 kilometers. Their primary purpose is to enable bulk power transmission with reduced resistive losses compared to conventional high voltage networks. Transformers dominate product type revenue due to the extreme material intensity of core steel and winding copper in UHV ratings. Gas insulated technology leads the technology dimension where space constraints and pollution exposure favor enclosed SF6 architectures, while superconducting systems represent the fastest-growing technology category as cryogenic cooling costs decline. Utilities command the largest end user share, though renewable energy applications are expanding fastest as offshore wind and desert solar projects require UHV export capacity.
China's MIIT enforces GB standards for UHV equipment interoperability and domestic content ratios that shape supplier qualification requirements. India's CEA mandates centralized testing protocols for 765 kV and 1200 kV class equipment under the national grid code, creating compliance barriers for non-certified manufacturers. The EU F-Gas Regulation is phasing down SF6 availability, forcing insulation technology transitions that will reshape product development priorities. Stakeholders must monitor how alternative insulation chemistries perform in accelerated aging tests before committing capital to next-generation UHV platforms.
Market Dynamics
China's dual carbon mandates and India's Green Energy Corridor directives are forcing a wholesale replacement of conventional transmission infrastructure with UHV-rated systems capable of bridging 1000+ kilometer renewable supply chains to coastal demand centers.
Growth Catalysts
- Renewable integration mandates:China's MIIT enforces domestic content ratios for UHV equipment interoperability, accelerating local manufacturing scale-up for 800 kV and 1200 kV class systems.
- SF6 phase-down protocols:The EU F-Gas Regulation is compressing availability of sulfur hexafluoride insulation, stimulating R&D investment in alternative dielectric chemistries and gas mixtures.
- Desert solar export corridors:India's CEA centralized testing protocols for 765 kV equipment under the national grid code are standardizing qualification pathways for Rajasthan and Gujarat solar farm interconnections.
Market Restraints
- Core steel supply concentration:Grain-oriented electrical steel production concentrates in a handful of East Asian and European mills, creating input cost volatility for UHV transformer core assemblies.
- Cryogenic cooling cost barriers:Superconducting UHV systems require liquid nitrogen infrastructure that remains economically prohibitive for all but the most space-constrained urban substations.
- Extended certification timelines:India's CEA mandates multi-year type-testing protocols for 1200 kV class equipment, stretching supplier qualification cycles beyond typical capital planning horizons.
Strategic Opportunities
- Hybrid insulation architectures:Mitsubishi Electric's hybrid UHV solutions for Japanese and Taiwanese installations demonstrate viable pathways for footprint reduction in dense urban environments.
- Offshore wind export capacity:North Sea and East Asian offshore wind clusters require UHV DC links to transmit gigawatt-scale generation to onshore load centers without intermediate conversion losses.
- PLI scheme manufacturing incentives:India's production-linked incentive schemes for power equipment are attracting Korean and European suppliers to establish domestic UHV component assembly operations.
Industry Challenges
- SF6 alternative validation gaps:Accelerated aging test data for fluoronitrile and vacuum interrupter technologies remains insufficient for utilities to commit procurement budgets to next-generation platforms.
- Specialized winding technician scarcity:UHV transformer manufacturing requires craftsmen capable of handling ultra-high-purity copper winding processes that resist automation and carry decades of tacit knowledge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra High Voltage (UHV) Appliances Market |
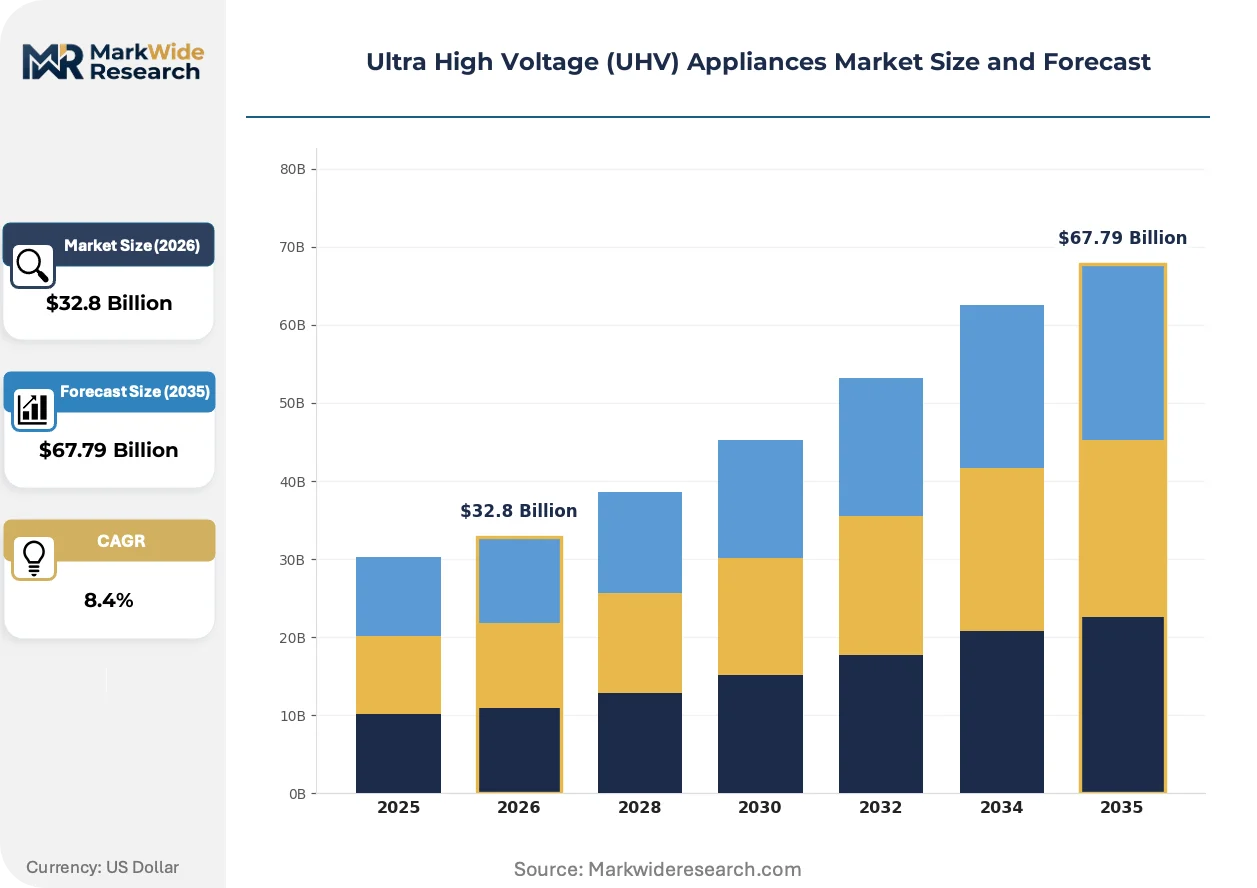
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $67.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transformers, Switchgear, Capacitors, Circuit Breakers End User: Utilities, Industrial Plants, Renewable Energy, Transportation Technology: Gas Insulated, Air Insulated, Hybrid Systems, Superconducting Application: Power Transmission, Substation Automation, Grid Integration, Voltage Regulation |
| Companies Covered | Hyundai Electric & Energy, Pinggao, China XD Group, Shanghai Sieyuan, Xuji Electric, ABB, Baoding Tianwei Group, Nari Technology, Mitsubishi Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra High Voltage (UHV) Appliances Market Trends and Innovations
Insulation chemistry transitions and procurement model fragmentation are simultaneously disrupting equipment specifications and supplier qualification pathways across major UHV corridors.
Composite bushing systems utilizing silicone rubber housing and fiber-reinforced epoxy cores are replacing traditional porcelain insulators in pollution-prone environments. State Grid Corporation of China and Power Grid Corporation of India are specifying composite interfaces for new 800 kV line installations. This material transition is integrating polymer science expertise from aerospace and automotive supply chains into electrical equipment manufacturing, compressing development cycles for next-generation outdoor termination assemblies.
The EU F-Gas Regulation mandates an 80% reduction in SF6 emissions by 2030, forcing manufacturers to accelerate fluoronitrile and vacuum interrupter commercialization. Siemens Energy and Hitachi Energy are piloting g3 gas mixtures in live 420 kV installations ahead of UHV scaling. European utilities face the steepest compliance curves, with German transmission system operators already incorporating SF6-free specifications into 2030 procurement tenders.
Utility procurement departments are unbundling transformer supply from installation and long-term service contracts, creating discrete vendor categories for OEMs, EPC integrators, and predictive maintenance providers. This disaggregation allows Chinese state-owned utilities to source core assemblies from domestic manufacturers while contracting European firms for site commissioning and digital monitoring systems. The pattern is most visible in China's western province renewable integration projects, where multi-source procurement has become standard practice.
Ultra High Voltage (UHV) Appliances Market Segmentation
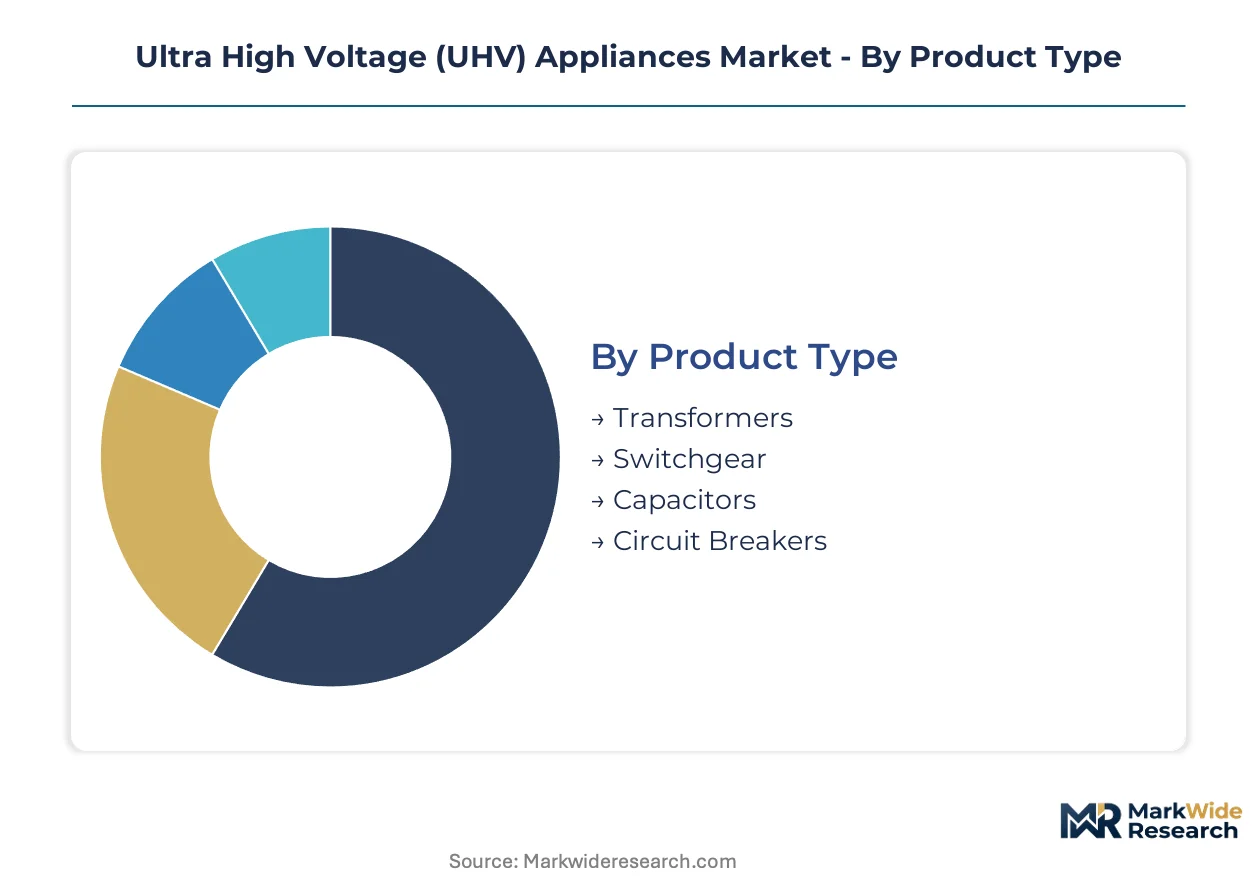
UHV appliance specifications diverge sharply across voltage classes and insulation architectures. Procurement teams weight material intensity, footprint constraints, and regulatory compliance differently depending on corridor geography and grid code requirements.
Product Type:
Material composition and winding precision separate premium UHV assemblies from standard high-voltage equipment.
- Transformers:Core assemblies utilize grain-oriented electrical steel with ultra-low core loss specifications, while windings demand high-purity copper processed under contamination-controlled conditions. State Grid Corporation of China sources these for 800 kV and 1200 kV corridors linking western renewable zones to eastern load centers, with domestic content ratios enforced under MIIT interoperability standards.
- Switchgear:Enclosed SF6 or alternative gas architectures house disconnectors and earthing switches in modular tank designs. India's CEA centralized testing protocols for 765 kV class equipment are standardizing qualification pathways for Rajasthan solar farm interconnections.
- Capacitors:Series compensation banks stabilize reactive power across 1000+ kilometer transmission spans.
- Circuit Breakers:Ultra-high-speed interruption mechanisms clear fault currents within critical stability windows.
Transformers lead on scale; switchgear leads on momentum as SF6 phase-down accelerates alternative insulation development.
End User:
Customer procurement authority and capital planning horizons reshape equipment specification priorities across segments.
- Utilities:Transmission system operators command multi-billion dollar procurement budgets with decade-long asset replacement cycles. China's western provinces concentrate the heaviest demand where massive solar and wind farms require UHV export capacity to coastal cities under dual carbon mandates.
- Renewable Energy:Offshore wind and desert solar developers require dedicated UHV links without intermediate conversion infrastructure. Green Energy Corridor directives in India are accelerating 765 kV and 1200 kV class orders for Gujarat and Rajasthan project clusters.
- Industrial Plants:Aluminum smelters and steel mills negotiate direct UHV connections for gigawatt-scale load centers.
- Transportation:Railway electrification authorities specify compact substation designs for high-speed corridor power feeds.
Utilities dominate absolute volume; renewable energy climbs fastest as generation assets migrate to remote high-resource zones.
Technology:
Insulation chemistry and cooling architecture determine footprint, maintenance intervals, and regulatory compliance exposure.
- Gas Insulated:SF6 or fluoronitrile mixtures enable 70% footprint reduction versus air-insulated equivalents, critical for dense urban substations in Japanese and Taiwanese installations. EU F-Gas Regulation mandates are compressing SF6 availability and stimulating g3 gas mixture pilots by Siemens Energy and Hitachi Energy.
- Superconducting:Cryogenic liquid nitrogen cooling eliminates resistive losses entirely, though infrastructure costs restrict deployment to space-constrained urban cores. Cost curves are declining as cooling system manufacturing scales.
- Air Insulated:Conventional porcelain bushing designs persist in rural corridors with abundant land availability.
- Hybrid Systems:Mitsubishi Electric combines gas-insulated compactness with air-insulated maintainability for Japanese land-constrained environments.
Gas insulated maintains volume leadership; superconducting gains share fastest as cryogenic infrastructure costs compress.
Application:
Functional role within the power system determines voltage rating, control system integration depth, and automation requirements.
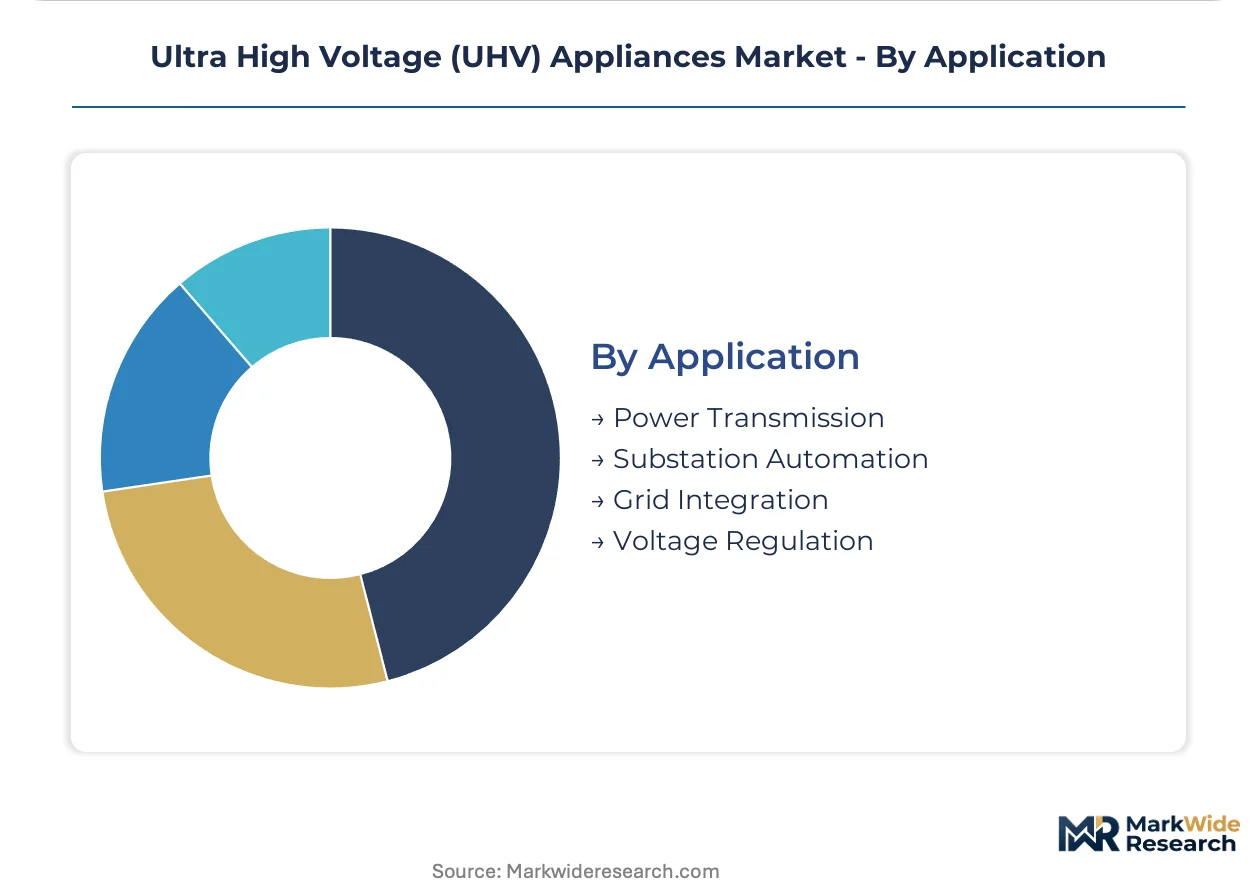
- Power Transmission:Bulk energy transfer across 1000+ kilometer corridors demands 800 kV AC and 1100 kV DC ratings with minimal intermediate substations. China's western province projects exemplify this architecture.
- Grid Integration:Synchronization equipment connects asynchronous renewable zones to synchronous main grids. India's national grid code mandates specific testing protocols for these interfaces.
- Substation Automation:Digital control systems enable remote operation and predictive maintenance for unmanned UHV facilities.
- Voltage Regulation:On-load tap changers and static VAR compensators maintain power quality across fluctuating renewable injection patterns.
Power transmission anchors capital deployment; grid integration expands most quickly as asynchronous renewable penetration rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting UHV manufacturing investment toward jurisdictions with domestic content incentives and centralized testing protocols. South Korean and European suppliers are establishing assembly operations in India to capture PLI scheme benefits, while Chinese state-owned utilities enforce MIIT interoperability standards that favor local core steel sourcing.
China
Western provinces including Xinjiang and Gansu host massive solar and wind farms requiring 800 kV and 1200 kV corridors to eastern load centers. MIIT enforces GB standards for equipment interoperability and domestic content ratios that shape supplier qualification. State Grid Corporation concentrates procurement in Shaanxi and Ningxia for renewable export capacity.
India
Rajasthan and Gujarat solar clusters drive 765 kV and 1200 kV class orders under Green Energy Corridor mandates. CEA centralized testing protocols create compliance barriers for non-certified manufacturers. Korean and European suppliers are establishing domestic assembly operations to capture PLI scheme incentives for power equipment manufacturing.
Japan
Land-constrained urban substations in Tokyo and Osaka favor hybrid UHV solutions that reduce footprint. METI oversees grid code requirements for equipment interoperability. Mitsubishi Electric anchors domestic manufacturing for Taiwanese and Southeast Asian export markets.
Germany
Transmission system operators incorporate SF6-free specifications into 2030 procurement tenders under EU F-Gas Regulation mandates. Siemens Energy pilots g3 gas mixtures in live installations ahead of UHV scaling. Industrial demand concentrates in the Ruhr corridor for aluminum smelter and steel mill connections.
South Korea
Hyundai Electric leverages domestic manufacturing to compete for Middle East and Southeast Asian contracts. MFDS-equivalent grid standards govern equipment certification for export markets. Busan-Ulsan industrial clusters anchor transformer core steel processing for regional supply.
Ultra High Voltage (UHV) Appliances Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue alternative insulation chemistries and service-based revenue models. The market structures around three tiers: integrated conglomerates with captive core steel supply, specialized switchgear manufacturers with gas-insulated expertise, and predictive maintenance providers unbundled from hardware supply. Strategic moves concentrate on geographic expansion through local assembly partnerships and technology licensing for SF6 alternative validation.
Among Asia-Pacific-based fabricators, Pinggao and China XD Group exemplify the integrated conglomerate archetype with domestic content ratio compliance, while ABB anchors the technology licensing tier for European alternative gas pilots. Mitsubishi Electric occupies a position bridging compact hybrid solutions for dense urban environments. These three represent distinct strategic postures: state-backed scale, regulatory-driven technology transfer, and footprint-optimized specialization.
| Leading Market Players |
|---|
| Hyundai Electric & Energy |
| Pinggao |
| China XD Group |
| Shanghai Sieyuan |
| Xuji Electric |
| ABB |
| Baoding Tianwei Group |
| Nari Technology |
| Mitsubishi Electric |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed producers in China and state-rolled Korean conglomerates anchor supply-side discipline, compressing procurement costs through captive grain-oriented electrical steel capacity while enforcing long-term contract pricing that shields utilities from spot volatility in copper winding materials.
Pricing Analysis
Distributor margins for UHV transformer assemblies compress at the 800 kV threshold where direct-to-utility procurement displaces intermediary layers. Three-tier pricing structure across premium certified, standard qualified, and economy domestic tiers separates ABB's gas-insulated systems from Chinese state-owned alternatives. Cost compression in the standard tier intensifies as MIIT domestic content ratios force localization. Renewable energy developers exhibit highest price sensitivity; transmission system operators absorb premiums for 1200 kV class reliability.
Supply Chain Analysis
Refurbishment flows for UHV transformer cores concentrate in Busan-Ulsan industrial clusters where Hyundai Electric reprocesses grain-oriented electrical steel for regional resale. China, South Korea, and Japan supply 90% of ultra-high-purity copper windings and SF6 gas insulation. Single-source vulnerability in cryogenic cooling equipment for superconducting systems threatens project timelines. Distribution runs through state-owned utility procurement departments with decade-long master service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in UHV appliances rests on cryogenic infrastructure cost curves declining faster than transformer core steel inflation, enabling superconducting premiums to capture widening spreads over conventional gas-insulated systems.
For Market Incumbents: Extend service contract bundling into predictive maintenance platforms to capture recurring revenue as hardware commoditizes under Chinese domestic content mandates. Deepen backward integration into grain-oriented electrical steel through Korean and Japanese mill partnerships to defend input cost position against volatile East Asian supply. Certification investment in fluoronitrile gas mixtures addresses EU F-Gas Regulation phase-down threats. For New Entrants and Emerging Players: Desert solar EPC contractors in Rajasthan and Gujarat represent the most penetrable buyer archetype as Green Energy Corridor mandates accelerate 765 kV procurement outside established supplier relationships. White-space exists in SF6 alternative validation services where accelerated aging test data gaps stall utility commitment. Target hybrid system integration for Japanese land-constrained substations through METI interoperability pathways. For Investors and Strategic Acquirers: Valuations sit cheapest among European switchgear specialists with g3 gas mixture pilots awaiting UHV scale certification. Long-term viability across the analysis window favors manufacturers with captive core steel supply or cryogenic cooling system partnerships. Acquisition targets should demonstrate CEA or MIIT qualification progress. Monitor EU F-Gas Regulation enforcement intensity as inflection indicator for alternative insulation chemistry adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Core Steel | Captive grain-oriented electrical steel supply insulates Hyundai Electric and Pinggao from East Asian mill price volatility. |
| SF6 Alternative Gas Certification | Siemens Energy and Hitachi Energy g3 mixture pilots under EU F-Gas Regulation create first-mover advantage in 2030 German tenders. |
| Domestic Assembly Partnerships | Korean and European suppliers establish Indian operations to capture PLI scheme incentives for Rajasthan solar interconnections. |
| Hybrid System Specialization | Mitsubishi Electric's compact architectures for Tokyo and Osaka substations command footprint-constrained premiums. |
| Long-term Service Unbundling | European firms capture Chinese western province commissioning and digital monitoring contracts separated from hardware supply. |
Research Methodology
Multiple input streams — utility procurement officer interviews, EPC contractor project databases, and regulatory filing analysis — were reconciled to construct demand-side estimates for UHV transformer and switchgear orders. Primary discussions with State Grid Corporation planning departments, CEA certification engineers, and Siemens Energy technology licensing teams informed technology transition timelines. Secondary validation drew from MIIT GB standard publications, EU F-Gas Regulation impact assessments, and Indian PLI scheme disclosure filings. Bottom-up project pipelines and top-down utility capital expenditure budgets were cross-referenced to anchor volume assumptions.
Historical order backlogs from transmission system operators were cross-referenced against panel input from equipment procurement directors to calibrate growth trajectories across the projection horizon. Segmentation modeling incorporated voltage class, insulation technology, end-user category, and geographic regulatory cluster dimensions. CAGRs were derived from utility renewable integration mandates and Green Energy Corridor directive implementation schedules. Cryogenic cooling cost curves and grain-oriented electrical steel price indices served as industry-specific forecast sensitivity inputs.
Underlying measurement precision varies by segment; superconducting system forecasts carry tighter precision than conventional gas-insulated equivalents given concentrated pilot project visibility. Forecasts reflect documented assumptions regarding MIIT domestic content enforcement and CEA certification timeline adherence. Practitioners should monitor EU F-Gas Regulation phase-down acceleration and Indian PLI scheme beneficiary announcements for early signals of supplier geographic repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Copper and Copper Alloy Busbars Market
Electrical Equipment
Europe Electric Drives Market
Electrical Equipment
Saudi Arabia Electric Motor Market
Electrical Equipment
North America Circuit Breakers Market
Electrical Equipment
India Electrical Enclosures Market
Electrical Equipment
Motor Control Centers (MMC) Market
Electrical Equipment
Air Circuit Breaker Market
Electrical Equipment
Busbar Systems Market
Electrical Equipment
Global Copper Clad Steel (CCS) Wire Market
Electrical Equipment
Vacuum Contactor Market
Electrical Equipment
HID Ballast Market
Electrical Equipment
Switchgear Monitoring System Market
Electrical Equipment
Portable Misting Fans Market
Electrical Equipment
Electrical Fuses Market
Electrical Equipment
Pad-Mounted Transformer Market
Electrical Equipment
Heat Shrink Terminations Market