
 Electrical Label Market | 2026-2036
Electrical Label Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical Label Market Analysis
Modular labeling kits that bundle pre-printed warning symbols with blank field-writeable surfaces are restructuring how electrical contractors procure safety identification. Brady Worldwide leverages its captive distribution network to sustain margins across industrial channels. 3M anchors its position through proprietary adhesive chemistry developed for high-temperature cable marking. Avery Dennison competes by extending film-based durability into photovoltaic and EV charging infrastructure applications.
An electrical label is a purpose-printed or digitally marked substrate, typically polyester or vinyl with pressure-sensitive adhesive backing, engineered to communicate voltage ratings, hazard classifications, and circuit identifiers under NFPA 70E and IEC 60601 exposure conditions. Self-adhesive labels occupy the largest volume position due to retrofit compatibility across legacy electrical panels, while heat-resistant labels capture expanding margin pools from transformer and switchgear OEMs. Equipment labels remain mature in residential wiring but show faster growth in commercial solar string combiner boxes where serial tracking meets arc-flash compliance.
OSHA mandates arc-flash boundary marking under 29 CFR 1910.335, while the EU RoHS directive and CE marking framework restrict halogenated substrates in labels sold into European electrical equipment. China's GB standards enforced by SAMR require bilingual hazard warnings on export-bound industrial control panels. Stakeholders must monitor how evolving national electrical codes recalibrate substrate thickness and print permanence specifications before committing to regional manufacturing footprints.
Market Dynamics
Modular labeling kits are restructuring contractor procurement patterns as electrical contractors shift from bulk blank stock to pre-configured safety bundles that reduce field installation time and compliance risk.
Growth Catalysts
- Data center expansion:Hyperscale facilities in the United States and Germany are consuming specialized arc-flash labels at volume as rack density increases thermal stress on identification substrates.
- OSHA 29 CFR 1910.335:The arc-flash boundary marking mandate is compelling facility managers to replace faded or non-compliant legacy labels across industrial electrical panels.
- Photovoltaic string combiners:Commercial solar installations in China require bilingual serial tracking labels that satisfy both GB standards and export destination requirements.
Market Restraints
- Petrochemical substrate volatility:Polyester and vinyl resin costs fluctuate with crude oil indices, compressing margins for pressure-sensitive adhesive label converters.
- East Asian supply concentration:Specialty high-temperature adhesives and halogen-free substrates depend on concentrated chemical manufacturing clusters in China and South Korea.
- RoHS substrate restrictions:The EU directive's halogenated compound limits force reformulation of legacy flame-retardant label materials, extending R&D cycles.
Strategic Opportunities
- EV charging infrastructure:DC fast-charging stations in Germany require weather-resistant cable markers that withstand thermal cycling and UV exposure.
- IEC 60601 medical equipment:The standard's biocompatibility and permanence requirements create premium positioning for film-based labels in diagnostic device manufacturing.
- Digital print-on-demand:Distributed manufacturing networks are enabling same-day custom label production for electrical contractors with variable circuit identifier needs.
Industry Challenges
- NFPA 70E certification timelines:Third-party arc-flash label validation extends product launch schedules by four to eight weeks for new substrate formulations.
- Legacy panel compatibility:Retrofit labeling on aged electrical equipment requires adhesive systems that bond to oxidized metal surfaces without surface preparation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical Label Market |
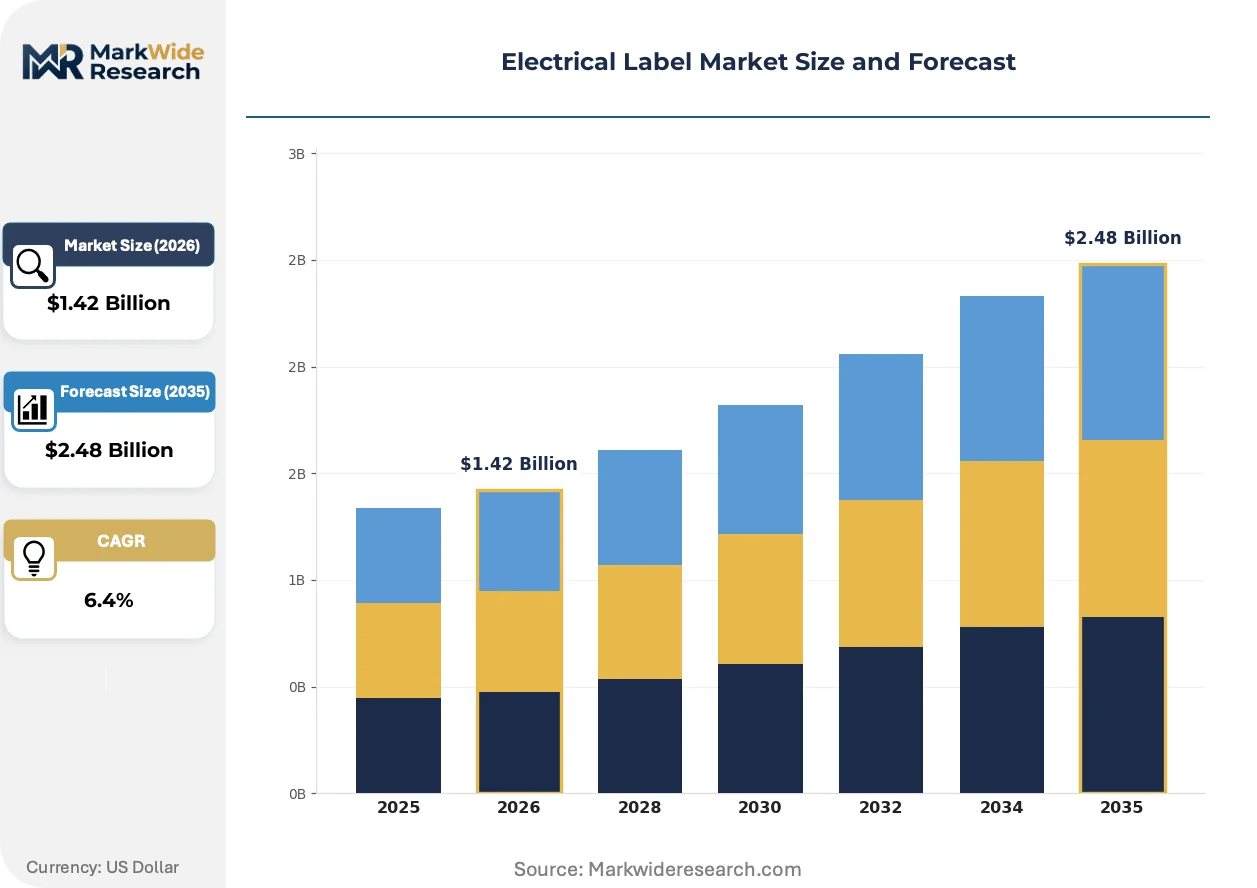
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Adhesive Labels, Heat-Resistant Labels, Warning Labels, Equipment Labels Material: Vinyl, Polyester, Paper, Polyethylene Application: Industrial Use, Residential Use, Commercial Use, Automotive Use End User: Manufacturers, Contractors, Retailers, Distributors |
| Companies Covered | Brady Worldwide, Seton, Brimar Industries, System Labels, Clarion Safety Systems, The Label Printers, CS Labels, Avery Dennison, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical Label Market Emerging Trajectories
Digital printing workflows and smart substrate engineering are compressing production lead times while expanding the functional range of electrical identification products beyond static hazard communication.
Near-field communication (NFC) embedded labels are integrating passive RFID chips into polyester substrates, enabling smartphone-based access to maintenance histories and arc-flash incident energy calculations. Industrial facility managers in the United States are piloting these connected identifiers in high-risk switchgear applications. The technology is integrating static compliance marking with dynamic asset management, compressing the distinction between safety labels and industrial IoT endpoints.
REACH substance restrictions are tightening compliance requirements for adhesive chemistry used in European electrical equipment exports. ECHA's candidate list expansions are forcing label manufacturers to reformulate pressure-sensitive systems around non-phthalate plasticizers and reduced-VOC solvents. German transformer OEMs are responding by qualifying alternative acrylic adhesive platforms that maintain high-temperature shear resistance without restricted substances.
Electrical contractors are consolidating supplier relationships around full-service identification vendors that bundle label design software, thermal transfer printers, and consumable programs. This vendor consolidation displaces fragmented procurement across separate label converters, printer distributors, and design consultancies. The pattern is most visible in United States commercial construction, where general contractors increasingly mandate single-source electrical identification compliance packages.
Electrical Label Market Segmentation
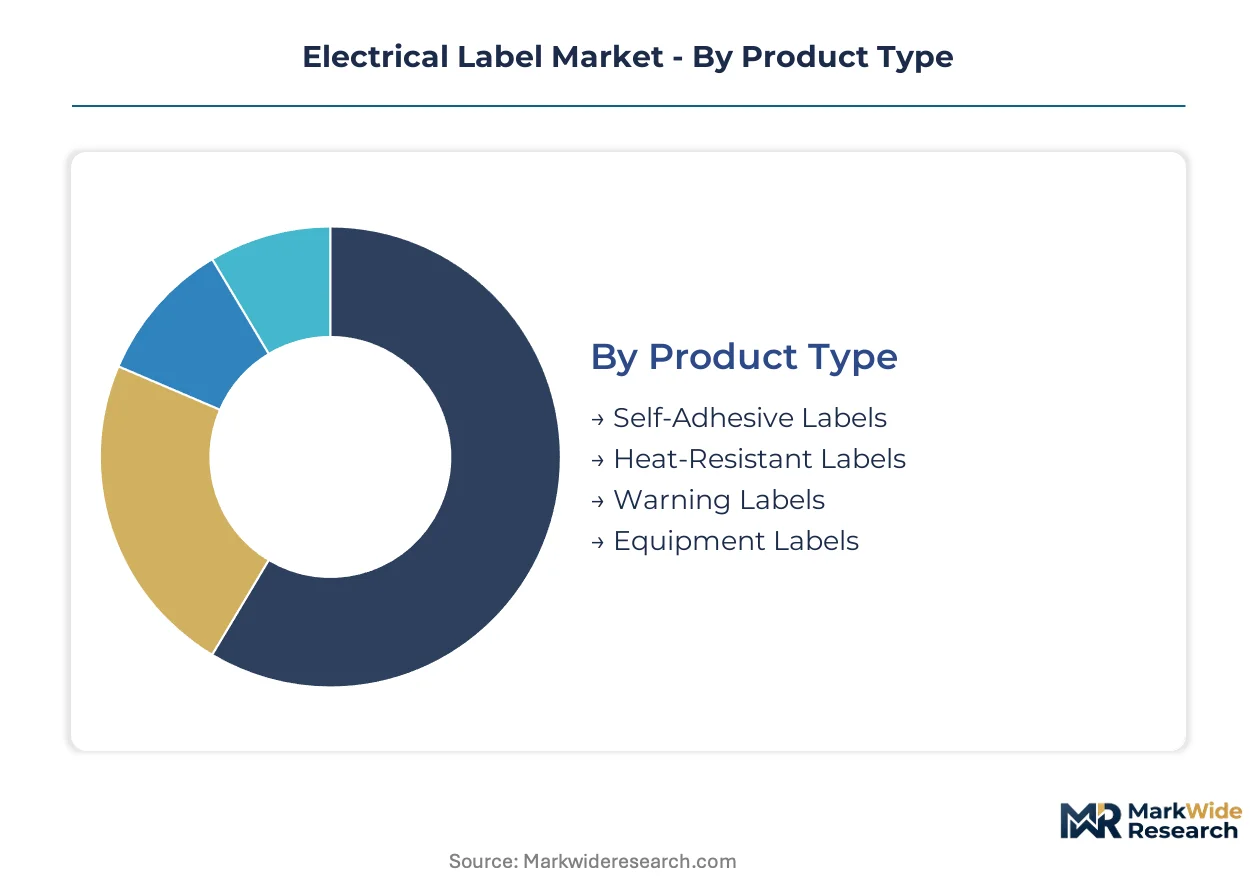
Electrical label procurement splits sharply between standardized safety markings and application-specific custom configurations. Material selection and adhesive chemistry vary dramatically across voltage environments, thermal exposure, and regulatory jurisdictions. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume commoditization dominates.
Product Type:
The customization-vs-standardization spectrum runs from pre-printed regulatory symbols requiring zero field modification to fully configurable blank substrates demanding thermal transfer printing infrastructure.
- Self-Adhesive Labels:Pressure-sensitive polyester or vinyl constructions with permanent acrylic adhesives dominate retrofit installations on legacy electrical panels. Demand concentrates in United States commercial construction where OSHA 29 CFR 1910.335 compliance deadlines are forcing wholesale label replacement cycles.
- Heat-Resistant Labels:Engineered with silicone or polyimide substrates rated for sustained temperatures above 150°C, these serve transformer OEMs and switchgear manufacturers. Germany's industrial equipment export sector consumes premium volumes as CE marking requirements tighten thermal performance verification.
- Warning Labels:Pre-printed arc-flash boundary and shock hazard symbols in standardized color codes per NFPA 70E. China's GB standards mandate bilingual variants for export-bound control panels.
- Equipment Labels:Circuit identifiers and voltage rating tags for panelboards and disconnect switches. Residential wiring applications favor economy-grade vinyl, while data center installations specify high-visibility retroreflective films.
Most installed capacity flows through Self-Adhesive Labels. Expansion is steepest in Heat-Resistant Labels.
Material:
Cost tier stratification separates commodity substrates from engineered films with certified flame-retardant and chemical-resistant properties.
- Vinyl:Flexible PVC formulations with permanent adhesives dominate indoor electrical panel marking where UV exposure remains minimal. United States contractors specify calendered vinyl for cost-sensitive residential and light commercial jobs.
- Polyester:Biaxially oriented PET films with solvent-resistant topcoats enable thermal transfer printing of variable data for industrial asset tracking. Germany's automotive wire harness suppliers qualify metallized polyester for electromagnetic shielding identification.
- Paper:Economy-grade facestocks with water-based adhesives serve temporary construction labeling and non-critical circuit documentation where moisture exposure is absent.
- Polyethylene:Low-density films with conformable properties wrap around irregular cable bundles and flexible conduit. China's photovoltaic cable manufacturers specify UV-stabilized polyethylene for outdoor string combiner applications.
Polyester commands the widest installed base across premium industrial applications. Vinyl maintains volume leadership in cost-driven segments.
Application:
Customer type determines whether procurement flows through distributor bulk programs or direct OEM specification.
- Industrial Use:Arc-flash labeling, motor control center identification, and switchgear safety marking under NFPA 70E and IEC standards. United States petrochemical facilities and German manufacturing plants drive specification-grade demand.
- Residential Use:Panel directory labels, circuit breaker identifiers, and NEC-compliant voltage markings. Volume concentrates in new construction and renovation through electrical contractor supply houses.
- Commercial Use:Integrated fire alarm, security, and electrical identification systems in multi-tenant buildings. China's commercial real estate development specifies bilingual safety labeling for mixed-use properties.
- Automotive Use:High-temperature wire marking and battery pack identification for electric vehicle production. Germany's automotive OEMs qualify labels for thermal cycling resistance in engine compartment environments.
Industrial Use absorbs the majority of specification-grade material. Commercial Use is expanding most quickly behind data center and EV charging infrastructure buildouts.
End User:
Supply concentration varies from fragmented contractor networks to consolidated OEM direct procurement.
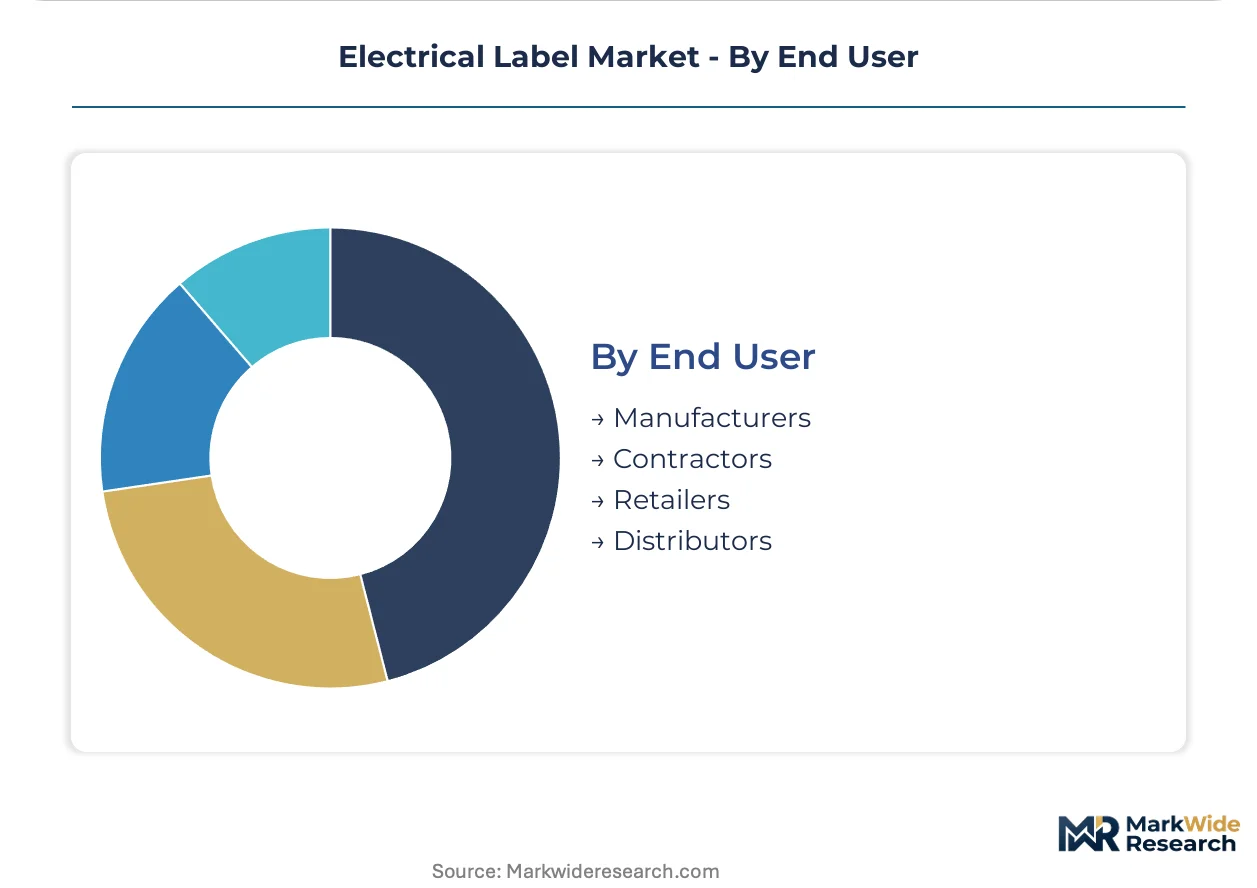
- Manufacturers:Transformer, switchgear, and industrial control panel OEMs specify labels at the design stage, often requiring lot traceability and certificate of compliance documentation.
- Contractors:Electrical installation firms purchase through distributor channels with variable circuit identifier needs driving demand for on-site thermal transfer printing capability.
- Retailers:Big-box hardware and electrical supply stores stock consumer-grade panel labels and generic warning symbols for residential DIY replacement.
- Distributors:Industrial supply houses bundle label programs with printers, ribbons, and design software as consolidated identification solutions.
Distributors channel the largest volume through bundled procurement programs. Manufacturers represent the highest-margin direct specification pathway.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrical label manufacturing originated in the industrial Midwest of the United States during the early twentieth century, with pressure-sensitive adhesive technology scaling through Milwaukee and Chicago converter networks before diffusing to European and Asian industrial centers.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth consumes specialized arc-flash labels rated for elevated thermal stress. OSHA enforces 29 CFR 1910.335 marking mandates across petrochemical facilities along the Gulf Coast. Brady Worldwide maintains captive distribution infrastructure through Milwaukee-area headquarters.
Germany
Transformer OEMs in Baden-Württemberg and Bavaria specify heat-resistant labels for export-bound industrial equipment. REACH substance restrictions enforced by ECHA compel adhesive reformulation away from phthalate plasticizers. Siemens Energy and ABB supplier networks in Mannheim concentrate premium label specification authority.
China
Photovoltaic string combiner manufacturing in Jiangsu and Zhejiang provinces drives bilingual serial tracking label demand. SAMR-administered GB standards mandate hazard warnings on export-bound control panels. BYD and CATL battery production facilities in Shenzhen specify high-temperature cable markers.
Japan
Automotive wire harness suppliers in Aichi Prefecture qualify metallized polyester labels for electromagnetic shielding identification. METI-administered JIS standards govern industrial electrical equipment marking permanence. Toyota and Honda supplier networks in Nagoya concentrate specification-grade procurement.
India
Commercial real estate development in Mumbai and Bangalore specifies bilingual safety labeling for mixed-use electrical infrastructure. BIS certification requirements tighten substrate performance verification for imported label materials. Schneider Electric and ABB manufacturing facilities in Pune drive OEM-direct procurement.
Electrical Label Market Vendor Landscape
Premium-margin players sit above commodity-margin players across adhesive chemistry sophistication and thermal performance certification. The vendor base stratifies into three tiers: diversified industrial conglomerates with captive adhesive technology, specialized identification converters with regional distribution density, and commodity label printers serving cost-sensitive construction channels. Dominant competitive moves include backward integration into specialty adhesive manufacturing and strategic partnerships with electrical equipment OEMs for design-stage specification.
Within the diversified industrial tier, 3M and Avery Dennison exemplify premium positioning through proprietary material science. Among specialized identification converters, Brady Worldwide occupies a position anchored by captive distribution infrastructure. Seton represents the regional converter archetype with density in North American industrial supply channels.
| Leading Market Players |
|---|
| Brady Worldwide |
| Seton |
| Brimar Industries |
| System Labels |
| Clarion Safety Systems |
| The Label Printers |
| CS Labels |
| Avery Dennison |
| 3M |
| Others |
Supply Flow & Price Mechanics
Backward integration into specialty adhesive manufacturing anchors both supply security and pricing power for premium electrical label producers. Brady Worldwide and 3M maintain captive production of high-temperature acrylic systems, insulating margin pools from petrochemical resin volatility that compresses converters dependent on merchant chemical supply.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates specification-grade heat-resistant labels from commodity vinyl panel markings. Certification tier—UL 969 permanence rating versus uncertified economy stock—drives the widest price spreads. Cost compression in standard-grade polyester labels is intensifying because Chinese converters are expanding thermal transfer printing capacity. Residential contractors through big-box retail channels exhibit the highest price sensitivity, while transformer OEMs in Germany accept premium positioning for REACH-compliant adhesive platforms.
Supply Chain Analysis
Ocean freight rate volatility from Shanghai to Hamburg and Long Beach directly impacts landed costs for pressure-sensitive adhesive laminates sourced from East Asian chemical clusters. Specialty silicone adhesive production concentrates in China, South Korea, and Japan, with biaxially oriented polyester film feedstock drawing from Taiwan and Germany. Single-source vulnerability runs through concentrated high-temperature polyimide substrate manufacturing in South Korea. Distribution runs through industrial supply houses that bundle label programs with thermal transfer printers and ribbon consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electrical label market functions as a stable compounder anchored by mandatory safety regulation refresh cycles that force recurring replacement demand across installed electrical infrastructure.
For Market Incumbents: Anticipate margin compression from Asian converters expanding into European certification territories by deepening captive adhesive production in Germany and the United States. Accelerate NFC-embedded smart label R&D to differentiate beyond static compliance marking and defend against commoditized thermal transfer blanks. For New Entrants and Emerging Players: Capture white-space in digital print-on-demand services for electrical contractors with variable circuit identifier needs, targeting fragmented United States commercial construction procurement. Penetrate through bundled software-printer-consumable programs rather than competing on label unit economics alone. For Investors and Strategic Acquirers: Roll-up economics work for regional identification converters because distributor channel relationships and local certification knowledge create defensible moats against Asian price competition. Target mid-cap specialists with density in United States industrial supply channels and proven UL validation capabilities. Watch for inflection when OSHA mandates next-generation arc-flash marking standards that obsolete legacy substrate formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Manufacturing | Captive supply of high-temperature acrylic systems insulates margins from petrochemical volatility affecting merchant-dependent converters. |
| Smart Label Technology Development | NFC-embedded substrates enable smartphone-based maintenance access, compressing the distinction between safety labels and industrial IoT endpoints. |
| REACH-Compliant Platform Qualification | German transformer OEMs are mandating non-phthalate adhesive systems ahead of ECHA candidate list expansions. |
| Distributed Print-on-Demand Network | Same-day custom production capability addresses electrical contractors with variable circuit identifier needs across commercial construction. |
| Single-Source Identification Compliance Packaging | General contractors in United States commercial construction increasingly mandate bundled design software, printer, and consumable programs. |
Methodological Framework
Coverage spans the United States, Germany, China, and Japan, with primary inputs from each market cluster. The research combines structured interviews with electrical contractor procurement managers, transformer OEM specification engineers, and industrial supply house category buyers with secondary validation from OSHA regulatory filings, ECHA substance restriction updates, SAMR GB standard publications, and SEC 10-K disclosures from listed identification manufacturers. Customs data on pressure-sensitive adhesive laminate trade flows and bottom-up channel checks triangulate against top-down market sizing.
Rate-of-change decomposition separates volume growth from value mix shift across the projection horizon. The analytical framework models product type, material grade, application environment, and end-user procurement channel as core segmentation dimensions. CAGRs derive from fitted growth curves applied to verified baseline consumption data, with specific inputs including data center construction permits, photovoltaic installation forecasts, and EV charging infrastructure deployment trajectories.
Regulatory timeline acceleration, petrochemical cost spikes, and Asian converter capacity expansion are the dominant revision risks that could compress or extend forecast ranges. Stakeholders should weight assumptions against their own operating context and monitor evolving national electrical code amendments for substrate specification changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Global Capacitor Bank Controllers Market
Electrical Equipment
PDU Power Cords Market
Electrical Equipment
High Voltage Commercial Switchgear Market
Electrical Equipment
France DC Motors Market
Electrical Equipment
Saudi Arabia Electric Motor Market
Electrical Equipment
Electrical Bushings Market
Electrical Equipment
Porcelain Insulators Market
Electrical Equipment
Middle East and Africa Electric Drives Market
Electrical Equipment
GCC Ceiling Fan Market
Electrical Equipment
Electronically Commutated (EC) Fan Market
Electrical Equipment
Europe Electrical Bushing Market
Electrical Equipment
Central Vacuum Receivers Market
Electrical Equipment
High Efficiency Low Voltage Aluminum Motors Market
Electrical Equipment
Copper and Copper Alloy Busbars Market
Electrical Equipment
HID Ballast Market
Electrical Equipment
Global Panelboards Market