
 Asia-Pacific Electrical Bushing Market | 2026-2036
Asia-Pacific Electrical Bushing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Electrical Bushing Market Outlook
Market Context with Strategic Players
Modular bushing assemblies with integrated condition-monitoring interfaces is expanding buyer choice across utility and OEM procurement channels in the Asia-Pacific region. Toshiba Corporation leverages its historical presence in Japan's high-voltage infrastructure to sustain premium positioning in liquid-immersed systems for transformer OEMs. Bharat Heavy Electricals Limited anchors large-scale public sector orders through backward integration into porcelain insulator manufacturing. ABB Ltd competes on digital bushing portfolios that merge sensor hardware with predictive analytics platforms for transmission operators.
Technical Definition and Structural Segments
An electrical bushing is a cylindrical insulating device, typically constructed from porcelain, polymer composites, or glass-reinforced epoxy, engineered to conduct high-voltage current through grounded transformer tanks, switchgear enclosures, or building walls while maintaining dielectric integrity across rated voltage classes up to 800 kV. Its primary industrial purpose centers on preventing flashover and containing electric field stress at conductor penetration points in power apparatus, thereby ensuring operational safety and equipment longevity in transmission and distribution networks. Polymer and composite product types are capturing margin pools from traditional porcelain as utilities prioritize lighter, vandalism-resistant alternatives for seismic zones and remote installations. Dry-type technology leads in commercial building and renewable energy applications where oil-free fire safety mandates apply, while liquid-immersed systems dominate utility-scale transformer integration given superior thermal performance. Power transmission applications remain the volume anchor, though renewable energy segments are structurally outpacing industrial equipment in growth velocity across Southeast Asian markets.
Regulatory Frame and Forward-Looking Close
China's MIIT enforces GB standards for bushing dielectric testing and materials certification, while India's BIS mandates IS mark compliance for electrical insulators deployed in central and state transmission projects. The EU F-Gas Regulation, through extraterritorial supply chain influence on European-headquartered manufacturers operating in Asia, is accelerating SF6-free bushing development timelines across the region. Japan's METI technical standards for earthquake-resistant grid infrastructure shape product specifications for equipment destined for the Northeast Asian archipelago. Stakeholders must monitor how divergent national certification regimes affect cross-border procurement economics and supplier qualification costs.
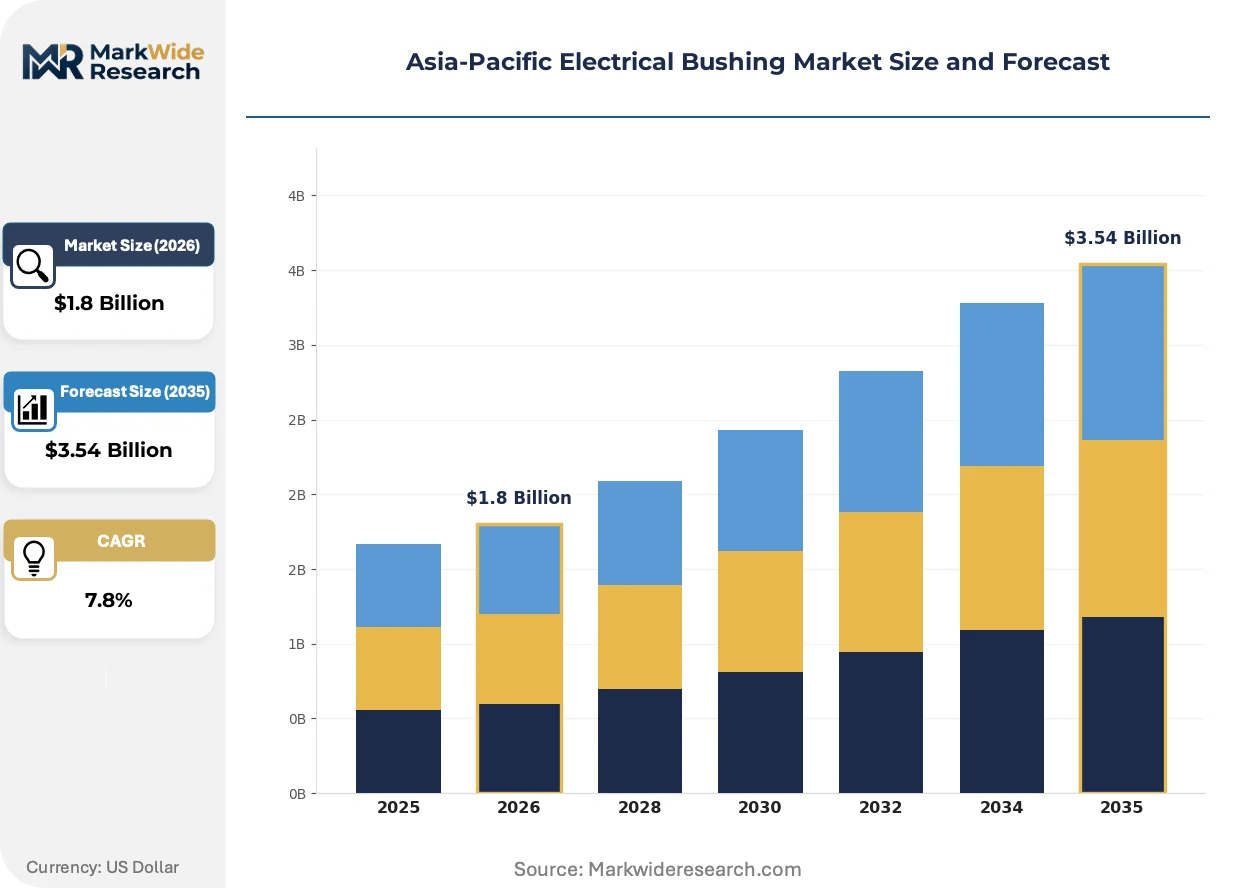
Market Dynamics
Grid modernization across Asia-Pacific is compressing replacement cycles for legacy porcelain bushings as transmission operators prioritize condition-monitored composite systems that reduce catastrophic failure risk in high-seismic corridors.
Growth Catalysts
- India's PLI scheme:Domestic manufacturing incentives for electrical equipment are accelerating local bushing production capacity and reducing import dependency for state transmission utilities.
- Ultra-high voltage corridors:China's expansion of 800 kV and 1000 kV transmission lines is generating concentrated demand for gas-insulated bushing assemblies with enhanced dielectric ratings.
- Seismic-resistant polymer formulations:Japan's METI technical standards for earthquake-proof grid infrastructure are mandating lightweight composite bushings in substation retrofits across the Northeast Asian archipelago.
Market Restraints
- Raw material concentration:High-purity alumina for porcelain insulators and specialized epoxy resins for composites face supply bottlenecks concentrated in Chinese chemical processing clusters.
- SF6 phase-out timelines:The EU F-Gas Regulation's extraterritorial pressure on European-headquartered manufacturers is forcing premature R&D redirection toward alternative insulation media with unproven field reliability.
- Specialized labor scarcity:Field commissioning of 400 kV+ bushing systems requires certified high-voltage technicians, with training pipelines failing to match utility deployment schedules in Indonesia and Vietnam.
Strategic Opportunities
- Renewable integration zones:Southeast Asian offshore wind and floating solar projects require marine-grade polymer bushings with salt-fog resistance, creating premium product tiers for coastal substations.
- Digital twin convergence:Integration of fiber-optic partial discharge sensors with cloud-based asset management platforms is opening recurring revenue streams for predictive maintenance service providers.
- Thailand's transmission buildout:The Electricity Generating Authority of Thailand's 500 kV network expansion is creating procurement windows for foreign suppliers meeting Thai Industrial Standards Institute certification.
Industry Challenges
- Type test certification timelines:BIS laboratory capacity constraints in India are extending IS mark approval cycles to 18-24 months, delaying commercialization for new composite formulations.
- Legacy asset interoperability:Retrofitting smart monitoring interfaces onto 1970s-era oil-impregnated paper bushings requires custom mechanical adapters that complicate warranty coverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Electrical Bushing Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.54 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Porcelain, Polymer, Composite, Glass Application: Power Transmission, Renewable Energy, Industrial Equipment, Commercial Buildings End User: Utilities, OEMs, Manufacturing, Construction Technology: Liquid-Immersed, Air-Insulated, Dry-Type, Hybrid |
| Companies Covered | Eaton Corporation PLC, Toshiba Corporation, ABB Ltd, Nexans SA, Hubbell Incorporated, Siemens AG, Bharat Heavy Electricals Limited, CG Power and Industrial Solutions Limited, General Electric Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Electrical Bushing Market Strategic Shifts
Material science breakthroughs and digital instrumentation are converging to redefine bushing lifecycle economics, shifting value capture from commodity hardware toward integrated asset-performance services.
Silicone rubber composite housings with hydrophobic surface coatings are decentralizing maintenance-intensive porcelain installations across coastal and high-pollution environments. Australian transmission network operators are specifying these systems for bushfire-prone corridors where ceramic fragility creates operational risk. The technology is decentralizing supplier power away from traditional porcelain foundries toward polymer compounders with in-house molding capabilities.
China's MIIT enforcement of revised GB/T standards for partial discharge testing is compressing product development cycles for domestic manufacturers. The regulations mandate online monitoring readiness as a precondition for 220 kV+ equipment qualification, forcing design teams to embed sensor ports during initial molding rather than retrofitting. Japanese transformer OEMs sourcing from Chinese suppliers report accelerated supplier audits to verify compliance with the new dielectric verification protocols.
Asset-owner procurement teams are unbundling bushing supply from transformer OEM packages to negotiate direct long-term service agreements with component specialists. This disintermediation is most pronounced in India's state transmission utilities, where central procurement cells now issue separate tenders for 10-year predictive maintenance subscriptions. The shift compresses price transparency for hardware while expanding contractual complexity around performance guarantees and sensor data ownership.
Asia-Pacific Electrical Bushing Market Segmentation
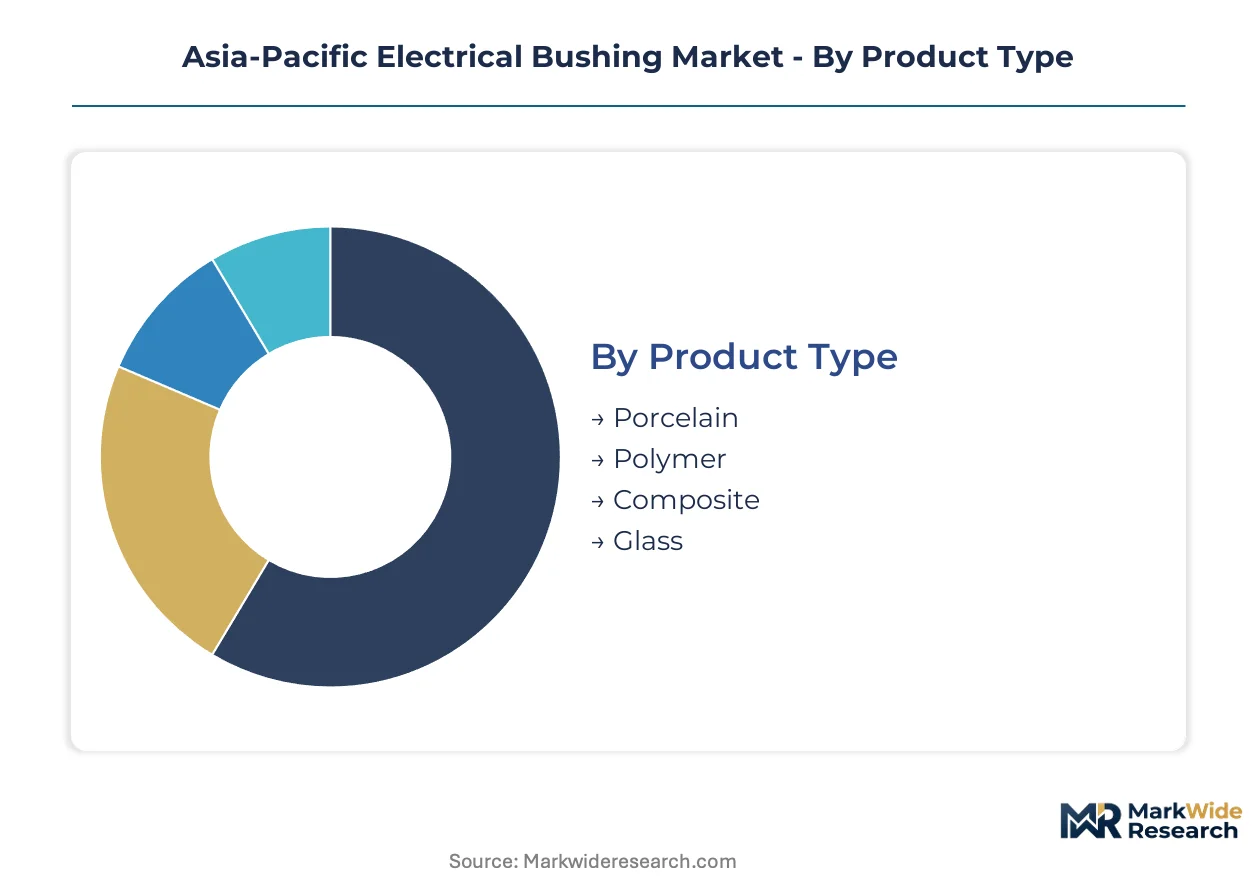
Segmentation in Asia-Pacific electrical bushings reveals divergent procurement logics across voltage classes and installation environments. Product material selection and insulation technology drive fundamentally different supplier qualification pathways for transmission utilities versus commercial developers.
Product Type:
Material composition dictates weight, seismic resilience, and pollution performance for buyers across China's ultra-high voltage corridors and Southeast Asian coastal zones.
- Polymer:Silicone rubber housings with hydrophobic surface coatings deliver vandalism resistance and reduced maintenance for remote substations. State Grid Corporation of China specifies these for 220 kV+ installations in high-pollution provinces where porcelain flashover risk escalates.
- Composite:Glass-fiber reinforced epoxy cores with polymer sheds combine mechanical strength with lightweight properties critical for Japan's earthquake-resistant grid retrofits. METI technical standards mandate these for substation upgrades across the Northeast Asian archipelago.
- Porcelain:Traditional alumina-based insulators retain cost advantage for 66 kV distribution networks in India's rural electrification programs.
- Glass:Borosilicate variants serve niche applications in high-temperature industrial environments with thermal cycling demands.
Polymer leads volumes today; composite is gaining share fastest.
Application:
Voltage rating and failure consequence severity separate procurement specifications for grid-scale operators from commercial building contractors.
- Power Transmission:400 kV to 800 kV bushing assemblies for transformer and switchgear integration dominate procurement volumes. China's State Grid and Southern Power Grid drive concentrated demand for gas-insulated systems in 1000 kV ultra-high voltage corridors.
- Renewable Energy:Offshore wind and floating solar projects in Vietnam and Indonesia require marine-grade polymer bushings with salt-fog resistance ratings. These installations command premium pricing for coastal substation equipment.
- Industrial Equipment:Steel mills and chemical plants specify heavy-duty bushings for furnace transformers and rectifier applications.
- Commercial Buildings:Dry-type technology dominates high-rise electrical infrastructure where fire safety codes prohibit oil-filled systems.
Power transmission anchors revenue; renewable energy is climbing the fastest.
End User:
Procurement sophistication and lifecycle cost horizons distinguish centralized utility buyers from fragmented construction sector purchasers.
- Utilities:State transmission companies in India and Thailand issue 10-year predictive maintenance contracts alongside hardware procurement. These buyers prioritize condition-monitoring readiness and sensor integration.
- OEMs:Transformer manufacturers in Japan and China source bushings as integrated subsystems, with Toshiba and ABB qualifying suppliers against internal dielectric testing protocols.
- Manufacturing:Industrial facility operators prioritize thermal performance and short-circuit withstand capability for process-critical power distribution.
- Construction:Commercial building developers emphasize first-cost minimization and code compliance over extended service life.
Utilities dominate contract value; OEMs are expanding procurement most quickly.
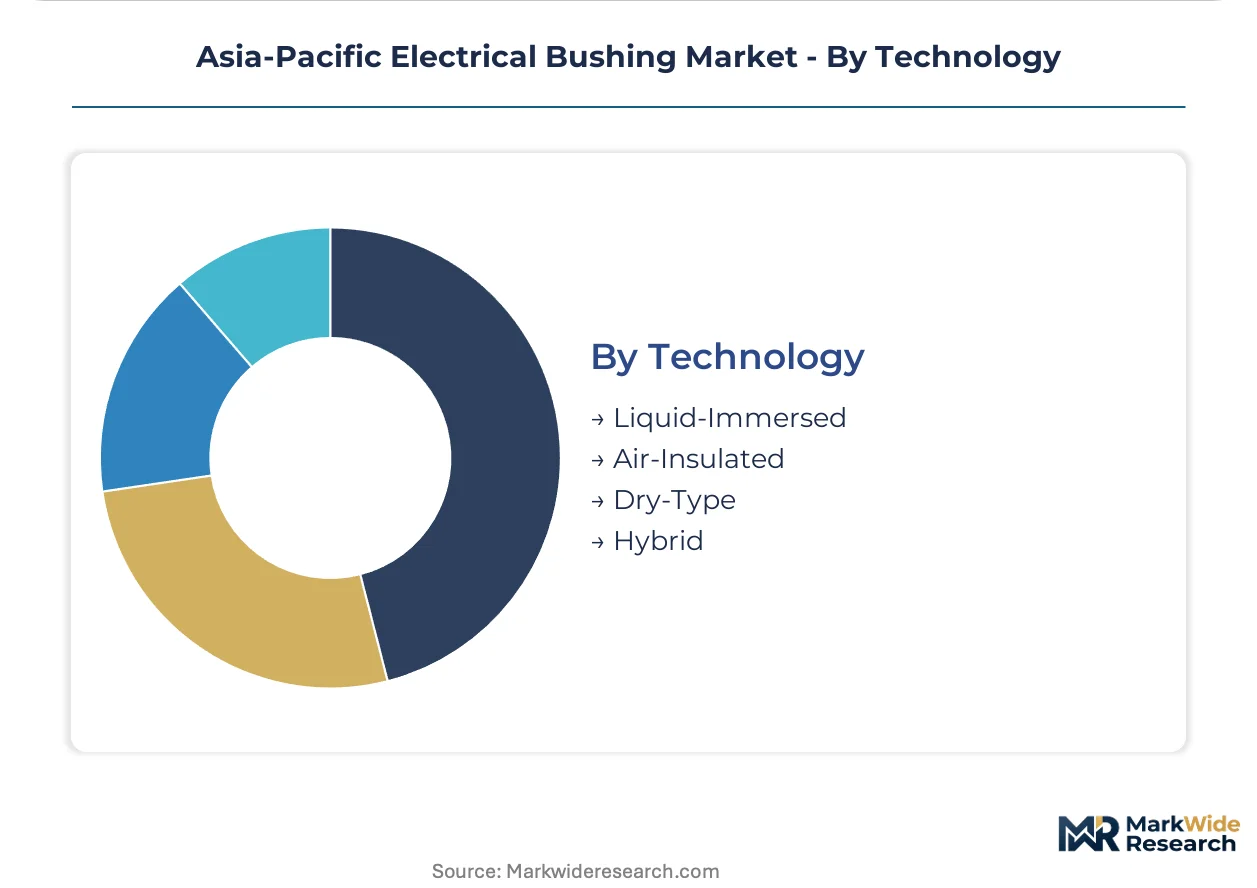
Technology:
Thermal management requirements and fire safety mandates create mutually exclusive specification sets for outdoor substations versus indoor commercial installations.
- Liquid-Immersed:Oil-impregnated paper insulation with porcelain or composite housings delivers superior heat dissipation for utility-scale transformers above 100 MVA. These systems dominate 220 kV+ applications in China's expanding transmission network.
- Dry-Type:Cast resin and RIP (resin-impregnated paper) constructions eliminate fire risk for underground substations and high-rise buildings. Singapore's building codes mandate these for commercial developments above 30 stories.
- Air-Insulated:Simpler constructions serve medium-voltage distribution switchgear in cost-sensitive rural electrification projects.
- Hybrid:Combined insulation systems address specialized applications requiring both thermal performance and reduced flammability.
Liquid-immersed leads installed base; dry-type is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-voltage electrical bushing manufacturing first achieved industrial scale in Japan's post-war reconstruction era, with Toshiba and Hitachi establishing porcelain insulator foundries that supplied Asia's initial transmission networks. Today's procurement patterns still reflect this geographic origin, though production capacity has dispersed across emerging manufacturing clusters.
China
State Grid Corporation and Southern Power Grid drive concentrated demand for 800 kV and 1000 kV gas-insulated bushing systems in ultra-high voltage corridors. MIIT enforces revised GB/T standards for partial discharge testing that mandate online monitoring readiness. Manufacturing clusters in the Yangtze River Delta around Shanghai supply composite housings for domestic transformer OEMs.
India
State transmission utilities in Maharashtra, Gujarat, and Tamil Nadu are scaling procurement of polymer bushings for 400 kV network expansion under the National Grid program. BIS mandates IS mark compliance for electrical insulators deployed in central and state projects, with laboratory capacity constraints extending approval cycles. Bharat Heavy Electricals Limited anchors large-scale public sector orders through backward integration into porcelain manufacturing.
Japan
METI technical standards for earthquake-resistant grid infrastructure mandate lightweight composite bushings in substation retrofits across the Northeast Asian archipelago. Transformer OEMs in the Kanto region source sensor-integrated systems for condition-monitored installations. Procurement prioritizes seismic resilience and predictive maintenance compatibility over first-cost minimization.
Thailand
The Electricity Generating Authority of Thailand's 500 kV network expansion creates procurement windows for foreign suppliers meeting Thai Industrial Standards Institute certification. Demand concentrates in the Bangkok metropolitan corridor and eastern seaboard industrial zones. State utility tenders increasingly specify 10-year service agreements alongside hardware supply.
Vietnam
Offshore wind and floating solar projects in the Mekong Delta and central coast require marine-grade polymer bushings with salt-fog resistance ratings. National Power Transmission Corporation procurement is accelerating for 220 kV substations serving renewable energy zones. Foreign suppliers face localization requirements for grid-scale equipment contracts.
Asia-Pacific Electrical Bushing Market Competitive Environment
Premium-margin players sit above commodity-margin players across digital integration and condition-monitoring capabilities. The vendor base organizes into three tiers: diversified electrical equipment conglomerates with captive bushing divisions, specialized insulator manufacturers with materials science expertise, and regional fabricators serving distribution voltage classes. Consolidation pressure is intensifying as utilities unbundle component supply from transformer OEM packages. Dominant competitive moves include vertical integration into sensor hardware and strategic partnerships with predictive analytics platforms.
Within the diversified conglomerate tier, Eaton Corporation PLC and Siemens AG occupy positions spanning multiple voltage classes and insulation technologies. Among Asia-Pacific specialists, Bharat Heavy Electricals Limited exemplifies the public-sector-anchored archetype with backward integration into porcelain manufacturing. Toshiba Corporation represents the premium-tier positioning built on historical infrastructure presence and seismic-resistance specialization.
| Leading Market Players |
|---|
| Eaton Corporation PLC |
| Toshiba Corporation |
| ABB Ltd |
| Nexans SA |
| Hubbell Incorporated |
| Siemens AG |
| Bharat Heavy Electricals Limited |
| CG Power and Industrial Solutions Limited |
| General Electric Company |
| Others |
Value Chain & Pricing Dynamics
Captive production of high-purity alumina and specialized epoxy resins anchors pricing power for established porcelain and composite bushing manufacturers across the Asia-Pacific region. State Grid Corporation of China and India's state transmission utilities leverage long-term offtake agreements to compress procurement costs for 220 kV+ installations, while smaller commercial buyers absorb volatility in polymer compound pricing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement contracts for electrical bushings in the Asia-Pacific market. Premium tiers capture sensor-integrated composite systems with predictive maintenance readiness, while economy tiers serve 66 kV distribution networks in India's rural electrification programs. Price differentiation rests on certification grade—BIS IS mark compliance commands 15-20% premiums over uncertified alternatives—and volume scale, with state utilities negotiating multi-year frameworks. Cost compression in standard-tier porcelain bushings is intensifying because Bharat Heavy Electricals Limited's backward integration into alumina processing floods domestic auction markets. Commercial building developers exhibit highest price sensitivity, prioritizing first-cost minimization over lifecycle service agreements.
Supply Chain Analysis
Dual-sourcing requirements from State Grid Corporation of China and India's National Grid program mandate multi-supplier qualification for critical 400 kV+ bushing assemblies. Geographic supply concentrates in China's Yangtze River Delta for composite housings, India's Tamil Nadu and Gujarat clusters for porcelain insulators, and Japan's Kanto region for seismic-resistant polymer formulations. Raw material dependencies draw from high-purity alumina processed in Shandong province, specialized silicone rubber compounds from South Korean petrochemical complexes, and glass-fiber reinforcements from domestic Japanese suppliers. Single-source vulnerability in Chinese alumina refining creates exposure to environmental compliance shutdowns. Distribution runs through transformer OEM captive supply chains and direct utility procurement cells, with aftermarket service contracts increasingly unbundled from initial hardware sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as transmission operators shift procurement specifications toward condition-monitored composite systems with embedded sensor infrastructure and 10-year predictive maintenance bundling.
For Market Incumbents: Acquire fiber-optic sensor technology capabilities to defend service revenue streams against disintermediation from transformer OEMs. State transmission utilities in India and Thailand are unbundling component supply from integrated transformer packages, threatening hardware margin pools. Incumbents must deepen backward integration into polymer compounding to secure formulation control for marine-grade salt-fog resistant variants demanded by Vietnam's offshore wind zones. For New Entrants and Emerging Players: Capture procurement windows in Thailand's 500 kV network expansion by securing Thai Industrial Standards Institute certification ahead of incumbent requalification cycles. The Electricity Generating Authority of Thailand's eastern seaboard industrial zones present the most penetrable geography, with foreign suppliers currently underrepresented in 220 kV+ substation tenders. A direct utility sales model bypassing transformer OEM channels maximizes pricing autonomy. For Investors and Strategic Acquirers: Roll-up economics work for specialized composite bushing manufacturers with captive polymer molding capabilities because utility procurement is consolidating around 10-year service contracts that favor integrated hardware-plus-analytics providers. The mid-cap specialist archetype—revenue between $50-200 million with METI or BIS certification—offers platform consolidation potential. Watch for acceleration in China's MIIT enforcement of GB/T online monitoring mandates as the inflection signal for sensor-integrated system demand.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Hardware Integration | State Grid Corporation mandates online monitoring readiness for 220 kV+ equipment qualification. |
| Backward Integration into Polymer Compounding | Bharat Heavy Electricals Limited's captive alumina supply anchors cost position in porcelain manufacturing. |
| Marine-Grade Certification Investment | Vietnam's offshore wind projects require salt-fog resistance ratings for coastal substation equipment. |
| Long-Term Service Contract Bundling | India's state transmission utilities now tender 10-year predictive maintenance alongside hardware procurement. |
| Seismic-Resistant Formulation Development | Japan's METI standards mandate lightweight composite bushings for earthquake-proof grid retrofits. |
Study Parameters
Coverage spans China, India, Japan, Thailand, and Vietnam, with primary inputs from each market's transmission utility procurement officers, transformer OEM sourcing managers, and polymer compound technical directors. Secondary validation draws from MIIT GB standards filings, BIS laboratory certification records, Electricity Generating Authority of Thailand tender documents, and customs data for electrical insulator trade flows. Bottom-up demand modeling from utility capital expenditure plans triangulates against top-down market sizing from equipment manufacturer revenue disclosures.
Granularity-level modeling disaggregates volume and value outputs across product type, application, end user, and technology dimensions, with voltage class and certification tier as additional industry-specific stratifiers. CAGRs derive from regression analysis of historical procurement patterns against projected grid modernization spending across the analysis window. Forecast inputs include State Grid Corporation's ultra-high voltage corridor buildout schedules and India's PLI scheme capacity addition timelines.
Regulatory enforcement delays, raw material supply disruptions, and utility capital reallocation are the dominant revision risks to the outlook. Deviation in China's MIIT standards implementation timeline would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Global Cooling Fan Market
Electrical Equipment
Vacuum Contactor Market
Electrical Equipment
Axial Fans Market
Electrical Equipment
Saudi Arabia Industrial Electrical Components Market
Electrical Equipment
Wire Splicing Kits Market
Electrical Equipment
Alligator Clips Market
Electrical Equipment
Lighting Contactor Market
Electrical Equipment
Saudi Arabia Electric Motor Market
Electrical Equipment
Copper and Aluminum Terminal Blocks Market
Electrical Equipment
Portable Misting Fans Market
Electrical Equipment
Global Electrical Steel Market
Electrical Equipment
Global Panelboards Market
Electrical Equipment
Earth Leakage Circuit Breakers Market
Electrical Equipment
Electrical Measuring Instrument Market
Electrical Equipment
Global Copper Clad Steel (CCS) Wire Market
Electrical Equipment
Global General Purpose Contactor Market