
 Global X-Ray Security Scanner Market | 2026-2036
Global X-Ray Security Scanner Market Size, Share, and Industry Trends Forecast 2026-2036
Global X-Ray Security Scanner Market Outlook
Software-defined threat-detection algorithms bundled as subscription upgrades is broadening what security integrators sell beyond hardware. Smiths Detection Inc. leverages its installed base across European aviation hubs to lock in recurring analytics revenue. Nuctech Company Limited anchors its expansion through state-backed financing of turnkey screening packages across developing markets. Leidos Holdings, Inc. competes on U.S. federal channel access rather than price.
X-ray security scanners employ ionizing radiation between 140 kV and 300 kV to penetrate dense cargo and luggage, generating grayscale or dual-energy images for contraband identification. These systems serve border control, critical infrastructure, and law enforcement agencies requiring non-invasive inspection of sealed containers. Conveyor belt scanners dominate installed value in aviation checkpoints where throughput requirements exceed 1,800 bags per hour. Computed tomography technology is capturing the fastest expansion as hold-baggage screening mandates tighten across the EU and Middle East. Fixed scanners represent a mature margin pool sustained by government maintenance contracts with decade-long renewal cycles.
The U.S. Transportation Security Administration enforces strict certification under its Qualified Products List, filtering which manufacturers access federal procurement channels. EASA in Europe harmonizes detection standards across member states while China's MIIT sets GB standards for domestic rail and port deployments. Stakeholders must monitor how divergent certification timelines between the FAA and EASA reshape product development roadmaps and regional launch sequencing.
Market Dynamics
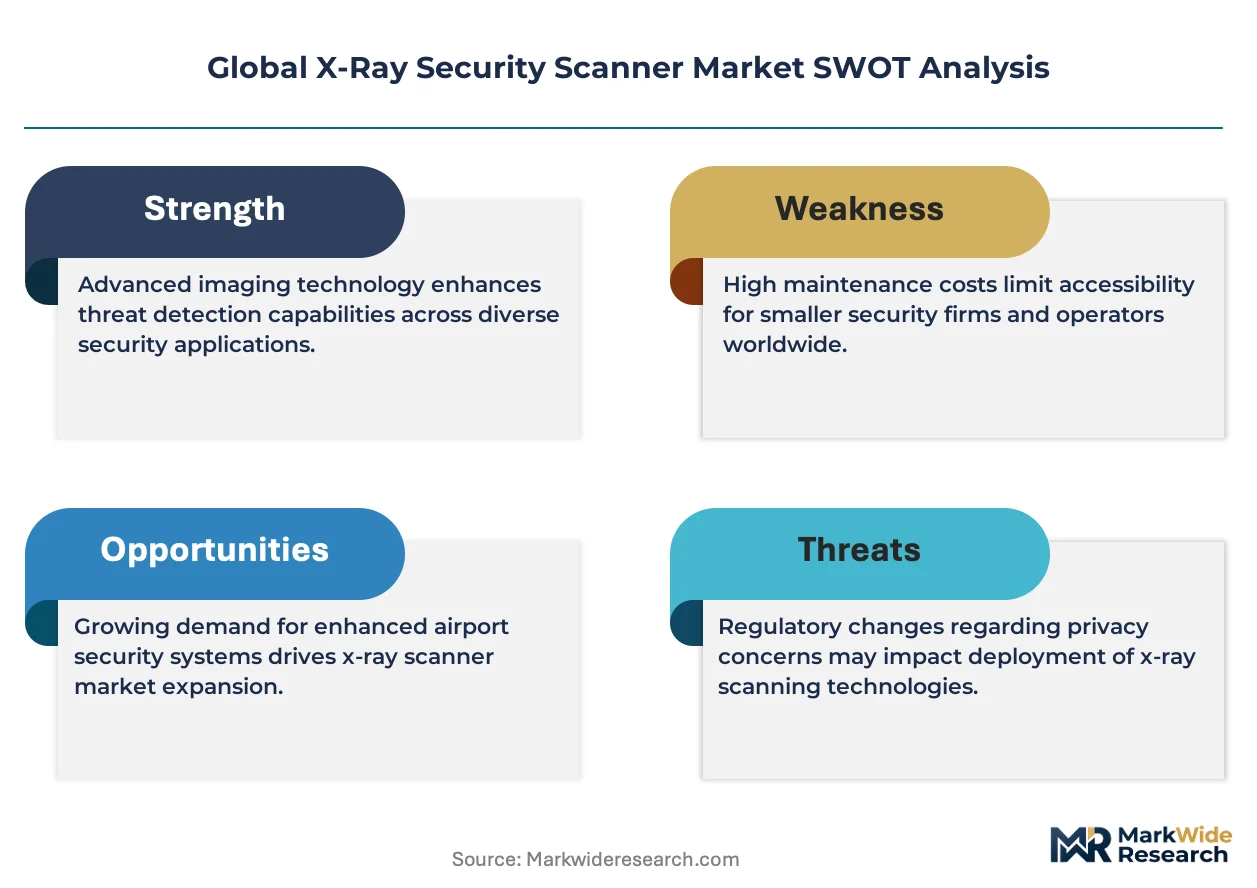
Computed tomography systems are forcing a wholesale replacement cycle across European aviation security infrastructure, while software-defined detection algorithms restructure vendor revenue models from hardware sales toward recurring analytics subscriptions.
Growth Catalysts
- EU Hold-Baggage Mandates:EASA screening requirements are compelling airports to upgrade from conventional X-ray to CT-based inspection systems.
- Belt-and-Road Port Modernization:State-backed financing is deploying turnkey screening infrastructure across developing market transshipment hubs.
- Dual-Energy Material Discrimination:Advanced sensor arrays now distinguish organic from inorganic contraband with reduced false-alarm rates.
Market Restraints
- High-Purity Tungsten Supply Concentration:Sourcing of radiation-shielding materials depends on concentrated mining operations in specific geographies.
- Ionizing Radiation Exposure Limits:FDA and EASA occupational safety thresholds constrain system throughput optimization.
- Passive Millimeter-Wave Substitution:Non-ionizing body scanners compete for checkpoint footprint in lower-threat environments.
Strategic Opportunities
- India Aviation Infrastructure Buildout:Greenfield airport construction under UDAN regional connectivity schemes creates first-mover positioning.
- Subscription Analytics Bundling:Threat-detection algorithm updates sold as recurring services transform one-time hardware margins.
- Rail and Metro Integration:High-speed rail networks in China and Europe adopt cargo screening for parcel logistics.
Industry Challenges
- Qualified Products List Certification Timelines:TSA and EASA approval cycles extend 18-24 months, delaying product launches.
- Legacy System Integration Complexity:New CT scanners must interface with existing baggage handling infrastructure without throughput degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global X-Ray Security Scanner Market |
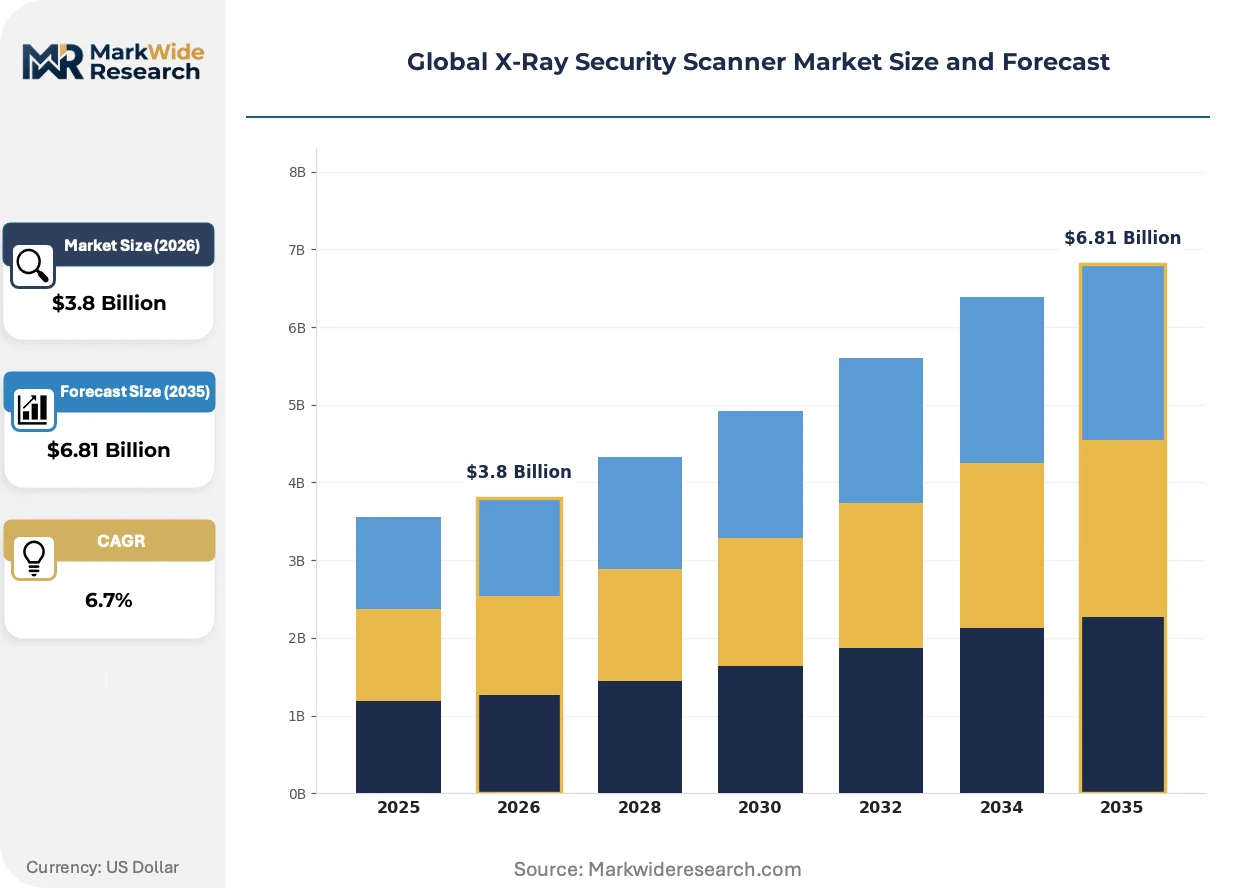
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Scanners, Conveyor Belt Scanners, Portable Scanners, Fixed Scanners Technology: Computed Tomography, 2D Imaging, 3D Imaging, Advanced Detection End User: Aviation, Customs, Public Safety, Military Installation Type: In-ground Systems, Surface-mounted Systems, Mobile Units, Temporary Installations |
| Companies Covered | Leidos Holdings, Inc., Astrophysics Inc., Smiths Detection Inc., Thales S.A., Rapiscan Systems Inc., OSI Systems, Inc., Analogic Corporation, L3Harris Technologies, Nuctech Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global X-Ray Security Scanner Market Strategic Shifts
Deep learning inference at the edge is collapsing detection latency from seconds to milliseconds, enabling real-time automated decisioning without human operator review queues. This shift redefines competitive advantage around algorithm training data scale rather than sensor hardware specifications alone.
Computed tomography reconstruction algorithms are absorbing baggage screening workloads previously requiring manual secondary inspection. Major European hubs including Frankfurt and Amsterdam are deploying these systems under EASA mandate timelines. The technology is absorbing mid-tier vendor market position by raising minimum viable performance thresholds beyond their R&D reach.
REACH restrictions on hazardous substances are tightening material compliance for scanner housing and shielding components. Manufacturers must reformulate lead-free radiation barriers and document full material transparency across supply chains. Aviation security integrators serving EU member states face the steepest compliance cost escalation.
Service contract unbundling is fragmenting buyer-vendor relationships as airport authorities separate hardware procurement from maintenance and software subscriptions. Large hub operators now negotiate detection algorithms independently from conveyor system vendors. This pattern is most pronounced in North American federal procurement channels where TSA Qualified Products List access determines vendor eligibility.
Global X-Ray Security Scanner Market Segmentation
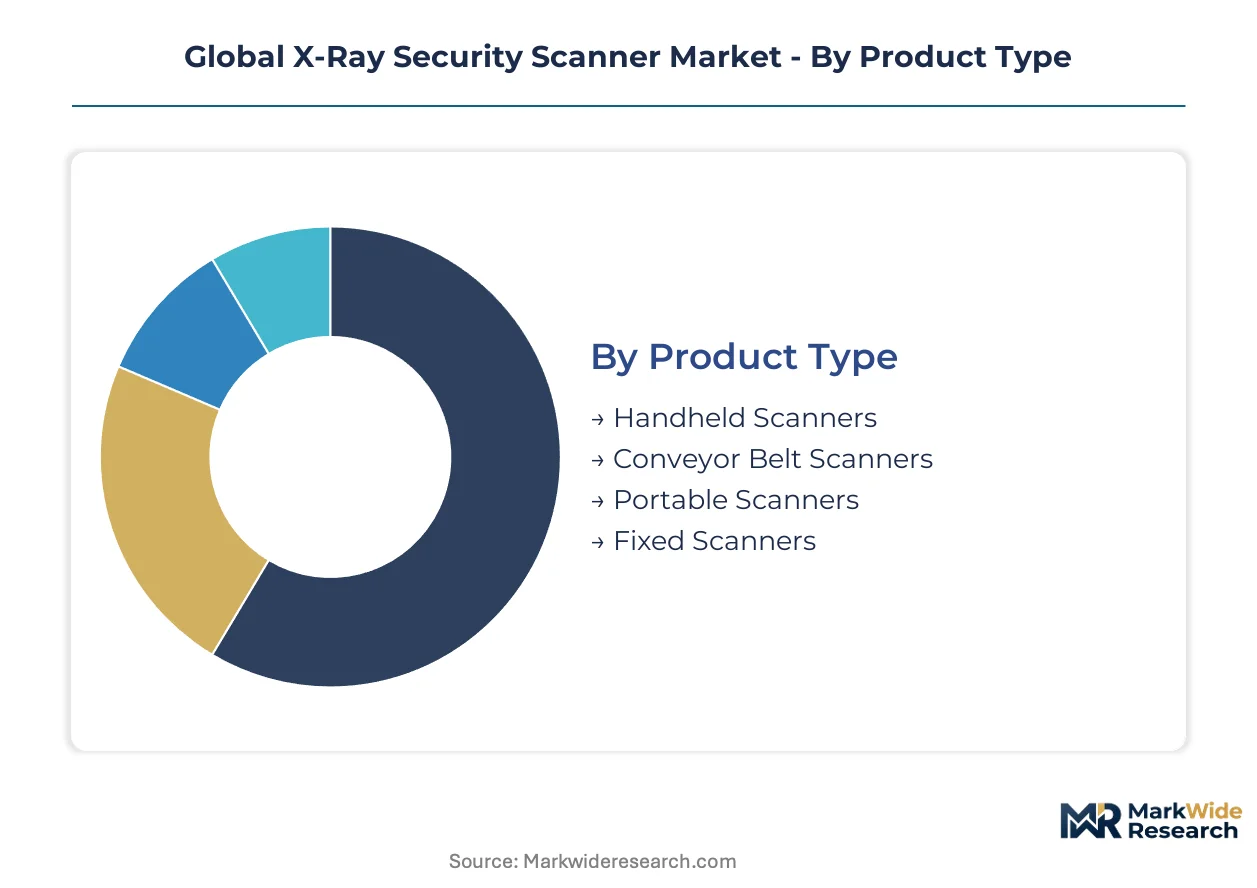
X-ray security scanner procurement diverges sharply between integrated infrastructure deployments and standalone tactical units. Understanding these structural splits reveals where capital concentrates versus where operational flexibility commands premium pricing.
Product Type:
Integration depth separates conveyor-fed checkpoint systems from field-deployable units requiring minimal infrastructure.
- Conveyor Belt Scanners:Continuous-feed systems process baggage through automated handling infrastructure at throughput rates exceeding 1,800 items hourly. Demand concentrates in EU aviation hubs under EASA hold-baggage mandates, where Frankfurt and Amsterdam anchor replacement cycles.
- Fixed Scanners:Permanent installations with embedded radiation shielding serve border crossings and critical infrastructure gates. Customs authorities in China and Saudi Arabia deploy these at Belt-and-Road transshipment nodes.
- Handheld Scanners:Battery-operated wands enable targeted inspection of suspicious items without moving objects to secondary screening.
- Portable Scanners:Collapsible units deploy to temporary checkpoints and event security perimeters with rapid setup protocols.
Volume placements concentrate in Conveyor Belt Scanners; the faster expansion belongs to Fixed Scanners.
Technology:
Imaging sophistication determines detection confidence levels and regulatory compliance thresholds across end-use categories.
- Computed Tomography:Multi-angle reconstruction generates volumetric data for automated threat recognition without manual secondary inspection. EU aviation security mandates are accelerating replacement of legacy 2D systems at London Heathrow and Paris Charles de Gaulle.
- 2D Imaging:Single-projection grayscale systems dominate price-sensitive customs and cargo applications where throughput requirements are moderate.
- 3D Imaging:Stereoscopic depth mapping improves contraband localization in parcel logistics and mail screening facilities.
- Advanced Detection:Machine-learning inference engines process dual-energy data to distinguish organic from inorganic materials with reduced false-alarm rates.
Deployment volumes favor 2D Imaging in developing markets; Computed Tomography claims the steepest expansion trajectory in regulated aviation channels.
End User:
Procurement authority and certification requirements fragment buyer decision-making across federal, municipal, and private operators.
- Aviation:Airport authorities and airlines face the strictest detection mandates under TSA Qualified Products List and EASA certification timelines. U.S. federal procurement channels filter vendor access through 18-24 month approval cycles.
- Customs:Border control agencies prioritize cargo throughput and trade facilitation alongside security effectiveness. China's port modernization drives concentrated demand at Shenzhen and Shanghai terminals.
- Public Safety:Municipal law enforcement and court facilities deploy entry-point screening with flexible threat-detection protocols.
- Military:Forward operating bases and installation perimeter security require hardened systems with electromagnetic interference resilience.
Revenue concentration sits with Aviation; Customs segments are climbing the fastest as developing economies expand port infrastructure.
Installation Type:
Physical mounting configuration determines integration complexity with existing facility infrastructure and relocation flexibility.
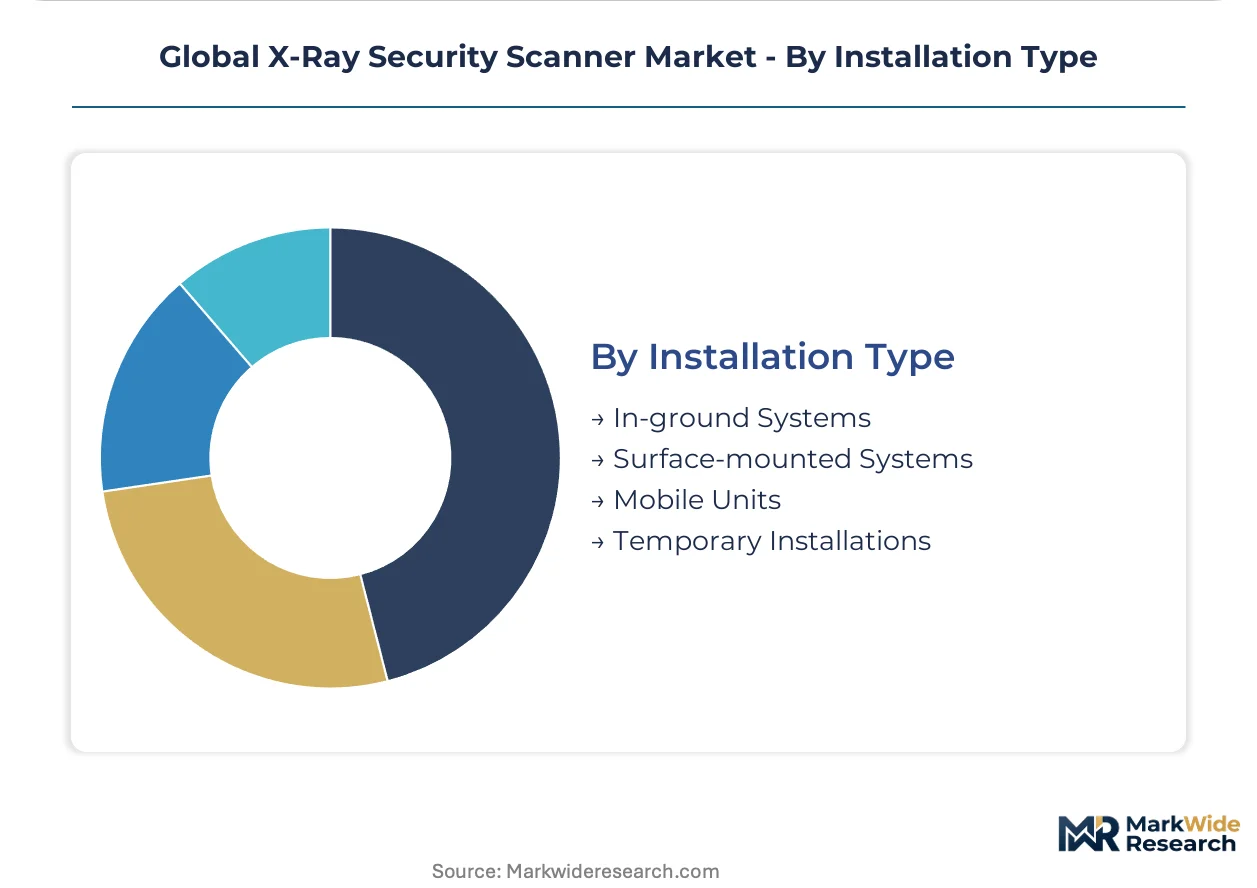
- Surface-mounted Systems:Elevated platforms above floor level simplify maintenance access and accommodate existing baggage handling layouts. These dominate retrofit installations at established EU aviation hubs.
- In-ground Systems:Flush-mounted conveyor tunnels minimize vertical space requirements and enable seamless material flow in new construction projects. India's UDAN regional airport buildout favors this configuration.
- Mobile Units:Vehicle-mounted or trailer-based systems relocate between event venues and emergency response sites.
- Temporary Installations:Rapid-deployment frames support construction site security and disaster response without permanent civil works.
Surface-mounted Systems retain the largest installed base; In-ground Systems are gaining share fastest in greenfield aviation construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt anchors European aviation security modernization, with its hub status driving CT scanner deployment timelines under EASA mandates. The city's baggage handling infrastructure serves as a template for hold-baggage screening upgrades across continental airports.
United States
The TSA Qualified Products List filters vendor access through 18-24 month federal certification cycles. Atlanta Hartsfield-Jackson and Dallas-Fort Worth anchor the largest checkpoint replacement programs. Domestic integrators compete on channel relationships rather than hardware pricing alone.
Germany
Frankfurt and Munich airports operate under EASA's tightened detection thresholds for hold-baggage screening. The country's customs administration deploys fixed scanners at Duisburg inland port and Hamburg container terminals. REACH compliance requirements are escalating material costs for radiation shielding components.
China
MIIT GB standards govern domestic rail and port scanner certifications. Shenzhen and Shanghai container terminals concentrate Belt-and-Road transshipment screening demand. State-backed financing packages are exporting turnkey screening infrastructure to developing markets.
India
UDAN regional connectivity schemes are greenlighting airport construction in tier-2 cities. Mumbai and Delhi's existing hubs face retrofit constraints for CT system integration. The Bureau of Indian Standards is drafting localization requirements for security equipment procurement.
United Arab Emirates
Dubai International's passenger volume is driving premium-tier checkpoint technology procurement. Jebel Ali port modernization is absorbing cargo screening systems for transshipment security. The country's civil aviation authority maintains parallel certification tracks with EASA standards.
Global X-Ray Security Scanner Market Competitive Environment
Capital-heavy producers compete with asset-light designers across divergent technology roadmaps. The vendor base stratifies between integrated security conglomerates and specialized detection technology developers. Three archetypes dominate: federal channel specialists leveraging procurement relationships, state-backed turnkey providers, and algorithm-centric software vendors. Consolidation pressures are intensifying as CT system complexity raises R&D minimums beyond mid-tier reach.
Within the federal channel specialist tier, Leidos Holdings, Inc. and L3Harris Technologies occupy positions shaped by TSA Qualified Products List access. Smiths Detection Inc. exemplifies the European aviation integrator archetype, while Nuctech Company Limited anchors the state-backed turnkey provider model. These three represent divergent competitive vectors: procurement relationship depth, installed base recurring revenue, and sovereign financing leverage.
| Leading Market Players |
|---|
| Leidos Holdings, Inc. |
| Astrophysics Inc. |
| Smiths Detection Inc. |
| Thales S.A. |
| Rapiscan Systems Inc. |
| OSI Systems, Inc. |
| Analogic Corporation |
| L3Harris Technologies |
| Nuctech Company Limited |
| Others |
Value Chain & Pricing Dynamics
REACH restrictions on hazardous substances in the EU gate qualified supply for radiation-shielding components and premium-tier pricing access for compliant manufacturers serving EASA-certified aviation channels. Buyers face steep compliance cost escalation for lead-free barriers, fragmenting vendor tiers between certified integrators and price-pressured alternatives.
Pricing Analysis
Throughput-guarantee contracts anchor value-based pricing for CT checkpoint systems, with vendors bundling detection algorithm subscriptions and uptime commitments. Pricing stratifies across EASA-certified premium tiers, TSA Qualified Products List mid-tiers, and uncertified economy alternatives. Cost compression in the economy tier intensifies because Chinese state-backed financing floods developing markets with turnkey packages. Customs authorities at Belt-and-Road ports exhibit highest price sensitivity; EU hub operators prioritize detection confidence over unit cost.
Supply Chain Analysis
Specialized manufacturing workforces in Germany, China, and the United States concentrate precision sensor array and radiation-shielding production. High-purity tungsten for collimators draws from concentrated mining operations; scintillator crystals and photodetector modules feed from Japanese and European suppliers. Single-source vulnerability in tungsten sourcing exposes lead times to geopolitical friction. Distribution runs through federal procurement channels in the US, state-backed project finance in China, and integrator-led turnkey contracts in the EU.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a technology-transition phase as computed tomography systems displace legacy 2D imaging across regulated aviation channels. This replacement cycle restructures vendor economics toward recurring software revenue and away from one-time hardware margins.
For Market Incumbents: To counter algorithm-centric entrants poaching analytics revenue, lock in multi-year detection-software subscriptions with airport authorities and deepen backward integration into scintillator crystal supply. Prioritize EASA certification maintenance as CT performance thresholds rise beyond mid-tier R&D reach.
For New Entrants and Emerging Players: The premium-to-economy price gap in handheld and portable scanner segments offers white-space entry without federal certification barriers. Target India's UDAN regional airport buildout where Bureau of Indian Standards localization requirements favor domestic assembly partnerships. Lead with rapid-deployment protocols for temporary event security and disaster response applications.
For Investors and Strategic Acquirers: TSA's expansion of Qualified Products List CT system categories is the leading indicator that consolidation momentum will accelerate as R&D minimums exclude sub-scale vendors. Position for algorithm-training data scale as the durable competitive moat rather than sensor hardware specifications. Watch for EASA mandating automated threat recognition without human review as the signal for software-centric valuations to displace hardware multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Detection Algorithm Subscription Bundling | Transforms one-time hardware margins into recurring revenue streams at Frankfurt and Amsterdam hubs. |
| EASA CT Certification Investment | Secures access to EU aviation replacement cycles as hold-baggage mandates tighten performance thresholds. |
| Backward Integration into Tungsten Supply | Reduces single-source vulnerability for radiation-shielding collimators amid concentrated mining geographies. |
| India Localization Partnership | Positions for UDAN regional airport construction under Bureau of Indian Standards procurement requirements. |
| Belt-and-Road Turnkey Export | Leverages state-backed financing to deploy screening infrastructure across developing market transshipment nodes. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with airport procurement directors, TSA certification officers, customs technology leads, and security integrator executives combined with secondary validation from EASA detection standard documents, FDA radiation safety filings, and MIIT GB certification databases. Bottom-up scanner shipment estimates and top-down infrastructure spending projections were triangulated across aviation, customs, and public safety end-use categories.
Data-stream reconciliation across product type, technology tier, end-user vertical, and installation configuration dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented volume trajectories and value-per-unit trends. Industry-specific forecast inputs included EASA mandate implementation timelines, TSA Qualified Products List expansion patterns, and Belt-and-Road port modernization disbursement cycles.
Inputs from EASA certification databases and TSA procurement records were available through the study window; gaps in real-time customs scanner deployment data introduce uncertainty bands around developing market volume estimates. Forecasts reflect assumptions regarding regulatory mandate adherence, supply chain stability for critical minerals, and algorithm performance advancement rates. Material deviation in EASA detection threshold announcements or tungsten supply disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
North America Wireless Monitoring and Surveillance Market
Security and Surveillance
Air Cargo Security Equipment Market
Security and Surveillance
North America Security Testing Market
Security and Surveillance
Multi-Layer Security Market
Security and Surveillance
North America Security Services Market
Security and Surveillance
Europe Border Security Market
Security and Surveillance
Forensic Technologies Market
Security and Surveillance
Crowdsourced Security Market
Security and Surveillance
India Perimeter Intrusion Detection and Prevention Market
Security and Surveillance
Global Corporate Travel Security Market
Security and Surveillance
Global Intrusion Detection System Market
Security and Surveillance
Full Body Scanner Market
Security and Surveillance
TSCM Equipment Market
Security and Surveillance
Global Physical Security Software Market
Security and Surveillance
Global Integration Security Services Market
Security and Surveillance
India Electronic Security Market