
 Air Cargo Screening Systems Market | 2026-2036
Air Cargo Screening Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Air Cargo Screening Systems Market Analysis
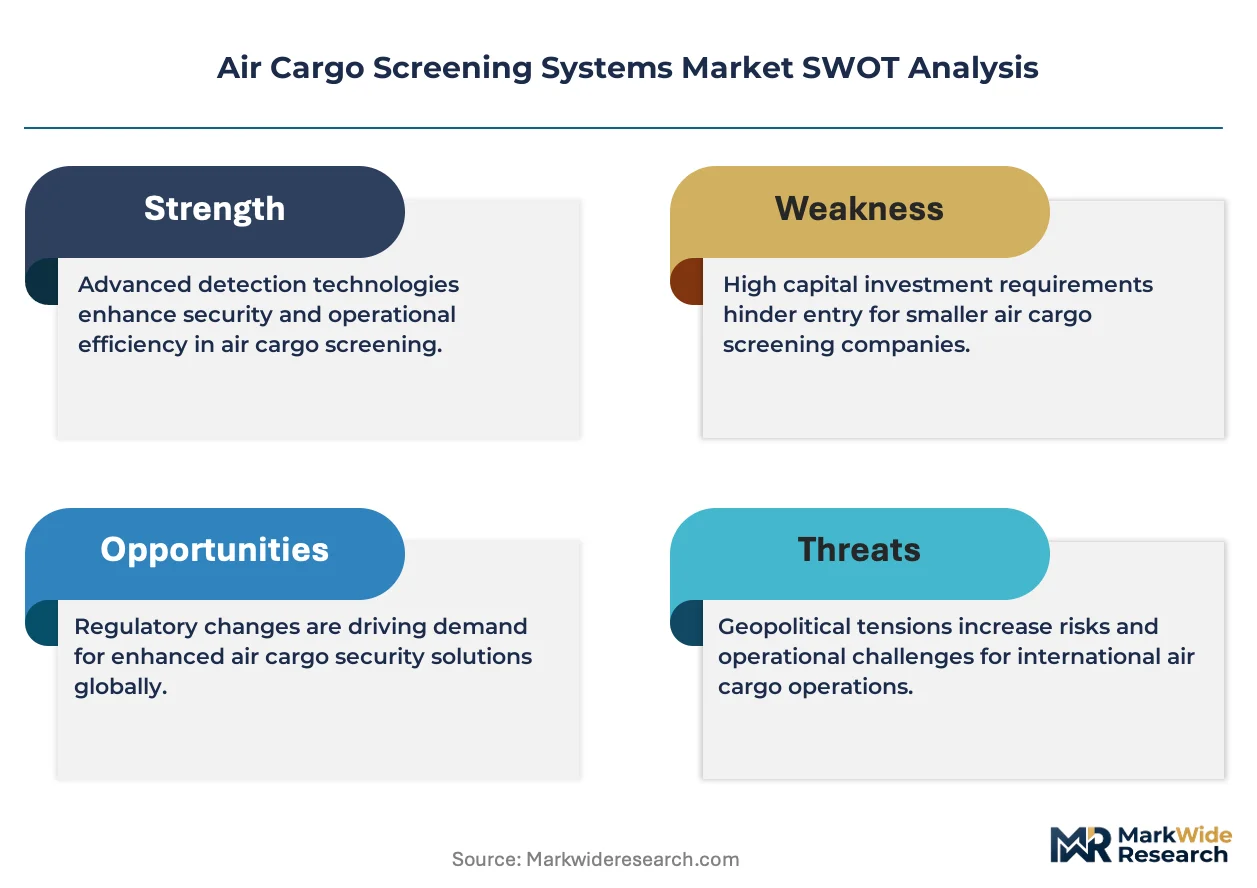
Software-defined threat detection algorithms are repositioning how screening capabilities get sold, shifting value from hardware ownership to continuous algorithmic updates. Smiths Detection Inc. leverages deep integration between hardware platforms and analytics layers to sustain recurring revenue streams. L3Harris Technologies Inc. anchors its position through federal channel control in North American aviation security. Nuctech Company Limited dominates price-sensitive procurement cycles across emerging airport infrastructure programs.
Air cargo screening systems employ ionizing radiation or non-ionizing electromagnetic methods to inspect palletized freight, containerized goods, and loose-loaded cargo for contraband, explosives, and hazardous materials, with typical X-ray systems operating at 1-6 MeV energy levels to penetrate dense aviation cargo. These systems serve the primary commercial purpose of maintaining air transport security while preserving freight throughput velocity at logistics chokepoints. Computed tomography technology leads investment flows due to its three-dimensional reconstruction capabilities that reduce false-positive rates, while explosives detection systems represent the fastest-growing segment as regulators mandate automated trace analysis for high-risk origin routes. Services and software components concentrate margin pools because airlines and freight operators increasingly outsource calibration, threat library updates, and compliance reporting rather than building in-house technical teams.
The Transportation Security Administration in the United States mandates 100% cargo screening on passenger aircraft through its Certified Cargo Screening Program, while the European Union's RA3 (Regulated Agent Third Country) framework dictates security standards for inbound air freight from non-EU origins. The International Civil Aviation Organization's Annex 17 standards further harmonize baseline requirements, forcing equipment vendors to design multi-jurisdiction certification pathways into product development cycles. Stakeholders must monitor how fragmentation between national implementation timelines affects deployment planning and service contract structuring.
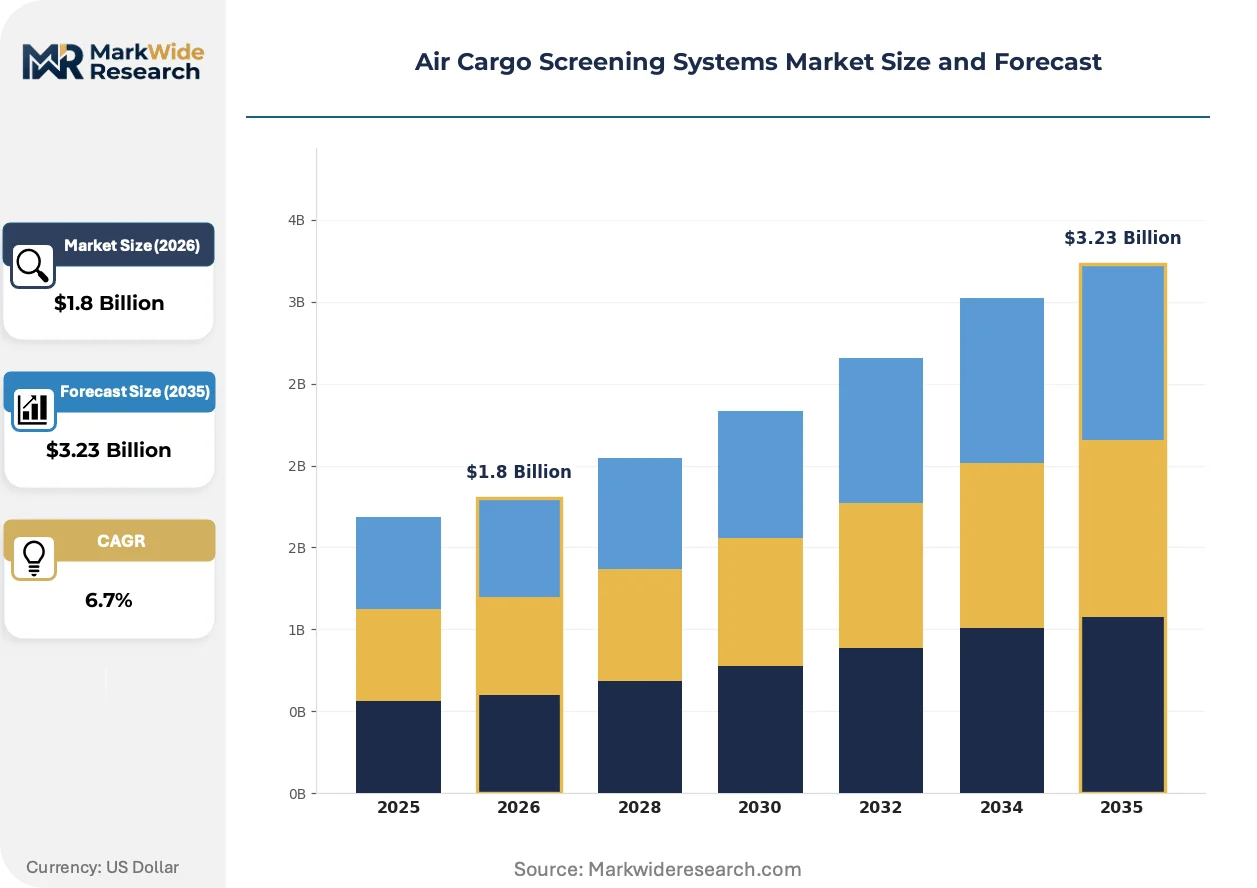
Market Dynamics
Software-defined threat detection algorithms are repositioning how screening capabilities get sold, shifting value from hardware ownership to continuous algorithmic updates that freight operators must subscribe to for compliance.
Growth Catalysts
- EU RA3 Framework Expansion:The European Union's updated Regulated Agent Third Country standards mandate enhanced screening for inbound freight from non-EU origins, forcing German freight forwarders to expand infrastructure.
- Explosives Trace Detection Mandates:Automated trace analysis requirements for high-risk origin routes are accelerating replacement cycles for legacy X-ray-only installations.
- Three-Dimensional Reconstruction Demand:Customs authorities in the Netherlands are capturing concentrated demand for computed tomography systems to achieve higher throughput accuracy at Rotterdam's cargo hubs.
Market Restraints
- High-Energy X-Ray Component Concentration:Specialized linear accelerator tubes for 1-6 MeV systems face supply concentration from a limited base of radiation source manufacturers.
- Multi-Jurisdiction Certification Burden:Equipment vendors must design parallel certification pathways for TSA, EASA, and ICAO Annex 17 compliance, extending product development timelines.
- Technical Throughput Limitations:Dense palletized freight inspection rates remain constrained by computational reconstruction speeds for tomographic imaging.
Strategic Opportunities
- Indian Airport Infrastructure Expansion:Price-sensitive procurement cycles for emerging greenfield cargo terminals present volume opportunities for screening system vendors.
- Services and Software Unbundling:Airlines increasingly outsource calibration, threat library updates, and compliance reporting rather than building in-house technical teams.
- Artificial Intelligence Convergence:Machine learning integration with existing X-ray platforms enables hardware retrofit rather than full replacement, opening upgrade revenue streams.
Industry Challenges
- Radiation Safety Specialist Scarcity:Qualified personnel for ionizing radiation system maintenance and calibration remain scarce across freight handling networks.
- Legacy System Integration Complexity:New computed tomography installations must interface with existing warehouse management systems and customs data platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Cargo Screening Systems Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: X-Ray, Computed Tomography, Explosives Detection, Magnetic Resonance Component: Hardware, Software, Services, Installation End User: Airports, Freight Forwarders, Cargo Terminals, Customs Application: Security Screening, Hazardous Material Detection, Compliance Checks, Risk Assessment |
| Companies Covered | Smiths Detection Inc., Rapiscan Systems Inc., L3Harris Technologies Inc., Leidos Inc., Nuctech Company Limited, OSI Systems Inc., 3DX-RAY, Astrophysics Inc., Autoclear LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Cargo Screening Systems Market Emerging Trajectories
Active algorithm development is separating screening system performance from hardware generation cycles, enabling continuous capability improvement without physical replacement.
Computed tomography reconstruction engines are electrifying threat identification accuracy by generating volumetric cargo images that eliminate blind spots inherent to two-dimensional projection systems. Customs authorities at Amsterdam Schiphol and Frankfurt Cargo hubs are adopting these platforms for high-value express freight lanes. The technology is electrifying competitive positioning by compressing the performance gap between premium-tier and mid-tier hardware categories through software-defined differentiation.
The European Union's CSRD sustainability disclosure requirements are mandating energy consumption transparency for security equipment procurement, altering vendor qualification criteria. Screening system manufacturers must now document power draw per inspected ton and end-of-life recyclability metrics. Airport authorities in France and Germany are prioritizing low-energy CT platforms in tender evaluations, reshaping R&D investment toward efficiency optimization.
Freight operators are unbundling after-sales service contracts from initial hardware purchases, treating threat library subscriptions and calibration services as separately negotiable spend categories. Large integrators at Luxembourg and Brussels cargo hubs are consolidating vendor relationships to secure volume discounts on algorithmic updates. This pattern concentrates most visibly among European express carriers managing multi-country compliance obligations through centralized procurement functions.
Air Cargo Screening Systems Market Segmentation
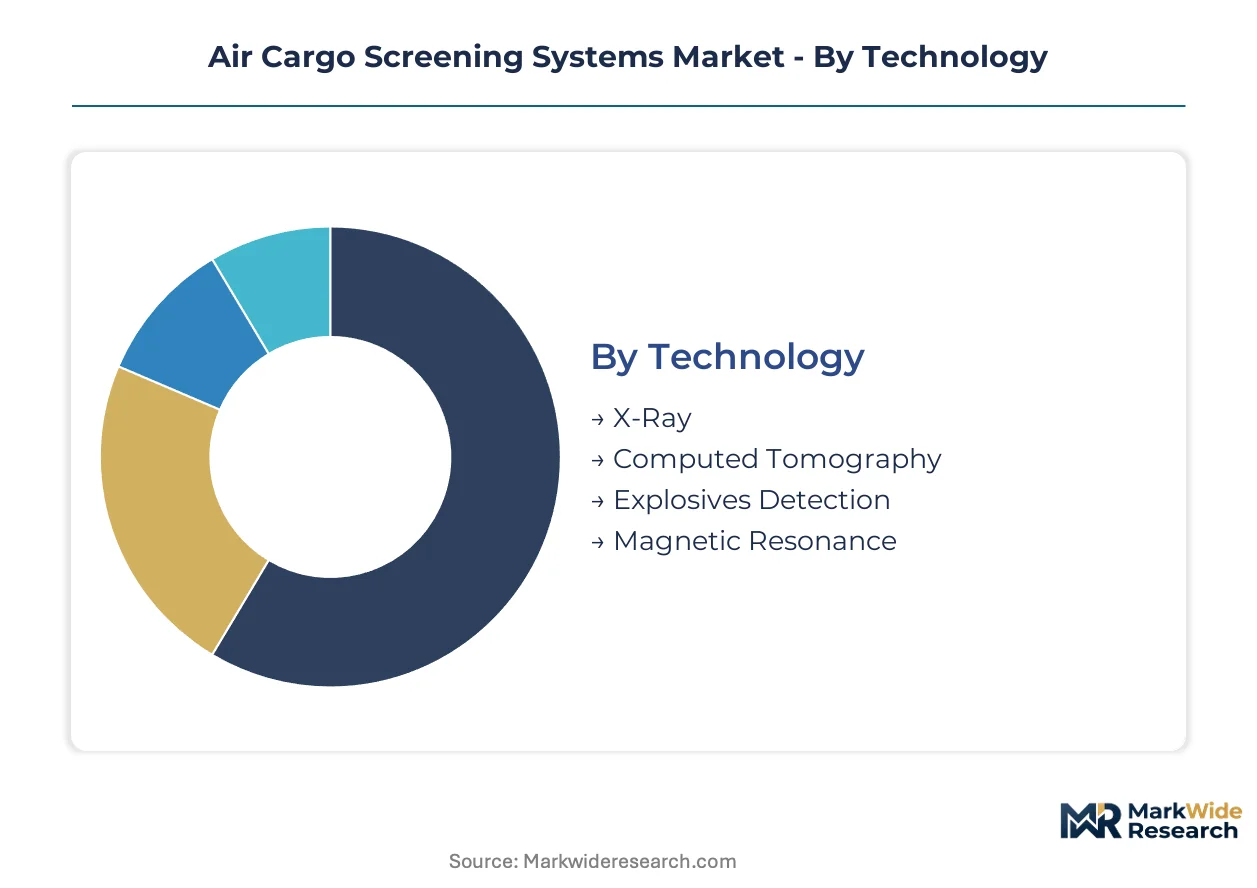
Technology choices in air cargo screening directly determine capital deployment cycles and recurring revenue potential for vendors. Component unbundling is reshaping contract structures as operators separate hardware procurement from algorithm subscriptions and calibration services.
Technology:
Upgrade cycles concentrate where regulatory mandates force replacement of legacy single-view X-ray platforms with volumetric imaging capabilities.
- X-Ray:Linear accelerator systems operating at 1-6 MeV penetrate dense palletized freight for two-dimensional threat projection. German freight forwarders retain these platforms for low-risk origin lanes where throughput speed outweighs reconstruction depth.
- Computed Tomography:Volumetric reconstruction engines generate three-dimensional cargo images that eliminate blind spots inherent to projection systems. Customs authorities in the Netherlands deploy these at Rotterdam cargo hubs to achieve higher accuracy without manual re-screening.
- Explosives Detection:Automated trace analysis platforms detect residue signatures from high-risk origin routes. Mandates from the Transportation Security Administration accelerate replacement demand for legacy installations lacking automated capabilities.
- Magnetic Resonance:Non-ionizing electromagnetic screening identifies liquid and gel contraband without radiation exposure. Airport authorities in France evaluate these platforms for pharmaceutical and perishable freight lanes where ionizing methods risk product degradation.
Computed Tomography sits at the top of the volume ranking, with Explosives Detection climbing the fastest as regulators mandate automated trace analysis for specific origin corridors.
Component:
Cost tier separation between capital-intensive hardware and recurring service streams determines margin distribution across vendor portfolios.
- Hardware:Linear accelerator tubes, detector arrays, and conveyor mechanisms constitute the physical screening platform. Supply concentration for high-energy X-ray components from limited radiation source manufacturers extends procurement lead times.
- Software:Threat detection algorithms and reconstruction engines enable continuous capability improvement without physical replacement. Freight operators subscribe to threat library updates to maintain compliance across evolving regulatory standards.
- Services:Calibration, maintenance, and compliance reporting contracts generate recurring revenue detached from initial hardware sales. Large integrators at Luxembourg cargo hubs consolidate vendor relationships to secure volume discounts on algorithmic updates.
- Installation:System integration with existing warehouse management and customs data platforms requires specialized technical coordination. Legacy system integration complexity extends deployment timelines for computed tomography upgrades at established freight terminals.
Hardware captures the largest absolute spend, with Services expanding most quickly as operators outsource technical capabilities rather than building in-house teams.
End User:
Application-specific throughput requirements and compliance liability structures shape procurement authority across the value chain.
- Airports:Passenger-cargo co-located facilities mandate 100% screening compliance under TSA Certified Cargo Screening Program protocols. These operators prioritize throughput velocity to prevent logistics chokepoints during peak flight schedules.
- Freight Forwarders:Third-party logistics providers bear direct liability for security compliance across multi-origin cargo consolidation. German forwarders expand screening infrastructure to meet EU RA3 framework requirements for inbound non-EU freight.
- Cargo Terminals:Dedicated air freight handling facilities at Amsterdam Schiphol and Frankfurt hubs manage high-volume express lanes. These operators unbundle after-sales contracts to treat threat library subscriptions as separately negotiable spend categories.
- Customs:Government authorities at Rotterdam and Brussels hubs deploy screening for revenue protection and contraband interdiction. Customs platforms demand highest reconstruction accuracy to minimize false-positive rates that trigger costly manual inspections.
Freight Forwarders lead procurement volume, with Customs gaining share fastest as authorities internalize screening capabilities previously outsourced to private operators.
Application:
Customer type differentiation separates commodity compliance screening from premium-tier risk assessment services.
- Security Screening:Baseline threat detection for explosives, weapons, and contraband in palletized and containerized freight. This application dominates procurement volumes across all end-user categories.
- Hazardous Material Detection:Identification of undeclared dangerous goods including lithium batteries, flammable liquids, and radioactive substances. Regulatory mandates from the International Civil Aviation Organization Annex 17 standards force equipment upgrades.
- Compliance Checks:Automated documentation verification against customs declarations and security protocols. The European Union's CSRD sustainability disclosure requirements now mandate energy consumption transparency for screening equipment procurement.
- Risk Assessment:Predictive analytics for origin-route profiling and targeted inspection prioritization. Machine learning integration with existing X-ray platforms enables hardware retrofit rather than full replacement for this application.
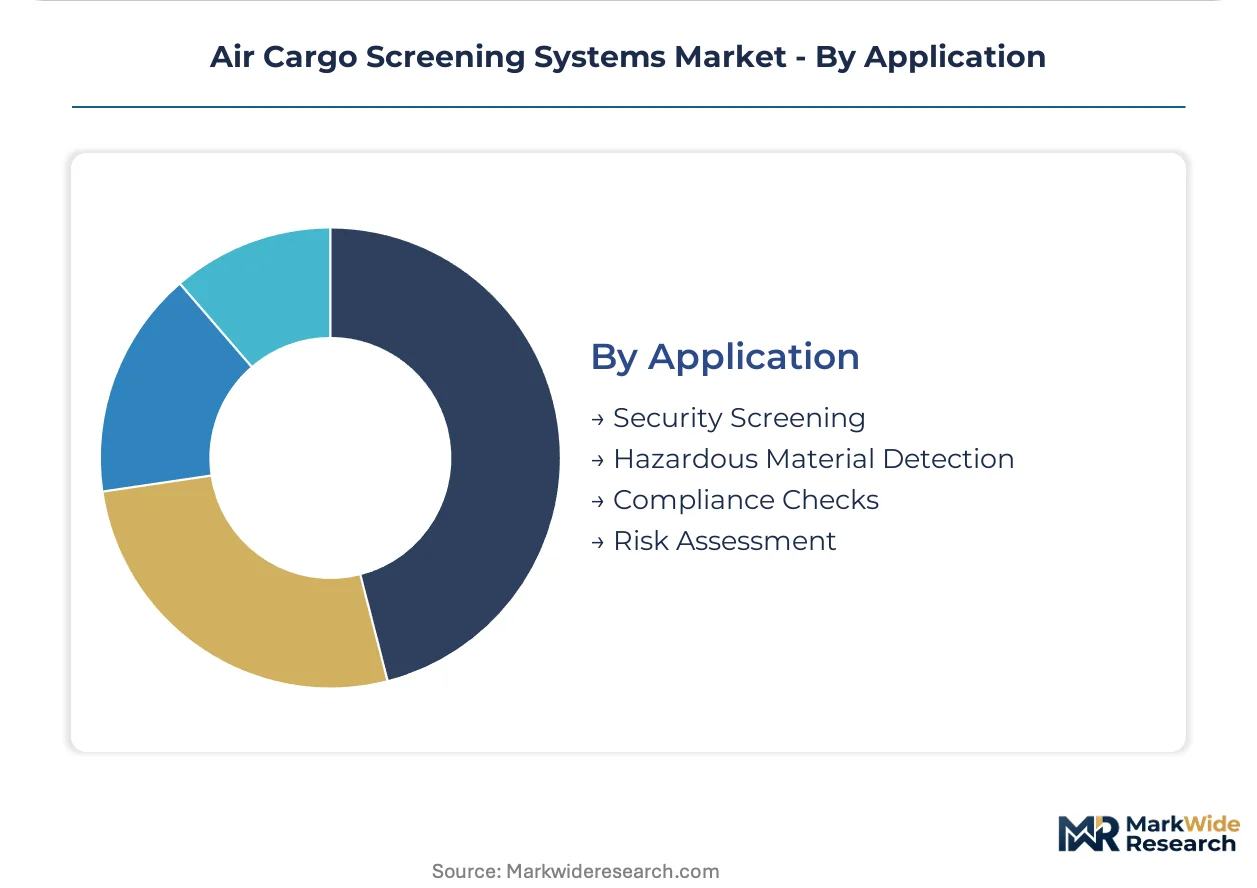
Security Screening dominates absolute deployment, with Risk Assessment advancing most quickly as artificial intelligence convergence enables software-defined capability expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping procurement patterns as freight operators migrate screening investments toward jurisdictions with harmonized certification standards and lower compliance overhead.
United States
The Transportation Security Administration's Certified Cargo Screening Program mandates 100% cargo screening on passenger aircraft, driving replacement demand at major cargo hubs. Federal procurement channels favor vendors with established supply relationships to the Department of Homeland Security. Chicago O'Hare and Memphis cargo terminals concentrate deployment volumes for express freight screening infrastructure.
Germany
Freight forwarders in Frankfurt and Leipzig are expanding screening infrastructure to comply with the European Union's updated RA3 framework for inbound non-EU freight. The country's federal aviation authority enforces strict certification timelines that extend equipment deployment schedules. Bavaria-based logistics clusters around Munich Airport represent the densest concentration of third-party screening facilities in Central Europe.
Netherlands
Customs authorities at Rotterdam cargo hubs are capturing concentrated demand for computed tomography systems to achieve higher throughput accuracy without manual re-screening. The Dutch customs administration operates under EU-wide security protocols while maintaining national discretion on technology procurement. Amsterdam Schiphol's dedicated cargo terminals unbundle after-sales contracts to treat algorithm subscriptions as separately negotiable spend categories.
China
Greenfield airport infrastructure programs across provincial cargo hubs are driving price-sensitive procurement cycles for emerging screening system vendors. The country's civil aviation regulator aligns domestic certification standards with International Civil Aviation Organization Annex 17 baselines while maintaining separate approval pathways. Zhengzhou and Chengdu cargo terminals exemplify the volume opportunity in central and western logistics corridors.
India
Airport Authority of India expansion programs for dedicated cargo terminals are creating volume opportunities for screening system vendors across price-sensitive procurement cycles. The Bureau of Indian Standards and Directorate General of Civil Aviation jointly oversee equipment certification timelines that extend deployment planning horizons. Maharashtra's Mumbai cargo cluster and Karnataka's Bangalore logistics hubs concentrate initial deployment volumes for express freight screening.
Air Cargo Screening Systems Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with federal channel relationships and price-positioning determining tier boundaries. The vendor base organizes around three archetypes: integrated security conglomerates with defense heritage, pure-play detection specialists with analytics depth, and emerging Asian fabricators competing on procurement cost. Consolidation pressure concentrates among mid-tier vendors lacking either channel control or manufacturing scale. Dominant competitive moves include strategic partnerships for algorithm licensing and geographic expansion through local certification partnerships.
Within the integrated conglomerate tier, Smiths Detection Inc. and L3Harris Technologies Inc. occupy positions anchored by federal procurement relationships and multi-jurisdiction certification portfolios. Nuctech Company Limited represents the emerging Asian fabricator archetype, competing through cost-optimized production for price-sensitive greenfield infrastructure programs. These three companies exemplify the strategic segmentation between channel-controlled incumbents and scale-driven challengers reshaping competitive dynamics across procurement cycles.
| Leading Market Players |
|---|
| Smiths Detection Inc. |
| Rapiscan Systems Inc. |
| L3Harris Technologies Inc. |
| Leidos Inc. |
| Nuctech Company Limited |
| OSI Systems Inc. |
| 3DX-RAY |
| Astrophysics Inc. |
| Autoclear LLC |
| Others |
Supply Flow & Price Mechanics
The European Union's CSRD sustainability disclosure requirements are gating qualified supply access and premium-tier pricing power by mandating energy consumption transparency and end-of-life recyclability documentation from screening system vendors. Airport authorities in France and Germany now prioritize low-energy CT platforms in tender evaluations, compressing margins for equipment lacking certified efficiency metrics while elevating pricing power for compliant manufacturers.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for mid-tier X-ray platforms as domestic fabricators compete aggressively on procurement cost. Three-tier pricing structure across premium, standard, and economy levels separates federal-certified CT systems from commercial-grade installations and basic single-view X-ray units. Cost compression in the standard tier is intensifying because European freight forwarders consolidate vendor relationships to secure volume discounts on algorithmic updates. Price-sensitive procurement cycles for emerging greenfield cargo terminals in India and China demonstrate highest buyer sensitivity, while TSA-certified deployments in the United States show lowest price elasticity due to compliance-driven specification requirements.
Supply Chain Analysis
Refurbishment flows for linear accelerator tubes and detector arrays are extending component lifecycles and creating secondary supply channels for price-conscious operators. Manufacturing concentration rests on the United States, Germany, and China for radiation source components, with specialized linear accelerator tubes drawing from a limited base of qualified suppliers. Critical dependencies include high-purity tungsten for X-ray anodes, scintillator crystals for detector arrays, and precision-machined conveyor mechanisms. Single-source vulnerability for 1-6 MeV linear accelerator tubes poses structural supply risk, as replacement timelines extend when primary manufacturers face capacity constraints. Distribution runs through direct federal procurement channels in North America, systems integrators in Europe, and state-owned aviation procurement entities in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The air cargo screening systems market functions as a stable compounder, with regulatory mandates for 100% cargo screening on passenger aircraft generating predictable replacement cycles and recurring service revenue streams.
For Market Incumbents: Deploy algorithmic subscription models to capture recurring revenue detached from hardware replacement cycles. Federal channel control through TSA and EASA certification investments protects against emerging Asian fabricators competing on procurement cost. Capacity additions in India and China by Nuctech Company Limited threaten mid-tier pricing power, necessitating defensive consolidation of freight forwarder relationships at Luxembourg and Brussels cargo hubs. For New Entrants and Emerging Players: The price-point gap between premium-tier CT systems and economy-grade X-ray platforms creates white-space opportunity for retrofit AI modules that upgrade existing hardware. Indian Airport Authority expansion programs for dedicated cargo terminals represent the most penetrable geography, with price-sensitive procurement cycles favoring cost-optimized production. A software-first go-to-market angle, offering threat library subscriptions without bundled hardware, bypasses capital-intensive manufacturing barriers. For Investors and Strategic Acquirers: Roll-up economics work for regional service specialists because freight operators increasingly outsource calibration and compliance reporting rather than building in-house technical teams. The 5-10 year viability window favors acquisition targets with established multi-jurisdiction certification portfolios and recurring service contract bases. Monitor TSA mandate expansion to all-cargo aircraft as the critical inflection signal for accelerated replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Licensing Partnership | Smiths Detection leverages deep hardware-analytics integration to sustain recurring revenue streams from freight operators. |
| Multi-Jurisdiction Certification Investment | Parallel TSA, EASA, and ICAO Annex 17 compliance pathways extend product development timelines but lock out unqualified competitors. |
| Services and Software Unbundling | Large integrators at Luxembourg cargo hubs treat threat library subscriptions as separately negotiable spend categories. |
| Green Manufacturing Transition | CSRD-mandated energy consumption transparency reshapes vendor qualification criteria toward low-energy CT platforms. |
| Geographic Expansion Through Local Certification | Nuctech Company Limited dominates price-sensitive procurement cycles across emerging airport infrastructure programs in China and India. |
Methodological Framework
Bottom-up freight forwarder and cargo terminal modeling reconciled against top-down radiation source manufacturer tracking forms the analytical core of this study. Primary interviews with airport security directors, customs technology procurement officers, freight forwarder operations managers, and screening system calibration technicians combined with secondary validation from TSA regulatory filings, EU RA3 framework documentation, ICAO Annex 17 standards, customs trade data, and vendor certification records. Triangulation across these sources ensures demand-side deployment figures align with supply-side production capacity.
Historical trendline analysis of replacement cycles and regulatory mandate implementation timelines anchors the projection framework. Segmentation dimensions modeled include technology type, component category, end-user archetype, and application purpose across the analysis window. CAGRs were derived from equipment deployment trajectories, subscription service adoption curves, and regulatory compliance deadline clustering. Industry-specific forecast inputs include EU RA3 framework expansion schedules and TSA Certified Cargo Screening Program mandate evolution.
Caveats apply where delays in multi-jurisdiction certification timelines or supply concentration for high-energy X-ray components could materially shift the outlook. Forecasts reflect assumptions about regulatory harmonization and freight throughput growth. Practitioners should monitor TSA mandate scope expansion and EU CSRD enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Global Firearm Sight Market
Security and Surveillance
Europe Security Screening Market
Security and Surveillance
Cargo Container X-Ray Inspection Systems Market
Security and Surveillance
Explosive Trace Detection Market
Security and Surveillance
Mass Transit Security Market
Security and Surveillance
Security Product Integration Services Market
Security and Surveillance
Security Analytics Market
Security and Surveillance
Europe Cargo and Vehicle Screening Market
Security and Surveillance
Global Law Enforcement Software Market
Security and Surveillance
Global Physical Security Software Market
Security and Surveillance
Security and Surveillance Equipment Market
Security and Surveillance
Security Holograms Market
Security and Surveillance
APAC Security Testing Market
Security and Surveillance
Private Military Security Services Market
Security and Surveillance
Security Operations Center Market
Security and Surveillance
Perimeter Security Market