
 Air Cargo Security Equipment Market | 2026-2036
Air Cargo Security Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Air Cargo Security Equipment Market Analysis
EU Green Deal aviation security amendments is rebalancing the cost-of-entry calculus for equipment vendors serving European air cargo hubs. Smiths Detection leverages its computed tomography portfolio to sustain technology leadership in explosive detection systems. Nuctech Company Limited anchors its competitive position through manufacturing scale and dominant presence across Asian cargo terminals. Leidos differentiates via integrated security platforms that combine screening hardware with threat-assessment software.
Air cargo security equipment encompasses screening and detection systems engineered to identify explosives, weapons, contraband, and unauthorized materials within freight shipments, typically operating at throughput rates exceeding 1,000 parcels per hour with false-alarm thresholds below 2%. These systems serve the primary commercial purpose of maintaining air transport safety while enabling compliant cargo flow through regulated supply chains. X-ray machines and explosive trace detectors represent the largest installed base, though computed tomography and 3D imaging segments are capturing expanding share as regulatory mandates tighten detection standards. Video analytics and RFID technology layers are emerging as margin-rich adjacencies, particularly among freight forwarders seeking integrated cargo tracking with security screening.
The US Transportation Security Administration, the European Union Aviation Safety Agency, and the International Civil Aviation Organization collectively shape equipment certification requirements, detection sensitivity thresholds, and operational protocols that vendors must satisfy for market access. China's Civil Aviation Administration and India's Bureau of Civil Aviation Security are enforcing parallel domestic standards that create additional compliance pathways for regionally focused suppliers. Stakeholders must monitor divergence between EU and US certification timelines, as asynchronous regulatory rollouts will fragment procurement cycles and reward vendors with flexible product architectures.
Market Dynamics
The air cargo security equipment market is experiencing structural pressure from regulatory divergence between the EU and US certification timelines, forcing vendors to architect flexible detection platforms that accommodate asynchronous mandate rollouts without full hardware redesigns.
Growth Catalysts
- EU Green Deal aviation security amendments:These regulations are mandating enhanced explosive detection capabilities at all-cargo airports, creating immediate replacement demand for legacy screening infrastructure.
- E-commerce logistics expansion:Parcel volumes through integrator hubs are forcing screening infrastructure upgrades to maintain throughput rates exceeding 1,000 parcels per hour.
- Computed tomography maturation:3D imaging systems are capturing expanding share as detection sensitivity thresholds tighten under ICAO protocols.
Market Restraints
- Certification cost concentration:Dual-track EU and US approval pathways impose redundant testing burdens on equipment vendors seeking cross-border market access.
- Detector material supply risk:Scintillator crystal production concentrates in limited Asian supply sources, exposing lead times to geopolitical friction.
- False-alarm rate floor:Current explosive trace detection technologies face fundamental sensitivity limits that prevent sub-2% alarm thresholds without unacceptable false negatives.
Strategic Opportunities
- India cargo terminal buildout:The Bureau of Civil Aviation Security is enforcing parallel domestic standards that create dedicated procurement pathways for regionally focused suppliers.
- RFID-security convergence:Freight forwarders are seeking integrated cargo tracking with screening, opening margin-rich adjacencies for platform vendors.
- Video analytics layering:AI-powered threat recognition overlays represent underpenetrated white space atop existing X-ray and CT installations.
Industry Challenges
- Computed tomography service engineering scarcity:Specialized technicians capable of maintaining rotating gantry assemblies and reconstruction algorithms remain concentrated at OEM facilities.
- Legacy system integration friction:New detection platforms must interface with existing baggage handling system architectures without disrupting 24/7 hub operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Cargo Security Equipment Market |
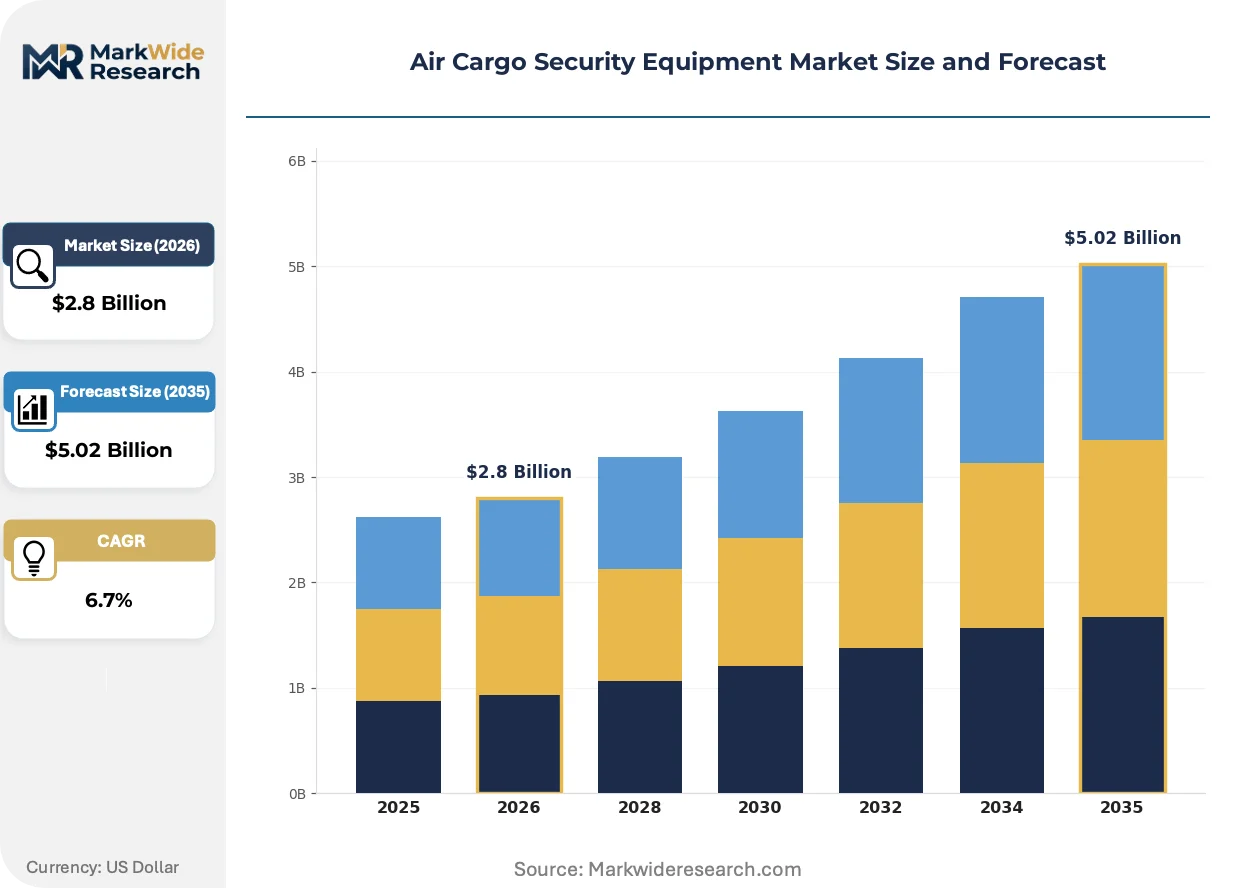
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray Machines, Explosive Trace Detectors, Biometric Scanners, Metal Detectors Technology: Computed Tomography, 3D Imaging, Video Analytics, RFID End User: Airports, Cargo Services, Freight Forwarders, Customs Authorities Installation Type: Fixed, Portable, Mobile, Integrated |
| Companies Covered | Smiths Detection, OSI Systems, Leidos, Nuctech Company Limited, Rapiscan Systems, L3Harris Technologies, Astrophysics Inc., Analogic Corporation, C.E.I.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Cargo Security Equipment Market Emerging Trajectories
Detection technology architectures are pivoting from hardware-centric screening stations toward software-defined platforms where algorithm updates extend equipment lifecycles. This shift compresses replacement cycles while elevating recurring revenue components in vendor business models.
Computed tomography is consolidating its position as the dominant detection modality for high-risk cargo lanes. Frankfurt and Leipzig hubs are deploying multi-view CT systems capable of automated explosive detection without operator interpretation. This consolidation is compressing demand for conventional 2D X-ray machines in premium screening segments.
REACH compliance deadlines for restricted substances in electronic components are forcing detector manufacturers to reformulate scintillator housings and circuit board substrates. Equipment vendors serving European air cargo terminals must certify supply chain documentation for phthalate and heavy metal content. German integrator hubs are prioritizing vendors with pre-validated material declarations to accelerate installation timelines.
Freight forwarders are unbundling after-sales service contracts from hardware procurement, selecting specialized maintenance providers independent of original equipment manufacturers. This disintermediation is visible across Netherlands and Belgium cargo clusters where third-party service firms now perform calibration and software updates on mixed-vendor screening lines. The shift pressures OEM margins on service attachments while opening specialist maintenance markets.
Air Cargo Security Equipment Market Segmentation
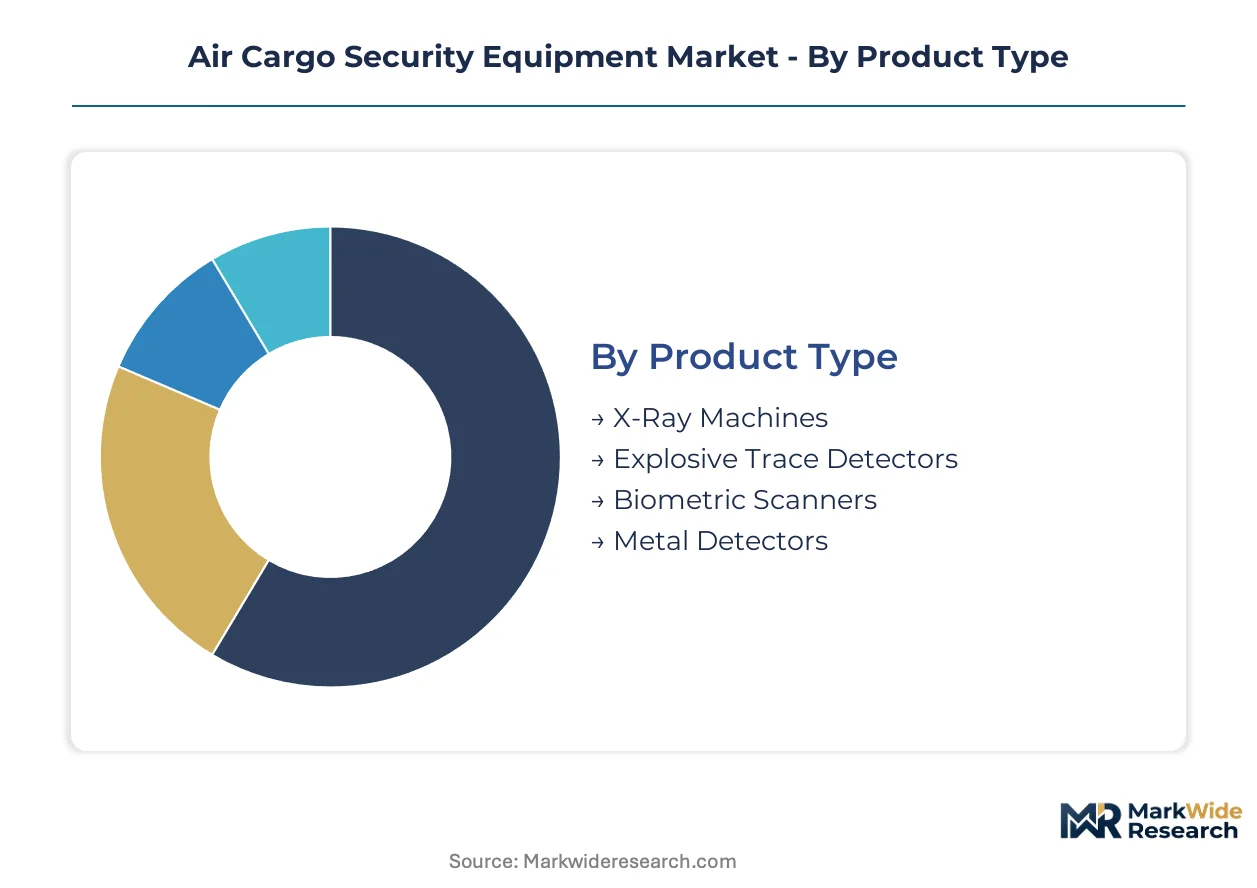
Air cargo security equipment segmentation reflects divergent certification burdens across product categories, with explosive detection systems facing dual-track EU and US approval pathways while biometric and tracking technologies navigate lighter compliance frameworks. Understanding these tiered regulatory loads enables vendors to prioritize R&D investment and anticipate procurement cycles across customer segments.
Product Type:
X-ray machines and explosive trace detectors carry the heaviest certification overhead, requiring TSA, EASA, and ICAO validation before hub deployment, while biometric scanners and metal detectors face streamlined national security clearances.
- X-Ray Machines:These systems employ dual-energy linear accelerators penetrating dense freight at throughput rates exceeding 1,000 parcels per hour. Frankfurt and Leipzig integrator hubs are driving replacement demand as EU Green Deal amendments mandate enhanced detection sensitivity for legacy installations.
- Explosive Trace Detectors:Ion mobility spectrometry and chemiluminescence technologies sample particulate residue from cargo surfaces. The sub-2% false-alarm threshold requirement under updated ICAO protocols is compressing demand toward next-generation systems with improved scintillator crystal sensitivity.
- Biometric Scanners:Fingerprint and iris recognition systems secure access-controlled cargo zones at customs facilities.
- Metal Detectors:Ferromagnetic and non-ferrous detection arrays screen loose cargo and palletized freight for weapons and contraband.
X-ray machines sit at the top of the volume ranking, with explosive trace detectors climbing the fastest.
Technology:
Technology segmentation tracks cost tier differentiation, with computed tomography commanding premium pricing against commoditized 2D imaging while software layers extract recurring revenue streams.
- Computed Tomography:Rotating gantry assemblies generate volumetric reconstructions enabling automated explosive detection without operator interpretation. Multi-view CT deployments at German all-cargo airports are displacing conventional X-ray lanes in high-risk screening segments.
- 3D Imaging:Stereoscopic and multi-angle projection systems deliver depth-resolved threat visualization at intermediate price points. Asian cargo terminals are adopting hybrid 3D-X-ray configurations to balance detection performance against capital constraints.
- Video Analytics:AI-powered threat recognition overlays screen passenger and cargo areas for anomalous behavior patterns.
- RFID:UHF and HF tag systems integrate security screening with supply chain tracking for freight forwarders seeking unified cargo visibility.
Computed tomography sits at the top of the volume ranking, with video analytics climbing the fastest.
End User:
End user segmentation maps procurement authority concentration, with airports and customs authorities controlling centralized capital budgets while freight forwarders fragment purchasing across decentralized operational units.
- Airports:Hub operators deploy integrated screening lines across inbound, outbound, and transfer cargo flows. The EU's updated aviation security regulations are mandating equipment refresh cycles at all-cargo facilities in Germany, Belgium, and the Netherlands.
- Cargo Services:Integrator-owned terminals at Leipzig and Memphis scale dedicated screening infrastructure to match e-commerce parcel volume growth.
- Freight Forwarders:Third-party logistics providers source screening capacity through airline and ground handler partnerships rather than direct equipment ownership.
- Customs Authorities:National inspection agencies operate selective examination systems targeting high-risk trade lanes and origin-destination pairs.
Airports sit at the top of the volume ranking, with cargo services climbing the fastest.
Installation Type:
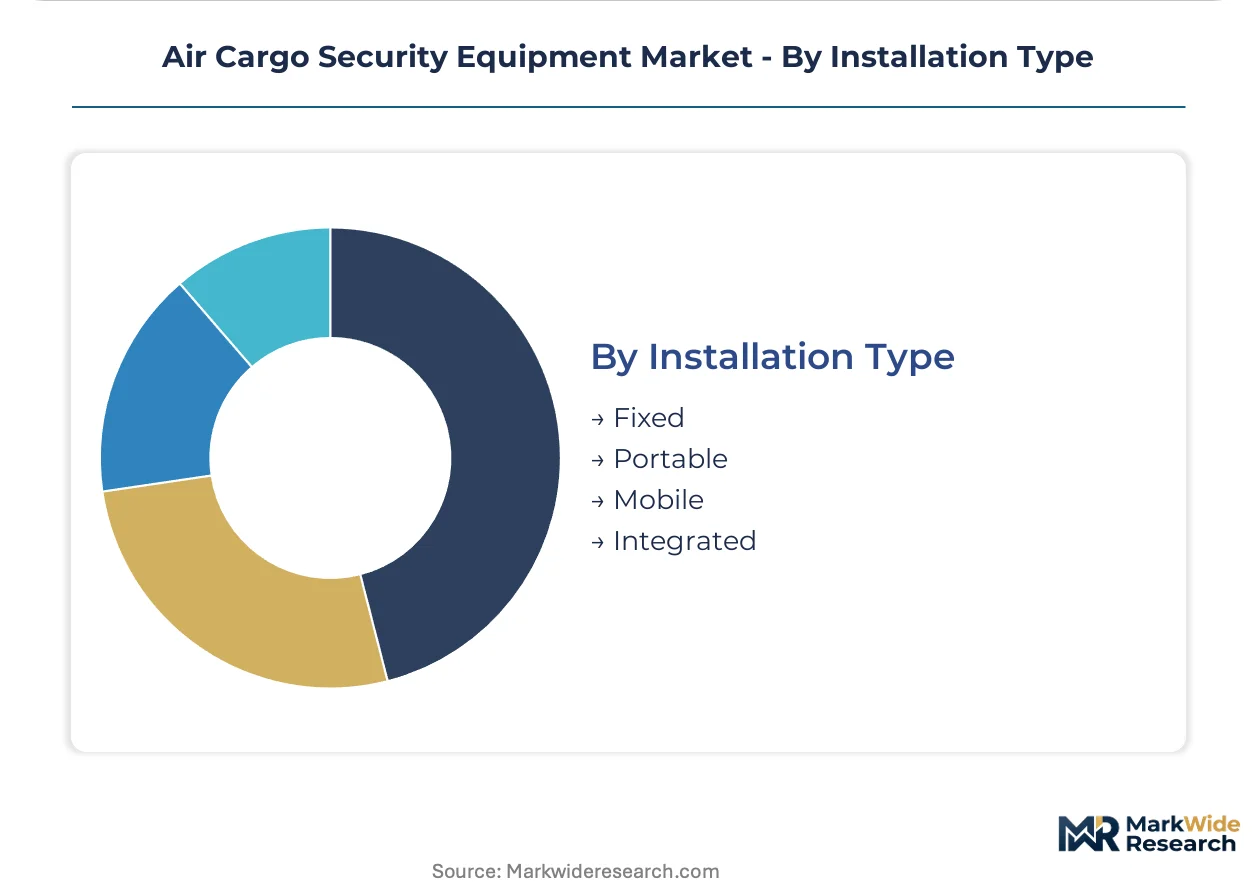
Installation segmentation reflects operational maturity gradients, with fixed infrastructure dominating established hubs while portable and mobile configurations penetrate emerging markets and contingency screening scenarios.
- Fixed:Permanent conveyor-integrated systems anchor high-throughput screening lanes with 24/7 operational profiles. German integrator hubs prioritize fixed CT installations with pre-validated REACH compliance documentation to accelerate commissioning timelines.
- Portable:Relocatable X-ray and trace detection units serve temporary cargo surges and seasonal peak operations.
- Mobile:Vehicle-mounted screening platforms enable rapid deployment to remote airfields and emergency logistics corridors.
- Integrated:Multi-technology screening stations combine detection modalities with automated sortation and data capture for unified cargo handling.
Fixed installations sit at the top of the volume ranking, with integrated systems climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The air cargo security equipment industry traces its commercial origins to post-2001 regulatory mandates in the United States and subsequent ICAO standardization, with equipment manufacturing scaling first through European integrator hubs and later across Asian cargo terminals.
United States
The Transportation Security Administration operates the world's largest certified screening fleet, with integrator hubs at Memphis and Louisville driving continuous equipment refresh cycles. TSA's Air Cargo Screening Technology List mandates third-party laboratory testing for explosive detection systems before hub deployment. Chicago O'Hare and Anchorage cargo terminals are consolidating screening lanes around computed tomography platforms to maintain throughput above regulatory minimums.
Germany
Frankfurt and Leipzig all-cargo airports account for the densest concentration of EU screening infrastructure investment, with EU Green Deal aviation security amendments accelerating replacement timelines for legacy X-ray installations. EASA's updated certification protocols for explosive detection systems are requiring enhanced material documentation under REACH compliance deadlines. Bavaria-based integrator facilities are prioritizing vendors with pre-validated scintillator supply chains to compress commissioning schedules.
China
The Civil Aviation Administration enforces parallel domestic certification standards that create dedicated procurement pathways for regionally focused equipment suppliers. Nuctech anchors manufacturing scale through captive production of scintillator crystals and detector assemblies. Shanghai Pudong and Beijing Capital cargo terminals are deploying hybrid 3D imaging configurations to balance detection performance against capital constraints in high-volume lanes.
India
The Bureau of Civil Aviation Security is enforcing phased mandates for explosive detection capability at all designated cargo terminals, creating procurement windows for screening hardware vendors. Delhi-Mumbai cargo corridors are driving infrastructure buildout as e-commerce parcel volumes strain existing 2D X-ray capacity. Bangalore and Hyderabad integrator facilities are selecting portable screening units to manage seasonal peak surges without permanent lane expansion.
United Arab Emirates
Dubai International and Abu Dhabi cargo hubs are consolidating screening infrastructure around multi-technology integrated platforms to maintain competitive positioning as transshipment gateways. The General Civil Aviation Authority aligns certification requirements with ICAO protocols while permitting accelerated approval pathways for vendors with EASA or TSA pre-qualification. Jebel Ali free zone cargo terminals are unbundling service contracts from hardware procurement, opening specialist maintenance markets independent of OEM channels.
Air Cargo Security Equipment Market Vendor Landscape
The competitive structure tilts toward technology-integrated platform vendors with established certification track records across multiple regulatory jurisdictions. Equipment supply concentrates among firms with captive detector manufacturing or long-term scintillator supply agreements, creating tiered access to high-throughput screening segments. Three archetypes dominate: computed tomography specialists leveraging algorithm differentiation, scale-driven manufacturers optimizing unit economics through vertical integration, and systems integrators combining hardware with threat-assessment software layers. Consolidation pressure manifests through strategic partnerships bridging hardware and analytics capabilities, alongside geographic expansion into emerging cargo terminal buildouts.
Among detection technology specialists, Smiths Detection and Leidos exemplify platform-centric positioning through integrated security architectures, while Nuctech Company Limited anchors the scale-driven manufacturing tier with dominant presence across Asian cargo terminals. OSI Systems and Rapiscan Systems occupy positions within the diversified technology conglomerate archetype, leveraging cross-segment engineering resources to sustain certification breadth. L3Harris Technologies represents the defense-industrial crossover pattern, applying aerospace imaging expertise to civil aviation screening requirements. Astrophysics Inc. and Analogic Corporation sit within the specialized component supplier tier, focusing on detector subsystems and reconstruction algorithms rather than complete screening platforms. C.E.I.A. anchors the European metal detection and access control specialization, with equipment certification pre-dating EU harmonization protocols.
| Leading Market Players |
|---|
| Smiths Detection |
| OSI Systems |
| Leidos |
| Nuctech Company Limited |
| Rapiscan Systems |
| L3Harris Technologies |
| Astrophysics Inc. |
| Analogic Corporation |
| C.E.I.A. |
| Others |
Supply Flow & Price Mechanics
Scintillator crystal costs flow from concentrated Asian production sources through three-tier pricing structures separating TSA-certified CT platforms from EASA-equivalent systems and uncertified economy configurations, with German integrator hubs absorbing premium markups for REACH-compliant material documentation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification tier and after-sales bundling intensity. TSA Air Cargo Screening Technology List validation commands 15-25% premiums over EASA-only equivalents, while freight forwarders in Netherlands-Belgium clusters show highest price sensitivity through unbundled service procurement. Cost compression in standard-tier X-ray machines intensifies as Chinese manufacturers scale detector assembly capacity.
Supply Chain Analysis
Regional distribution centers in Germany, China, and the United States anchor hub-and-spoke fulfillment patterns for screening hardware, with scintillator crystal supply drawing from Japanese and Chinese chemical processors. Detector gantry assemblies hinge on specialized machining capacity concentrated in Bavaria and Guangdong provinces. Single-source vulnerability in high-purity sodium iodide crystal production exposes lead times to geopolitical friction. Distribution runs through OEM-direct channels for certified platforms and third-party integrators for portable configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
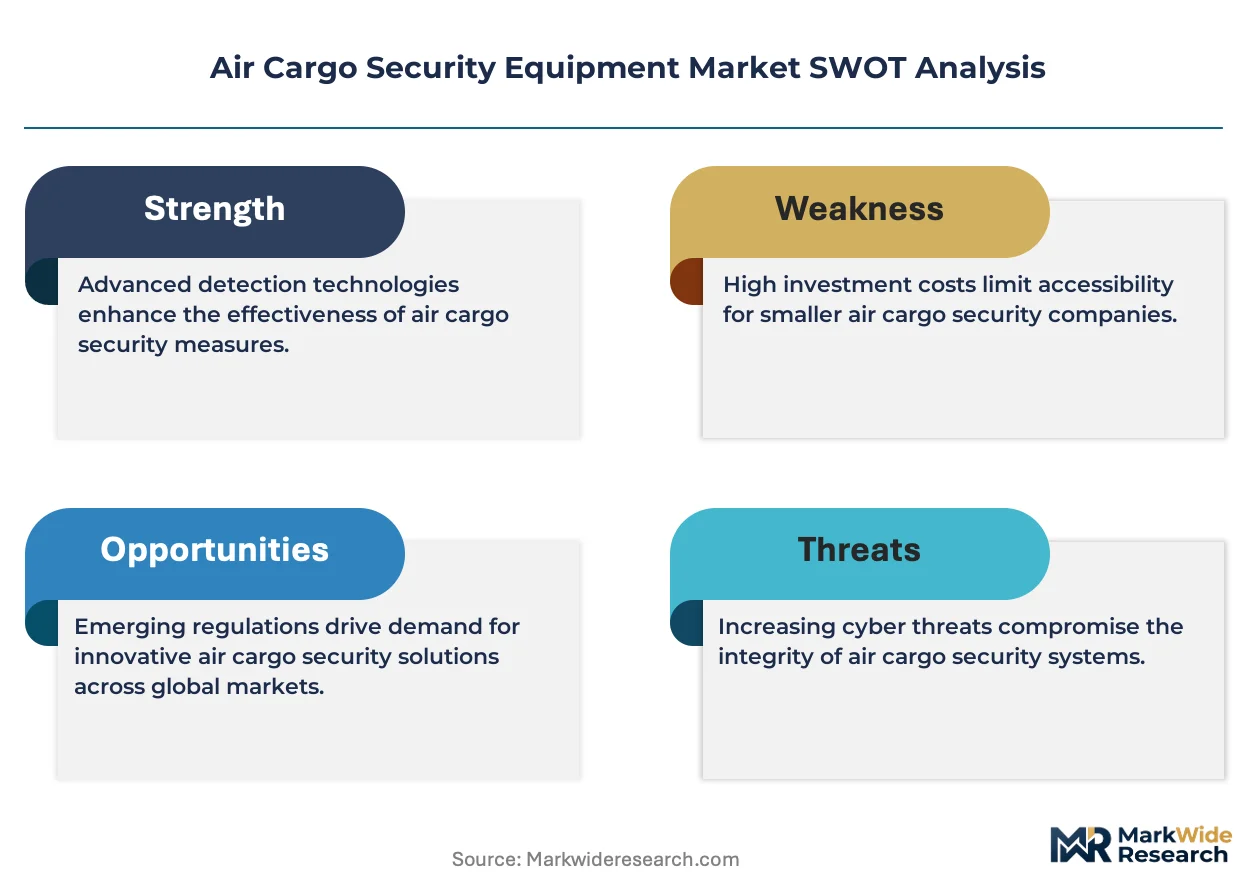
This market reads as a late-cycle quality story where EU Green Deal aviation security amendments shift procurement authority toward integrator hubs demanding premium detection sensitivity specifications.
For Market Incumbents: Hedge certification concentration risk by maintaining parallel TSA and EASA validation tracks for CT platforms, while securing captive scintillator supply agreements to defend margin position against Chinese scale entrants. Reinforce service attachment rates through predictive maintenance software layers that complicate third-party disintermediation.
For New Entrants and Emerging Players: India's Bureau of Civil Aviation Security phased mandates open a window for portable screening unit penetration at Bangalore and Hyderabad seasonal peak operations, bypassing fixed-installation incumbents. Target freight forwarder RFID-security convergence demand with modular tracking-screening bundles that bypass airport capital budget gatekeepers.
For Investors and Strategic Acquirers: Consolidation pressure builds where video analytics software layers remain fragmented across standalone AI vendors lacking hardware certification relationships. Five-to-ten year viability favors platform vendors with embedded algorithm update revenue streams over pure hardware manufacturers. Watch for ICAO protocol divergence between EU and US detection sensitivity thresholds as inflection signal for flexible-architecture acquirers.
| Strategic Initiative | Industry Significance |
|---|---|
| Computed Tomography Platform Certification | TSA and EASA dual-track validation secures access to Memphis and Frankfurt integrator hub procurement. |
| Scintillator Supply Agreement | Captive sourcing from Japanese crystal processors insulates against Chinese supply disruption and REACH compliance delays. |
| Video Analytics Software Layer | AI-powered threat recognition overlays extract recurring revenue from installed X-ray and CT bases at Netherlands cargo terminals. |
| RFID-Security Convergence Module | Integrated cargo tracking with screening addresses freight forwarder demand for unified supply chain visibility. |
| Third-Party Service Contract Capture | Independent maintenance provision at Jebel Ali free zone fragments OEM service margins and builds specialist market position. |
Methodological Framework
Coverage spans the United States, Germany, China, India, and the United Arab Emirates, with primary inputs from each combining interviews with airport security directors, cargo terminal operations managers, freight forwarder procurement leads, and OEM service engineering heads with secondary validation from TSA Air Cargo Screening Technology List certifications, EASA regulatory filings, ICAO protocol documentation, and Bureau of Civil Aviation Security mandate schedules. Bottom-up equipment shipment data triangulates against top-down cargo terminal capital expenditure disclosures.
Granularity-level modeling deploys product type, technology modality, end-user category, and installation configuration as core segmentation dimensions across the projection horizon, with computed tomography penetration rates and e-commerce parcel volume growth as industry-specific forecast inputs. CAGRs derive from logistic curve fitting of equipment replacement cycles against regulatory mandate timelines.
Revisions become necessary when ICAO protocol divergence accelerates, scintillator supply disruptions materialize, or integrator hub consolidation shifts procurement authority. Forecasts reflect documented assumptions around certification timeline synchronization and detector technology maturation curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Security and Surveillance Equipment Market
Security and Surveillance
India Perimeter Intrusion Detection and Prevention Market
Security and Surveillance
India Electronic Security Market
Security and Surveillance
Middle East and Africa Cargo and Vehicle Screening Market
Security and Surveillance
North America Security Services Market
Security and Surveillance
Narcotics Scanner Market
Security and Surveillance
Burglar Alarm Systems Market
Security and Surveillance
Airport Baggage Screening Systems Market
Security and Surveillance
Global Manned Security Service Market
Security and Surveillance
Europe People Screening Market
Security and Surveillance
Middle East Manned Security Services Market
Security and Surveillance
Europe Rockfall Radar Market
Security and Surveillance
Consumer Security Market
Security and Surveillance
Crowdsourced Security Market
Security and Surveillance
Signal Jamming Systems Market
Security and Surveillance
Global Firearm Sight Market