
 Global Contraband Detector Market | 2026-2036
Global Contraband Detector Market Size, Share, and Industry Trends Forecast 2026-2036
Global Contraband Detector Market Analysis
Millimeter-wave resolution standards are redrawing procurement criteria across aviation and customs agencies. Smiths Detection Group Ltd leverages its long-standing installed base at Heathrow, Dubai, and Singapore Changi to sustain service revenue streams. Nuctech Company Limited anchors its competitive stance through manufacturing scale and dominant positioning within China's domestic port modernization programs.
A contraband detector is an electronic screening apparatus engineered to identify prohibited materials, weapons, explosives, narcotics, or undeclared goods through electromagnetic, radiation, or optical sensing modalities, typically operating at throughput rates exceeding 1,000 items per hour in baggage handling configurations. X-ray technology occupies the largest installed base across customs checkpoints, though radiation detection capabilities are gaining share in high-threat corridor deployments. On the application dimension, airport security commands premium pricing while transportation hubs represent the fastest-growing addressable pool as mass transit agencies in India, Brazil, and Saudi Arabia accelerate capital programs.
The United States Transportation Security Administration coordinates with the FAA to mandate specific detection sensitivity thresholds for checked and carry-on baggage systems, while EU member states implement CE marking and MDR-aligned performance disclosures for screening equipment deployed at Schengen entry points. China's SAMR enforces GB standards for radiation-emitting security devices, creating a segmented compliance landscape that manufacturers must navigate on a country-by-country basis. Stakeholders should monitor how divergent certification timelines across Washington, Brussels, and Beijing reshape product roadmaps and regional market access priorities.
Market Dynamics
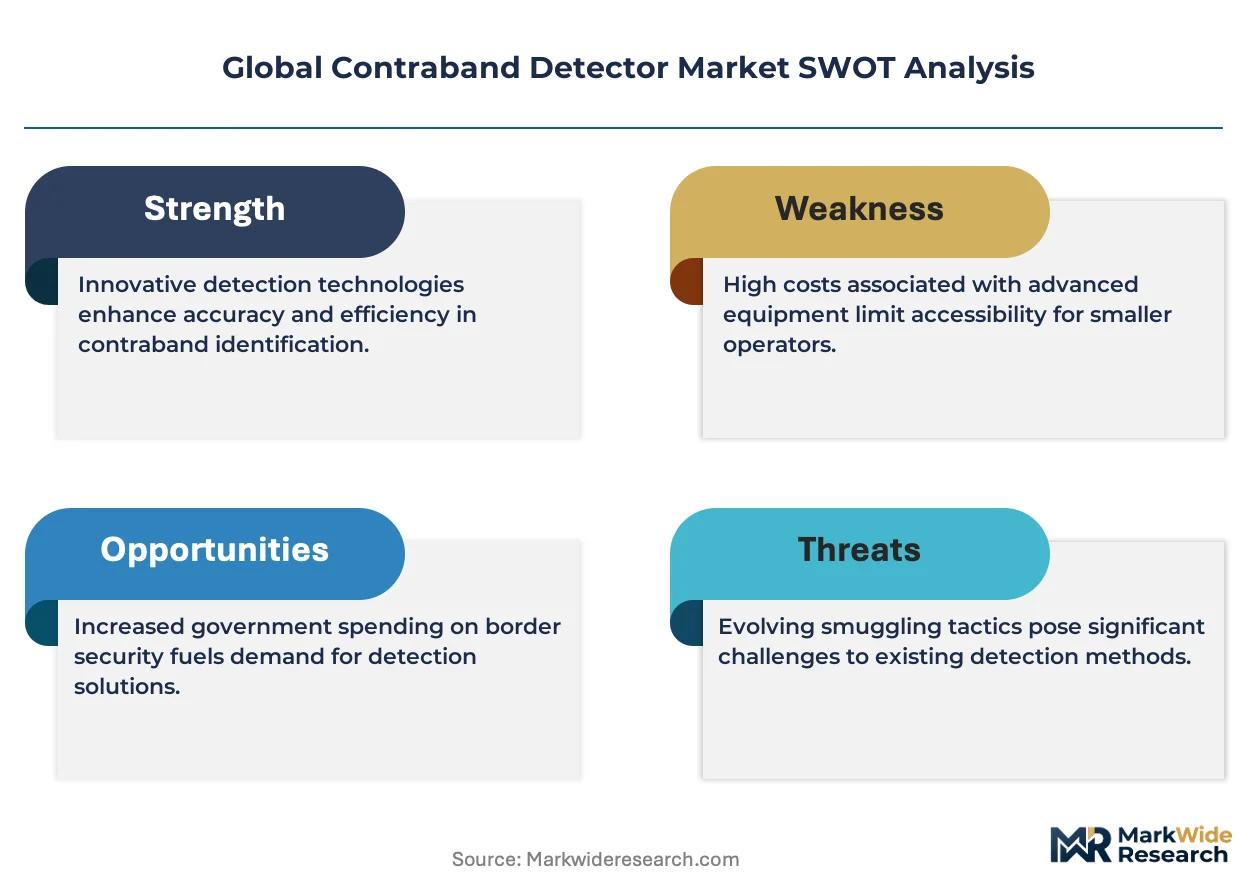
Aviation security mandates and AI-enabled detection thresholds are forcing simultaneous hardware refresh cycles and algorithm recertification across installed screening fleets. Procurement officers now face compressed timelines to replace legacy X-ray tunnels with multi-sensor platforms capable of satisfying divergent national certification regimes.
Growth Catalysts
- EU AI Act compliance deadlines:Airport operators in Germany, France, and Italy are accelerating replacement of rule-based detection algorithms with certified machine-learning classifiers to meet binding operational risk thresholds.
- China's port modernization:SAMR-mandated GB standards for radiation-emitting devices are driving wholesale equipment turnover at container terminals in Shanghai, Shenzhen, and Ningbo-Zhoushan.
- Millimeter-wave fusion architectures:Customs agencies in the United States and United Arab Emirates are specifying combined active/passive millimeter-wave systems for passenger screening checkpoints.
Market Restraints
- Helium-3 supply concentration:Radiation detection subsystem manufacturers remain dependent on Russian and Qatari isotope supply chains subject to export licensing volatility.
- FAA certification timelines:The Transportation Security Administration's phased sensitivity threshold mandates create 18-to-24-month approval backlogs for new baggage screening platforms.
- Neutron generator cost structure:Active interrogation systems requiring sealed-tube neutron sources face input cost escalation from tungsten and beryllium ceramic suppliers.
Strategic Opportunities
- Saudi Arabia's Giga-project security:NEOM and Red Sea Global developments are specifying integrated perimeter-screening networks combining passive millimeter-wave with chemical trace portals.
- Railway station modernization:Indian Railways and Brazil's CPTM are deploying portable X-ray and passive screening units at high-throughput urban transit nodes lacking fixed infrastructure.
- EU Green Deal procurement incentives:CE-marked screening equipment with disclosed embodied carbon footprints qualifies for preferential tender scoring in Dutch and Danish port authority RFPs.
Industry Challenges
- Machine-learning validation engineering:Manufacturers lack sufficient annotated threat libraries to satisfy FDA-equivalent algorithm performance documentation for explosive detection systems.
- Legacy system integration:Airport operators in the United States and United Kingdom face fiber-optic and power infrastructure constraints when retrofitting 1990s-era baggage halls with high-data-throughput sensor fusion platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Contraband Detector Market |
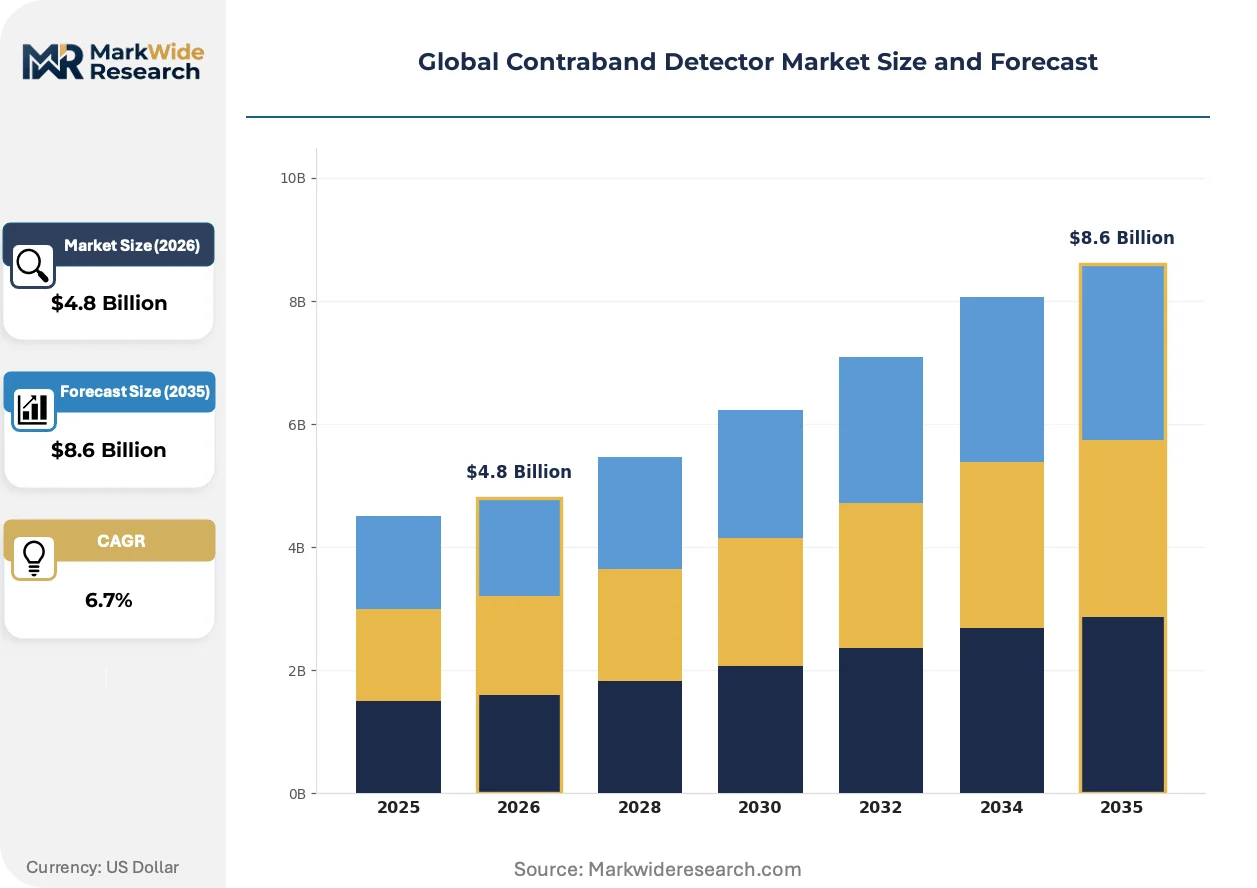
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
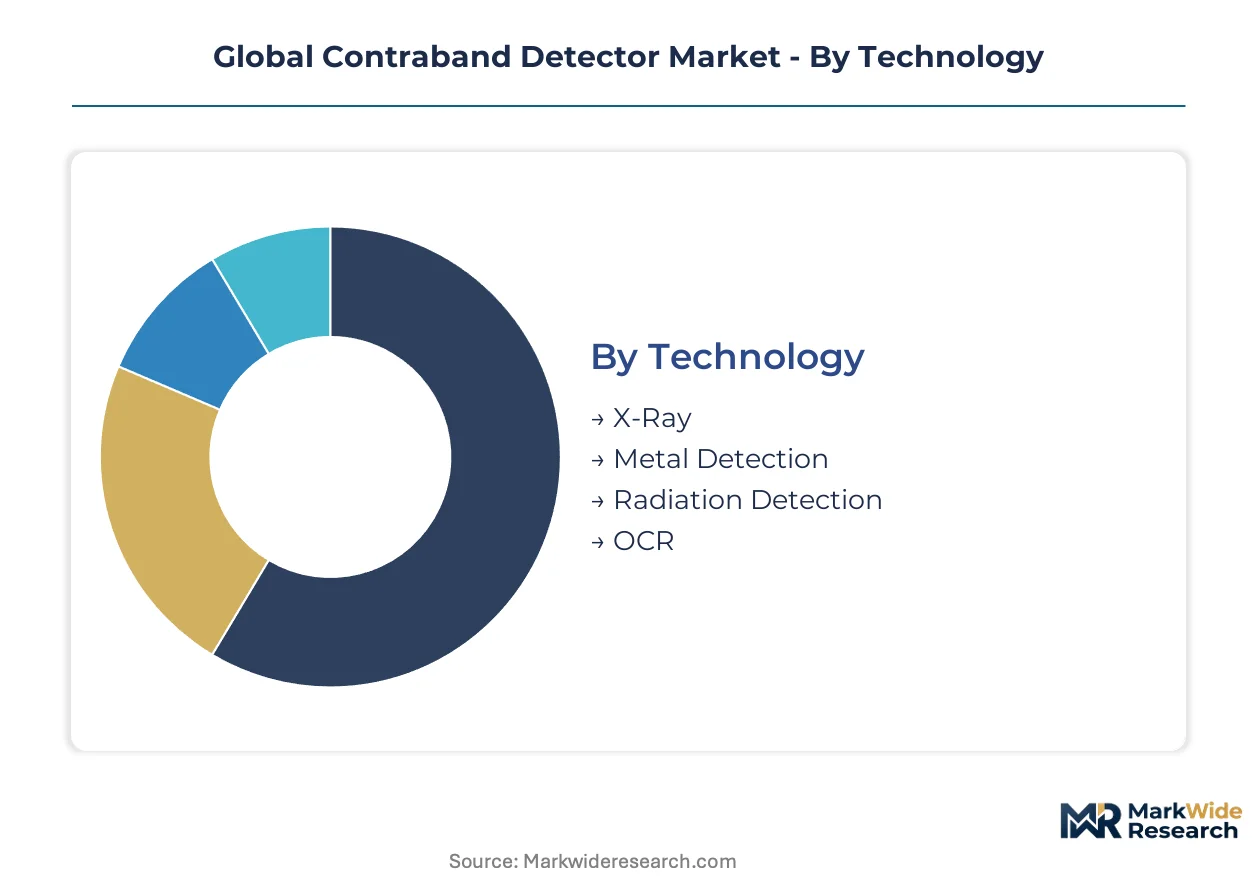
| Segmentation | Technology: X-Ray, Metal Detection, Radiation Detection, OCR Application: Customs, Military, Airport Security, Transportation Hubs End User: Government, Law Enforcement, Private Security, Transportation Companies Form Factor: Handheld, Portable, Fixed, Vehicle Mounted |
| Companies Covered | Smiths Detection Group Ltd, OSI Systems, Inc., Nuctech Company Limited, Leidos, L3Harris Technologies, Rapiscan Systems, Metrasens, Astrophysics Inc., ADANI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Contraband Detector Market Emerging Trajectories
Detection modality convergence and algorithmic recertification requirements are compressing product development cycles while fragmenting vendor specialization. Procurement patterns increasingly favor platforms capable of satisfying multiple national regulatory regimes through firmware-configurable detection libraries.
Passive millimeter-wave imaging arrays with real-time synthetic aperture processing are supplanting active scanned-beam portals at aviation checkpoints. The United States Transportation Security Administration has accelerated deployment at Category X airports following operational validation trials. This technology compression is enabling higher passenger throughput without lane expansion, reshaping terminal architecture specifications.
The EU AI Act's risk-based classification system for biometric and behavioral detection algorithms is mandating conformity assessment by notified bodies before operational deployment. Manufacturers must now maintain technical documentation and post-market monitoring systems equivalent to medical device obligations. Schengen-area airports in Germany and the Netherlands are prioritizing suppliers with existing MDR audit trails to compress certification timelines.
Mass transit agencies in India, Brazil, and Saudi Arabia are unbundling after-sales service from capital equipment contracts, creating dedicated multi-vendor maintenance pools. Delhi Metro and São Paulo CPTM now procure screening hardware through lease-to-own structures while contracting regional service integrators for calibration and spare parts logistics. This channel restructuring compresses vendor margins while extending equipment lifecycle accountability to third-party operators.
Global Contraband Detector Market Segmentation
Regulatory divergence across aviation, customs, and defense procurement channels fragments demand specifications and certification timelines. Vendors must architect product platforms capable of satisfying multiple detection thresholds and form-factor constraints simultaneously.
Technology:
FAA, EU AI Act, and SAMR GB standards enforce divergent sensitivity and algorithmic transparency requirements across detection modalities.
- X-Ray:Dual-energy and computed tomography configurations dominate checked baggage installations at Category X airports. Demand concentrates in the United States where TSA mandates specify minimum effective atomic number discrimination for explosive detection systems. FAA certification timelines extend 18-to-24 months for new tunnel deployments.
- Metal Detection:Millimeter-wave fusion architectures are displacing conventional induction coils at passenger screening checkpoints. Germany's Federal Police and the UAE's aviation authority specify combined active/passive systems for throughput optimization without lane expansion.
- Radiation Detection:Helium-3 and boron trifluoride neutron capture detectors serve portal monitors at border crossings. Supply chain concentration in Russian and Qatari isotope markets constrains subsystem availability.
- OCR:Automated container code recognition integrates with customs manifest databases at port terminals. Chinese SAMR enforces GB standards for optical character verification accuracy in Shanghai and Shenzhen container handling facilities.
Established volume favors X-Ray; emerging adoption favors Metal Detection.
Application:
Cost tier differentiation separates premium aviation security from volume transportation hub procurement.
- Customs:Multi-sensor platforms combining X-ray, radiation detection, and chemical trace analysis inspect containerized cargo at seaports. China's port modernization programs at Ningbo-Zhoushan and Shenzhen drive equipment turnover under SAMR-mandated GB compliance deadlines.
- Military:Man-portable and vehicle-mounted systems operate in contested logistics environments. Procurement prioritizes ruggedized form factors with passive millimeter-wave and ground-penetrating radar capabilities.
- Airport Security:Checked baggage, carry-on, and passenger screening each demand distinct certification pathways. EU AI Act conformity assessment for automated threat detection algorithms adds 6-to-12 months to deployment timelines at Schengen entry points.
- Transportation Hubs:Mass transit agencies in India and Brazil deploy portable screening units at high-throughput urban nodes lacking fixed infrastructure. Lease-to-own structures separate capital equipment from regional service contracts.
Aviation commands premium pricing; transportation hubs are climbing the fastest.
End User:
Customer type determines procurement authority complexity and contract structuring.
- Government:National customs and border protection agencies specify multi-year framework agreements with embedded technology refresh clauses. EU Green Deal procurement incentives favor CE-marked equipment with disclosed embodied carbon footprints in Dutch and Danish tenders.
- Law Enforcement:Tactical units require handheld and portable form factors for warrant-based searches and emergency response. Interoperability with existing command-and-control systems constrains vendor selection.
- Private Security:Critical infrastructure operators at data centers and energy facilities procure perimeter screening under insurance-mandated risk mitigation protocols.
- Transportation Companies:Railway and bus operators in São Paulo and Delhi unbundle after-sales service from hardware acquisition, contracting third-party integrators for calibration logistics.
Government procurement dominates contract value; private security shows steepest expansion trajectory.
Form Factor:
Application setting and infrastructure maturity dictate mobility requirements.
- Handheld:Battery-powered chemical trace and radiation detectors support law enforcement field operations. Miniaturized sensor packages trade sensitivity for portability.
- Portable:Deployable X-ray and millimeter-wave units serve temporary checkpoints and event security. Indian Railways and Brazil's CPTM specify rapid-deployment configurations for station modernization.
- Fixed:Tunnel and portal installations at airports and seaports require fiber-optic and power infrastructure upgrades in 1990s-era facilities.
- Vehicle Mounted:Mobile screening platforms patrol border corridors and support military convoy security. Neom and Red Sea Global developments in Saudi Arabia specify integrated perimeter networks combining passive millimeter-wave with chemical trace portals.
Fixed installations anchor revenue stability; portable configurations gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export millimeter-wave screening systems to aviation authorities in the United States and United Arab Emirates, establishing a transatlantic trade corridor in advanced passenger checkpoint technology.
United States
The Transportation Security Administration mandates specific detection sensitivity thresholds for checked and carry-on baggage systems, coordinating with the FAA on 18-to-24-month certification timelines. Category X airports in Atlanta and Los Angeles accelerate deployment of passive millimeter-wave imaging arrays following operational validation trials.
Germany
Federal Police specifications for combined active/passive millimeter-wave systems drive procurement at Frankfurt and Munich airports. EU AI Act conformity assessment requirements add 6-to-12 months to deployment timelines for automated threat detection algorithms. Industrial concentration in Bavaria supports sensor fusion platform development.
China
Port modernization programs at Ningbo-Zhoushan and Shenzhen drive equipment turnover under SAMR-mandated GB standards for radiation-emitting devices. Domestic manufacturing scale anchors positioning within container terminal automation initiatives. Yangtze River Delta clusters concentrate production capacity.
India
Indian Railways deploys portable X-ray and passive screening units at high-throughput urban transit nodes lacking fixed infrastructure. Lease-to-own procurement structures separate capital equipment from regional service contracts. Delhi Metro and Mumbai suburban networks specify rapid-deployment configurations.
Saudi Arabia
NEOM and Red Sea Global developments specify integrated perimeter-screening networks combining passive millimeter-wave with chemical trace portals. Giga-project security requirements create dedicated demand for vehicle-mounted mobile platforms. Riyadh and Jeddah anchor procurement authority.
Global Contraband Detector Market Vendor Landscape
Listed leaders compete with private specialists across certification-tracked procurement channels, creating a tiered structure where public-company scale advantages meet private-firm agility in navigating national regulatory regimes. The vendor base organizes around three strategic archetypes: diversified defense contractors leveraging existing government relationships, pure-play detection specialists focusing on algorithmic differentiation, and state-affiliated manufacturers capturing domestic modernization programs. Consolidation pressure operates through technology licensing partnerships and strategic alliances rather than outright acquisition, as national security sensitivities constrain cross-border M&A.
Among UK- and US-based listed entities, Smiths Detection Group Ltd and OSI Systems, Inc. exemplify the diversified defense-contractor archetype with established installed bases at major aviation hubs. Nuctech Company Limited, a Beijing-based limited company, occupies a position representing state-affiliated manufacturing scale. These three anchors illustrate how competitive positioning fragments across geographic regulatory spheres rather than consolidating globally.
| Leading Market Players |
|---|
| Smiths Detection Group Ltd |
| OSI Systems, Inc. |
| Nuctech Company Limited |
| Leidos |
| L3Harris Technologies |
| Rapiscan Systems |
| Metrasens |
| Astrophysics Inc. |
| ADANI |
| Others |
Supply Flow & Price Mechanics
Manufacturing scale at Yangtze River Delta production clusters shapes both supply concentration and price floors for millimeter-wave sensor arrays. Dual-source strategies for helium-3 isotopes and neutron generator ceramics compress margins while elevating entry barriers for non-integrated vendors.
Pricing Analysis
Current-generation passive millimeter-wave systems command substantial premiums over legacy active scanned-beam portals and prior-generation X-ray tunnels. Three-tier pricing structure across aviation-certified, customs-grade, and portable-economy levels separates TSA-mandated baggage screening from Indian Railways lease-to-own procurement. Cost compression in the portable segment intensifies because mass transit agencies unbundle service contracts from hardware acquisition. Government customs agencies exhibit lowest price sensitivity due to multi-year framework agreements with embedded refresh clauses.
Supply Chain Analysis
Russian and Qatari isotope supply chains underwrite global availability of helium-3 neutron capture detectors for radiation portal monitors. Component sourcing draws from Chinese tungsten ceramic suppliers, German precision optics manufacturers, and Japanese semiconductor foundries for millimeter-wave transceiver modules. Single-source vulnerability in sealed-tube neutron generator assemblies creates procurement risk for active interrogation system builders. Distribution runs through national security equipment integrators holding cleared personnel status with customs and aviation authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in transportation hub security creates penetration tailwinds as Indian Railways and Brazil's CPTM accelerate capital programs beyond saturated aviation procurement channels.
For Market Incumbents: Compound installed base advantages at Category X airports into adjacent customs and mass transit verticals through firmware-configurable detection libraries. Defend against pure-play algorithm specialists by embedding EU AI Act MDR audit trails into platform architectures. Prioritize backward integration into neutron generator ceramics to offset tungsten and beryllium cost escalation. For New Entrants and Emerging Players: Differentiate on rapid-deployment portable configurations for railway station modernization programs lacking fixed infrastructure. Target India's lease-to-own procurement structures and Saudi Arabia's Giga-project perimeter networks as penetrable white spaces. Pursue regional service integrator partnerships to bypass direct competition with established aviation vendors. For Investors and Strategic Acquirers: Algorithm-centric detection software vendors with existing notified body relationships represent priority acquisition archetypes for platform consolidation plays. Long-term viability hinges on multi-regulatory certification asset bases spanning FAA, EU AI Act, and SAMR GB compliance pathways. Monitor helium-3 supply agreement renegotiations as inflection indicators for radiation detection subsystem margins.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Regulatory Certification Investment | EU AI Act MDR audit trails compress deployment timelines at Schengen airports. |
| Neutron Generator Backward Integration | In-house tungsten ceramic production insulates margins from Qatari supply volatility. |
| Portable Configuration Development | Rapid-deployment units capture Indian Railways and São Paulo CPTM modernization demand. |
| Regional Service Integrator Partnership | Third-party maintenance pools extend lifecycle accountability beyond hardware margins. |
| Algorithm Library Firmware Expansion | Machine-learning classifier updates satisfy divergent national sensitivity thresholds. |
Methodological Framework
Operator-level perspectives from TSA procurement officers, EU aviation security coordinators, SAMR certification engineers, and Indian Railways infrastructure planners anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against FAA certification databases, EU notified body disclosure registers, Chinese customs equipment procurement records, and SEC filings from listed defense contractors. Bottom-up unit deployment estimates triangulated with top-down addressable infrastructure spending across the analysis window.
Sensitivity analysis around helium-3 supply disruption scenarios and FAA certification timeline compression informed the analytical framework. Segmentation dimensions modeled include detection modality, application setting, procurement authority type, and regional regulatory cluster. CAGRs were derived from infrastructure spending trajectories and equipment replacement cycles. Industry-specific forecast inputs encompass TSA sensitivity threshold mandate schedules and SAMR-mandated GB compliance deadlines at Chinese container terminals.
The analysis sits within stated boundaries; outcomes outside sustained aviation security capital allocation and stable isotope supply chain conditions would require recalibration. Forecasts reflect documented assumptions regarding regulatory timeline adherence and procurement authority budget continuity. Practitioners should keep alternative scenarios live as EU AI Act enforcement intensity and China port automation investment pacing evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
North America Wireless Monitoring and Surveillance Market
Security and Surveillance
Cargo Container X-Ray Inspection Systems Market
Security and Surveillance
Global X-Ray Security Scanner Market
Security and Surveillance
North America Cargo and Vehicle Screening Market
Security and Surveillance
Global Adaptive Security Market
Security and Surveillance
Air Cargo Security Equipment Market
Security and Surveillance
Europe Security Testing Market
Security and Surveillance
Door and Window Alarm Market
Security and Surveillance
Global Security Assurance Market
Security and Surveillance
Forensic Technologies Market
Security and Surveillance
Asia-Pacific Security Services Market
Security and Surveillance
Home Security Solution Market
Security and Surveillance
Middle East and Africa Cargo Inspection Market
Security and Surveillance
Global Container Security Market
Security and Surveillance
Destructible Security Labels Market
Security and Surveillance
Asia-Pacific Urban Security Screening Market