
 North America Security Screening Market | 2026-2036
North America Security Screening Market Size, Share, and Industry Trends Forecast 2026-2036
North America Security Screening Market Analytics
Security-cleared engineering talent shortages across the United States and Canada is unwinding deployment timelines for next-generation checkpoint systems. Smiths Detection Inc. sustains its technology leadership in computed tomography baggage screening through deep R&D commitments. L3Harris Technologies dominates passenger screening contracts at tier-one US airports with integrated ProVision systems. OSI Systems Inc. leverages its Rapiscan brand to anchor cargo and vehicle inspection segments across North American ports of entry.
North America security screening encompasses the detection, identification, and threat-assessment of personnel, baggage, cargo, and vehicles using electromagnetic, ionizing radiation, and advanced sensor technologies, typically operating at energy levels from 140 kV to 320 kV for X-ray systems and millimeter-wave frequencies for passenger portals. These systems serve critical functions in preventing unauthorized weapons, explosives, and contraband from entering controlled transportation, government, and public venues. Among product types, X-ray machines occupy the largest installed base while advanced imaging technology captures the fastest replacement cycle as airports retire legacy metal detectors. On the end-user dimension, aerospace terminals generate the highest absolute spending, though public events represent the most price-sensitive procurement channel with compressed decision timelines.
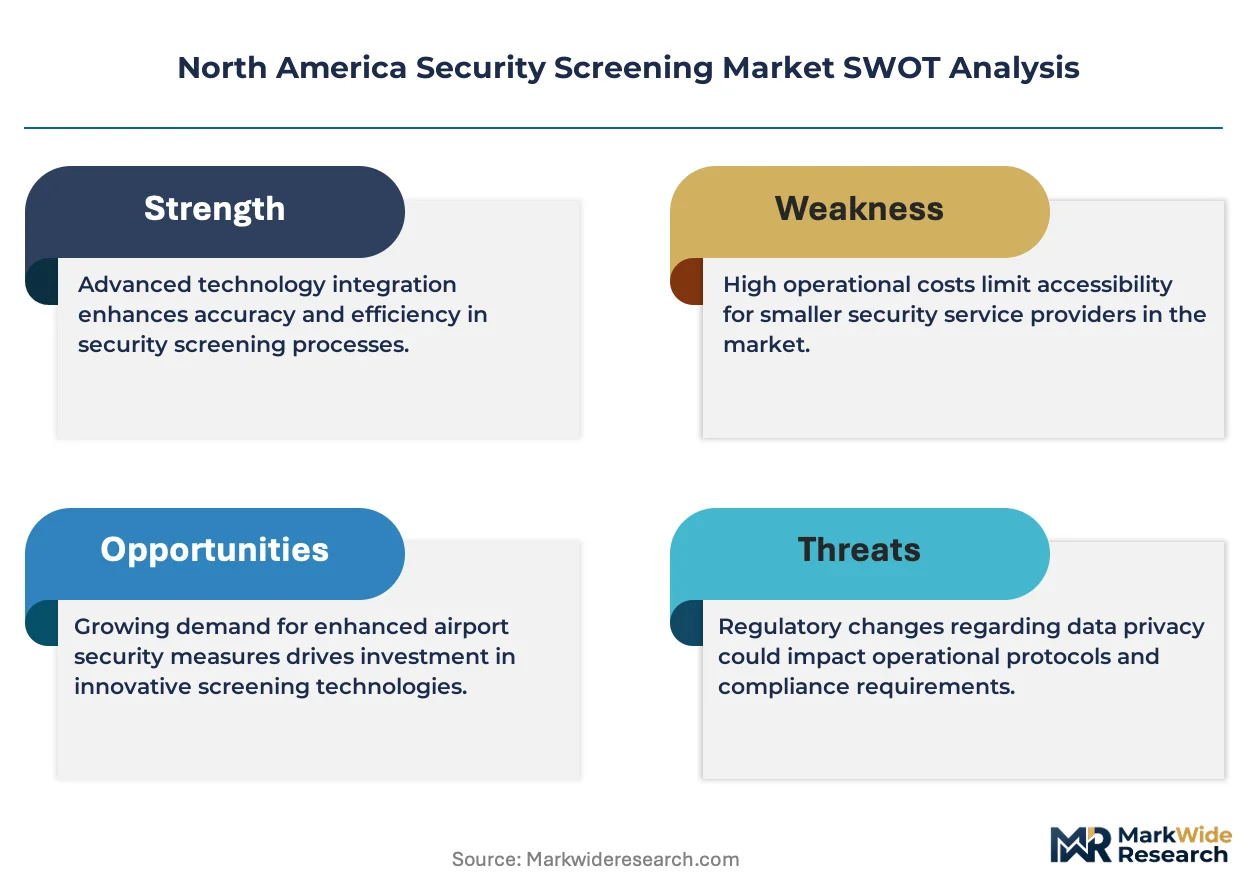
The Transportation Security Administration enforces checkpoint technology mandates that directly shape vendor qualification and product certification requirements for US airport deployments. Transport Canada's screening regulations and the FAA's security program standards create parallel compliance pathways that influence cross-border equipment standardization and procurement specifications. Stakeholders must monitor how biometric integration requirements and AI analytics validation protocols reshape competitive qualification thresholds and deployment economics across federal, state, and municipal contracting tiers.
Market Dynamics
The Transportation Security Administration's checkpoint technology mandates are compressing vendor qualification timelines and forcing parallel certification tracks across federal, state, and municipal contracting tiers. Equipment refresh cycles accelerate as airports modernize legacy metal detector lanes.
Growth Catalysts
- TSA PreCheck expansion:Enrollment growth across the United States drives demand for dedicated expedited screening lanes requiring specialized passenger portal configurations.
- FAA security program standards:Updated directives mandate computed tomography baggage screening deployment at tier-one US airports, triggering bulk procurement cycles.
- Millimeter-wave frequency adoption:Advanced imaging technology captures replacement demand as facilities retire legacy electromagnetic screening systems.
Market Restraints
- Security-cleared engineering scarcity:Talent shortages across the United States and Canada unwind deployment timelines for next-generation checkpoint installations.
- Input cost volatility:Semiconductor component pricing fluctuation disrupts manufacturing schedules for sensor-integrated screening systems.
- Regulatory fragmentation:Divergent Transport Canada screening regulations and TSA mandates create cross-border equipment standardization friction.
Strategic Opportunities
- Biometric integration mandates:Federal requirements for facial recognition at checkpoints open white space for multimodal authentication system vendors.
- Public events procurement channel:Compressed decision timelines at sports and entertainment venues favor rapid-deployment screening configurations.
- AI analytics validation protocols:Emerging certification pathways for automated threat detection create first-mover advantage for algorithm-compliant suppliers.
Industry Challenges
- Integration complexity with legacy infrastructure:Retrofitting existing checkpoint footprints without operational disruption demands specialized installation protocols.
- Certification timeline compression:Accelerated TSA qualification windows strain testing laboratory capacity and delay product commercialization.
- Capex intensity for hub expansions:Major airport modernization programs require multi-year capital commitments that strain municipal financing structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Security Screening Market |
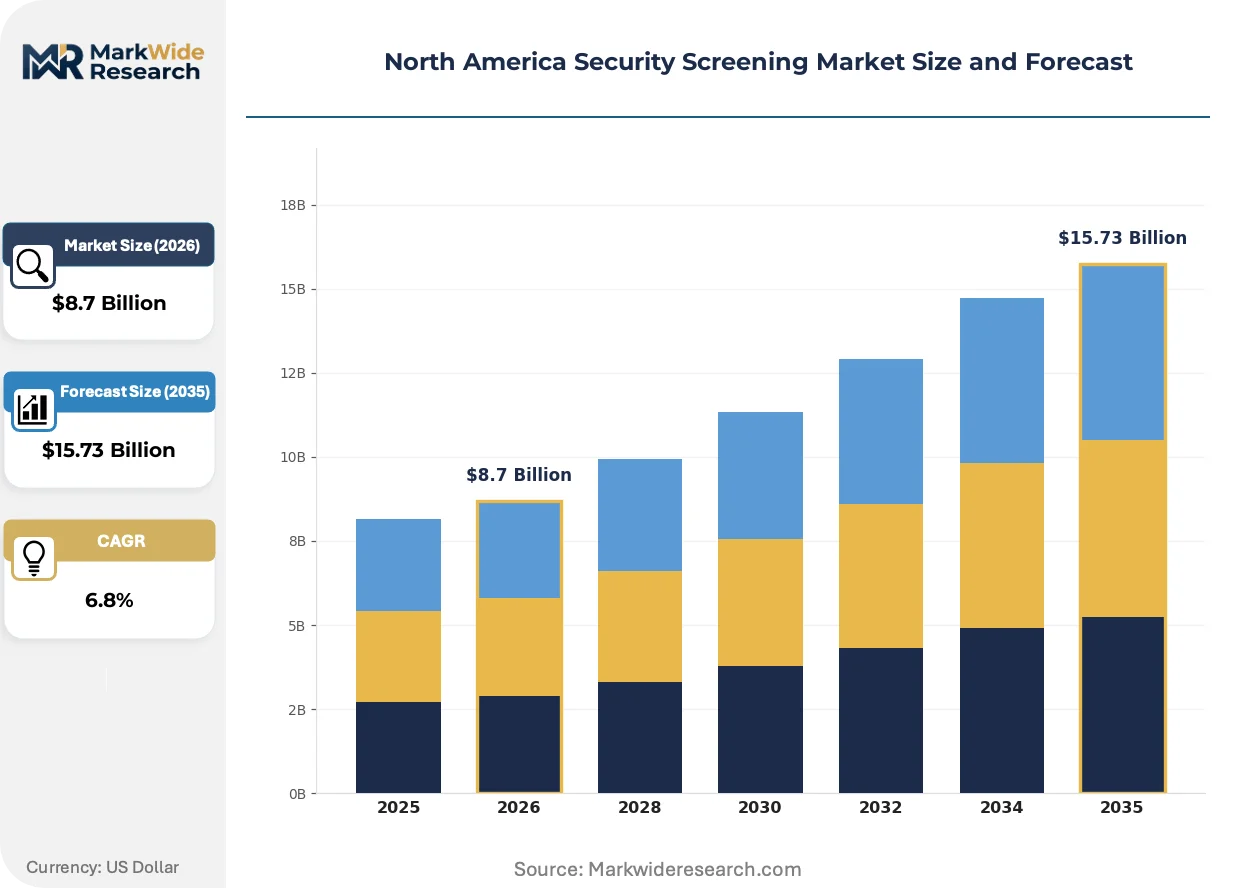
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray Machines, Metal Detectors, Explosive Trace Detectors, Advanced Imaging Technology End User: Aerospace, Transportation, Government, Public Events Solution: Hardware, Software, Integrated Systems, Maintenance Services Technology: Biometric Systems, RFID, Laser Scanning, AI Analytics |
| Companies Covered | Analogic Corporation, CEIA SpA, Smiths Detection Inc., 3DX-Ray Ltd, Gilardoni SpA, L3Harris Technologies, Astrophysics Inc., Teledyne ICM SA, OSI Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Security Screening Market Evolving Landscape
Computed tomography baggage screening is bifurcating market positioning between high-throughput hub installations and compact regional terminal configurations. Vendors must now optimize for divergent operational constraints simultaneously.
Dual-energy X-ray detection systems is bifurcating the installed base between legacy single-energy machines and advanced material-discrimination platforms. Tier-one US airports are adopting the latter at accelerated replacement cycles. The technology is bifurcating service contract structures into performance-based maintenance agreements versus traditional time-and-materials arrangements.
The Transportation Security Administration's biometric integration requirements are reshaping passenger portal specifications across federally funded airport deployments. Vendors must now embed facial recognition capabilities alongside millimeter-wave detection hardware. The US Southeast hub expansions in Atlanta and Miami represent the most concentrated near-term deployment pressure.
Consolidated procurement through airport authority joint ventures is displacing individual terminal purchasing decisions across the United States and Canada. Bulk equipment tenders now span multiple facility sites under single contract vehicles. The US Southeast and major Canadian gateways exhibit the most pronounced buyer concentration effects.
North America Security Screening Market Segmentation
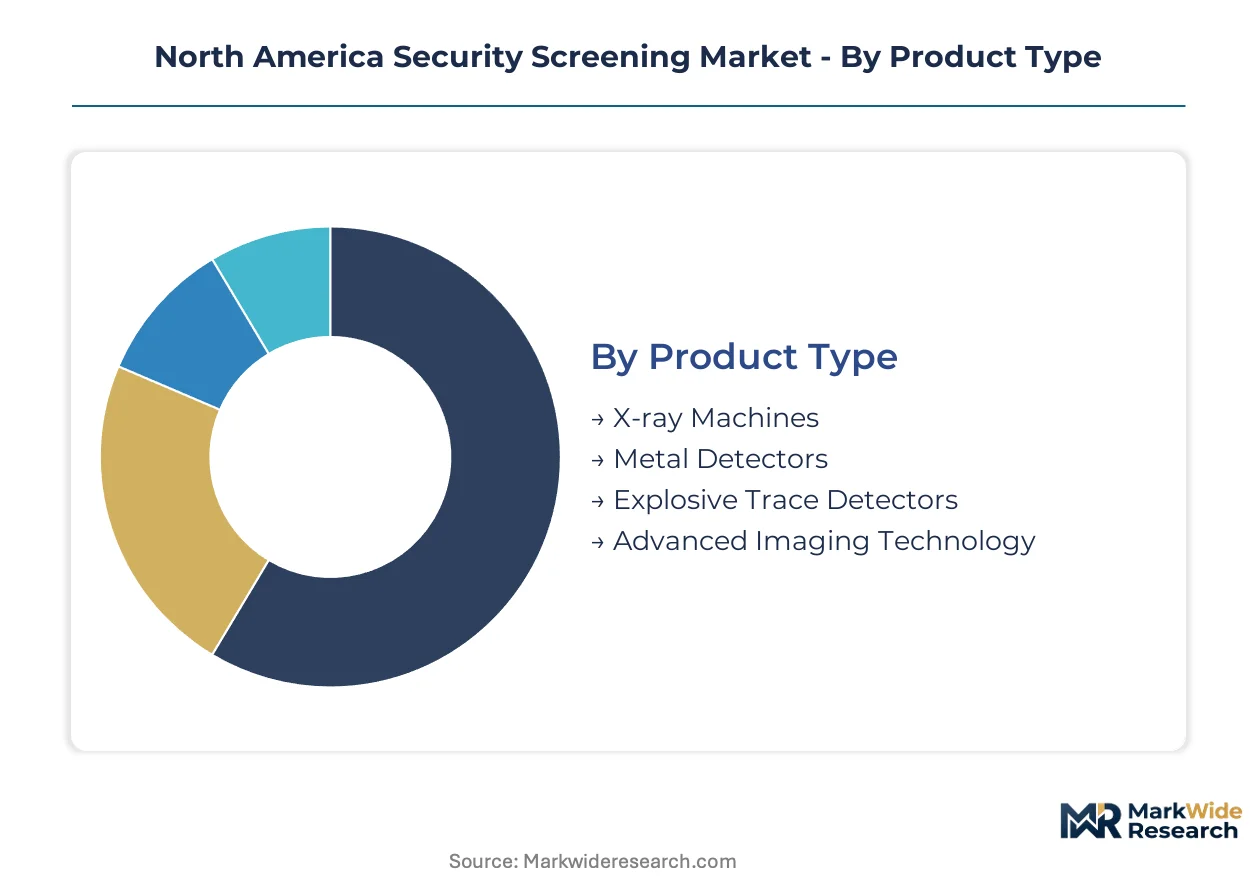
Segmentation in security screening reveals how procurement decisions split between federal mandate compliance and operational efficiency priorities. Vendors must align product configurations with distinct buyer economics across aerospace terminals, government facilities, and temporary public venues.
Product Type:
Domestic US manufacturing dominates X-ray and advanced imaging equipment, while explosive trace detector supply chains rely heavily on European sensor imports.
- X-ray Machines:Dual-energy and computed tomography variants operate at 140 kV to 320 kV energy levels for material discrimination. Demand concentrates at tier-one US airports in Atlanta and Miami where TSA mandates are driving bulk replacement of single-energy legacy units.
- Advanced Imaging Technology:Millimeter-wave passenger portals now embed biometric facial recognition per federal checkpoint requirements. The US Southeast hub expansions represent the steepest deployment pressure for these integrated configurations.
- Metal Detectors:Electromagnetic induction systems face accelerated retirement cycles across Canadian and US terminals.
- Explosive Trace Detectors:Ion mobility spectrometry and chemiluminescence devices anchor secondary screening protocols at airport checkpoints.
X-ray machines hold the largest share; momentum sits with advanced imaging technology.
End User:
Cost tier differentiation separates capital-intensive aerospace installations from price-sensitive temporary deployments.
- Aerospace:Airport authorities command the highest absolute spending with multi-year modernization budgets spanning checkpoint lanes and hold baggage systems. TSA PreCheck expansion across the United States is creating dedicated expedited lane procurement separate from standard checkpoint refresh.
- Transportation:Rail and port facilities in the US and Canada require cargo and vehicle inspection systems with extended operational duty cycles. Transport Canada screening regulations create parallel compliance pathways that influence cross-border equipment specifications.
- Government:Federal courthouse and military base installations prioritize security-cleared installation protocols.
- Public Events:Sports and entertainment venues operate on compressed decision timelines favoring rapid-deployment rental configurations.
Aerospace captures the largest revenue pool; public events represent the fastest-climbing procurement channel.
Solution:
Application complexity drives buyer preference from standalone hardware toward bundled service contracts.
- Hardware:Sensor-integrated screening platforms face semiconductor component pricing volatility that disrupts manufacturing schedules.
- Integrated Systems:Multimodal checkpoint configurations combine millimeter-wave portals, CT baggage screening, and biometric authentication under unified control architectures. FAA security program standards mandate this convergence at federally funded US airport deployments.
- Software:Threat detection algorithms require TSA validation protocols before commercial deployment.
- Maintenance Services:Performance-based agreements are displacing traditional time-and-materials contracts at major hub installations.
Hardware retains the dominant revenue position; integrated systems are gaining share fastest.
Technology:
Customer type segmentation separates federal mandate-driven adoption from discretionary facility upgrades.
- Biometric Systems:Facial recognition integration at passenger portals now carries federal funding eligibility requirements. The Transportation Security Administration's mandates are reshaping vendor qualification thresholds across US airport deployments.
- AI Analytics:Automated threat detection algorithms require emerging certification pathways that create first-mover advantage for compliant suppliers. AI analytics validation protocols are compressing product commercialization timelines for algorithm-compliant vendors.
- RFID:Asset tracking and passenger flow management applications support checkpoint throughput optimization.
- Laser Scanning:Standoff detection systems address perimeter security applications at critical infrastructure sites.
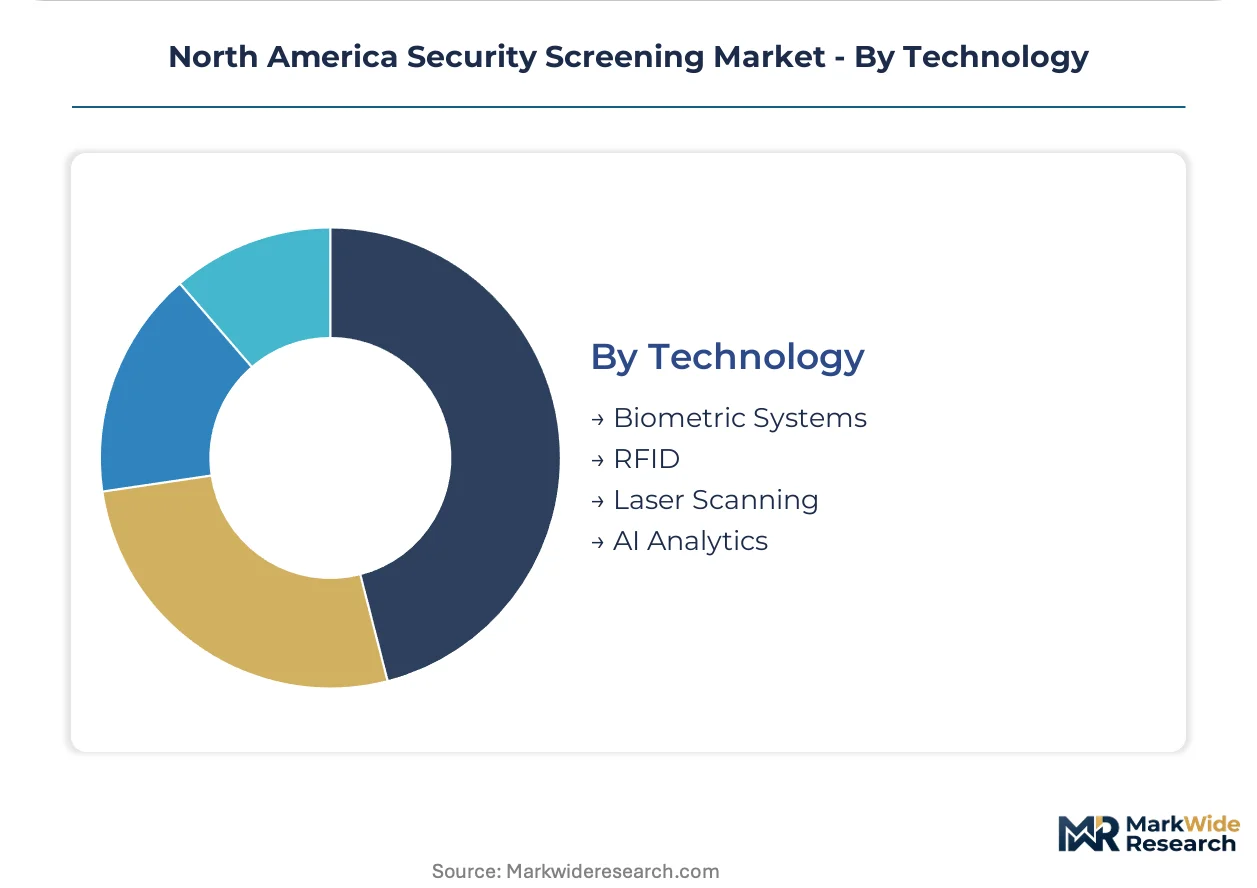
Biometric systems command the largest installed base; AI analytics represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Transportation Security Administration anchors procurement patterns across the dominant United States market, where checkpoint modernization mandates cascade through federal, state, and municipal contracting tiers. Canada follows parallel compliance pathways under Transport Canada screening regulations, while Mexico presents emerging demand at cross-border logistics corridors.
United States
Atlanta and Miami hub expansions drive concentrated procurement of next-generation screening lanes. The FAA security program standards mandate computed tomography baggage screening deployment at tier-one airports. TSA PreCheck enrollment growth accelerates dedicated expedited lane procurement separate from standard checkpoint refresh cycles.
Canada
Transport Canada screening regulations create cross-border equipment standardization requirements that influence vendor qualification thresholds. Toronto Pearson and Vancouver International anchor demand for integrated passenger and baggage screening systems. Health Canada compliance protocols extend to security-cleared installation workforce certification across federal installations.
Mexico
Cross-border freight corridors generate cargo and vehicle inspection demand at Laredo and Tijuana port-of-entry facilities. The country's national aviation regulator aligns terminal security upgrades with ICAO standards. Mexico City International Airport modernization programs attract multimodal checkpoint configuration tenders.
US Southeast
Florida and Georgia airport authorities consolidate procurement through joint venture structures spanning multiple facility sites. Miami International and Hartsfield-Jackson Atlanta drive the steepest deployment pressure for millimeter-wave passenger portals with biometric integration. State-level transportation agencies coordinate federal funding eligibility for checkpoint technology mandates.
US West Coast
Los Angeles International and San Francisco International anchor Pacific gateway screening infrastructure investment. California state environmental regulations intersect with TSA mandates to shape equipment energy efficiency specifications. Seattle-Tacoma International modernization programs extend to Alaska Airlines hub operations requiring dedicated PreCheck lane configurations.
North America Security Screening Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure consolidating around vendors capable of delivering multimodal checkpoint configurations under compressed federal qualification timelines. Tier-one US airports increasingly favor bundled service contracts over standalone hardware procurement, forcing portfolio diversification across detection technologies. Two strategic archetypes dominate: diversified defense-electronics conglomerates with captive airport relationships, and focused detection specialists leveraging deep R&D commitments. Competitive moves concentrate on M&A to fill technology gaps and strategic partnerships to access security-cleared installation capacity.
Within the integrated systems tier, L3Harris Technologies and Smiths Detection Inc. exemplify archetypes capable of delivering unified control architectures combining passenger portals, baggage screening, and biometric authentication. OSI Systems Inc. anchors the specialist tier through its Rapiscan brand presence across cargo and vehicle inspection segments. CEIA SpA represents European-origin specialists competing on compact regional terminal configurations optimized for divergent operational constraints.
| Leading Market Players |
|---|
| Analogic Corporation |
| CEIA SpA |
| Smiths Detection Inc. |
| 3DX-Ray Ltd |
| Gilardoni SpA |
| L3Harris Technologies |
| Astrophysics Inc. |
| Teledyne ICM SA |
| OSI Systems Inc. |
| Others |
Value Network & Pricing Analysis
TSA certification protocols gate both vendor qualification and price differentiation simultaneously, compressing margins for uncertified suppliers while embedding premium capture for qualified incumbents across federal contracting tiers.
Pricing Analysis
Price spreads between US-manufactured and European-imported screening equipment run wide across the North American market. Three-tier pricing structure across premium, standard, and economy levels separates TSA-certified integrated systems from uncertified hardware and rental configurations. Cost compression in the public events channel is intensifying because compressed procurement timelines favor rapid-deployment rentals over capital purchases. Aerospace terminals exhibit lowest price sensitivity due to federal funding eligibility, while municipal public venues face acute budget constraints.
Supply Chain Analysis
Inventory buffers for millimeter-wave sensor arrays and CT detector components have thinned to critical levels across North American manufacturing facilities. Domestic US production anchors X-ray and advanced imaging equipment assembly, while European suppliers feed explosive trace detector sensor modules and Asian foundries source semiconductor components. Single-source vulnerability concentrates in advanced sensor subassemblies where qualified alternative suppliers remain scarce. Distribution runs through authorized dealer networks serving airport authorities, with direct OEM relationships dominating tier-one hub procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Checkpoint technology is shifting toward platform economics as biometric authentication and AI analytics converge under unified control architectures, creating interoperability premiums for vendors with integrated multimodal capabilities.
For Market Incumbents: Secure security-cleared engineering capacity through captive workforce development or acquisition of specialized installation firms, as talent scarcity now constrains deployment velocity more than manufacturing scale. Deepen backward integration into sensor component production to buffer semiconductor pricing volatility and protect margin structures against Asian foundry concentration. For New Entrants and Emerging Players: Anchor in rapid-deployment rental configurations for sports and entertainment venues, where compressed decision timelines favor flexible service models over capital sales and incumbent certification advantages matter less. Pursue Transport Canada parallel certification pathways to access Toronto Pearson and Vancouver International procurement flows outside TSA-dominated competitive arenas. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across integrated multimodal checkpoint systems as biometric hardware and AI software development costs compound. Target acquisition profiles should emphasize firms with validated TSA certification pipelines and established security-cleared installation workforces. Monitor FAA security program standard updates as the critical signal for equipment refresh cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Integration Certification | TSA validation unlocks federal funding eligibility across Atlanta and Miami hub expansions. |
| Security-Cleared Workforce Acquisition | Captive installation capacity compresses deployment timelines for next-generation checkpoint lanes. |
| AI Analytics Validation Pathway | First-mover certification advantage captures automated threat detection procurement mandates. |
| Joint Venture Procurement Consolidation | Multi-site contract vehicles displace individual terminal purchasing across US Southeast authorities. |
| Performance-Based Service Transition | Outcome maintenance agreements displace time-and-materials structures at major hub installations. |
Research Methodology
Cross-validation between airport authority procurement records and TSA certification databases anchors the qualitative findings in documented vendor qualification pathways. Primary interviews with TSA program managers, airport engineering directors, security-cleared installation contractors, and screening equipment procurement officers combined with secondary analysis of FAA security directives, Transport Canada regulations, SEC filings from publicly traded vendors, and customs import records for European sensor components. Bottom-up equipment deployment tracking and top-down federal budget appropriation analysis triangulate market sizing.
Sensitivity analysis across semiconductor pricing scenarios and TSA certification timeline variations tests forecast robustness throughout the projection horizon. Segmentation modeling spans product type, end-user vertical, solution architecture, and technology integration level, with additional dimensioning by federal funding eligibility tier. CAGRs derive from equipment replacement cycle analysis and hub expansion pipeline tracking, incorporating TSA PreCheck enrollment trajectories and FAA mandate compliance deadlines as demand drivers.
Decision-makers should treat outputs as directional under assumptions of continued TSA checkpoint technology mandate enforcement and stable federal airport capital funding; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Explosive Trace Detection Market
Security and Surveillance
Global Security Assurance Market
Security and Surveillance
Home Security Sensors Market
Security and Surveillance
Europe Cargo and Vehicle Screening Market
Security and Surveillance
North America People Screening Market
Security and Surveillance
Global Intrusion Detection System Market
Security and Surveillance
Latin America Electronics Security Market
Security and Surveillance
Cargo and Vehicle Screening Market
Security and Surveillance
Sirens Market
Security and Surveillance
Integrated Security Services Market
Security and Surveillance
Anti-Piracy Protection Market
Security and Surveillance
5G-Enhanced Surveillance Market
Security and Surveillance
Global Threat Intelligence Management Market
Security and Surveillance
Residential Security Market
Security and Surveillance
Home Security Market
Security and Surveillance
Commercial Security Market