
 Head and Neck Cancer Drugs Market | 2026-2036
Head and Neck Cancer Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Head and Neck Cancer Drugs Market Insights
FDA Breakthrough Therapy Designation is reorganizing competitive entry timelines for novel agents. Merck & Co., Inc. anchors its position through dominant PD-1 inhibitor development in recurrent or metastatic settings. Bristol-Myers Squibb Company leverages dual immunotherapy combinations to sustain pipeline differentiation. Eli Lilly and Company specializes in antibody-drug conjugates targeting EGFR-expressing tumors.
Head and neck cancer drugs comprise systemic and localized therapeutic agents designed to interrupt oncogenic signaling, modulate immune recognition, or induce DNA damage in squamous cell carcinomas arising from the oral cavity, pharynx, and larynx. These agents require cold-chain distribution for biologics, sterile compounding for cytotoxic regimens, and molecular diagnostic pairing to identify actionable mutations. Immunotherapy now commands the deepest investment pools as checkpoint inhibitors displace platinum-based chemotherapy in first-line metastatic disease, while targeted therapy segments attract focused development around cetuximab biosimilars and next-generation EGFR inhibitors. The application split orbits oral cancer and oropharyngeal cancer, with HPV-positive oropharyngeal subtypes driving protocol redesign toward de-escalation trials.
FDA, EMA, and the EU's Clinical Trials Regulation collectively govern trial conduct, labeling, and post-market surveillance across major development corridors. The FDA's Project Orbis enables concurrent oncology program reviews with Health Canada, TGA, and Swissmedic, compressing multi-territory launch intervals. Stakeholders must monitor how real-world evidence requirements from these regulators reshape post-approval commitment burdens and lifecycle management strategies.
Market Dynamics
Checkpoint inhibitor immunotherapy is compressing platinum-based chemotherapy's first-line position in recurrent or metastatic settings, forcing protocol redesign across oncology departments and reimbursement frameworks.
Growth Catalysts
- Project Orbis:The FDA's concurrent review mechanism with Health Canada, TGA, and Swissmedic compresses multi-territory launch timelines for breakthrough oncology therapies.
- HPV-positive oropharynal subtype recognition:Molecular diagnostic pairing enables de-escalation trial designs that reduce treatment toxicity while preserving efficacy endpoints.
- Medicare reimbursement policies:United States outpatient infusion centers receive favorable reimbursement rates for immunotherapy administration, concentrating demand in ambulatory settings.
Market Restraints
- Cold-chain biologics distribution:Temperature-controlled logistics for checkpoint inhibitors impose infrastructure requirements that limit rural and lower-income market access.
- Platinum supply concentration:Cytotoxic backbone agents depend on concentrated mining and refining operations, creating input cost volatility for chemotherapy manufacturing.
- EMA real-world evidence requirements:Post-approval commitment burdens for conditional marketing authorizations extend lifecycle management costs and regulatory friction.
Strategic Opportunities
- Antibody-drug conjugate expansion:EGFR-targeting conjugates offer tissue-specific cytotoxic delivery that opens differentiation space beyond naked monoclonal antibodies.
- De-escalation trial protocols:HPV-positive oropharyngeal cancer subtypes enable reduced-intensity treatment arms that preserve oncologic outcomes with lower toxicity profiles.
- Specialized compounding pharmacies:Sterile cytotoxic preparation outsourcing creates channel innovation for hospital-adjacent infusion networks.
Industry Challenges
- Companion diagnostic integration:PD-L1 expression testing and HPV status determination require pathology workflow reconfiguration that delays treatment initiation.
- Biosimilar cetuximab transition:Reference product erosion forces manufacturing network reconfiguration and contract renegotiation across distribution channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Head and Neck Cancer Drugs Market |
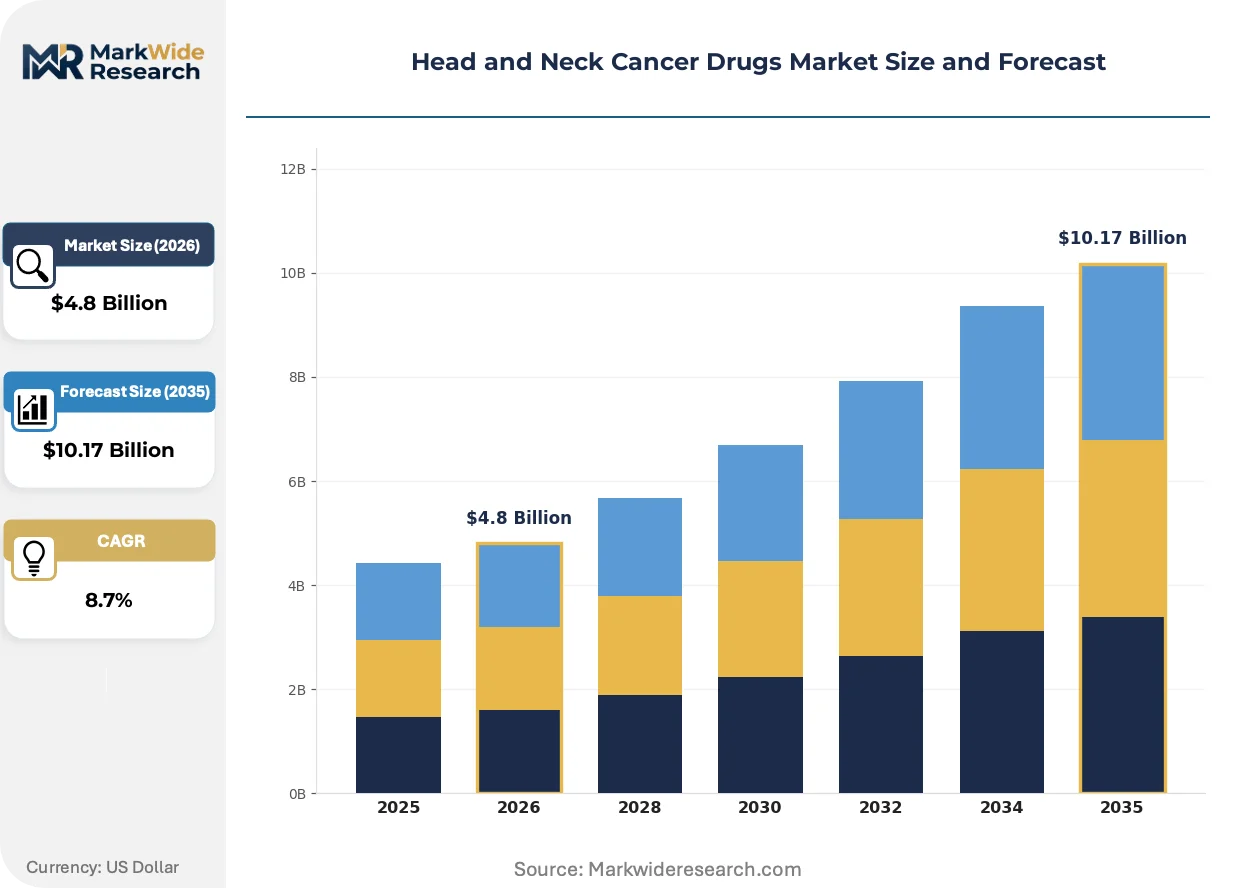
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Targeted Therapy, Radiation Therapy Application: Oral Cancer, Nasopharyngeal Cancer, Oropharyngeal Cancer, Laryngeal Cancer End User: Hospitals, Cancer Treatment Centers, Research Institutes, Homecare Administration Route: Oral, Intravenous, Subcutaneous, Topical |
| Companies Covered | Sanofi, F. Hoffmann-La Roche Ltd, Merck & Co., Inc., Regeneron Pharmaceuticals, Inc., Pfizer Inc., Bristol-Myers Squibb Company, AstraZeneca plc, Johnson & Johnson, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Head and Neck Cancer Drugs Market Trends and Innovations
Immunotherapy protocol expansion is restructuring competitive entry patterns, with therapeutic modality convergence and regulatory pathway compression defining the current innovation cycle.
Next-generation sequencing-based molecular profiling is supplanting single-biomarker immunohistochemistry in treatment selection protocols. Tertiary hospital oncology departments in the United States and Germany are adopting comprehensive genomic panels at accelerating pace. This shift is supplanting empiric chemotherapy selection with precision-matched trial enrollment and targeted therapy allocation.
The EU Clinical Trials Regulation harmonizes protocol submission and safety reporting across member states, reducing redundant national competent authority reviews. Pharmaceutical sponsors now file single centralized applications rather than sequential country-by-country submissions. This regulatory streamlining most affects early-phase oncology trials, with contract research organizations restructuring European site networks to capture centralized assessment efficiencies.
Site-of-care migration toward community oncology practices is fragmenting historical hospital-centric infusion volumes. United States Medicare Advantage plans and commercial payers are steering stable immunotherapy maintenance toward lower-cost ambulatory settings. This channel rotation is most visible in Florida and Texas metropolitan corridors, where independent oncology groups capture checkpoint inhibitor administration from academic medical centers.
Head and Neck Cancer Drugs Market Segmentation
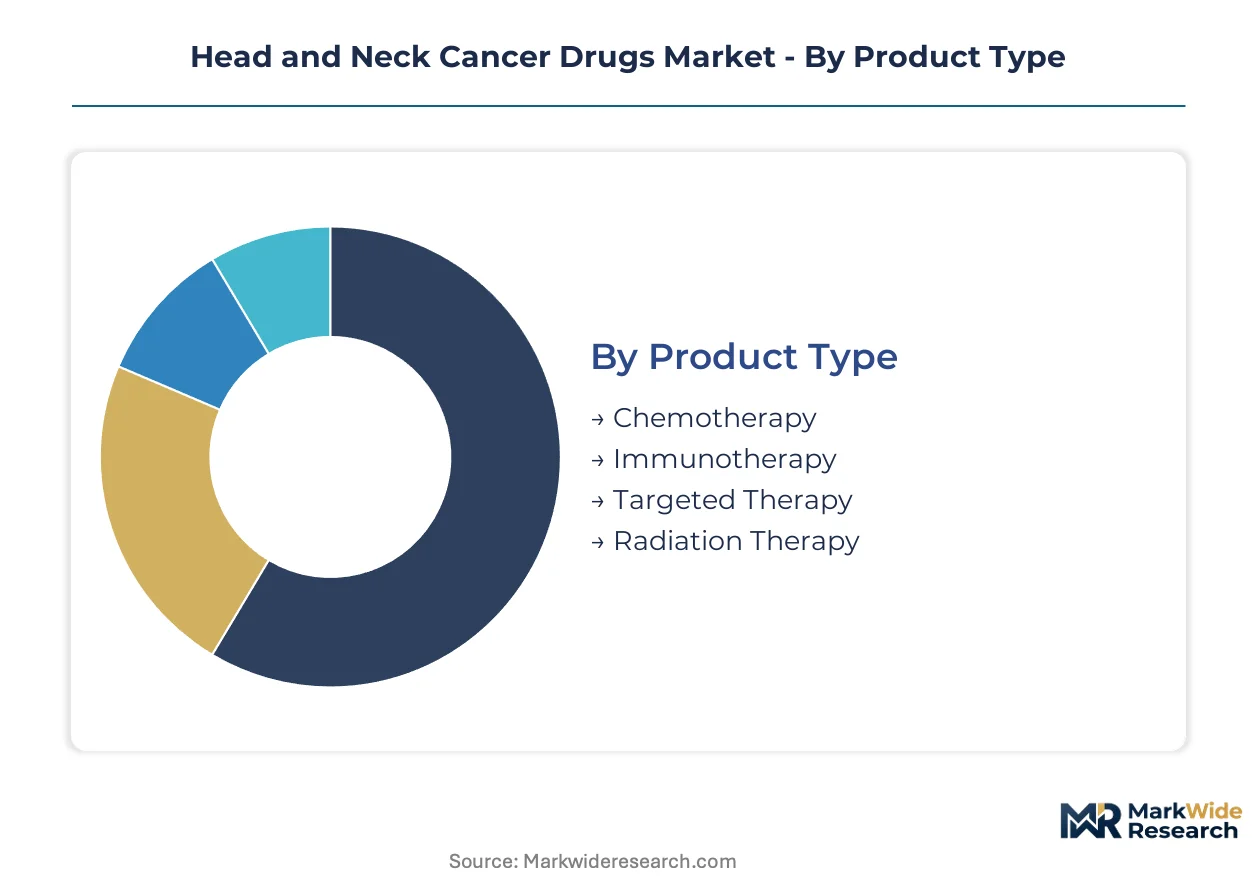
Segmentation in head and neck cancer drugs determines reimbursement pathways, distribution infrastructure requirements, and site-of-care economics. Treatment modality selection drives cold-chain logistics investment, sterile compounding capacity, and molecular diagnostic pairing protocols across delivery channels.
Product Type:
Channel mix varies sharply by product type: immunotherapy concentrates in hospital outpatient departments and ambulatory infusion centers, while chemotherapy flows through specialized compounding pharmacies and radiation therapy remains fixed in hospital-based departments.
- Immunotherapy:Checkpoint inhibitors targeting PD-1/PD-L1 pathways require cold-chain distribution and extended infusion monitoring. Demand concentrates in tertiary hospital oncology departments across the United States and Germany, driven by FDA breakthrough therapy designations compressing launch timelines.
- Targeted Therapy:EGFR inhibitors and antibody-drug conjugates demand molecular diagnostic pairing and tissue-specific delivery mechanisms. Cancer treatment centers in urban United States corridors capture the deepest prescription volumes, constrained by companion diagnostic integration delays.
- Chemotherapy:Platinum-based cytotoxic agents remain the backbone for neoadjuvant and concurrent protocols.
- Radiation Therapy:Radioisotopes and radiosensitizers require fixed linear accelerator infrastructure.
By volume, chemotherapy leads. By growth pace, immunotherapy is ahead.
Application:
Cost tier stratification separates applications: oropharyngeal cancer commands premium immunotherapy pricing, while oral cancer segments across de-escalation trial protocols and laryngeal cancer retains older cytotoxic standards.
- Oropharyngeal Cancer:HPV-positive subtypes drive protocol redesign toward reduced-intensity treatment arms with preserved efficacy. United States academic medical centers lead enrollment in de-escalation trials, supported by Medicare reimbursement for outpatient infusion.
- Oral Cancer:Squamous cell carcinomas of the oral cavity require multimodal approaches combining surgery, radiation, and systemic therapy. German tertiary hospitals and United States National Cancer Institute-designated centers capture the highest case volumes, facing challenges in rural access to molecular profiling.
- Nasopharyngeal Cancer:Endemic variants in select populations shape regional trial concentration.
- Laryngeal Cancer:Organ-preservation protocols dominate treatment selection in advanced disease.
By patient volume, oral cancer leads. By protocol innovation velocity, oropharyngeal cancer is expanding most quickly.
End User:
Customer type determines procurement scale and service bundling: hospitals integrate diagnostics and therapy, cancer treatment centers unbundle infusion services, and homecare captures stable maintenance regimens.
- Hospitals:Tertiary academic medical centers command integrated diagnostic-therapeutic workflows with molecular tumor boards and clinical trial access. United States metropolitan hospital systems in Texas and Florida face site-of-care migration pressure as Medicare Advantage steers patients toward ambulatory alternatives.
- Cancer Treatment Centers:Independent oncology groups and hospital-affiliated ambulatory centers specialize in infusion administration and toxicity management. Community practices in United States suburban corridors gain share fastest from academic center referrals, driven by payer cost-containment mandates.
- Research Institutes:Early-phase trial sites concentrate in regulatory-efficient jurisdictions.
- Homecare:Oral targeted agents and subcutaneous immunotherapy enable administration outside institutional settings.
By treatment volume, hospitals lead. By share gain trajectory, cancer treatment centers are climbing the fastest.
Administration Route:
Supply concentration shapes route selection: intravenous dominates biologics manufacturing scale, oral enables patient self-administration, and subcutaneous offers channel arbitrage between hospital and home settings.
- Intravenous:Large-molecule biologics and cytotoxic agents require sterile compounding and infusion supervision. United States outpatient infusion centers and German day-clinic networks capture the deepest volume concentration, constrained by cold-chain infrastructure gaps in rural territories.
- Oral:Small-molecule tyrosine kinase inhibitors and chemotherapy prodrugs enable decentralized dispensing and patient self-management. Pharmacy benefit managers in United States commercial and Medicare Part D channels control access through formulary placement and prior authorization protocols.
- Subcutaneous:Checkpoint inhibitor formulations reduce infusion duration and site-of-care requirements.
- Topical:Localized agents address premalignant lesions and palliative mucosal indications.
By protocol frequency, intravenous leads. By convenience-driven conversion, subcutaneous is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement policies in the United States concentrate outpatient immunotherapy demand in ambulatory infusion centers. Germany's EMA-aligned regulatory framework accelerates centralized trial approvals across member states. Japan's PMDA maintains distinct local clinical data requirements that extend oncology drug launch intervals.
United States
Tertiary hospital oncology departments in Texas and Florida expand immunotherapy protocols fastest. FDA Project Orbis enables concurrent reviews with Health Canada, TGA, and Swissmedic that compress multi-territory launch timelines. Metropolitan hospital systems in these states face site-of-care migration as Medicare Advantage steers stable maintenance toward community oncology practices.
Germany
Academic medical centers in Bavaria and Baden-Württemberg lead European enrollment in de-escalation trials for HPV-positive oropharyngeal subtypes. EMA centralized procedures under the EU Clinical Trials Regulation eliminate redundant national competent authority reviews. The Heidelberg and Munich clusters capture the deepest concentration of molecular tumor boards and comprehensive genomic panel adoption.
Japan
PMDA's requirement for Japan-specific clinical data in oncology indications extends regulatory review durations relative to FDA timelines. Tokyo and Osaka metropolitan hospital networks anchor domestic immunotherapy demand. The country's national health insurance pricing negotiations compress reimbursement premiums for novel checkpoint inhibitors versus US benchmarks.
United Kingdom
NICE technology appraisals create distinct access thresholds for head and neck cancer immunotherapy versus EU5 markets. London and Manchester cancer centers concentrate early-phase trial enrollment. NHS England's Cancer Drugs Fund provides conditional reimbursement pathways that accelerate patient access pending confirmatory evidence generation.
China
NMPA's breakthrough therapy designation pathway compresses review timelines for domestically developed PD-1 inhibitors. Beijing and Shanghai tertiary hospitals anchor demand concentration. The National Reimbursement Drug List inclusion negotiations determine commercial access scale for imported versus domestic oncology biologics.
Head and Neck Cancer Drugs Market Competitive Landscape
Listed leaders compete with private specialists across checkpoint inhibitor development and antibody-drug conjugate pipelines. The market structure concentrates around large-cap pharmaceutical conglomerates with oncology divisions, mid-cap biotech specialists, and emerging biosimilar manufacturers. Three archetypes dominate: PD-1/PD-L1 checkpoint developers, EGFR-targeting conjugate specialists, and platinum-based cytotoxic incumbents. Consolidation pressure drives strategic partnerships for companion diagnostic pairing and capacity expansion for cold-chain biologics distribution.
Within the large-cap pharmaceutical tier, Merck & Co., Inc., Bristol-Myers Squibb Company, and Eli Lilly and Company occupy anchor positions that exemplify divergent modality strategies. Merck represents the checkpoint inhibitor archetype through PD-1 pathway dominance. Bristol-Myers Squibb sits within the dual immunotherapy combination space. Eli Lilly exemplifies the antibody-drug conjugate specialization targeting EGFR-expressing tumors. These three structures illustrate how therapeutic modality selection determines competitive positioning across recurrent and metastatic treatment settings.
| Leading Market Players |
|---|
| Sanofi |
| F. Hoffmann-La Roche Ltd |
| Merck & Co., Inc. |
| Regeneron Pharmaceuticals, Inc. |
| Pfizer Inc. |
| Bristol-Myers Squibb Company |
| AstraZeneca plc |
| Johnson & Johnson |
| Eli Lilly and Company |
| Others |
Pricing and Supply Chain Analysis
Ninety-day cold-chain inventory cycles for checkpoint inhibitors concentrate pricing power with distributors possessing validated cryogenic logistics, while Medicare reimbursement compression in United States outpatient settings feeds back into manufacturer channel rebate negotiations. This interdependence between biologics shelf-life constraints and payer cost-containment mandates structures procurement leverage across the value chain.
Pricing Analysis
Certification level (FDA-breakthrough versus standard approval pathway) creates the primary spread between premium immunotherapy positioning and commodity chemotherapy tiers. Three-tier pricing structure across premium checkpoint inhibitors, standard EGFR-targeting agents, and economy platinum-based cytotoxics dominates contract negotiations. Pricing pressure stems from biosimilar cetuximab entry forcing reference product discounting. Community oncology practices exhibit highest price sensitivity due to Medicare Advantage steerage, while academic medical centers prioritize clinical trial access over unit cost.
Supply Chain Analysis
Forty-five to sixty-day lead times for sterile cytotoxic compounding anchor procurement planning across hospital-adjacent infusion networks. Active pharmaceutical ingredient production concentrates in India, China, and Switzerland for oncology biologics and small molecules. Platinum salts and monoclonal antibody cell lines constitute critical input dependencies. Single-source vulnerability pervades cold-chain logistics providers for rural United States territories. Distribution runs through specialized compounding pharmacies and hospital outpatient departments rather than retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Companion diagnostic-platform interoperability is restructuring competitive moats around molecular profiling ecosystems, with next-generation sequencing integration determining protocol inclusion or exclusion for novel agents.
For Market Incumbents: Compound defensive positioning through backward integration into companion diagnostic development and captive cold-chain capacity in Texas and Florida metropolitan corridors. Checkpoint inhibitor commoditization from PD-1 pathway crowding threatens margin compression. Priority lever rests on molecular diagnostic pairing exclusivity and de-escalation trial data generation for HPV-positive oropharyngeal subtypes. For New Entrants and Emerging Players: Rural access gaps in molecular tumor board coverage present service-layer white-space where academic centers under-serve community oncology practices. Subcutaneous immunotherapy formulation development offers fastest penetration trajectory given site-of-care migration toward ambulatory settings. Go-to-market angle centers on pharmacy benefit manager formulary placement negotiations for oral targeted agents. For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical conglomerates divesting legacy cytotoxic manufacturing networks amid immunotherapy portfolio prioritization. Five-to-ten year viability favors antibody-drug conjugate specialists with tissue-specific delivery platforms over platinum-based chemistry incumbents. Signal to watch: FDA Project Orbis expansion beyond current partner regulators indicating accelerated multi-territory launch capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | Molecular profiling pairing with checkpoint inhibitors secures protocol inclusion at NCI-designated centers. |
| De-escalation Trial Advancement | HPV-positive oropharyngeal subtype data generation enables reduced-toxicity positioning against standard-of-care. |
| Subcutaneous Formulation Development | Reduced infusion duration captures site-of-care migration toward community oncology practices. |
| Cold-Chain Capacity Expansion | Validated cryogenic logistics in Texas and Florida metropolitan corridors supports outpatient infusion growth. |
| Biosimilar Manufacturing Scale-Up | Cetuximab reference product erosion creates volume opportunity in cost-sensitive community settings. |
Research Methodology
Desk research of FDA breakthrough therapy designation filings, EMA centralized procedure submissions, and ClinicalTrials.gov protocol registries preceded structured interviews with oncology drug development executives, hospital formulary directors, payer access specialists, and cold-chain logistics operators. Secondary validation drew from Medicare reimbursement databases, GPO contract repositories, and pharmaceutical SEC 10-K oncology segment disclosures. Bottom-up prescription volume modeling and top-down therapeutic class allocation triangulated market sizing.
Variance decomposition across treatment modality, administration route, patient population, and regional regulatory cluster shaped analytical framework construction over the projection horizon. Segmentation dimensions encompassed immunotherapy, targeted therapy, chemotherapy, and radiation therapy by product type; oropharyngeal, oral, nasopharyngeal, and laryngeal cancer by application; and hospitals, cancer treatment centers, research institutes, and homecare by end user. CAGRs derived from protocol adoption curve analysis and reimbursement trajectory modeling. Forecast inputs incorporated PD-L1 expression testing penetration rates and HPV status determination workflow adoption.
Underlying assumptions cover FDA breakthrough therapy designation sustainment, EMA real-world evidence commitment fulfillment, and Medicare outpatient infusion reimbursement stability, with deviation risk concentrated in biosimilar substitution velocity and site-of-care migration pace. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
North America Kidney Cancer Therapeutics and Diagnostics Market
Oncology
France Radiation Oncology Market
Oncology
Global Particle Therapy Market
Oncology
Internal Radiation Therapy Market
Oncology
Single-Room Proton Therapy Systems Market
Oncology
Europe Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Throat Cancer Market
Oncology
North America Veterinary Oncology Market
Oncology
Cancer Cachexia Market
Oncology
Liposarcoma Treatment Market
Oncology
Ewing Sarcoma Treatment Market
Oncology
Pituitary Cancer Market
Oncology
Small Cell Lung Cancer (SCLC) Treatment Market
Oncology
Colorectal Cancer Screening Market
Oncology
Glottic Cancer Treatment Market
Oncology
Breast Cancer Liquid Biopsy Market